China Advanced Vehicle Collision Avoidance Technologies Market Size & Growth Rate
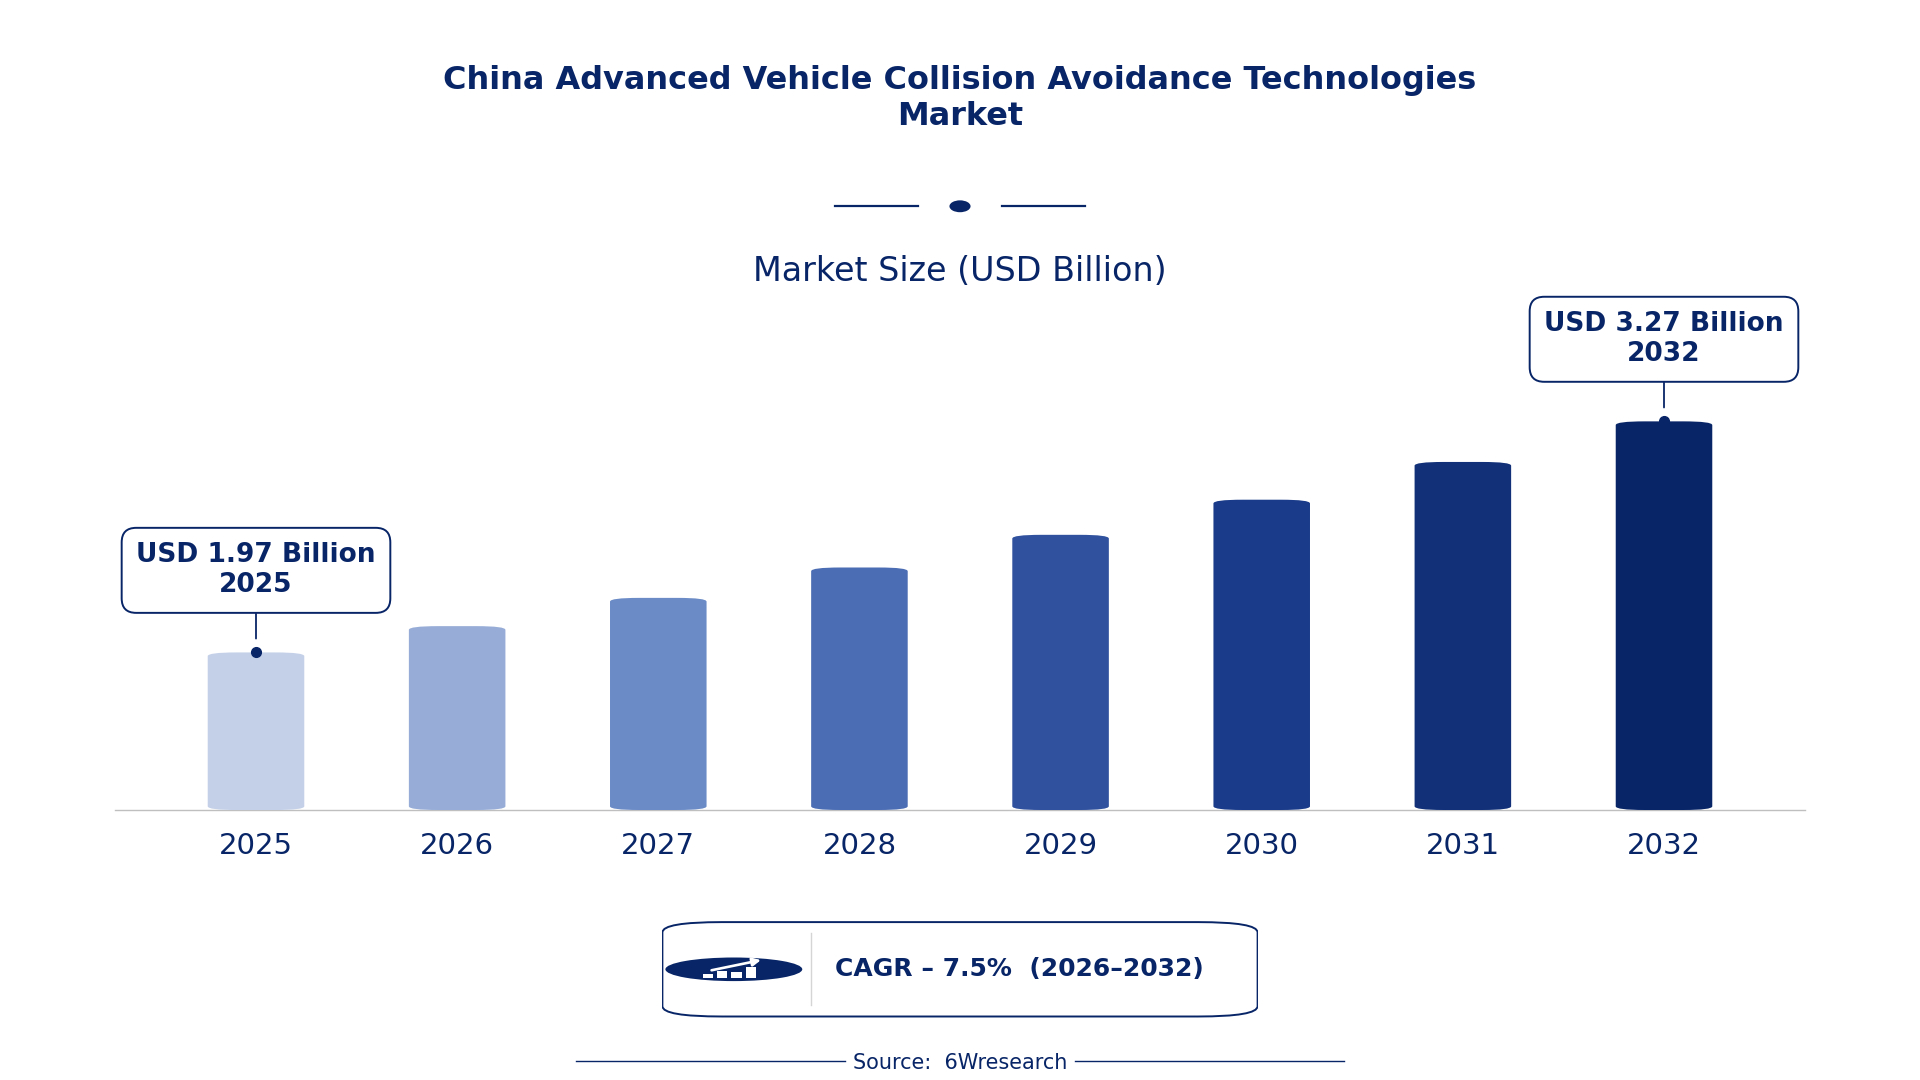
According to 6Wresearch internal database and industry insights, the China Advanced Vehicle Collision Avoidance Technologies Market was valued at USD 1.97 billion in 2025 and is projected to reach USD 3.27 billion by 2032, growing at a CAGR of approximately 7.5% during 2026–2032.
China Advanced Vehicle Collision Avoidance Technologies Market Highlights
| Report Metric | Details |
| Report Name | China Advanced Vehicle Collision Avoidance Technologies Market |
| Market Size 2025 | USD 1.97 billion |
| Market Size 2032 | USD 3.27 billion |
| Absolute Growth 2025–2032 | USD 1.30 billion |
| CAGR 2026–2032 | 7.5% |
| Peak Annual Growth | 10.0% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Advanced Vehicle Collision Avoidance Technologies Market, 2025 | Automatic Emergency Braking (AEB) (44% share) |
| Leading Technology Type, 2025 | AI-Based (41% share) |
| Leading Detection Method, 2025 | Camera + Radar (41% share) |
| Leading Integration Type, 2025 | OEM-Integrated (46% share) |
| Leading Vehicle Segment, 2025 | Passenger Cars (41% share) |
| Fastest-Growing Advanced Vehicle Collision Avoidance Technologies Market | Lane Departure Warning Systems (9.1% CAGR) |
| Fastest-Growing Technology Type | LIDAR/GPS Enabled (9.8% CAGR) |
| Fastest-Growing Detection Method | Sensor Fusion (8.9% CAGR) |
| Fastest-Growing Integration Type | Aftermarket & OEM (9.3% CAGR) |
| Fastest-Growing Vehicle Segment | SUVs & Sedans (10.0% CAGR) |
| Growing Sector | Passenger Cars |
| Key End Users | Automotive manufacturers, fleet operators, safety technology suppliers |
China Advanced Vehicle Collision Avoidance Technologies Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
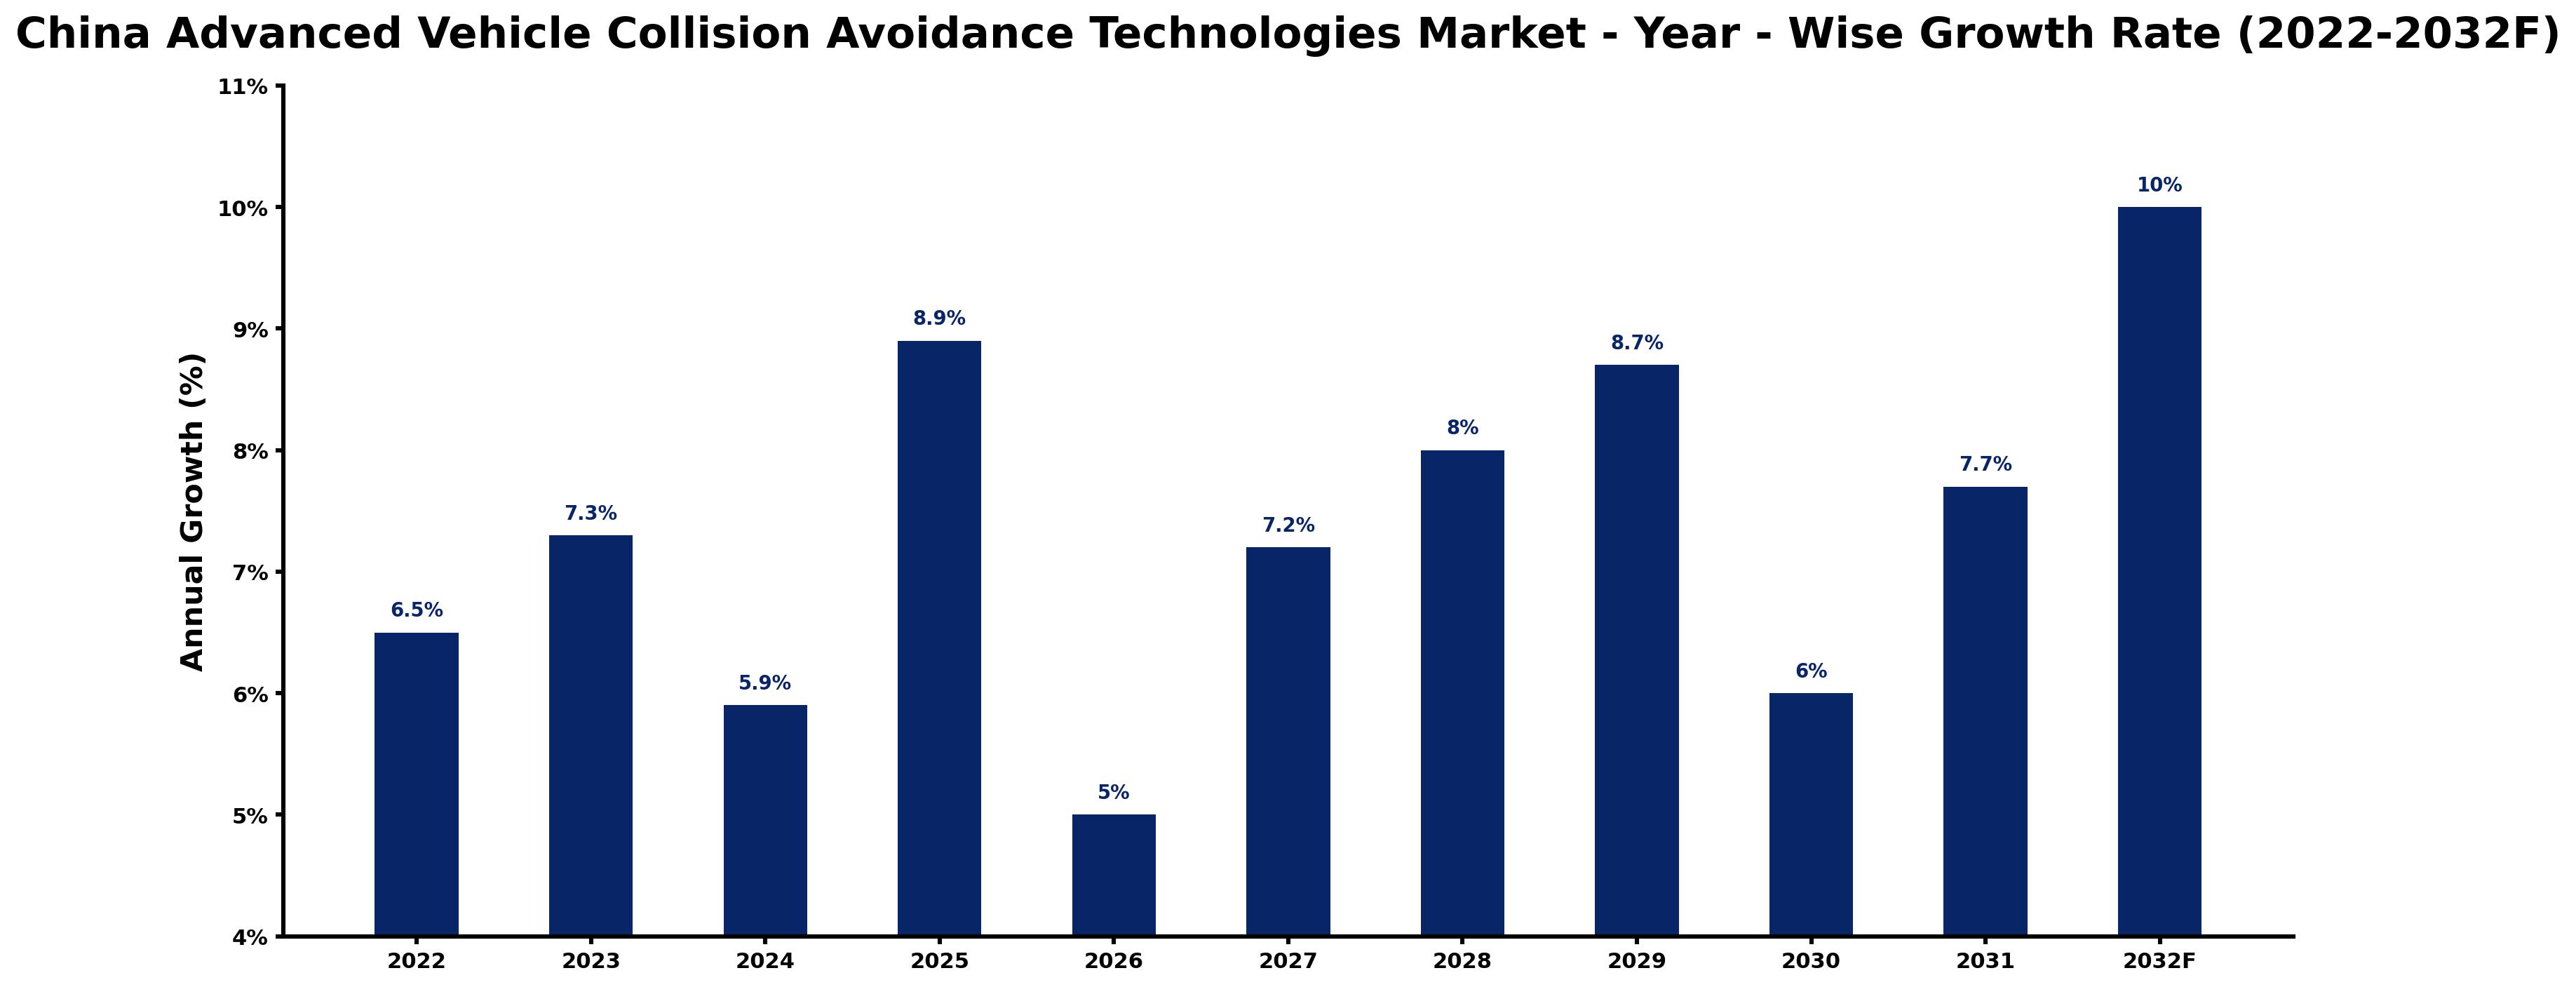
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.5 | The market experienced steady growth due to increasing vehicle production and safety awareness driven by the '14th Five-Year Plan for the Development of the Automotive Industry'. |
| 2023 | 7.3 | Demand accelerated as more vehicles incorporated advanced collision avoidance technologies, supported by the 'Made in China 2025' initiative. |
| 2024 | 5.9 | Growth slowed as manufacturers adjusted to evolving safety standards, particularly the updated GB/T 34590-2017. |
| 2025 | 8.9 | A surge in adoption of Automatic Emergency Braking systems drove growth in the market as awareness of safety increased. |
| 2026 | 5.0 | Market growth will decelerate as competition intensifies and innovation cycles lengthen, impacting new product introductions. |
| 2027 | 7.2 | Investment in R&D for safety technologies is projected to lead to a rebound in market growth as new features are developed. |
| 2028 | 8.0 | Demand is expected to rise as urban areas increasingly adopt advanced vehicle safety features, reflecting consumer preferences. |
| 2029 | 8.7 | The market will continue to expand due to rising consumer safety expectations and regulatory support for advanced technologies. |
| 2030 | 6.0 | Growth will slow as market saturation begins to affect new vehicle sales, limiting expansion opportunities. |
| 2031 | 7.7 | Increased focus on integrating AI technologies in vehicles will spur renewed demand for advanced collision avoidance systems. |
| 2032 | 10.0 | The market is projected to peak as new standards further improve vehicle safety and consumer adoption increases. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Advanced Vehicle Collision Avoidance Technologies Market Synopsis
Advanced Vehicle Collision Avoidance Technologies in China encompass systems designed to improve vehicle safety by preventing accidents. The China Advanced Vehicle Collision Avoidance Technologies Market is growing due to significant automotive production, with over 25 million vehicles produced in 2022. Investments in R&D and updated safety standards are driving demand, as more than 50% of new passenger vehicles in urban areas are expected to feature these systems by 2023.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing automotive production and safety regulations drive demand for collision avoidance technologies. | Driver | High | Automatic Emergency Braking (AEB) |
| Increasing consumer awareness of vehicle safety features enhances adoption rates. | Driver | High | Forward Collision Warning (FCW) |
| Rising demand for advanced safety features in passenger vehicles creates investment opportunities. | Opportunity | High | Passenger Cars |
| The Guangdong province's focus on automotive manufacturing presents significant market entry opportunities. | Opportunity | Medium | SUVs & Sedans |
| High costs associated with R&D and technology integration can limit smaller manufacturers' market entry. | Restraint | High | OEM-Integrated |
| Regulatory compliance costs for safety standards can strain budgets for manufacturers. | Restraint | Medium | Aftermarket & OEM |
| Supply chain disruptions affect timely delivery of advanced components for collision avoidance systems. | Challenge | High | Commercial Fleets |
| Rapid technological advancements require continuous investment, posing a challenge for established players. | Challenge | Medium | Luxury Vehicles |
Evaluation of Drivers in China Advanced Vehicle Collision Avoidance Technologies Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased vehicle production in China leads to higher demand for safety technologies. | Automatic Emergency Braking (AEB) | Over 25 million vehicles produced in 2022 drives the need for advanced safety features. |
| Growing consumer awareness of safety features boosts adoption rates of collision avoidance technologies. | Forward Collision Warning (FCW) | The rise in consumer safety concerns has led to a 30% increase in AEB adoption in new vehicles. |
| Investment in R&D for advanced safety technologies improves product offerings and market competitiveness. | AI-Based | The automotive safety market is projected to reach 200 billion yuan by 2025, encouraging innovation. |
| Government initiatives promoting smart vehicle technologies support market expansion. | Lane Departure Warning Systems | The 'Made in China 2025' initiative fosters investment in advanced vehicle technologies. |
| Urbanization and increased vehicle ownership create a larger customer base for collision avoidance systems. | Passenger Cars | By 2023, over 50% of new passenger vehicles in urban areas are projected to feature these systems. |
In 2022, over 25 million vehicles were produced, creating a need for advanced safety features. The uptake of Automatic Emergency Braking systems rose by 30% in 2022, showcasing consumer preferences for enhanced safety. Urban regions are projected to see over 50% of new passenger vehicles equipped with these technologies by 2023, further driving market expansion. Investment in R&D for safety technologies is expected to rise, resulting in solutions that cater to changing consumer needs.
Evaluation of Restraints in China Advanced Vehicle Collision Avoidance Technologies Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High R&D costs limit smaller manufacturers' ability to compete effectively. | OEM-Integrated | Investment in advanced safety technologies can exceed 100 million yuan, restricting market entry. |
| Compliance with evolving safety standards increases operational costs for manufacturers. | Aftermarket & OEM | The updated National Standard GB/T 34590-2017 requires significant investments for compliance. |
| Supply chain disruptions hinder timely access to essential components for collision avoidance systems. | Commercial Fleets | Delays in component delivery can lead to increased operational risks for fleet managers. |
| Technological advancements require continuous investment, straining established players' resources. | Luxury Vehicles | Maintaining competitiveness in technology integration demands substantial financial commitment. |
| Market saturation limits growth potential for established collision avoidance technologies. | Passenger Cars | As more vehicles are equipped with these systems, new sales opportunities diminish. |
China Advanced Vehicle Collision Avoidance Technologies Market Challenges
Buyers and suppliers in the China Advanced Vehicle Collision Avoidance Technologies market face notable supply chain disruptions, largely due to dependence on imported components, which can delay production timelines by up to six months. Competition intensifies as local manufacturers increase output, resulting in a 30% rise in the adoption of advanced technologies among new vehicles, pushing existing suppliers to innovate swiftly. Buyers encounter difficulties in adhering to updated safety standards, such as the GB/T 34590-2017, leading to compliance costs that can raise vehicle prices by 15%. Furthermore, escalating research and development expenses, expected to reach 200 billion yuan by 2025, strain budgets for both producers and buyers.
Trends in the China Advanced Vehicle Collision Avoidance Technologies Market
Buyers and suppliers in the China Advanced Vehicle Collision Avoidance Technologies Market are adjusting to the following trends.
- Rise of AI-Based Technologies: In 2023, AI-Based technologies are increasingly adopted in collision avoidance systems, improving predictive safety measures. This shift aligns with the growing demand for intelligent safety features, with a projected growth rate of 9.8% for LIDAR/GPS Enabled systems.
- Adoption of Advanced Safety Features: The 'Automotive Safety Technology Promotion Plan' launched in 2023 encourages manufacturers to integrate advanced safety technologies. This initiative aims to increase the adoption of safety features, with over 50% of new vehicles expected to comply by 2023.
- Urban Adoption of Safety Technologies: Urban areas are experiencing a surge in the adoption of collision avoidance technologies, driven by safety regulations. By 2023, more than 50% of new passenger vehicles in urban regions are projected to feature these systems.
- Standardization of Safety Technologies: The China Automotive Technology and Research Center is actively standardizing collision avoidance technologies. This initiative aims to improve safety requirements, positively impacting the market with updated standards expected to be fully implemented by 2023.
Investment Opportunities in the China Advanced Vehicle Collision Avoidance Technologies Market
Below are the investment opportunities with the strongest case in the China Advanced Vehicle Collision Avoidance Technologies Market.
- Demand from Urban Consumers: Urban consumers are increasingly prioritising advanced safety features in their vehicles. With over 50% of new passenger vehicles expected to incorporate these systems by 2023, manufacturers can leverage this trend by collaborating with local suppliers.
- Investment in R&D for Safety Technologies: The automotive industry is poised to invest heavily in R&D for advanced safety technologies. With the automotive safety market projected to reach 200 billion yuan by 2025, opportunities for joint ventures with research institutions are abundant.
- Expansion in Guangdong Province: Guangdong province stands out as a leading hub for automotive manufacturing, offering opportunities for suppliers of collision avoidance technologies. By focusing on integrating advanced safety features, local partnerships can facilitate market entry.
- Government Subsidy Programs: The government’s subsidy programme for electric vehicles that incorporate advanced safety features presents investment opportunities. By collaborating with local manufacturers, suppliers can access these subsidies and strengthen their market presence.
Government Initiatives in the China Advanced Vehicle Collision Avoidance Technologies Market
The '14th Five-Year Plan for the Development of the Automotive Industry' launched in 2021 highlights safety technologies, particularly collision avoidance systems. This plan encourages manufacturers to invest in advanced safety features, aligning with national safety objectives. The Ministry of Industry and Information Technology (MIIT) backs these initiatives, aiming for widespread adoption of safety technologies in vehicles. Additionally, the updated National Standard GB/T 34590-2017, revised in 2022, imposes stricter regulations on manufacturers, compelling compliance with new safety requirements.
The National Intelligent Transportation System Development Plan (2021-2025) initiated by the Ministry of Transport promotes the integration of collision avoidance technologies in vehicles. This plan facilitates funding for research and development projects focused on improving vehicle safety. The National Development and Reform Commission (NDRC) allocated 500 million yuan in 2023 for automotive safety technology research, supporting manufacturers in adopting advanced safety features. Furthermore, the China Automotive Technology and Research Center (CATARC) plays a crucial role in standardising safety technologies, ensuring compliance among manufacturers.
Future Insight of the China Advanced Vehicle Collision Avoidance Technologies Market
Several forward-looking factors are set to boost the China Advanced Vehicle Collision Avoidance Technologies market in the coming years. The government's subsidy programme for electric vehicles featuring advanced safety technologies will stimulate consumer interest and purchasing. Initiatives from the National Development and Reform Commission will encourage the development of smart vehicle technologies, promoting further innovation. By 2023, urban areas are expected to see over half of new passenger vehicles equipped with collision avoidance systems, indicating a strong shift towards improved road safety.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Advanced Vehicle Collision Avoidance Technologies Market – Automatic Emergency Braking (AEB) Dominated, Lane Departure Warning Systems Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, the largest advanced vehicle collision avoidance technologies market category in 2025 was Automatic Emergency Braking (AEB), with a 44% share of total revenue. Automatic Emergency Braking (AEB) holds the largest market share due to its critical role in accident prevention, with a reported 30% increase in adoption in 2022. This technology is widely embraced by both manufacturers and consumers for its proven effectiveness in enhancing vehicle safety. Lane Departure Warning Systems are set to record the highest CAGR in this split, 9.1% over 2026–2032. Lane Departure Warning Systems are rapidly gaining traction, bolstered by government subsidies for electric vehicles that incorporate advanced safety features. This financial backing is expected to significantly boost adoption rates and improve overall road safety standards. Suppliers should prioritise the integration of advanced safety technologies to meet the growing demand in the automotive sector.
By Technology Type – AI-Based Dominated, LIDAR/GPS Enabled Expected to Grow Fastest
AI-Based took a 41% share of technology type in 2025, more than any other category. AI-Based technologies lead the market share as they employ sophisticated algorithms for predictive safety measures, essential for modern vehicle systems. Their increasing demand reflects manufacturers' focus on enhancing vehicle safety features. LIDAR/GPS Enabled is projected to grow fastest, at a CAGR of 9.8% during 2026–2032. LIDAR/GPS Enabled systems are experiencing swift growth due to their ability to provide precise spatial awareness, crucial for navigation in complex environments. As urbanisation continues, the demand for these technologies is likely to rise significantly. Buyers should invest in LIDAR/GPS Enabled technologies to ensure enhanced safety and compliance with evolving standards.
By Detection Method – Camera + Radar Dominated, Sensor Fusion Expected to Grow Fastest
In 2025, Camera + Radar led the detection method split with a 41% share. Camera + Radar systems dominate the market share as they combine multiple technologies for improved detection capabilities, vital for vehicle safety. Their prevalent use in new vehicle models underscores their importance in collision avoidance strategies. Over 2026–2032, Sensor Fusion is expected to post the fastest growth, at a CAGR of 8.9%. Sensor Fusion is rapidly gaining popularity as it integrates data from various sensors for accurate environment mapping, essential for modern vehicle safety. This method's effectiveness in enhancing safety metrics will drive its adoption in the near future. Suppliers should focus on developing Sensor Fusion technologies to align with market trends and consumer safety expectations.
By Integration Type – OEM-Integrated Dominated, Aftermarket & OEM Expected to Grow Fastest
With a 46% revenue share in 2025, OEM-Integrated was the largest integration type category. OEM-Integrated systems capture the largest market share as they are incorporated into vehicles during manufacturing, ensuring widespread adoption among new models. This integration is crucial for meeting safety regulations and fulfilling consumer expectations. The quickest growth will come from Aftermarket & OEM, forecast to expand at a CAGR of 9.3% between 2026 and 2032. Aftermarket & OEM solutions are witnessing the fastest growth as they provide options for installation in existing vehicles, thereby broadening market reach. This flexibility allows consumers to enhance their vehicles with advanced safety features easily. Suppliers must consider both OEM-Integrated and aftermarket solutions to cater to diverse consumer needs in the automotive market.
By Vehicle Segment – Passenger Cars Dominated, SUVs & Sedans Expected to Grow Fastest
Passenger Cars accounted for a 41% market share by vehicle segment in 2025. Passenger Cars hold the largest market share as they are the primary segment for collision avoidance technologies, driven by significant consumer demand for enhanced safety features. This segment's growth is supported by the increasing production of vehicles equipped with advanced systems. SUVs & Sedans are set to record the highest CAGR in this split, 10.0% over 2026–2032. SUVs & Sedans are experiencing the fastest growth due to their rising popularity and the growing adoption of safety technologies among consumers. This trend reflects a shift in consumer preferences towards vehicles that prioritise safety features. Suppliers should focus on developing collision avoidance technologies specifically tailored for the expanding SUV and Sedan segments to capitalise on this trend.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Advanced Vehicle Collision Avoidance Technologies Market Outlook
- Market Size of China Advanced Vehicle Collision Avoidance Technologies Market, 2025
- Forecast of China Advanced Vehicle Collision Avoidance Technologies Market, 2032
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Revenues & Volume for the Period 2022 - 2032F
- China Advanced Vehicle Collision Avoidance Technologies Market Trend Evolution
- China Advanced Vehicle Collision Avoidance Technologies Market Drivers and Challenges
- China Advanced Vehicle Collision Avoidance Technologies Price Trends
- China Advanced Vehicle Collision Avoidance Technologies Porter's Five Forces
- China Advanced Vehicle Collision Avoidance Technologies Industry Life Cycle
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Advanced Vehicle Collision Avoidance Technologies Market for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Forward Collision Warning (FCW) for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Automatic Emergency Braking (AEB) for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Lane Departure Warning Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Blind Spot Detection Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Technology Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Vision-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By AI-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By LIDAR/GPS Enabled for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Radar-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Detection Method for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Camera + Radar for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Sensor Fusion for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Road Edge Detection for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Side Monitoring Sensors for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Integration Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By OEM-Integrated for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Aftermarket & OEM for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By In-Vehicle Module for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Mirror Integration for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Vehicle Segment for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Passenger Cars for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By SUVs & Sedans for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Commercial Fleets for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Vehicle Collision Avoidance Technologies Market Revenues & Volume By Luxury Vehicles for the Period 2022 - 2032F
- China Advanced Vehicle Collision Avoidance Technologies Import Export Trade Statistics
- Market Opportunity Assessment By Advanced Vehicle Collision Avoidance Technologies Market
- Market Opportunity Assessment By Technology Type
- Market Opportunity Assessment By Detection Method
- Market Opportunity Assessment By Integration Type
- Market Opportunity Assessment By Vehicle Segment
- China Advanced Vehicle Collision Avoidance Technologies Top Companies Market Share
- China Advanced Vehicle Collision Avoidance Technologies Competitive Benchmarking By Technical and Operational Parameters
- China Advanced Vehicle Collision Avoidance Technologies Company Profiles
- China Advanced Vehicle Collision Avoidance Technologies Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Advanced Vehicle Collision Avoidance Technologies Market
- Forward Collision Warning (FCW)
- Automatic Emergency Braking (AEB)
- Lane Departure Warning Systems
- Blind Spot Detection Systems
By Technology Type
- Vision-Based
- AI-Based
- LIDAR/GPS Enabled
- Radar-Based
By Detection Method
- Camera + Radar
- Sensor Fusion
- Road Edge Detection
- Side Monitoring Sensors
By Integration Type
- OEM-Integrated
- Aftermarket & OEM
- In-Vehicle Module
- Mirror Integration
By Vehicle Segment
- Passenger Cars
- SUVs & Sedans
- Commercial Fleets
- Luxury Vehicles






































