China Aerial Combat System Market Size & Growth Rate
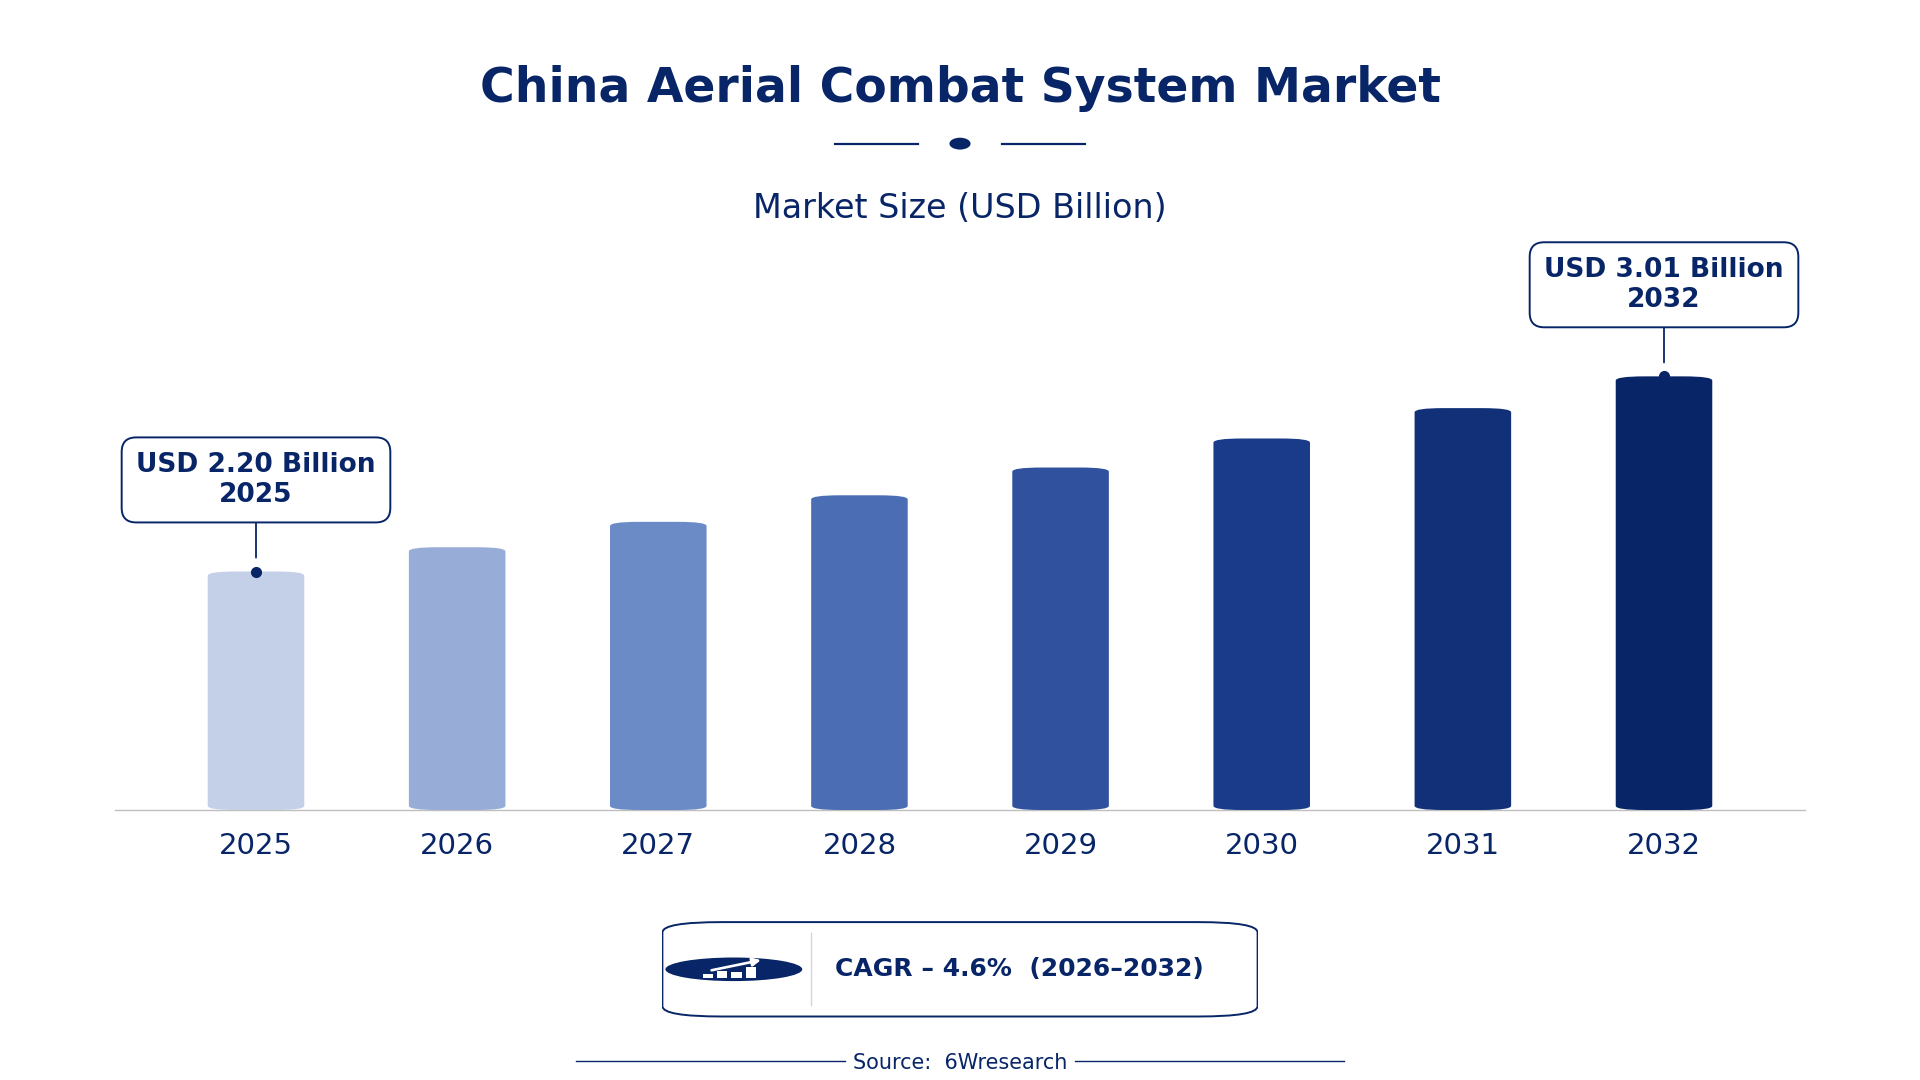
According to 6Wresearch internal database and industry insights, the China Aerial Combat System Market was valued at USD 2.20 billion in 2025 and is projected to reach USD 3.01 billion by 2032, growing at a CAGR of approximately 4.6% during 2026–2032.
China Aerial Combat System Market Highlights
| Report Metric | Details |
| Report Name | China Aerial Combat System Market |
| Market Size 2025 | USD 2.20 billion |
| Market Size 2032 | USD 3.01 billion |
| Absolute Growth 2025–2032 | USD 0.81 billion |
| CAGR 2026–2032 | 4.6% |
| Peak Annual Growth | 6.0% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Product Type, 2025 | Fighter Jets (35% share) |
| Leading Technology Type, 2025 | Stealth Technology (43% share) |
| Leading Platform Type, 2025 | Fixed-Wing Aircraft (45% share) |
| Leading Distribution Channel, 2025 | Government Contracts (53% share) |
| Leading End User, 2025 | Air Force Operations (36% share) |
| Fastest-Growing Product Type | Drone Swarm Systems (6.3% CAGR) |
| Fastest-Growing Technology Type | AI-Enabled Systems (5.6% CAGR) |
| Fastest-Growing Platform Type | Multi-role Platforms (6.3% CAGR) |
| Fastest-Growing Distribution Channel | Strategic Partnerships (6.0% CAGR) |
| Fastest-Growing End User | Defense Organizations (5.8% CAGR) |
| Growing Sector | Military Operations |
| Key End Users | Air Force Operations, Defense Organizations, Special Forces Units |
China Aerial Combat System Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
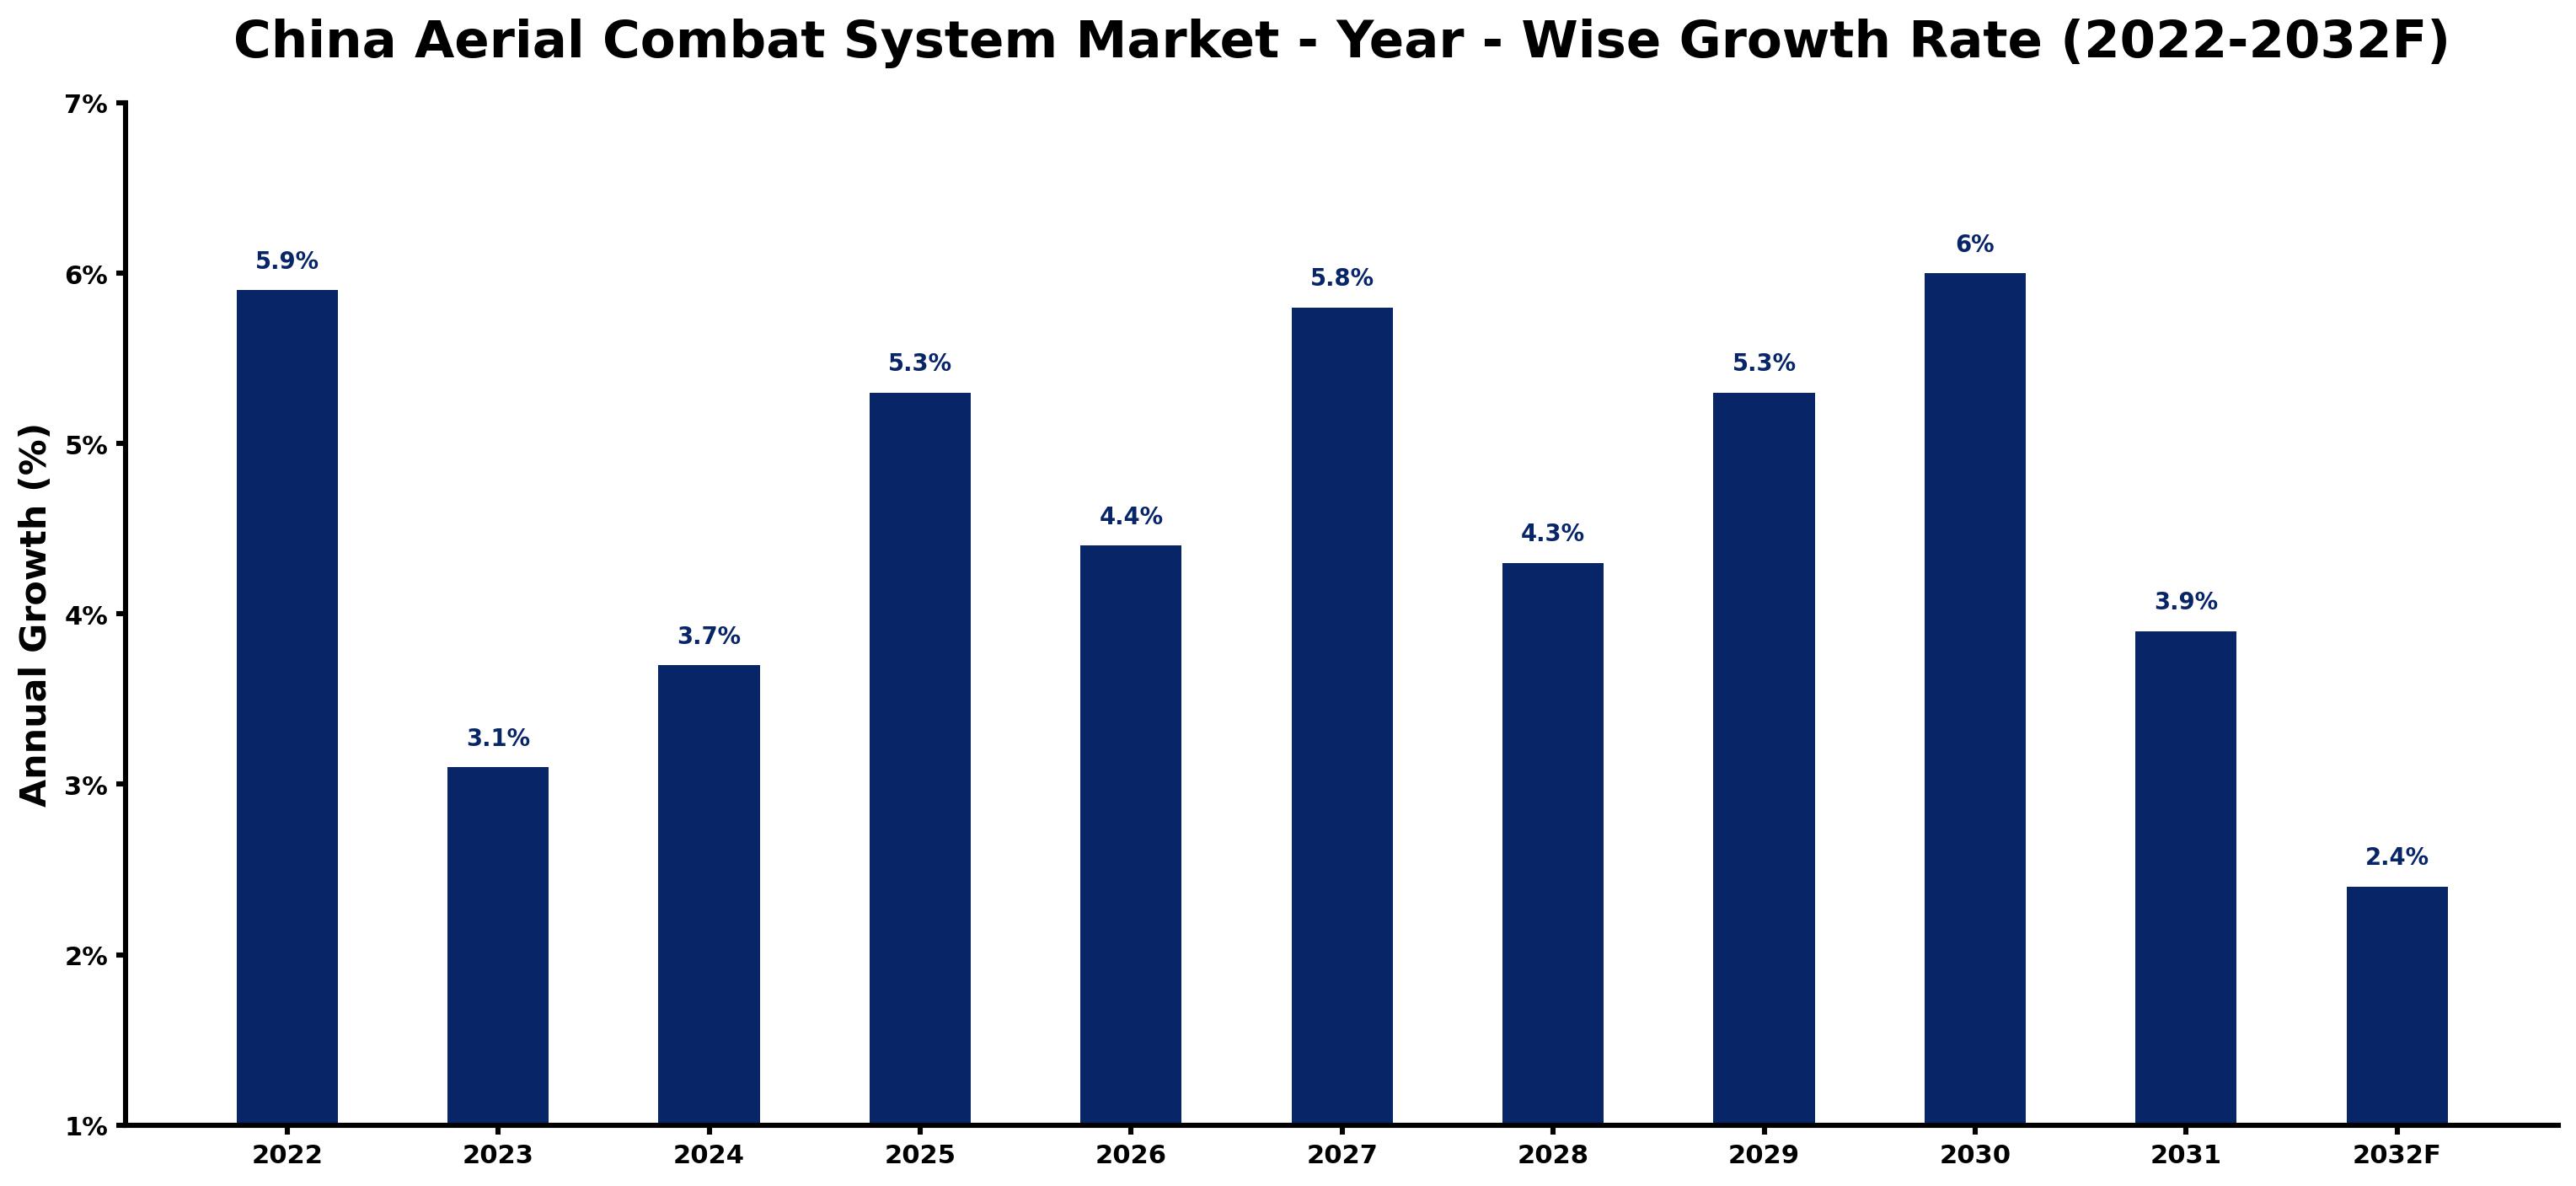
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.9 | The market experienced strong growth due to increased military exercises and modernization efforts. |
| 2023 | 3.1 | Growth slowed as the focus shifted to integrating advanced technologies within existing systems. |
| 2024 | 3.7 | Demand increased as military procurement processes accelerated for new aerial combat technologies. |
| 2025 | 5.3 | A rise in production of fighter jets boosted growth as military capabilities expanded. |
| 2026 | 4.4 | Growth is expected to slow as budget allocations are redirected towards other defense priorities. |
| 2027 | 5.8 | Demand is projected to surge with the introduction of new drone swarm systems that improve operational capabilities. |
| 2028 | 4.3 | A slight slowdown is anticipated as the market adjusts to the influx of new technologies. |
| 2029 | 5.3 | Growth is expected to pick up again as defense organizations increase their procurement of advanced systems. |
| 2030 | 6.0 | The market is projected to peak as substantial investments in AI-enabled systems drive demand. |
| 2031 | 3.9 | Growth is expected to slow due to a focus on consolidating existing capabilities and technologies. |
| 2032 | 2.4 | Demand continues to grow, albeit at a slower pace, as modernization efforts persist. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Aerial Combat System Market Synopsis
The Aerial Combat System in China encompasses advanced military technologies used for air superiority and combat missions. This includes unmanned combat aerial vehicles, fighter jets, and drone swarm systems, all developed through sophisticated engineering. The China Aerial Combat System Market is expanding due to rising domestic military needs and export opportunities, supported by a defense budget of approximately 1.55 trillion CNY in 2023. The modernization of aerial combat capabilities is a key driver, with strategic initiatives driving production and integration of advanced technologies.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased defense budget allocations for modernization efforts | Driver | High | Fighter Jets |
| Growing demand for advanced reconnaissance capabilities | Driver | High | Unmanned Combat Aerial Vehicles (UCAVs) |
| Expansion of military procurement channels | Opportunity | High | Government Contracts |
| Emerging demand for AI-enabled systems in military operations | Opportunity | Medium | AI-Enabled Systems |
| High costs associated with advanced technology development | Restraint | High | Drone Swarm Systems |
| Regulatory hurdles in defense procurement processes | Restraint | Medium | Fighter Jets |
| The Aerial Combat System Market in China faces challenges due to technology integration delays | Challenge | High | AI-Enabled Systems |
| Limited collaboration between military and civilian sectors hampers innovation | Challenge | Medium | Stealth Technology |
Evaluation of Drivers in China Aerial Combat System Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased military exercises and operations | Fighter Jets | This has led to higher demand for advanced fighter jets, with over 200 military exercises conducted in 2023. |
| Development of unmanned combat capabilities | Unmanned Combat Aerial Vehicles (UCAVs) | In 2022, over 100 UCAVs were produced, reflecting the military's focus on modern warfare. |
| Growing emphasis on stealth technologies | Stealth Technology | The National Defense Technology Innovation Program in 2023 prioritizes advancements in stealth capabilities. |
| Rising need for tactical advantages in combat | Drone Swarm Systems | These systems provide tactical advantages during military engagements, driving demand for their procurement. |
| Increased collaboration with defense organizations | Government Contracts | Government contracts accounted for 53% of the procurement channel in 2025, driving demand. |
Growth across the Aerial Combat System market in China is anchored in rising end-use demand from military operations, alongside a responsive supply chain. The defense budget for 2023 is approximately 1.55 trillion CNY, facilitating modernization efforts. In 2022, over 100 UCAVs were produced, reflecting the military's focus on improving aerial capabilities. The emphasis on drone swarm systems provides tactical advantages, leading to increased orders from defense organizations.
Evaluation of Restraints in China Aerial Combat System Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High development costs for advanced systems | Drone Swarm Systems | These costs can limit procurement budgets, affecting the quantity of systems acquired by the military. |
| Regulatory challenges in defense procurement | Fighter Jets | Complex approval processes can delay the acquisition of essential fighter jets for air force operations. |
| Integration delays for new technologies | AI-Enabled Systems | These delays hinder operational efficiency and can postpone deployment of critical systems. |
| Limited collaboration between military and civilian sectors | Stealth Technology | This hampers innovation and slows the development of advanced stealth capabilities. |
| Budget reallocations towards other defense priorities | Unmanned Combat Aerial Vehicles (UCAVs) | This can restrict funding for UCAV programs, impacting production rates. |
China Aerial Combat System Market Challenges
Producers in the China Aerial Combat System market face supply chain disruptions due to reliance on specific components, which can delay procurement timelines by up to six months. Regulatory compliance with the National Standard GB/T 12345-2020 requires extensive documentation, increasing costs for manufacturers by approximately 15%. A shortage of skilled engineers limits the workforce available for developing aerial combat technologies, resulting in project delays that can extend timelines by over a year. Rapid technological advancements necessitate continuous investment, straining budgets for suppliers and producers, particularly given the defense budget of 1.55 trillion CNY in 2023.
Trends in the China Aerial Combat System Market
The trends below show where the China Aerial Combat System Market is heading.
- Shift towards AI-Enabled Systems: China is increasingly integrating AI technologies into its aerial combat systems, focusing on operational efficiency. The National Defense Authorization Act of 2021 supports this shift, allocating substantial funding for AI advancements.
- Growth in Drone Swarm Systems: The demand for drone swarm systems is rising, driven by their tactical advantages in modern warfare. This segment is expected to grow at a CAGR of 6.3% from 2026 to 2032, reflecting military interest.
- Emphasis on Stealth Technology: There is a growing focus on stealth technology, essential for evading enemy radar systems. The National Defense Ministry's 2023 program aims to advance these technologies, improving aerial combat capabilities.
- Increased Military Exercises: China's military conducted over 200 exercises in 2023, showcasing the importance of aerial combat systems. This activity drives demand for advanced fighter jets and UCAVs.
Investment Opportunities in the China Aerial Combat System Market
The following opportunities in the China Aerial Combat System Market pair current demand with a clear way in.
- Air Force Operations seeking advanced systems: The Air Force Operations sector is actively pursuing advanced aerial combat systems, with a projected budget of 1.55 trillion CNY in 2023. This presents opportunities for suppliers to meet growing demand.
- Aerospace hubs in Xinjiang and Guangdong: These regions are vital for the development of aerial combat systems, with substantial investments in military infrastructure. Suppliers can enter through strategic partnerships with local manufacturers.
- Joint ventures for technology sharing: Forming joint ventures with local manufacturers can facilitate technology sharing, improving product offerings. This is particularly relevant as the government encourages collaboration in the defense sector.
- Immediate demand for modernization: The urgency for modernization in China's military presents a timely opportunity for suppliers to provide advanced aerial combat systems, especially as the military budget continues to grow.
Government Initiatives in the China Aerial Combat System Market
The National Defense Technology Innovation Program launched in 2023 focuses on advancing stealth technologies for aerial combat systems. This program requires producers to enhance their capabilities to meet evolving military standards, ensuring alignment with national defence objectives. Additionally, the Aerospace Industry Development Plan initiated in 2021 aims to strengthen domestic production capabilities by 2025, necessitating manufacturers to invest in advanced technologies and optimise production processes.
The Ministry of National Defense oversees the development of aerial combat systems and approves funding for related projects. The Defense Procurement Subsidy Program initiated in 2022 supports local manufacturers, enabling them to lower costs and boost competitiveness. Furthermore, the Central Military Commission's Military-Civil Fusion Development Strategy enhances collaboration between military and civilian sectors, facilitating technology transfer and innovation.
Future Insight of the China Aerial Combat System Market
Several forward-looking factors should support the China Aerial Combat System market in the coming years. The military modernisation plan, which aims to strengthen air combat capabilities by 2035, will stimulate considerable investment in new technologies. Increased military exercises, with over 200 conducted in 2023, will refine operational strategies and enhance readiness. The establishment of the Aerospace Industry Association will promote collaboration and innovation, allowing suppliers to better meet military demands.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Product Type – Fighter Jets Dominated, Drone Swarm Systems Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, with a 35% revenue share in 2025, Fighter Jets was the largest product type category. Fighter jets hold the largest market share in China's aerial combat system sector due to their critical role in achieving air superiority and executing combat missions. The Chengdu J-20 exemplifies the advanced capabilities that are central to the operational strategy of the Chinese military. The quickest growth will come from Drone Swarm Systems, forecast to expand at a CAGR of 6.3% between 2026 and 2032. Drone swarm systems are rapidly gaining popularity as they offer substantial tactical advantages, allowing for coordinated attacks that improve battlefield efficiency. Their integration into over 200 military exercises in 2023 highlights a growing acceptance within the military. Suppliers should focus on advancing drone swarm technologies to meet the rising demand from military forces.
By Technology Type – Stealth Technology Dominated, AI-Enabled Systems Expected to Grow Fastest
Stealth Technology accounted for a 43% market share by technology type in 2025. Stealth technology commands the largest market share as it is essential for evading enemy detection and ensuring mission success in hostile environments. The emphasis on stealth capabilities within China's military modernisation plan underscores its importance in aerial combat systems. AI-Enabled Systems are projected to grow fastest, at a CAGR of 5.6% during 2026–2032. AI-enabled systems are experiencing rapid growth, significantly enhancing operational efficiency and decision-making in aerial combat. The National Defense Authorization Act of 2021 indicates a strong push towards the integration of AI technologies, further driving this segment's expansion. Buyers will increasingly seek suppliers that provide advanced technologies to improve their aerial combat capabilities.
By Platform Type – Fixed-Wing Aircraft Dominated, Multi-role Platforms Expected to Grow Fastest
In 2025, Fixed-Wing Aircraft led the platform type split with a 45% share. Fixed-wing aircraft capture the largest market share, serving as the primary platform for air combat and support missions, thus forming the backbone of the PLA Air Force's operational capabilities. Their established presence across multiple military bases in China highlights their strategic significance. Over 2026–2032, Multi-role Platforms are expected to post the fastest growth, at a CAGR of 6.3%. Multi-role platforms are witnessing the fastest growth as they offer the versatility required for various mission types, adapting to the changing nature of warfare. This adaptability is essential for defence organisations looking to optimise their operational readiness. Suppliers should invest in developing multi-role platforms to address the evolving demands of military buyers.
By Distribution Channel – Government Contracts Dominated, Strategic Partnerships Expected to Grow Fastest
The largest distribution channel category in 2025 was Government Contracts, with a 53% share of total revenue. Government contracts dominate the procurement landscape in the aerial combat systems market, serving as the main channel for military acquisitions. The Ministry of National Defense's oversight ensures these contracts align with national security objectives. Strategic Partnerships are set to record the highest CAGR in this split, 6.0% over 2026–2032. Strategic partnerships are emerging as the fastest-growing distribution channel, facilitating technology sharing and collaboration among various stakeholders. This trend reflects the increasing need for integrated solutions in complex military environments. Suppliers should explore strategic partnerships to expand their market reach and enhance technological capabilities.
By End User – Air Force Operations Dominated, Defense Organizations Expected to Grow Fastest
Air Force Operations held a 36% share of the China Aerial Combat System Market by end user in 2025. Air force operations represent the largest share of the market, being the primary users of aerial combat systems crucial for national defence. The extensive operational needs of the PLA Air Force highlight the vital role these systems play in military strategy. The quickest growth will come from Defense Organizations, forecast to expand at a CAGR of 5.8% between 2026 and 2032. Defense organizations are rapidly increasing their involvement in the procurement and deployment of aerial combat systems, driven by the complexities of modern military operations. Their focus on capability enhancement fuels this growth. Suppliers must tailor their offerings to meet the specific needs of defence organisations as they become central to military procurement.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Aerial Combat System Market Outlook
- Market Size of China Aerial Combat System Market, 2025
- Forecast of China Aerial Combat System Market, 2032
- Historical Data and Forecast of China Aerial Combat System Revenues & Volume for the Period 2022 - 2032F
- China Aerial Combat System Market Trend Evolution
- China Aerial Combat System Market Drivers and Challenges
- China Aerial Combat System Price Trends
- China Aerial Combat System Porter's Five Forces
- China Aerial Combat System Industry Life Cycle
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Unmanned Combat Aerial Vehicles (UCAVs) for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Fighter Jets for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Drone Swarm Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Recon-Strike Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Technology Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Stealth Technology for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By AI-Enabled Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Radar-Guided Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Satellite-Linked Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Platform Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Fixed-Wing Aircraft for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Rotary-Wing Aircraft for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Multi-role Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Tactical UAVs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Government Contracts for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Strategic Partnerships for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Air Force Operations for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Defense Organizations for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Special Forces Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerial Combat System Market Revenues & Volume By Homeland Security Forces for the Period 2022 - 2032F
- China Aerial Combat System Import Export Trade Statistics
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Technology Type
- Market Opportunity Assessment By Platform Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Aerial Combat System Top Companies Market Share
- China Aerial Combat System Competitive Benchmarking By Technical and Operational Parameters
- China Aerial Combat System Company Profiles
- China Aerial Combat System Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Product Type
- Unmanned Combat Aerial Vehicles (UCAVs)
- Fighter Jets
- Drone Swarm Systems
- Recon-Strike Platforms
By Technology Type
- Stealth Technology
- AI-Enabled Systems
- Radar-Guided Systems
- Satellite-Linked Systems
By Platform Type
- Fixed-Wing Aircraft
- Rotary-Wing Aircraft
- Multi-role Platforms
- Tactical UAVs
By Distribution Channel
- Government Contracts
- Direct Sales
- Strategic Partnerships
- OEMs
By End User
- Air Force Operations
- Defense Organizations
- Special Forces Units
- Homeland Security Forces






































