China Aerospace Actuation Market Size & Growth Rate
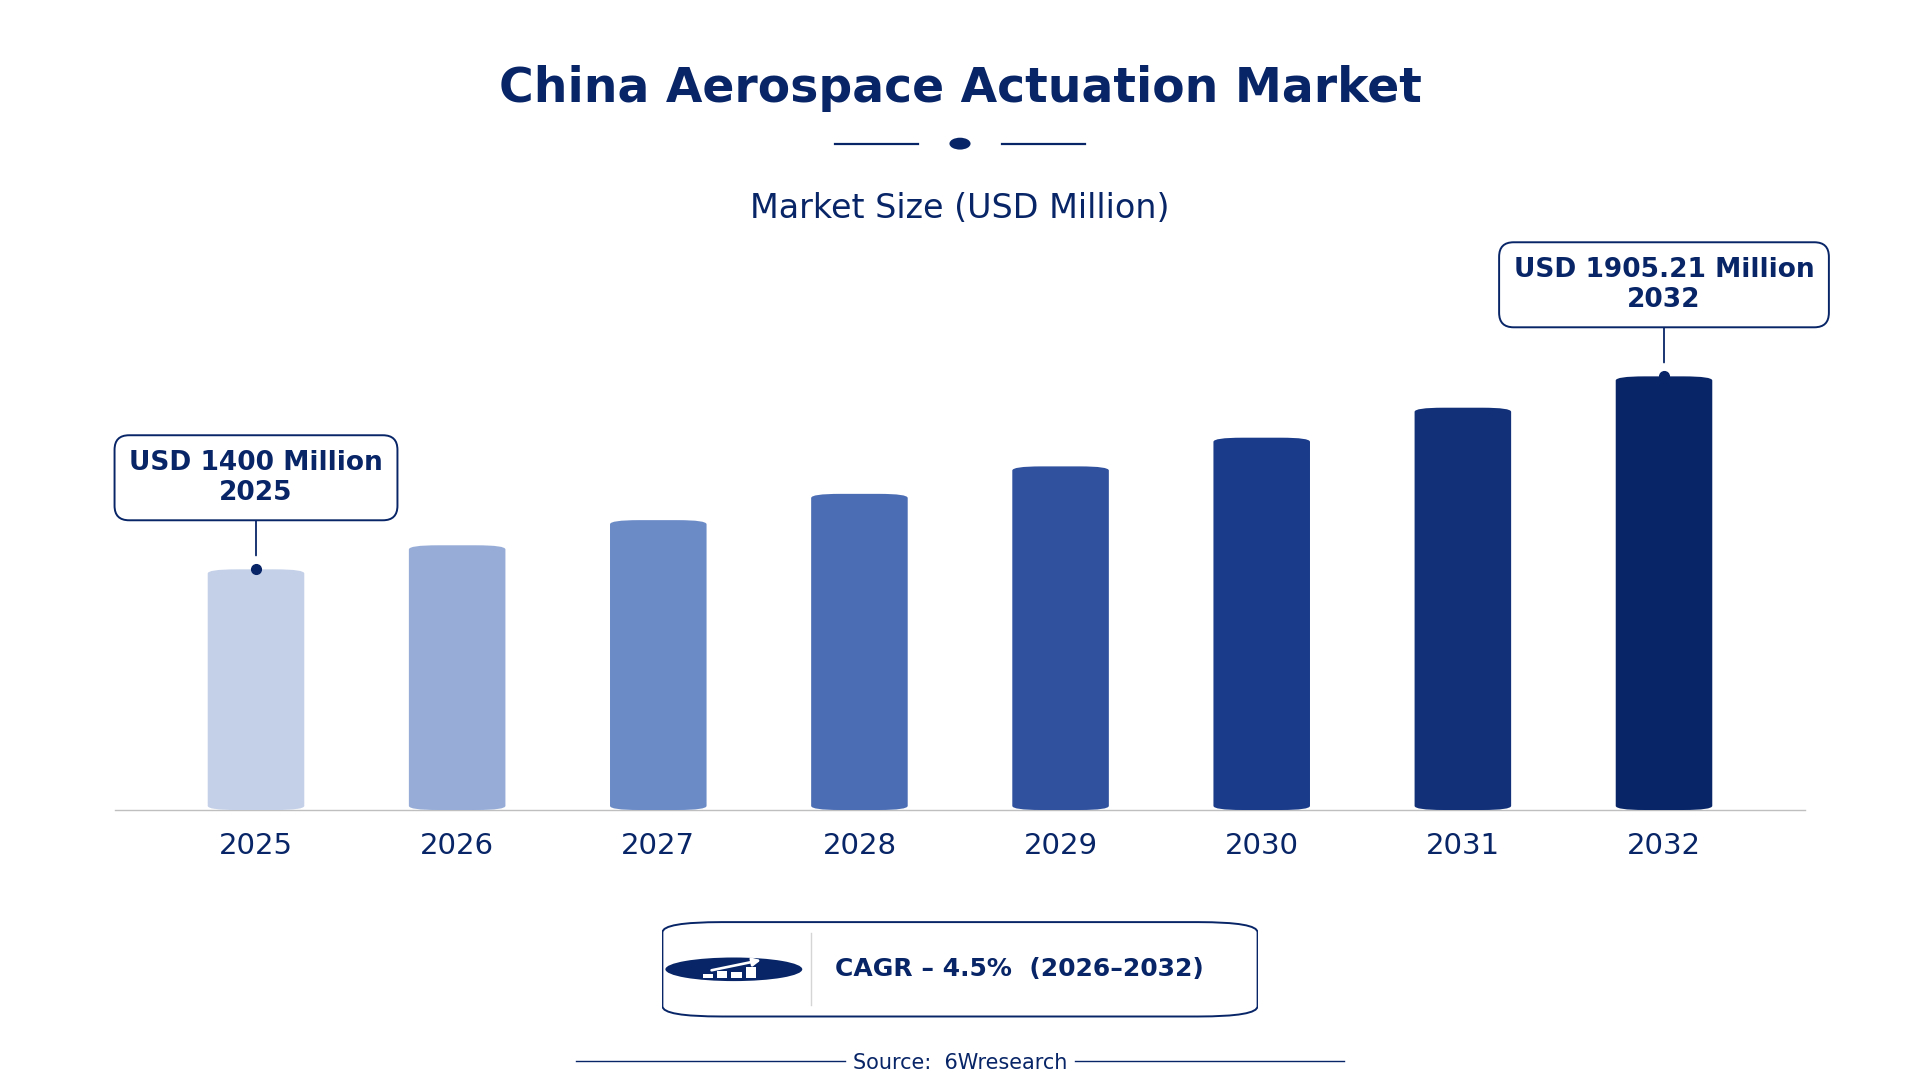
According to 6Wresearch internal database and industry insights, the China Aerospace Actuation Market was valued at USD 1,400 million in 2025 and is projected to reach USD 1,905.21 million by 2032, growing at a CAGR of approximately 4.5% during 2026–2032.
China Aerospace Actuation Market Highlights
| Report Metric | Details |
| Report Name | China Aerospace Actuation Market |
| Market Size 2025 | USD 1,400 million |
| Market Size 2032 | USD 1,905.21 million |
| Absolute Growth 2025–2032 | USD 505.21 million |
| CAGR 2026–2032 | 4.5% |
| Peak Annual Growth | 6.5% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Product Type, 2025 | Linear Actuators (39% share) |
| Leading Actuation Mechanism, 2025 | Electric (46% share) |
| Leading Application Area, 2025 | Landing Gear Systems (46% share) |
| Leading Distribution Channel, 2025 | OEMs (47% share) |
| Leading End User, 2025 | Aircraft Manufacturers (45% share) |
| Fastest-Growing Product Type | Electro-Mechanical Actuators (6.9% CAGR) |
| Fastest-Growing Actuation Mechanism | Servo-Driven (7.1% CAGR) |
| Fastest-Growing Application Area | Wing Control Surfaces (6.1% CAGR) |
| Fastest-Growing Distribution Channel | Government Contracts (6.0% CAGR) |
| Fastest-Growing End User | Military Aerospace (6.5% CAGR) |
| Growing Sector | Military Aerospace |
| Key End Users | Aircraft Manufacturers, Military Aerospace, Commercial Aviation |
China Aerospace Actuation Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
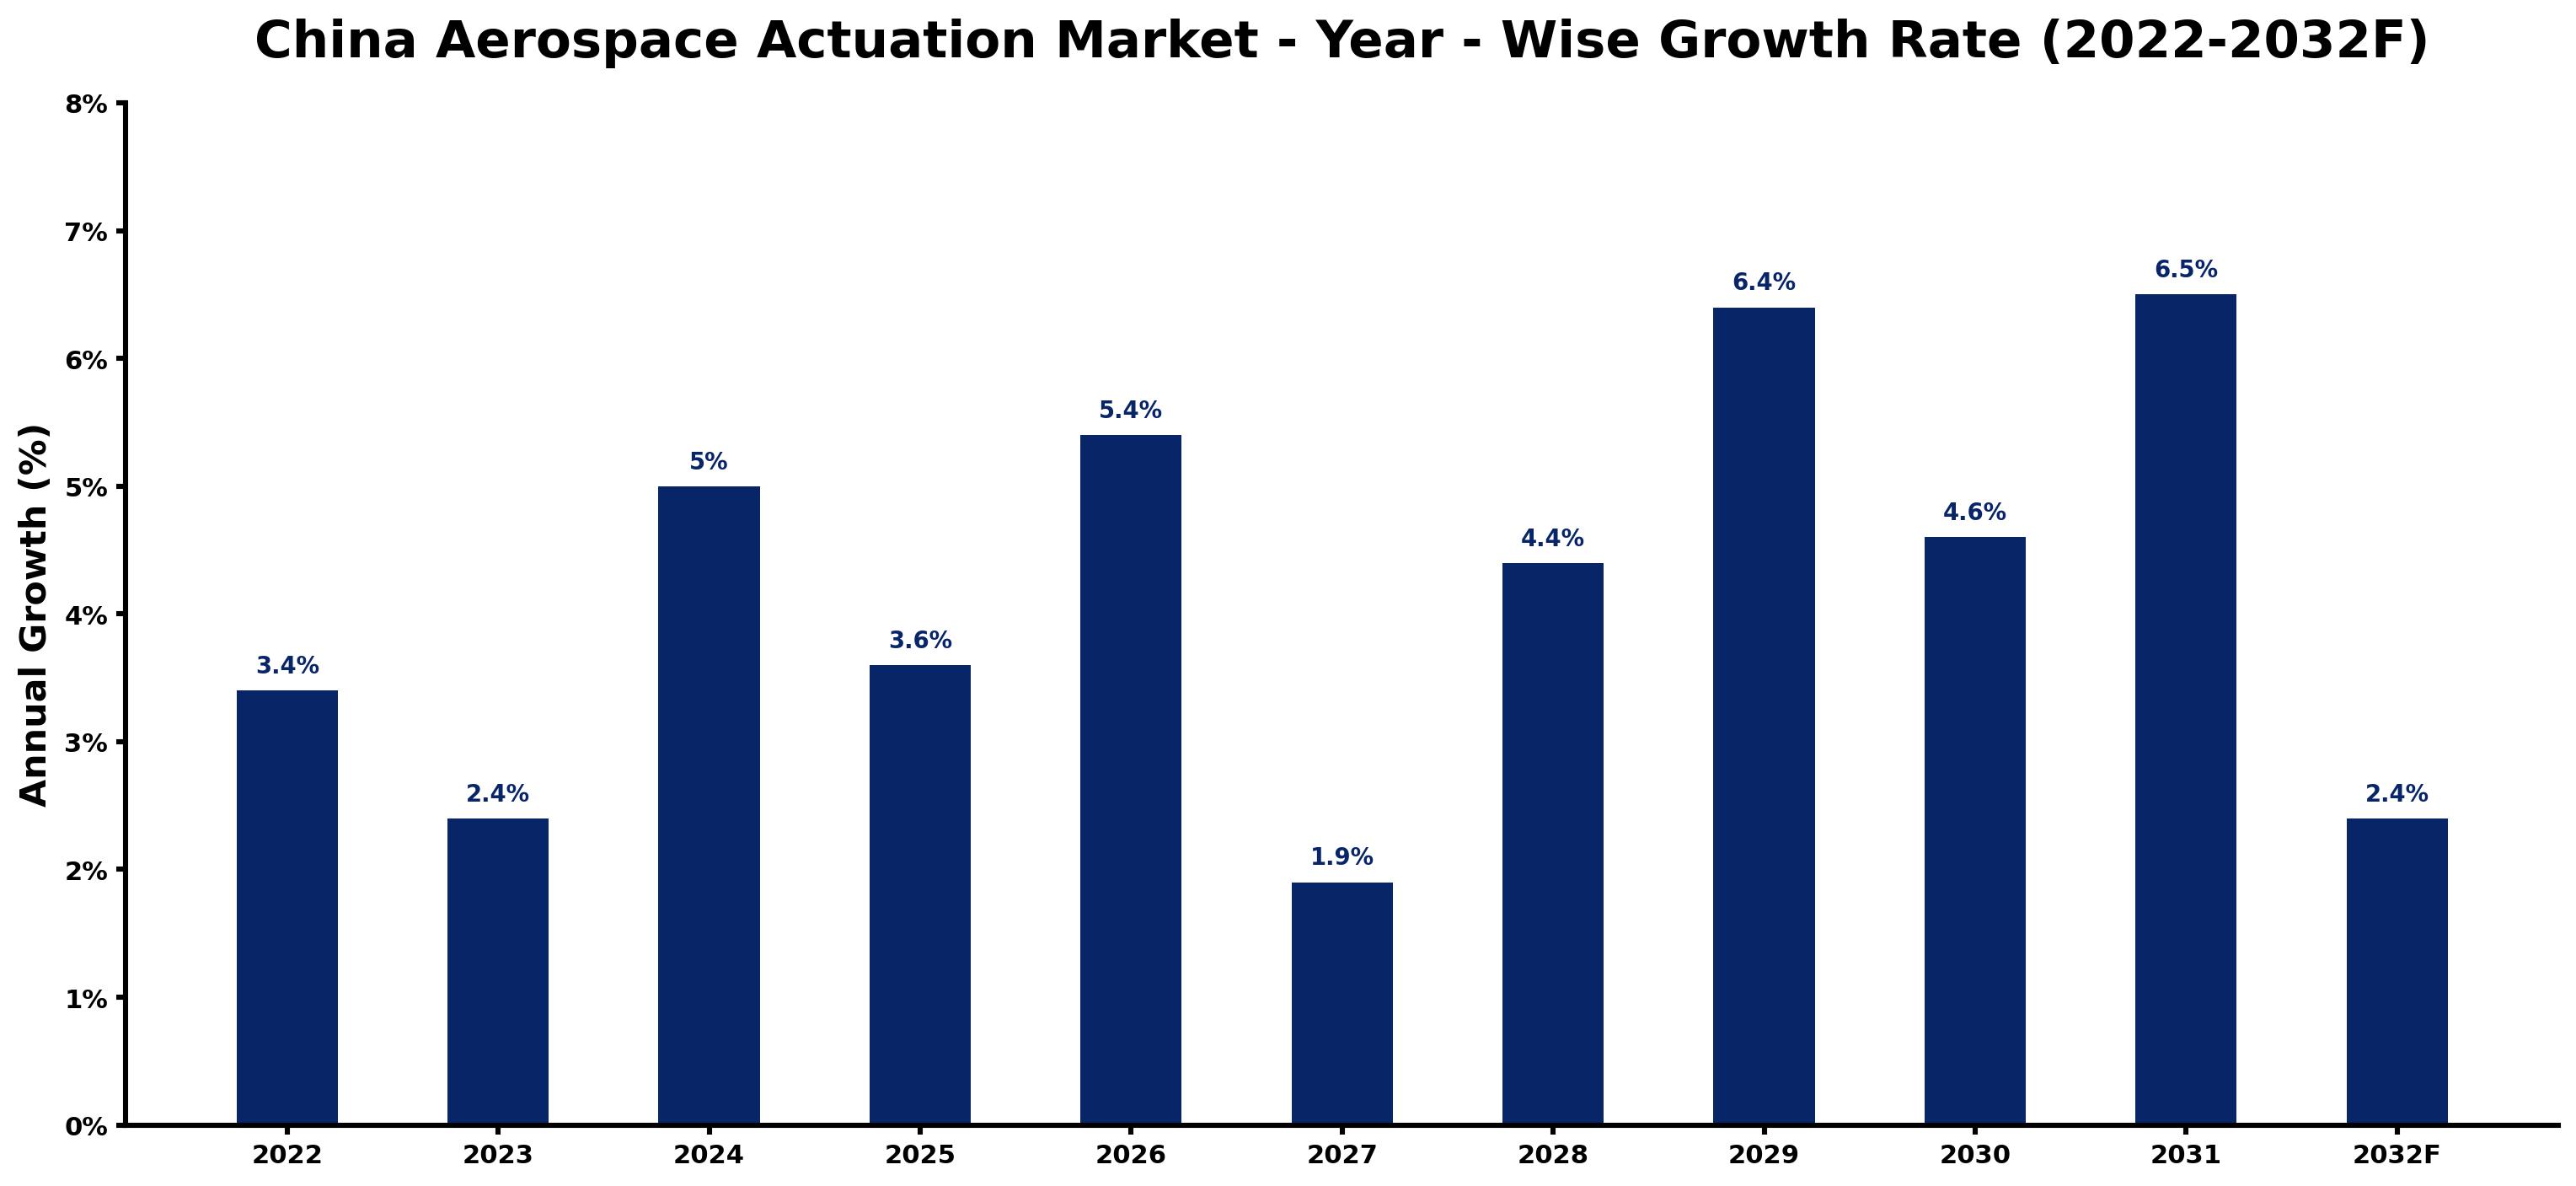
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.4 | The market experienced steady growth due to increasing domestic demand from military and commercial aviation sectors. |
| 2023 | 2.4 | Growth slowed as the market adjusted to the impacts of global supply chain disruptions affecting production timelines. |
| 2024 | 5.0 | Demand surged as the military aerospace segment benefitted from the Ministry of National Defense's modernization plan. |
| 2025 | 3.6 | Growth slowed again as the aerospace sector faced production challenges linked to material shortages. |
| 2026 | 5.4 | A recovery in demand is expected, driven by rising production targets for commercial aircraft set by the government. |
| 2027 | 1.9 | Growth is projected to slow as the market faces challenges in meeting high-quality standards required by regulations. |
| 2028 | 4.4 | Demand is expected to increase due to advancements in aerospace technology and production efficiency improvements. |
| 2029 | 6.4 | A surge in demand is projected as military contracts expand, boosting procurement of actuation systems under government initiatives. |
| 2030 | 4.6 | Growth is anticipated to slow as the market adjusts to new regulatory requirements impacting production. |
| 2031 | 6.5 | Demand is expected to peak with increased investments in aerospace technology and infrastructure development. |
| 2032 | 2.4 | Growth is projected to slow as the market stabilises after reaching peak demand driven by production targets. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Aerospace Actuation Market Synopsis
The China Aerospace Actuation Market encompasses systems that control the movement of aircraft components, including landing gear and braking systems. These systems are crafted using advanced materials and precision engineering. The market is growing due to strong domestic demand from military and commercial aviation sectors. With over 200 civil aviation airports, the need for actuation systems is substantial. The country aims to produce 1,000 commercial aircraft annually by 2035, driving further demand for these systems.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising domestic demand from military and commercial aviation sectors drives the need for advanced actuation systems. | Driver | High | Commercial Aviation |
| The modernization plan by the Ministry of National Defense supports growth in military aerospace applications. | Driver | High | Military Aerospace |
| The increasing number of civil aviation airports creates opportunities for actuation system suppliers. | Opportunity | High | Linear Actuators |
| The push for advanced aerospace technologies opens avenues for innovation in actuation systems. | Opportunity | High | Linear Actuators |
| Compliance with ISO 9001 certification requirements can limit the number of eligible manufacturers. | Restraint | Medium | Linear Actuators |
| The high cost of advanced materials may restrict market entry for smaller manufacturers. | Restraint | Medium | Linear Actuators |
| Buyers face challenges in sourcing high-quality components due to stringent regulations. | Challenge | High | Linear Actuators |
| Suppliers encounter delays in production due to complex certification processes. | Challenge | High | Linear Actuators |
Evaluation of Drivers in China Aerospace Actuation Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased military spending on modernization initiatives boosts demand for actuation systems. | Military Aerospace | The Ministry of National Defense's 2021 plan aims to improve capabilities and requires advanced actuation systems, driving procurement. |
| Rising production targets for commercial aircraft drive demand for actuation systems. | Aircraft Manufacturers | China aims to produce 1,000 commercial aircraft annually by 2035, increasing the need for actuation systems significantly. |
| Technological advancements in aerospace manufacturing improve actuation system performance. | Electro-Mechanical Actuators | These systems are increasingly adopted for their efficiency and reliability in modern aircraft, leading to higher sales. |
| Growing demand for efficient actuation systems in commercial aviation supports market growth. | Commercial Aviation | The Chinese aviation market is projected to serve 1.6 billion passengers by 2035, necessitating more efficient aircraft systems. |
| The Aerospace Industry Development Plan encourages investment in domestic production capabilities. | Linear Actuators | Launched in 2020, this plan reduces reliance on imports, boosting local manufacturing and increasing market supply. |
Market growth for Aerospace Actuation in China is underpinned by rising domestic demand from military and commercial aviation sectors, alongside substantial investment in technology. With over 200 civil aviation airports, the need for actuation systems continues to grow, creating opportunities for suppliers. The projected increase in passenger traffic to 1.6 billion by 2035 drives the need for more efficient actuation solutions. The Aerospace Industry Development Plan promotes local production, reducing reliance on imports and strengthening the supply chain.
Evaluation of Restraints in China Aerospace Actuation Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with advanced materials limit market participation. | Linear Actuators | Manufacturers must invest heavily in materials that meet stringent aerospace standards, impacting pricing strategies. |
| Strict compliance with ISO 9001 certification can restrict the number of eligible suppliers. | Linear Actuators | This certification is mandatory for aerospace manufacturers, creating barriers for smaller firms to enter the market. |
| Complex certification processes delay product launches for suppliers. | Linear Actuators | Suppliers must navigate rigorous testing and approval pathways before market entry, which can extend lead times. |
| Limited availability of skilled workforce can hinder production capabilities. | Linear Actuators | The aerospace manufacturing industry employs over 600,000 people, but demand for skilled labour is high, impacting output. |
| Supply chain disruptions can impact timely delivery of components. | Linear Actuators | Global supply chain challenges have affected the availability of critical aerospace materials, delaying production schedules. |
China Aerospace Actuation Market Challenges
Buyers and suppliers in the China aerospace actuation market encounter fierce competition from both domestic and international sources, which compresses prices and diminishes profit margins for producers. Supply chain disruptions arise from reliance on imported specialised components, leading to production delays that can extend lead times by up to six months for manufacturers. Rapid technological advancements in aerospace actuation systems necessitate ongoing investment, yet many local producers struggle to keep pace, risking obsolescence and limiting their market opportunities. A shortage of skilled workers in precision engineering hampers production efficiency, increasing operational costs for manufacturers and obstructing their ability to meet rising demand.
Trends in the China Aerospace Actuation Market
Several trends are reshaping the China Aerospace Actuation Market; the most important are set out below.
- Shift towards Electric Actuation Systems: The Aerospace Industry Development Plan promotes the adoption of electric actuation systems, which are increasingly preferred for their efficiency. With a projected share of 46% by 2025, this trend reflects a notable shift in aerospace technology.
- Increased Focus on Military-Civilian Integration: The Military-Civilian Integration Development Strategy encourages collaboration between military and civilian aerospace sectors. This initiative is expected to drive innovation and efficiency in actuation systems, benefiting both sectors.
- Expansion of Aerospace Manufacturing Hubs: Jiangsu province is emerging as a key aerospace manufacturing hub, contributing to the national goal of producing 1,000 commercial aircraft annually by 2035. This growth is driving demand for actuation systems in the region.
- Rising Standards for Aerospace Safety: The Civil Aviation Administration of China updated safety regulations in 2022, improving reliability for actuation systems in commercial aircraft. This regulatory change is essential for manufacturers aiming to meet stringent safety requirements.
Investment Opportunities in the China Aerospace Actuation Market
Below are the investment opportunities with the strongest case in the China Aerospace Actuation Market.
- Supply of Advanced Actuation Systems: There is a growing opportunity to supply advanced actuation systems, particularly in military applications. With military spending on the rise, suppliers can pursue contracts under the Ministry of National Defense's modernisation plan, valued at billions.
- Investment in Aerospace Manufacturing Facilities: Investment in new aerospace manufacturing facilities in Jiangsu province presents a promising opportunity. With the region's focus on producing 1,000 commercial aircraft by 2035, partnerships with local manufacturers can facilitate market entry.
- Gap in High-Quality Component Supply: The market reveals a gap in high-quality aerospace components, particularly for military applications. Suppliers can target military aerospace manufacturers, aligning with the Ministry of National Defense's focus on modernisation.
- Entry through Joint Ventures: Establishing joint ventures with local aerospace manufacturers can provide a strategic entry route. This approach aligns with the government's push for domestic production capabilities under the Aerospace Industry Development Plan.
Government Initiatives in the China Aerospace Actuation Market
In 2020, the National Development and Reform Commission launched the 'Aerospace Industry Development Plan', aimed at boosting domestic production capabilities and reducing reliance on imports. This initiative is expected to improve local manufacturing and enhance the competitiveness of the aerospace sector in China, with an investment of 300 billion CNY for technological advancements from 2020 to 2025. In 2021, the Ministry of Industry and Information Technology initiated the 'Made in China 2025' strategy, focusing on upgrading aerospace manufacturing technologies and standards, which further supports the growth of the aerospace actuation market.
The Military-Civilian Integration Development Strategy promotes collaboration between military and civilian aerospace sectors, enabling better resource allocation and innovation. The Civil Aviation Administration of China (CAAC) updated safety regulations in 2022, focusing on improving the reliability of aerospace actuation systems in commercial aircraft. This regulatory change ensures that manufacturers adhere to higher safety standards, benefiting both producers and buyers in the aerospace actuation market.
Future Insight of the China Aerospace Actuation Market
By 2032, buyers and suppliers in the China aerospace actuation market can expect notable advancements driven by a government investment of 300 billion CNY in aerospace technology. The implementation of the Aerospace Industry Development Plan will improve manufacturing capabilities, increasing the availability of advanced actuation systems. The Chinese aviation sector's goal to serve 1.6 billion passengers by 2035 will further amplify the demand for reliable actuation solutions. The ongoing emphasis on ISO 9001 certification will ensure high-quality standards, strengthening the competitive position of local producers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Product Type – Linear Actuators Dominated, Electro-Mechanical Actuators Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, Linear Actuators held a 39% share of the China Aerospace Actuation Market by product type in 2025. Linear actuators are essential for controlling critical aircraft systems, making them a key choice for aerospace manufacturers. Their widespread use in landing gear applications solidifies their leading market share in the China aerospace actuation market. The quickest growth will come from Electro-Mechanical Actuators, forecast to expand at a CAGR of 6.9% between 2026 and 2032. Electro-mechanical actuators are increasingly preferred in modern aircraft due to their efficiency and reliability, driving their rapid growth. As the aerospace sector adopts more advanced technologies, this sub-segment is set to expand significantly. Suppliers should focus on enhancing their electro-mechanical actuator offerings to meet the surging demand.
By Actuation Mechanism – Electric Dominated, Servo-Driven Expected to Grow Fastest
With a 46% revenue share in 2025, Electric was the largest actuation mechanism category. Electric actuation mechanisms are widely used in modern aircraft, ensuring optimal performance across various systems. Their established presence in numerous aircraft types reinforces their leading market share in the aerospace actuation market. Servo-Driven is projected to grow fastest, at a CAGR of 7.1% during 2026–2032. Servo-driven actuation mechanisms are crucial for applications requiring high precision and control, especially in advanced aircraft designs. As manufacturers seek improved performance, this segment is poised for swift growth. Suppliers should prioritise developing servo-driven solutions to capitalise on the increasing demand.
By Application Area – Landing Gear Systems Dominated, Wing Control Surfaces Expected to Grow Fastest
Landing Gear Systems accounted for a 46% market share by application area in 2025. Landing gear systems are vital for aircraft takeoff and landing operations, making them a primary focus for aerospace manufacturers. Their critical role in aviation safety ensures they maintain the largest market share in aerospace actuation. Wing Control Surfaces are set to record the highest CAGR in this split, 6.1% over 2026–2032. Wing control surfaces are essential for aerodynamic control during flight, leading to their rapid adoption in new aircraft designs. As the industry advances, this application area is set for substantial growth. This highlights the need for suppliers to invest in technologies that enhance wing control surface actuation.
By Distribution Channel – OEMs Dominated, Government Contracts Expected to Grow Fastest
The largest distribution channel category in 2025 was OEMs, with a 47% share of total revenue. OEMs serve as the primary distribution channel for actuation systems, directly connecting manufacturers with essential components. Their established relationships with aircraft manufacturers ensure they maintain a dominant market share in the aerospace actuation market. Over 2026–2032, Government Contracts are expected to post the fastest growth, at a CAGR of 6.0%. Government contracts are increasingly significant for defence-related aerospace projects, driving demand for actuation systems in military applications. This growth reflects heightened military investment in aerospace capabilities and indicates a shift in procurement strategies. Suppliers should strengthen ties with government entities to tap into this lucrative distribution channel.
By End User – Aircraft Manufacturers Dominated, Military Aerospace Expected to Grow Fastest
In 2025, Aircraft Manufacturers led the end user split with a 45% share. Aircraft manufacturers are the main users of aerospace actuation systems, relying on these components for their production lines. Their substantial purchasing power greatly contributes to their leading market share in the aerospace actuation sector. The quickest growth will come from Military Aerospace, forecast to expand at a CAGR of 6.5% between 2026 and 2032. Military aerospace is a major sector driving demand for advanced actuation systems, especially as nations modernise their fleets. This focus on military applications is expected to accelerate growth in this segment. Suppliers should align their strategies to meet the specific needs of military aerospace to capture this expanding market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Aerospace Actuation Market Outlook
- Market Size of China Aerospace Actuation Market, 2025
- Forecast of China Aerospace Actuation Market, 2032
- Historical Data and Forecast of China Aerospace Actuation Revenues & Volume for the Period 2022 - 2032F
- China Aerospace Actuation Market Trend Evolution
- China Aerospace Actuation Market Drivers and Challenges
- China Aerospace Actuation Price Trends
- China Aerospace Actuation Porter's Five Forces
- China Aerospace Actuation Industry Life Cycle
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Linear Actuators for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Rotary Actuators for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Electro-Mechanical Actuators for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Pneumatic Actuators for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Actuation Mechanism for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Electric for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Hydraulic for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Servo-Driven for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Air-Driven for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Landing Gear Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Wing Control Surfaces for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Braking Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Seat & Cargo Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Government Contracts for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Industrial Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Aircraft Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Military Aerospace for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Commercial Aviation for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Actuation Market Revenues & Volume By Business Jet Operators for the Period 2022 - 2032F
- China Aerospace Actuation Import Export Trade Statistics
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Actuation Mechanism
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Aerospace Actuation Top Companies Market Share
- China Aerospace Actuation Competitive Benchmarking By Technical and Operational Parameters
- China Aerospace Actuation Company Profiles
- China Aerospace Actuation Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Product Type
- Linear Actuators
- Rotary Actuators
- Electro-Mechanical Actuators
- Pneumatic Actuators
By Actuation Mechanism
- Electric
- Hydraulic
- Servo-Driven
- Air-Driven
By Application Area
- Landing Gear Systems
- Wing Control Surfaces
- Braking Systems
- Seat & Cargo Systems
By Distribution Channel
- OEMs
- Government Contracts
- Direct Sales
- Industrial Suppliers
By End User
- Aircraft Manufacturers
- Military Aerospace
- Commercial Aviation
- Business Jet Operators






































