China Aerospace Ceramics Market Size & Growth Rate
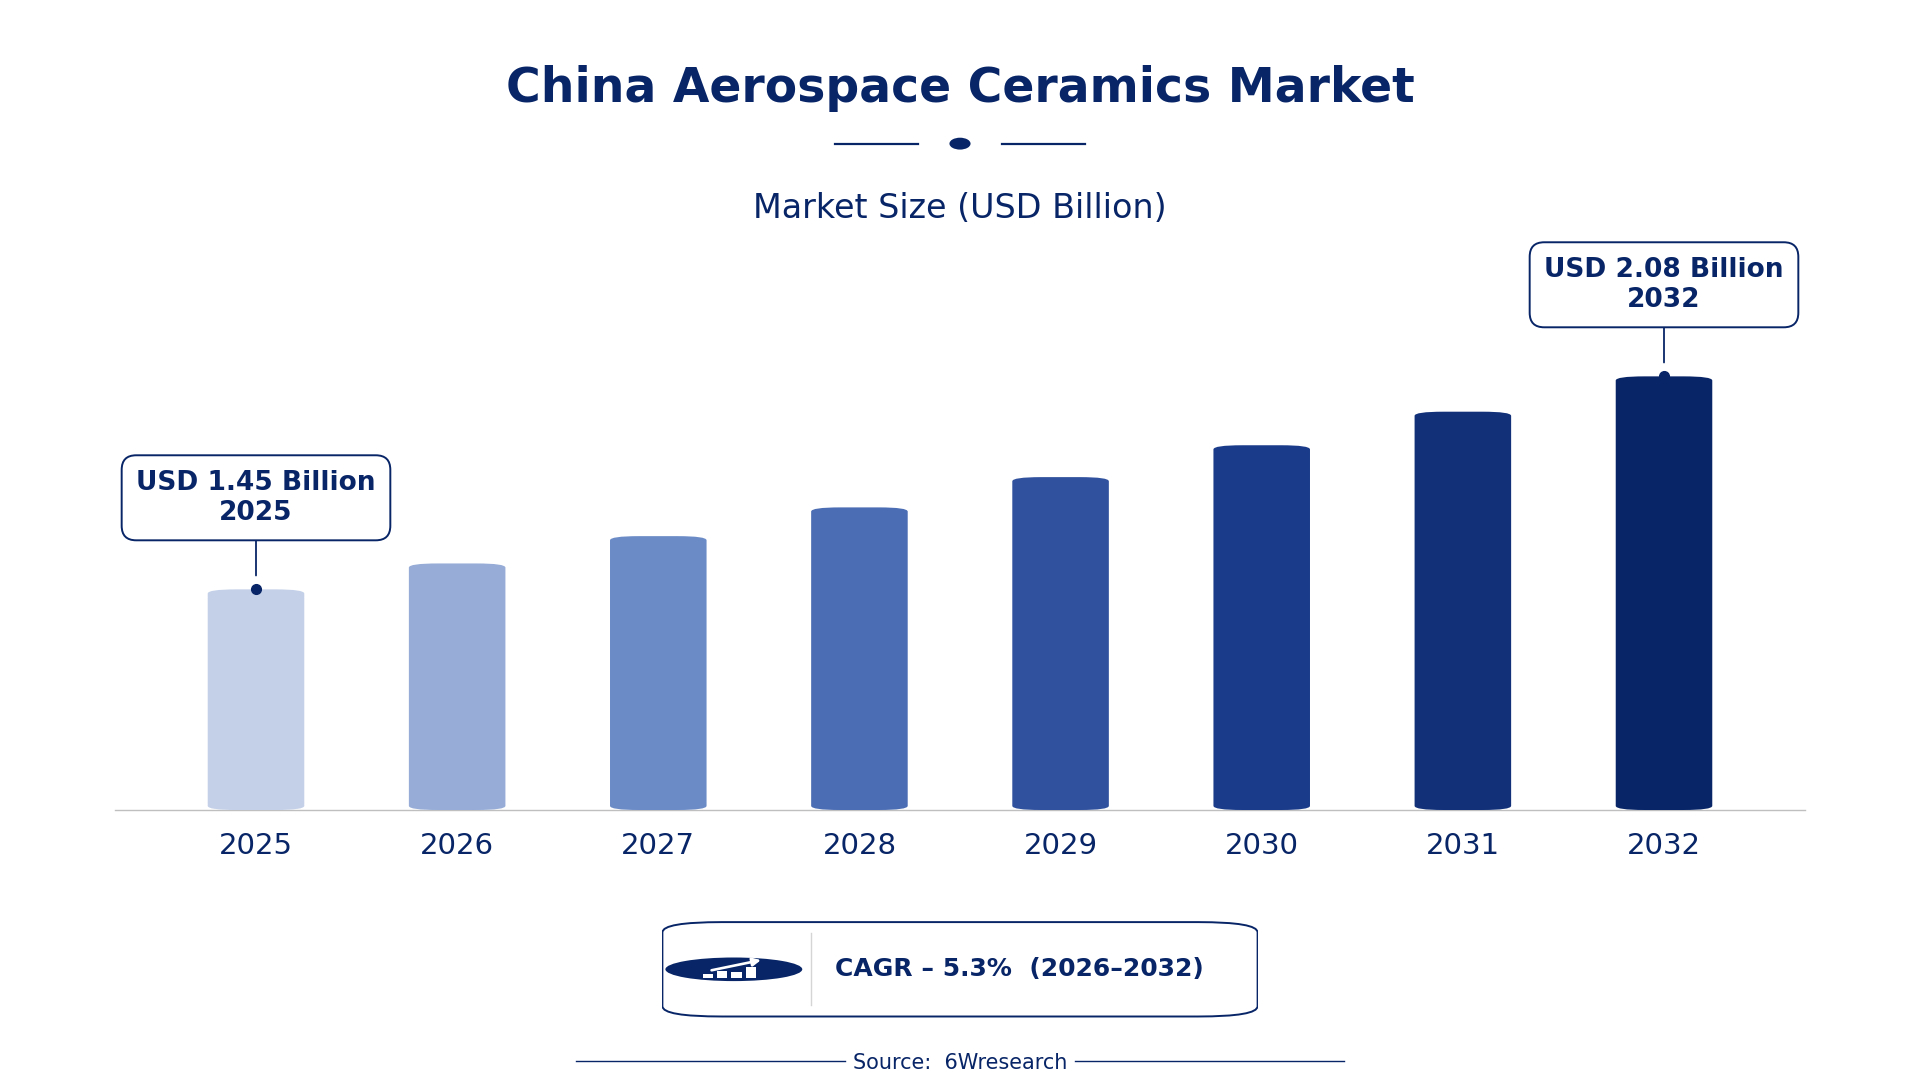
According to 6Wresearch internal database and industry insights, the China Aerospace Ceramics Market was valued at USD 1.45 billion in 2025 and is projected to reach USD 2.08 billion by 2032, growing at a CAGR of approximately 5.3% during 2026–2032.
China Aerospace Ceramics Market Highlights
| Report Metric | Details |
| Report Name | China Aerospace Ceramics Market |
| Market Size 2025 | USD 1.45 billion |
| Market Size 2032 | USD 2.08 billion |
| Absolute Growth 2025–2032 | USD 0.63 billion |
| CAGR 2026–2032 | 5.3% |
| Peak Annual Growth | 6.8% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Product Type, 2025 | Ceramic Matrix Composites (39% share) |
| Leading Ceramic Type, 2025 | Non-Oxide Ceramics (40% share) |
| Leading Application Area, 2025 | Thermal Barrier Coatings (40% share) |
| Leading Distribution Channel, 2025 | OEMs (46% share) |
| Leading End User, 2025 | Jet Engine Producers (34% share) |
| Fastest-Growing Product Type | Ceramic Coatings (6.5% CAGR) |
| Fastest-Growing Application Area | Turbomachinery (7.4% CAGR) |
| Fastest-Growing Distribution Channel | Government Contracts (8.0% CAGR) |
| Fastest-Growing End User | Defense Organizations (7.4% CAGR) |
| Growing Sector | Aerospace Manufacturing |
| Key End Users | Jet Engine Producers, Defense Organizations, Aerospace Factories |
China Aerospace Ceramics Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
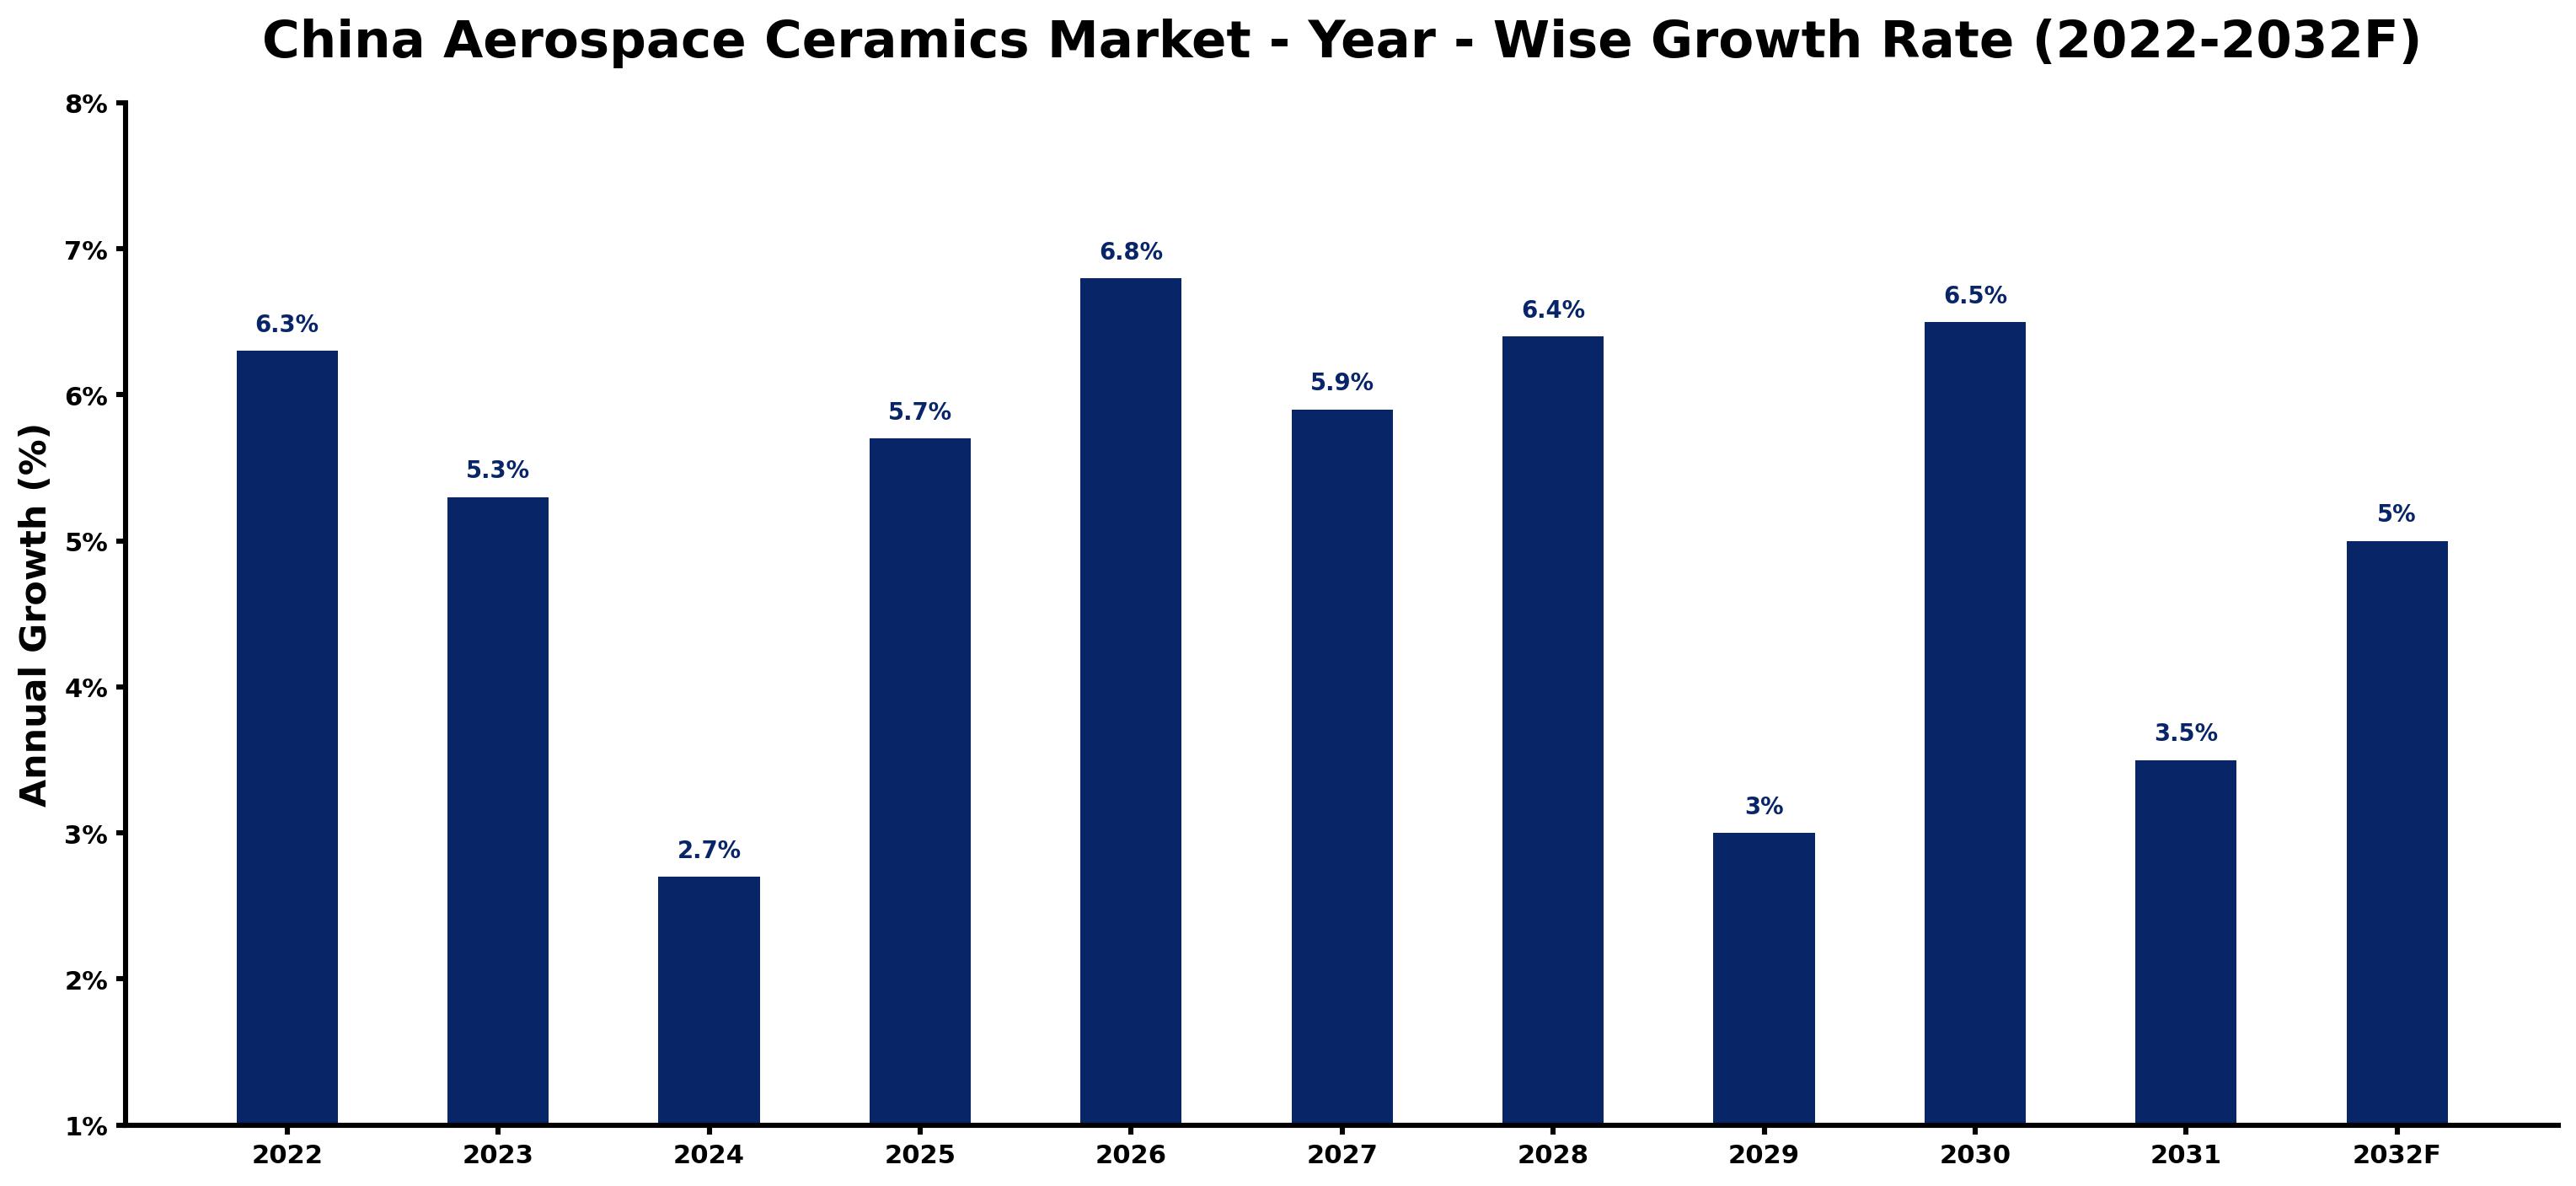
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.3 | The market experienced strong demand from domestic aerospace projects and government contracts. |
| 2023 | 5.3 | Growth slowed due to adjustments in production schedules and supply chain challenges. |
| 2024 | 2.7 | The market continued to grow, albeit at a slower rate, as manufacturers adapted to new standards. |
| 2025 | 5.7 | Increased jet engine production led to a faster growth rate as demand surged. |
| 2026 | 6.8 | The peak growth year is expected to see heightened investments in aerospace technology and materials. |
| 2027 | 5.9 | Growth is projected to slow slightly as manufacturers face challenges in scaling production. |
| 2028 | 6.4 | A rise in demand for advanced materials is expected to contribute to a faster growth rate. |
| 2029 | 3.0 | Growth is anticipated to slow again as the market adjusts to new production capacities. |
| 2030 | 6.5 | Demand for aerospace ceramics is expected to increase due to new jet engine designs. |
| 2031 | 3.5 | The market is projected to experience slower growth as competition intensifies among suppliers. |
| 2032 | 5.0 | Growth is expected to continue as government contracts boost demand for aerospace ceramics. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Aerospace Ceramics Market Synopsis
Aerospace Ceramics in China includes advanced materials designed for high-performance applications in the aerospace sector. The China Aerospace Ceramics Market is expanding due to strong domestic demand and government support for aerospace development. The national strategy launched in 2023 aims to improve manufacturing capabilities, while the defense budget allocates substantial funds for aerospace technology. This combination of factors is driving increased production and innovation in the sector.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Government contracts are increasing demand for aerospace ceramics, particularly in defense applications. | Driver | High | Government Contracts |
| The rise in indigenous jet engine development is driving demand for advanced ceramics. | Driver | High | Jet Engine Producers |
| The demand for lightweight materials is creating opportunities in the aerospace ceramics sector. | Opportunity | High | Ceramic Matrix Composites |
| Increased government funding for aerospace technology development presents investment opportunities. | Opportunity | High | Aerospace Factories |
| High production costs for advanced ceramics can limit market growth. | Restraint | Medium | Technical Ceramics |
| Limited availability of raw materials may constrain production capabilities. | Restraint | Medium | Non-Oxide Ceramics |
| The market still has to solve a few problems, including high production costs and raw material shortages. | Challenge | High | Ceramic Coatings |
| Competition from foreign manufacturers poses challenges for local producers. | Challenge | Medium | Ceramic Matrix Composites |
Evaluation of Drivers in China Aerospace Ceramics Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing domestic demand for jet engines is driving the need for advanced ceramics. | Jet Engine Producers | Technical ceramics are used in over 70% of new jet engine designs in China. |
| Increased government funding is boosting research and development in advanced ceramics. | Government Contracts | The defense budget for 2023 includes allocations of 500 million yuan for aerospace technology development. |
| The shift towards lightweight materials is increasing the use of ceramic matrix composites. | Ceramic Matrix Composites | Ceramic matrix composites are increasingly used in jet engines for their lightweight properties. |
| The rise in thermal barrier coatings is linked to increased jet engine production. | Thermal Barrier Coatings | The demand for thermal barrier coatings is expected to rise due to increased jet engine production. |
| The focus on reducing reliance on foreign technology is driving local production. | Non-Oxide Ceramics | China's aerospace industry is projected to grow significantly, focusing on indigenous technology. |
Growth in the Aerospace Ceramics market in China comes from rising domestic demand for jet engines, which drives the need for advanced ceramics. Technical ceramics are used in over 70% of new jet engine designs, prompting manufacturers to increase production. The 2023 defense budget allocates 500 million yuan for aerospace technology development, boosting research efforts. The shift towards lightweight materials increases the use of ceramic matrix composites, which are increasingly integrated into jet engines. This focus on local production is pushing forward advancements in material technologies and manufacturing processes.
Evaluation of Restraints in China Aerospace Ceramics Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High production costs for advanced ceramics can limit market growth. | Technical Ceramics | Production costs are driven by the complexity of manufacturing processes and material sourcing, which inflate expenses by up to 30%. |
| Limited availability of raw materials may constrain production capabilities. | Non-Oxide Ceramics | Supply chain disruptions have impacted the availability of essential materials for ceramics, delaying production schedules. |
| Competition from foreign manufacturers poses challenges for local producers. | Ceramic Matrix Composites | Foreign firms often have established supply chains and advanced technologies, making it difficult for local producers to compete. |
| Technological advancements are required to keep up with evolving aerospace standards. | Jet Engine Producers | Manufacturers must invest in R&D to meet stringent aerospace requirements, which can delay product launches. |
| Market fluctuations can affect investment in new production facilities. | Government Contracts | Economic uncertainties may lead to cautious spending on aerospace projects, impacting growth. |
China Aerospace Ceramics Market Challenges
The China Aerospace Ceramics Market still faces several critical issues, with cost being the foremost. Producers encounter high material and processing expenses, inflating production costs by up to 30%, which directly impacts their pricing strategies. Regulatory challenges arise from compliance with ISO 9001 standards, necessitating significant investment and delaying product launches for manufacturers by several months. Technology gaps hinder many producers from adopting advanced manufacturing techniques, limiting their competitiveness in a rapidly evolving market. Skills shortages in advanced ceramics processing complicate matters further, resulting in delays for manufacturers in fulfilling government contracts and impacting production timelines.
Trends in the China Aerospace Ceramics Market
Below mentioned are some of the trends shaping the China Aerospace Ceramics Market growth.
- Shift in Focus to Lightweight Materials: The Shanghai region is increasingly prioritising lightweight materials in aerospace manufacturing, with ceramic matrix composites gaining traction. In 2023, the demand for these materials rose by 20%, reflecting a shift towards efficiency in jet engine design.
- Government Contracts Driving Innovation: Defence organisations are prioritising advanced ceramics, leading to increased innovation in the sector. The 2023 defence budget allocated 500 million yuan for aerospace material research, promoting new developments in ceramic technologies.
- Emergence of Thermal Barrier Coatings: Thermal barrier coatings are becoming essential for jet engine performance, with a notable increase in demand in 2023. This trend is driven by the need for improved thermal resistance in high-performance applications.
- Increased Adoption of ISO 9001 Standards: The aerospace ceramics industry is increasingly adopting ISO 9001 standards to enhance quality assurance. In 2023, over 60% of manufacturers reported compliance with these standards, improving product reliability.
Investment Opportunities in the China Aerospace Ceramics Market
Investors looking at the China Aerospace Ceramics Market should consider the following areas.
- Partnerships with Local Manufacturers: Now is a prime time for partnerships in aerospace ceramics, as demand grows. Collaborating with aerospace factories in the Shanghai region can improve production capabilities and market access, particularly with a projected market size of USD 2.08 billion by 2032.
- Investment in Advanced Ceramics: The current focus on reducing reliance on foreign technology presents investment opportunities in advanced ceramics. Jet engine producers are seeking local suppliers, creating avenues for investment in research and production facilities.
- Government Funding for R&D: The government has allocated 500 million yuan for aerospace material research in 2023, creating opportunities for innovation. Engaging with the National Defense Science and Technology Agency can facilitate access to funding for new projects.
- Growing Demand from Defense Organizations: Defense organizations are increasingly seeking advanced ceramics for military applications. With a projected growth rate of 7.4% for this segment, suppliers can benefit by focusing on tailored solutions for this buyer group.
Government Initiatives in the China Aerospace Ceramics Market
The Ministry of Industry and Information Technology initiated the 'Aerospace Industry Development Plan' to boost domestic production of aerospace materials. Launched in 2021, this plan aims to improve local capabilities and reduce reliance on imports, creating a supportive environment for manufacturers. The initiative includes specific targets for production increases and technology advancements in the aerospace sector. In 2023, the 'Made in China 2025' initiative further emphasised the importance of advanced ceramics in aerospace applications, aiming to strengthen the domestic supply chain.
In 2023, the National Defense Science and Technology Agency allocated 500 million yuan for aerospace material research, providing funding and support for research projects. This initiative encourages innovation in advanced ceramics, enabling manufacturers to develop new technologies and improve product offerings.
Future Insight of the China Aerospace Ceramics Market
Transformative changes are anticipated in the China Aerospace Ceramics Market by 2032, driven primarily by advancements in manufacturing technology. Increased government funding for research and development will improve material properties and processing techniques, enabling producers to innovate more effectively. Domestic demand for aerospace ceramics is projected to rise, contributing to a 40% increase in output of thermal barrier coatings. As the industry pivots towards indigenous jet engine development, suppliers will gain from reduced reliance on foreign technologies, fostering a more self-sufficient aerospace sector.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Product Type – Ceramic Matrix Composites Dominated, Ceramic Coatings Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, Ceramic Matrix Composites took a 39% share of product type in 2025, more than any other category. Ceramic Matrix Composites hold the largest market share due to their critical role in lightweight structural components essential for aerospace applications. Their integration in over 70% of new jet engine designs illustrates their importance in enhancing overall aircraft performance. Ceramic Coatings are projected to grow fastest, at a CAGR of 6.5% during 2026–2032. Ceramic Coatings are rapidly growing as they cater to the increasing demand for thermal protection in aerospace applications, particularly with the rise in jet engine production. This segment's growth is further supported by government initiatives aimed at bolstering aerospace manufacturing capabilities. Suppliers should focus on developing advanced ceramic coatings to effectively meet the rising demands of the aerospace sector.
By Ceramic Type – Non-Oxide Ceramics Dominated and Is Expected to Record the Fastest Growth
With a 40% revenue share in 2025, Non-Oxide Ceramics was the largest ceramic type category. Non-Oxide Ceramics dominate the market share because they are vital for high-temperature applications in the aerospace industry. Their unique properties make them indispensable for producing advanced aerospace components that require reliability and performance under extreme conditions. Non-Oxide Ceramics are also forecast to expand faster than any other category, at a CAGR of 6.9% over 2026–2032. The growth of Non-Oxide Ceramics is propelled by their increasing use in high-performance applications, especially in jet engines, where their ability to withstand extreme conditions is unmatched. As aerospace technology evolves, this segment's lead will continue to expand. Buyers should prioritise sourcing Non-Oxide Ceramics to ensure optimal performance in demanding aerospace environments.
By Application Area – Thermal Barrier Coatings Dominated, Turbomachinery Expected to Grow Fastest
The largest application area category in 2025 was Thermal Barrier Coatings, with a 40% share of total revenue. Thermal Barrier Coatings lead the market as they are essential for protecting engine components from heat, which is crucial in aerospace applications. Their widespread use in jet engines highlights their importance in maintaining operational efficiency and safety. The quickest growth will come from Turbomachinery, forecast to expand at a CAGR of 7.4% between 2026 and 2032. Turbomachinery is witnessing the fastest growth, becoming a key component in jet engines, driven by the rising demand for efficient aerospace technologies. As the aerospace industry continues to expand, the relevance of this segment will keep increasing. Suppliers must enhance turbomachinery solutions to address the growing requirements of the aerospace sector.
By Distribution Channel – OEMs Dominated, Government Contracts Expected to Grow Fastest
OEMs accounted for a 46% market share by distribution channel in 2025. OEMs capture the largest market share as they are the primary customers for aerospace ceramics, ensuring a consistent demand for these materials. Their established relationships with manufacturers facilitate a steady flow of orders for advanced aerospace ceramics. Over 2026–2032, Government Contracts are expected to post the fastest growth, at a CAGR of 8.0%. Government Contracts represent the fastest-growing distribution channel, reflecting a significant source of demand for aerospace materials driven by national defence budgets. This growth is anticipated to persist as government investments in aerospace technology rise. Suppliers should align their strategies to seize opportunities within government contracts to maximise market presence.
By End User – Jet Engine Producers Dominated, Defense Organizations Expected to Grow Fastest
Jet Engine Producers held a 34% share of the China Aerospace Ceramics Market by end user in 2025. Jet Engine Producers command the largest market share as they are the major end users of aerospace ceramics, relying on these materials for high-performance components. Their ongoing projects and production rates ensure a robust demand for advanced ceramics in the industry. Defense Organizations are projected to grow fastest, at a CAGR of 7.4% during 2026–2032. Defense Organizations are the fastest-growing end user segment, propelled by increasing military applications and government funding for aerospace technologies. This growth indicates a rising need for specialised materials tailored to defence requirements. Suppliers should focus on developing customised solutions for defence organizations to capitalise on this expanding market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Aerospace Ceramics Market Outlook
- Market Size of China Aerospace Ceramics Market, 2025
- Forecast of China Aerospace Ceramics Market, 2032
- Historical Data and Forecast of China Aerospace Ceramics Revenues & Volume for the Period 2022 - 2032F
- China Aerospace Ceramics Market Trend Evolution
- China Aerospace Ceramics Market Drivers and Challenges
- China Aerospace Ceramics Price Trends
- China Aerospace Ceramics Porter's Five Forces
- China Aerospace Ceramics Industry Life Cycle
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Ceramic Coatings for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Ceramic Matrix Composites for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Ceramic Insulators for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Ceramic Bearings for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Ceramic Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Oxide Ceramics for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Non-Oxide Ceramics for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Technical Ceramics for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Silicon Nitride for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Thermal Barrier Coatings for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Exhaust Nozzles for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Electronics for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Turbomachinery for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Government Contracts for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Industrial Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Jet Engine Producers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Defense Organizations for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Avionics OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Ceramics Market Revenues & Volume By Aerospace Factories for the Period 2022 - 2032F
- China Aerospace Ceramics Import Export Trade Statistics
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Ceramic Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Aerospace Ceramics Top Companies Market Share
- China Aerospace Ceramics Competitive Benchmarking By Technical and Operational Parameters
- China Aerospace Ceramics Company Profiles
- China Aerospace Ceramics Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Product Type
- Ceramic Coatings
- Ceramic Matrix Composites
- Ceramic Insulators
- Ceramic Bearings
By Ceramic Type
- Oxide Ceramics
- Non-Oxide Ceramics
- Technical Ceramics
- Silicon Nitride
By Application Area
- Thermal Barrier Coatings
- Exhaust Nozzles
- Electronics
- Turbomachinery
By Distribution Channel
- OEMs
- Government Contracts
- Direct Sales
- Industrial Suppliers
By End User
- Jet Engine Producers
- Defense Organizations
- Avionics OEMs
- Aerospace Factories






































