China Aerospace Composites Bonding Market Size & Growth Rate
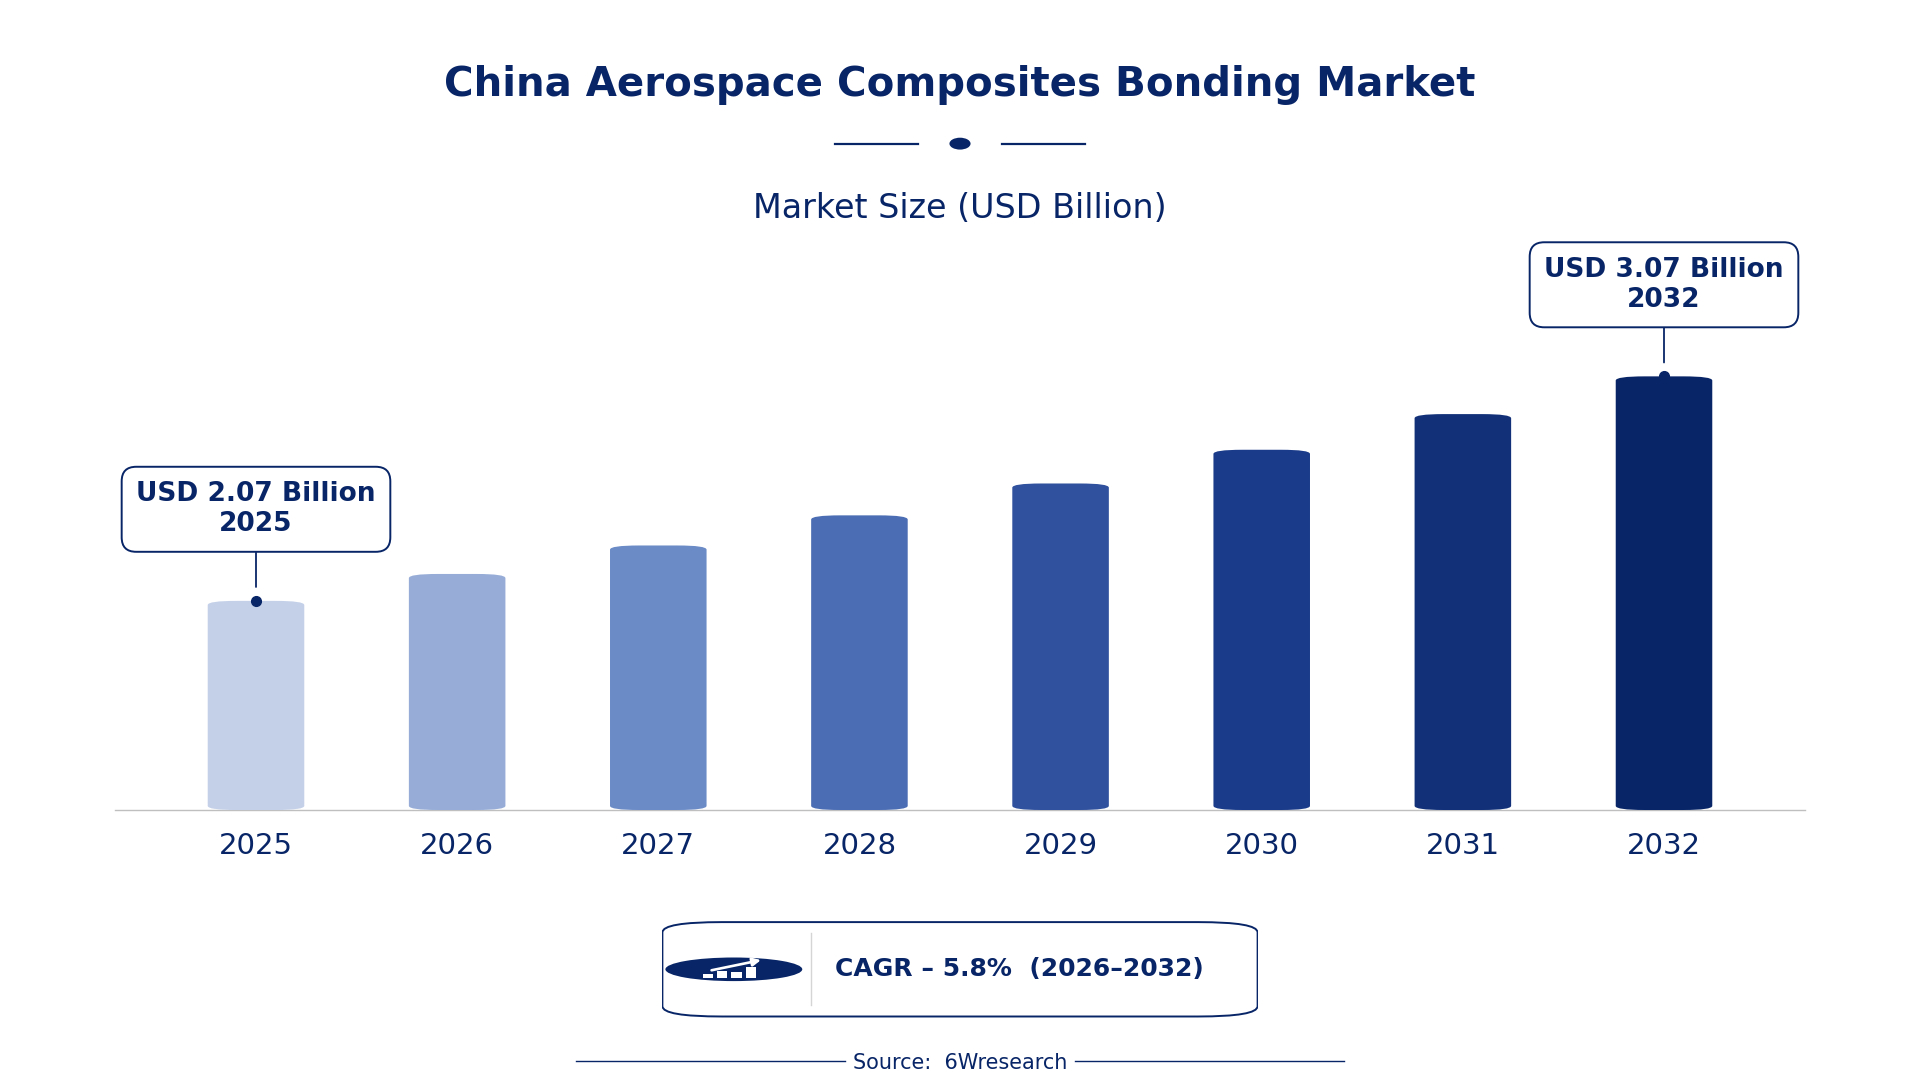
According to 6Wresearch internal database and industry insights, the China Aerospace Composites Bonding Market was valued at USD 2.07 billion in 2025 and is projected to reach USD 3.07 billion by 2032, growing at a CAGR of approximately 5.8% during 2026–2032.
China Aerospace Composites Bonding Market Highlights
| Report Metric | Details |
| Report Name | China Aerospace Composites Bonding Market |
| Market Size 2025 | USD 2.07 billion |
| Market Size 2032 | USD 3.07 billion |
| Absolute Growth 2025–2032 | USD 1 billion |
| CAGR 2026–2032 | 5.8% |
| Peak Annual Growth | 8.4% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Bonding Type, 2025 | Structural Adhesives (36% share) |
| Leading Resin Type, 2025 | Epoxy Resin (44% share) |
| Leading Application Area, 2025 | Wing Structures (53% share) |
| Leading Distribution Channel, 2025 | OEMs (46% share) |
| Leading End User, 2025 | Aircraft Manufacturers (38% share) |
| Fastest-Growing Bonding Type | Film Adhesives (7.8% CAGR) |
| Fastest-Growing Resin Type | Thermoset Resin (7.8% CAGR) |
| Fastest-Growing Application Area | Fuselage Assembly (7.6% CAGR) |
| Fastest-Growing Distribution Channel | Direct Sales (8.4% CAGR) |
| Fastest-Growing End User | Composite Material Providers (7.2% CAGR) |
| Growing Sector | Aerospace Manufacturing |
| Key End Users | Aircraft Manufacturers, Composite Material Providers, OEMs |
China Aerospace Composites Bonding Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
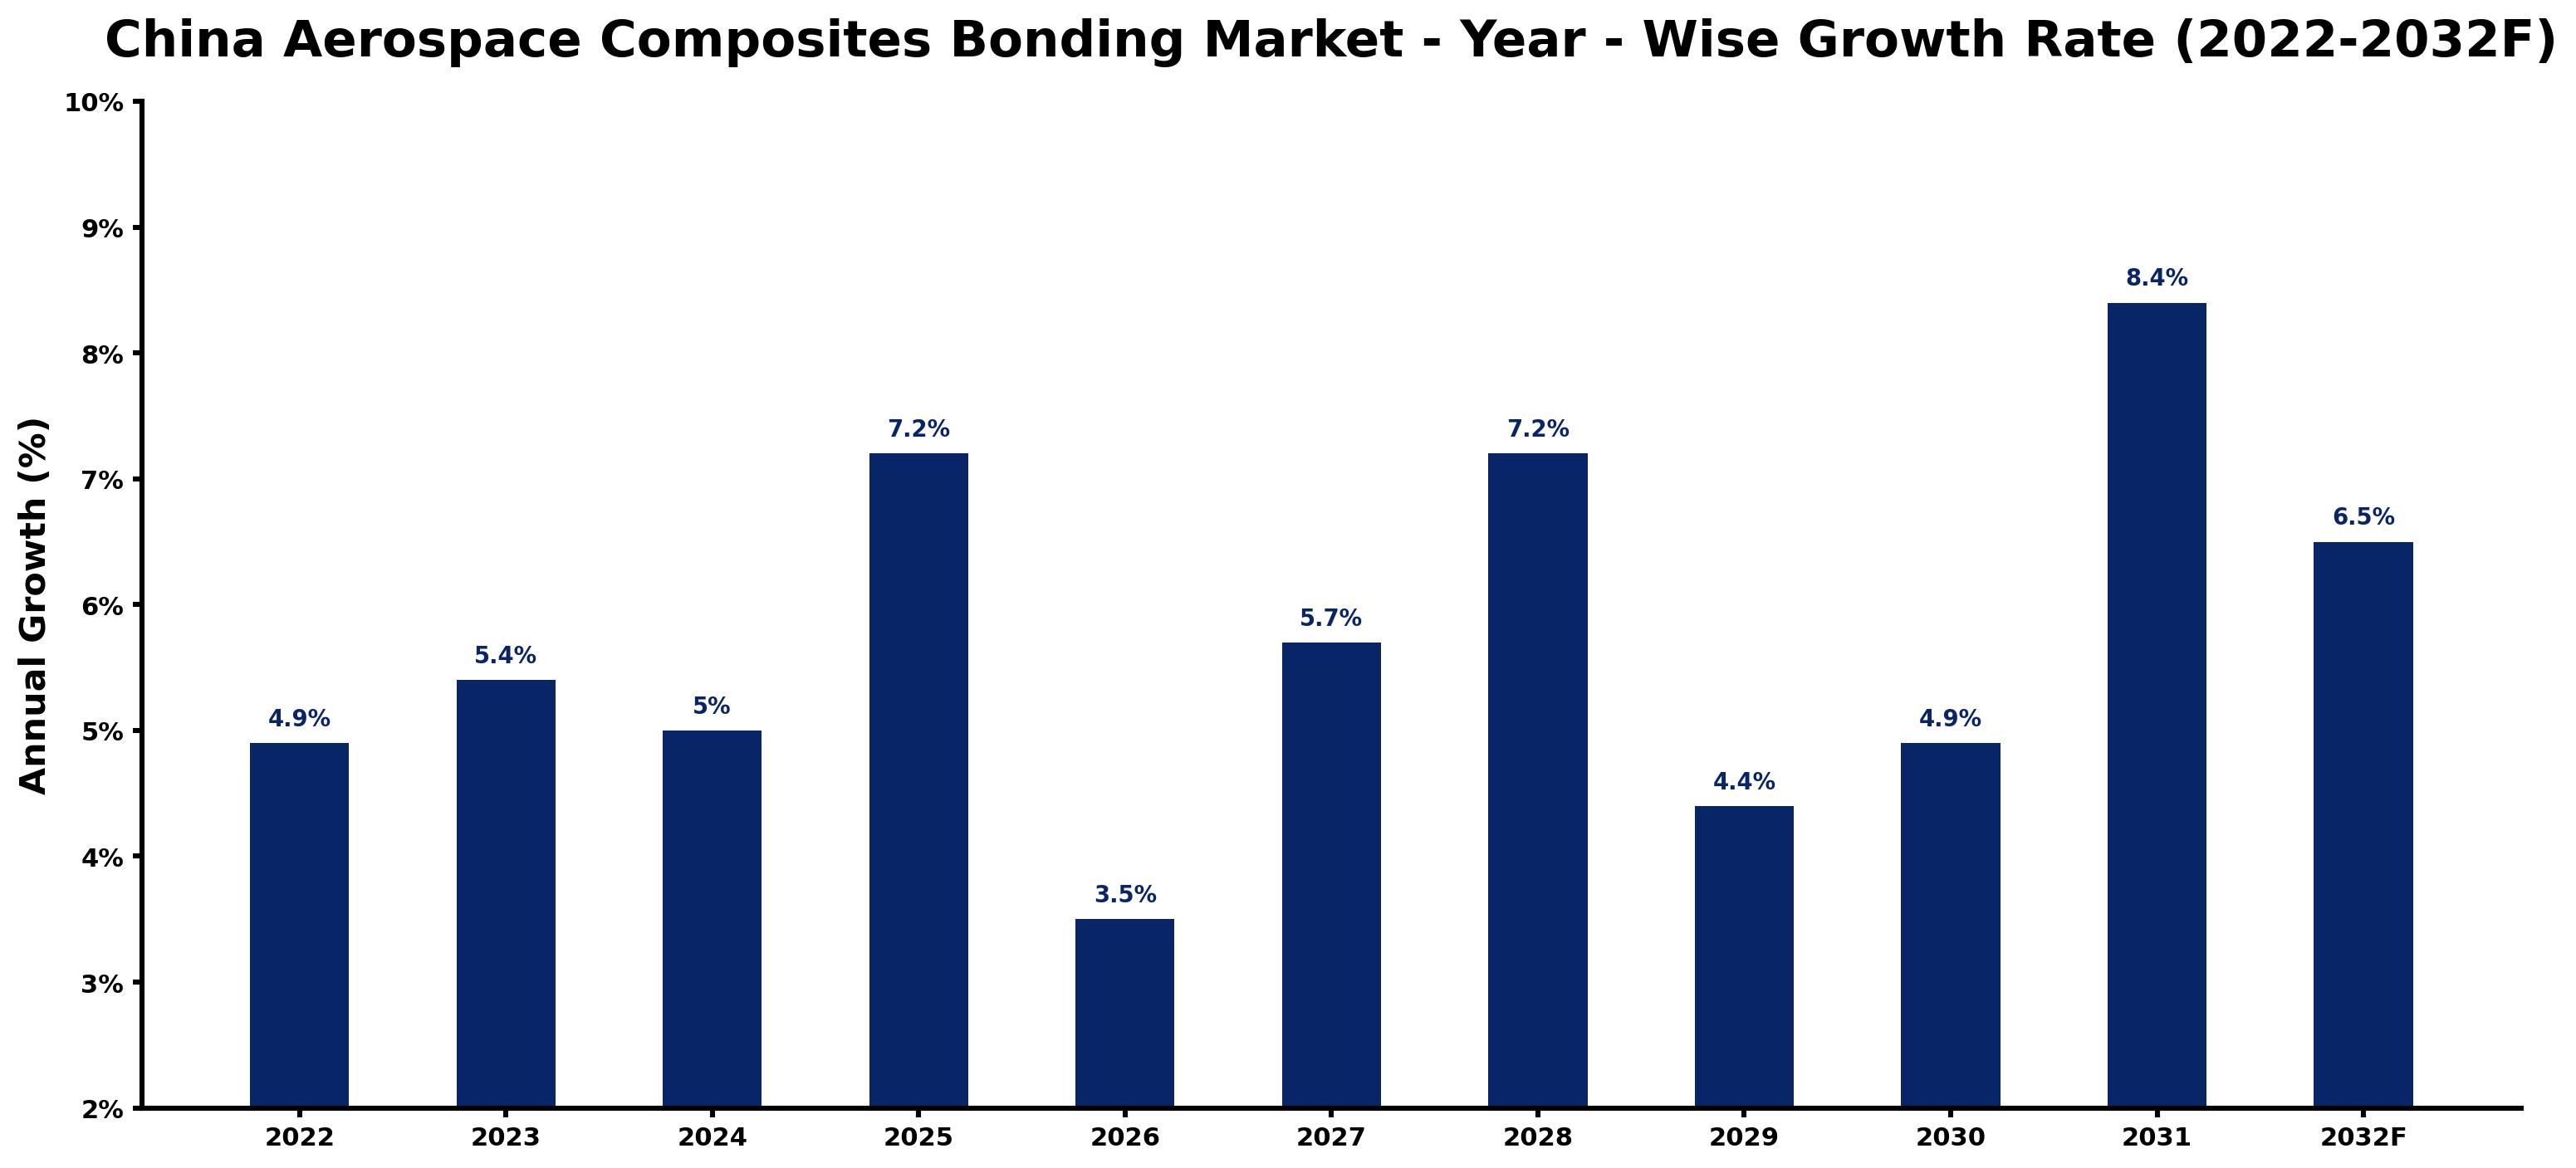
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.9 | The aerospace sector produced over 300 commercial aircraft, driving demand for bonding materials. |
| 2023 | 5.4 | Growth was supported by ongoing investments in aerospace technology and increased production capabilities. |
| 2024 | 5.0 | The market experienced a slowdown as production adjustments were made in response to demand fluctuations. |
| 2025 | 7.2 | The peak growth rate was driven by the successful implementation of the Aerospace Industry Development Plan. |
| 2026 | 3.5 | A slowdown occurred as the market is expected to stabilise after rapid growth in previous years. |
| 2027 | 5.7 | Demand is projected to rise again as local manufacturers increase their production capacity and efficiency. |
| 2028 | 7.2 | The market is expected to continue growing due to heightened investments in aerospace R&D and technology. |
| 2029 | 4.4 | A slowdown is anticipated as production levels adjust to meet market saturation. |
| 2030 | 4.9 | Growth is projected to resume as manufacturers adapt to new standards and increase their output. |
| 2031 | 8.4 | The market is expected to peak due to advancements in aerospace technology and production methods. |
| 2032 | 6.5 | A slowdown is projected as the market stabilises after reaching high production levels. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Aerospace Composites Bonding Market Synopsis
The China Aerospace Composites Bonding Market encompasses the use of adhesives to join composite materials in aircraft manufacturing. These adhesives are essential for structural applications in components like wings and fuselage. The market is expanding due to strong domestic demand from local aircraft manufacturers and substantial investments in aerospace technology. In 2023, the National Development and Reform Commission launched the Aerospace Industry Development Plan, targeting a 30% increase in local production by 2025. This initiative, alongside a skilled workforce of over 1 million professionals, is driving further growth in the sector.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Strong domestic aircraft production | Driver | High | Structural Adhesives |
| Increased investment in aerospace technology | Driver | High | Epoxy Resin |
| Growing demand for lightweight materials | Opportunity | High | Film Adhesives |
| Expansion of local manufacturing capabilities | Opportunity | High | Wing Structures |
| Compliance with stringent safety regulations | Restraint | High | Paste Adhesives |
| Limited availability of high-quality materials | Restraint | Medium | Thermoset Resin |
| Challenges in meeting international standards | Challenge | High | Fuselage Assembly |
| High costs associated with advanced materials | Challenge | Medium | Engine Nacelles |
Evaluation of Drivers in China Aerospace Composites Bonding Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing production of commercial aircraft | Structural Adhesives | In 2022, over 300 commercial aircraft were produced, driving demand for bonding materials essential for structural integrity. |
| Investment in aerospace R&D | Epoxy Resin | The government invested over $10 billion in aerospace R&D since 2020, supporting the development of advanced bonding materials. |
| Rising demand for lightweight composites | Film Adhesives | The need for lightweight materials in aircraft manufacturing is increasing, leading to higher consumption of film adhesives. |
| Expansion of aerospace manufacturing hubs | Wing Structures | With 15 major aerospace manufacturing hubs in China, the demand for bonding materials in wing structures is increasing. |
| Growth in local aircraft production capacity | Fuselage Assembly | China aims to increase its domestic aircraft production capacity by 20% by 2025, boosting the need for bonding materials. |
Expansion of the Aerospace Composites Bonding market in China is backed by rising end-use demand from local aircraft manufacturers and a strong supply response. In 2022, over 300 commercial aircraft were produced, increasing the need for bonding materials. The demand for lightweight materials is also rising, which is expected to lead to higher consumption of film adhesives. With 15 major aerospace manufacturing hubs, the need for bonding materials in wing structures is growing, further driving market expansion.
Evaluation of Restraints in China Aerospace Composites Bonding Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Compliance with stringent safety regulations | Paste Adhesives | The CAAC updated its Aerospace Safety Regulations in 2021, requiring rigorous testing and certification of bonding materials. |
| Limited availability of high-quality materials | Thermoset Resin | The supply chain for high-quality thermoset resins is constrained, affecting production timelines and costs. |
| Challenges in meeting international standards | Fuselage Assembly | Manufacturers face difficulties in aligning their products with international aerospace standards, impacting export potential. |
| High costs associated with advanced materials | Engine Nacelles | The use of advanced materials in engine nacelles increases production costs, limiting manufacturer profit margins. |
| Market entry barriers for new suppliers | Film Adhesives | New suppliers struggle to meet the established quality standards required by major aircraft manufacturers. |
China Aerospace Composites Bonding Market Challenges
The China Aerospace Composites Bonding Market encounters various practical issues that affect producers. Supply chain disruptions often hinder the availability of essential adhesives, potentially delaying aircraft production timelines for manufacturers. Technological gaps in bonding materials result in inefficiencies, particularly for smaller producers who find it challenging to implement new solutions. Increasing raw material costs have raised the price of aerospace composites bonding, compelling manufacturers to either absorb higher expenses or pass them on to buyers, which could elevate aircraft prices by up to 15%. Skills shortages in the aerospace workforce restrict the adoption of advanced bonding techniques, impacting the quality and reliability of bonded components for manufacturers.
Trends in the China Aerospace Composites Bonding Market
Buyers and suppliers in the China Aerospace Composites Bonding Market are adjusting to the following trends.
- Shift towards Advanced Adhesive Technologies: China is increasingly embracing advanced adhesive technologies in aerospace manufacturing, particularly for wing structures. In 2023, the market for structural adhesives experienced a rise of 7.2%, contributing to the overall growth of the sector.
- Growing Preference for Lightweight Materials: Aircraft manufacturers are prioritising lightweight materials to improve fuel efficiency. This trend has been apparent since 2022, with a reported 44% increase in the use of epoxy resins during production.
- Increased Focus on Sustainability: Sustainability initiatives are transforming the aerospace sector, with a notable shift towards eco-friendly bonding materials. In 2023, the National Development and Reform Commission emphasised sustainability in the Aerospace Industry Development Plan.
- Expansion of Direct Sales Channels: Direct sales channels are gaining prominence in the aerospace composites bonding market. In 2023, direct sales accounted for an 8.4% growth rate, reflecting a change in distribution strategies.
Investment Opportunities in the China Aerospace Composites Bonding Market
Below are the investment opportunities with the strongest case in the China Aerospace Composites Bonding Market.
- Aircraft Manufacturers Seeking Advanced Solutions: Aircraft manufacturers are increasingly looking for advanced bonding solutions to improve aircraft performance. The market gap for new materials is projected to reach USD 2.07 billion by 2025.
- Partnerships with Local Suppliers: Local partnerships are essential for new entrants aiming to penetrate the aerospace bonding market. Collaborating with established OEMs can facilitate market entry and compliance with standards.
- Investment in Aerospace Manufacturing Hubs: Investment in aerospace manufacturing hubs, particularly in regions like Beijing and Shanghai, is essential. The government aims for a 30% increase in local production by 2025.
- Focus on Quality Assurance Schemes: The establishment of quality assurance schemes presents opportunities for suppliers. The Aerospace Product Quality Assurance Scheme ensures high standards, attracting buyers looking for reliable materials.
Government Initiatives in the China Aerospace Composites Bonding Market
The regulatory framework for aerospace composites bonding in China is shaped by several key measures. The Aerospace Safety Regulations, updated by the CAAC in 2021, mandate strict compliance for bonding materials used in aircraft. Additionally, the Aerospace Innovation Strategy launched by the Ministry of Industry and Information Technology in 2022 aims to enhance domestic capabilities in aerospace composites. This strategy supports local manufacturers in meeting international standards and improving product quality. Furthermore, the National Development and Reform Commission approved the Aerospace Industry Development Plan in 2023, targeting a 30% increase in local production capacity by 2025.
The implementation of these regulations is overseen by various agencies, including the CAAC and the Ministry of Industry and Information Technology. The CAAC ensures adherence to safety regulations, while the Ministry of Industry and Information Technology funds initiatives that strengthen domestic aerospace capabilities. The Aerospace Product Quality Assurance Scheme, established by the State Administration for Market Regulation, ensures that bonding materials meet high standards, benefiting both producers and buyers.
Future Insight of the China Aerospace Composites Bonding Market
The China Aerospace Composites Bonding Market is expected to evolve significantly by 2032, driven by the 'Aerospace Industry Development Plan' which aims to bolster local manufacturing capabilities. Domestic aircraft production capacity is set to rise by 20% by 2025, leading to increased demand for innovative bonding solutions. Investments exceeding $10 billion in aerospace R&D since 2020 are anticipated to result in breakthroughs in bonding technologies. Compliance with ISO 9001 standards will improve quality management across the sector, benefiting both buyers and suppliers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Bonding Type – Structural Adhesives Dominated, Film Adhesives Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, Structural Adhesives held a 36% share of the China Aerospace Composites Bonding Market by bonding type in 2025. Structural adhesives command the largest market share due to their vital role in ensuring the structural integrity of aircraft components. Their importance is highlighted by the production of over 300 commercial aircraft in 2022, which relies heavily on these adhesives for safety and performance. Film Adhesives are set to record the highest CAGR in this split, 7.8% over 2026–2032. Film adhesives are experiencing rapid growth as they are essential for bonding composite layers in aircraft structures. This trend is driven by the anticipated 20% increase in aircraft production capacity by 2025, indicating a strong commitment to advanced aerospace technology. Suppliers should prioritise structural adhesives to meet the growing demands from local aircraft manufacturers.
By Resin Type – Epoxy Resin Dominated, Thermoset Resin Expected to Grow Fastest
With a 44% revenue share in 2025, Epoxy Resin was the largest resin type category. Epoxy resin leads the market share as it is widely recognised for its strong bonding properties, making it the preferred choice among manufacturers. Its extensive use in various aerospace applications solidifies its position in the market. The quickest growth will come from Thermoset Resin, forecast to expand at a CAGR of 7.8% between 2026 and 2032. Thermoset resin is growing rapidly due to its importance in durable and heat-resistant applications, which are critical in aerospace manufacturing. The increasing emphasis on high-performance materials in aircraft production drives this growth. Suppliers should prioritise the development of epoxy resin solutions to cater to the strong demand from the aerospace industry.
By Application Area – Wing Structures Dominated, Fuselage Assembly Expected to Grow Fastest
The largest application area category in 2025 was Wing Structures, with a 53% share of total revenue. Wing structures hold the largest market share as they are critical for the overall performance and safety of aircraft. The aerospace sector's focus on enhancing wing design and efficiency solidifies this segment's leading position. Over 2026–2032, Fuselage Assembly is expected to post the fastest growth, at a CAGR of 7.6%. Fuselage assembly is the fastest-growing application area, reflecting its crucial role in the overall aircraft structure. The increasing complexity of fuselage designs requires advanced bonding solutions, driving significant demand in this segment. Suppliers need to adjust their strategies to cater to the rising demand for bonding solutions in fuselage assembly.
By Distribution Channel – OEMs Dominated, Direct Sales Expected to Grow Fastest
In 2025, OEMs led the distribution channel split with a 46% share. OEMs hold the largest market share as they are the primary customers for aerospace bonding materials, directly influencing production standards. Their established connections with manufacturers ensure a consistent demand for high-quality bonding solutions. Direct Sales is projected to grow fastest, at a CAGR of 8.4% during 2026–2032. Direct sales are growing rapidly as they offer a streamlined approach for suppliers to connect with manufacturers. This method enhances communication and response times, strengthening supplier-customer relationships. Suppliers should enhance their direct sales channels to better serve OEMs and meet evolving market demands.
By End User – Aircraft Manufacturers Dominated, Composite Material Providers Expected to Grow Fastest
Aircraft Manufacturers accounted for a 38% market share by end user in 2025. Aircraft manufacturers represent the largest market share as they are the main consumers of bonding products essential for aircraft assembly. Their substantial investments in new aircraft models drive the demand for advanced bonding solutions. Composite Material Providers are set to record the highest CAGR in this split, 7.2% over 2026–2032. Composite material providers are the fastest-growing end users, supplying essential materials that require effective bonding for aircraft production. The increasing utilisation of composites in aircraft design fuels this growth. Suppliers should focus on forming partnerships with composite material providers to capitalise on this expanding market segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Aerospace Composites Bonding Market Outlook
- Market Size of China Aerospace Composites Bonding Market, 2025
- Forecast of China Aerospace Composites Bonding Market, 2032
- Historical Data and Forecast of China Aerospace Composites Bonding Revenues & Volume for the Period 2022 - 2032F
- China Aerospace Composites Bonding Market Trend Evolution
- China Aerospace Composites Bonding Market Drivers and Challenges
- China Aerospace Composites Bonding Price Trends
- China Aerospace Composites Bonding Porter's Five Forces
- China Aerospace Composites Bonding Industry Life Cycle
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Bonding Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Film Adhesives for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Paste Adhesives for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Liquid Shims for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Structural Adhesives for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Resin Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Epoxy Resin for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Phenolic Resin for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Polyurethane Resin for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Thermoset Resin for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Wing Structures for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Engine Nacelles for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Fuselage Assembly for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Interiors & Seats for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Industrial Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Aircraft Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Aerospace Engineers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Composite Material Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Composites Bonding Market Revenues & Volume By Cabin Component Suppliers for the Period 2022 - 2032F
- China Aerospace Composites Bonding Import Export Trade Statistics
- Market Opportunity Assessment By Bonding Type
- Market Opportunity Assessment By Resin Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Aerospace Composites Bonding Top Companies Market Share
- China Aerospace Composites Bonding Competitive Benchmarking By Technical and Operational Parameters
- China Aerospace Composites Bonding Company Profiles
- China Aerospace Composites Bonding Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Bonding Type
- Film Adhesives
- Paste Adhesives
- Liquid Shims
- Structural Adhesives
By Resin Type
- Epoxy Resin
- Phenolic Resin
- Polyurethane Resin
- Thermoset Resin
By Application Area
- Wing Structures
- Engine Nacelles
- Fuselage Assembly
- Interiors & Seats
By Distribution Channel
- OEMs
- Industrial Suppliers
- Direct Sales
- Online Platforms
By End User
- Aircraft Manufacturers
- Aerospace Engineers
- Composite Material Providers
- Cabin Component Suppliers






































