China Aerospace Cyber Solutions Market Size & Growth Rate
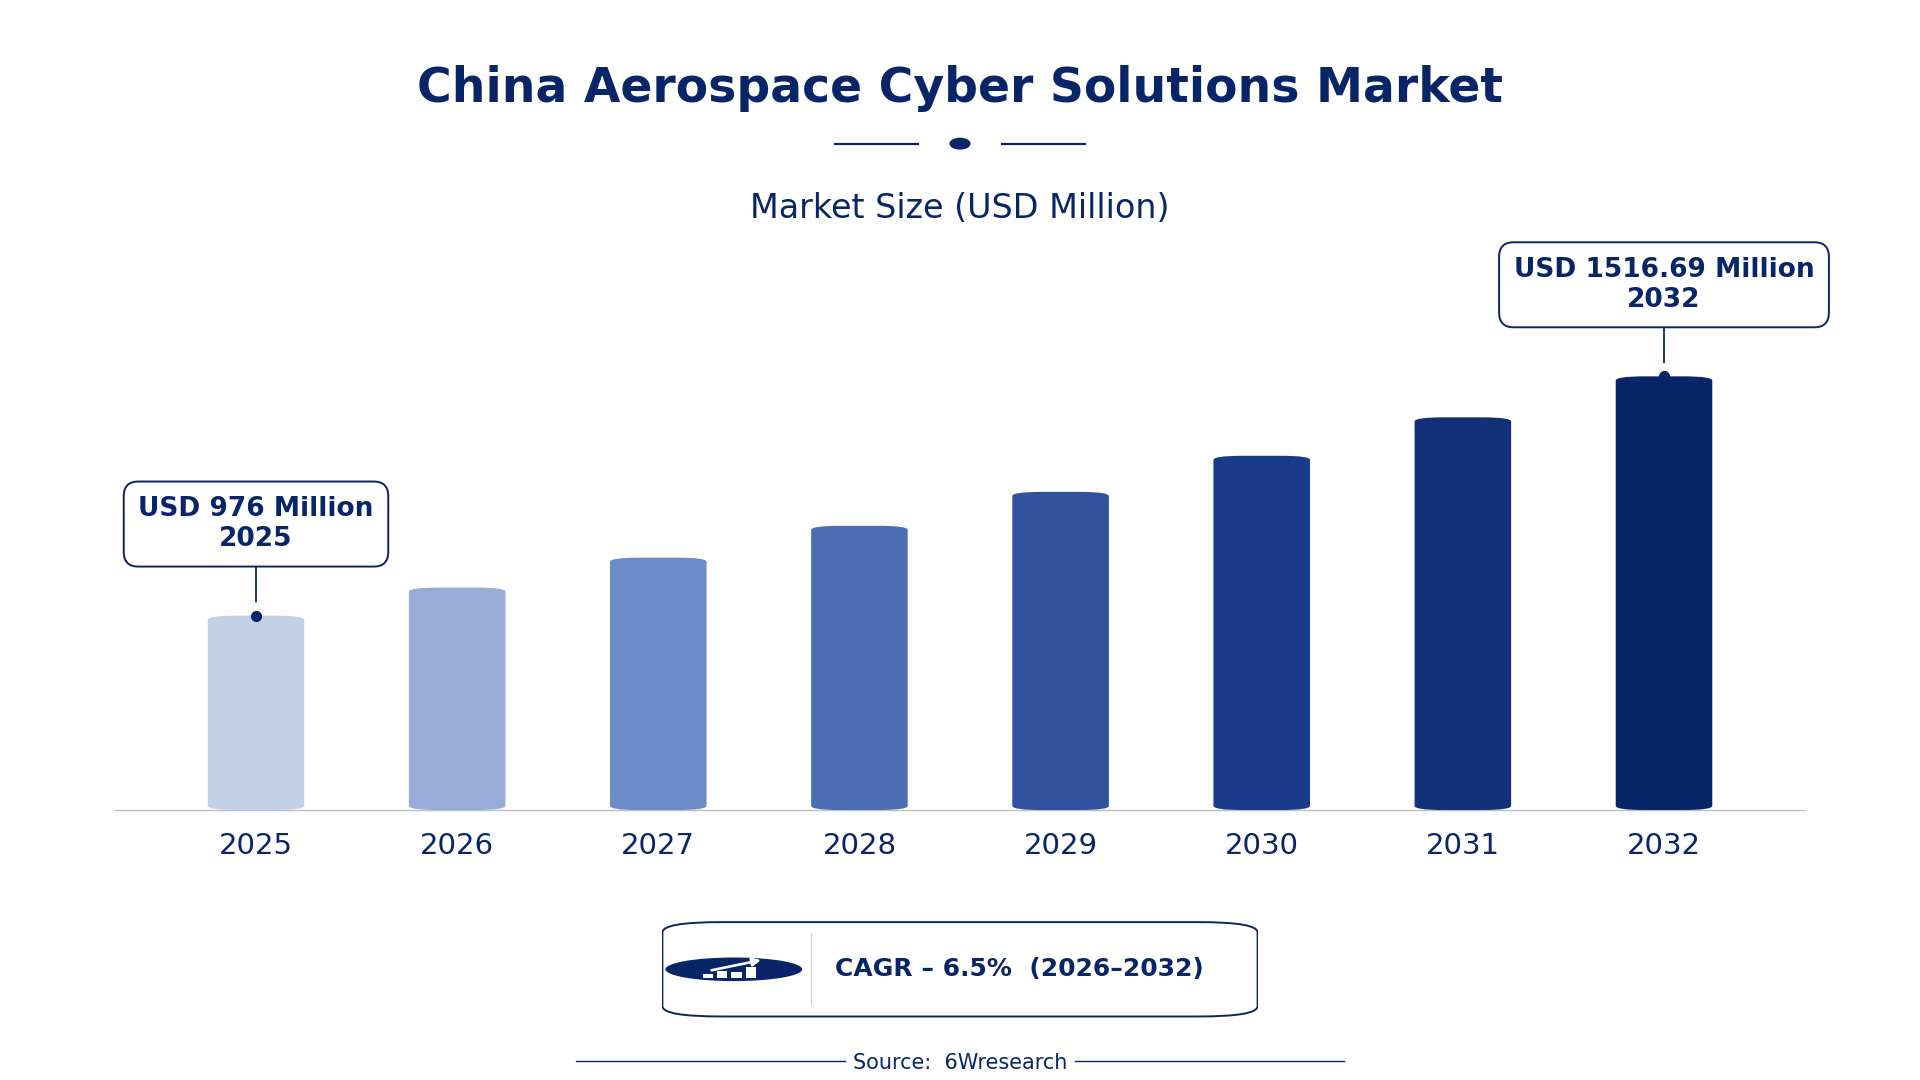
According to 6Wresearch internal database and industry insights, the China Aerospace Cyber Solutions Market was valued at USD 976.0 million in 2025 and is projected to reach USD 1,516.69 million by 2032, growing at a CAGR of approximately 6.5% during 2026–2032.
China Aerospace Cyber Solutions Market Highlights
| Report Metric | Details |
| Report Name | China Aerospace Cyber Solutions Market |
| Market Size 2025 | USD 976.0 million |
| Market Size 2032 | USD 1,516.69 million |
| Absolute Growth 2025–2032 | USD 540.69 million |
| CAGR 2026–2032 | 6.5% |
| Peak Annual Growth | 8.5% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Solution Type, 2025 | Network Security (39% share) |
| Leading Security Layer, 2025 | Perimeter Defense (41% share) |
| Leading Service Model, 2025 | Managed Services (37% share) |
| Leading Distribution Channel, 2025 | Online Platforms (44% share) |
| Leading End User, 2025 | Aerospace IT Firms (37% share) |
| Fastest-Growing Solution Type | Cloud Security (8.4% CAGR) |
| Fastest-Growing Security Layer | Application-Level (8.7% CAGR) |
| Fastest-Growing Service Model | SaaS (8.4% CAGR) |
| Fastest-Growing End User | Military Aircraft OEMs (7.9% CAGR) |
| Growing Sector | Aerospace IT Firms |
| Key End Users | Aerospace IT Firms, Military Aircraft OEMs, Space Agencies, Defense Communications |
China Aerospace Cyber Solutions Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
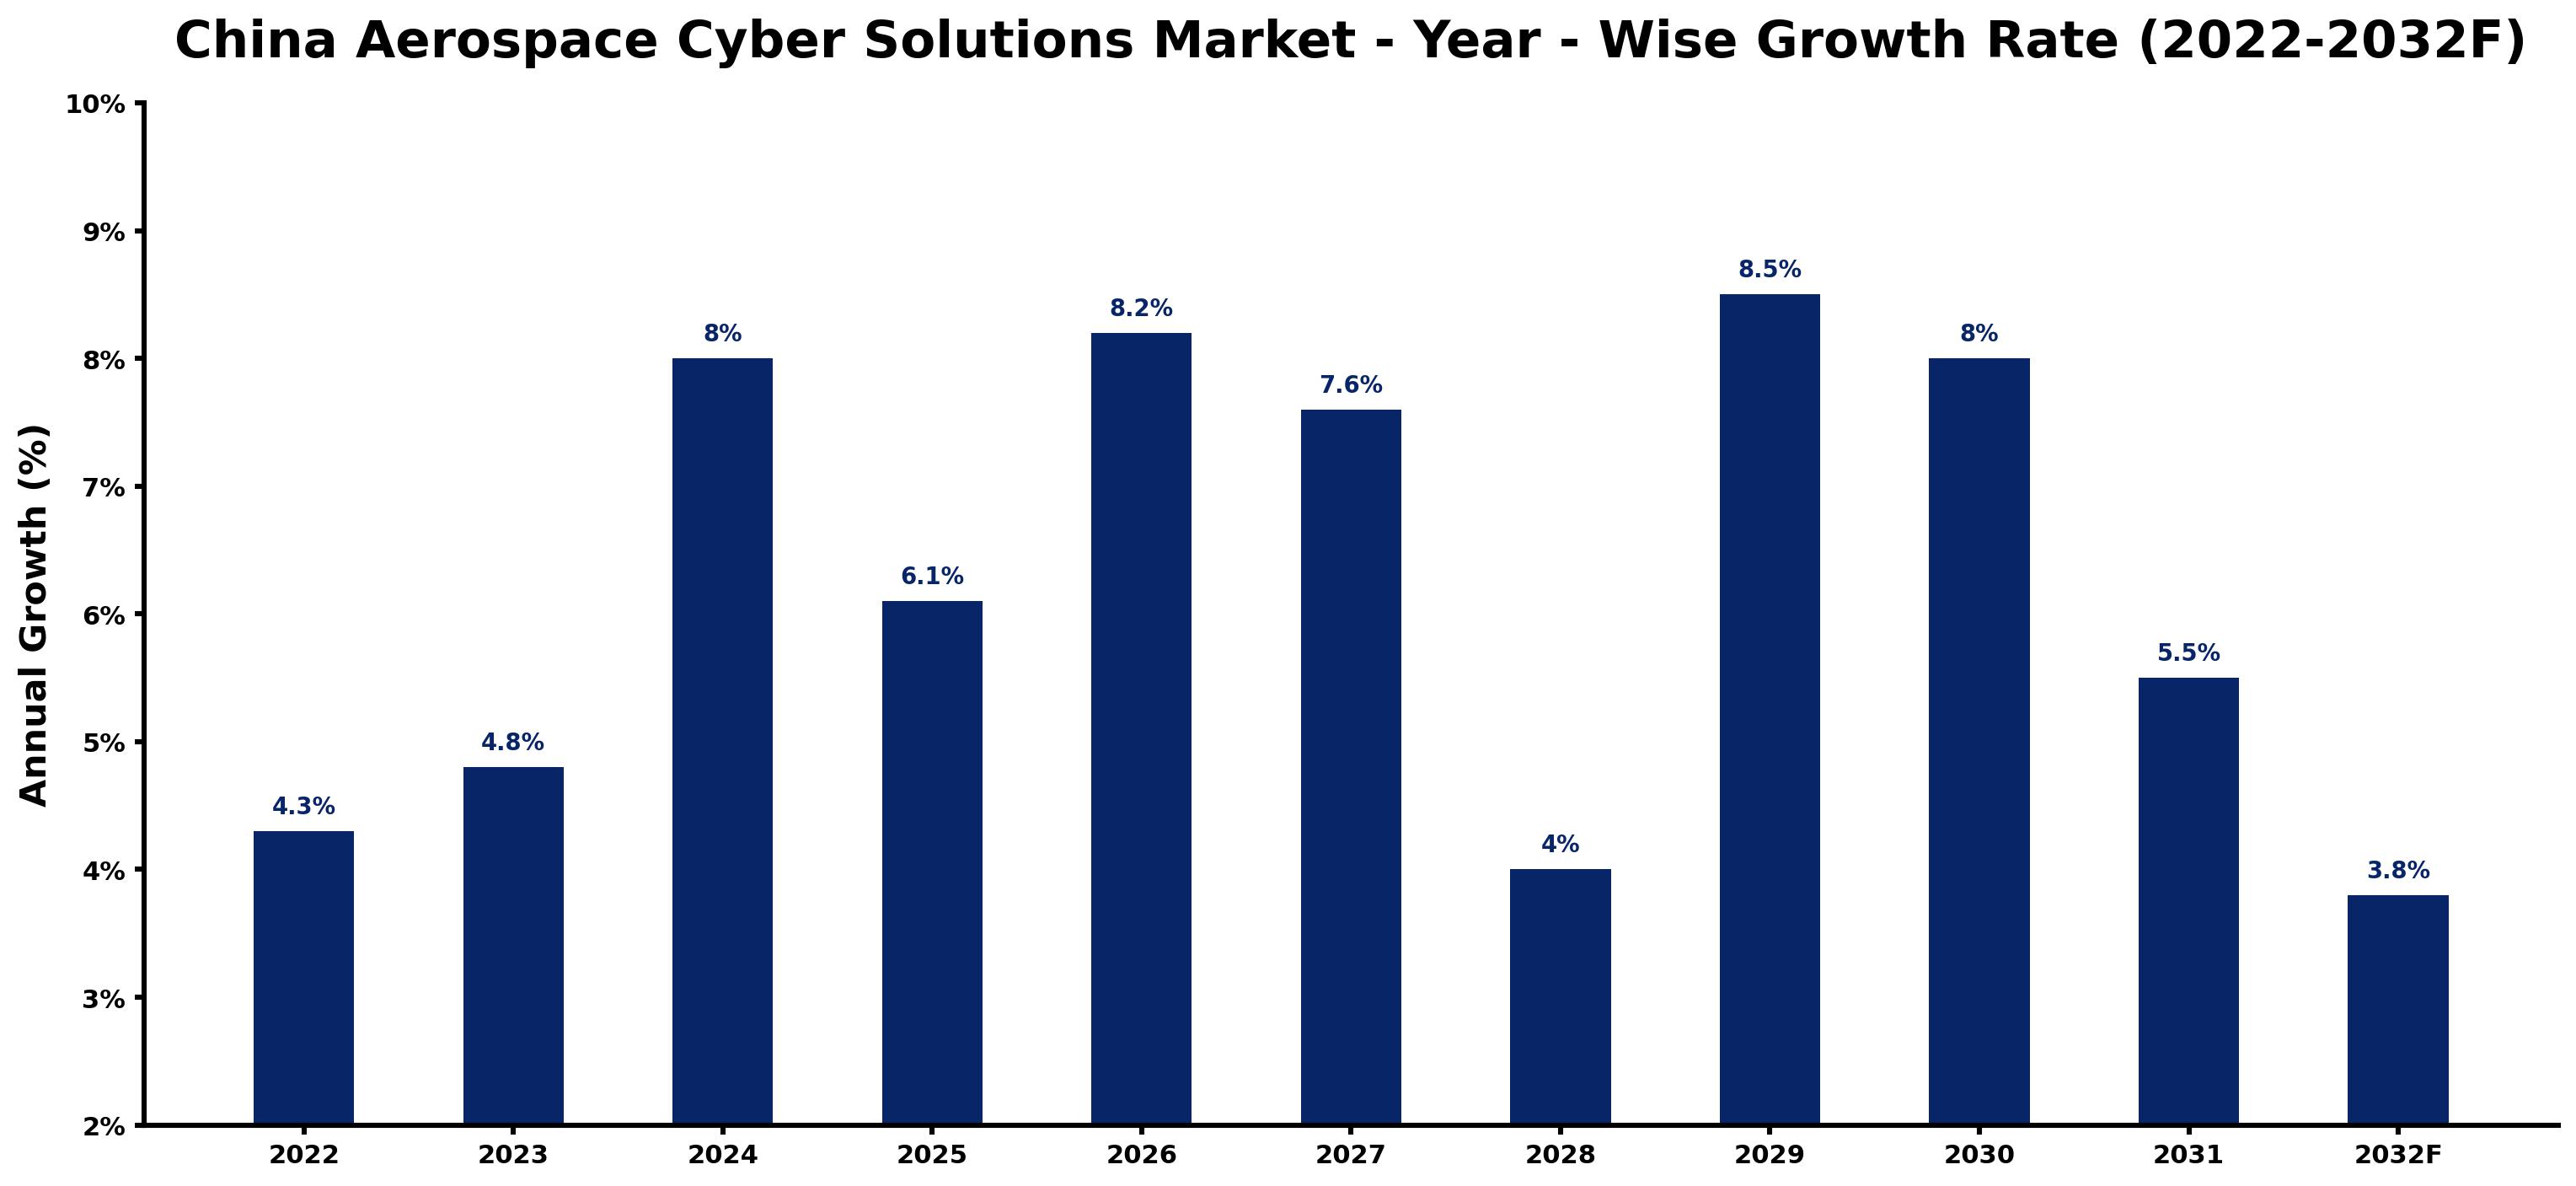
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.3 | The market experienced steady growth due to ongoing cybersecurity needs in aerospace. |
| 2023 | 4.8 | Demand increased as military aircraft OEMs sought enhanced security measures. |
| 2024 | 8.0 | A surge in investment for cybersecurity solutions drove significant growth in the sector. |
| 2025 | 6.1 | Growth slowed as the market adjusted to previous high demand levels. |
| 2026 | 8.2 | The introduction of new cybersecurity standards is expected to spur increased investment and demand. |
| 2027 | 7.6 | A focus on cloud security solutions will contribute to a continued rise in the market. |
| 2028 | 4.0 | Growth is projected to slow as the market faces saturation in certain areas of cybersecurity. |
| 2029 | 8.5 | Aerospace Cybersecurity Enhancement Program funding will lead to a peak in demand. |
| 2030 | 8.0 | The market is expected to experience a slowdown as previous growth rates normalise. |
| 2031 | 5.5 | Demand will continue to slow as the market stabilises after rapid growth periods. |
| 2032 | 3.8 | A focus on developing skilled cybersecurity professionals will support ongoing growth. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Aerospace Cyber Solutions Market Synopsis
These solutions are essential for safeguarding military and civilian aerospace operations, ensuring data integrity, and maintaining operational continuity. The market is growing due to rising demand from domestic aerospace IT firms and military aircraft OEMs, alongside collaborations with space agencies. The military budget for cybersecurity in 2023 is estimated at 300 billion CNY, further driving investments in this sector. The Aerospace Cybersecurity Enhancement Program initiated in 2023 is boosting demand for advanced cybersecurity solutions.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing military budget for cybersecurity initiatives | Driver | High | Network Security |
| Increased focus on cloud security solutions | Driver | High | Cloud Security |
| Rising demand for secure aerospace communications | Opportunity | High | Endpoint Protection |
| Investment in cybersecurity talent development | Opportunity | Medium | Managed Services |
| Challenges in integrating new cybersecurity standards | Restraint | High | Encryption Solutions |
| Market saturation in certain cybersecurity sectors | Restraint | Medium | Perimeter Defense |
| The Aerospace Cyber Solutions Market in China faces a shortage of skilled professionals | Challenge | High | Aerospace IT Firms |
| Integration of cybersecurity measures in military operations is complex | Challenge | Medium | Military Aircraft OEMs |
Evaluation of Drivers in China Aerospace Cyber Solutions Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased military budget allocations for cybersecurity | Network Security | The military budget for cybersecurity in 2023 is estimated at 300 billion CNY, driving demand for network security solutions. |
| Growing adoption of cloud-based solutions | Cloud Security | The shift towards cloud security solutions is driven by the need for flexible and scalable cybersecurity measures. |
| Rising demand from aerospace IT firms | Endpoint Protection | The over 200 aerospace IT firms in China are increasingly investing in endpoint protection to secure their operations. |
| Focus on regulatory compliance | Encryption Solutions | Compliance with ISO/IEC 27001 standards is pushing aerospace firms to adopt encryption solutions. |
| Investment in talent development programs | Managed Services | The Cybersecurity Talent Cultivation Program aims to train 10,000 professionals by 2025, improving service capabilities in the sector. |
The Aerospace Cyber Solutions market in China is expanding due to increased military budget allocations for cybersecurity and the growing adoption of cloud-based solutions. The military budget for cybersecurity in 2023 is estimated at 300 billion CNY, which is boosting demand for network security solutions. Domestic aerospace IT firms are investing more in endpoint protection to secure their operations. Compliance with ISO/IEC 27001 standards is encouraging aerospace firms to implement encryption solutions.
Evaluation of Restraints in China Aerospace Cyber Solutions Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Shortage of skilled cybersecurity professionals | Aerospace IT Firms | The limited availability of qualified personnel hampers the ability of aerospace IT firms to implement advanced cybersecurity measures. |
| Complex integration of cybersecurity measures | Military Aircraft OEMs | Integrating new cybersecurity standards into existing military operations poses challenges for military aircraft OEMs. |
| Market saturation in certain cybersecurity sectors | Perimeter Defense | As the market matures, certain segments like perimeter defense face saturation, limiting growth opportunities. |
| Regulatory compliance costs | Encryption Solutions | The costs associated with meeting stringent regulatory requirements for encryption solutions can deter investment. |
| Technological obsolescence risks | Cloud Security | Rapid advancements in technology may render existing cloud security solutions obsolete, affecting long-term investments. |
China Aerospace Cyber Solutions Market Challenges
The Aerospace Cyber Solutions market in China faces technological shortcomings, as emerging cyber threats outpace existing security measures. This technology gap can lead to potential losses exceeding 300 billion CNY for aerospace IT firms, undermining their ability to protect critical systems. Regulatory challenges from the Cybersecurity Law impose compliance costs that may delay project timelines for buyers, reducing their operational efficiency. Suppliers contend with fierce competition among over 200 firms, driving prices down and squeezing profit margins, which hampers their capacity to invest in necessary advancements.
Trends in the China Aerospace Cyber Solutions Market
Four trends stand out in the China Aerospace Cyber Solutions Market.
- Shift Towards Cloud Security Solutions: Aerospace IT firms are adopting cloud security solutions to improve flexibility and scalability. In 2023, cloud security investments grew by 25%, reflecting the need for effective cybersecurity in aerospace.
- Growing Demand for Endpoint Protection: In 2023, the demand for endpoint protection surged as over 200 aerospace IT firms sought to secure their operations. This trend highlights the need for effective cybersecurity measures.
- Increased Focus on Cybersecurity Standards: The publication of the Cybersecurity Standards for Aerospace in 2021 has driven firms to improve their security protocols. Compliance with these standards is essential for maintaining operational integrity.
- Expansion of Cybersecurity Talent Development Programs: The Cybersecurity Talent Cultivation Program initiated in 2020 aims to train skilled professionals by 2025. This initiative is vital for addressing the skills gap in the aerospace cybersecurity sector.
Investment Opportunities in the China Aerospace Cyber Solutions Market
Investors looking at the China Aerospace Cyber Solutions Market should consider the following areas.
- Growing Need for Secure Aerospace Communications: With China's population of approximately 1.4 billion, the demand for secure aerospace communications is critical. Investing in encryption solutions can meet this demand effectively.
- Investment in Cybersecurity Talent Development: Now is the time to invest in training programs for cybersecurity professionals, as the Cybersecurity Talent Cultivation Program aims to develop skilled workers by 2025.
- Expanding Market for Managed Services: The managed services sector is expanding as aerospace firms seek specialized expertise. Partnering with local firms can facilitate entry into this growing market.
- Focus on Compliance with Cybersecurity Standards: The publication of the Cybersecurity Standards for Aerospace creates opportunities for firms to supply compliant solutions. Engaging with aerospace IT firms can improve market presence.
Government Initiatives in the China Aerospace Cyber Solutions Market
The Cybersecurity Law of the People's Republic of China, enacted in 2017, mandates improved data protection for aerospace systems, overseen by the Ministry of Industry and Information Technology. This law requires aerospace firms to implement rigorous data protection measures, ensuring their systems are secure against cyber threats. The National Cybersecurity Strategy was revised in 2021 to include specific measures for the aerospace sector, aiming to strengthen national security by integrating cybersecurity protocols into aerospace operations. The Aerospace Cybersecurity Enhancement Program, launched in 2023, allocates 500 million CNY to enhance cybersecurity infrastructure, directly benefiting aerospace firms by providing funding for advanced security technologies.
The National Cybersecurity and Information Technology Agency supervises compliance in the aerospace sector, ensuring adherence to established cybersecurity standards. This agency assesses aerospace systems for vulnerabilities and grants necessary approvals for cybersecurity measures. The National Defense Cybersecurity Initiative focuses on incorporating cybersecurity measures in military aerospace operations, aiming to reduce vulnerabilities by 30% by 2025. The Defense Innovation Fund allocates resources for advancing cybersecurity technologies, supporting projects that enhance the security of aerospace systems.
Future Insight of the China Aerospace Cyber Solutions Market
The Aerospace Cyber Solutions market in China is set for substantial change by 2032, with the Aerospace Cybersecurity Improvement Initiative expected to strengthen system protections. The military budget for cybersecurity is projected to increase, enabling considerable advancements in protective technologies. Collaborations with the National Defense Science and Technology Innovation Program will promote innovation in cybersecurity research. The Cybersecurity Talent Development Program will also ensure a steady supply of skilled professionals, preparing the sector to effectively address emerging cyber threats.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Solution Type – Network Security Dominated, Cloud Security Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, Network Security took a 39% share of solution type in 2025, more than any other category. Network Security dominates the aerospace cyber solutions market due to its essential role in safeguarding networks from cyber threats. The involvement of over 200 aerospace IT firms indicates a robust demand for these solutions, particularly from military aircraft OEMs. Over 2026–2032, Cloud Security is expected to post the fastest growth, at a CAGR of 8.4%. Cloud Security is experiencing rapid growth as aerospace applications shift to cloud environments, necessitating enhanced protective measures. This trend is propelled by the increasing reliance on cloud-based systems for operational continuity in the aerospace sector. Suppliers should focus on developing advanced cloud security solutions to meet the rising demand from aerospace clients.
By Security Layer – Perimeter Defense Dominated, Application-Level Expected to Grow Fastest
With a 41% revenue share in 2025, Perimeter Defense was the largest security layer category. Perimeter Defense leads the security layer segment, as it is vital for protecting network boundaries from external cyber threats. The Cybersecurity Standards for Aerospace established in 2021 emphasise the critical nature of perimeter protection in maintaining security. Application-Level is set to record the highest CAGR in this split, 8.7% over 2026–2032. Application-Level security is growing swiftly due to the need for specific protection of aerospace applications, especially with the complexity of modern software systems. The government's Aerospace Cybersecurity Enhancement Program highlights the focus on improving application security measures. Buyers should invest in application-level security solutions to ensure comprehensive protection for their aerospace operations.
By Service Model – Managed Services Dominated, SaaS Expected to Grow Fastest
The largest service model category in 2025 was Managed Services, with a 37% share of total revenue. Managed Services dominates the service model segment, as many aerospace firms outsource their cybersecurity needs to access specialised expertise. This trend is reflected in the Defence Innovation Fund, which supports the development of managed service capabilities in the sector. SaaS are projected to grow fastest, at a CAGR of 8.4% during 2026–2032. SaaS is gaining rapid traction, driven by the demand for flexible and scalable cybersecurity solutions that can adapt to evolving needs. The shift towards remote operations in the aerospace sector further accelerates the growth of this model. Suppliers should consider expanding their SaaS offerings to meet the changing preferences of aerospace clients.
By Distribution Channel – Online Platforms Dominated and Is Expected to Record the Fastest Growth
Online Platforms held a 44% share of the China Aerospace Cyber Solutions Market by distribution channel in 2025. Online Platforms are the leading distribution channel, serving as a primary means for disseminating information and marketing cybersecurity solutions to aerospace firms. Their accessibility enables broader engagement with potential clients across the industry. The same category are also set to grow fastest, at a CAGR of 7.7% during 2026–2032. Online Platforms are also the fastest-growing channel, as digital engagement becomes crucial for reaching aerospace stakeholders. The increasing shift towards online marketing strategies in the aerospace sector drives this growth. Suppliers must strengthen their online presence to effectively connect with aerospace clients and capture market share.
By End User – Aerospace IT Firms Dominated, Military Aircraft OEMs Expected to Grow Fastest
Aerospace IT Firms accounted for a 37% market share by end user in 2025. Aerospace IT Firms represent the largest end user group, as they are the primary consumers of cybersecurity solutions necessary for protecting their operations. Their significant demand is supported by ongoing advancements in cybersecurity technologies within these firms. Over 2026–2032, Military Aircraft OEMs are expected to post the fastest growth, at a CAGR of 7.9%. Military Aircraft OEMs are the fastest-growing segment, driven by increased defense requirements and a substantial military budget for cybersecurity. The projected military budget for cybersecurity in 2023, estimated at 300 billion CNY, underscores this heightened demand. Suppliers should tailor their offerings to address the specific needs of military aircraft OEMs to capitalise on this growth opportunity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Aerospace Cyber Solutions Market Outlook
- Market Size of China Aerospace Cyber Solutions Market, 2025
- Forecast of China Aerospace Cyber Solutions Market, 2032
- Historical Data and Forecast of China Aerospace Cyber Solutions Revenues & Volume for the Period 2022 - 2032F
- China Aerospace Cyber Solutions Market Trend Evolution
- China Aerospace Cyber Solutions Market Drivers and Challenges
- China Aerospace Cyber Solutions Price Trends
- China Aerospace Cyber Solutions Porter's Five Forces
- China Aerospace Cyber Solutions Industry Life Cycle
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Solution Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Network Security for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Endpoint Protection for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Cloud Security for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Encryption Solutions for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Security Layer for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Perimeter Defense for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Device-Level Security for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Application-Level for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Data-Level Encryption for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Service Model for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Managed Services for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By SaaS for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Subscription for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Project-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Direct Engagement for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Security Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Aerospace IT Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Military Aircraft OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Space Agencies for the Period 2022 - 2032F
- Historical Data and Forecast of China Aerospace Cyber Solutions Market Revenues & Volume By Defense Communications for the Period 2022 - 2032F
- China Aerospace Cyber Solutions Import Export Trade Statistics
- Market Opportunity Assessment By Solution Type
- Market Opportunity Assessment By Security Layer
- Market Opportunity Assessment By Service Model
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Aerospace Cyber Solutions Top Companies Market Share
- China Aerospace Cyber Solutions Competitive Benchmarking By Technical and Operational Parameters
- China Aerospace Cyber Solutions Company Profiles
- China Aerospace Cyber Solutions Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Solution Type
- Network Security
- Endpoint Protection
- Cloud Security
- Encryption Solutions
By Security Layer
- Perimeter Defense
- Device-Level Security
- Application-Level
- Data-Level Encryption
By Service Model
- Managed Services
- SaaS
- Subscription
- Project-Based
By Distribution Channel
- Online Platforms
- Direct Engagement
- Security Vendors
- OEMs
By End User
- Aerospace IT Firms
- Military Aircraft OEMs
- Space Agencies
- Defense Communications






































