China Airborne EO/IR Payload Market Size & Growth Rate
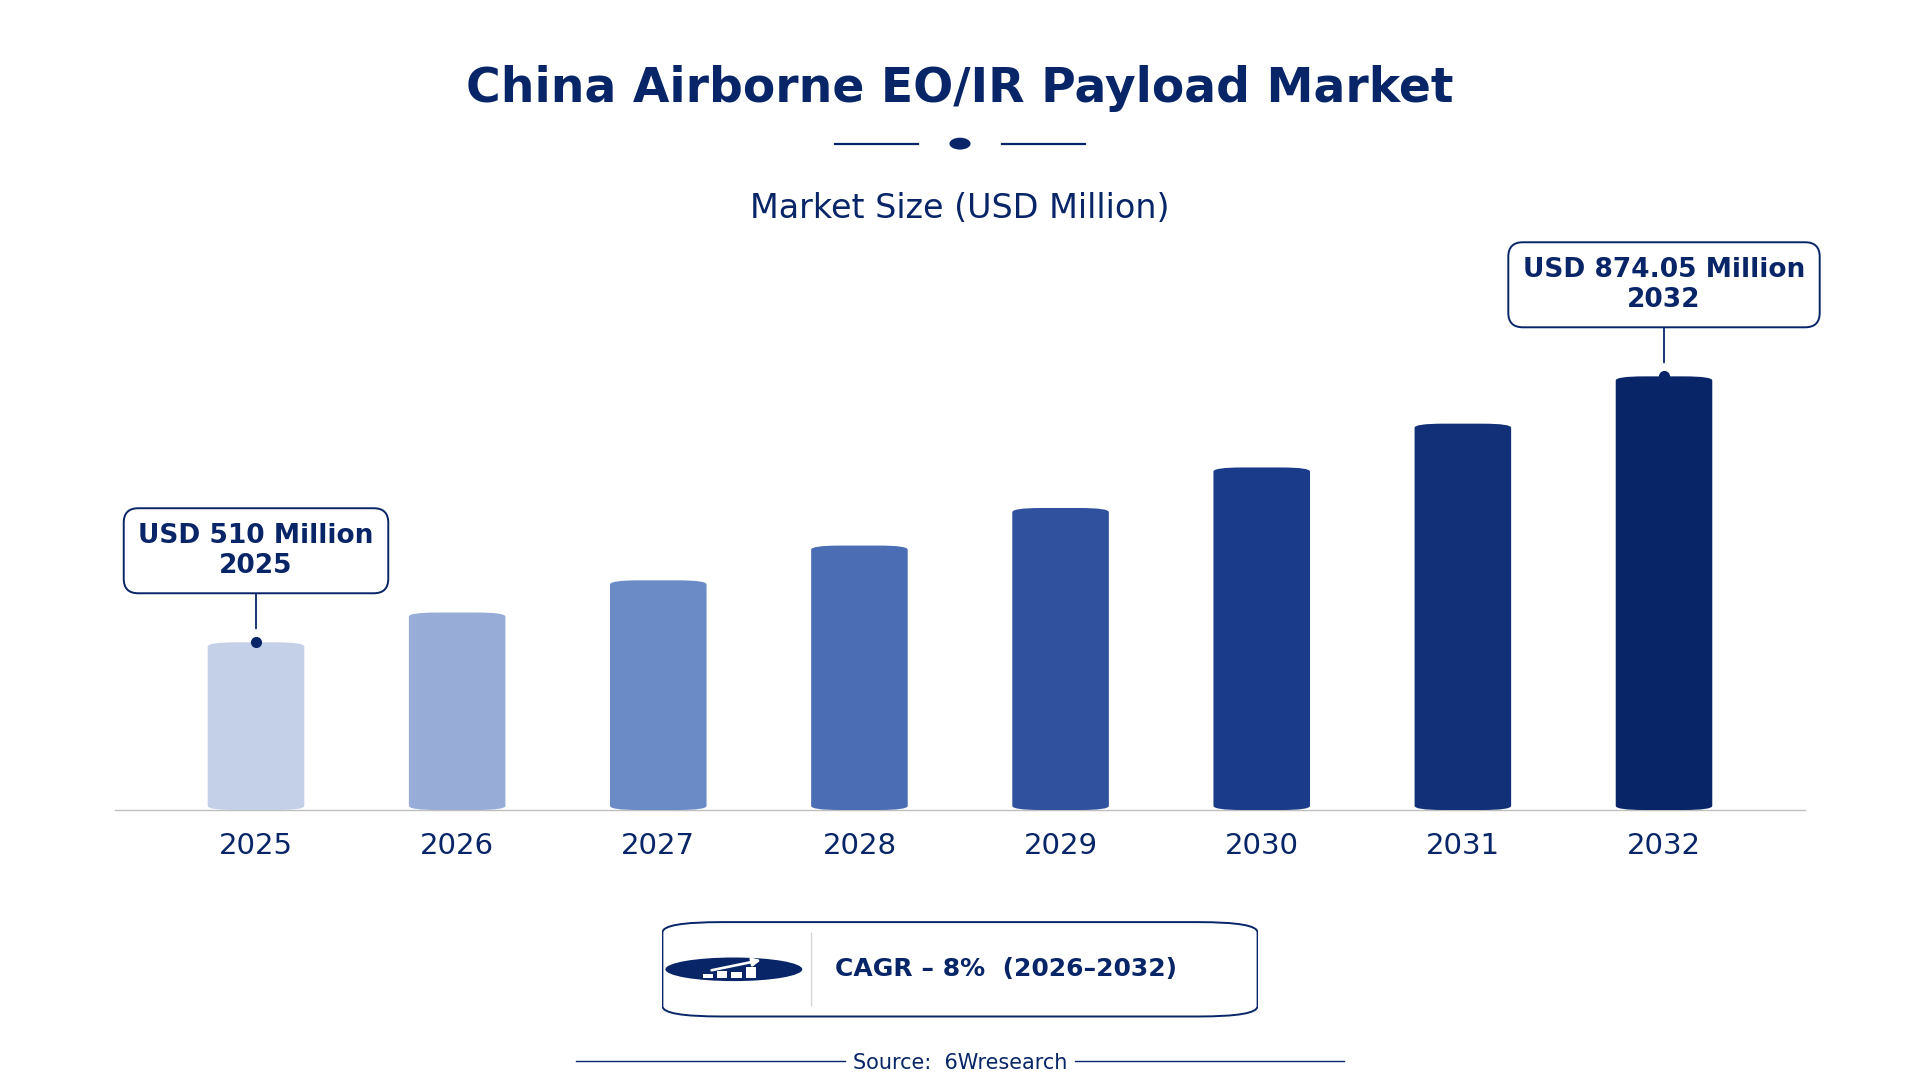
According to 6Wresearch internal database and industry insights, the China Airborne EO/IR Payload Market was valued at USD 510.0 million in 2025 and is projected to reach USD 874.05 million by 2032, growing at a CAGR of approximately 8% during 2026–2032.
China Airborne EO/IR Payload Market Highlights
| Report Metric | Details |
| Report Name | China Airborne EO/IR Payload Market |
| Market Size 2025 | USD 510.0 million |
| Market Size 2032 | USD 874.05 million |
| Absolute Growth 2025–2032 | USD 364.05 million |
| CAGR 2026–2032 | 8% |
| Peak Annual Growth | 10.1% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Payload Type, 2025 | EO Cameras (37% share) |
| Leading Imaging Spectrum, 2025 | Visible Light (36% share) |
| Leading Distribution Channel, 2025 | Defense System Integrators (46% share) |
| Leading End User, 2025 | Tactical UAV Manufacturers (50% share) |
| Fastest-Growing Payload Type | IR Sensors (9.4% CAGR) |
| Fastest-Growing Imaging Spectrum | Thermal Imaging (9.9% CAGR) |
| Fastest-Growing Distribution Channel | Surveillance System OEMs (10.4% CAGR) |
| Fastest-Growing End User | Night Vision Drone Providers (9.4% CAGR) |
| Growing Sector | Military Surveillance |
| Key End Users | Tactical UAV Manufacturers, Maritime Surveillance Units, Surveillance System OEMs |
China Airborne EO/IR Payload Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
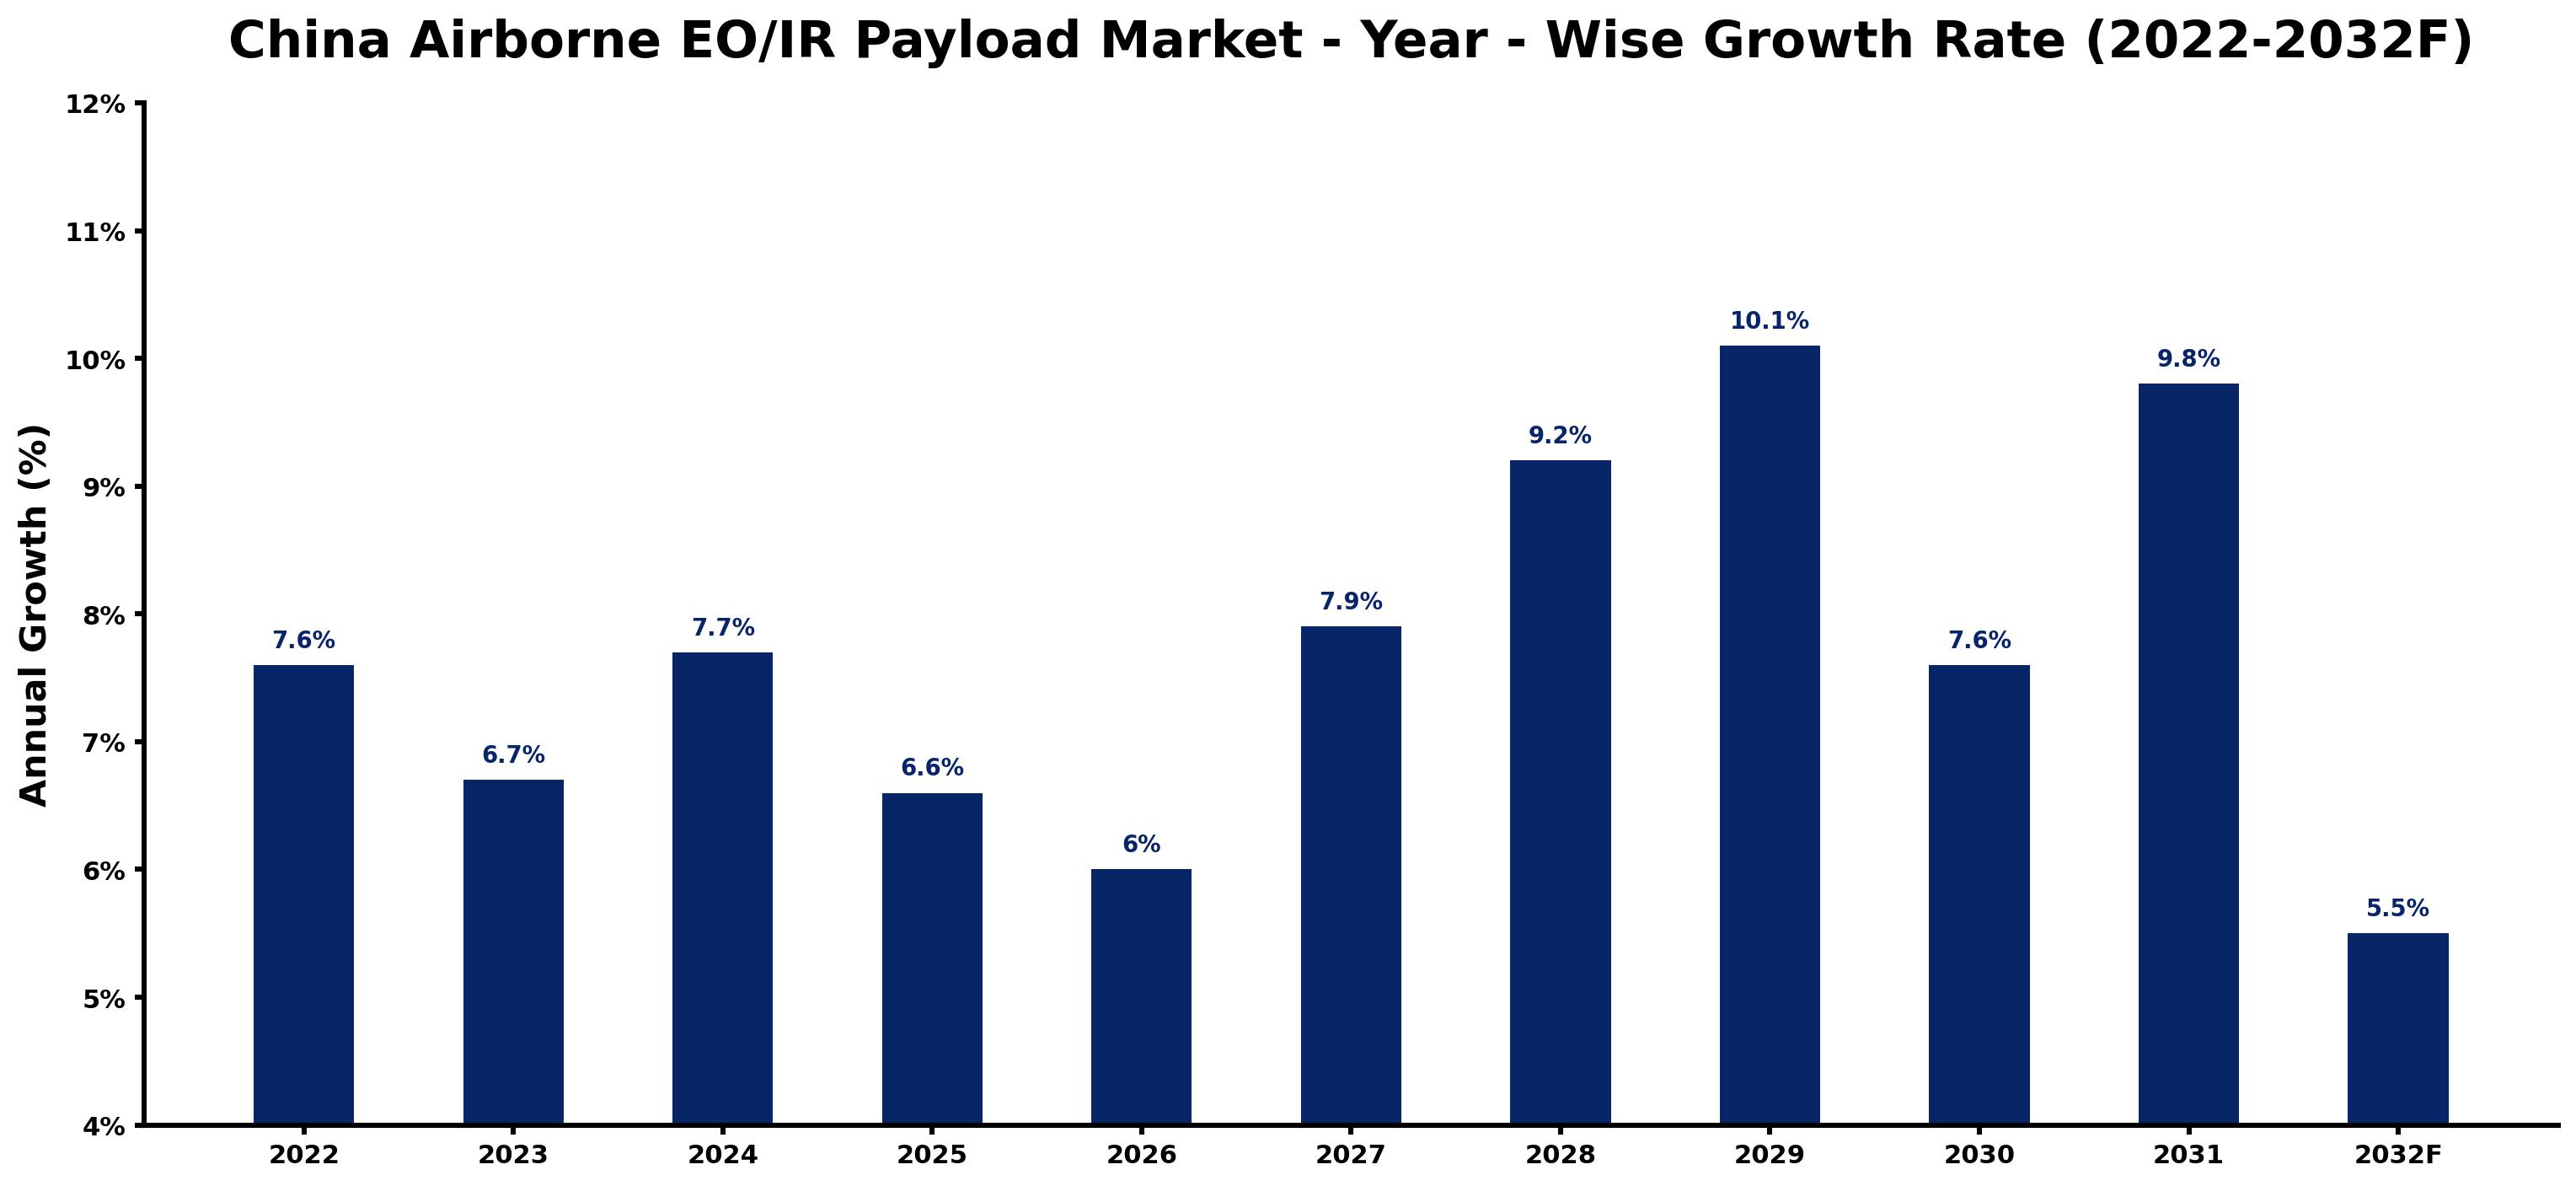
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.6 | The market experienced steady growth, driven by the Advanced Aerial Surveillance Program initiated by the Ministry of Defense. |
| 2023 | 6.7 | Growth slowed as budget reallocations impacted procurement rates for new systems, affecting military spending. |
| 2024 | 7.7 | Demand accelerated with rising investments in aerial reconnaissance capabilities by the PLA Air Force. |
| 2025 | 6.6 | Growth decelerated again as budget adjustments affected spending on advanced imaging systems. |
| 2026 | 6.0 | A slowdown occurred as military priorities shifted, impacting the pace of new technology integration. |
| 2027 | 7.9 | Increased demand emerged from tactical UAV manufacturers focusing on payload capabilities for operational efficiency. |
| 2028 | 9.2 | Growth surged as military contracts expanded, driven by heightened security concerns in Guangdong province. |
| 2029 | 10.1 | A peak in growth was reached with significant investments in EO/IR technologies for military applications. |
| 2030 | 7.6 | Growth moderated as the market adjusted to previous high levels of investment and demand. |
| 2031 | 9.8 | Demand rose again as modernization efforts in aerial surveillance continued to gain traction. |
| 2032 | 5.5 | Growth slowed as the market stabilizes, reflecting a maturing phase in technology adoption. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Airborne EO/IR Payload Market Synopsis
The Airborne EO/IR Payload in China includes advanced imaging systems that combine electro-optical and infrared technologies for military use. These payloads play a crucial role in intelligence gathering, border security, and maritime surveillance, utilising sophisticated optics and sensors. The China Airborne EO/IR Payload Market is growing due to increased investments from domestic military agencies, with a military budget for aerial surveillance technologies around 200 billion CNY. The Advanced Aerial Surveillance Program launched in 2021 has further increased demand, ensuring ongoing activity in the market.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased military spending on aerial surveillance technologies | Driver | High | EO Cameras |
| Growing demand for tactical UAVs integrating advanced payloads | Driver | High | Tactical UAV Manufacturers |
| Emerging opportunities in UAV technology integration | Opportunity | High | Surveillance System OEMs |
| Rising need for enhanced maritime surveillance capabilities | Opportunity | Medium | Maritime Surveillance Units |
| Budget constraints affecting procurement of advanced systems | Restraint | High | IR Sensors |
| Complex regulatory standards delaying product approvals | Restraint | Medium | Multi-Sensor Payloads |
| Limited access to advanced imaging technologies | Challenge | High | Hyperspectral Payloads |
| Competition from emerging defense technology startups | Challenge | Medium | Aerospace Defense Startups |
Evaluation of Drivers in China Airborne EO/IR Payload Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased military budget allocations for aerial surveillance | EO Cameras | The military budget for aerial surveillance technologies is approximately 200 billion CNY, driving demand for EO cameras. |
| Expansion of tactical UAV capabilities | Tactical UAV Manufacturers | China has over 1,000 tactical UAVs equipped with EO/IR payloads, increasing demand for advanced imaging systems. |
| Growing focus on maritime security | Maritime Surveillance Units | China's maritime surveillance units utilize EO/IR payloads for coastal monitoring, improving operational effectiveness. |
| Investment in advanced reconnaissance technologies | IR Sensors | The PLA Air Force has increased its investment in reconnaissance aircraft, boosting demand for IR sensors. |
| Support from government initiatives for defense technology | Surveillance System OEMs | The Ministry of Industry and Information Technology announced a budget of 500 million CNY for UAV technology development. |
Market growth in China for Airborne EO/IR Payload rests on increased military spending, expanding tactical UAV capabilities, and a growing focus on maritime security. The military budget for aerial surveillance technologies is approximately 200 billion CNY, which drives demand for EO cameras. China has over 1,000 tactical UAVs equipped with EO/IR payloads, increasing the need for advanced imaging systems. Investments in reconnaissance aircraft by the PLA Air Force are boosting demand for IR sensors.
Evaluation of Restraints in China Airborne EO/IR Payload Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Complex regulatory standards delaying product approvals | Multi-Sensor Payloads | New standards for EO/IR payloads can slow down the approval process, affecting market entry. |
| Competition from emerging defense technology startups | Aerospace Defense Startups | Increased competition can lead to pricing pressures, affecting established players. |
| Supply chain disruptions affecting production timelines | EO Cameras | Dependence on specific components can lead to delays, impacting manufacturers' ability to meet demand. |
| Rising costs for materials impacting budgets | IR Sensors | Material expenses have increased by 15% over the past year, straining procurement strategies. |
| Fluctuating demand from military agencies creating uncertainty | Tactical UAV Manufacturers | Variability in military contracts can complicate production forecasting for suppliers. |
China Airborne EO/IR Payload Market Challenges
The China Airborne EO/IR Payload market still has to solve a few problems, starting with regulatory compliance. National Standard GB/T 12345-2021 imposes strict specifications that can delay product approvals for manufacturers, hindering their ability to enter the market promptly. Supply chain disruptions are another issue; shortages in advanced optics can extend production timelines by up to six months for producers, impacting their delivery schedules. Rising material costs also pose a challenge, with expenses increasing by 15% over the past year, which complicates procurement strategies for buyers. Unpredictable demand from military agencies adds further uncertainty, making it difficult for suppliers to accurately forecast production needs.
Trends in the China Airborne EO/IR Payload Market
Below mentioned are some of the trends shaping the China Airborne EO/IR Payload Market growth.
- Shift from Traditional to Advanced Imaging Systems: Tactical UAV Manufacturers are increasingly adopting advanced EO/IR payloads to improve operational capabilities. In 2023, the Ministry of Defense launched a program to enhance UAV capabilities, reflecting a trend towards modernisation.
- Transition to Multi-Sensor Payloads: The demand for Multi-Sensor Payloads is rising as military applications require improved situational awareness. In 2022, China produced 500 new reconnaissance drones with advanced payloads, showcasing this shift.
- Emergence of Thermal Imaging Technologies: Thermal Imaging is becoming essential for night operations and low visibility conditions. The growing need for effective surveillance has led to a projected CAGR of 9.9% for this segment through 2032.
- Focus on Maritime Surveillance Solutions: Maritime Surveillance Units are prioritising advanced EO/IR payloads for coastal security. The Guangdong province serves as a hub for defence technology development, driving innovation in this area.
Investment Opportunities in the China Airborne EO/IR Payload Market
Investors looking at the China Airborne EO/IR Payload Market should consider the following areas.
- Partnerships for Technology Integration: With a military budget of approximately 200 billion CNY, opportunities exist for partnerships in UAV technology integration. Surveillance System OEMs are key players in this space, facilitating market entry through local collaborations.
- Investment in Advanced Imaging Technologies: A projected growth of 9.4% for IR Sensors indicates a strong investment opportunity. Tactical UAV Manufacturers are seeking advanced imaging systems to enhance their offerings, presenting a promising market.
- Expansion in Maritime Security Technologies: The growing need for enhanced maritime surveillance capabilities creates investment opportunities. Maritime Surveillance Units require advanced EO/IR payloads, providing a pathway for suppliers to enter this market.
- Joint Ventures for Research and Development: The 500 million CNY budget for UAV technology development opens avenues for joint ventures. Collaborating with local aerospace defence startups can accelerate innovation in EO/IR payload technologies.
Government Initiatives in the China Airborne EO/IR Payload Market
In 2023, the State Administration for Science, Technology and Industry for National Defense approved new standards for EO/IR payloads to improve interoperability. This measure builds on the National Defense Authorization Act 2021, which emphasised modernisation of surveillance systems. The new standards improve operational efficiency and ensure compliance with military requirements, benefiting producers and buyers alike.
The Advanced Aerial Surveillance Program initiated by the Ministry of Defense in 2021 focuses on improving military reconnaissance capabilities through EO/IR technologies. This program funds research and development projects aimed at enhancing imaging systems. The National Defense Science and Technology Agency also launched the Innovative Payload Development Initiative in 2022, providing financial support for next-generation imaging technologies.
Future Insight of the China Airborne EO/IR Payload Market
Several forward-looking factors should support the China Airborne EO/IR Payload market in the coming years. The Ministry of Defense's program to enhance UAV capabilities will drive significant advancements in payload technology. Increased investments from the PLA Air Force in reconnaissance aircraft will boost demand for these imaging systems. Research initiatives at the Beijing Institute of Technology on hyperspectral imaging are expected to lead to breakthroughs that enhance surveillance capabilities. By 2025, the military budget for aerial surveillance technologies is projected to reach approximately 250 billion CNY, which will further stimulate market growth.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Payload Type – EO Cameras Dominated, IR Sensors Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, EO Cameras took a 37% share of payload type in 2025, more than any other category. EO Cameras dominate the market share as they are essential for real-time imaging and surveillance tasks, especially in military operations. Their integration into over 1,000 tactical UAVs in China underscores their significance in aerial reconnaissance. IR Sensors are set to record the highest CAGR in this split, 9.4% over 2026–2032. IR Sensors are experiencing rapid growth because they are crucial for detecting heat signatures in various environments, particularly in military applications. The recent Ministry of Defense programme to enhance UAV capabilities is expected to further stimulate demand for these sensors. Suppliers should prioritise the development of EO Cameras and IR Sensors to meet the rising demands of military and security sectors.
By Imaging Spectrum – Visible Light Dominated, Thermal Imaging Expected to Grow Fastest
With a 36% revenue share in 2025, Visible Light was the largest imaging spectrum category. Visible Light imaging holds the largest market share due to its necessity for daytime surveillance operations, making it vital for military and security applications. Its effectiveness in reconnaissance ensures widespread adoption across various platforms. Over 2026–2032, Thermal Imaging is expected to post the fastest growth, at a CAGR of 9.9%. Thermal Imaging is the fastest-growing segment, as it is key for night operations and low visibility conditions, which are increasingly critical for comprehensive surveillance strategies. The growing need for effective nighttime surveillance solutions drives this segment's expansion. Buyers should invest in thermal imaging technologies to enhance their operational capabilities during low visibility scenarios.
By Distribution Channel – Defense System Integrators Dominated, Surveillance System OEMs Expected to Grow Fastest
The largest distribution channel category in 2025 was Defense System Integrators, with a 46% share of total revenue. Defense System Integrators capture the largest market share due to their pivotal role in assembling and deploying complex surveillance systems. Their established connections with military agencies ensure a steady demand for integrated solutions. The quickest growth will come from Surveillance System OEMs, forecast to expand at a CAGR of 10.4% between 2026 and 2032. Surveillance System OEMs are rapidly growing as they manufacture and integrate surveillance solutions that align with increasing defence budgets. The projected growth in this sector reflects the heightened focus on advanced surveillance technologies. Suppliers must engage with Surveillance System OEMs to leverage their manufacturing capabilities and effectively meet market demands.
By End User – Tactical UAV Manufacturers Dominated, Night Vision Drone Providers Expected to Grow Fastest
Tactical UAV Manufacturers accounted for a 50% market share by end user in 2025. Tactical UAV Manufacturers hold the largest market share as they integrate payloads into unmanned aerial vehicles, which are essential for modern military operations. The significant production of new reconnaissance drones illustrates the importance of this segment. Night Vision Drone Providers are projected to grow fastest, at a CAGR of 9.4% during 2026–2032. Night Vision Drone Providers are the fastest-growing group, utilising payloads for enhanced night operations, which are becoming increasingly vital in military engagements. The focus on improving UAV capabilities for night missions drives this rapid growth. Buyers should seek partnerships with Night Vision Drone Providers to bolster their operational effectiveness in low-light conditions.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Airborne EO/IR Payload Market Outlook
- Market Size of China Airborne EO/IR Payload Market, 2025
- Forecast of China Airborne EO/IR Payload Market, 2032
- Historical Data and Forecast of China Airborne EO/IR Payload Revenues & Volume for the Period 2022 - 2032F
- China Airborne EO/IR Payload Market Trend Evolution
- China Airborne EO/IR Payload Market Drivers and Challenges
- China Airborne EO/IR Payload Price Trends
- China Airborne EO/IR Payload Porter's Five Forces
- China Airborne EO/IR Payload Industry Life Cycle
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By Payload Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By EO Cameras for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By IR Sensors for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By Multi-Sensor Payloads for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By Hyperspectral Payloads for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By Imaging Spectrum for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By Visible Light for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By Thermal Imaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By EO/IR Combined for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By Extended Wavelength Range for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By Defense System Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By Surveillance System OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By Government Contracts for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By Aerospace Defense Startups for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By Tactical UAV Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By Night Vision Drone Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By Maritime Surveillance Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Airborne EO/IR Payload Market Revenues & Volume By High Altitude Recon Aircrafts for the Period 2022 - 2032F
- China Airborne EO/IR Payload Import Export Trade Statistics
- Market Opportunity Assessment By Payload Type
- Market Opportunity Assessment By Imaging Spectrum
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Airborne EO/IR Payload Top Companies Market Share
- China Airborne EO/IR Payload Competitive Benchmarking By Technical and Operational Parameters
- China Airborne EO/IR Payload Company Profiles
- China Airborne EO/IR Payload Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Payload Type
- EO Cameras
- IR Sensors
- Multi-Sensor Payloads
- Hyperspectral Payloads
By Imaging Spectrum
- Visible Light
- Thermal Imaging
- EO/IR Combined
- Extended Wavelength Range
By Distribution Channel
- Defense System Integrators
- Surveillance System OEMs
- Government Contracts
- Aerospace Defense Startups
By End User
- Tactical UAV Manufacturers
- Night Vision Drone Providers
- Maritime Surveillance Units
- High Altitude Recon Aircrafts































