China Aircraft Assembly Automation Market Size & Growth Rate
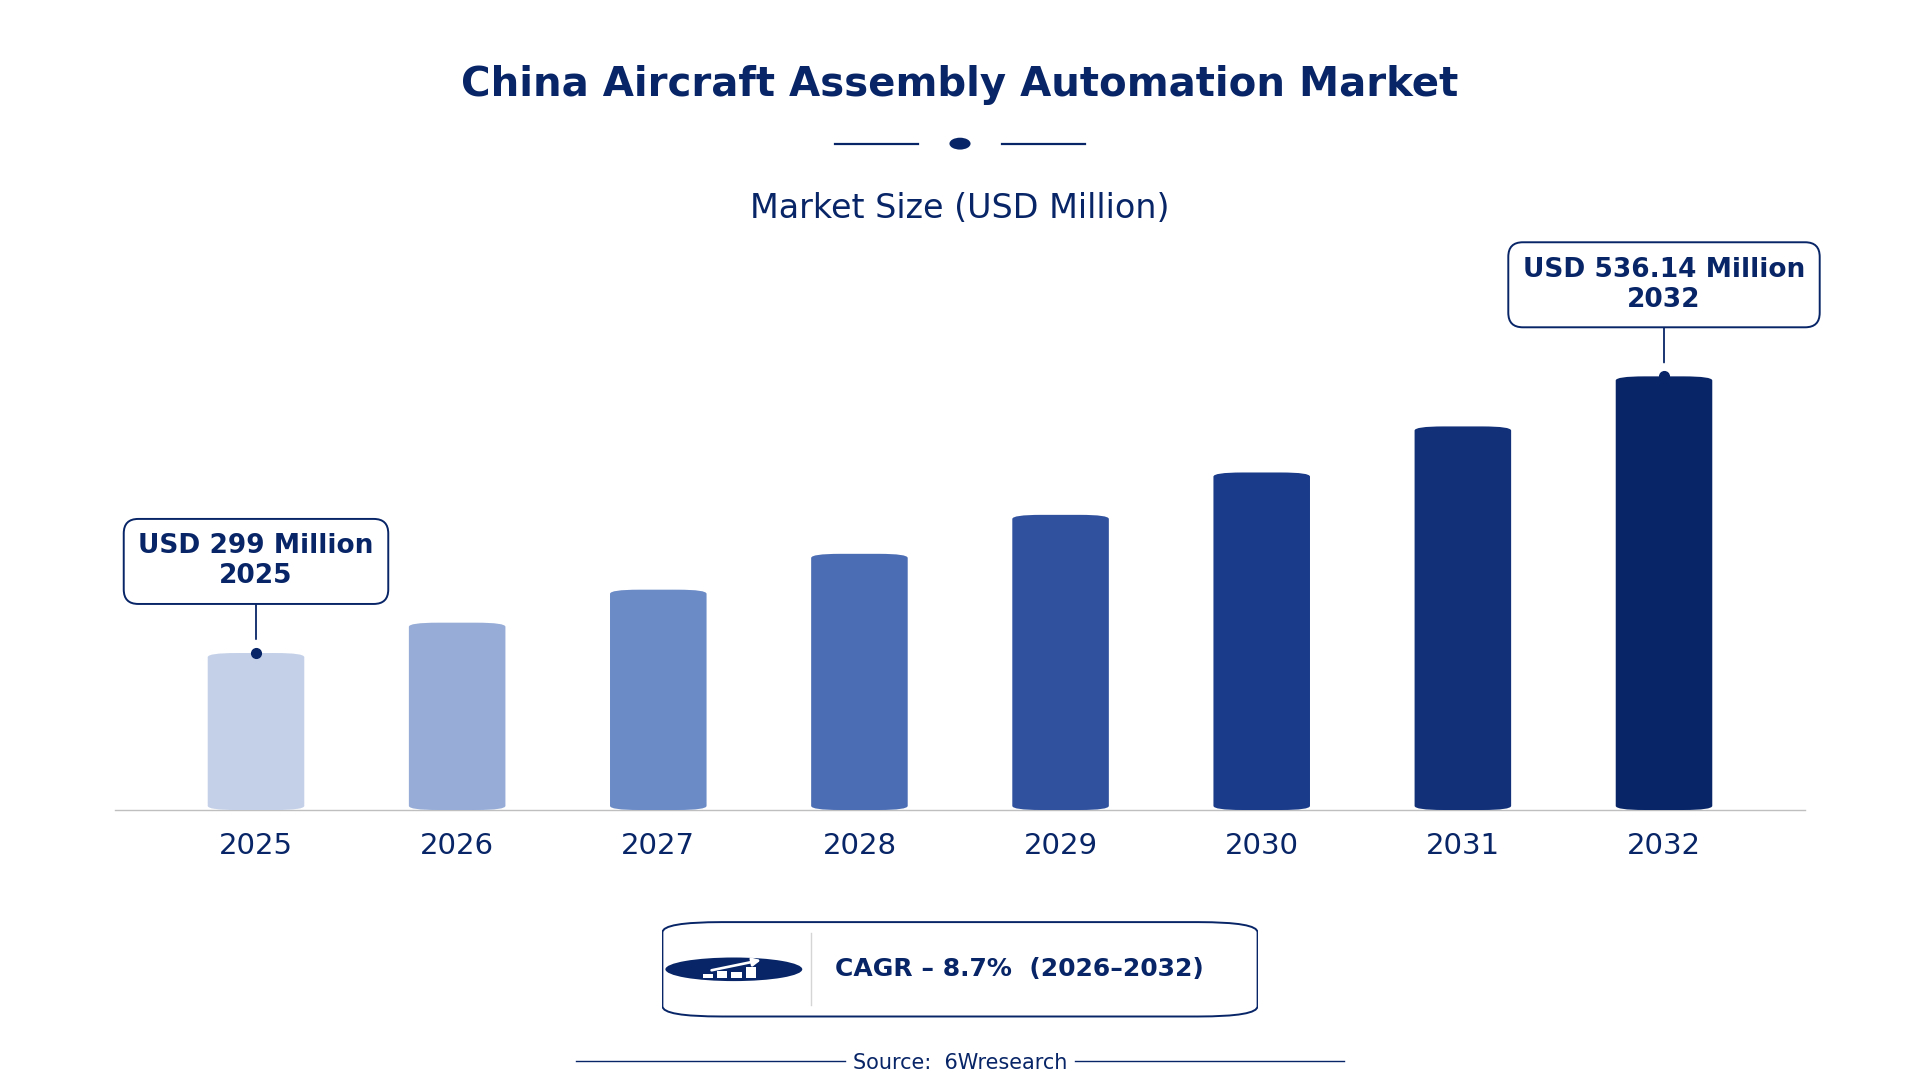
According to 6Wresearch internal database and industry insights, the China Aircraft Assembly Automation Market was valued at USD 299.0 million in 2025 and is projected to reach USD 536.14 million by 2032, growing at a CAGR of approximately 8.7% during 2026–2032.
China Aircraft Assembly Automation Market Highlights
| Report Metric | Details |
| Report Name | China Aircraft Assembly Automation Market |
| Market Size 2025 | USD 299.0 million |
| Market Size 2032 | USD 536.14 million |
| Absolute Growth 2025–2032 | USD 237.14 million |
| CAGR 2026–2032 | 8.7% |
| Peak Annual Growth | 11.1% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Automation Type, 2025 | Robotic Drilling Systems (40% share) |
| Leading Technology Used, 2025 | AI-Powered Robots (44% share) |
| Leading Distribution Channel, 2025 | Aircraft Tool Integrators (39% share) |
| Leading End User, 2025 | Commercial Aircraft OEMs (51% share) |
| Fastest-Growing Automation Type | Automated Inspection Tools (10.2% CAGR) |
| Fastest-Growing Distribution Channel | Aerospace Automation Firms (10.8% CAGR) |
| Fastest-Growing End User | Military Aircraft Manufacturers (9.7% CAGR) |
| Growing Sector | Military Aircraft Manufacturers |
| Key End Users | Commercial Aircraft OEMs, Military Aircraft Manufacturers, Helicopter Manufacturing Plants, Quality Assurance Units |
China Aircraft Assembly Automation Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
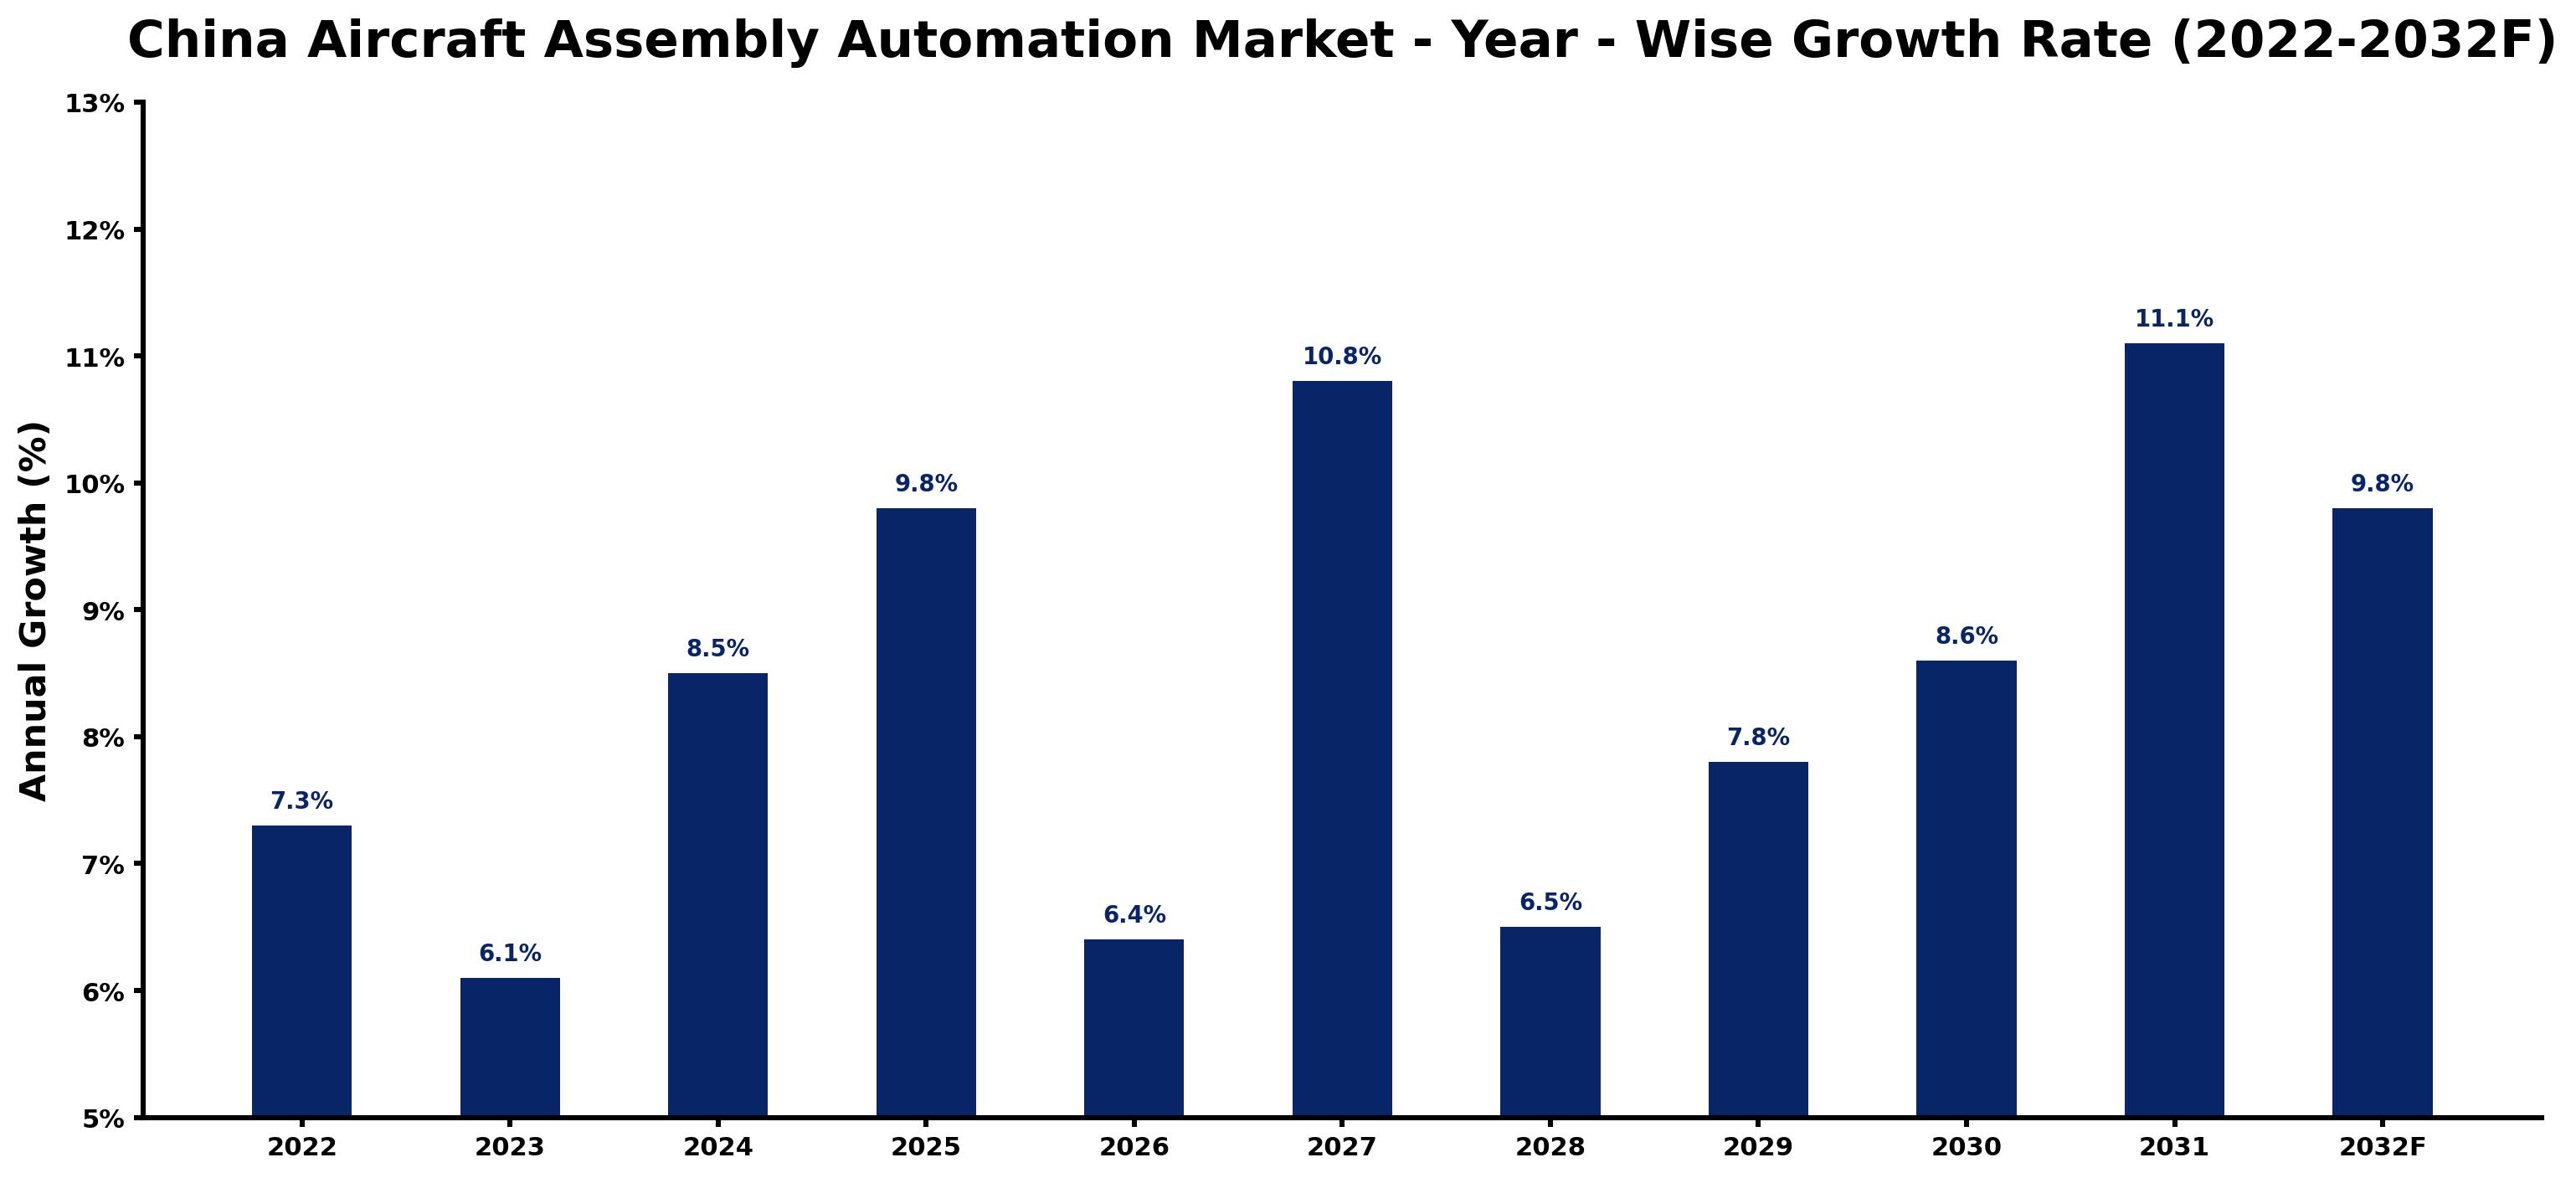
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.3 | The market saw steady growth due to ongoing investments in automation technologies. |
| 2023 | 6.1 | Growth slowed as companies adjusted to new safety standards set by the Civil Aviation Administration of China. |
| 2024 | 8.5 | Demand increased with the implementation of the Aerospace Automation Development Plan promoting robotics. |
| 2025 | 9.8 | The market peaked as production rates surged, driven by rising domestic air travel demand. |
| 2026 | 6.4 | Growth is expected to slow due to a temporary reduction in investment as companies reassess their strategies. |
| 2027 | 10.8 | Demand is projected to surge again as military aircraft manufacturers expand their production capabilities. |
| 2028 | 6.5 | Growth is expected to slow as the market stabilises after rapid expansions in previous years. |
| 2029 | 7.8 | Demand is projected to increase as new aerospace projects are initiated in the Beijing-Tianjin-Hebei region. |
| 2030 | 8.6 | Growth is expected to accelerate as foreign investments in automation technologies begin to materialise. |
| 2031 | 11.1 | The market is projected to peak again due to heightened demand for commercial aircraft in the domestic market. |
| 2032 | 9.8 | Growth is expected to slow as the market approaches maturity, with a focus on efficiency improvements. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Aircraft Assembly Automation Market Synopsis
Aircraft Assembly Automation in China utilises advanced technologies to streamline aircraft manufacturing processes. This includes robotic systems for drilling, riveting, painting, and inspection, which enhance precision and safety. The China Aircraft Assembly Automation Market is growing due to increasing domestic air travel demand, substantial investments in automation technologies, and supportive government initiatives. For example, the National Aerospace Industry Development Plan aims to improve technological capabilities by 2025, further propelling market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased investment in robotics technology is driving demand for automation solutions in aircraft assembly. | Driver | High | Robotic Drilling Systems |
| The rising domestic air travel demand is pushing commercial aircraft OEMs to expand production. | Driver | High | Commercial Aircraft OEMs |
| The current gap in automation capabilities presents opportunities for suppliers to introduce advanced technologies. | Opportunity | High | Aerospace Automation Firms |
| The increasing need for efficient manufacturing processes creates demand for integrated automation solutions. | Opportunity | High | Aircraft Tool Integrators |
| High initial investment costs can deter smaller manufacturers from adopting automation technologies. | Restraint | Medium | Robotic Painting Arms |
| Strict safety regulations can slow down the implementation of new automation technologies. | Restraint | Medium | Automated Inspection Tools |
| The market still has to solve a few problems, including high costs of technology integration. | Challenge | Medium | AI-Powered Robots |
| Limited skilled workforce in automation technologies poses challenges for manufacturers. | Challenge | Medium | CNC Technology |
Evaluation of Drivers in China Aircraft Assembly Automation Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising investments in automation technologies | AI-Powered Robots | These investments enhance production efficiency, with the installed base of CNC machines in aerospace exceeding 50,000 units, prompting OEMs to increase automation adoption. |
| Growing domestic air travel demand | Commercial Aircraft OEMs | The population of approximately 1.4 billion fuels demand for air travel, leading OEMs to invest more in assembly automation to meet this rising need. |
| Government initiatives promoting automation | Aerospace Automation Firms | The National Aerospace Industry Development Plan encourages investment in automation, resulting in increased demand for advanced automation solutions from firms. |
| Focus on quality assurance and safety | Automated Inspection Tools | The updated 'Aerospace Safety Regulation' mandates stringent quality checks, driving demand for automated inspection technologies to ensure compliance. |
| Increased military aircraft production | Military Aircraft Manufacturers | State-owned enterprises are expanding military production, necessitating advanced automation technologies to enhance efficiency and meet production targets. |
China's population of approximately 1.4 billion boosts demand for air travel, prompting OEMs to invest in assembly automation. The National Aerospace Industry Development Plan aims to improve technological capabilities by 2025, encouraging investments in automation. The Shanghai Free Trade Zone promotes foreign investment in aerospace automation, increasing the supply of advanced tools. State-owned enterprises are increasing military aircraft production, requiring advanced automation technologies for efficiency.
Evaluation of Restraints in China Aircraft Assembly Automation Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High initial investment costs can deter smaller manufacturers from adopting automation technologies. | Robotic Painting Arms | The cost of implementing robotic systems can exceed several million yuan, limiting access for smaller firms. |
| Strict safety regulations can slow down the implementation of new automation technologies. | Automated Inspection Tools | Compliance with the updated Aerospace Safety Regulation requires extensive testing and certification, delaying deployment. |
| Limited availability of skilled workforce in automation technologies poses challenges for manufacturers. | AI-Powered Robots | The installed base of CNC machines exceeds 50,000 units, but skilled operators remain scarce, hindering growth. |
| Market volatility can affect investment decisions in automation technologies. | CNC Technology | Economic fluctuations can lead to reduced budgets for automation, impacting procurement decisions. |
| Competition from international manufacturers can pressure local firms to innovate. | Aerospace Automation Firms | Foreign companies often offer advanced solutions, making it difficult for local firms to compete without innovation. |
China Aircraft Assembly Automation Market Challenges
The China Aircraft Assembly Automation Market still faces several challenges, starting with outdated technology in many manufacturing plants. Numerous facilities depend on legacy systems, which can delay production timelines by up to 20%, affecting efficiency for producers. Intense competition among local manufacturers results in price wars, compelling suppliers to cut prices, which can jeopardise quality and safety standards. A shortage of skilled workers in advanced automation techniques limits training centres' ability to meet industry needs, creating a talent gap that could take years to bridge. Supply chain disruptions, worsened by global events, can lead to delays in acquiring essential components, causing production halts for manufacturers.
Trends in the China Aircraft Assembly Automation Market
Buyers and suppliers in the China Aircraft Assembly Automation Market are adjusting to the following trends.
- Shift in Demand from Commercial to Military Aircraft: Military Aircraft Manufacturers are increasingly investing in automation technologies to enhance production efficiency. In 2023, the National Defense Industry Bureau reported a 30% increase in military aircraft production, driving demand for automation solutions.
- Transition to AI-Driven Automation: The integration of AI technologies in manufacturing processes is becoming widespread. The Aerospace Automation Development Plan launched in 2021 aims for a 30% efficiency improvement by 2025, encouraging manufacturers to adopt AI-driven systems.
- Emergence of Advanced Inspection Technologies: Automated Inspection Tools are gaining popularity as quality assurance becomes paramount. In 2023, the National Aerospace Administration updated its safety regulations to include automated inspection, enhancing compliance and quality.
- Growth of Integrated Automation Solutions: Aircraft Tool Integrators are broadening their offerings to deliver comprehensive automation solutions. In 2023, the market for integrated tools is expected to grow significantly, driven by the demand for efficiency.
Investment Opportunities in the China Aircraft Assembly Automation Market
Several openings in the China Aircraft Assembly Automation Market merit attention from investors.
- Current Demand for Advanced Robotics: The timing is perfect for suppliers to introduce advanced robotics systems, as the market is projected to grow significantly by 2035. Commercial Aircraft OEMs are actively seeking solutions to enhance production efficiency.
- Investment in Automation Technologies: The demand for automation technologies is urgent, with a budget of 500 million yuan allocated for innovation in the aerospace sector. Aerospace Automation Firms can gain by partnering with local manufacturers.
- Gap in Skilled Workforce: With a shortage of skilled workers in automation, there is a chance for training programmes. The National Aerospace Industry Development Plan aims to enhance workforce skills by 2025, creating demand for educational services.
- Growing Military Aircraft Production: The rise in military aircraft production offers an opportunity for suppliers of assembly automation technologies. The Chengdu Aircraft Industry Group is expanding its capabilities, necessitating advanced automation solutions.
Government Initiatives in the China Aircraft Assembly Automation Market
In 2023, the State Administration for Science, Technology and Industry for National Defense initiated the 'AI Integration in Military Aircraft Production Program', building on the existing 'Aerospace Automation Development Plan' from 2021. This new measure aims to improve efficiency by 30% by 2025, requiring manufacturers to adopt advanced AI technologies in their processes. Additionally, the National Development and Reform Commission approved the 'Aerospace Industry Revitalization Strategy' in 2022, focusing on enhancing domestic production capabilities and reducing reliance on imports.
The Ministry of Industry and Information Technology oversees the implementation of various aerospace initiatives, including the approval of funding for automation projects. In 2022, a subsidy programme was announced with a budget of 500 million yuan to support companies investing in automation technologies, facilitating innovation in the aerospace sector. This funding allows manufacturers to adopt advanced technologies, improving production efficiency and safety standards.
Future Insight of the China Aircraft Assembly Automation Market
By 2032, buyers and suppliers in the China Aircraft Assembly Automation Market can expect considerable changes due to advancements in robotics and AI integration. The National Aerospace Industry Development Plan will drive investment in new automation technologies, refining production processes. The installed base of CNC machines in aerospace is anticipated to surpass 50,000 units, enhancing manufacturing efficiency. The Shanghai Free Trade Zone will encourage foreign investment, promoting collaboration and innovation in aerospace automation, ultimately improving production safety and reliability.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Automation Type – Robotic Drilling Systems Dominated, Automated Inspection Tools Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, Robotic Drilling Systems took a 40% share of automation type in 2025, more than any other category. Robotic Drilling Systems hold the largest market share due to their critical role in achieving the precision necessary for aircraft assembly. Their significance is highlighted by the stringent safety standards set by the Civil Aviation Administration of China, which these systems help fulfil. Over 2026–2032, Automated Inspection Tools are expected to post the fastest growth, at a CAGR of 10.2%. Automated Inspection Tools are experiencing rapid growth as manufacturers prioritise quality assurance processes. The increasing focus on compliance with safety and quality standards is driving investment in these tools, ensuring their swift adoption in the market. Suppliers should focus on developing advanced inspection technologies to meet the rising demand from manufacturers.
By Technology Used – AI-Powered Robots Dominated and Is Expected to Record the Fastest Growth
AI-Powered Robots held a 44% share of the China Aircraft Assembly Automation Market by technology used in 2025. AI-Powered Robots command a substantial market share as they greatly enhance efficiency and precision in assembly tasks, making them indispensable for manufacturers. Their widespread use aligns with the National Aerospace Industry Development Plan's goals for technological progress by 2025. The same category are also set to grow fastest, at a CAGR of 10.3% during 2026–2032. The growth of AI-Powered Robots is fuelled by their essential role in optimising production processes, which keeps them at the forefront of the market. Continuous investment in AI technologies will likely strengthen their position and expand their market share. Buyers should consider investing in AI-driven solutions to improve their production capabilities and maintain competitiveness.
By Distribution Channel – Aircraft Tool Integrators Dominated, Aerospace Automation Firms Expected to Grow Fastest
Aircraft Tool Integrators accounted for a 39% market share by distribution channel in 2025. Aircraft Tool Integrators command a substantial market share as they effectively combine various automation tools, streamlining the manufacturing process for clients. Their expertise is particularly valued in regions like the Beijing-Tianjin-Hebei aerospace hub. Aerospace Automation Firms are projected to grow fastest, at a CAGR of 10.8% during 2026–2032. Aerospace Automation Firms are seeing the fastest growth as they specialise in tailored automation solutions that meet the unique needs of the aerospace sector. This trend is supported by increasing foreign investment in regions like the Shanghai Free Trade Zone. Suppliers must strengthen partnerships with aerospace automation firms to capture emerging opportunities in the market.
By End User – Commercial Aircraft OEMs Dominated, Military Aircraft Manufacturers Expected to Grow Fastest
In 2025, Commercial Aircraft OEMs led the end user split with a 51% share. Commercial Aircraft OEMs represent the largest share of the market as they are the primary users of assembly automation technology for large-scale production. Their significant output, evidenced by over 1,000 commercial aircraft units produced in 2022, underscores their vital role in the industry. Military Aircraft Manufacturers are set to record the highest CAGR in this split, 9.7% over 2026–2032. Military Aircraft Manufacturers are the fastest-growing segment, driven by heightened defence aviation needs and government support for military aircraft production. Their increasing reliance on automation technologies will likely boost their market presence. Suppliers should tailor their offerings to meet the specific needs of military manufacturers to capitalise on this growth opportunity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Aircraft Assembly Automation Market Outlook
- Market Size of China Aircraft Assembly Automation Market, 2025
- Forecast of China Aircraft Assembly Automation Market, 2032
- Historical Data and Forecast of China Aircraft Assembly Automation Revenues & Volume for the Period 2022 - 2032F
- China Aircraft Assembly Automation Market Trend Evolution
- China Aircraft Assembly Automation Market Drivers and Challenges
- China Aircraft Assembly Automation Price Trends
- China Aircraft Assembly Automation Porter's Five Forces
- China Aircraft Assembly Automation Industry Life Cycle
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By Automation Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By Robotic Drilling Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By Riveting Machines for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By Robotic Painting Arms for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By Automated Inspection Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By Technology Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By AI-Powered Robots for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By CNC Technology for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By Vision Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By ML/AI Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By Aircraft Tool Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By Industrial Equipment Dealers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By Aerospace Automation Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By Online Automation Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By Commercial Aircraft OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By Military Aircraft Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By Helicopter Manufacturing Plants for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Automation Market Revenues & Volume By Quality Assurance Units for the Period 2022 - 2032F
- China Aircraft Assembly Automation Import Export Trade Statistics
- Market Opportunity Assessment By Automation Type
- Market Opportunity Assessment By Technology Used
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Aircraft Assembly Automation Top Companies Market Share
- China Aircraft Assembly Automation Competitive Benchmarking By Technical and Operational Parameters
- China Aircraft Assembly Automation Company Profiles
- China Aircraft Assembly Automation Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Automation Type
- Robotic Drilling Systems
- Riveting Machines
- Robotic Painting Arms
- Automated Inspection Tools
By Technology Used
- AI-Powered Robots
- CNC Technology
- Vision Systems
- ML/AI Based
By Distribution Channel
- Aircraft Tool Integrators
- Industrial Equipment Dealers
- Aerospace Automation Firms
- Online Automation Vendors
By End User
- Commercial Aircraft OEMs
- Military Aircraft Manufacturers
- Helicopter Manufacturing Plants
- Quality Assurance Units






































