China Aircraft Assembly Tooling Market Size & Growth Rate
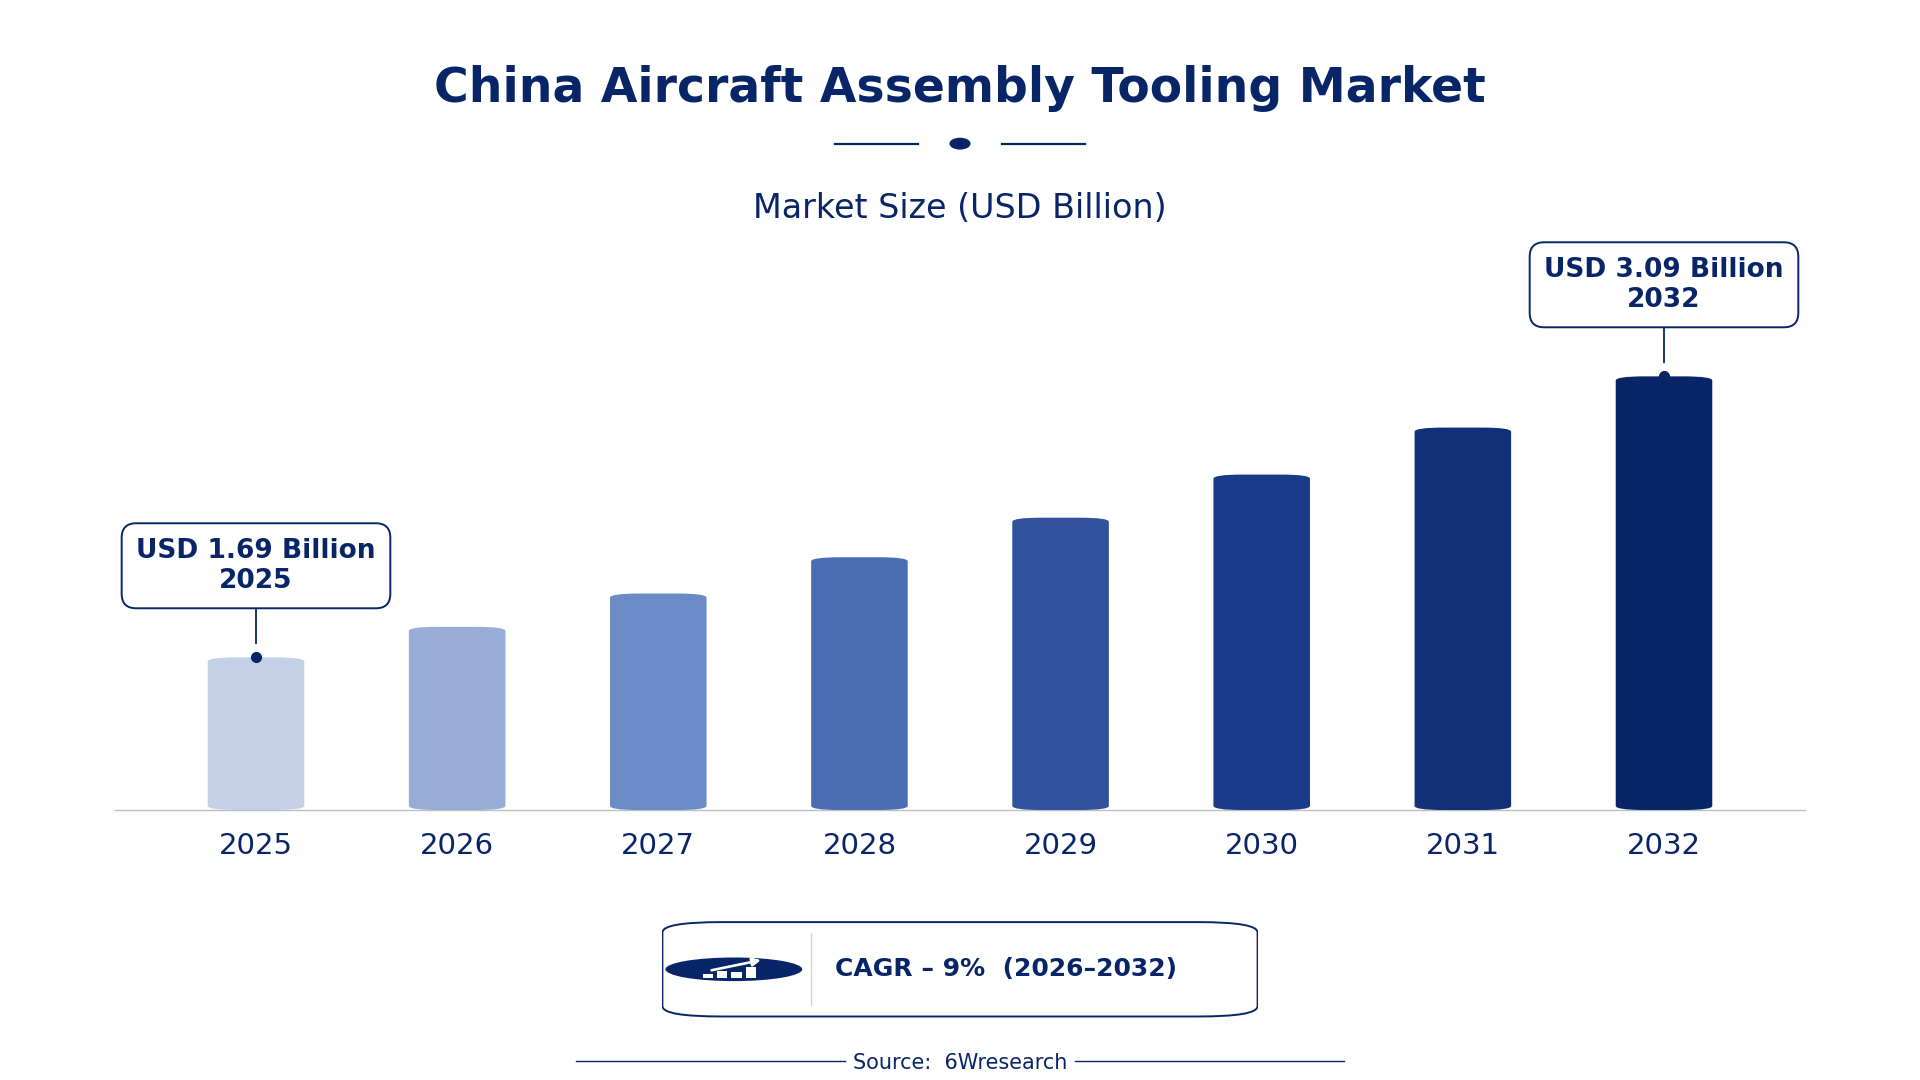
According to 6Wresearch internal database and industry insights, the China Aircraft Assembly Tooling Market was valued at USD 1.69 billion in 2025 and is projected to reach USD 3.09 billion by 2032, growing at a CAGR of approximately 9% during 2026–2032.
China Aircraft Assembly Tooling Market Highlights
| Report Metric | Details |
| Report Name | China Aircraft Assembly Tooling Market |
| Market Size 2025 | USD 1.69 billion |
| Market Size 2032 | USD 3.09 billion |
| Absolute Growth 2025–2032 | USD 1.40 billion |
| CAGR 2026–2032 | 9% |
| Peak Annual Growth | 11.3% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Tool Type, 2025 | Wing Assembly Jigs (36% share) |
| Leading Application Area, 2025 | Large Components (45% share) |
| Leading Distribution Channel, 2025 | Aviation Tool Dealers (40% share) |
| Leading End User, 2025 | Aerospace OEMs (45% share) |
| Fastest-Growing Tool Type | Fuselage Fixtures (10.9% CAGR) |
| Fastest-Growing Application Area | Body Integration (10.4% CAGR) |
| Fastest-Growing Distribution Channel | Custom Tooling Providers (11.7% CAGR) |
| Fastest-Growing End User | Defense Aircraft Builders (11.4% CAGR) |
| Growing Sector | Aerospace |
| Key End Users | Aerospace OEMs, Aircraft Assembly Plants, Defense Aircraft Builders, Aviation Tool Dealers |
China Aircraft Assembly Tooling Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
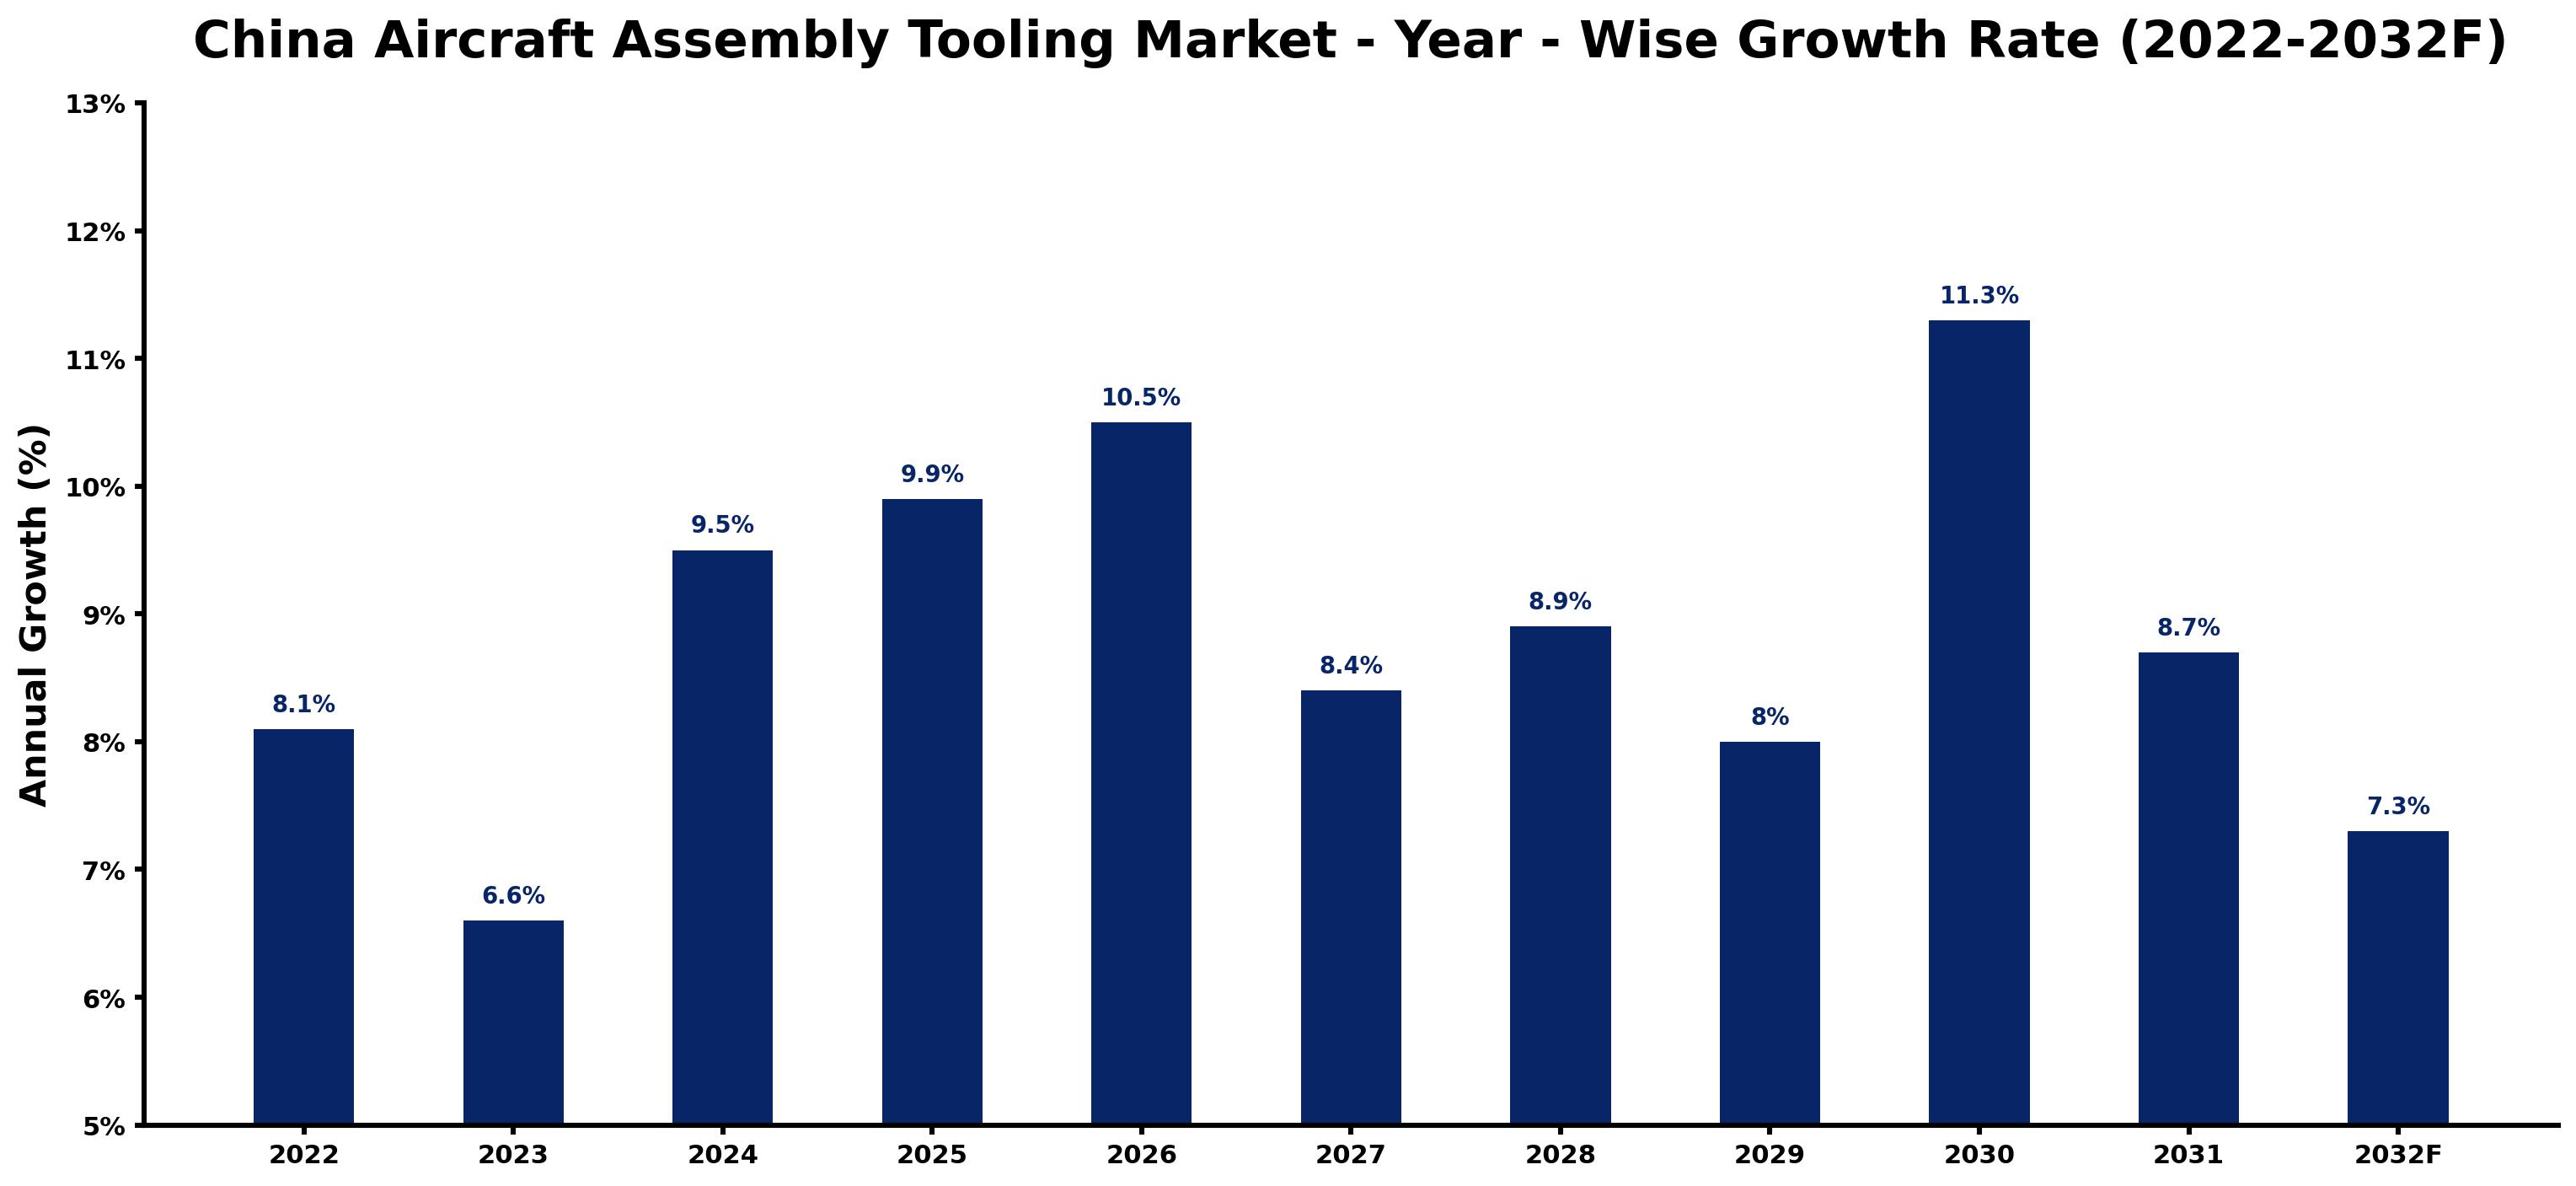
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 8.1 | The market experienced steady growth due to increased production demands from domestic aerospace manufacturers. |
| 2023 | 6.6 | Growth slowed as manufacturers faced supply chain challenges affecting tooling availability. |
| 2024 | 9.5 | A surge in aircraft production plans led to faster growth in tooling requirements. |
| 2025 | 9.9 | Demand increased as production ramped up to meet the needs of over 1,000 aircraft annually. |
| 2026 | 10.5 | Investment in advanced manufacturing technologies boosted demand for high-quality tooling. |
| 2027 | 8.4 | Growth slowed as manufacturers adjusted to market fluctuations and production schedules. |
| 2028 | 8.9 | An increase in military aircraft production led to a resurgence in tooling demand. |
| 2029 | 8.0 | Demand slowed slightly as manufacturers focused on optimizing existing production lines. |
| 2030 | 11.3 | A peak in growth occurred due to a significant rise in aircraft orders and production. |
| 2031 | 8.7 | Demand growth slowed as the market began to stabilise following the peak year. |
| 2032 | 7.3 | Growth continues but at a slower pace as the market matures and consolidates. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Aircraft Assembly Tooling Market Synopsis
The Aircraft Assembly Tooling market in China encompasses specialized tools and fixtures essential for manufacturing and assembling aircraft components. These tools are made from high-strength materials and are vital for the precise assembly of wings, fuselage, and large components. The market is projected to grow significantly due to increasing domestic manufacturing capabilities and ongoing government support for aviation projects. With the aerospace industry expected to reach approximately 1 trillion yuan by 2030, demand is driven by both commercial and defense sectors. The growing workforce in the aerospace sector further fuels this expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising domestic aircraft production drives demand for assembly tooling. | Driver | High | Large Components |
| Investment in advanced manufacturing technologies enhances tooling capabilities. | Driver | High | Fuselage Fixtures |
| The increasing number of aircraft assembly plants creates a need for more tooling. | Opportunity | High | Aircraft Assembly Plants |
| Growing military aircraft production presents new tooling opportunities. | Opportunity | Medium | Defense Aircraft Builders |
| Regulatory compliance costs can limit tooling investments for manufacturers. | Restraint | High | Aerospace OEMs |
| Supply chain disruptions can delay tooling availability for assembly processes. | Restraint | Medium | Aviation Tool Dealers |
| The Aircraft Assembly Tooling market faces challenges from rising material costs. | Challenge | High | Custom Tooling Providers |
| Technological advancements require continuous investment in tooling upgrades. | Challenge | Medium | Industrial Distributors |
Evaluation of Drivers in China Aircraft Assembly Tooling Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased aircraft production targets necessitate more assembly tooling. | Large Components | China's aerospace industry aims to produce over 7,000 commercial aircraft by 2035, driving demand for tooling. |
| Investment in advanced manufacturing technologies boosts production efficiency. | Fuselage Fixtures | Government initiatives promote modernization in manufacturing, leading to higher tooling requirements. |
| The expansion of commercial aviation increases the need for assembly tools. | Defense Aircraft Builders | The projected market size of the aerospace industry is approximately 1 trillion yuan by 2030. |
| Growing military budgets support the development of defense aircraft. | Defense Aircraft Builders | China's defense budget for aerospace development reached 1.5 trillion yuan in 2023. |
| The establishment of new assembly plants boosts tooling demand. | Aircraft Assembly Plants | Over 50 aircraft assembly plants are operational in China, requiring specialized tooling. |
The Aircraft Assembly Tooling market in China is growing on the back of increased domestic production and investment in advanced manufacturing technologies. The aerospace industry is projected to reach a market size of approximately 1 trillion yuan by 2030, which is driving demand for assembly tools. With over 7,000 commercial aircraft expected to be produced by 2035, aerospace manufacturers are increasing their tooling purchases. The defense budget for aerospace development reached 1.5 trillion yuan in 2023, further stimulating demand. The establishment of more than 50 aircraft assembly plants across the country is also contributing to the need for specialized tooling solutions.
Evaluation of Restraints in China Aircraft Assembly Tooling Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory compliance costs can limit tooling investments for manufacturers. | Aerospace OEMs | Compliance with updated safety standards increases operational costs for manufacturers. |
| Supply chain disruptions can delay tooling availability for assembly processes. | Aviation Tool Dealers | Global supply chain issues have affected the timely delivery of essential tooling. |
| Rising material costs impact the pricing of assembly tooling. | Custom Tooling Providers | Increased costs for high-strength materials affect profit margins and pricing strategies. |
| Technological advancements require continuous investment in tooling upgrades. | Industrial Distributors | Keeping up with new technologies necessitates frequent updates to existing tooling. |
| Market fluctuations can lead to uncertainty in tooling demand. | Defense Aircraft Builders | Changes in defense budgets can affect long-term planning for tooling investments. |
China Aircraft Assembly Tooling Market Challenges
The Aircraft Assembly Tooling market in China faces stringent regulatory requirements that impose compliance costs on producers. The Civil Aviation Administration of China enforces safety standards, compelling manufacturers to allocate up to 20% of their tooling budgets for testing and certification. Technological gaps persist, as local advancements lag behind global benchmarks, creating sourcing issues for importers that can delay production by up to six months. Supply chain interruptions are common, particularly for specialised components, extending lead times for buyers by 30%. Increased competition from international suppliers pressures local manufacturers to reduce prices, limiting their ability to invest in innovation.
Trends in the China Aircraft Assembly Tooling Market
The trends below show where the China Aircraft Assembly Tooling Market is heading.
- Shift in Focus to Advanced Manufacturing Techniques: Aerospace OEMs are increasingly adopting advanced manufacturing techniques to improve efficiency. This shift began in 2021, supported by the National Aerospace Industry Development Plan, which aims to enhance domestic tooling production capabilities.
- Growing Demand for Custom Tooling Solutions: The trend towards custom tooling solutions is rising as manufacturers seek specialised tools for unique assembly needs. This trend has been evident since 2022, with custom tooling providers experiencing an 11.7% CAGR.
- Increased Emphasis on Safety Standards: The CAAC updated Aircraft Tooling Safety Standards in 2022 to enhance operational safety in assembly processes. This change has led to stricter compliance requirements for manufacturers, impacting their tooling procurement strategies.
- Expansion of Aerospace Manufacturing Hubs: The Guangdong province is emerging as a key hub for aircraft assembly, with significant investments in manufacturing facilities. This trend has gained momentum since 2023, driven by a growing workforce in the aerospace sector.
Investment Opportunities in the China Aircraft Assembly Tooling Market
The following opportunities in the China Aircraft Assembly Tooling Market pair current demand with a clear way in.
- Gap in High-Quality Tooling: Investing in advanced manufacturing capabilities can help suppliers capture this growing market, with the aerospace sector projected to reach 1 trillion yuan by 2030.
- Need for Specialized Tooling in Defense Sector: Establishing partnerships with local manufacturers can facilitate entry into this market, particularly in the defence aircraft sector, which has a budget of 1.5 trillion yuan.
- Opportunities in Emerging Aerospace Hubs: Investing in local distribution channels can enhance market presence in regions like Guangdong, which is becoming a key manufacturing hub.
- Growing Workforce in Aerospace Sector: Collaborating with educational institutions can help develop a skilled workforce, supporting the anticipated production of over 7,000 aircraft by 2035.
Government Initiatives in the China Aircraft Assembly Tooling Market
The National Aerospace Industry Development Plan (2021-2025) aims to strengthen domestic tooling production capabilities, overseen by the Ministry of Industry and Information Technology. This plan promotes investment in advanced manufacturing technologies and supports the growth of local tooling suppliers. Additionally, the National Standard for Aircraft Assembly Tooling established in 2021 ensures quality and safety across the sector, requiring manufacturers to comply with stringent regulations. These measures improve the operational capabilities of tooling producers and enhance overall industry standards.
In 2023, the State Council launched the Aerospace Innovation Fund with a budget of 20 billion yuan to support technological advancements in tooling. The fund is administered by the Ministry of Industry and Information Technology, which oversees various initiatives to promote innovation in the aerospace sector. Furthermore, the Civil Aviation Administration of China (CAAC) updated the Aircraft Tooling Safety Standards in 2022 to improve operational safety and quality control in assembly processes. These efforts aim to create a more competitive environment for tooling manufacturers and enhance the overall safety of aircraft assembly.
Future Insight of the China Aircraft Assembly Tooling Market
By 2032, the Aircraft Assembly Tooling market in China will experience significant transformations, driven by advancements in manufacturing technology. The Ministry of Industry and Information Technology's 2021 programme is expected to boost production efficiency by 25%, enabling suppliers to innovate more effectively. With 50 billion yuan allocated for aerospace initiatives, the market will likely see the emergence of custom tooling solutions tailored to specific assembly needs. As the number of commercial aircraft is projected to exceed 7,000, buyers will benefit from a wider array of high-quality tooling options, improving assembly precision and reducing costs.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Tool Type – Wing Assembly Jigs Dominated, Fuselage Fixtures Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, with a 36% revenue share in 2025, Wing Assembly Jigs was the largest tool type category. Wing assembly jigs command the largest market share as they are indispensable for the precise assembly of aircraft wings, a fundamental aspect of aircraft manufacturing. The presence of over 50 aircraft assembly plants in China underscores the sustained demand for these jigs, vital for operational efficiency. Over 2026–2032, Fuselage Fixtures are expected to post the fastest growth, at a CAGR of 10.9%. Fuselage fixtures are experiencing the fastest growth due to their critical role in aligning and supporting complex fuselage sections in modern aircraft. The projected expansion of China's aerospace industry, aiming for a market size of approximately 1 trillion yuan by 2030, is a key factor driving this demand. Suppliers should prioritise the development of fuselage fixtures to leverage this growth opportunity.
By Application Area – Large Components Dominated, Body Integration Expected to Grow Fastest
The largest application area category in 2025 was Large Components, with a 45% share of total revenue. The large components application area holds the highest market share as it is essential for managing oversized aircraft parts, prevalent in modern aircraft designs. This is particularly notable in the Shanghai region, a major hub for aircraft manufacturing and assembly activities. The quickest growth will come from Body Integration, forecast to expand at a CAGR of 10.4% between 2026 and 2032. Body integration is the fastest-growing application area, fuelled by the increasing necessity for seamless assembly of various aircraft sections, which is crucial for advanced aircraft production. The forecasted rise in the number of commercial aircraft, expected to exceed 7,000 by 2035, further supports this growth trajectory. Buyers should invest in solutions that enhance body integration capabilities to meet the evolving demands of aircraft assembly.
By Distribution Channel – Aviation Tool Dealers Dominated, Custom Tooling Providers Expected to Grow Fastest
In 2025, Aviation Tool Dealers led the distribution channel split with a 40% share. Aviation tool dealers capture the largest market share as they provide essential tools directly to manufacturers, ensuring a reliable supply chain for the aerospace sector. Their established networks and industry expertise are vital in supporting the increasing number of aerospace OEMs across China. Custom Tooling Providers are projected to grow fastest, at a CAGR of 11.7% during 2026–2032. Custom tooling providers represent the fastest-growing distribution channel, responding to the rising demand for tailored solutions that cater to specific assembly needs in the aerospace sector. With substantial government funding directed towards aerospace development, this segment is poised for rapid growth. Suppliers should consider forming partnerships with custom tooling providers to effectively meet niche market requirements.
By End User – Aerospace OEMs Dominated, Defense Aircraft Builders Expected to Grow Fastest
Aerospace OEMs accounted for a 45% market share by end user in 2025. Aerospace OEMs hold the largest market share as the primary users of assembly tooling, essential for the production of various aircraft models. With over 30 major manufacturers in the country, their demand for high-quality tooling remains strong and consistent. Defense Aircraft Builders are set to record the highest CAGR in this split, 11.4% over 2026–2032. Defense aircraft builders represent the fastest-growing end user segment, driven by increased government spending on military aircraft production and the need for advanced assembly tooling. This trend is supported by China's defence budget for aerospace development, which reached 1.5 trillion yuan in 2023. Suppliers should tailor their offerings to meet the specific requirements of defense aircraft builders to capture this growing segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Aircraft Assembly Tooling Market Outlook
- Market Size of China Aircraft Assembly Tooling Market, 2025
- Forecast of China Aircraft Assembly Tooling Market, 2032
- Historical Data and Forecast of China Aircraft Assembly Tooling Revenues & Volume for the Period 2022 - 2032F
- China Aircraft Assembly Tooling Market Trend Evolution
- China Aircraft Assembly Tooling Market Drivers and Challenges
- China Aircraft Assembly Tooling Price Trends
- China Aircraft Assembly Tooling Porter's Five Forces
- China Aircraft Assembly Tooling Industry Life Cycle
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Tool Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Wing Assembly Jigs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Fastening Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Fuselage Fixtures for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Precision Gauges for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Large Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Riveting/Bolting for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Body Integration for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Alignment & Tolerance for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Aviation Tool Dealers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Industrial Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Custom Tooling Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Online Tool Shops for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Aerospace OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Aircraft Assembly Plants for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Defense Aircraft Builders for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Assembly Tooling Market Revenues & Volume By Aircraft Tool Rooms for the Period 2022 - 2032F
- China Aircraft Assembly Tooling Import Export Trade Statistics
- Market Opportunity Assessment By Tool Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Aircraft Assembly Tooling Top Companies Market Share
- China Aircraft Assembly Tooling Competitive Benchmarking By Technical and Operational Parameters
- China Aircraft Assembly Tooling Company Profiles
- China Aircraft Assembly Tooling Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Tool Type
- Wing Assembly Jigs
- Fastening Tools
- Fuselage Fixtures
- Precision Gauges
By Application Area
- Large Components
- Riveting/Bolting
- Body Integration
- Alignment & Tolerance
By Distribution Channel
- Aviation Tool Dealers
- Industrial Distributors
- Custom Tooling Providers
- Online Tool Shops
By End User
- Aerospace OEMs
- Aircraft Assembly Plants
- Defense Aircraft Builders
- Aircraft Tool Rooms






































