China Aircraft Braking Components Market Size & Growth Rate
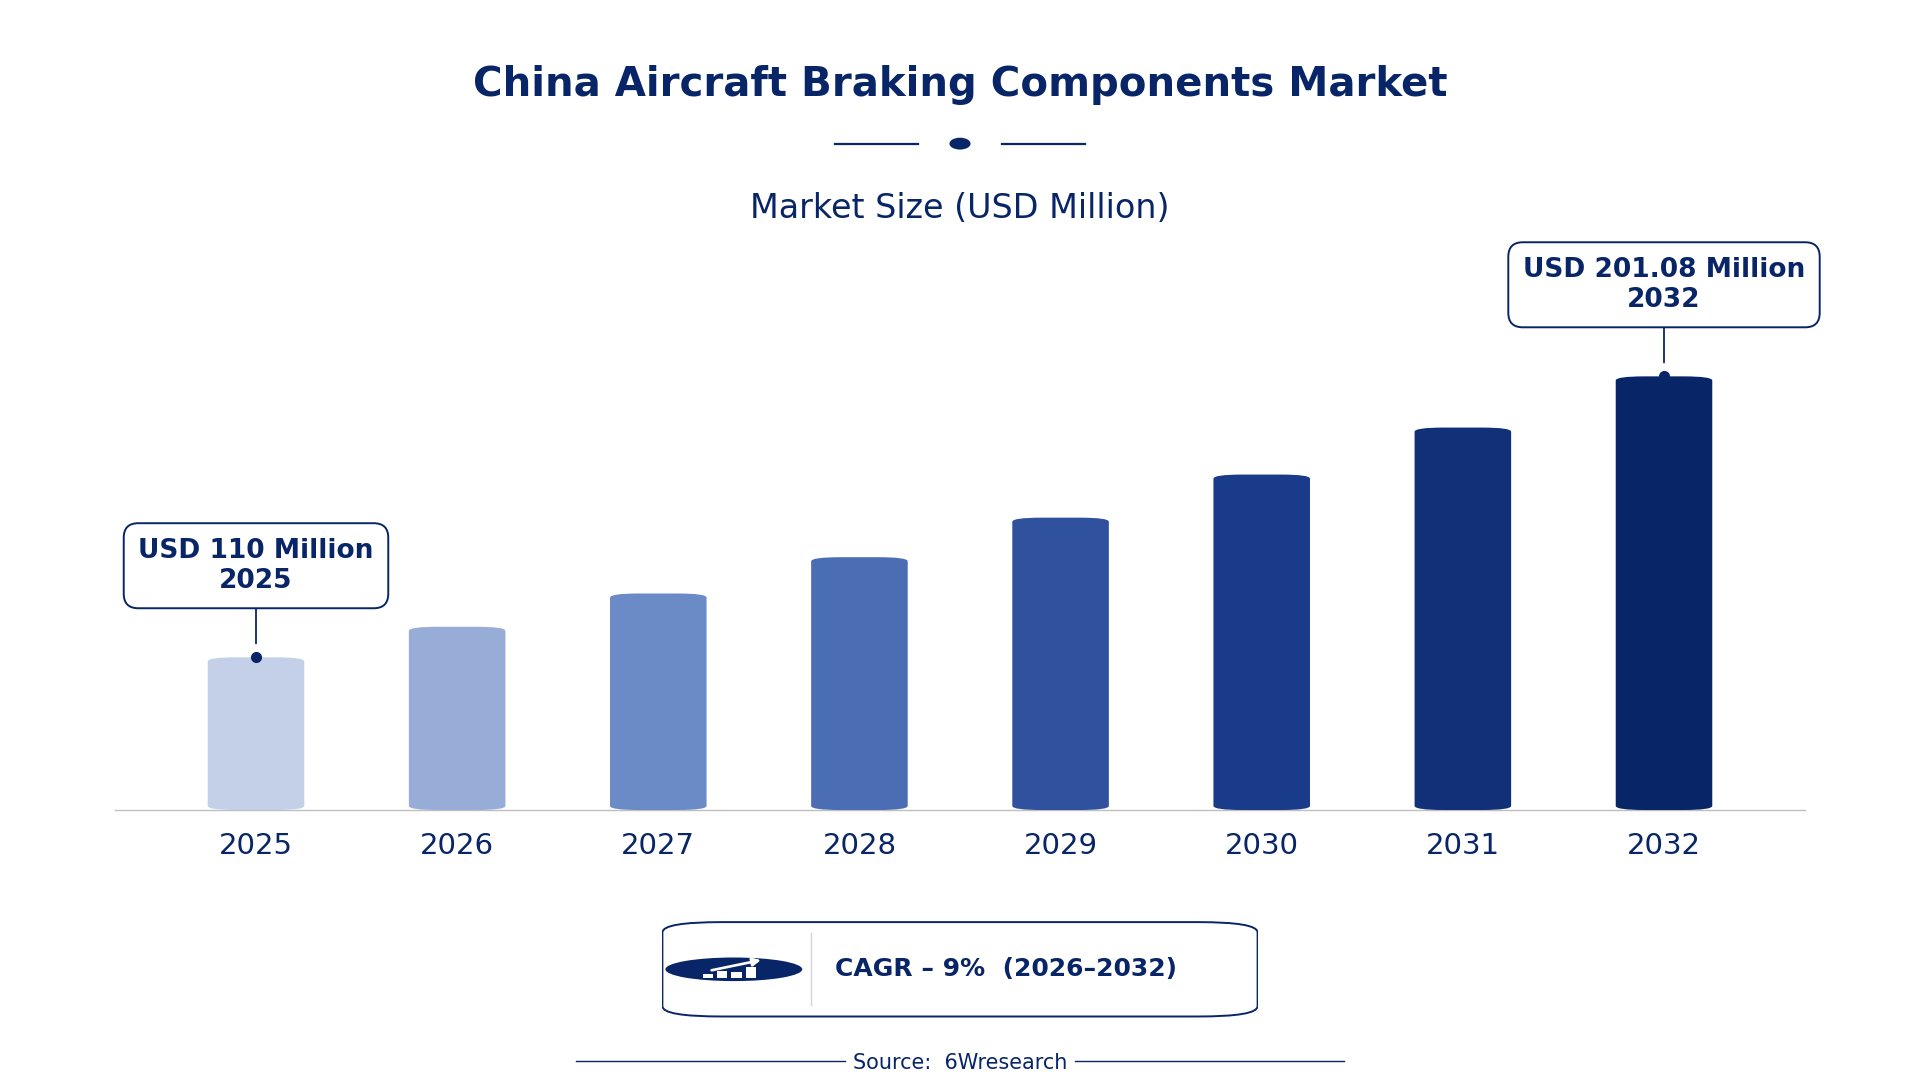
According to 6Wresearch internal database and industry insights, the China Aircraft Braking Components Market was valued at USD 110.0 million in 2025 and is projected to reach USD 201.08 million by 2032, growing at a CAGR of approximately 9% during 2026–2032.
China Aircraft Braking Components Market Highlights
| Report Metric | Details |
| Report Name | China Aircraft Braking Components Market |
| Market Size 2025 | USD 110.0 million |
| Market Size 2032 | USD 201.08 million |
| Absolute Growth 2025–2032 | USD 91.08 million |
| CAGR 2026–2032 | 9% |
| Peak Annual Growth | 11.1% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Brake Discs (45% share) |
| Leading Material Type, 2025 | Steel Alloy (42% share) |
| Leading Distribution Channel, 2025 | OEM Partners (46% share) |
| Leading End User, 2025 | Aviation MRO Facilities (40% share) |
| Fastest-Growing Component Type | Actuators (11.6% CAGR) |
| Fastest-Growing Material Type | Carbon Composite (11.3% CAGR) |
| Fastest-Growing End User | Airplane Manufacturers (10.2% CAGR) |
| Growing Sector | Aviation MRO Facilities |
| Key End Users | Aviation MRO Facilities, Airplane Manufacturers, Defense Aviation Units, Civil Aircraft OEMs |
China Aircraft Braking Components Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
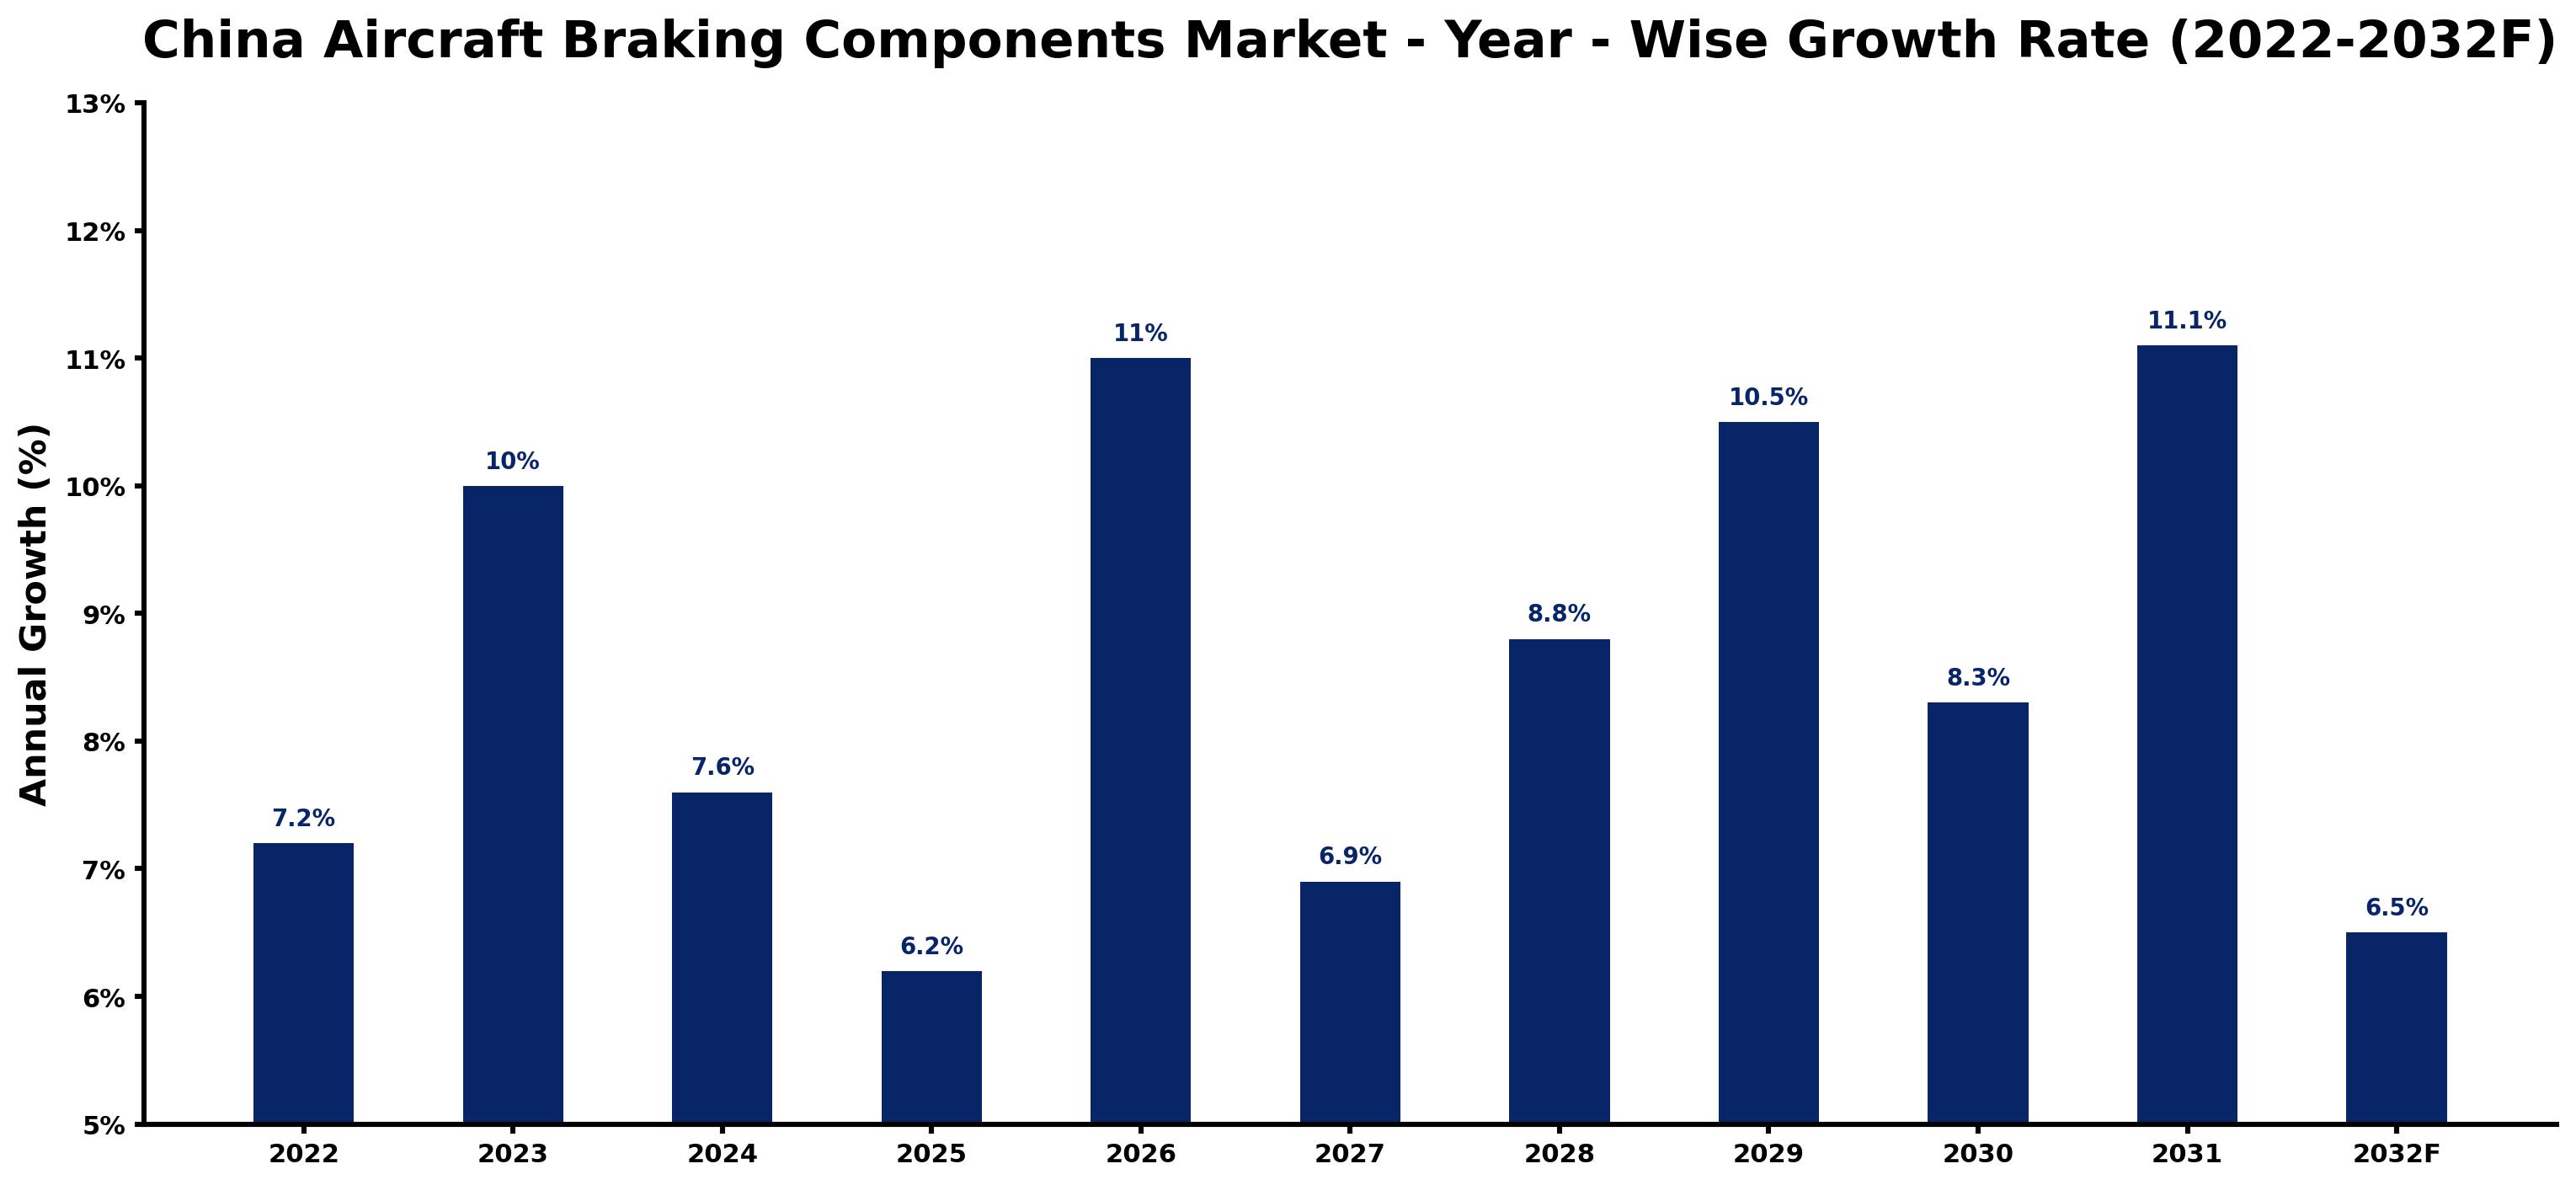
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.2 | The aviation sector showed strong passenger growth, driving demand for reliable braking components. |
| 2023 | 10.0 | Increased focus on safety standards boosted the need for compliant braking systems across the industry. |
| 2024 | 7.6 | The market experienced a slowdown as production adjustments took place to meet updated safety protocols. |
| 2025 | 6.2 | Demand continued to grow, albeit at a slower pace, as MRO facilities expanded their service offerings. |
| 2026 | 11.0 | The market rebounded with renewed investment in domestic aircraft production, increasing component demand. |
| 2027 | 6.9 | A slowdown occurred as suppliers faced challenges in adopting new technologies for braking systems. |
| 2028 | 8.8 | Growth accelerated again due to rising demand for advanced braking components in new aircraft. |
| 2029 | 10.5 | The expansion of aviation MRO facilities further increased the need for replacement braking components. |
| 2030 | 8.3 | A slight slowdown was noted as the market adjusted to the growing fleet size and maintenance needs. |
| 2031 | 11.1 | The peak growth year saw significant investments in durable braking components driven by defense spending. |
| 2032 | 6.5 | Growth slowed as the market stabilised, reflecting the maturation of the aviation sector's infrastructure. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Aircraft Braking Components Market Synopsis
Aircraft Braking Components in China are critical safety devices essential for the safe landing and takeoff of aircraft. These components are made from materials like carbon composites and steel alloys, designed to withstand high temperatures and stress. The China Aircraft Braking Components Market is growing due to strong demand from domestic manufacturers and a vast network of maintenance, repair, and overhaul facilities. With over 200 aviation MRO facilities contributing to component demand, the market is expected to thrive as the aviation sector continues to expand, aiming for a fleet size of 7,000 aircraft by 2035.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising domestic aircraft production | Driver | High | Brake Pads |
| Increasing passenger traffic in civil aviation | Driver | High | Brake Discs |
| Investment in MRO facilities | Opportunity | High | Aviation MRO Facilities |
| Growing demand for lightweight materials | Opportunity | Medium | Carbon Composite |
| Stringent safety regulations | Restraint | High | Steel Alloy |
| Supply chain disruptions | Restraint | Medium | Actuators |
| High costs of advanced materials | Challenge | High | Electronic |
| Technological integration challenges | Challenge | Medium | Anti-Skid Units |
Evaluation of Drivers in China Aircraft Braking Components Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased domestic aircraft production | Brake Pads | The civil aviation sector's growth, serving over 600 million passengers in 2022, drives demand for reliable braking systems. |
| Expansion of aviation MRO facilities | Brake Discs | With over 200 MRO facilities in China, the need for replacement components is rising as the sector expands. |
| Growing focus on safety standards | Actuators | Updated safety protocols increase the need for compliant braking systems, boosting actuator demand across the industry. |
| Investment in lightweight materials | Carbon Composite | Carbon composites are increasingly used for their weight reduction benefits, aligning with the industry's shift towards efficiency. |
| Rising defense budget for aviation | Steel Alloy | China's defense budget is projected to exceed $200 billion by 2025, increasing demand for durable braking components. |
Market growth in China for Aircraft Braking Components rests on rising domestic aircraft production, increased focus on safety standards and the expansion of aviation MRO facilities. The civil aviation sector served over 600 million passengers in 2022, driving demand for reliable braking systems. With over 200 MRO facilities, the need for replacement components is increasing. Updated safety protocols increase the need for compliant braking systems, boosting actuator demand across the industry. China's defense budget for aviation is set to exceed $200 billion by 2025, further increasing demand for durable braking components.
Evaluation of Restraints in China Aircraft Braking Components Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of advanced materials | Electronic | The shift towards advanced materials like carbon composites raises production costs, impacting pricing strategies for suppliers. |
| Supply chain disruptions | Actuators | Recent global supply chain issues have delayed component availability, affecting timely deliveries to manufacturers. |
| Stringent safety regulations | Steel Alloy | Compliance with updated CAAC safety standards requires additional investments, impacting operational budgets for producers. |
| Limited local manufacturing capabilities | Brake Pads | The reliance on imported components can lead to delays and increased costs for manufacturers. |
| Market saturation in certain segments | Brake Discs | As the market matures, growth opportunities in established segments become more challenging. |
China Aircraft Braking Components Market Challenges
The China Aircraft Braking Components Market faces a few practical problems, and the first is cost. Rising material prices for carbon composites and steel alloys have increased production costs by around 15% over the past year, straining budgets for buyers in the aviation sector. Many suppliers rely on outdated manufacturing technology, which delays the rollout of advanced braking systems, compromising safety and efficiency for aircraft operators. Compliance with CAAC standards necessitates ISO 9001 certification, a lengthy process that can take up to six months, hindering suppliers' ability to respond to urgent market demands. Supply chain disruptions in the Shanghai region have led to delivery delays, forcing buyers to extend lead times and maintain higher inventory levels, impacting operational efficiency.
Trends in the China Aircraft Braking Components Market
Four trends stand out in the China Aircraft Braking Components Market.
- Shift towards Lightweight Materials: Since 2021, the aviation sector has increasingly adopted carbon composite materials for braking systems, improving efficiency. This trend is supported as carbon composites are projected to grow by 11.3% through 2032 due to their benefits.
- Increased Investment in MRO Facilities: Aviation MRO facilities have seen significant upgrades since 2023, driven by the Aviation Safety Improvement Program. This initiative aims to improve operational capabilities across the country, enhancing service quality.
- Focus on Safety Standards: The Civil Aviation Administration of China has updated safety regulations since 2022, ensuring compliance across the industry. This regulatory shift aims to improve overall safety in aviation operations, benefiting manufacturers.
- Growth of Domestic Manufacturing: The Aviation Industry Development Plan (2021-2025) initiated in 2021 promotes local manufacturing capabilities, targeting a significant increase in domestic production by 2025, enhancing supply chain reliability.
Investment Opportunities in the China Aircraft Braking Components Market
Some of the investment opportunities in the China Aircraft Braking Components Market are mentioned below.
- Partnerships with Local MRO Facilities: Collaborating with local MRO facilities presents a valuable opportunity, as they are primary users of braking components. Suppliers can establish joint ventures to strengthen market presence and meet demand.
- Investment in Advanced Materials: Investing in carbon composite materials for braking components is timely, given their projected growth of 11.3%. Suppliers can target aviation manufacturers looking for lightweight solutions to enhance performance.
- Entering the OEM Market: Establishing partnerships with OEM partners is vital, as they dominate the distribution channel with a 46% share. Suppliers should seek certifications to meet OEM standards and gain market access.
- Expansion in the Shanghai Region: Focusing on the Shanghai region, a hub for aircraft manufacturing, offers opportunities for suppliers to meet rising demand for braking components through local partnerships and collaborations.
Government Initiatives in the China Aircraft Braking Components Market
The Ministry of Industry and Information Technology launched the 'Aviation Industry Development Plan (2021-2025)' to boost local manufacturing capabilities, aiming for a 25% increase in domestic production by 2025. The 'Regulations on the Safety Management of Civil Aviation' updated in 2022 enhance safety protocols for aircraft components, ensuring compliance among manufacturers. The 'Aviation Safety Improvement Program' initiated by the National Development and Reform Commission in 2023 allocates funding for MRO facilities to upgrade their equipment and processes, supporting the adoption of advanced technologies.
Aviation MRO facilities benefit from the funding provided by the 'Aviation Safety Improvement Program', which supports upgrades in equipment and processes. This initiative aims to improve operational capabilities and ensure that facilities can meet the growing demand for high-quality components. The program is expected to facilitate the adoption of advanced technologies, improving safety and efficiency in aviation operations. Furthermore, the Ministry of Transport's 'Green Aviation Initiative' encourages the use of sustainable materials, aligning with global trends towards environmental responsibility, promoting eco-friendly practices.
Future Insight of the China Aircraft Braking Components Market
The China Aircraft Braking Components Market is set to evolve as the aviation sector aims for a fleet size of 7,000 aircraft by 2035. Increased government investment in domestic manufacturing will drive advancements in braking technologies, enhancing safety and performance. The presence of over 200 MRO facilities will facilitate maintenance needs, ensuring consistent demand for high-quality components. The national strategy to improve aviation safety standards by 2025 will encourage suppliers to adopt innovative materials and technologies, positioning them for long-term success.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Component Type – Brake Discs Dominated, Actuators Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, in 2025, Brake Discs led the component type split with a 45% share. Brake discs are essential for the effectiveness of aircraft braking systems, making them a preferred choice among aviation buyers. Their critical role in ensuring safety during landings and takeoffs has resulted in a substantial installed base across various aircraft types in China. Actuators are projected to grow fastest, at a CAGR of 11.6% during 2026–2032. The actuator segment is growing rapidly due to the increasing demand for advanced braking systems in modern aircraft. With projections indicating a fleet size of 7,000 aircraft by 2035, the necessity for reliable actuators will continue to rise. Suppliers should focus on developing actuator technology to meet the increasing demands of the aviation sector.
By Material Type – Steel Alloy Dominated, Carbon Composite Expected to Grow Fastest
Steel Alloy took a 42% share of material type in 2025, more than any other category. Steel alloy remains the leading material in aircraft braking components due to its strength and durability, making it a preferred choice among manufacturers. Its widespread use in various aircraft types solidifies its position in the market. The quickest growth will come from Carbon Composite, forecast to expand at a CAGR of 11.3% between 2026 and 2032. Carbon composites are gaining traction for their lightweight and heat-resistant properties, driving their rapid adoption in aircraft braking systems. As safety standards evolve, the shift towards carbon composites will likely accelerate. Buyers should consider transitioning to carbon composite materials to improve aircraft performance and comply with emerging safety regulations.
By Distribution Channel – OEM Partners Dominated and Is Expected to Record the Fastest Growth
The largest distribution channel category in 2025 was OEM Partners, with a 46% share of total revenue. OEM partners dominate the distribution channel by providing original equipment directly to manufacturers, ensuring that aircraft are equipped with reliable braking components. Their established relationships within the aviation industry significantly enhance their market share. OEM Partners are also forecast to expand faster than any other category, at a CAGR of 10.5% over 2026–2032. The OEM partners segment is also the fastest-growing, propelled by the rising demand for original equipment as China's aircraft fleet expands. This growth reinforces their leading position in the market. Suppliers must strengthen partnerships with OEMs to secure a competitive edge in the rapidly growing aviation market.
By End User – Aviation MRO Facilities Dominated, Airplane Manufacturers Expected to Grow Fastest
With a 40% revenue share in 2025, Aviation MRO Facilities was the largest end user category. Aviation MRO facilities represent the largest end-user group, as they are vital for the maintenance and repair of braking components, ensuring aircraft safety. Their extensive presence across China supports a strong demand for these critical components. Over 2026–2032, Airplane Manufacturers are expected to post the fastest growth, at a CAGR of 10.2%. Airplane manufacturers are experiencing the fastest growth as they ramp up production to satisfy the increasing demand for new aircraft. This trend is expected to further elevate the demand for braking components. Suppliers should adapt their strategies to address the specific needs of airplane manufacturers to capitalise on this growth opportunity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Aircraft Braking Components Market Outlook
- Market Size of China Aircraft Braking Components Market, 2025
- Forecast of China Aircraft Braking Components Market, 2032
- Historical Data and Forecast of China Aircraft Braking Components Revenues & Volume for the Period 2022 - 2032F
- China Aircraft Braking Components Market Trend Evolution
- China Aircraft Braking Components Market Drivers and Challenges
- China Aircraft Braking Components Price Trends
- China Aircraft Braking Components Porter's Five Forces
- China Aircraft Braking Components Industry Life Cycle
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Brake Pads for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Brake Discs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Actuators for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Anti-Skid Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Carbon Composite for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Steel Alloy for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Hydraulic for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Electronic for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Aircraft Part Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By OEM Partners for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Online Aviation Marketplaces for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By System Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Aviation MRO Facilities for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Airplane Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Defense Aviation Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Braking Components Market Revenues & Volume By Civil Aircraft OEMs for the Period 2022 - 2032F
- China Aircraft Braking Components Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Aircraft Braking Components Top Companies Market Share
- China Aircraft Braking Components Competitive Benchmarking By Technical and Operational Parameters
- China Aircraft Braking Components Company Profiles
- China Aircraft Braking Components Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Component Type
- Brake Pads
- Brake Discs
- Actuators
- Anti-Skid Units
By Material Type
- Carbon Composite
- Steel Alloy
- Hydraulic
- Electronic
By Distribution Channel
- Aircraft Part Distributors
- OEM Partners
- Online Aviation Marketplaces
- System Integrators
By End User
- Aviation MRO Facilities
- Airplane Manufacturers
- Defense Aviation Units
- Civil Aircraft OEMs






































