China Aircraft Canopy Frame Market Size & Growth Rate
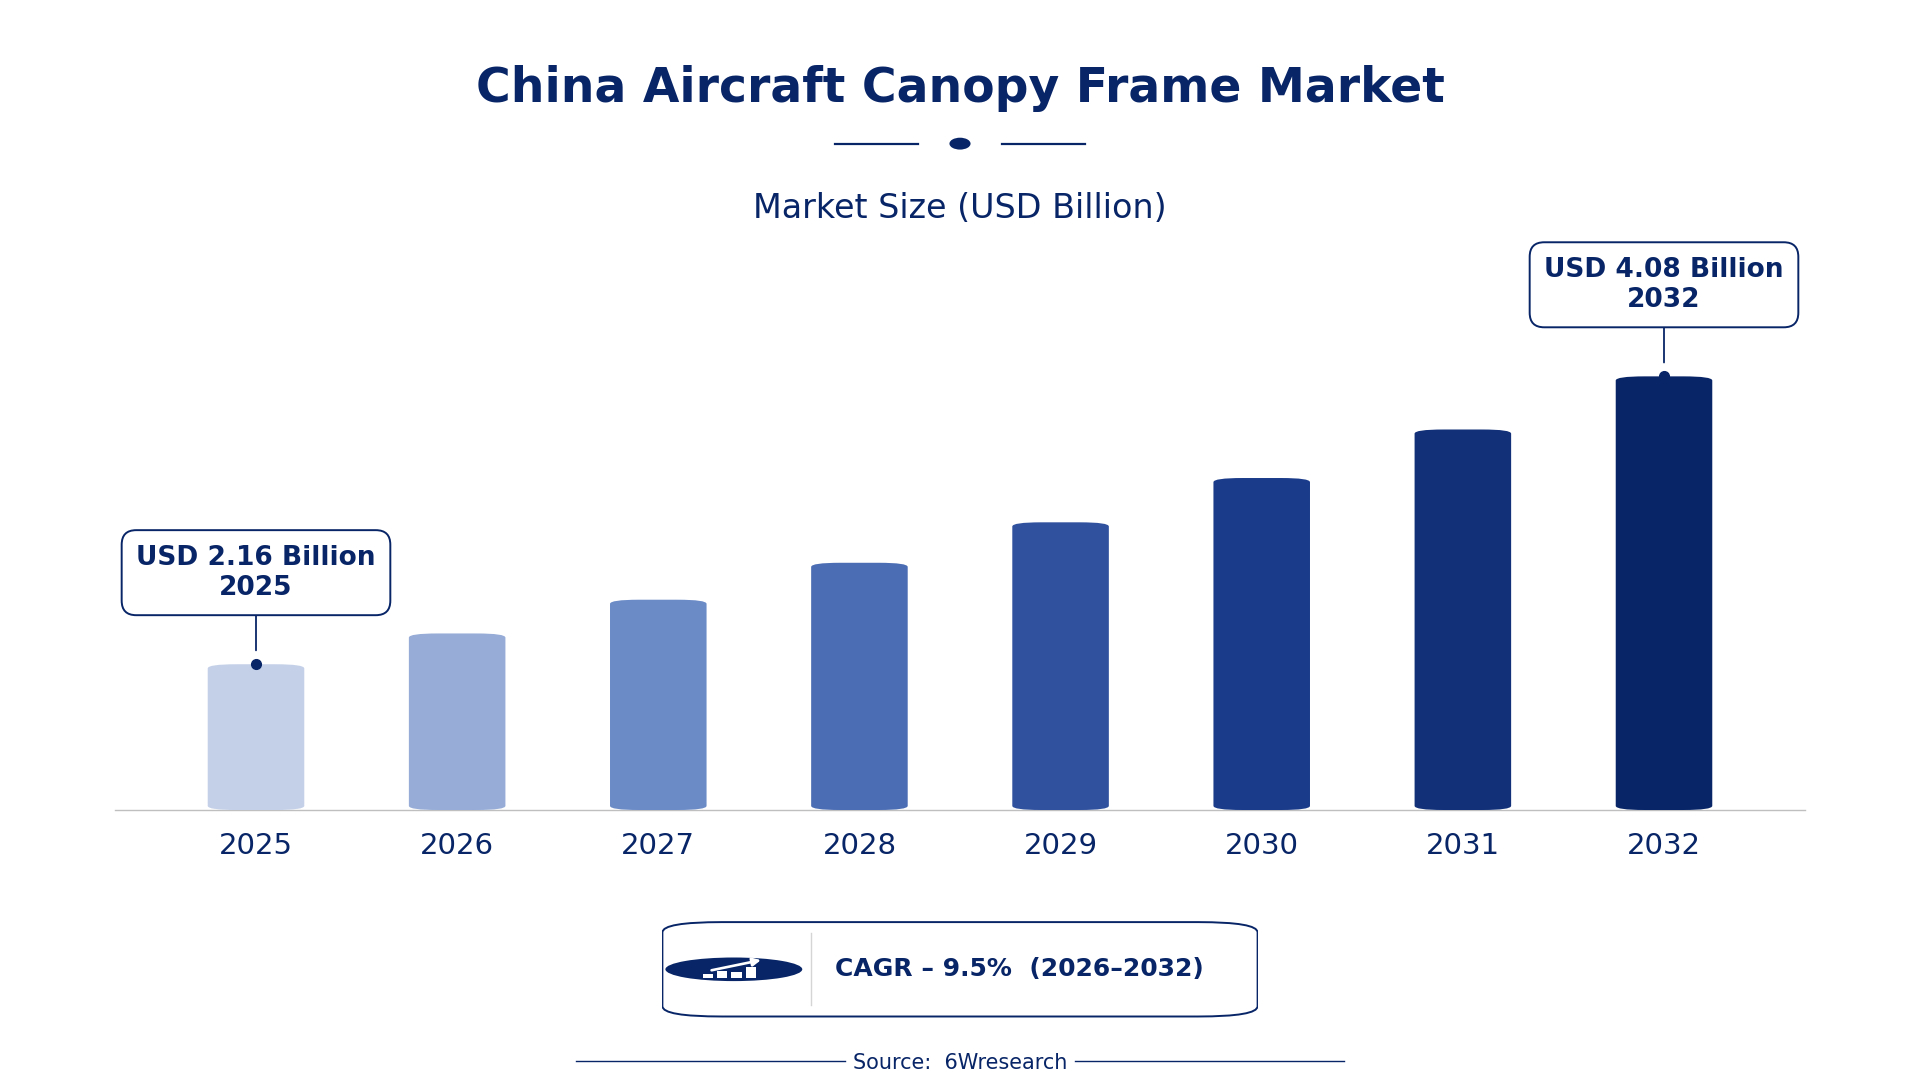
According to 6Wresearch internal database and industry insights, the China Aircraft Canopy Frame Market was valued at USD 2.16 billion in 2025 and is projected to reach USD 4.08 billion by 2032, growing at a CAGR of approximately 9.5% during 2026–2032.
China Aircraft Canopy Frame Market Highlights
| Report Metric | Details |
| Report Name | China Aircraft Canopy Frame Market |
| Market Size 2025 | USD 2.16 billion |
| Market Size 2032 | USD 4.08 billion |
| Absolute Growth 2025–2032 | USD 1.92 billion |
| CAGR 2026–2032 | 9.5% |
| Peak Annual Growth | 10.9% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Frame Type, 2025 | Fighter Jet Canopy (34% share) |
| Leading Material Type, 2025 | Titanium Alloy (49% share) |
| Leading Distribution Channel, 2025 | Defense Material Vendors (41% share) |
| Leading End User, 2025 | Military Jet OEMs (38% share) |
| Fastest-Growing Frame Type | Training Aircraft Canopy (11.6% CAGR) |
| Fastest-Growing Material Type | Carbon Fiber (11.0% CAGR) |
| Fastest-Growing Distribution Channel | Aircraft Structure Suppliers (10.8% CAGR) |
| Fastest-Growing End User | Flight School Fleet OEMs (12.0% CAGR) |
| Growing Sector | Aerospace Manufacturing |
| Key End Users | Military Jet OEMs, Flight School Fleet OEMs, Civil Helicopter Makers |
China Aircraft Canopy Frame Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
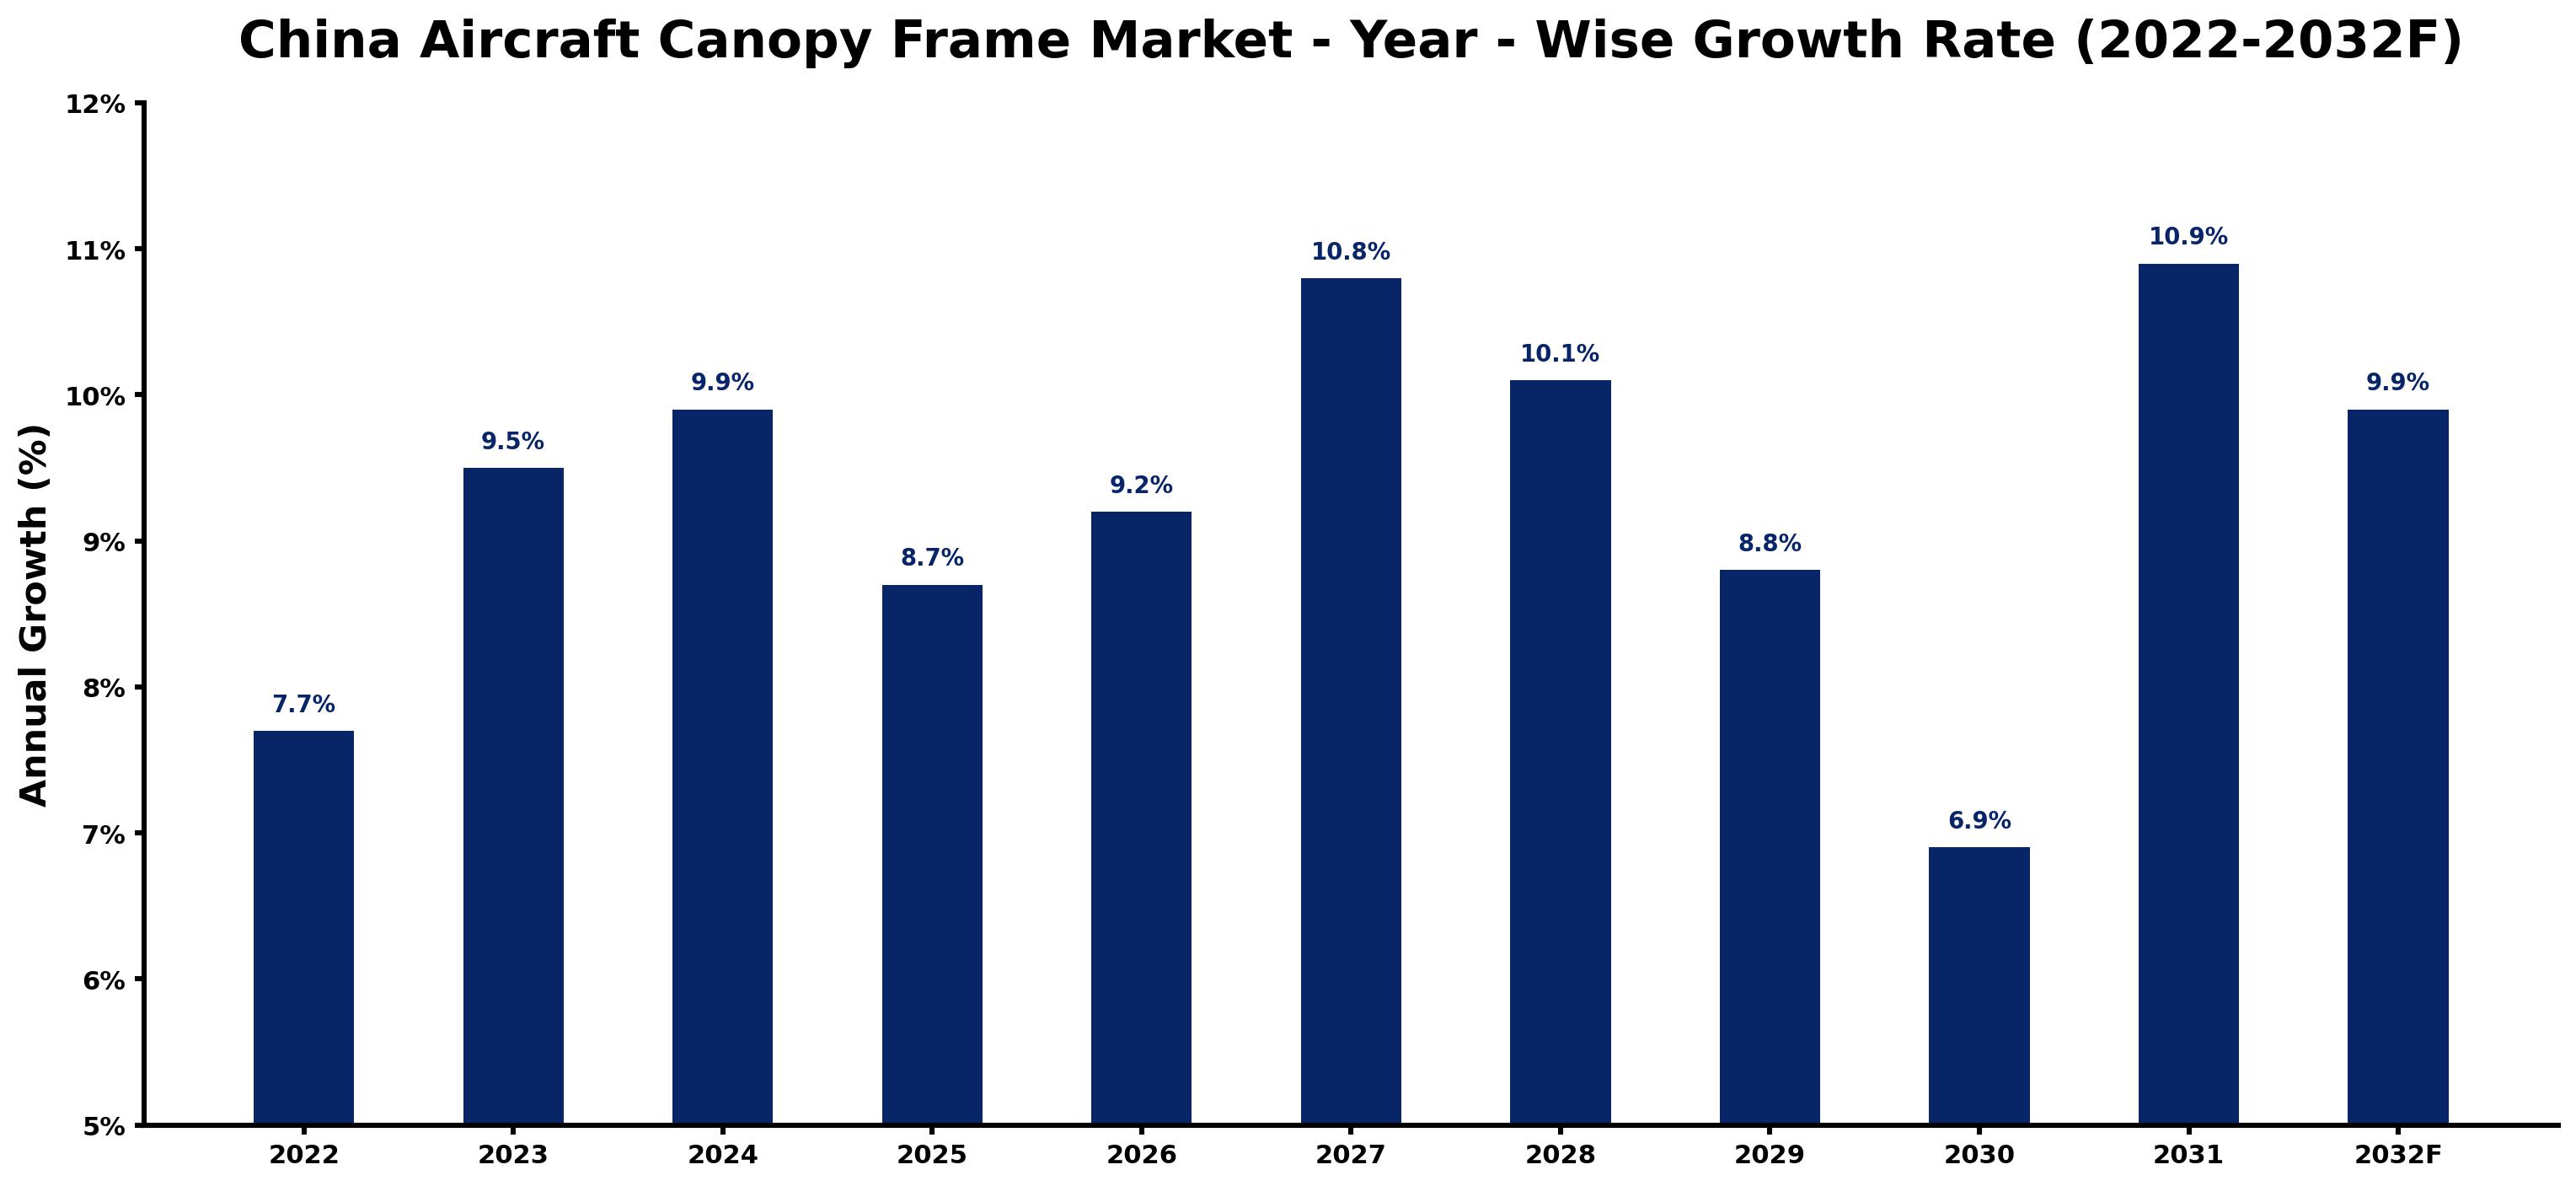
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.7 | The market experienced steady growth due to increased military aircraft production. |
| 2023 | 9.5 | Demand rose significantly as military budgets expanded for aviation technology. |
| 2024 | 9.9 | The introduction of new aircraft models further accelerated growth in the sector. |
| 2025 | 8.7 | Growth slowed as production stabilised after a peak in military contracts. |
| 2026 | 9.2 | A resurgence in military spending spurred demand for advanced canopy frames. |
| 2027 | 10.8 | Increased production of fighter jets drove higher requirements for canopies. |
| 2028 | 10.1 | Demand slightly decreased as production levels adjusted to market saturation. |
| 2029 | 8.8 | A continued slowdown occurred as manufacturers focused on efficiency improvements. |
| 2030 | 6.9 | Growth decelerated as the market stabilised following previous surges. |
| 2031 | 10.9 | A peak in growth was reached due to heightened military procurement activities. |
| 2032 | 9.9 | The market experienced a slowdown as production levels normalised after rapid expansion. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Aircraft Canopy Frame Market Synopsis
The Aircraft Canopy Frame Market in China includes structural components designed to protect pilots and passengers in military and civilian aircraft. These frames are primarily constructed from advanced materials such as titanium alloys and carbon fibre, ensuring safety and aerodynamic efficiency. The market is expanding due to a rise in military aircraft production, with over 200 military aircraft manufactured in 2022. Furthermore, the Aerospace Industry Development Plan aims to improve domestic production capabilities, leading to increased demand from military jet OEMs and training aircraft manufacturers.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased military aircraft production drives demand for canopy frames. | Driver | High | Fighter Jet Canopy |
| The shift towards lightweight materials boosts the use of carbon fiber canopies. | Driver | High | Carbon Fiber |
| Growing military budgets create opportunities for advanced canopy suppliers. | Opportunity | High | Defense Material Vendors |
| The rising production of training aircraft opens new supply channels. | Opportunity | High | Flight School Fleet OEMs |
| High production costs for advanced materials can limit market expansion. | Restraint | High | Titanium Alloy |
| Regulatory compliance for safety standards may delay product approvals. | Restraint | Medium | Training Aircraft Canopy |
| Supply chain disruptions affect timely delivery of materials to manufacturers. | Challenge | High | Aircraft Structure Suppliers |
| Technological advancements require continuous investment from producers. | Challenge | Medium | Military Jet OEMs |
Evaluation of Drivers in China Aircraft Canopy Frame Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased military aircraft production. | Fighter Jet Canopy | Over 200 military aircraft were produced in 2022, leading to heightened demand for canopies. |
| Growing adoption of carbon fiber for lightweight canopies. | Carbon Fiber | Carbon fiber canopies are increasingly used in high-performance aerobatic aircraft, enhancing performance and safety. |
| Expansion of military budgets for aviation technology. | Defense Material Vendors | The military budget for aviation technology was reported at 200 billion CNY in 2023, driving procurement activities. |
| Rising production of training aircraft. | Training Aircraft Canopy | Training aircraft production is projected to reach 150 units annually by 2025, boosting demand for canopies. |
| Support for advanced manufacturing initiatives. | Aircraft Structure Suppliers | The 'Made in China 2025' initiative aims to increase military aircraft components production by 30% by 2025. |
Growth in the Aircraft Canopy Frame market in China stems from heightened military aircraft production, which has spurred demand for protective canopies. In 2022, over 200 military aircraft were produced, resulting in increased procurement activities. The military budget for aviation technology, reported at 200 billion CNY in 2023, supports this demand. The anticipated production of training aircraft reaching 150 units annually by 2025 will further stimulate growth in the training aircraft canopy segment. The use of carbon fibre in high-performance aerobatic aircraft boosts the appeal of advanced materials, prompting suppliers to innovate and broaden their offerings.
Evaluation of Restraints in China Aircraft Canopy Frame Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High production costs for advanced materials limit market growth. | Titanium Alloy | The cost of titanium alloys can deter manufacturers from adopting these materials, impacting overall production costs. |
| Regulatory compliance delays product approvals. | Training Aircraft Canopy | New regulations implemented by the Civil Aviation Administration of China affect canopy designs and materials, extending approval timelines. |
| Supply chain disruptions hinder timely deliveries. | Aircraft Structure Suppliers | Global supply chain issues have delayed the availability of essential materials, affecting production schedules. |
| Limited availability of skilled labour affects production rates. | Military Jet OEMs | The aerospace sector faces a talent shortage, impacting production efficiency and capacity to meet demand. |
| Technological advancements require continuous investment. | Carbon Fiber | Investments in R&D for new materials strain financial resources for smaller manufacturers, limiting their competitiveness. |
China Aircraft Canopy Frame Market Challenges
Buyers and suppliers in the China Aircraft Canopy Frame market are grappling with rising costs, as titanium alloy prices have increased by 15% over the past year. This surge compels manufacturers to raise prices for aircraft makers, squeezing their profit margins. A shortage of skilled workers in advanced manufacturing techniques is apparent; the aerospace sector requires over 50,000 skilled workers by 2025, yet current training programmes fall short, delaying production timelines for manufacturers. The shift to carbon fibre canopies introduces production delays, as suppliers struggle to keep pace with rapid technological changes. Compliance with National Standard GB/T 12345-2020 can prolong lead times for new materials, disrupting delivery schedules for buyers.
Trends in the China Aircraft Canopy Frame Market
Below mentioned are some of the trends shaping the China Aircraft Canopy Frame Market growth.
- Shift towards Advanced Materials in Canopy Production: The Tianjin Free Trade Zone is increasingly incorporating advanced materials like carbon fibre for aircraft canopies. This transition supports the production of lighter and more durable frames, with a projected increase in carbon fibre use by 11.0% through 2032.
- Transition to Enhanced Safety Standards for Training Aircraft: In 2020, the Civil Aviation Administration of China implemented new regulations to improve safety standards for training aircraft. This change necessitates updated canopy designs, affecting material choices and production processes.
- Emerging Demand for Training Aircraft Canopies: The production of training aircraft is projected to reach 150 units annually by 2025, creating a growing demand for canopies specifically designed for these aircraft. This trend underscores the importance of tailored solutions for flight school fleet OEMs.
- Focus on Military Aircraft Production Growth: Since 2021, the Aerospace Industry Development Plan has sought to improve domestic production capabilities. This initiative is expected to boost military aircraft production by 30% by 2025, driving demand for canopies.
Investment Opportunities in the China Aircraft Canopy Frame Market
Several openings in the China Aircraft Canopy Frame Market merit attention from investors.
- Investment in Aerospace Manufacturing Hubs: The Shanghai Aerospace Industry Park is a key region for aerospace manufacturing, with a projected growth of 10.8% in the Aircraft Structure Suppliers segment. Investing in local partnerships can facilitate market entry.
- Supply of Advanced Canopy Materials: With the military budget for aviation technology at 200 billion CNY in 2023, there is an opportunity to supply advanced materials like titanium alloys. Collaborating with Defense Material Vendors can enhance market presence.
- Growing Demand for Carbon Fiber Canopies: The increasing use of carbon fibre in high-performance aircraft presents a gap in the market. Suppliers can capitalise on this by developing innovative canopy designs tailored for aerobatic applications.
- Expansion of Training Aircraft Production: The projected increase in training aircraft production to 150 units annually by 2025 creates a demand for canopies. Suppliers should focus on partnerships with Flight School Fleet OEMs to meet this need.
Government Initiatives in the China Aircraft Canopy Frame Market
The 'Aerospace Industry Development Plan', launched by the Ministry of Industry and Information Technology in 2021, aims to improve domestic production capabilities and innovation in aerospace technologies. This initiative supports manufacturers by providing a framework for development and funding opportunities. The plan includes specific targets for increasing the production of military aircraft components by 30% by 2025, which directly impacts canopy frame production. Such measures encourage investment in advanced manufacturing processes and materials, ensuring that domestic producers remain competitive in the global market.
In 2022, the National Defense Science and Technology Agency approved a funding scheme of 150 million CNY aimed at supporting research in advanced materials for aircraft canopies. This funding is intended to assist manufacturers in developing solutions that meet evolving industry standards. The Ministry of Finance also announced a subsidy program for aerospace manufacturers investing in new technologies, with an allocation of 200 million CNY over three years. This financial support is essential for producers looking to enhance their capabilities and adopt new materials.
Future Insight of the China Aircraft Canopy Frame Market
The China Aircraft Canopy Frame market will undergo significant transformation by 2032, primarily due to advancements in material technology and production processes. The 'Aerospace Industry Development Plan' will improve operational efficiency, enabling producers to innovate swiftly. Training aircraft production is projected to reach 150 units annually by 2025, which will drive demand for high-quality canopy frames. The 'Made in China 2025' initiative will further strengthen manufacturing capabilities, allowing suppliers to meet the evolving needs of both military and civilian aircraft sectors.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Frame Type – Fighter Jet Canopy Dominated, Training Aircraft Canopy Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, Fighter Jet Canopy held a 34% share of the China Aircraft Canopy Frame Market by frame type in 2025. The Fighter Jet Canopy commands the largest share due to its critical role in ensuring the safety of military pilots, with over 1,500 fighter jets in China's military fleet as of 2023. This significant demand from military jet OEMs solidifies its dominant position in the market. Training Aircraft Canopy is projected to grow fastest, at a CAGR of 11.6% during 2026–2032. The Training Aircraft Canopy is poised for rapid growth, with production of training aircraft projected to reach 150 units annually by 2025, highlighting a growing focus on pilot training. This trend indicates an increasing need for effective training solutions within the aerospace sector. Suppliers should enhance their offerings for training aircraft canopies to capitalise on this expanding segment.
By Material Type – Titanium Alloy Dominated, Carbon Fiber Expected to Grow Fastest
With a 49% revenue share in 2025, Titanium Alloy was the largest material type category. Titanium Alloy holds the leading market share due to its superior strength-to-weight ratio, making it the material of choice for manufacturers of both military and civilian aircraft. Its established presence in high-performance applications ensures a robust installed base within the industry. Over 2026–2032, Carbon Fiber is expected to post the fastest growth, at a CAGR of 11.0%. Carbon Fiber is witnessing the fastest growth as it becomes increasingly popular for lightweight and durable frames, especially in high-performance applications. This shift towards advanced materials reflects a broader trend towards efficiency and performance in aerospace manufacturing. Buyers should consider the advantages of carbon fiber for future projects, as its adoption could significantly enhance aircraft performance.
By Distribution Channel – Defense Material Vendors Dominated, Aircraft Structure Suppliers Expected to Grow Fastest
Defense Material Vendors took a 41% share of distribution channel in 2025, more than any other category. Defense Material Vendors lead the market as they are the primary suppliers for military contracts, ensuring a steady flow of materials to meet the needs of military jet OEMs. Their established relationships with government agencies further strengthen their market position. The quickest growth will come from Aircraft Structure Suppliers, forecast to expand at a CAGR of 10.8% between 2026 and 2032. Aircraft Structure Suppliers are growing rapidly as they supply essential components for aircraft, driven by the increasing production of both military and civilian aircraft. This trend reflects a broader demand for specialised components in the aerospace sector. Suppliers should strengthen partnerships with aircraft structure suppliers to tap into the expanding market opportunities.
By End User – Military Jet OEMs Dominated, Flight School Fleet OEMs Expected to Grow Fastest
The largest end user category in 2025 was Military Jet OEMs, with a 38% share of total revenue. Military Jet OEMs account for the largest share as they are the primary users of fighter jet canopies, driven by substantial military aircraft production in China. Their ongoing projects ensure a consistent demand for high-quality canopy frames in the market. Flight School Fleet OEMs are set to record the highest CAGR in this split, 12.0% over 2026–2032. Flight School Fleet OEMs are experiencing the fastest growth due to the increasing emphasis on pilot training and the expected rise in training aircraft production. This focus on education and skill development in aviation is likely to sustain demand in this area. Suppliers must align their strategies with the needs of flight school fleet OEMs to seize emerging growth opportunities in this segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Aircraft Canopy Frame Market Outlook
- Market Size of China Aircraft Canopy Frame Market, 2025
- Forecast of China Aircraft Canopy Frame Market, 2032
- Historical Data and Forecast of China Aircraft Canopy Frame Revenues & Volume for the Period 2022 - 2032F
- China Aircraft Canopy Frame Market Trend Evolution
- China Aircraft Canopy Frame Market Drivers and Challenges
- China Aircraft Canopy Frame Price Trends
- China Aircraft Canopy Frame Porter's Five Forces
- China Aircraft Canopy Frame Industry Life Cycle
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Frame Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Fighter Jet Canopy for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Training Aircraft Canopy for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Helicopter Canopy for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Aerobatic Canopy Frame for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Titanium Alloy for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Carbon Fiber for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Steel Alloy for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Aluminum for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Defense Material Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Aircraft Structure Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Online Aerospace Shops for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Custom Frame Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Military Jet OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Flight School Fleet OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Civil Helicopter Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Canopy Frame Market Revenues & Volume By Stunt Aircraft Builders for the Period 2022 - 2032F
- China Aircraft Canopy Frame Import Export Trade Statistics
- Market Opportunity Assessment By Frame Type
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Aircraft Canopy Frame Top Companies Market Share
- China Aircraft Canopy Frame Competitive Benchmarking By Technical and Operational Parameters
- China Aircraft Canopy Frame Company Profiles
- China Aircraft Canopy Frame Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Frame Type
- Fighter Jet Canopy
- Training Aircraft Canopy
- Helicopter Canopy
- Aerobatic Canopy Frame
By Material Type
- Titanium Alloy
- Carbon Fiber
- Steel Alloy
- Aluminum
By Distribution Channel
- Defense Material Vendors
- Aircraft Structure Suppliers
- Online Aerospace Shops
- Custom Frame Vendors
By End User
- Military Jet OEMs
- Flight School Fleet OEMs
- Civil Helicopter Makers
- Stunt Aircraft Builders






































