China Aircraft Data Protection Market Size & Growth Rate
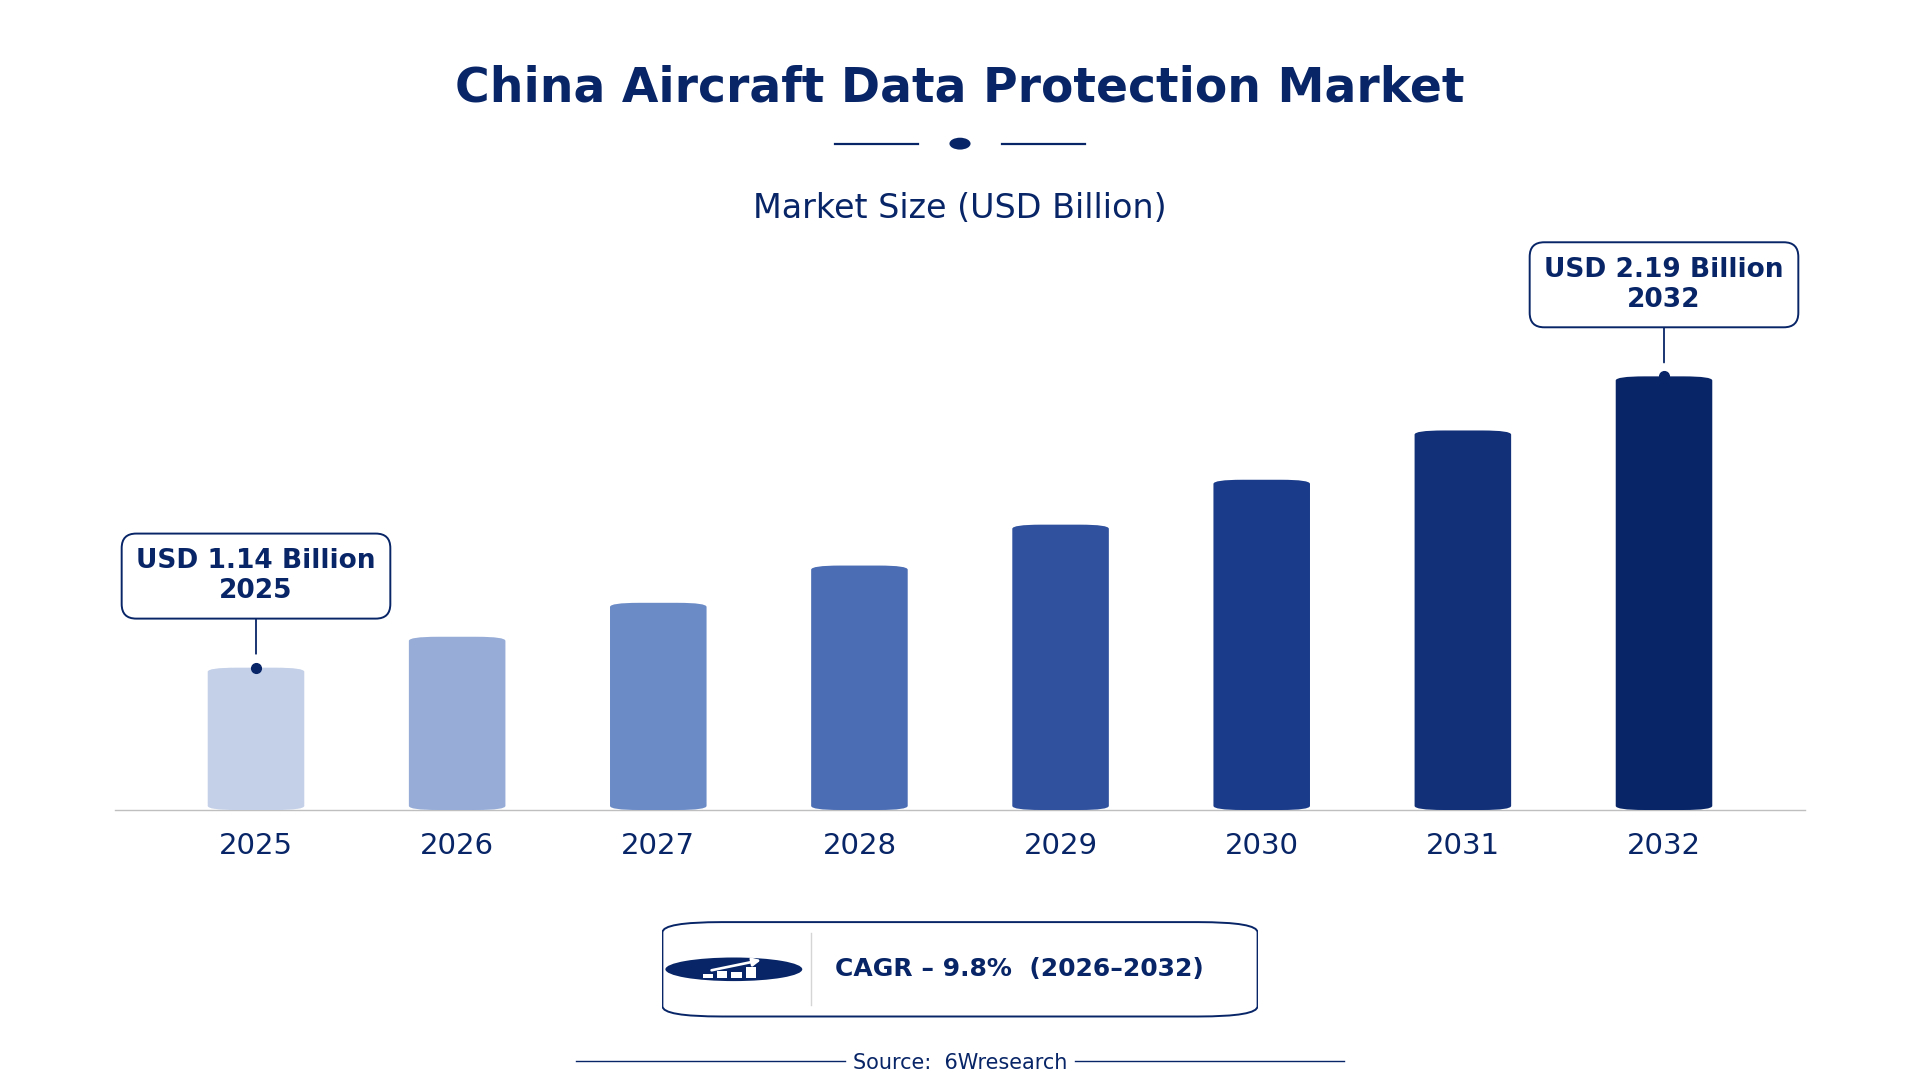
According to 6Wresearch internal database and industry insights, the China Aircraft Data Protection Market was valued at USD 1.14 billion in 2025 and is projected to reach USD 2.19 billion by 2032, growing at a CAGR of approximately 9.8% during 2026–2032.
China Aircraft Data Protection Market Highlights
| Report Metric | Details |
| Report Name | China Aircraft Data Protection Market |
| Market Size 2025 | USD 1.14 billion |
| Market Size 2032 | USD 2.19 billion |
| Absolute Growth 2025–2032 | USD 1.05 billion |
| CAGR 2026–2032 | 9.8% |
| Peak Annual Growth | 11.8% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Protection Type, 2025 | Encrypted Storage (38% share) |
| Leading Data Format, 2025 | Solid-State Drives (37% share) |
| Leading Distribution Channel, 2025 | Cybersecurity Integrators (47% share) |
| Leading End User, 2025 | Aircraft OEMs (39% share) |
| Fastest-Growing Protection Type | Fireproof Data Boxes (11.0% CAGR) |
| Fastest-Growing Data Format | Crash Survivable (12.1% CAGR) |
| Fastest-Growing Distribution Channel | Online Aerospace Suppliers (12.4% CAGR) |
| Fastest-Growing End User | Commercial Airlines (12.4% CAGR) |
| Growing Sector | Aerospace Manufacturing |
| Key End Users | Aircraft OEMs, Commercial Airlines, Cybersecurity Integrators, Defense Aircraft Units |
China Aircraft Data Protection Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
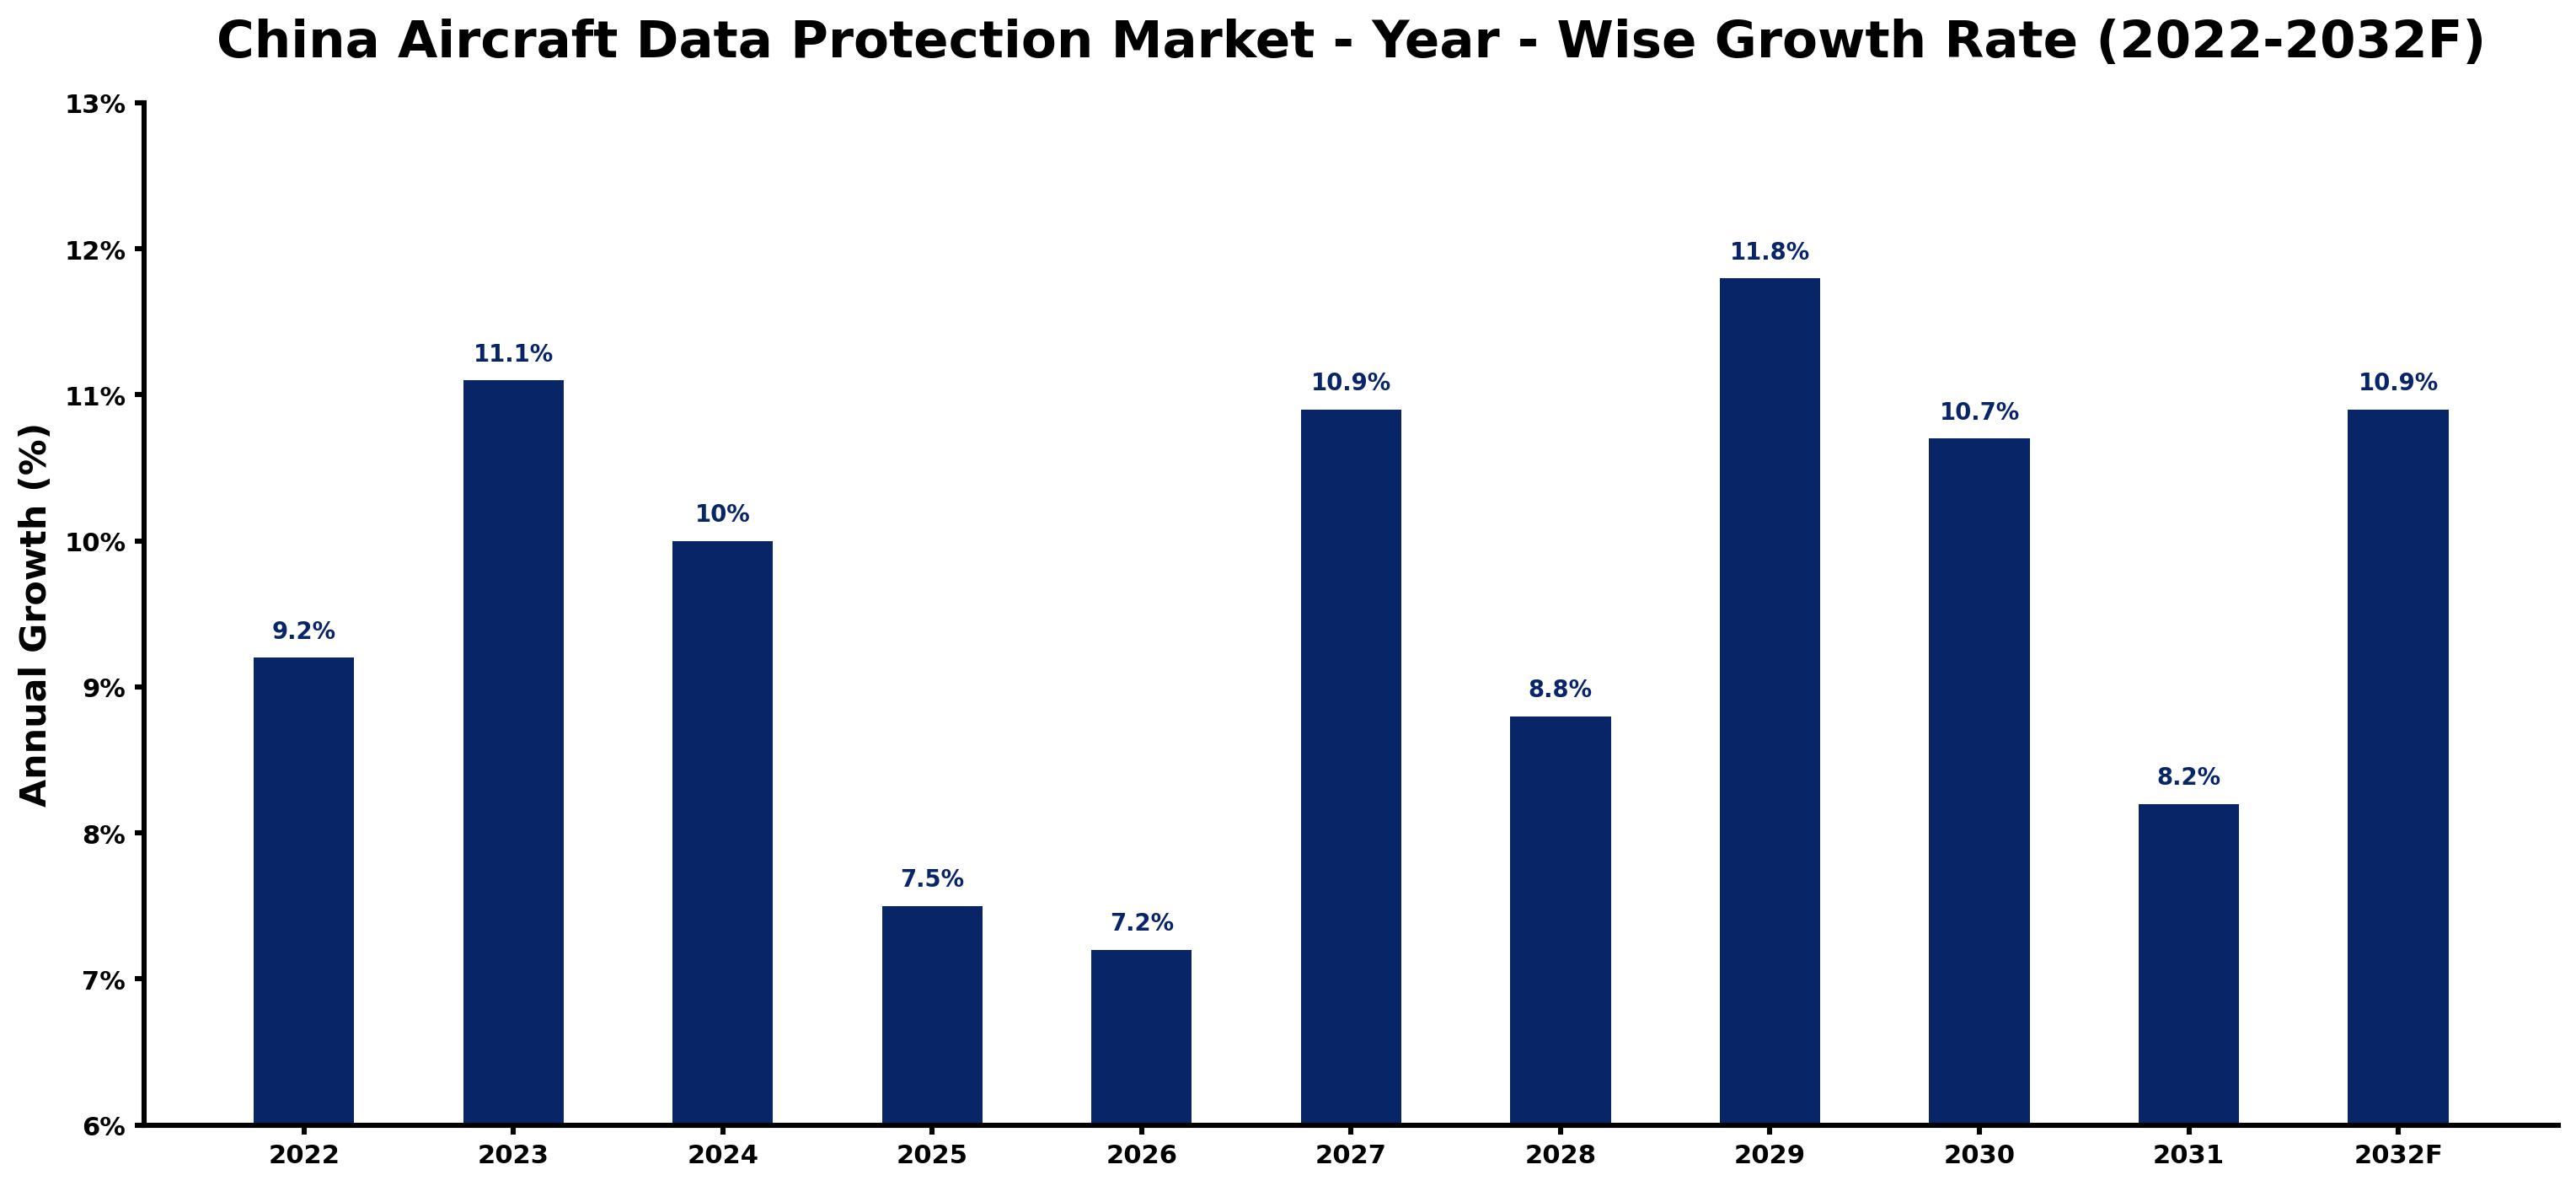
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 9.2 | The market experienced steady demand from domestic manufacturers and airlines. |
| 2023 | 11.1 | Growth accelerated due to increased investments in data protection technologies. |
| 2024 | 10.0 | A slowdown occurred as market maturation began impacting growth rates. |
| 2025 | 7.5 | Continued demand from commercial airlines contributed to a further slowdown. |
| 2026 | 7.2 | Growth slowed as the market adjusted to evolving regulatory requirements. |
| 2027 | 10.9 | Demand surged with rising air traffic and the need for enhanced data security. |
| 2028 | 8.8 | A slowdown was noted as the market stabilised after rapid growth phases. |
| 2029 | 11.8 | The market peaked with heightened investments in cybersecurity measures. |
| 2030 | 10.7 | Growth slowed as the market began to normalise post-peak performance. |
| 2031 | 8.2 | A further slowdown occurred as the market adjusted to established standards. |
| 2032 | 10.9 | Growth is expected to rise again with new technological advancements. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Aircraft Data Protection Market Synopsis
Aircraft Data Protection in China focuses on securing data generated and stored within aircraft systems through encryption and robust storage solutions. This market thrives on the necessity to protect flight data and adhere to aviation regulations. The Civil Aviation Administration of China enforces stringent data protection standards, prompting demand from domestic manufacturers and airlines. As China's aerospace industry approaches a market size of $1 trillion by 2035, investments in data protection technologies are set to rise sharply. The growing number of commercial aircraft further stimulates this demand, creating an active market environment.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing air traffic and passenger numbers drive the need for enhanced data protection solutions. | Driver | High | Commercial Airlines |
| Increased investments in cybersecurity technologies create opportunities for innovation in data protection. | Driver | High | Cybersecurity Integrators |
| The aerospace industry is projected to reach $1 trillion by 2035, highlighting significant investment potential. | Opportunity | High | Aircraft OEMs |
| The expansion of the Beijing-Tianjin-Hebei region as a manufacturing hub increases demand for data protection. | Opportunity | High | Encrypted Storage |
| Regulatory compliance requirements can slow down the adoption of new technologies in the market. | Restraint | Medium | Encrypted Storage |
| The high cost of implementing advanced data protection measures can limit market access for smaller players. | Restraint | Medium | Cloud Data Sync |
| Buyers face challenges in adapting to rapidly changing cybersecurity regulations and standards. | Challenge | High | Commercial Airlines |
| Suppliers encounter difficulties in keeping pace with technological advancements and market demands. | Challenge | High | Cybersecurity Integrators |
Evaluation of Drivers in China Aircraft Data Protection Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased air traffic leading to higher data protection needs. | Commercial Airlines | China's air traffic is projected to reach 1 billion passengers by 2035. |
| Growing investments in cybersecurity technologies improve data protection capabilities. | Cybersecurity Integrators | The defense budget allocated $224 billion for military modernization, including data security. |
| Regulatory mandates drive compliance-driven purchases of data protection solutions. | Aircraft OEMs | The Civil Aviation Administration of China mandates data protection standards for all commercial aircraft. |
| Technological advancements in data storage solutions improve data integrity. | Encrypted Storage | Solid-State Drives, which hold a 37% market share, are essential for reliable data storage. |
| Partnerships with international firms expand the range of available solutions. | Cloud Service Providers | The Shanghai Free Trade Zone is a key area for aerospace innovation and data protection solutions. |
Air traffic in China is anticipated to reach 1 billion passengers by 2035, driving the need for enhanced data protection solutions. The defence budget has allocated $224 billion for military modernisation, which boosts investments in protection technologies. Compliance with standards set by the Civil Aviation Administration of China urges manufacturers to invest in advanced solutions. The market benefits from the adoption of modern storage technologies that ensure reliable data integrity and propel growth in this sector.
Evaluation of Restraints in China Aircraft Data Protection Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory compliance can slow down the introduction of new technologies. | Encrypted Storage | The National Standard GB/T 20237-2019 outlines data protection requirements for aviation. |
| High implementation costs may deter smaller companies from entering the market. | Cloud Data Sync | The need for advanced solutions can be financially burdensome for new entrants. |
| Limited awareness among smaller airlines about data protection technologies hampers adoption. | Commercial Airlines | Many smaller airlines struggle to keep pace with evolving data protection standards. |
| Complexity of integrating new data protection systems can delay implementation. | Cybersecurity Integrators | The integration of advanced systems often requires significant time and resources. |
| Market saturation in certain segments may limit growth opportunities. | Encrypted Storage | As the market matures, competition increases, making differentiation challenging. |
China Aircraft Data Protection Market Challenges
Buyers and suppliers in the China Aircraft Data Protection market encounter a skills gap, as the rapid growth of the aerospace sector exceeds the supply of qualified professionals. This shortage exists due to insufficient specialised training programs, delaying project timelines for manufacturers and airlines. Technology integration issues are also prevalent, with many legacy systems lacking modern encryption and secure transmission protocols, complicating compliance with the Civil Aviation Administration of China standards. Such non-compliance can incur fines up to $1 million for airlines, disrupting operations. Increasing competition from international firms pressures local suppliers to lower prices, risking the quality of data protection solutions and leaving buyers vulnerable to inadequate services that fail to meet regulatory requirements.
Trends in the China Aircraft Data Protection Market
Four trends stand out in the China Aircraft Data Protection Market.
- Shift towards Advanced Encryption Techniques: China is increasingly adopting advanced encryption techniques to secure data in aircraft systems. The 2023 Cybersecurity Law outlines strict regulations for data protection, pushing manufacturers to upgrade their systems. This shift is expected to improve compliance and security measures.
- Growing Demand for Real-Time Data Processing: The demand for real-time data processing is rising as airlines seek to improve operational efficiency. The National Aerospace Industry Association of China promotes standards for data protection, encouraging investments in real-time systems. This trend supports the integration of advanced technologies into aircraft operations.
- Expansion of Data Protection Standards: The Civil Aviation Administration of China has expanded data protection standards, requiring compliance from all commercial aircraft. This initiative is driving the adoption of secure data transmission protocols, ensuring that sensitive information is safeguarded effectively. Compliance is essential for maintaining operational integrity.
- Increased Focus on Cybersecurity Partnerships: Cybersecurity partnerships are becoming essential as threats to data integrity rise. The Ministry of Industry and Information Technology launched a program in 2021 to enhance cybersecurity in aviation, fostering collaboration between manufacturers and cybersecurity firms. This focus strengthens the overall security framework.
Investment Opportunities in the China Aircraft Data Protection Market
Investors looking at the China Aircraft Data Protection Market should consider the following areas.
- $1 trillion aerospace market by 2035: With China's aerospace industry projected to reach a market size of $1 trillion by 2035, substantial investment opportunities exist in data protection technologies. Aircraft OEMs are actively seeking advanced solutions to meet regulatory standards, presenting a market entry point.
- Growing manufacturing hub in Beijing-Tianjin-Hebei: The Beijing-Tianjin-Hebei region is emerging as a key manufacturing hub, increasing demand for data protection solutions. Investment in local production facilities can facilitate partnerships with Aircraft OEMs and enhance market presence.
- Rising passenger numbers driving data protection needs: As China's air traffic is projected to reach 1 billion passengers by 2035, the need for effective data protection solutions will increase. Suppliers can target Commercial Airlines to provide tailored data protection technologies.
- Emerging demand for real-time data solutions: The shift towards real-time data processing creates a demand for innovative data protection solutions. Cybersecurity Integrators can capitalise on this trend by offering cutting-edge technologies to improve operational efficiency.
Government Initiatives in the China Aircraft Data Protection Market
The 2023 Cybersecurity Law of China introduces stringent regulations for data protection, enhancing the framework established by the National Standard GB/T 20237-2019. This law mandates that all commercial aircraft adhere to specific data protection standards, ensuring compliance across the aviation sector. Producers must invest in technologies that meet these requirements, while buyers benefit from improved security measures that protect sensitive information. The law also emphasises the importance of safeguarding flight data, driving further investments in data protection solutions.
The Ministry of Industry and Information Technology (MIIT) supports the implementation of cybersecurity measures through funding and approval of relevant projects. In 2021, MIIT launched a programme aimed at enhancing cybersecurity in aviation, allocating significant resources to improve data protection capabilities. This initiative facilitates collaboration between manufacturers and cybersecurity firms, ensuring that data protection technologies are effectively integrated into aircraft systems. By promoting industry standards and best practices, MIIT plays an important role in advancing data protection in the aviation sector.
Future Insight of the China Aircraft Data Protection Market
The China Aircraft Data Protection market will undergo significant changes by 2032, driven by the adoption of advanced encryption technologies and robust storage solutions. The Ministry of Industry and Information Technology's 2021 program to strengthen cybersecurity in aviation will elevate industry standards. With the aerospace industry projected to reach a market size of $1 trillion by 2035, innovation in data protection methods will accelerate. The expansion of the airport network to 400 will heighten the need for effective data security measures, enabling buyers and suppliers to meet the demands of a rapidly evolving aviation landscape.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Protection Type – Encrypted Storage Dominated, Fireproof Data Boxes Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, in 2025, Encrypted Storage led the protection type split with a 38% share. Encrypted storage holds the largest market share as it is essential for securing flight data, which is vital for compliance with the Civil Aviation Administration of China's regulations. This segment's significance is highlighted by its widespread adoption across commercial aircraft in the country. Fireproof Data Boxes are set to record the highest CAGR in this split, 11.0% over 2026–2032. Fireproof data boxes are rapidly gaining popularity due to the increasing focus on physical data protection in response to rising cybersecurity threats. The emphasis placed on such measures by the 2022 National Defense Cybersecurity Strategy is driving their adoption in the aviation sector. Suppliers must enhance their encrypted storage offerings to align with regulatory standards, while buyers should consider investing in fireproof data boxes for comprehensive data protection.
By Data Format – Solid-State Drives Dominated, Crash Survivable Expected to Grow Fastest
With a 37% revenue share in 2025, Solid-State Drives was the largest data format category. Solid-state drives dominate the market share as they offer reliable and fast data storage, which is crucial for the efficient functioning of aircraft systems. Their extensive application among manufacturers has created a solid installed base within the aviation industry. Crash Survivable is projected to grow fastest, at a CAGR of 12.1% during 2026–2032. Crash survivable formats are experiencing rapid growth because they are specifically designed to withstand extreme conditions, making them essential for protecting critical data during emergencies. With air traffic in China projected to reach 1 billion passengers by 2035, the demand for these resilient solutions is expected to surge. Suppliers should focus on advancing crash survivable technologies, while buyers must prioritise these formats to enhance their data security measures.
By Distribution Channel – Cybersecurity Integrators Dominated, Online Aerospace Suppliers Expected to Grow Fastest
The largest distribution channel category in 2025 was Cybersecurity Integrators, with a 47% share of total revenue. Cybersecurity integrators hold the largest market share as they are instrumental in implementing tailored protection solutions for the aviation sector. Their expertise ensures adherence to the stringent data protection regulations mandated by the Chinese government. Over 2026–2032, Online Aerospace Suppliers are expected to post the fastest growth, at a CAGR of 12.4%. Online aerospace suppliers are experiencing the fastest growth due to the shift towards digital procurement, which facilitates easier access to essential data protection components. This trend aligns with the broader push for innovation within the aerospace industry, particularly in key regions like the Shanghai Free Trade Zone. Suppliers must strengthen their online presence to capture increasing demand, while buyers should utilise online platforms for more efficient procurement of data protection solutions.
By End User – Aircraft OEMs Dominated, Commercial Airlines Expected to Grow Fastest
Aircraft OEMs held a 39% share of the China Aircraft Data Protection Market by end user in 2025. Aircraft OEMs command the largest market share as they are the primary users of data protection technologies in manufacturing, ensuring compliance with national standards. Their significant investments in data security demonstrate a commitment to safeguarding sensitive information throughout the production process. The quickest growth will come from Commercial Airlines, forecast to expand at a CAGR of 12.4% between 2026 and 2032. Commercial airlines are witnessing the fastest growth in data protection demand as they increasingly rely on secure operational data to enhance safety and efficiency. With projected growth in air traffic, their need for robust data protection solutions will continue to rise. Suppliers should tailor their offerings to meet the specific needs of commercial airlines, while buyers must align their data protection strategies with operational requirements.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Aircraft Data Protection Market Outlook
- Market Size of China Aircraft Data Protection Market, 2025
- Forecast of China Aircraft Data Protection Market, 2032
- Historical Data and Forecast of China Aircraft Data Protection Revenues & Volume for the Period 2022 - 2032F
- China Aircraft Data Protection Market Trend Evolution
- China Aircraft Data Protection Market Drivers and Challenges
- China Aircraft Data Protection Price Trends
- China Aircraft Data Protection Porter's Five Forces
- China Aircraft Data Protection Industry Life Cycle
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By Protection Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By Encrypted Storage for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By Fireproof Data Boxes for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By In-Flight Data Backup for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By Cloud Data Sync for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By Data Format for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By Solid-State Drives for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By Crash Survivable for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By Real-Time Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By Encrypted Networks for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By Cybersecurity Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By Online Aerospace Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By OEM System Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By Cloud Service Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By Aircraft OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By Commercial Airlines for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By Defense Aircraft Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Data Protection Market Revenues & Volume By MRO and Flight Ops for the Period 2022 - 2032F
- China Aircraft Data Protection Import Export Trade Statistics
- Market Opportunity Assessment By Protection Type
- Market Opportunity Assessment By Data Format
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Aircraft Data Protection Top Companies Market Share
- China Aircraft Data Protection Competitive Benchmarking By Technical and Operational Parameters
- China Aircraft Data Protection Company Profiles
- China Aircraft Data Protection Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Protection Type
- Encrypted Storage
- Fireproof Data Boxes
- In-Flight Data Backup
- Cloud Data Sync
By Data Format
- Solid-State Drives
- Crash Survivable
- Real-Time Systems
- Encrypted Networks
By Distribution Channel
- Cybersecurity Integrators
- Online Aerospace Suppliers
- OEM System Vendors
- Cloud Service Providers
By End User
- Aircraft OEMs
- Commercial Airlines
- Defense Aircraft Units
- MRO and Flight Ops






































