China Aircraft Engine Materials Market Size & Growth Rate
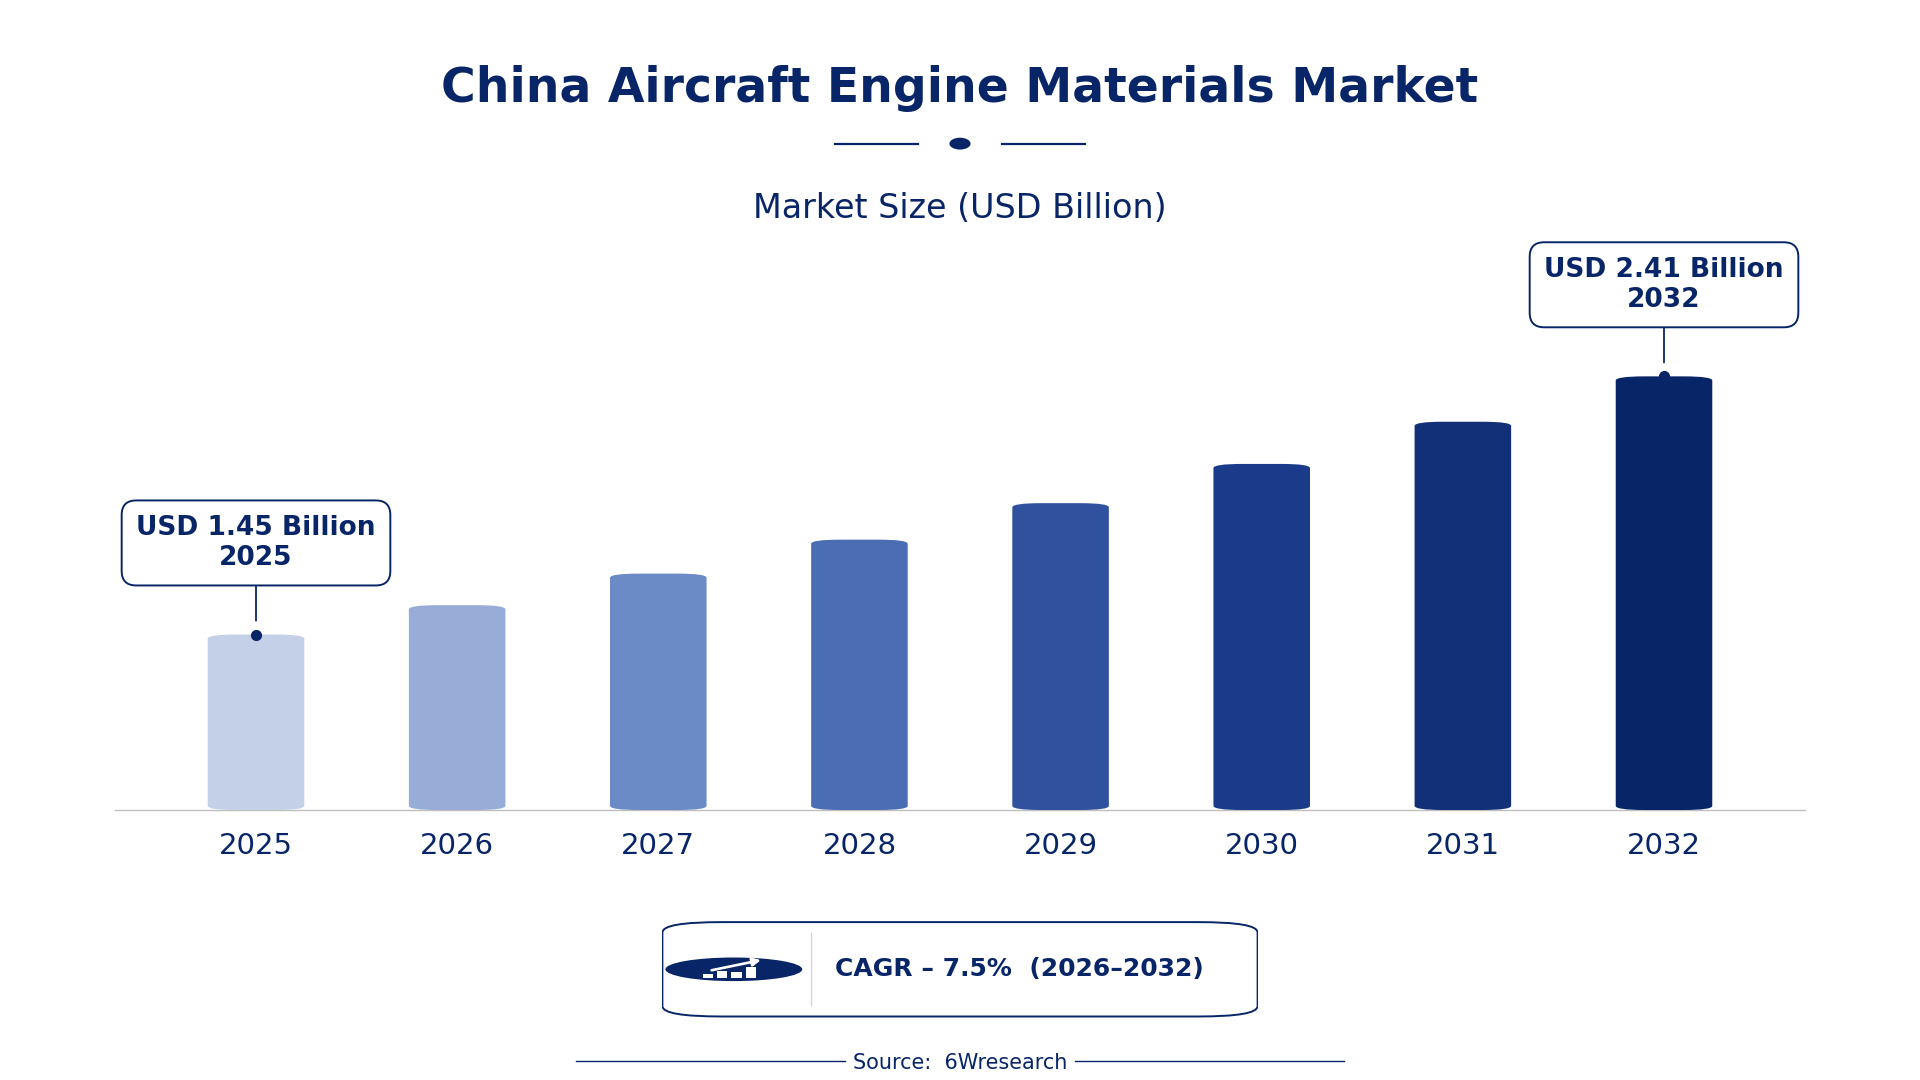
According to 6Wresearch internal database and industry insights, the China Aircraft Engine Materials Market was valued at USD 1.45 billion in 2025 and is projected to reach USD 2.41 billion by 2032, growing at a CAGR of approximately 7.5% during 2026–2032.
China Aircraft Engine Materials Market Highlights
| Report Metric | Details |
| Report Name | China Aircraft Engine Materials Market |
| Market Size 2025 | USD 1.45 billion |
| Market Size 2032 | USD 2.41 billion |
| Absolute Growth 2025–2032 | USD 0.96 billion |
| CAGR 2026–2032 | 7.5% |
| Peak Annual Growth | 9.8% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Material Type, 2025 | Superalloys (38% share) |
| Leading Application Area, 2025 | Turbine Blades (45% share) |
| Leading Distribution Channel, 2025 | Alloy Manufacturers (36% share) |
| Leading End User, 2025 | Aircraft Engine OEMs (42% share) |
| Fastest-Growing Material Type | Ceramic Matrix Composites (9.9% CAGR) |
| Fastest-Growing Application Area | Combustion Chamber (10.2% CAGR) |
| Fastest-Growing Distribution Channel | Industrial Suppliers (9.2% CAGR) |
| Fastest-Growing End User | Jet Engine Designers (9.8% CAGR) |
| Growing Sector | Combustion Chamber |
| Key End Users | Turbine Blades, Combustion Chamber, Fan & Compressor, Bearings & Shafts |
China Aircraft Engine Materials Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
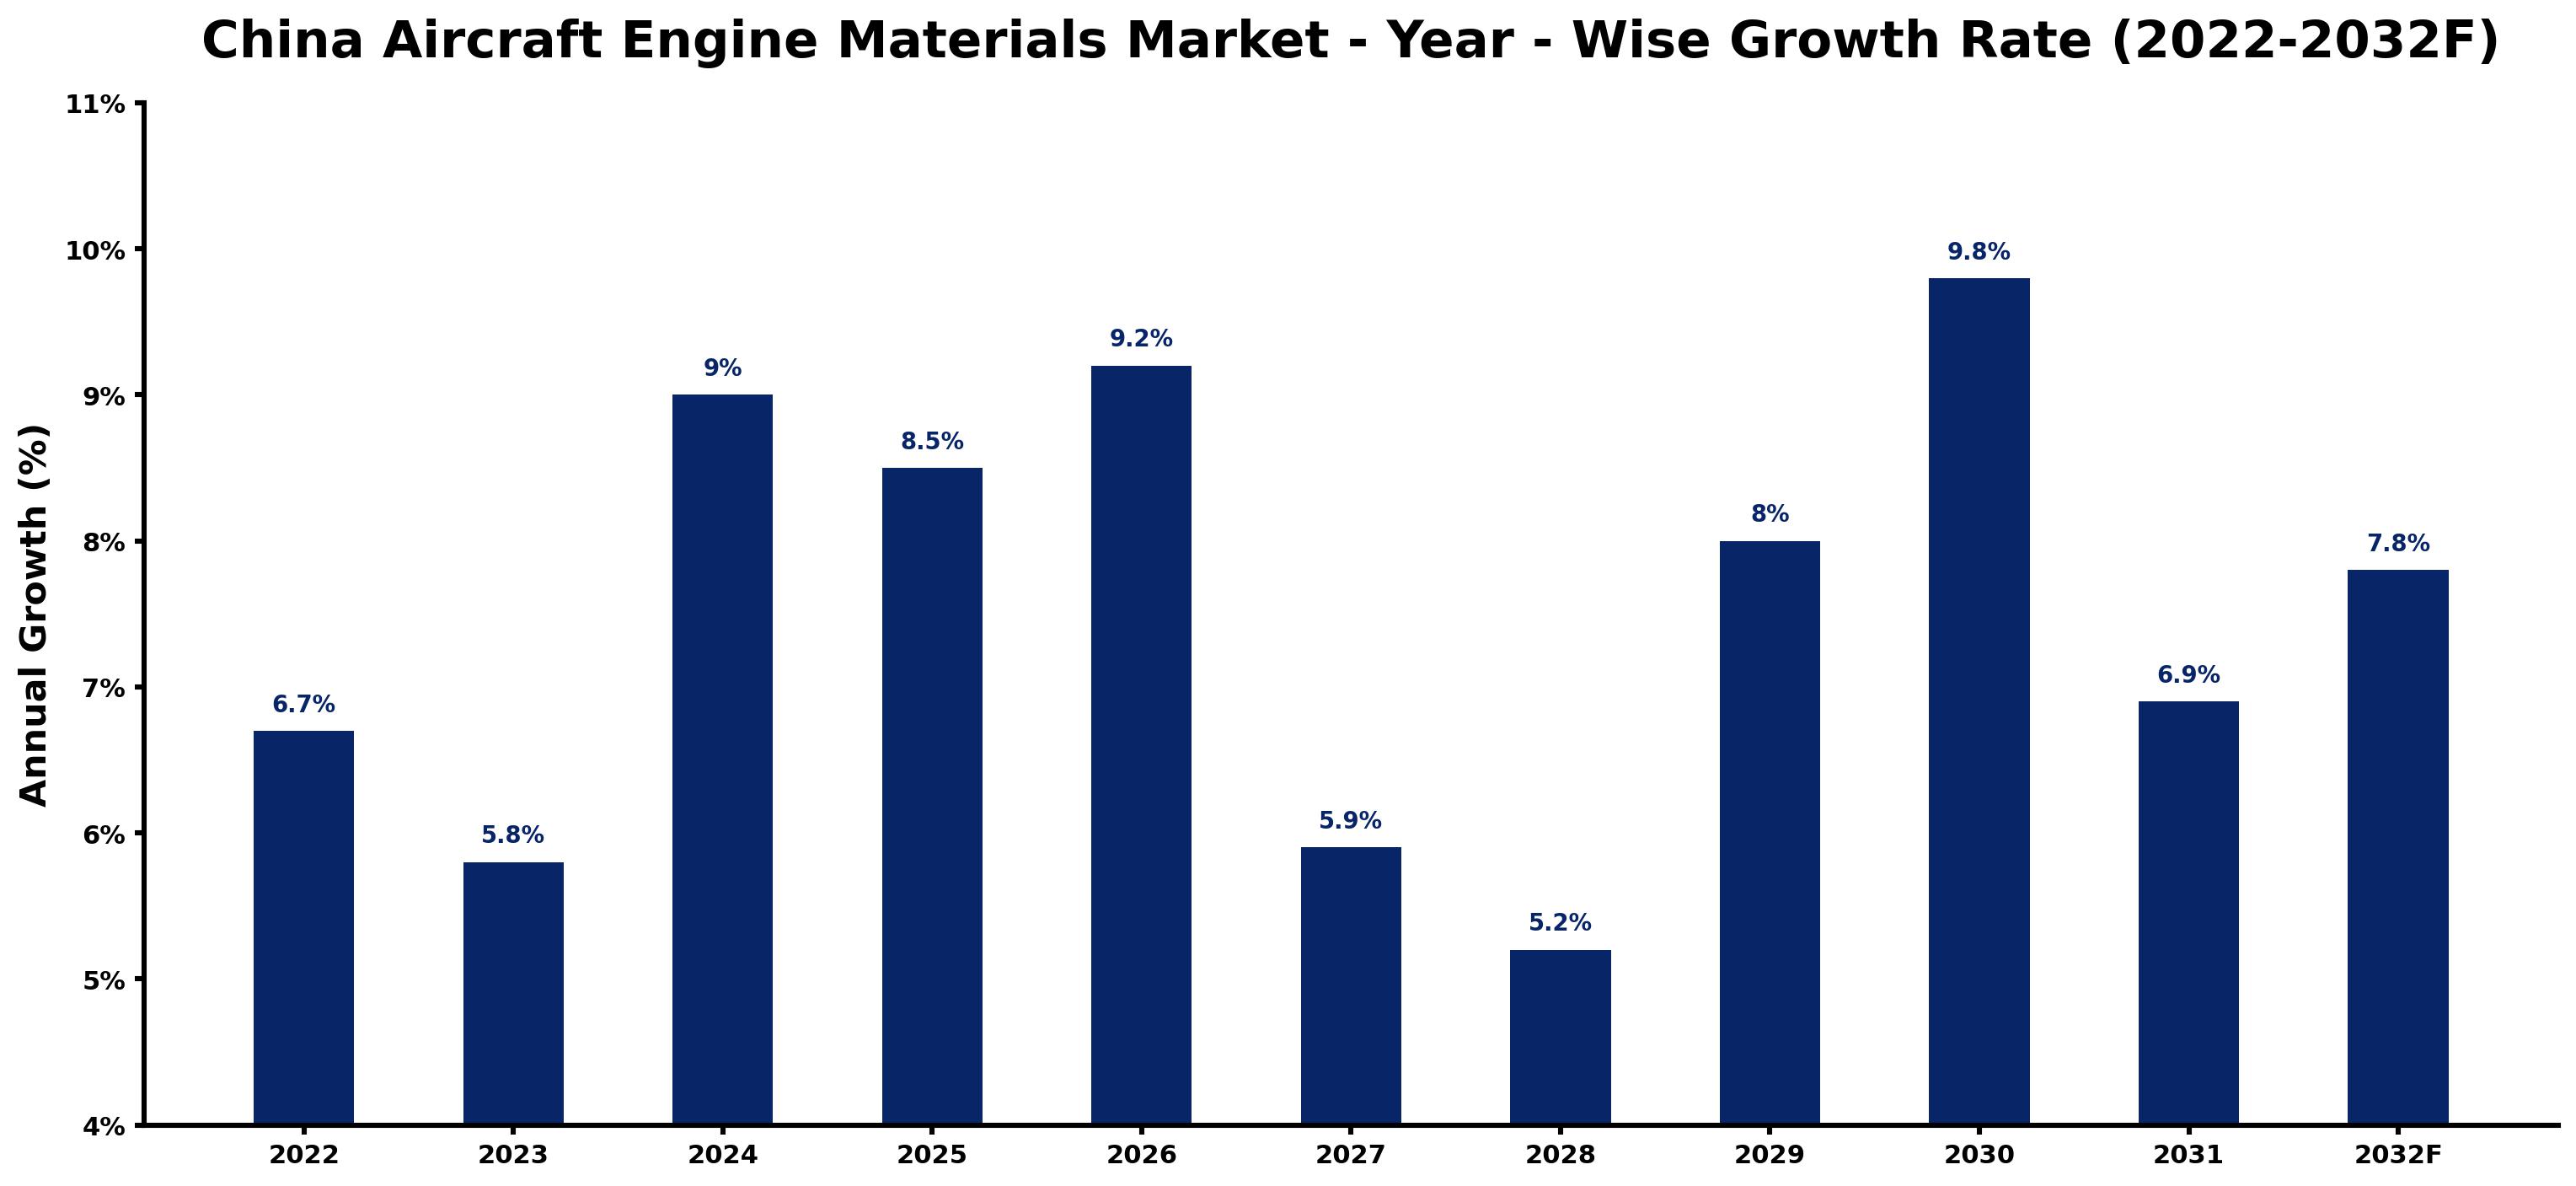
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.7 | The market experienced steady growth due to strong demand from the aviation sector. |
| 2023 | 5.8 | Demand growth slowed as the aerospace industry faced supply chain disruptions. |
| 2024 | 9.0 | Increased production of commercial aircraft spurred higher demand for materials. |
| 2025 | 8.5 | A rise in military aircraft production contributed to market expansion. |
| 2026 | 9.2 | The introduction of advanced alloys is expected to boost material requirements in engines. |
| 2027 | 5.9 | Demand growth is projected to moderate as manufacturers adjust to market conditions. |
| 2028 | 5.2 | Technological advancements in material science will lead to new applications. |
| 2029 | 8.0 | A surge in aircraft orders is expected to revitalise the materials market. |
| 2030 | 9.8 | The market is projected to peak as demand for high-performance materials surges. |
| 2031 | 6.9 | Growth is expected to slow as the market stabilises after peak demand. |
| 2032 | 7.8 | Continued investment in aerospace R&D is projected to support ongoing material needs. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Aircraft Engine Materials Market Synopsis
Aircraft Engine Materials in China include advanced alloys and composites designed for high-performance jet engines. These materials are essential for components like turbine blades and combustion chambers, manufactured through processes such as casting and forging. The China Aircraft Engine Materials Market is growing due to increasing demand from both commercial and military aviation sectors, driven by substantial investments in aerospace R&D and a projected requirement for new aircraft by 2041.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased domestic aircraft production drives demand for high-performance materials. | Driver | High | Turbine Blades |
| Growing military aviation needs expand the market for specialized materials. | Driver | High | Superalloys |
| Investment in aerospace innovation creates opportunities for advanced materials suppliers. | Opportunity | High | Ceramic Matrix Composites |
| The need for lightweight materials in engines opens new markets. | Opportunity | High | Titanium Alloys |
| High production costs limit the growth of certain material types. | Restraint | Medium | High-Temp Steel |
| Regulatory compliance can delay material approvals for manufacturers. | Restraint | Medium | Superalloys |
| Supply chain disruptions affect timely delivery of materials. | Challenge | High | Alloy Manufacturers |
| Technological challenges in material development hinder innovation. | Challenge | Medium | Ceramic Matrix Composites |
Evaluation of Drivers in China Aircraft Engine Materials Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Strong demand from commercial aircraft production increases material needs. | Turbine Blades | In 2022, over 300 commercial aircraft were produced, driving demand for high-performance materials. |
| Military aircraft production boosts requirements for specialized materials. | Superalloys | China's defense budget for aerospace technology increased by 5% in 2023, raising material demand. |
| Technological advancements in aerospace R&D create new material applications. | Ceramic Matrix Composites | Aerospace R&D investment reached approximately $15 billion in 2022, promoting innovation. |
| Quality standards ensure safety in material production. | Titanium Alloys | National standards for aircraft materials are defined by GB/T 24500-2009, guiding manufacturers. |
| Partnerships with international organizations facilitate material technology exchange. | High-Temp Steel | Collaborations with global aerospace entities enhance knowledge transfer and innovation. |
Growth across the Aircraft Engine Materials market in China is anchored in rising demand from the commercial aviation sector, military aircraft production, and technological advancements. In 2022, over 300 commercial aircraft were produced, increasing the need for high-performance materials. The defense budget for aerospace technology increased by 5% in 2023, further driving demand for specialized materials. Aerospace R&D investment reached approximately $15 billion in 2022, promoting innovation in material applications. National standards defined by GB/T 24500-2009 ensure quality and safety, guiding manufacturers in their production processes.
Evaluation of Restraints in China Aircraft Engine Materials Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Stringent regulations slow down material approvals. | Superalloys | The Civil Aviation Administration of China requires compliance with national standards, delaying production timelines for manufacturers by up to six months. |
| Competition from international suppliers creates pricing pressures. | Turbine Blades | Local producers struggle to match the advanced technology and lower costs offered abroad, impacting profit margins for domestic manufacturers. |
| Supply chain disruptions increase costs for producers. | Ceramic Matrix Composites | Challenges in sourcing raw materials can lead to increased production costs, forcing manufacturers to raise prices for buyers. |
| Delayed deliveries of critical components affect production schedules. | Titanium Alloys | Buyers in the aviation sector face challenges in securing timely deliveries, which can increase operational costs. |
| Limited domestic innovation in material technology hampers growth. | High-Temp Steel | A lack of investment in R&D compared to international standards restricts the development of advanced materials. |
China Aircraft Engine Materials Market Challenges
The China Aircraft Engine Materials market encounters several practical issues, starting with stringent regulations that can delay material approvals. Adherence to national standards, enforced by the Civil Aviation Administration of China, can extend production timelines for manufacturers by as much as six months. Additionally, local producers face stiff competition from international suppliers, which pressures pricing and diminishes profit margins for domestic manufacturers. Disruptions in sourcing raw materials can also inflate costs for producers, leading to higher prices for buyers. Lastly, buyers in the aviation sector often experience challenges in securing timely deliveries of critical components, potentially delaying aircraft production schedules and raising operational costs.
Trends in the China Aircraft Engine Materials Market
Buyers and suppliers in the China Aircraft Engine Materials Market are adjusting to the following trends.
- Shift Towards Advanced Alloys: The Shanghai Free-Trade Zone encourages innovation in aerospace materials, facilitating a transition towards advanced alloys for improved performance. This initiative is expected to elevate material quality and efficiency, boosting competitiveness.
- Increased Demand from Military Aviation: Defence Aircraft Builders are increasingly pursuing specialised materials due to a 5% rise in China's defence budget for aerospace technology in 2023. This trend is propelling innovation and material development throughout the sector.
- Emergence of New Material Standards: The introduction of GB/T 24500-2009 has established new benchmarks for aircraft materials, ensuring higher quality and safety. This change is likely to significantly influence production practices, benefiting both manufacturers and buyers.
- Focus on Lightweight Materials: Jet Engine Designers are prioritising lightweight materials like Ceramic Matrix Composites, which excel in high-performance applications. This trend is driven by the demand for fuel efficiency in aviation, prompting innovation.
Investment Opportunities in the China Aircraft Engine Materials Market
Investors looking at the China Aircraft Engine Materials Market should consider the following areas.
- Investment in R&D Facilities: The Beijing-Tianjin-Hebei region is set for investment in R&D facilities, with a projected aerospace market size of $1 trillion by 2035. This presents opportunities for suppliers to collaborate with local manufacturers and enhance innovation.
- Supply of Advanced Composites: With a growing demand for lightweight and heat-resistant materials, suppliers should focus on providing advanced composites. The military aviation sector is a key buyer group that requires these materials for new aircraft.
- Expansion of Production Capabilities: The need for new aircraft by 2041 creates opportunities for expanding production capabilities in the aerospace sector. Collaborating with Aircraft Engine OEMs can facilitate market entry and enhance production efficiency.
- Development of Innovative Materials: The ongoing investment in aerospace R&D, with approximately $15 billion in 2022, opens avenues for developing new materials. Suppliers can engage with research institutions to drive advancements and meet market demands.
Government Initiatives in the China Aircraft Engine Materials Market
The Civil Aviation Administration of China oversees regulations that impact the Aircraft Engine Materials market. The national standard GB/T 24500-2009, established in 2009, ensures the quality and safety of aircraft materials. Compliance with these standards is essential for manufacturers, as it affects their ability to produce and market materials effectively. Additionally, the Ministry of Industry and Information Technology supports various development programs aimed at improving the aerospace sector, including funding for R&D initiatives and technology upgrades to enhance material quality.
Aircraft Engine OEMs benefit from the support provided by the Ministry of Industry and Information Technology through funding for development programs. These initiatives aim to improve the quality and availability of aircraft engine materials, ensuring that manufacturers can meet the growing demands of the aviation sector. The National Natural Science Foundation of China also funds aerospace material research projects, fostering innovation and collaboration between research institutions and manufacturers to enhance material development.
Future Insight of the China Aircraft Engine Materials Market
By 2032, buyers and suppliers in the China Aircraft Engine Materials market will experience notable advancements due to increased R&D investments and strengthened international collaborations. China's aerospace R&D investment is projected to reach approximately $20 billion by 2035, leading to improved material solutions. The establishment of the Shanghai Free-Trade Zone will encourage material innovation, while partnerships with international aerospace organisations will facilitate valuable technology exchanges. Support from the Ministry of Industry and Information Technology for development programmes is expected to improve the quality and availability of aircraft engine materials.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Material Type – Superalloys Dominated, Ceramic Matrix Composites Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, Superalloys accounted for a 38% market share by material type in 2025. Superalloys dominate the China Aircraft Engine Materials Market due to their essential role in turbine blades, which are crucial for optimal engine performance. Their extensive application in both commercial and military aviation further solidifies their leading market share. The quickest growth will come from Ceramic Matrix Composites, forecast to expand at a CAGR of 9.9% between 2026 and 2032. Ceramic Matrix Composites are rapidly gaining traction as they are ideal for lightweight and heat-resistant applications in engines, catering to the increasing demand for fuel-efficient aircraft. As the aviation sector expands, the need for these advanced materials will continue to rise. Suppliers should focus on developing Ceramic Matrix Composites to capitalise on the growing demand in the aviation industry.
By Application Area – Turbine Blades Dominated, Combustion Chamber Expected to Grow Fastest
In 2025, Turbine Blades led the application area split with a 45% share. Turbine Blades hold the largest share in the market as they are critical components made from advanced materials that enhance engine efficiency. The robust production of commercial aircraft in China significantly drives the demand for these materials, reinforcing their leading position. Combustion Chamber is projected to grow fastest, at a CAGR of 10.2% during 2026–2032. The Combustion Chamber segment is witnessing rapid growth due to the need for materials that can withstand extreme conditions, reflecting the industry's focus on improving engine performance. As the aviation market grows, the demand for these materials will steadily increase. Buyers should prioritise sourcing high-quality materials for combustion chambers to ensure optimal engine performance and reliability.
By Distribution Channel – Alloy Manufacturers Dominated, Industrial Suppliers Expected to Grow Fastest
The largest distribution channel category in 2025 was Alloy Manufacturers, with a 36% share of total revenue. Alloy Manufacturers lead the market share as they produce essential materials for aircraft engines, directly addressing the needs of aircraft engine OEMs. Their established presence in the industry ensures a steady supply of high-performance materials, reinforcing their market position. Industrial Suppliers are set to record the highest CAGR in this split, 9.2% over 2026–2032. Industrial Suppliers are experiencing the fastest growth as they provide a diverse range of materials, responding to the increasing demand from various sectors within the aviation industry. This trend indicates a shift towards more diversified sourcing strategies among manufacturers. Suppliers should strengthen partnerships with industrial suppliers to enhance distribution networks and meet the rising demand for aircraft engine materials.
By End User – Aircraft Engine OEMs Dominated, Jet Engine Designers Expected to Grow Fastest
With a 42% revenue share in 2025, Aircraft Engine OEMs was the largest end user category. Aircraft Engine OEMs represent the largest share in the market as the primary users of aircraft engine materials for production. Their continuous investments in research and development and production capacity drive significant demand for advanced materials, maintaining their leadership. Over 2026–2032, Jet Engine Designers are expected to post the fastest growth, at a CAGR of 9.8%. Jet Engine Designers are the fastest-growing segment as they increasingly utilise advanced materials in their designs to improve engine efficiency and performance. This trend highlights a growing emphasis on innovation within the aviation sector. Suppliers must engage with jet engine designers to align their offerings with the latest advancements in aircraft engine technology.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Aircraft Engine Materials Market Outlook
- Market Size of China Aircraft Engine Materials Market, 2025
- Forecast of China Aircraft Engine Materials Market, 2032
- Historical Data and Forecast of China Aircraft Engine Materials Revenues & Volume for the Period 2022 - 2032F
- China Aircraft Engine Materials Market Trend Evolution
- China Aircraft Engine Materials Market Drivers and Challenges
- China Aircraft Engine Materials Price Trends
- China Aircraft Engine Materials Porter's Five Forces
- China Aircraft Engine Materials Industry Life Cycle
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Superalloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Ceramic Matrix Composites for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Titanium Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By High-Temp Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Turbine Blades for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Combustion Chamber for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Fan & Compressor for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Bearings & Shafts for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Alloy Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Industrial Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Online Metals Retailers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Forging Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Aircraft Engine OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Jet Engine Designers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Business Jet OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Materials Market Revenues & Volume By Defense Aircraft Builders for the Period 2022 - 2032F
- China Aircraft Engine Materials Import Export Trade Statistics
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Aircraft Engine Materials Top Companies Market Share
- China Aircraft Engine Materials Competitive Benchmarking By Technical and Operational Parameters
- China Aircraft Engine Materials Company Profiles
- China Aircraft Engine Materials Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Material Type
- Superalloys
- Ceramic Matrix Composites
- Titanium Alloys
- High-Temp Steel
By Application Area
- Turbine Blades
- Combustion Chamber
- Fan & Compressor
- Bearings & Shafts
By Distribution Channel
- Alloy Manufacturers
- Industrial Suppliers
- Online Metals Retailers
- Forging Suppliers
By End User
- Aircraft Engine OEMs
- Jet Engine Designers
- Business Jet OEMs
- Defense Aircraft Builders






































