China Aircraft Engine Overhaul Market Size & Growth Rate
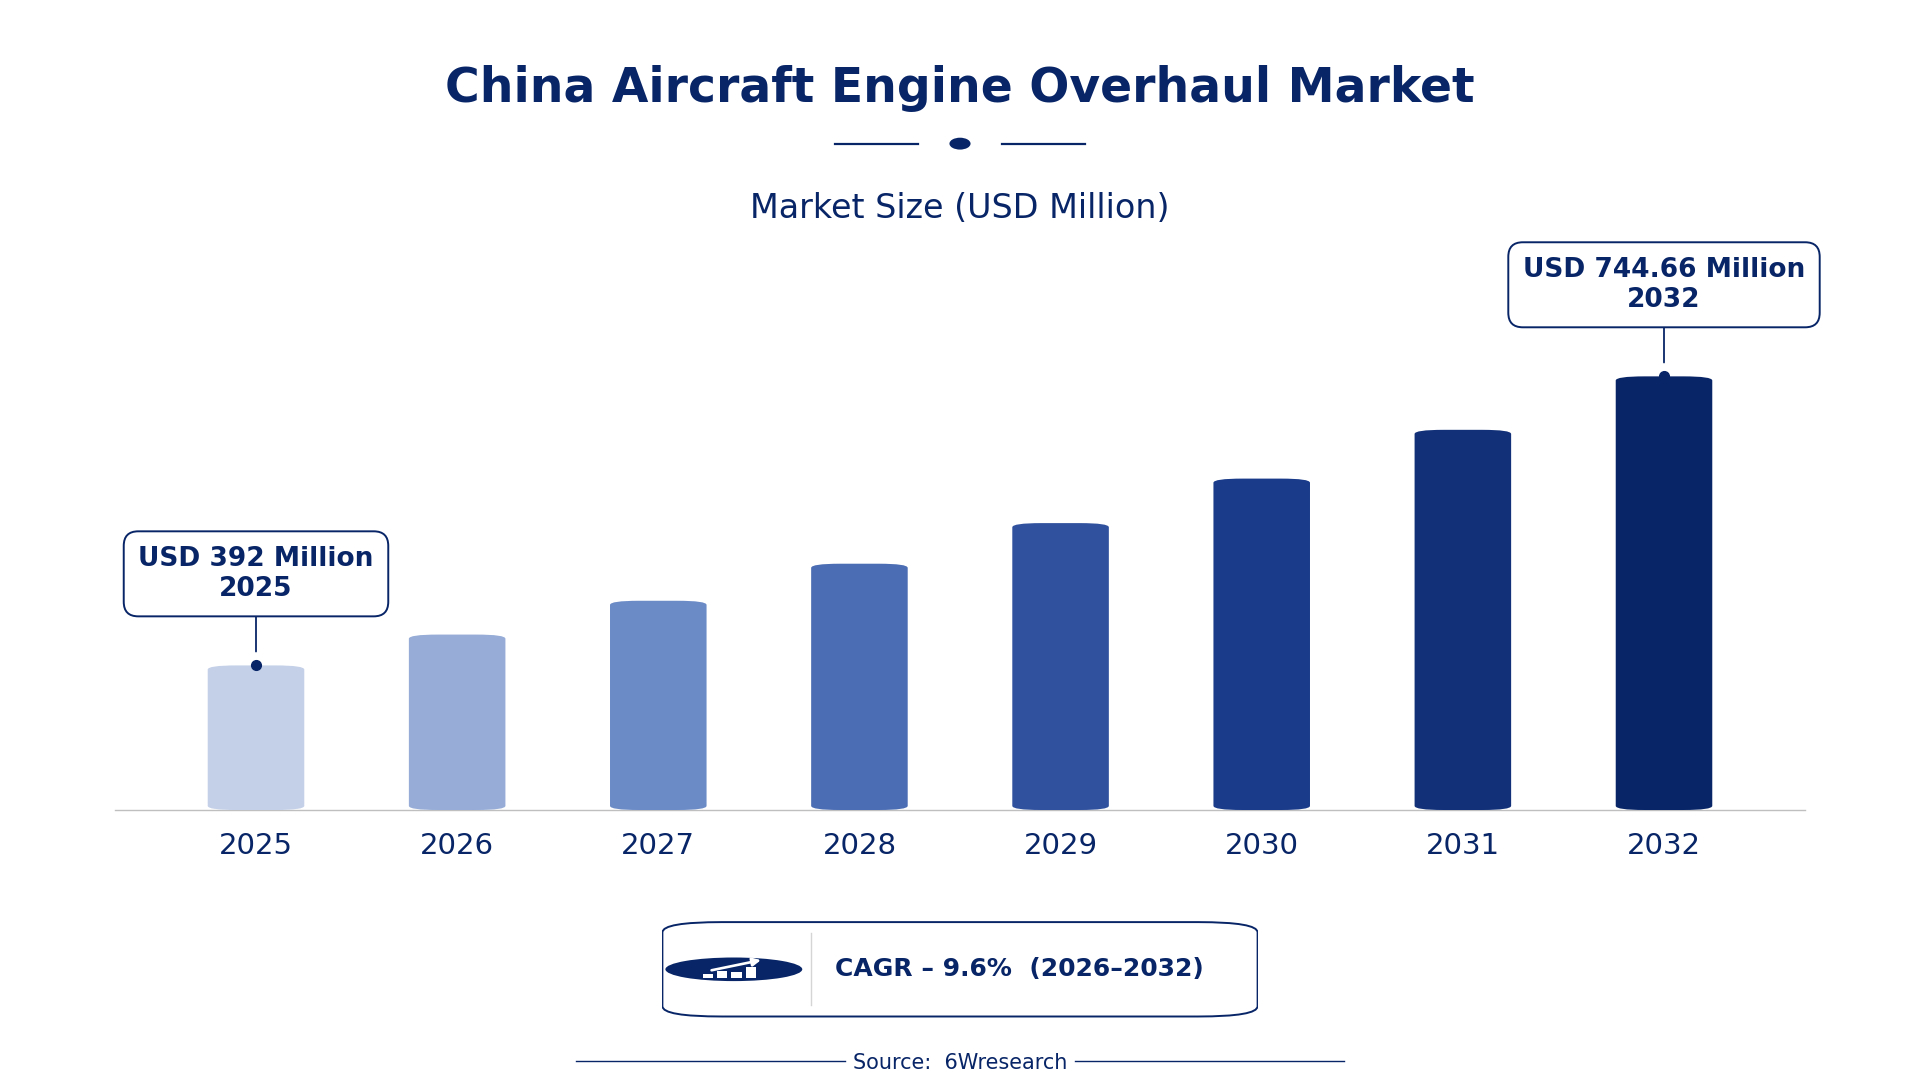
According to 6Wresearch internal database and industry insights, the China Aircraft Engine Overhaul Market was valued at USD 392.0 million in 2025 and is projected to reach USD 744.66 million by 2032, growing at a CAGR of approximately 9.6% during 2026–2032.
China Aircraft Engine Overhaul Market Highlights
| Report Metric | Details |
| Report Name | China Aircraft Engine Overhaul Market |
| Market Size 2025 | USD 392.0 million |
| Market Size 2032 | USD 744.66 million |
| Absolute Growth 2025–2032 | USD 352.66 million |
| CAGR 2026–2032 | 9.6% |
| Peak Annual Growth | 12.2% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Overhaul Type, 2025 | Hot Section Overhaul (51% share) |
| Leading Component Area, 2025 | Turbine Components (45% share) |
| Leading Distribution Channel, 2025 | Certified MROs (37% share) |
| Leading End User, 2025 | Commercial Jet Operators (45% share) |
| Fastest-Growing Overhaul Type | Cold Section Overhaul (11.6% CAGR) |
| Fastest-Growing Component Area | Compressor Modules (11.3% CAGR) |
| Fastest-Growing Distribution Channel | OEM Partnerships (11.0% CAGR) |
| Fastest-Growing End User | Business Aviation Services (12.0% CAGR) |
| Growing Sector | business aviation services |
| Key End Users | commercial jet operators, air cargo fleet operators, government aviation units, business aviation services |
China Aircraft Engine Overhaul Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
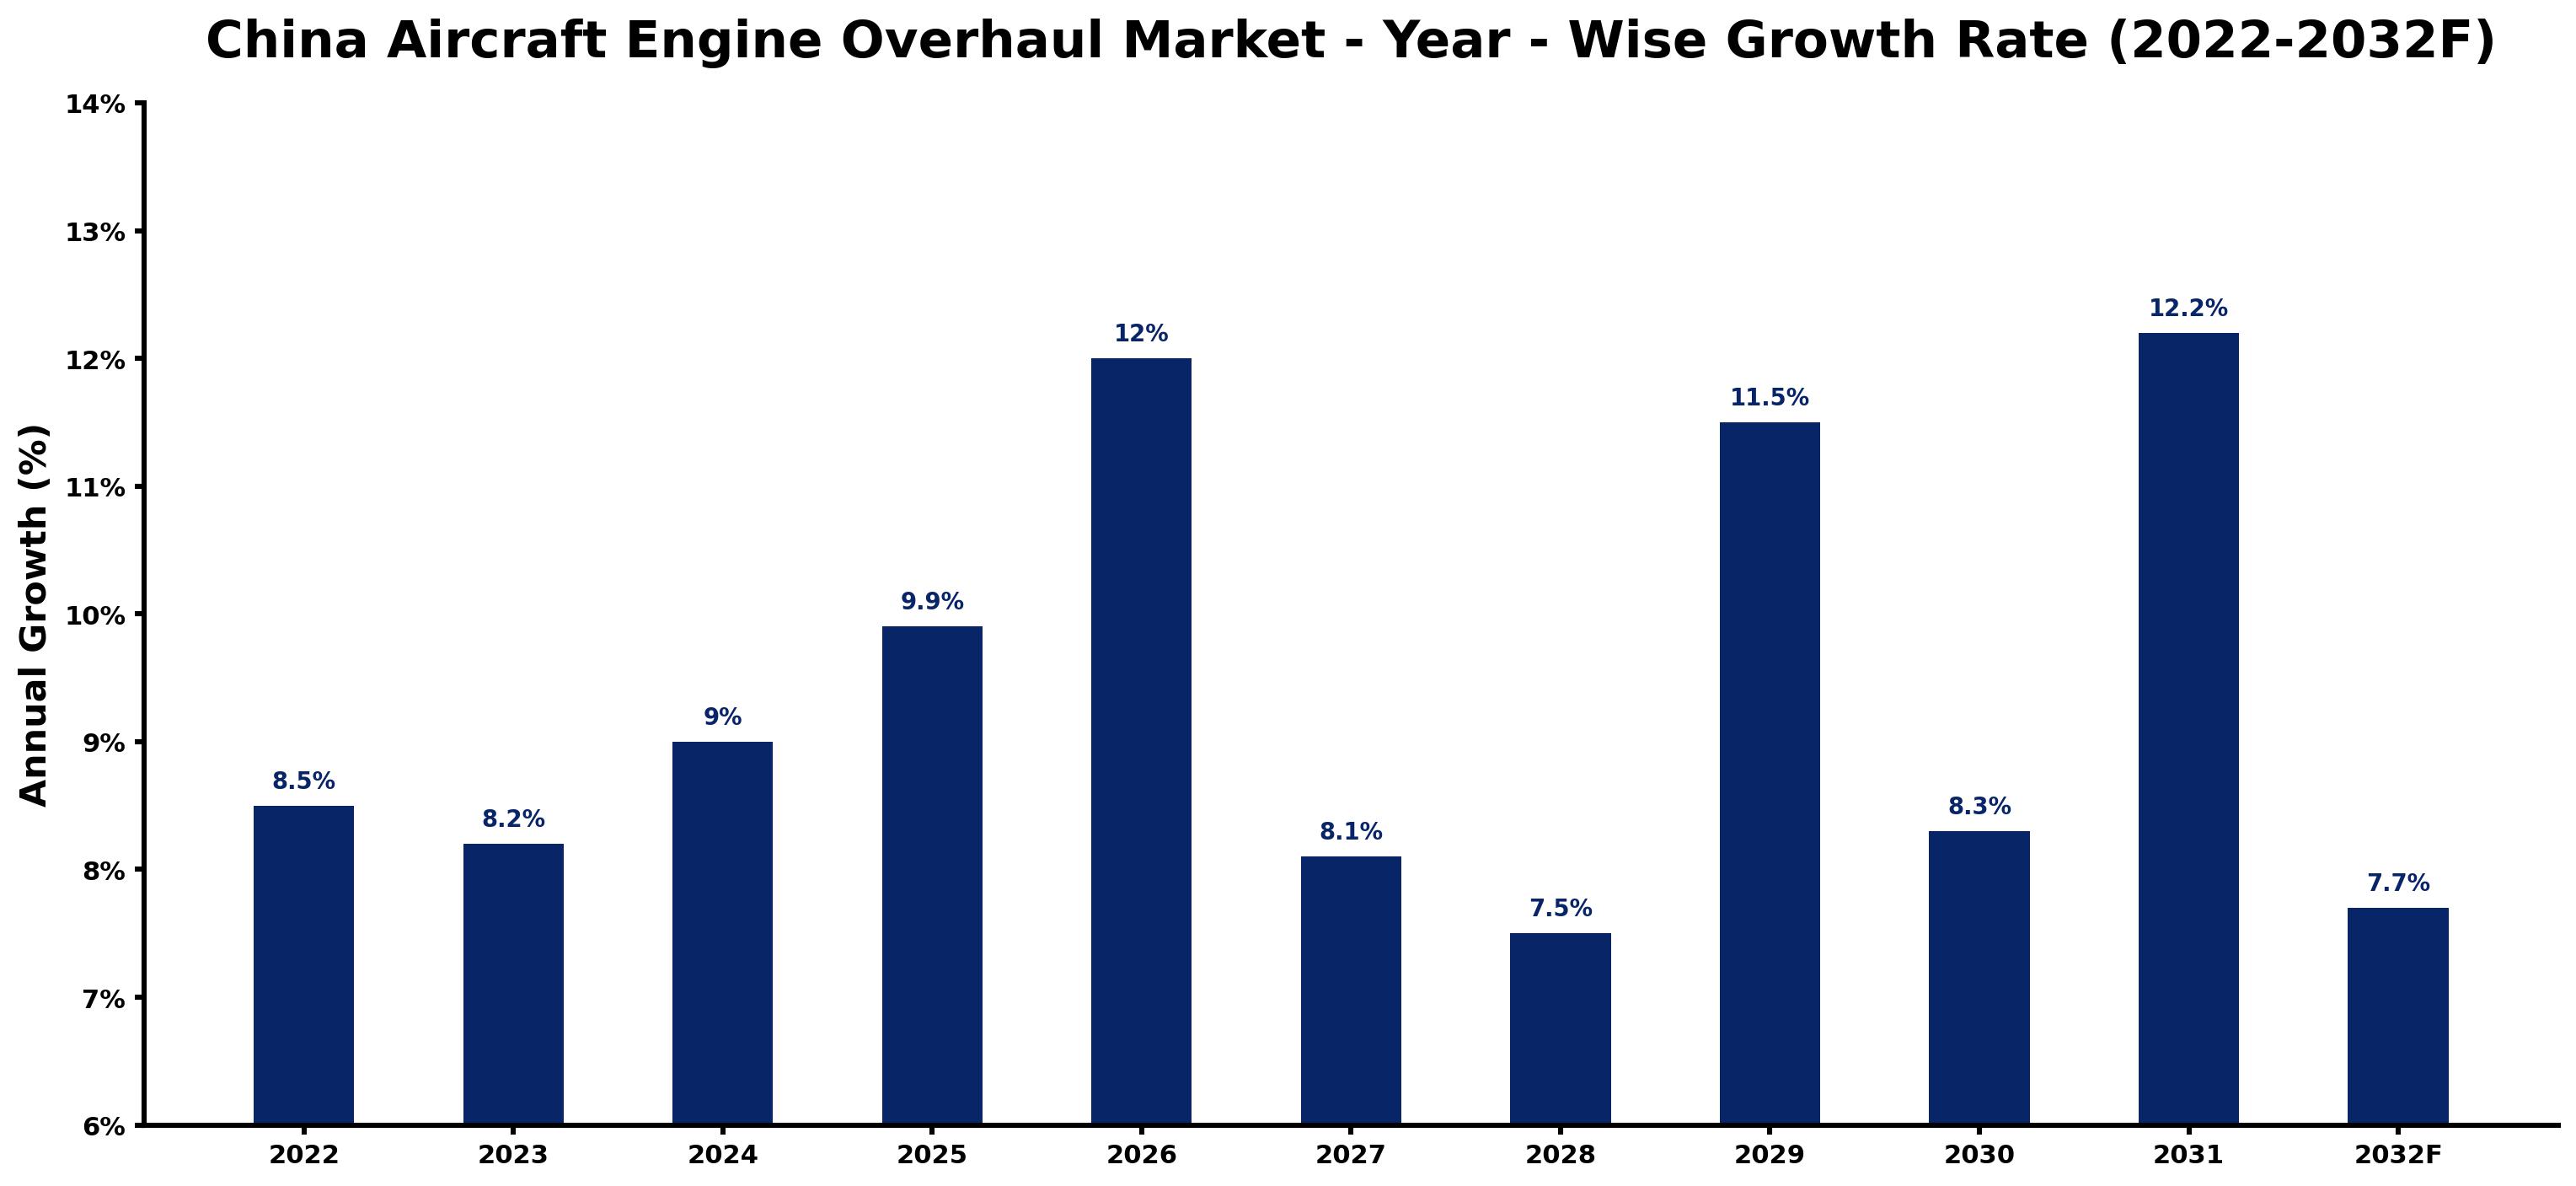
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 8.5 | The aviation sector showed strong activity with over 3,000 commercial aircraft needing overhauls. |
| 2023 | 8.2 | Demand for overhaul services slowed slightly as operators adjusted to maintenance schedules. |
| 2024 | 9.0 | Increased flight hours led to a faster demand for engine overhauls among operators. |
| 2025 | 9.9 | The peak in growth was driven by the rising number of aircraft requiring regular maintenance. |
| 2026 | 12.0 | A surge in air travel is expected to boost demand for engine overhaul services significantly. |
| 2027 | 8.1 | Demand growth slows as the market adjusts to the influx of new aircraft entering service. |
| 2028 | 7.5 | The market continues to experience a slowdown as operators focus on efficiency improvements. |
| 2029 | 11.5 | Renewed demand arises as older aircraft fleets require more extensive maintenance services. |
| 2030 | 8.3 | A slight slowdown occurs as the market stabilises after a period of rapid growth. |
| 2031 | 12.2 | The peak growth rate reflects the increasing need for comprehensive engine overhauls. |
| 2032 | 7.7 | Demand growth slows as the market matures and operators optimise maintenance strategies. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Aircraft Engine Overhaul Market Synopsis
Aircraft Engine Overhaul in China involves thorough maintenance and repair of aircraft engines to ensure safety and efficiency. This process includes both hot section and cold section overhauls, crucial for extending engine life and optimising performance. The China Aircraft Engine Overhaul Market is expanding due to the increasing volume of air travel, with forecasts suggesting the aviation sector will accommodate 1.4 billion passengers by 2035. The growing demand from commercial jet operators and government aviation units further propels this expansion. The Shanghai region stands out as a major hub, supported by numerous certified MRO facilities.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising air traffic and fleet age create a strong demand for regular engine maintenance. | Driver | High | Full Engine Overhaul |
| The growth of the air cargo market necessitates reliable engine performance for cargo fleets. | Driver | High | Air Cargo Fleet Operators |
| Investment in OEM partnerships is increasing to enhance parts availability and service quality. | Opportunity | Medium | OEM Partnerships |
| The expansion of business aviation services presents new avenues for maintenance providers. | Opportunity | Medium | Business Aviation Services |
| High costs associated with maintenance can deter operators from timely overhauls. | Restraint | High | Commercial Jet Operators |
| Regulatory compliance requirements can complicate the overhaul process for operators. | Restraint | Medium | Government Aviation Units |
| The Aircraft Engine Overhaul Market in China faces challenges due to a shortage of skilled technicians. | Challenge | High | Certified MROs |
| Technological advancements in engine design may outpace current overhaul capabilities. | Challenge | Medium | Engine Repair Contractors |
Evaluation of Drivers in China Aircraft Engine Overhaul Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased air travel leads to a higher number of flight hours, necessitating more frequent overhauls. | Commercial Jet Operators | In 2022, over 3,000 registered commercial aircraft required regular engine overhauls. |
| The average lifespan of commercial aircraft engines is around 20 years, driving demand for overhauls. | Full Engine Overhaul | Regular overhauls are essential to ensure compliance with aviation safety regulations. |
| The growth of the air cargo market, projected to rise by 10% annually, boosts maintenance needs. | Air Cargo Fleet Operators | Increased cargo operations require reliable engine performance and timely maintenance. |
| The Shanghai region's status as a maintenance hub encourages investment in overhaul services. | Certified MROs | Several certified MRO facilities are located in Shanghai, increasing service availability. |
| Government aviation units require stringent maintenance protocols for safety compliance. | Government Aviation Units | Funding from the National Defense Authorization Act supports maintenance and upgrades. |
Market growth for Aircraft Engine Overhaul in China is underpinned by rising air traffic, fleet age and increasing demand from commercial operators. The air cargo market is projected to grow by 10% annually, driving further demand for reliable engine performance. The Shanghai region serves as a key hub, with several certified MRO facilities increasing service availability.
Evaluation of Restraints in China Aircraft Engine Overhaul Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High maintenance costs can deter timely overhauls, impacting operational efficiency. | Commercial Jet Operators | Operators may delay necessary overhauls due to budget constraints, risking safety compliance. |
| Regulatory compliance can complicate the overhaul process, leading to delays. | Government Aviation Units | Strict regulations require thorough inspections and documentation, extending turnaround times. |
| A shortage of skilled technicians limits the capacity of MRO facilities to meet demand. | Certified MROs | The lack of qualified personnel can lead to longer wait times for overhaul services. |
| Technological advancements may outpace current overhaul capabilities, creating service gaps. | Engine Repair Contractors | Newer engine designs may require specialized knowledge and equipment not widely available. |
| Market saturation in certain regions can lead to increased competition and pricing pressure. | OEM Partnerships | As more players enter the market, profit margins may decline, affecting service quality. |
China Aircraft Engine Overhaul Market Challenges
The Aircraft Engine Overhaul market in China encounters considerable cost pressures for airlines, with each overhaul costing around 1 million RMB, which strains operators managing older fleets. Intense competition among maintenance, repair, and overhaul facilities leads to price reductions that may compromise service quality and safety for airlines. Supply chain disruptions arise from dependence on specific components, potentially causing aircraft downtime of up to 30%, which adversely affects operational efficiency for operators. Compliance with CAAC regulations incurs additional costs for MRO providers, limiting their competitive edge in the market.
Trends in the China Aircraft Engine Overhaul Market
Below mentioned are some of the trends shaping the China Aircraft Engine Overhaul Market growth.
- Shift in Demand Towards Business Aviation Services: Business aviation services are experiencing a surge in demand as more private operators seek maintenance solutions. In 2022, this segment grew by 12%, reflecting a shift in customer preferences for personalised service.
- Transition from Traditional MROs to OEM Partnerships: OEM partnerships are becoming more prevalent in the overhaul market, with a growth rate of 11% projected through 2032. This shift allows operators to access original parts and expertise more efficiently.
- Emergence of Online Maintenance Vendors: Online maintenance vendors are gaining traction, with a 5% market share in 2023. This trend reflects a growing preference for digital solutions in parts procurement and service scheduling.
- Growth of the Shanghai Maintenance Hub: The Shanghai region is solidifying its position as a key maintenance hub, with over 15 certified MRO facilities established by 2025. This concentration of services improves operational efficiency for local operators.
Investment Opportunities in the China Aircraft Engine Overhaul Market
Several openings in the China Aircraft Engine Overhaul Market merit attention from investors.
- Investment in Certified MRO Facilities: With the aviation sector projected to grow, there is a strong need for more certified MRO facilities. The Shanghai region, with its established infrastructure, presents an ideal opportunity for investment.
- Expansion of OEM Partnerships: Now is an opportune time to invest in OEM partnerships, as they are expected to grow by 11% through 2032. Collaborating with manufacturers can improve service quality and parts availability.
- Focus on Business Aviation Maintenance: The rising demand for business aviation services creates opportunities for maintenance providers. By targeting private operators, suppliers can capture a growing market segment.
- Development of Online Maintenance Solutions: The rise of online maintenance vendors presents a unique opportunity to streamline parts procurement. Investing in digital platforms can attract a new customer base seeking convenience.
Government Initiatives in the China Aircraft Engine Overhaul Market
The regulatory framework for aircraft maintenance in China is shaped by laws such as the CAAC's regulations, which mandate that all aircraft engines undergo overhaul every 6,000 flight hours. Additionally, the 'Aviation Industry Development Plan' launched in 2021 focuses on improving domestic capabilities and safety standards. These measures ensure that operators comply with rigorous maintenance protocols, promoting safety and efficiency in the sector. The Chinese government has invested over 100 million RMB in aviation safety programs since 2020 to support these initiatives.
The Civil Aviation Administration of China (CAAC) plays a vital role in approving maintenance procedures and standards. The CAAC oversees the certification of MRO facilities and ensures compliance with national regulations. Funding for aviation safety programs is allocated to enhance maintenance capabilities across the industry. The CAAC's efforts aim to improve the overall safety and reliability of aircraft operations, benefiting both operators and passengers.
Future Insight of the China Aircraft Engine Overhaul Market
The Aircraft Engine Overhaul market in China is set to transform by 2032, primarily driven by advancements in technology and government support. The 14th Five-Year Plan focuses on developing technological capabilities, which will enhance domestic overhaul services. By 2035, the aviation sector is projected to serve 1.4 billion passengers, substantially increasing the demand for efficient engine maintenance. Government investments exceeding 100 million RMB in aviation safety programmes will raise maintenance standards, benefiting both buyers and suppliers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Overhaul Type – Hot Section Overhaul Dominated, Cold Section Overhaul Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, Hot Section Overhaul accounted for a 51% market share by overhaul type in 2025. Hot Section Overhaul holds the largest share as it is essential for maintaining engine performance and safety across China's fleet of over 3,000 registered commercial aircraft. The CAAC mandates regular maintenance procedures, making this segment critical for operators aiming to comply with stringent aviation safety regulations. Cold Section Overhaul is set to record the highest CAGR in this split, 11.6% over 2026–2032. Cold Section Overhaul is experiencing rapid growth as airlines increasingly focus on engine efficiency and longevity, especially with the aviation sector projected to accommodate 1.4 billion passengers by 2035. This heightened emphasis on operational efficiency positions Cold Section Overhaul for continued market expansion, reinforcing its importance in the overhaul landscape. Suppliers should prioritise investments in Cold Section Overhaul services to meet the rising demand from airlines focused on enhancing operational efficiency.
By Component Area – Turbine Components Dominated, Compressor Modules Expected to Grow Fastest
With a 45% revenue share in 2025, Turbine Components was the largest component area category. Turbine Components dominate the market share due to their vital role in ensuring the overall functionality of aircraft engines, which directly impacts performance and safety. With commercial aircraft engines in China averaging a lifespan of approximately 20 years, the demand for turbine component overhauls remains consistently robust. Over 2026–2032, Compressor Modules are expected to post the fastest growth, at a CAGR of 11.3%. Compressor Modules are growing rapidly as they play a crucial role in optimising engine air intake efficiency, which is increasingly important for airlines aiming to enhance performance. The surge in commercial flights in China further drives the need for efficient compressor module services, propelling this segment's growth. Suppliers should focus on expanding their offerings in Compressor Modules to leverage the increasing demand for efficient engine performance.
By Distribution Channel – Certified MROs Dominated, OEM Partnerships Expected to Grow Fastest
In 2025, Certified MROs led the distribution channel split with a 37% share. Certified MROs lead the market share as they are the primary service providers for aircraft engine overhauls, ensuring compliance with national standards established by the CAAC. Their established reputation and certification make them the preferred choice for operators seeking reliable and compliant overhaul services. The quickest growth will come from OEM Partnerships, forecast to expand at a CAGR of 11.0% between 2026 and 2032. OEM Partnerships are witnessing rapid growth as they provide essential access to original parts crucial for maintaining the integrity of overhauled engines. As the aviation sector expands, the reliance on OEM partnerships for quality components will continue to drive this segment's growth. Suppliers should explore strategic OEM partnerships to enhance their service offerings and effectively meet the demands of the growing aviation market.
By End User – Commercial Jet Operators Dominated, Business Aviation Services Expected to Grow Fastest
Commercial Jet Operators took a 45% share of end user in 2025, more than any other category. Commercial Jet Operators account for the largest user segment, necessitating regular overhauls to ensure safety and compliance for their extensive fleets. This segment's substantial share reflects the strong demand from operators who rely on consistent maintenance to keep their aircraft operational and compliant with regulations. Business Aviation Services are projected to grow fastest, at a CAGR of 12.0% during 2026–2032. Business Aviation Services are experiencing the fastest growth due to the increasing demand for maintenance in the private aviation sector, driven by a rise in affluent individuals seeking personalised travel options. This trend indicates that the market for business aviation maintenance will continue to expand rapidly, creating new opportunities. Suppliers should tailor their services to meet the growing needs of Business Aviation Services, ensuring competitiveness in this expanding market segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Aircraft Engine Overhaul Market Outlook
- Market Size of China Aircraft Engine Overhaul Market, 2025
- Forecast of China Aircraft Engine Overhaul Market, 2032
- Historical Data and Forecast of China Aircraft Engine Overhaul Revenues & Volume for the Period 2022 - 2032F
- China Aircraft Engine Overhaul Market Trend Evolution
- China Aircraft Engine Overhaul Market Drivers and Challenges
- China Aircraft Engine Overhaul Price Trends
- China Aircraft Engine Overhaul Porter's Five Forces
- China Aircraft Engine Overhaul Industry Life Cycle
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Overhaul Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Hot Section Overhaul for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Cold Section Overhaul for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Full Engine Overhaul for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Modular Replacement for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Component Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Turbine Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Compressor Modules for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By End-to-End Rebuild for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Swappable Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Certified MROs for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By OEM Partnerships for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Engine Repair Contractors for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Online Maintenance Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Commercial Jet Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Business Aviation Services for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Air Cargo Fleet Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Engine Overhaul Market Revenues & Volume By Government Aviation Units for the Period 2022 - 2032F
- China Aircraft Engine Overhaul Import Export Trade Statistics
- Market Opportunity Assessment By Overhaul Type
- Market Opportunity Assessment By Component Area
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Aircraft Engine Overhaul Top Companies Market Share
- China Aircraft Engine Overhaul Competitive Benchmarking By Technical and Operational Parameters
- China Aircraft Engine Overhaul Company Profiles
- China Aircraft Engine Overhaul Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Overhaul Type
- Hot Section Overhaul
- Cold Section Overhaul
- Full Engine Overhaul
- Modular Replacement
By Component Area
- Turbine Components
- Compressor Modules
- End-to-End Rebuild
- Swappable Units
By Distribution Channel
- Certified MROs
- OEM Partnerships
- Engine Repair Contractors
- Online Maintenance Vendors
By End User
- Commercial Jet Operators
- Business Aviation Services
- Air Cargo Fleet Operators
- Government Aviation Units






































