China Aircraft Risk Management Market Size & Growth Rate
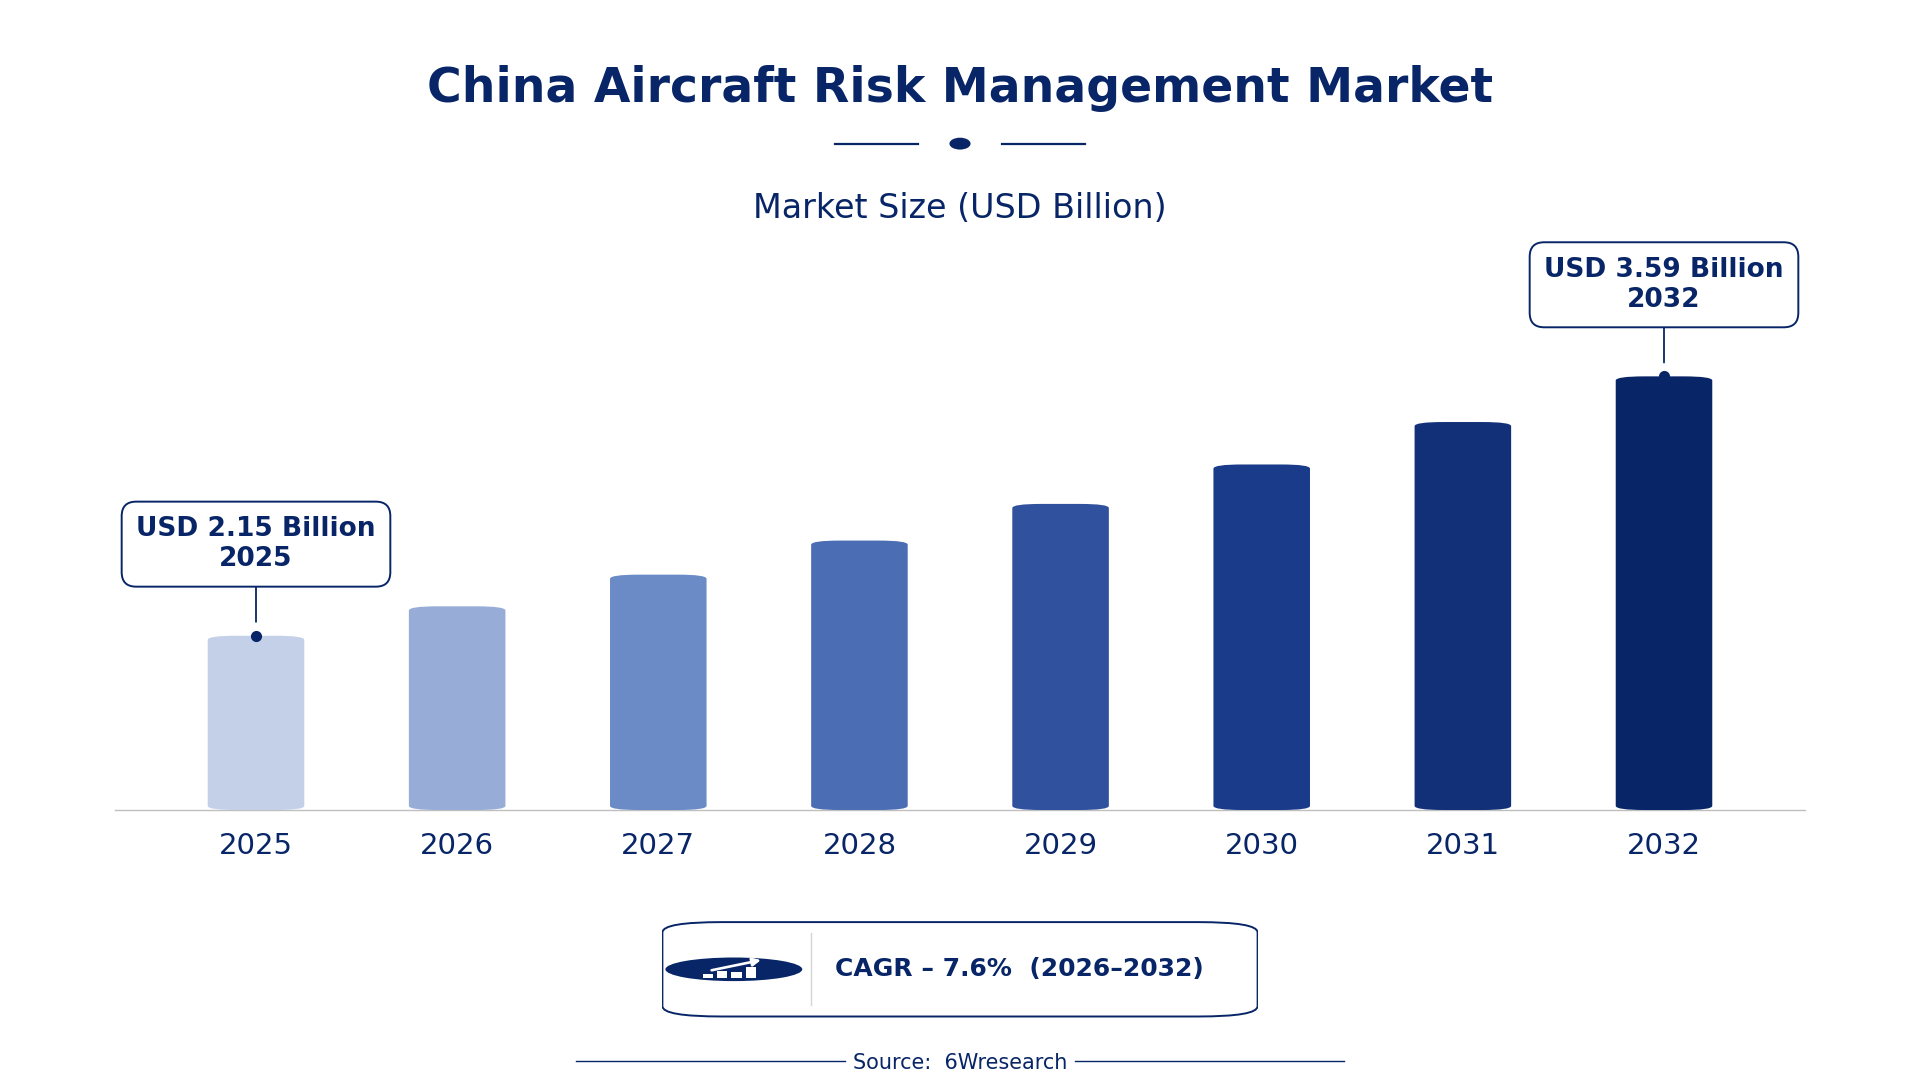
According to 6Wresearch internal database and industry insights, the China Aircraft Risk Management Market was valued at USD 2.15 billion in 2025 and is projected to reach USD 3.59 billion by 2032, growing at a CAGR of approximately 7.6% during 2026–2032.
China Aircraft Risk Management Market Highlights
| Report Metric | Details |
| Report Name | China Aircraft Risk Management Market |
| Market Size 2025 | USD 2.15 billion |
| Market Size 2032 | USD 3.59 billion |
| Absolute Growth 2025–2032 | USD 1.44 billion |
| CAGR 2026–2032 | 7.6% |
| Peak Annual Growth | 10.1% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Risk Type, 2025 | Flight Risk (42% share) |
| Leading Software Type, 2025 | Predictive Tools (43% share) |
| Leading Distribution Channel, 2025 | Direct Sales (35% share) |
| Leading End User, 2025 | Airlines (37% share) |
| Fastest-Growing Risk Type | Cyber Risk (9.4% CAGR) |
| Fastest-Growing Distribution Channel | Online Platforms (8.9% CAGR) |
| Fastest-Growing End User | Fleet Operators (8.7% CAGR) |
| Growing Sector | Fleet Operators |
| Key End Users | Airlines, Fleet Operators, MRO Providers, Avionics Firms |
China Aircraft Risk Management Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
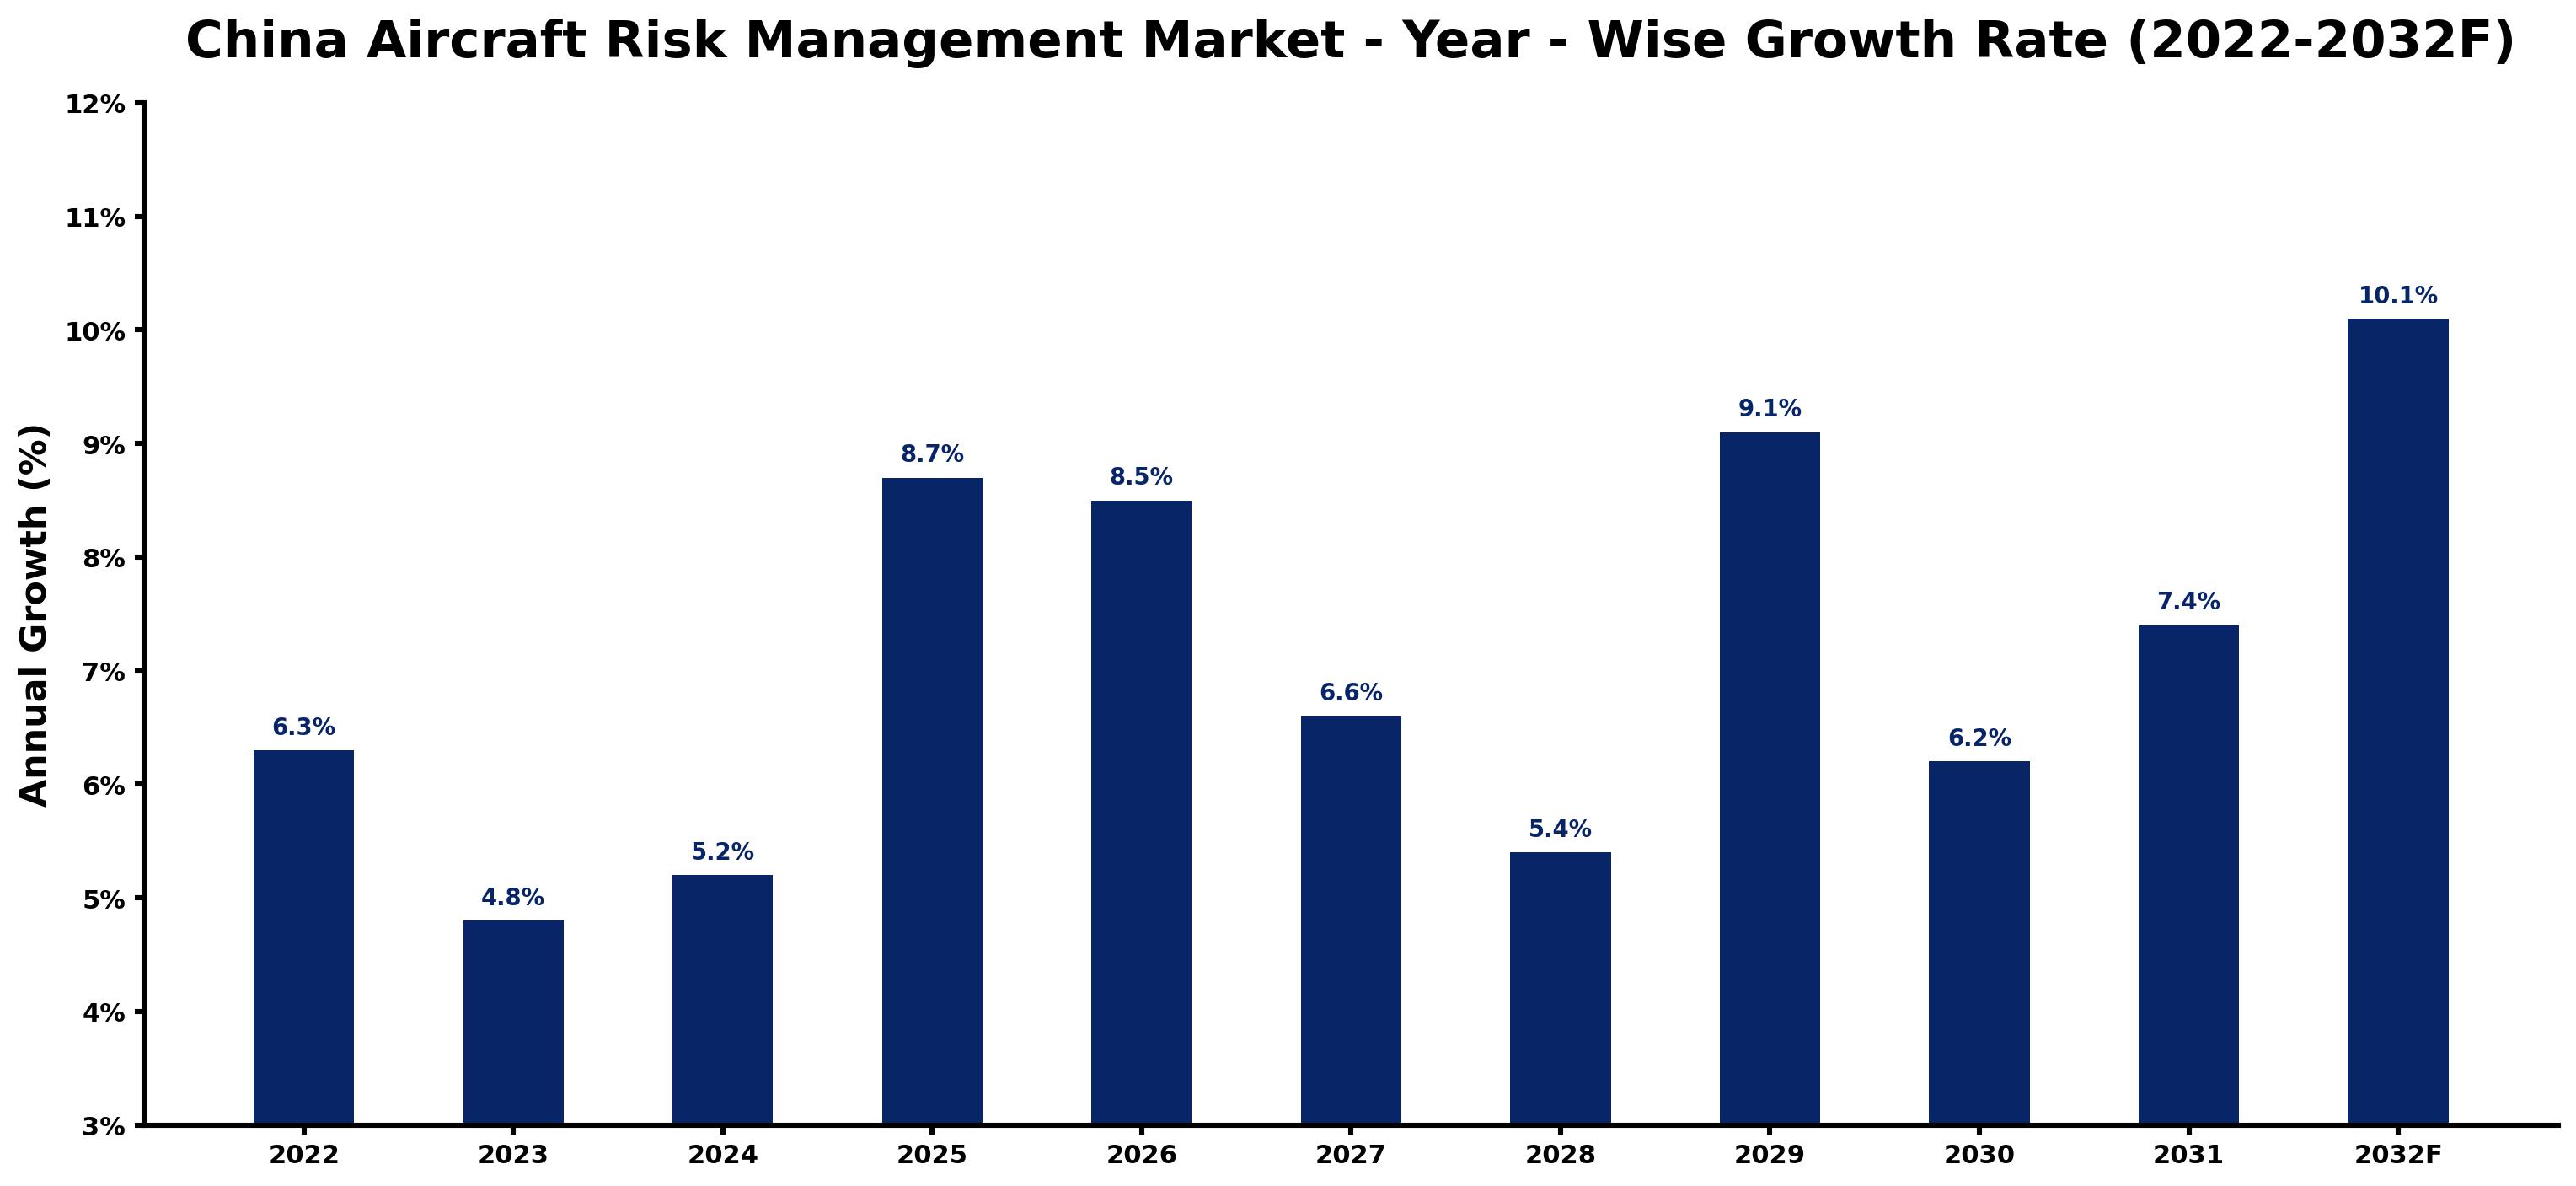
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.3 | The market experienced steady growth, driven by increasing passenger traffic and safety requirements. |
| 2023 | 4.8 | Growth slowed due to heightened competition among airlines affecting pricing strategies. |
| 2024 | 5.2 | Demand increased as airlines sought to enhance operational efficiency through risk management solutions. |
| 2025 | 8.7 | The market peaked with significant investments in safety protocols and predictive maintenance technologies. |
| 2026 | 8.5 | Growth moderated as regulatory changes required additional compliance measures for service providers. |
| 2027 | 6.6 | A further slowdown occurred as buyers adjusted to new operational costs from regulatory compliance. |
| 2028 | 5.4 | The market continued to grow, albeit at a slower pace, as airlines focused on risk mitigation strategies. |
| 2029 | 9.1 | A rebound in growth was noted as the air cargo sector expanded, increasing demand for risk management tools. |
| 2030 | 6.2 | Growth decelerated as airlines faced challenges in implementing new safety management systems. |
| 2031 | 7.4 | An increase in growth was observed as the workforce in the aerospace sector expanded, supporting demand. |
| 2032 | 10.1 | The market reached its peak growth as cybersecurity measures became essential for aviation operations. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Aircraft Risk Management Market Synopsis
Aircraft Risk Management in China focuses on evaluating and reducing risks tied to aviation operations, employing advanced software solutions for safety and compliance. The China Aircraft Risk Management Market is expanding due to increasing passenger volumes and the demand for enhanced safety measures. By 2035, the aviation sector is expected to accommodate 1,000 million passengers, which will elevate the need for effective risk management solutions. Government initiatives, including the Aviation Safety Enhancement Program, further propel this growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing passenger traffic and operational demands drive the need for risk management solutions. | Driver | High | Flight Risk |
| The growing focus on predictive maintenance improves operational efficiency and safety. | Driver | High | Predictive Tools |
| Investment in airport infrastructure creates opportunities for advanced risk management solutions. | Opportunity | High | Airlines |
| The expansion of the air cargo market necessitates effective risk management strategies. | Opportunity | High | Fleet Operators |
| Regulatory compliance requirements can increase operational costs for airlines. | Restraint | Medium | Operational Risk |
| Limited awareness of advanced risk management tools may hinder market growth. | Restraint | Medium | Maintenance Risk |
| Challenges in adapting to rapidly evolving cybersecurity threats pose risks. | Challenge | High | Cyber Risk |
| High competition among software providers may lead to pricing pressures. | Challenge | Medium | Predictive Tools |
Evaluation of Drivers in China Aircraft Risk Management Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising passenger traffic necessitates improved safety protocols and risk management solutions. | Flight Risk | China's aviation industry is projected to reach 1,000 million passengers by 2035, driving demand for risk management. |
| The need for predictive maintenance tools is increasing operational efficiency. | Predictive Tools | The demand for predictive maintenance solutions is growing due to improved operational efficiency, with the MRO market valued at approximately $15 billion. |
| Investment in airport infrastructure supports the adoption of risk management technologies. | Airlines | The government allocated $1 billion in 2022 to improve airport infrastructure, encouraging risk management adoption. |
| The expansion of the air cargo market drives demand for effective risk management. | Fleet Operators | China's air cargo market is expanding, necessitating effective risk management strategies. |
| Regulatory compliance requirements drive the need for standardised risk management practices. | Operational Risk | The Civil Aviation Administration of China (CAAC) sets safety standards for the aviation sector. |
The Aircraft Risk Management market in China is expanding due to rising passenger traffic, a heightened emphasis on predictive maintenance, and considerable investments in airport infrastructure. The aviation industry is anticipated to reach 1,000 million passengers by 2035, prompting the need for improved safety protocols. The growing demand for predictive maintenance solutions stems from the need for better operational efficiency, with the aviation maintenance, repair, and overhaul market valued at around $15 billion. Furthermore, the growth of the air cargo market increases the need for effective risk management strategies as companies aim to reduce operational risks.
Evaluation of Restraints in China Aircraft Risk Management Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory compliance requirements can increase operational costs for airlines. | Operational Risk | Stricter regulations from the CAAC can lead to higher operational costs for airlines. |
| Limited awareness of advanced risk management tools may hinder market growth. | Maintenance Risk | Many airlines are not fully aware of the benefits of predictive maintenance solutions. |
| Challenges in adapting to rapidly evolving cybersecurity threats can hinder market growth. | Cyber Risk | The CAAC's 2023 report highlighted the importance of cybersecurity in aviation risk management. |
| High competition among software providers may lead to pricing pressures. | Predictive Tools | Increased competition can result in lower prices, affecting profitability for providers. |
| Integration of new technologies can be costly and time-consuming for airlines. | Flight Risk | Airlines may struggle with the financial burden of implementing advanced risk management systems. |
China Aircraft Risk Management Market Challenges
The Aircraft Risk Management market in China encounters several practical issues, starting with fierce competition among over 600 commercial airlines, which pressures service prices and compresses profit margins for risk management providers. Buyers are facing rising compliance costs due to stricter regulations from the Civil Aviation Administration of China, leading to operational expenses that can increase by 15% of their budgets. Supply chain disruptions hinder access to advanced software solutions, causing delays in risk assessment processes that can extend project timelines for producers by several months. Regulatory changes, including new safety management systems mandated by the CAAC, require substantial investment from aviation service providers, costing them millions in necessary upgrades and training.
Trends in the China Aircraft Risk Management Market
The trends below show where the China Aircraft Risk Management Market is heading.
- Shift towards Predictive Maintenance Solutions: Since 2021, airlines have increasingly adopted predictive maintenance tools to forecast potential risks and maintenance needs. This shift improves operational efficiency and enhances safety protocols.
- Transition to Enhanced Cybersecurity Measures: The Aviation Cybersecurity Strategy introduced in 2021 has led to a stronger focus on cybersecurity. This shift is essential as the CAAC reported a 10% increase in air traffic in 2023, necessitating effective cybersecurity measures.
- Emergence of Real-time Risk Management Dashboards: The demand for real-time dashboards has surged as airlines seek immediate insights into operational metrics. This trend is supported by the growing need for operational efficiency in the aviation sector, particularly in high-traffic regions.
- Growth in Cloud-based Risk Management Solutions: The shift towards cloud software began in 2022, allowing for scalable risk management solutions. This change enables airlines to access risk management tools from anywhere, enhancing operational flexibility.
Investment Opportunities in the China Aircraft Risk Management Market
Some of the investment opportunities in the China Aircraft Risk Management Market are mentioned below.
- Establish Partnerships with Airlines: Now is an opportune moment to invest in partnerships with airlines that require advanced risk management solutions. With the aviation industry projected to reach 1,000 million passengers by 2035, the demand for effective tools is on the rise.
- Invest in Predictive Maintenance Technologies: The increasing focus on predictive maintenance presents opportunities for investment in advanced technologies. Airlines are progressively adopting these solutions to enhance operational efficiency and safety.
- Expand in the Beijing-Tianjin-Hebei Region: The Beijing-Tianjin-Hebei region serves as a major hub for aviation operations in China. Investing in risk management solutions here can capture a substantial market share as demand escalates.
- Engage with Government Initiatives: Engaging with government initiatives, such as the Aviation Safety Enhancement Program, can provide avenues for development and funding. This program supports advancements in safety protocols and risk management practices.
Government Initiatives in the China Aircraft Risk Management Market
The Civil Aviation Administration of China (CAAC) implemented the Safety Management System (SMS) Framework in 2020 to standardise risk management practices across airlines and MRO providers. This framework mandates that aviation service providers adhere to specific safety protocols, thereby improving overall safety standards. In 2021, the CAAC introduced the Aviation Cybersecurity Strategy to strengthen defences against cyber threats in the aviation sector. This strategy requires airlines to implement effective cybersecurity measures to safeguard sensitive data and operational integrity. The National Development and Reform Commission (NDRC) approved the Aviation Infrastructure Development Plan in 2022, aiming to invest $1 billion in airport upgrades, which supports the adoption of risk management solutions.
The Aviation Safety Enhancement Program launched by the CAAC in 2023 aims to bolster safety protocols across the industry. This program provides funding and resources for airlines to adopt advanced risk management technologies. The Ministry of Industry and Information Technology (MIIT) initiated the Smart Aviation Initiative in 2022 to promote the adoption of advanced technologies in aviation risk management, enabling airlines to enhance their operational capabilities. The CAAC's ongoing efforts to standardise risk management practices ensure that aviation service providers can meet regulatory requirements effectively.
Future Insight of the China Aircraft Risk Management Market
The Aircraft Risk Management market in China is set to evolve significantly by 2032, driven by advancements in predictive maintenance technologies and a stronger emphasis on cybersecurity measures. The government's Made in China 2025 initiative will improve manufacturing capabilities, enabling the development of sophisticated risk management tools. By 2025, China's aerospace workforce is projected to grow to 1.5 million, supporting the demand for comprehensive risk management strategies. The National Aerospace Technology Innovation Program will stimulate research and development, encouraging innovation in risk mitigation practices.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Risk Type – Flight Risk Dominated, Cyber Risk Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, Flight Risk took a 42% share of risk type in 2025, more than any other category. Flight Risk commands the largest share because it is vital for ensuring flight safety and meeting regulatory standards. With over 600 commercial airlines in operation, effective management of flight risks is essential for maintaining compliance and operational integrity. Cyber Risk is projected to grow fastest, at a CAGR of 9.4% during 2026–2032. Cyber Risk is witnessing rapid growth due to the increasing prevalence of cybersecurity threats in aviation, as highlighted by the CAAC's 2023 report. This heightened focus on cybersecurity will drive further advancements and investments in risk management solutions, ensuring robust protection in a digital environment. This trend indicates that suppliers must enhance their cybersecurity offerings to align with the aviation sector's increasing focus on risk management.
By Software Type – Predictive Tools Dominated and Is Expected to Record the Fastest Growth
Predictive Tools held a 43% share of the China Aircraft Risk Management Market by software type in 2025. Predictive Tools hold the largest market share as they are crucial for forecasting potential risks and optimising maintenance schedules. The aviation industry's growing emphasis on predictive maintenance solutions underscores their essential role in enhancing operational efficiency. The same category are also set to grow fastest, at a CAGR of 10.1% during 2026–2032. Predictive Tools are also the fastest-growing segment, aligning perfectly with the industry's ongoing push for improved operational efficiency. Their increasing adoption will further entrench their leading position in the market, reinforcing their importance in effective risk management. Suppliers should prioritise the development of advanced predictive capabilities to sustain their competitive edge in the aircraft risk management market.
By Distribution Channel – Direct Sales Dominated, Online Platforms Expected to Grow Fastest
Direct Sales accounted for a 35% market share by distribution channel in 2025. Direct Sales leads the distribution channel share as it remains the primary method for selling risk management software directly to users. This approach allows for tailored solutions that meet specific client needs in the aviation sector. Online Platforms are set to record the highest CAGR in this split, 8.9% over 2026–2032. Online Platforms are experiencing rapid growth as more companies shift towards digital sales channels, reflecting changing buyer preferences. This trend indicates a need for suppliers to strengthen their online presence and capabilities. Suppliers must invest in online sales strategies to capture the growing segment of digital buyers in the aircraft risk management market.
By End User – Airlines Dominated, Fleet Operators Expected to Grow Fastest
The largest end user category in 2025 was Airlines, with a 37% share of total revenue. Airlines represent the largest share of end users as they are the main consumers of risk management solutions, essential for their operations. The projected increase in air traffic, with a 10% rise in 2023, further fuels this demand for reliable risk management. Over 2026–2032, Fleet Operators are expected to post the fastest growth, at a CAGR of 8.7%. Fleet Operators are the fastest-growing segment, utilising risk management tools to efficiently manage multiple aircraft. Their increasing operational complexity and the need for streamlined processes will drive further adoption of these solutions in the coming years. Suppliers should tailor their offerings to meet the unique needs of fleet operators to capitalise on this growing segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Aircraft Risk Management Market Outlook
- Market Size of China Aircraft Risk Management Market, 2025
- Forecast of China Aircraft Risk Management Market, 2032
- Historical Data and Forecast of China Aircraft Risk Management Revenues & Volume for the Period 2022 - 2032F
- China Aircraft Risk Management Market Trend Evolution
- China Aircraft Risk Management Market Drivers and Challenges
- China Aircraft Risk Management Price Trends
- China Aircraft Risk Management Porter's Five Forces
- China Aircraft Risk Management Industry Life Cycle
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Risk Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Flight Risk for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Operational Risk for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Maintenance Risk for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Cyber Risk for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Software Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Predictive Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Real-time Dashboards for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Cloud Software for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Analytics Suite for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Industrial Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Specialty Stores for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Airlines for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Fleet Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By MRO Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Aircraft Risk Management Market Revenues & Volume By Avionics Firms for the Period 2022 - 2032F
- China Aircraft Risk Management Import Export Trade Statistics
- Market Opportunity Assessment By Risk Type
- Market Opportunity Assessment By Software Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Aircraft Risk Management Top Companies Market Share
- China Aircraft Risk Management Competitive Benchmarking By Technical and Operational Parameters
- China Aircraft Risk Management Company Profiles
- China Aircraft Risk Management Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Risk Type
- Flight Risk
- Operational Risk
- Maintenance Risk
- Cyber Risk
By Software Type
- Predictive Tools
- Real-time Dashboards
- Cloud Software
- Analytics Suite
By Distribution Channel
- Online Platforms
- Direct Sales
- Industrial Suppliers
- Specialty Stores
By End User
- Airlines
- Fleet Operators
- MRO Providers
- Avionics Firms































