China In-Car Information Display Market Size & Growth Rate
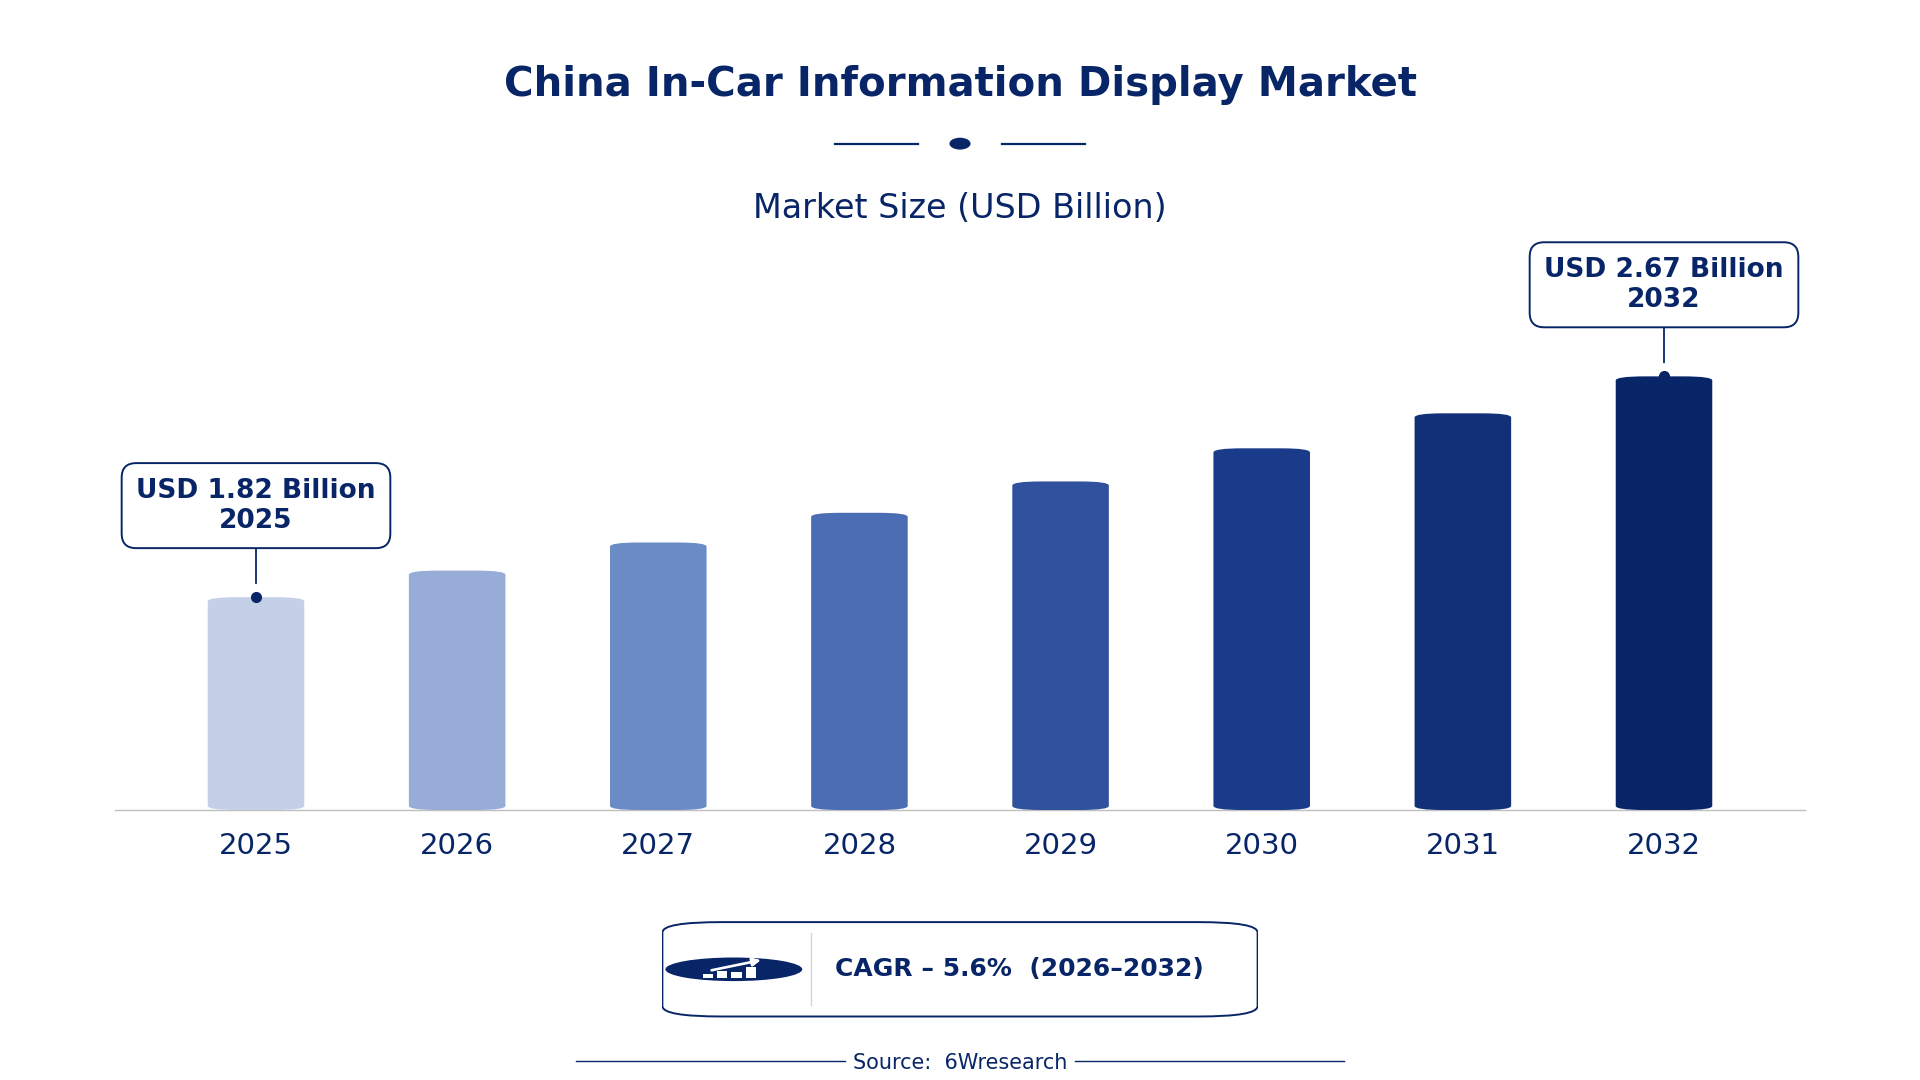
According to 6Wresearch internal database and industry insights, the China In-Car Information Display Market was valued at USD 1.82 billion in 2025 and is projected to reach USD 2.67 billion by 2032, growing at a CAGR of approximately 5.6% during 2026–2032.
China In-Car Information Display Market Highlights
| Report Metric | Details |
| Report Name | China In-Car Information Display Market |
| Market Size 2025 | USD 1.82 billion |
| Market Size 2032 | USD 2.67 billion |
| Absolute Growth 2025–2032 | USD 0.85 billion |
| CAGR 2026–2032 | 5.6% |
| Peak Annual Growth | 7.6% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Display Type, 2025 | Center Stack Display (34% share) |
| Leading Screen Technology, 2025 | TFT (38% share) |
| Leading Size Range, 2025 | 7–12 inch (50% share) |
| Leading End User, 2025 | OEMs (38% share) |
| Fastest-Growing Display Type | Head-Up Display (6.8% CAGR) |
| Fastest-Growing Screen Technology | OLED (7.1% CAGR) |
| Fastest-Growing Size Range | 10–15 inch (6.8% CAGR) |
| Fastest-Growing End User | Electric & Premium Vehicles (6.8% CAGR) |
| Growing Sector | Electric & Premium Vehicles |
| Key End Users | OEMs, Electric & Premium Vehicles, Next-Gen Car Makers, Infotainment Suppliers |
China In-Car Information Display Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
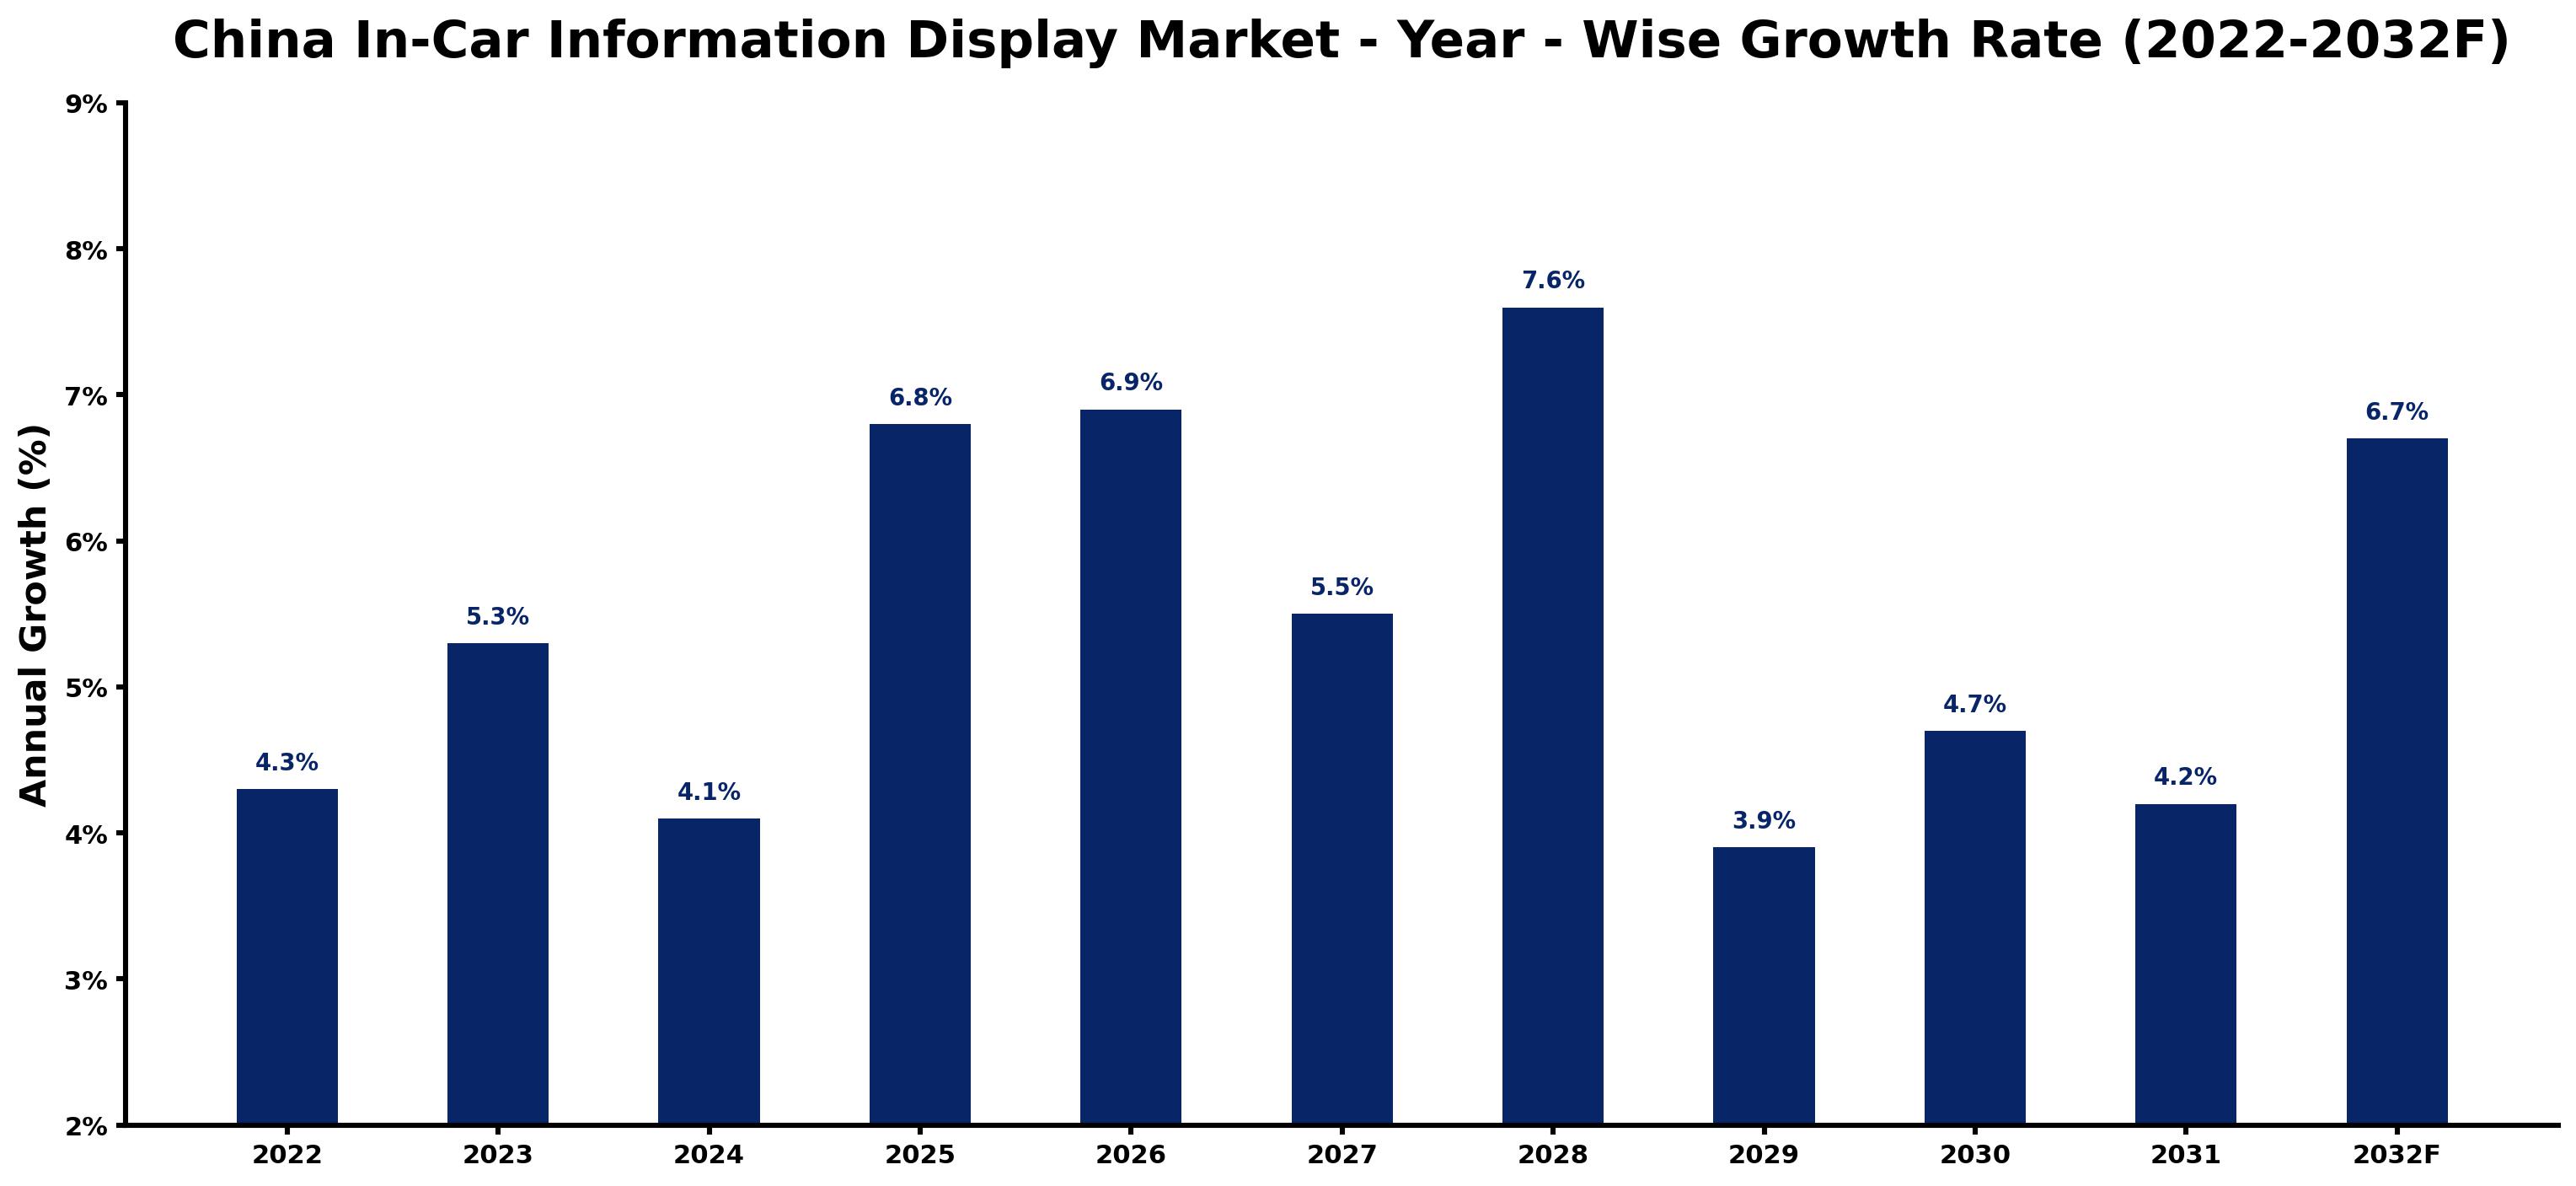
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.3 | The automotive market produced over 25 million vehicles, driving demand for displays. |
| 2023 | 5.3 | Growth was supported by the increasing adoption of electric vehicles, which require advanced displays. |
| 2024 | 4.1 | The market experienced a slowdown as manufacturers adjusted to evolving technology demands. |
| 2025 | 6.8 | A surge in premium vehicle sales led to higher demand for larger displays in cars. |
| 2026 | 6.9 | Technological advancements in display quality are expected to boost consumer interest in new models. |
| 2027 | 5.5 | The market is projected to slow as manufacturers face challenges in sourcing materials for displays. |
| 2028 | 7.6 | Growth is expected due to the rising popularity of head-up displays in new vehicles. |
| 2029 | 3.9 | A slowdown is anticipated as the market matures and competition intensifies among manufacturers. |
| 2030 | 4.7 | Growth will resume as new energy vehicle initiatives gain traction among consumers. |
| 2031 | 4.2 | The market is expected to experience a slight slowdown as manufacturers focus on sustainability practices. |
| 2032 | 6.7 | Demand is projected to rise as the average size of center stack displays increases. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China In-Car Information Display Market Synopsis
The In-Car Information Display Market in China encompasses electronic interfaces that provide drivers and passengers with essential information and entertainment. These displays, made using advanced technologies like TFT and OLED, are integral to navigation and vehicle diagnostics. The market is expanding due to strong automotive production, with over 25 million vehicles made in 2022, and rising demand for electric vehicles. The 'New Energy Vehicle Industry Development Plan' aims for 20% of vehicles to be electric by 2025, further driving this growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing vehicle production and sales drive demand for in-car displays. | Driver | High | Center Stack Display |
| The growing electric vehicle market boosts demand for advanced display technologies. | Driver | High | Head-Up Display |
| Investment in smart vehicle technologies opens new avenues for display manufacturers. | Opportunity | High | Instrument Panel Display |
| The shift towards larger displays presents opportunities for suppliers to innovate. | Opportunity | Medium | Center Stack Display |
| Supply chain disruptions may hinder the availability of display components. | Restraint | High | Center Stack Display |
| High production costs for advanced display technologies could limit market growth. | Restraint | Medium | Center Stack Display |
| Buyers face challenges in sourcing high-quality display components amidst competition. | Challenge | High | Center Stack Display |
| Suppliers struggle with rapid technological changes, impacting their production timelines. | Challenge | Medium | Electric & Premium Vehicles |
Evaluation of Drivers in China In-Car Information Display Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising vehicle production increases demand for integrated displays. | Center Stack Display | Over 25 million vehicles were produced in 2022, increasing the need for integrated displays. |
| Growing electric vehicle sales drive demand for advanced display technologies. | Head-Up Display | In 2022, 15% of new vehicles sold were electric, requiring modern display technologies. |
| Investment in smart vehicle initiatives promotes display technology integration. | Instrument Panel Display | The 'Intelligent Connected Vehicle Development Strategy' aims to improve display solutions. |
| Consumer preference for larger displays boosts market opportunities. | Center Stack Display | The average size of center stack displays is increasing to 12-15 inches in premium vehicles. |
| Technological advancements in display quality attract buyers. | Head-Up Display | The adoption rate of head-up displays in new cars was around 10% in 2022. |
In 2022, over 25 million vehicles were produced, leading to heightened demand for integrated displays. The average size of centre stack displays is expanding to 12-15 inches in premium vehicles, appealing to consumers. The adoption rate of head-up displays in new cars reached approximately 10% in 2022, reflecting the increasing interest in advanced display solutions. Investment in smart vehicle technologies is set to further improve the integration of display systems in the automotive sector.
Evaluation of Restraints in China In-Car Information Display Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions hinder the availability of display components. | Center Stack Display | Recent global supply chain issues have affected the sourcing of critical materials for displays. |
| High production costs for advanced display technologies limit market growth. | Center Stack Display | The increasing costs of raw materials have raised the production expenses for manufacturers. |
| Limited consumer awareness of advanced display features restricts adoption. | Center Stack Display | Many buyers remain unaware of the benefits of advanced in-car display technologies. |
| Competition among manufacturers leads to price wars, impacting profitability. | Instrument Panel Display | Intense competition has driven down prices, affecting profit margins for suppliers. |
| Regulatory compliance may slow down product development timelines. | Center Stack Display | Manufacturers must adhere to strict automotive standards, delaying new product launches. |
China In-Car Information Display Market Challenges
Buyers and suppliers in the China In-Car Information Display market encounter considerable cost challenges, with raw material prices surging by 20% over the past year, which pressures manufacturers' profit margins. This increase is primarily due to global supply chain disruptions, causing delays in production schedules for producers and raising costs for buyers. The rapid pace of technological advancements in display technologies presents another challenge, as many suppliers struggle to keep pace, risking obsolescence and diminishing their competitiveness. A skills gap in the workforce complicates matters further, limiting producers' capacity to implement new technologies effectively, which can hinder innovation for buyers seeking advanced features.
Trends in the China In-Car Information Display Market
Below mentioned are some of the trends shaping the China In-Car Information Display Market growth.
- Shift towards Larger Displays in Premium Vehicles: China's automotive market is increasingly favouring larger centre stack displays, with an average size rising to 12-15 inches in premium vehicles. This trend reflects consumer demand for enhanced infotainment experiences, supported by the growing electric vehicle market, which accounted for 15% of new sales in 2022.
- Emergence of Head-Up Displays: The adoption of head-up displays in new vehicles is gaining traction, with a 10% adoption rate in 2022. This technology improves driver safety by projecting essential information onto the windshield, aligning with the 'Intelligent Connected Vehicle Development Strategy'.
- Integration of Smart Vehicle Technologies: The automotive industry is increasingly incorporating smart technologies into vehicles, driven by the 'New Energy Vehicle Industry Development Plan'. This initiative aims for 20% of vehicles to be electric by 2025, promoting advanced display technologies.
- Rise of OLED Displays in Luxury Vehicles: OLED displays are becoming more popular in luxury vehicles, with a projected growth rate of 7.1% from 2026 to 2032. This shift is driven by consumer preference for superior display quality and colour reproduction.
Investment Opportunities in the China In-Car Information Display Market
Several openings in the China In-Car Information Display Market merit attention from investors.
- Supply of Advanced Display Technologies: There is a growing opportunity to supply advanced display technologies, particularly OLED, which is projected to grow at a rate of 7.1%. Suppliers can target electric and premium vehicle manufacturers in Guangdong province, forming local partnerships.
- Investment in Smart Vehicle Initiatives: Investment in smart vehicle technologies presents opportunities for display manufacturers. The 'Intelligent Connected Vehicle Development Strategy' encourages innovation, allowing suppliers to collaborate with OEMs in Jiangsu province to improve product offerings.
- Expansion of Head-Up Display Market: The head-up display market is expanding rapidly, with a projected growth rate of 6.8%. Suppliers should focus on electric and premium vehicle manufacturers to meet the increasing demand for this technology.
- Development of Larger Center Stack Displays: The trend towards larger centre stack displays offers opportunities for manufacturers. Targeting OEMs in major automotive hubs like Guangdong can facilitate entry into this growing segment.
Government Initiatives in the China In-Car Information Display Market
In 2023, the State Council approved the 'Intelligent Connected Vehicle Development Strategy', which aims to improve the integration of AI in automotive technologies. This policy builds on the 'Automotive Industry Development Policy' from 2021, which focused on innovation and sustainability. The new strategy targets advancements in display technologies by 2025, supporting manufacturers in developing smarter vehicles. The strategy also encourages collaboration between technology firms and automotive manufacturers, promoting innovation in display solutions. Overall, these measures aim to improve the quality and functionality of in-car displays, benefiting both producers and consumers.
The Ministry of Industry and Information Technology oversees the implementation of the 'New Energy Vehicle Industry Development Plan', which promotes the adoption of electric vehicles and advanced display technologies. This initiative supports manufacturers by providing guidelines and standards for EV production. The plan aims for 20% of vehicles to be electric by 2025, creating a conducive environment for display technology advancements. Additionally, the National Development and Reform Commission funds projects that enhance automotive technology, ensuring compliance with national standards.
Future Insight of the China In-Car Information Display Market
By 2032, buyers and suppliers in the China In-Car Information Display market can expect substantial advancements driven by the 'New Energy Vehicle Industry Development Plan' and the 'Intelligent Connected Vehicle Development Strategy'. These initiatives will facilitate the integration of cutting-edge technologies into vehicles, improving user experiences. The average size of centre stack displays is projected to increase to 12-15 inches, catering to consumer preferences for larger screens. Additionally, the government's subsidy programme for electric vehicle manufacturers will likely accelerate the adoption of innovative display solutions, creating new opportunities for suppliers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Display Type – Center Stack Display Dominated, Head-Up Display Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, the largest display type category in 2025 was Center Stack Display, with a 34% share of total revenue. Center Stack Displays hold the largest market share as they are integral to vehicle infotainment systems, which are vital for enhancing user experience. The automotive industry in China, producing over 25 million vehicles in 2022, drives substantial demand for these displays. Head-Up Display is set to record the highest CAGR in this split, 6.8% over 2026–2032. The Head-Up Display segment is witnessing rapid growth as it significantly enhances driver safety by projecting critical information directly onto the windshield. This technology is becoming increasingly popular, particularly with the rise of electric vehicles that prioritise advanced safety features. Suppliers should focus on developing Head-Up Display technologies to meet the increasing demand for safety-oriented in-car solutions.
By Screen Technology – TFT Dominated, OLED Expected to Grow Fastest
TFT accounted for a 38% market share by screen technology in 2025. TFT technology leads the market as it is widely used for cost-effective displays in a majority of vehicles. Its affordability and reliability make it the preferred choice among manufacturers catering to the mass automotive market. Over 2026–2032, OLED is expected to post the fastest growth, at a CAGR of 7.1%. OLED technology is gaining traction in luxury vehicles, driven by consumer preferences for higher-quality displays that offer better colour accuracy and contrast. As more premium models are released, the demand for OLED screens will likely accelerate. Manufacturers should consider investing in OLED technology to capture the growing segment of luxury vehicle buyers seeking superior display quality.
By Size Range – 7–12 inch Dominated, 10–15 inch Expected to Grow Fastest
7–12 inch held a 50% share of the China In-Car Information Display Market by size range in 2025. The 7–12 inch display size is the most common choice for infotainment systems, making it the leading segment in the market. This size effectively meets the functional requirements of modern vehicles while fitting well within design constraints. The quickest growth will come from 10–15 inch, forecast to expand at a CAGR of 6.8% between 2026 and 2032. The 10–15 inch size range is experiencing the fastest growth as larger displays gain popularity in premium vehicles. As consumer preferences shift towards more engaging and user-friendly interfaces, this size is likely to see greater adoption. Suppliers should adjust their offerings to align with the trend towards larger display sizes to satisfy evolving market demands.
By End User – OEMs Dominated, Electric & Premium Vehicles Expected to Grow Fastest
In 2025, OEMs led the end user split with a 38% share. OEMs dominate the market share as they are the primary manufacturers of vehicles, directly influencing the demand for in-car information displays. Their established relationships with component suppliers ensure a reliable supply chain for display technologies. Electric & Premium Vehicles are projected to grow fastest, at a CAGR of 6.8% during 2026–2032. Electric and Premium Vehicles are driving the fastest growth in the market due to their increasing demand for advanced displays that enhance user experience and vehicle functionality. As the electric vehicle market expands, the need for sophisticated display solutions will continue to rise. Suppliers should prioritise partnerships with OEMs focused on electric and premium vehicles to capitalise on this growing segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China In-Car Information Display Market Outlook
- Market Size of China In-Car Information Display Market, 2025
- Forecast of China In-Car Information Display Market, 2032
- Historical Data and Forecast of China In-Car Information Display Revenues & Volume for the Period 2022 - 2032F
- China In-Car Information Display Market Trend Evolution
- China In-Car Information Display Market Drivers and Challenges
- China In-Car Information Display Price Trends
- China In-Car Information Display Porter's Five Forces
- China In-Car Information Display Industry Life Cycle
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By Display Type for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By Center Stack Display for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By Instrument Panel Display for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By Head-Up Display for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By Passenger Display for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By Screen Technology for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By TFT, IPS for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By AMOLED, OLED for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By AR-Enhanced for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By Privacy-Zoned for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By Size Range for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By 7 12 inch for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By 10 15 inch for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By Windshield Projection for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By Multi-screen UX for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By Electric & Premium Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By Next-Gen Car Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Information Display Market Revenues & Volume By Infotainment Suppliers for the Period 2022 - 2032F
- China In-Car Information Display Import Export Trade Statistics
- Market Opportunity Assessment By Display Type
- Market Opportunity Assessment By Screen Technology
- Market Opportunity Assessment By Size Range
- Market Opportunity Assessment By End User
- China In-Car Information Display Top Companies Market Share
- China In-Car Information Display Competitive Benchmarking By Technical and Operational Parameters
- China In-Car Information Display Company Profiles
- China In-Car Information Display Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Display Type
- Center Stack Display
- Instrument Panel Display
- Head-Up Display
- Passenger Display
By Screen Technology
- TFT
- IPS
- AMOLED
- OLED
- AR-Enhanced
- Privacy-Zoned
By Size Range
- 7–12 inch
- 10–15 inch
- Windshield Projection
- Multi-screen UX
By End User
- OEMs
- Electric & Premium Vehicles
- Next-Gen Car Makers
- Infotainment Suppliers































