China In-Car Storage Market Size & Growth Rate
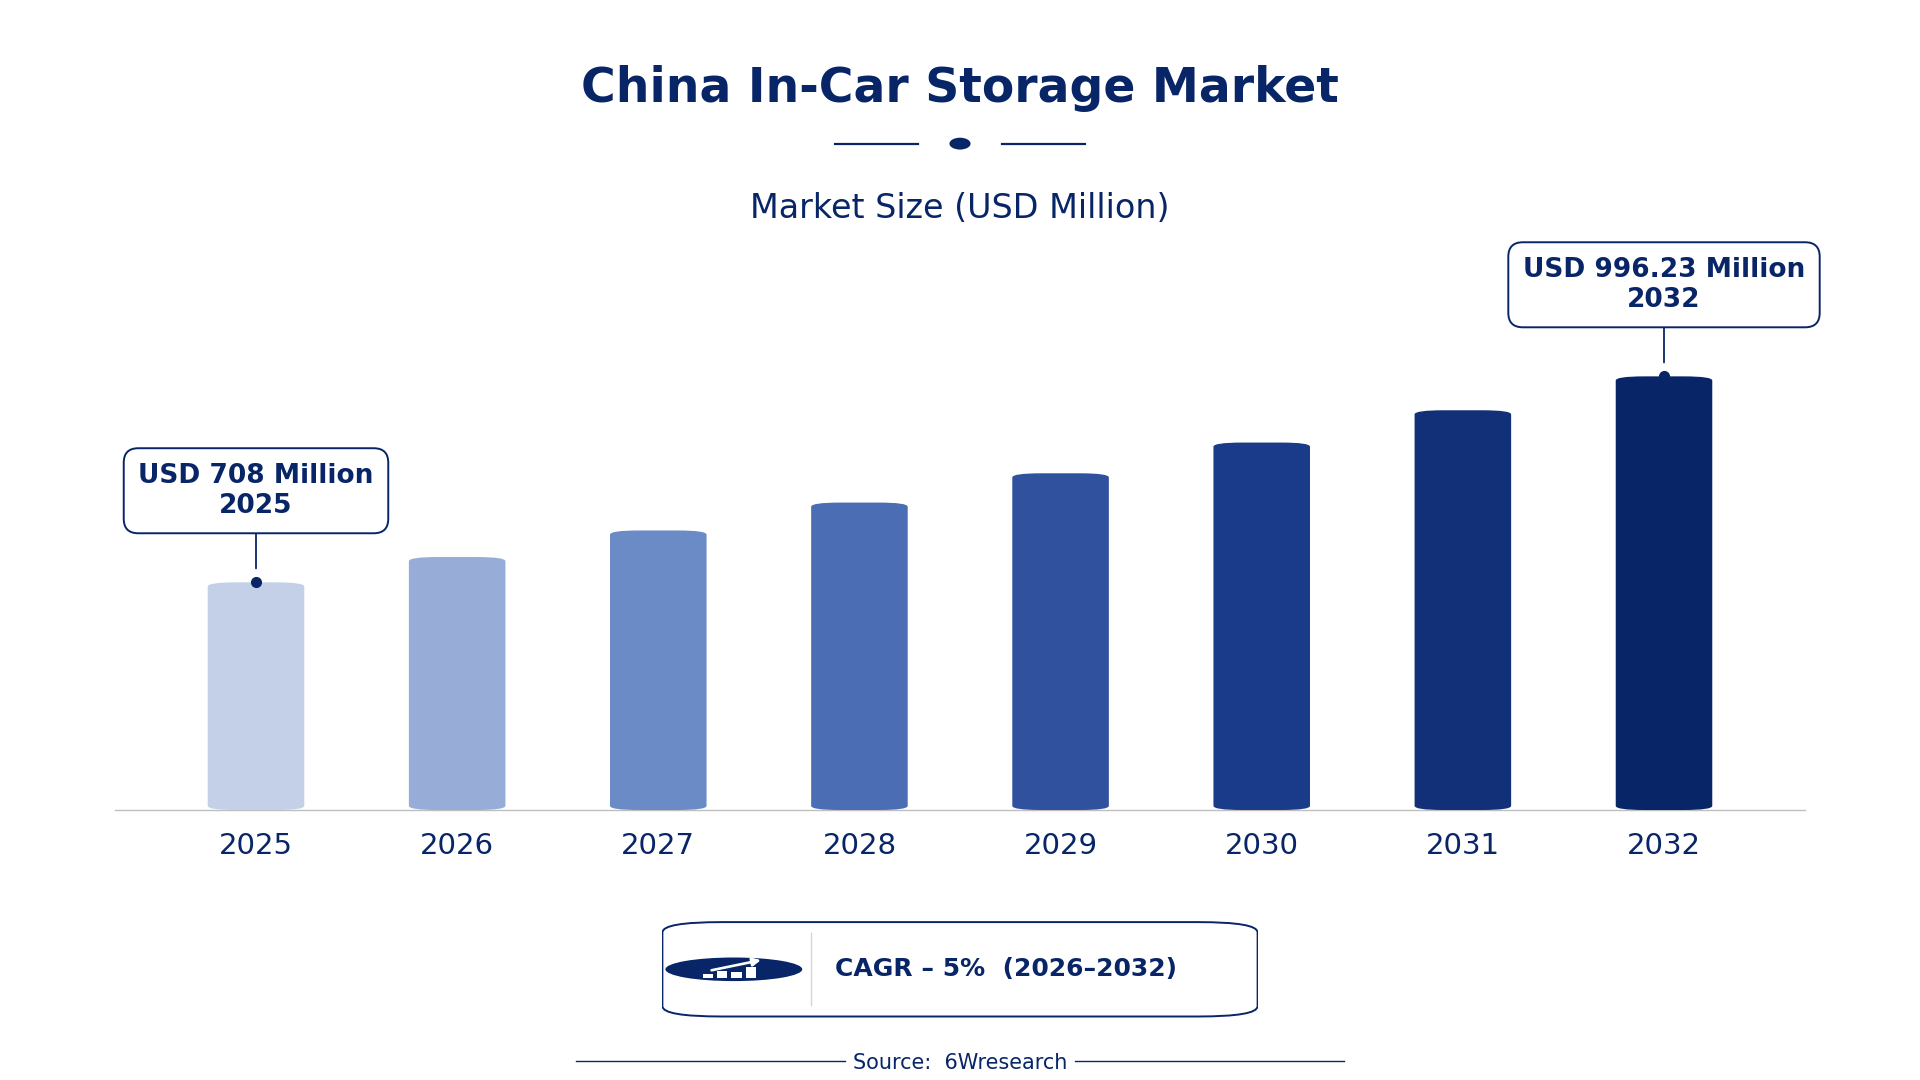
According to 6Wresearch internal database and industry insights, the China In-Car Storage Market was valued at USD 708.0 million in 2025 and is projected to reach USD 996.23 million by 2032, growing at a CAGR of approximately 5% during 2026–2032.
China In-Car Storage Market Highlights
| Report Metric | Details |
| Report Name | China In-Car Storage Market |
| Market Size 2025 | USD 708.0 million |
| Market Size 2032 | USD 996.23 million |
| Absolute Growth 2025–2032 | USD 288.23 million |
| CAGR 2026–2032 | 5% |
| Peak Annual Growth | 7.4% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Storage Type, 2025 | SSD (Automotive-Grade) (43% share) |
| Leading Form Factor, 2025 | Integrated Memory (40% share) |
| Leading Capacity Range, 2025 | 128–512 GB (52% share) |
| Leading End User, 2025 | Infotainment Manufacturers (37% share) |
| Fastest-Growing Form Factor | High-Speed Flash (6.1% CAGR) |
| Fastest-Growing Capacity Range | 16–128 GB (6.0% CAGR) |
| Fastest-Growing End User | Connected Vehicle Platforms (6.4% CAGR) |
| Growing Sector | automotive manufacturing |
| Key End Users | Infotainment Manufacturers, Navigation System Makers, Data Logging OEMs, Connected Vehicle Platforms |
China In-Car Storage Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
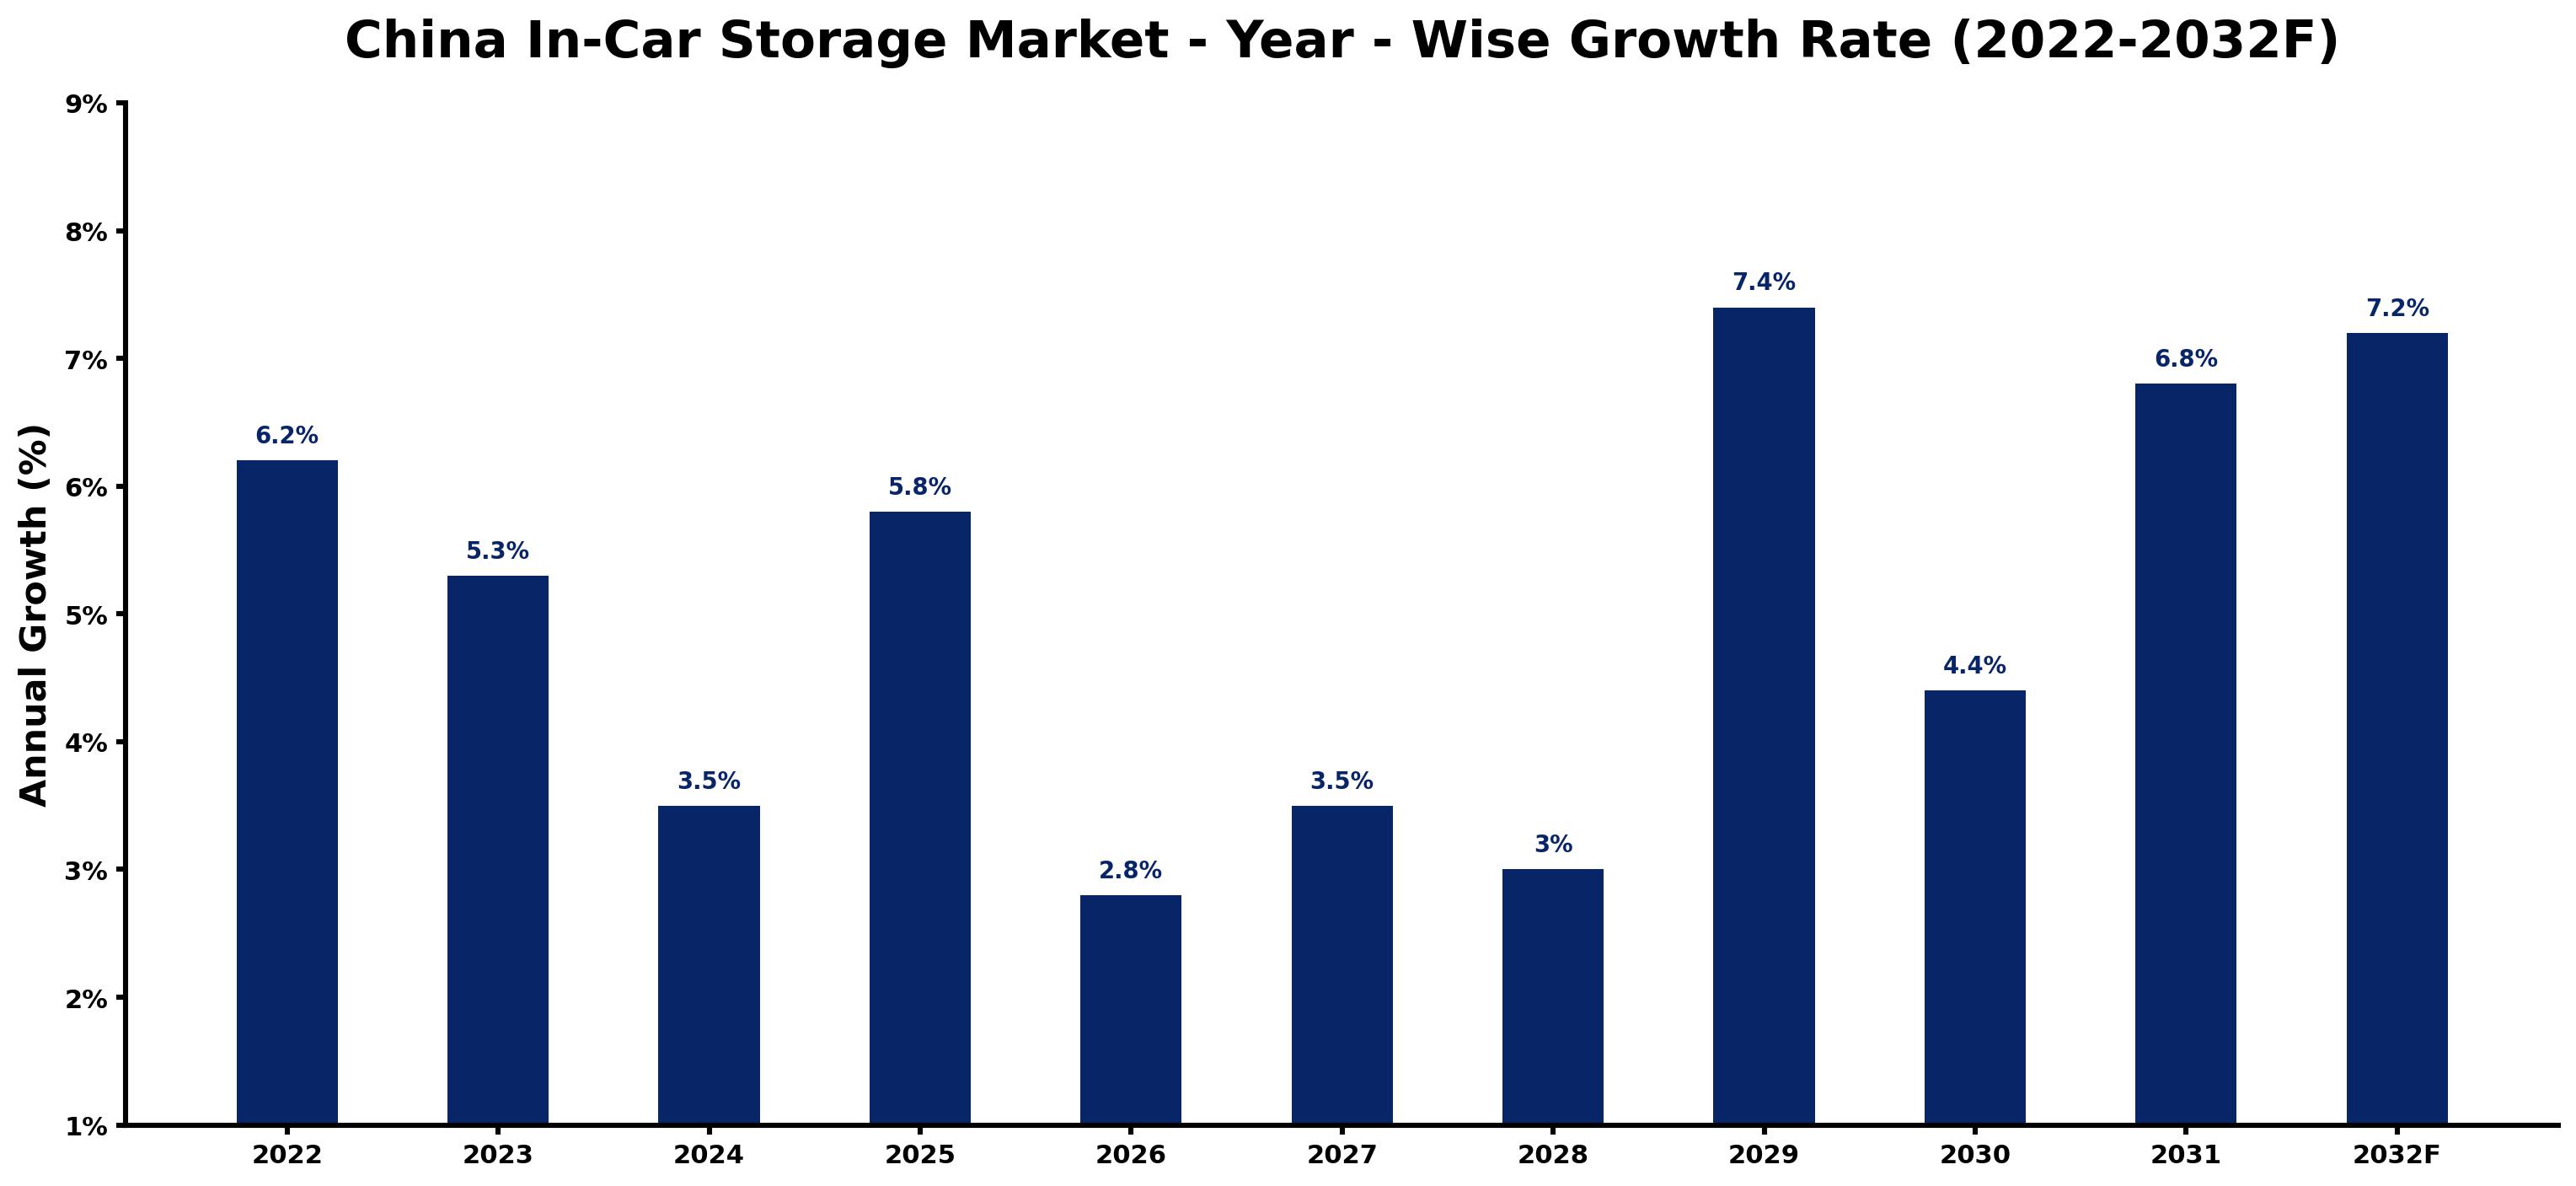
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.2 | The automotive sector produced over 26 million vehicles, driving demand for storage solutions. |
| 2023 | 5.3 | Growth slowed as manufacturers adjusted to supply chain challenges affecting production. |
| 2024 | 3.5 | Market growth continued to slow due to increasing competition among storage technologies. |
| 2025 | 5.8 | Demand increased as vehicle connectivity expanded, leading to higher storage requirements. |
| 2026 | 2.8 | Growth is expected to decelerate as manufacturers face challenges integrating advanced technologies. |
| 2027 | 3.5 | A rise in demand for connected vehicles is projected to spur growth in storage solutions. |
| 2028 | 3.0 | Market growth is expected to slow as manufacturers focus on cost efficiencies and technology integration. |
| 2029 | 7.4 | Demand is projected to surge due to the introduction of new smart vehicle technologies and standards. |
| 2030 | 4.4 | Growth is expected to slow as the market stabilises after rapid technological advancements. |
| 2031 | 6.8 | Increased vehicle production and connectivity will drive demand for in-car storage solutions. |
| 2032 | 7.2 | A focus on high-capacity storage options is projected to continue boosting market growth. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China In-Car Storage Market Synopsis
The In-Car Storage Market in China encompasses various memory solutions used in vehicles, including flash memory and cloud integration. These solutions are essential for infotainment systems, navigation aids, and data logging. The market is growing due to the automotive sector, which produced over 26 million vehicles in 2022, and increasing vehicle connectivity. Demand is driven by domestic manufacturers and a national push for smart vehicle technologies, including the 2021 Smart Vehicle Innovation Development Strategy. Infotainment Manufacturers and Navigation System Makers are key buyer groups, further propelling the market's expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising vehicle production and connectivity requirements | Driver | High | SSD (Automotive-Grade) |
| Growing demand for high-speed data access in vehicles | Driver | High | High-Speed Flash |
| Expansion of smart vehicle technology initiatives | Opportunity | High | Connected Vehicle Platforms |
| Increasing demand for high-capacity storage solutions | Opportunity | Medium | Embedded eMMC |
| Competition from alternative storage solutions | Restraint | High | SD Card Storage |
| Challenges in integrating new technologies in vehicles | Restraint | Medium | SSD (Automotive-Grade) |
| Supply chain disruptions affecting production timelines | Challenge | High | Infotainment Manufacturers |
| High costs associated with advanced storage technologies | Challenge | Medium | Navigation System Makers |
Evaluation of Drivers in China In-Car Storage Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased vehicle production | SSD (Automotive-Grade) | In 2022, over 26 million vehicles were produced, increasing demand for high-speed storage. |
| Growing vehicle connectivity | High-Speed Flash | The average vehicle now features 32 GB of embedded storage, driving demand for faster solutions. |
| National initiatives promoting smart vehicles | Connected Vehicle Platforms | The 2021 Smart Vehicle Innovation Development Strategy aims to support automotive technology development. |
| Rising consumer expectations for infotainment systems | Embedded eMMC | As infotainment systems evolve, demand for integrated storage solutions increases. |
| Technological advancements in data management | Infotainment Manufacturers | Innovations in automotive technology are driving the need for more efficient data storage. |
In 2022, over 26 million vehicles were produced, which raised the demand for high-speed storage solutions. The average vehicle is now equipped with 32 GB of embedded storage, reflecting rising consumer expectations for infotainment systems. The 2021 Smart Vehicle Innovation Development Strategy aims to support automotive technology, increasing the need for integrated storage solutions. As technological advancements continue, the demand for efficient data management in vehicles will also rise.
Evaluation of Restraints in China In-Car Storage Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Competition from alternative storage solutions | SD Card Storage | The presence of various storage options limits market share for SD card solutions, affecting sales. |
| Integration challenges with new technologies | SSD (Automotive-Grade) | Manufacturers face difficulties in incorporating advanced storage technologies into existing systems. |
| Supply chain disruptions | Infotainment Manufacturers | Ongoing supply chain issues delay production timelines, impacting the availability of in-car storage. |
| High costs of advanced storage technologies | Navigation System Makers | The expense associated with advanced storage solutions can deter investment from manufacturers. |
| Market saturation in lower-end segments | Embedded eMMC | As the market matures, growth in lower-end segments becomes increasingly difficult. |
China In-Car Storage Market Challenges
The China In-Car Storage Market encounters several practical issues, with technology integration being a primary concern. Many vehicles still depend on outdated data storage solutions, limiting functionality and performance for automotive manufacturers. This technological lag can delay product launches by up to six months for producers. Cost pressures arise as the average vehicle now requires 32 GB of embedded storage, increasing production expenses for suppliers. Competition intensifies as domestic manufacturers innovate quickly, compelling suppliers to reduce prices or risk losing contracts. A skills gap in advanced semiconductor technology complicates suppliers' ability to meet the rising demand for high-performance storage solutions.
Trends in the China In-Car Storage Market
Four trends stand out in the China In-Car Storage Market.
- Shift Towards Higher Capacity Storage: Infotainment Manufacturers are increasingly adopting higher capacity storage solutions, with many vehicles now featuring 256 GB options. This shift is driven by the need for improved data management and connectivity, reflecting a growing trend in the automotive sector.
- Transition to Cloud-Based Storage Solutions: Cloud-based storage solutions are gaining traction in the automotive sector, particularly for connected vehicles. This trend is supported by the 2023 Connected Vehicle Development Plan, which emphasises the importance of data management in modern vehicles.
- Emergence of Advanced Data Management Standards: ISO/IEC 7816 standards are shaping automotive data storage practices in China. These standards ensure secure automotive applications, impacting how manufacturers approach data management.
- Focus on Integrated Memory Solutions: The automotive industry is prioritising integrated memory solutions, essential for operation in vehicles. This trend is evident in the Guangdong province, a major hub for automotive manufacturing.
Investment Opportunities in the China In-Car Storage Market
Below are the investment opportunities with the strongest case in the China In-Car Storage Market.
- Guangdong Province as a Manufacturing Hub: Guangdong province is a key area for automotive manufacturing, presenting opportunities for suppliers of in-car storage solutions. With over 26 million vehicles produced in 2022, companies can enter through local partnerships.
- Growing Demand for Smart Vehicle Technologies: The increasing focus on smart vehicle technologies creates an opportunity for storage solution providers. The 2021 Smart Vehicle Innovation Development Strategy aims to support automotive technology development, encouraging investments in advanced storage.
- Investment in High-Speed Data Solutions: Investing in high-speed data storage solutions is essential as consumer expectations rise. Infotainment Manufacturers are seeking storage options to meet the demand for advanced infotainment systems.
- Approval Pathways for Advanced Technologies: Navigating approval pathways for advanced storage technologies is vital for market entry. The National Key R&D Program supports projects focused on automotive data storage innovations.
Government Initiatives in the China In-Car Storage Market
The 'Smart Vehicle Innovation Development Strategy' launched by the Ministry of Industry and Information Technology in 2021 significantly impacts in-car storage solutions by promoting advanced automotive technologies. This strategy aims to enhance the integration of data storage systems within vehicles, ensuring they meet modern connectivity demands. The 'Automotive Industry Development Policy' updated in 2020 by the National Development and Reform Commission further supports this initiative by encouraging the adoption of innovative storage technologies. Together, these measures are designed to improve the safety and performance standards of automotive data storage systems, benefiting both producers and buyers in the market.
The Ministry of Transport oversees the 'Connected Vehicle Development Plan,' which funds projects aimed at improving data management systems in vehicles. This plan ensures that manufacturers can access financial support for developing advanced in-car storage solutions. The State Administration for Market Regulation introduced the 'Automotive Data Management Regulations' in 2023, establishing guidelines that ensure data integrity and security in automotive storage. These regulations are crucial for manufacturers, as compliance is necessary for market entry and maintaining consumer trust in automotive data systems.
Future Insight of the China In-Car Storage Market
By 2032, the China In-Car Storage Market will undergo significant transformations as government initiatives and industry standards evolve. The national plan to enhance vehicle connectivity will necessitate more advanced data storage capabilities. Innovations presented at the Shanghai International Auto Show will drive the demand for higher storage capacities and faster access speeds. With the automotive-grade SSD market projected to grow, suppliers will need to align their offerings with the specific needs of connected vehicles, ensuring competitiveness in a fast-changing landscape.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Storage Type – SSD (Automotive-Grade) Dominated and Is Expected to Record the Fastest Growth
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, SSD (Automotive-Grade) took a 43% share of storage type in 2025, more than any other category. The SSD (Automotive-Grade) segment commands the largest market share due to its critical role in high-speed data access for modern vehicles. This demand is underscored by the automotive sector in China producing over 26 million vehicles in 2022, necessitating reliable storage solutions. The same category is also set to grow fastest, at a CAGR of 7.5% during 2026–2032. The SSD (Automotive-Grade) segment is also the fastest-growing, fuelled by the increasing average capacity of automotive SSDs, with many vehicles now featuring options up to 256 GB. As government initiatives promote smart vehicle technology, this segment's lead is expected to widen further. Suppliers should focus on advancing SSD technologies to meet the rising demand for high-performance in-car storage solutions.
By Form Factor – Integrated Memory Dominated, High-Speed Flash Expected to Grow Fastest
In 2025, Integrated Memory led the form factor split with a 40% share. Integrated Memory holds the largest market share as it is fundamental for the seamless operation of automotive applications, ensuring efficient data processing. This form factor is essential for infotainment systems that require fast and reliable data retrieval. High-Speed Flash is set to record the highest CAGR in this split, 6.1% over 2026–2032. High-Speed Flash is the fastest-growing segment, vital for performance in data-intensive applications such as connected vehicles. The increasing emphasis on vehicle connectivity drives demand for this form factor, indicating a shift towards more advanced storage solutions. Buyers should consider investing in high-speed flash solutions to improve the performance of their data-intensive automotive applications.
By Capacity Range – 128–512 GB Dominated, 16–128 GB Expected to Grow Fastest
128–512 GB accounted for a 52% market share by capacity range in 2025. The 128–512 GB capacity range leads the market share as it is increasingly utilised for high-performance systems in modern vehicles. This range effectively addresses the needs of advanced infotainment systems and connected vehicle technologies that demand substantial data storage. 16–128 GB is projected to grow fastest, at a CAGR of 6.0% during 2026–2032. The 16–128 GB capacity range is the fastest-growing segment, commonly used for standard applications in vehicles. As more vehicles integrate basic connectivity features, this capacity range is expected to see significant adoption. Suppliers should offer a variety of capacity options to cater to both high-performance and standard applications in vehicles.
By End User – Infotainment Manufacturers Dominated, Connected Vehicle Platforms Expected to Grow Fastest
Infotainment Manufacturers held a 37% share of the China In-Car Storage Market by end user in 2025. Infotainment Manufacturers dominate the market share as they are the primary users of in-car storage solutions, significantly influencing the demand for advanced storage technologies. The robust automotive sector in China, producing over 26 million vehicles, highlights the importance of this user group. Over 2026–2032, Connected Vehicle Platforms are expected to post the fastest growth, at a CAGR of 6.4%. Connected Vehicle Platforms represent the fastest-growing end user segment, essential for data management and connectivity in modern vehicles. The push for enhanced vehicle connectivity, supported by recent government initiatives, is driving this segment's rapid growth. Suppliers should align their strategies to support the evolving needs of connected vehicle platforms to capture emerging market opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China In-Car Storage Market Outlook
- Market Size of China In-Car Storage Market, 2025
- Forecast of China In-Car Storage Market, 2032
- Historical Data and Forecast of China In-Car Storage Revenues & Volume for the Period 2022 - 2032F
- China In-Car Storage Market Trend Evolution
- China In-Car Storage Market Drivers and Challenges
- China In-Car Storage Price Trends
- China In-Car Storage Porter's Five Forces
- China In-Car Storage Industry Life Cycle
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By Storage Type for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By Embedded eMMC for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By SD Card Storage for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By SSD (Automotive-Grade) for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By Cloud-Based Cache for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By Form Factor for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By Integrated Memory for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By Replaceable for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By High-Speed Flash for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By Edge Computing for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By Capacity Range for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By 16 128 GB for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By 16 64 GB for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By 128 512 GB for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By Dynamic Scaling for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By Infotainment Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By Navigation System Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By Data Logging OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China In-Car Storage Market Revenues & Volume By Connected Vehicle Platforms for the Period 2022 - 2032F
- China In-Car Storage Import Export Trade Statistics
- Market Opportunity Assessment By Storage Type
- Market Opportunity Assessment By Form Factor
- Market Opportunity Assessment By Capacity Range
- Market Opportunity Assessment By End User
- China In-Car Storage Top Companies Market Share
- China In-Car Storage Competitive Benchmarking By Technical and Operational Parameters
- China In-Car Storage Company Profiles
- China In-Car Storage Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Storage Type
- Embedded eMMC
- SD Card Storage
- SSD (Automotive-Grade)
- Cloud-Based Cache
By Form Factor
- Integrated Memory
- Replaceable
- High-Speed Flash
- Edge Computing
By Capacity Range
- 16–128 GB
- 16–64 GB
- 128–512 GB
- Dynamic Scaling
By End User
- Infotainment Manufacturers
- Navigation System Makers
- Data Logging OEMs
- Connected Vehicle Platforms































