China Industrial Aluminium Market Size & Growth Rate
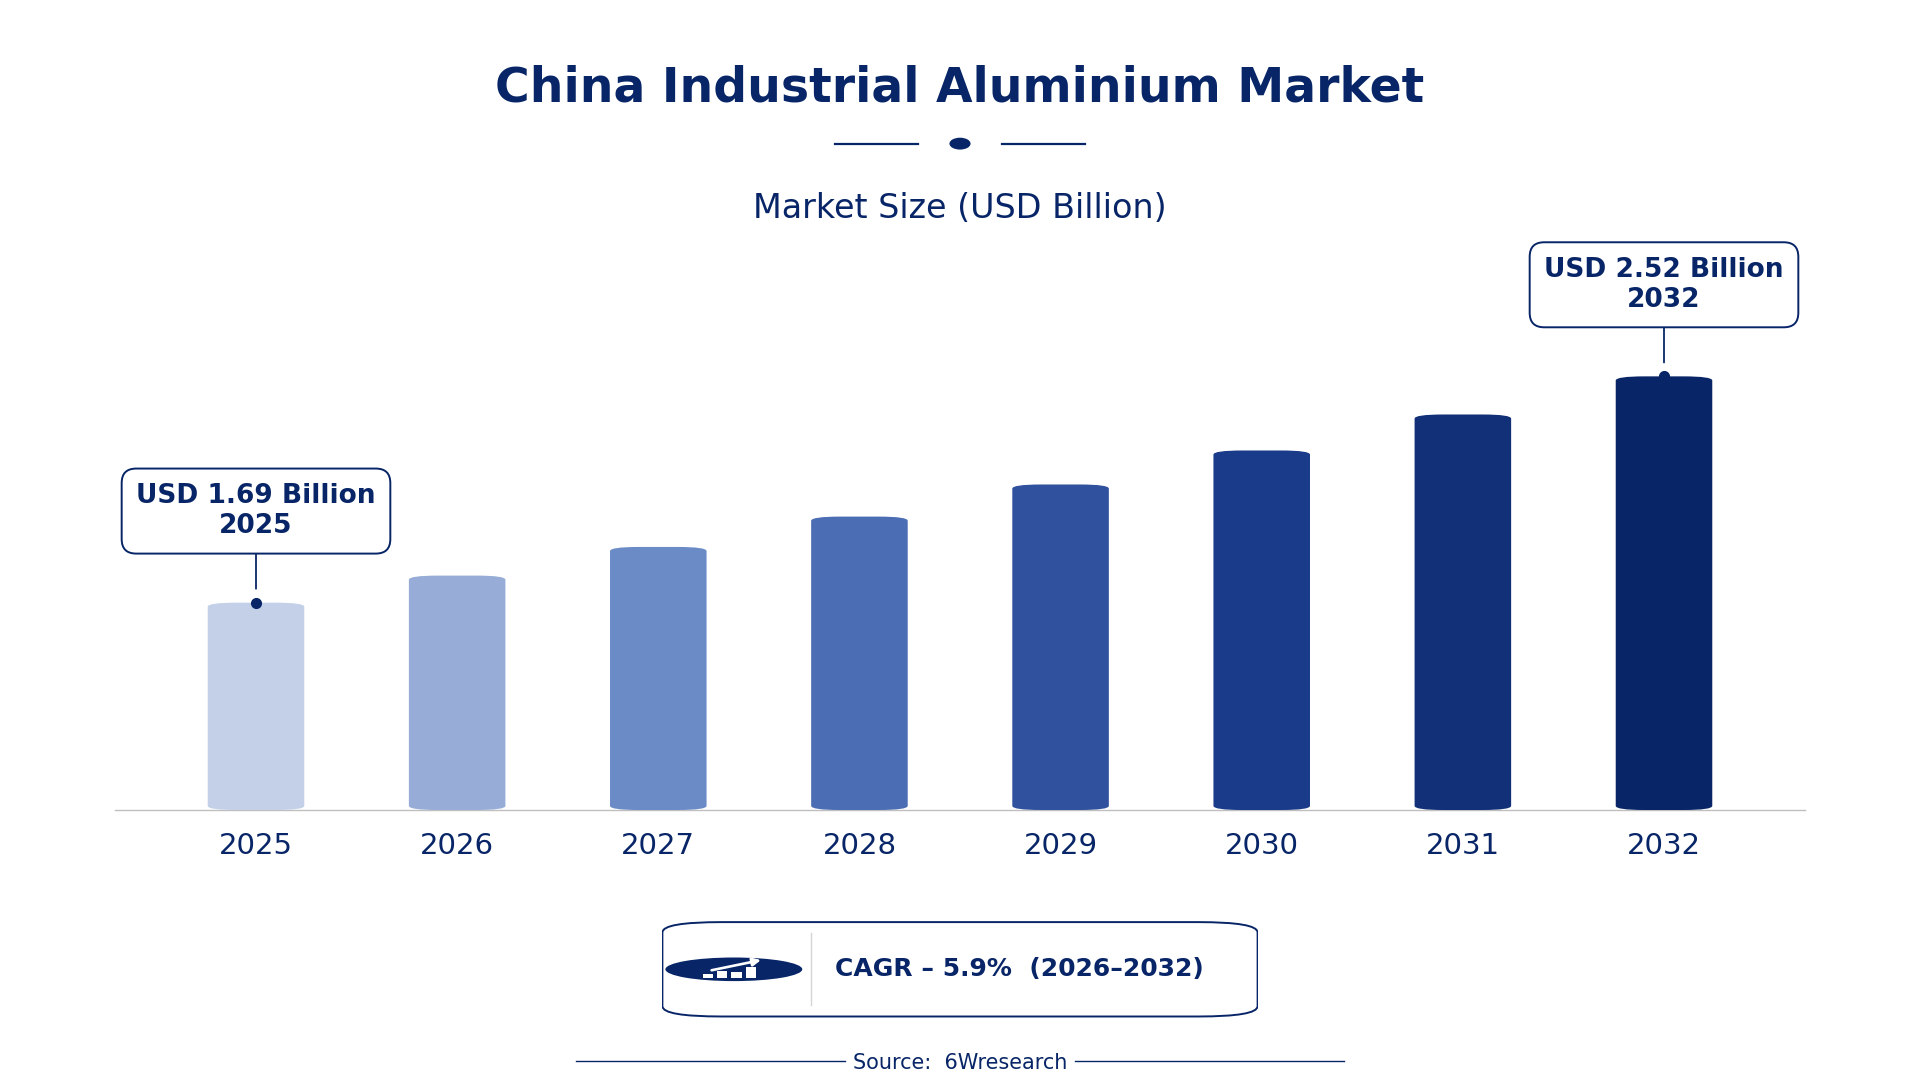
According to 6Wresearch internal database and industry insights, the China Industrial Aluminium Market was valued at USD 1.69 billion in 2025 and is projected to reach USD 2.52 billion by 2032, growing at a CAGR of approximately 5.9% during 2026–2032.
China Industrial Aluminium Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Aluminium Market |
| Market Size 2025 | USD 1.69 billion |
| Market Size 2032 | USD 2.52 billion |
| Absolute Growth 2025–2032 | USD 0.83 billion |
| CAGR 2026–2032 | 5.9% |
| Peak Annual Growth | 8.0% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Product Type, 2025 | Rolled Aluminium (43% share) |
| Leading Processing Form, 2025 | Sheets & Plates (46% share) |
| Leading Application Segment, 2025 | Construction & Auto (52% share) |
| Leading End User, 2025 | Vehicle Manufacturers (51% share) |
| Fastest-Growing Product Type | Aluminium Foil (8.5% CAGR) |
| Fastest-Growing Processing Form | Thin Sheets (7.7% CAGR) |
| Fastest-Growing Application Segment | Packaging Industry (7.4% CAGR) |
| Fastest-Growing End User | Food & Pharma Manufacturers (7.1% CAGR) |
| Growing Sector | Packaging Industry |
| Key End Users | Construction & Auto, Machinery Components, Packaging Industry, Railways & Aerospace |
China Industrial Aluminium Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
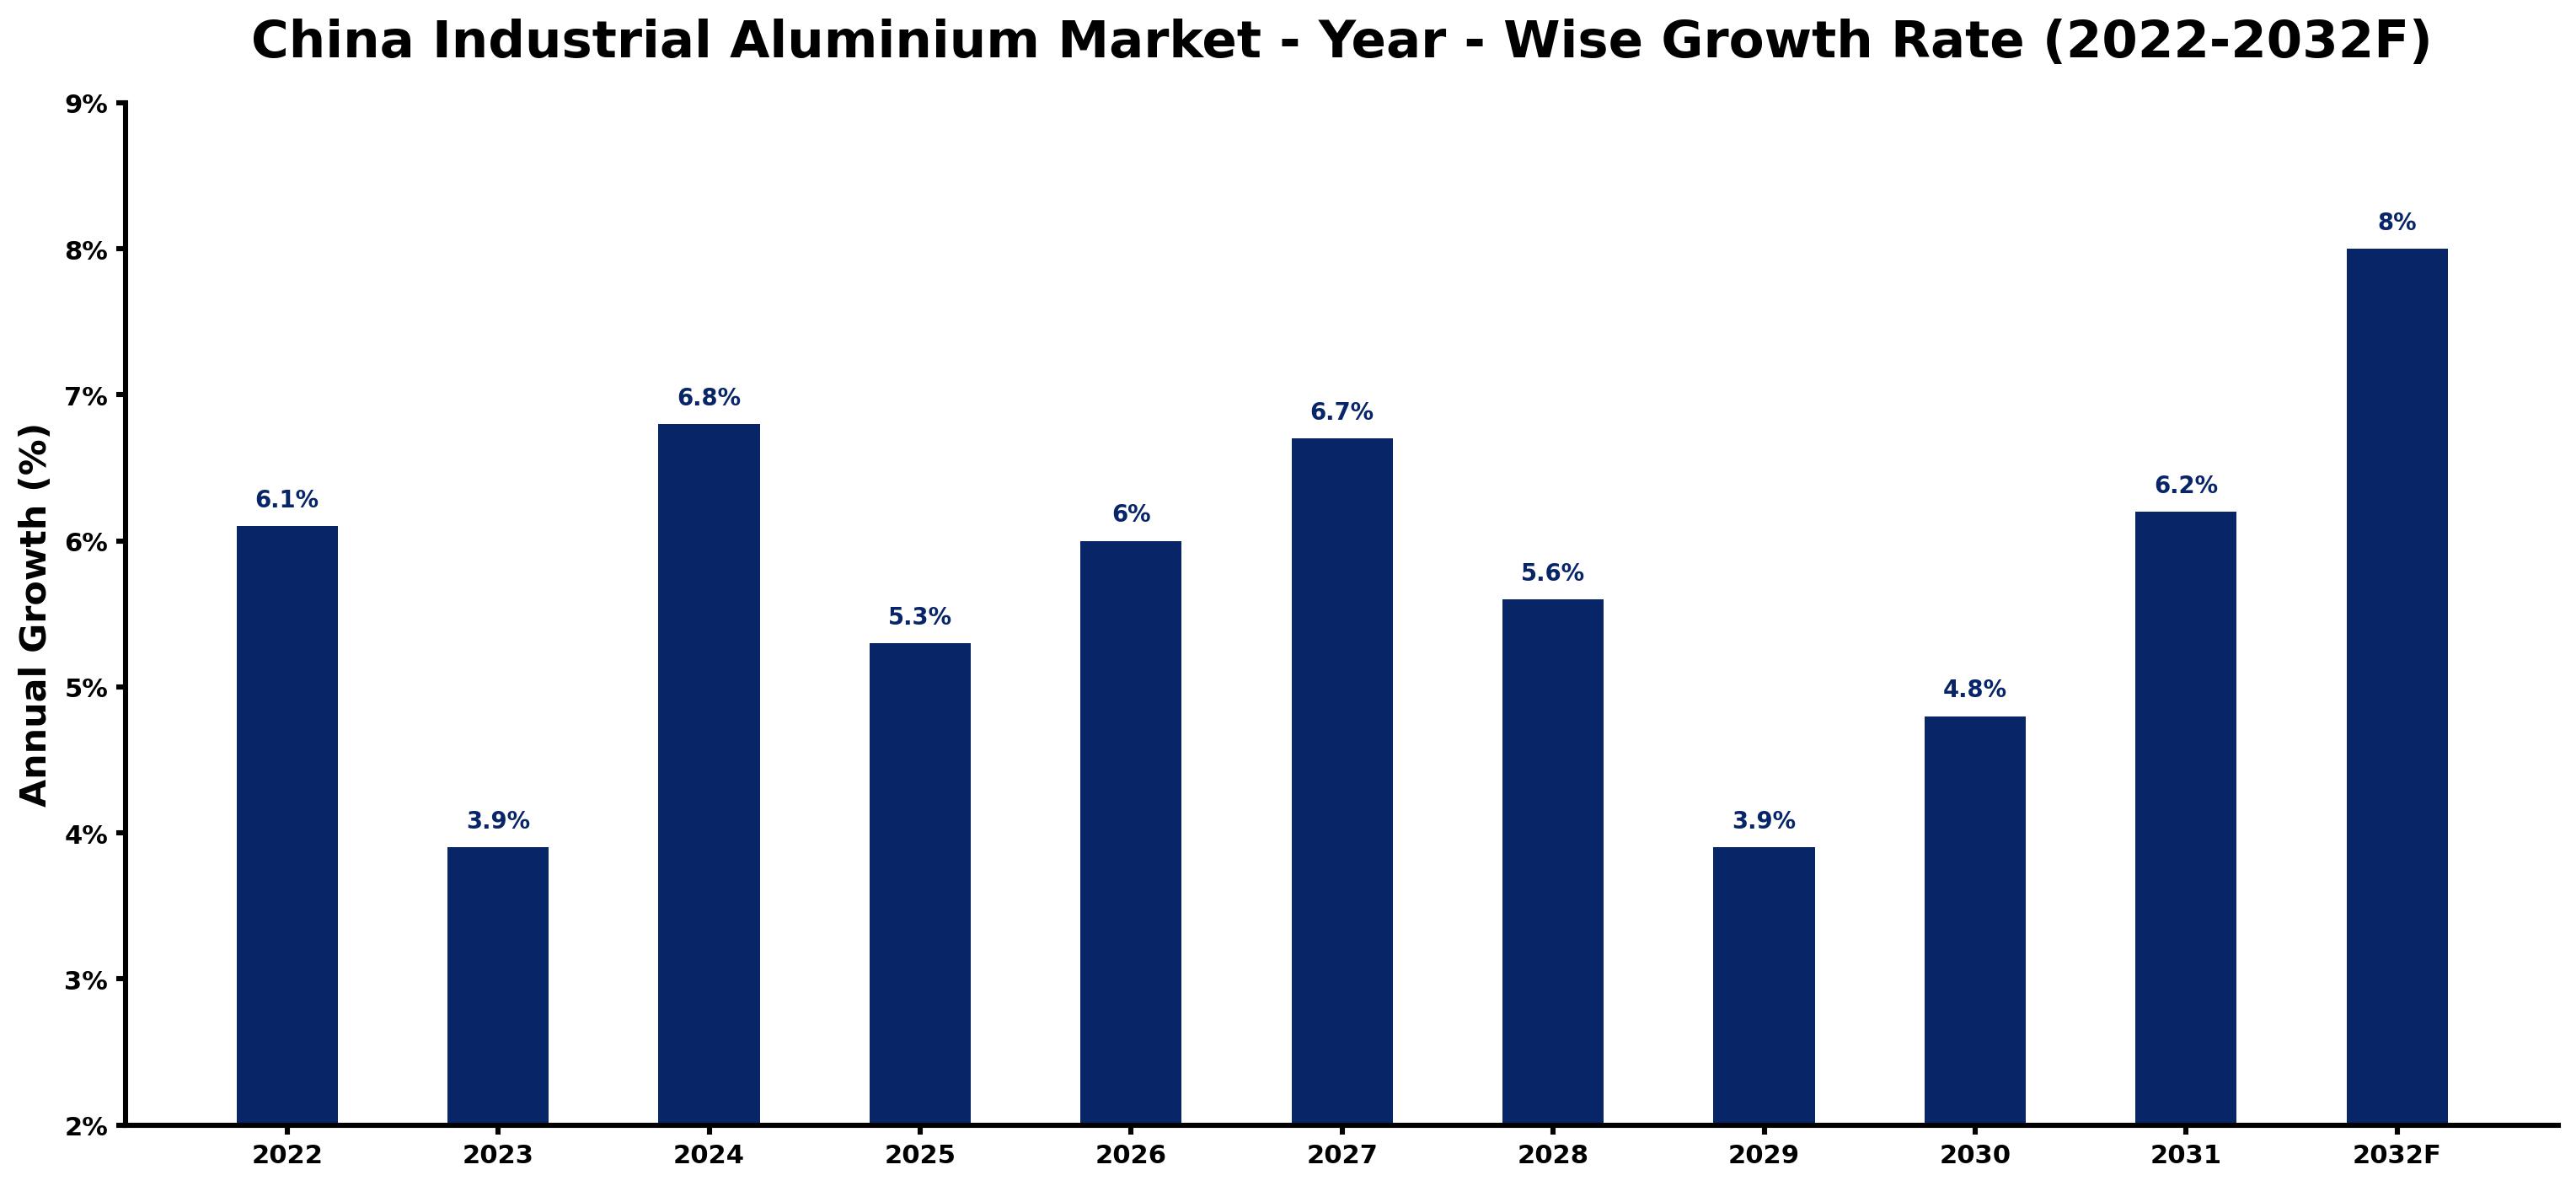
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.1 | The market experienced solid growth due to strong demand from the construction sector. |
| 2023 | 3.9 | Growth slowed as the automotive industry faced temporary production challenges. |
| 2024 | 6.8 | Demand surged as infrastructure projects ramped up, boosting aluminium consumption. |
| 2025 | 5.3 | Growth decelerated as the automotive sector adjusted to new standards. |
| 2026 | 6.0 | The construction sector's expansion is projected to drive higher aluminium demand from infrastructure firms. |
| 2027 | 6.7 | Increased vehicle production will support rising aluminium consumption in automotive applications. |
| 2028 | 5.6 | Market growth is anticipated to slow as demand stabilises following previous peaks in construction projects. |
| 2029 | 3.9 | The automotive sector's demand growth is expected to decelerate, impacting overall market performance. |
| 2030 | 4.8 | Construction projects are likely to increase, driving aluminium purchases again from infrastructure firms. |
| 2031 | 6.2 | Rising demand from vehicle manufacturers is anticipated to support market growth. |
| 2032 | 8.0 | The market is projected to peak as infrastructure investments reach new heights. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Aluminium Market Synopsis
Industrial Aluminium in China encompasses a versatile metal used in construction, transportation, and packaging. Produced through processes like smelting and rolling, its lightweight and corrosion-resistant properties make it ideal for various applications. The China Industrial Aluminium Market is expanding due to strong domestic demand, particularly from the construction sector, which accounts for over 40% of aluminium consumption. The automotive industry is projected to consume 10 million tonnes by 2025, further driving market growth. This growth is supported by ongoing infrastructure projects and technological advancements in aluminium processing.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Strong domestic demand from the construction sector drives aluminium purchases. | Driver | High | Construction & Auto |
| Growing vehicle production increases the demand for aluminium components. | Driver | High | Vehicle Manufacturers |
| Aluminium recycling initiatives present opportunities for sustainable production. | Opportunity | Medium | Rolled Aluminium |
| The growing packaging industry requires more aluminium for consumer products. | Opportunity | High | Packaging Industry |
| Fluctuating raw material prices can impact production costs. | Restraint | High | Rolled Aluminium |
| Environmental regulations may impose additional compliance costs. | Restraint | Medium | Rolled Aluminium |
| The China Industrial Aluminium Market faces challenges from fluctuating demand. | Challenge | High | Rolled Aluminium |
| Technological advancements in production processes may require significant investment. | Challenge | Medium | Rolled Aluminium |
Evaluation of Drivers in China Industrial Aluminium Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased infrastructure spending fuels demand for aluminium sheets and plates. | Sheets & Plates | The construction sector accounted for over 40% of aluminium demand in China in 2022. |
| Rising vehicle manufacturing necessitates more extruded aluminium components. | Extruded Aluminium | Vehicle manufacturers are projected to consume 10 million tonnes of aluminium by 2025. |
| Growing demand for packaging materials drives aluminium foil production. | Aluminium Foil | Aluminium foil production reached 2 million tonnes in 2022. |
| Technological advancements in aluminium processing improve production efficiency. | Rolled Aluminium | The Guangdong province is a major hub for aluminium processing, enhancing production capabilities. |
| The push for sustainable practices increases recycling of aluminium products. | Rolled Aluminium | The National Development and Reform Commission supports aluminium recycling initiatives, boosting supply. |
Expansion of the Industrial Aluminium market in China is backed by rising domestic demand from construction and automotive sectors. The construction sector accounted for over 40% of aluminium demand in 2022, driving purchases of sheets and plates. Vehicle manufacturers are expected to consume 10 million tonnes of aluminium by 2025, increasing the need for extruded components. Aluminium foil production reached 2 million tonnes in 2022, reflecting growth in the packaging industry. Advances in processing methods are improving efficiency, particularly in the Guangdong province, a key processing hub for aluminium.
Evaluation of Restraints in China Industrial Aluminium Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Fluctuating raw material prices can lead to increased production costs. | Rolled Aluminium | The volatility in aluminium prices affects profit margins for manufacturers, impacting their financial stability. |
| Environmental regulations may impose additional compliance costs. | Rolled Aluminium | Producers must invest in sustainable practices to meet regulatory standards, increasing operational expenses. |
| Limited recycling infrastructure can restrict the supply of recycled aluminium. | Rolled Aluminium | The need for improved recycling facilities hampers growth in this segment, affecting supply availability. |
| Competition from alternative materials may limit aluminium's market share. | Rolled Aluminium | Substitutes like plastics and composites are increasingly used in construction, challenging aluminium's position. |
| Trade policies can affect the import and export dynamics of aluminium. | Rolled Aluminium | Changes in tariffs impact the cost structure for manufacturers, influencing pricing strategies. |
China Industrial Aluminium Market Challenges
The China Industrial Aluminium Market faces several practical problems, beginning with a skills shortage among workers in the aluminium processing sector. This gap arises from a lack of specialised training programmes, which delays production timelines for manufacturers. Rising input costs present another challenge, as raw material prices have surged by 15% over the past year, squeezing profit margins for suppliers. Technological limitations also hinder efficiency; many facilities still rely on outdated machinery, which can reduce output by 20%. Supply chain disruptions from global events have caused delays in raw material deliveries, resulting in production halts for producers.
Trends in the China Industrial Aluminium Market
The trends below show where the China Industrial Aluminium Market is heading.
- Shift Towards Sustainable Aluminium Production: The 'Green Manufacturing Standard' introduced in 2023 encourages environmentally friendly aluminium production methods. This initiative aims for a 30% increase in recycled aluminium by 2025, promoting sustainability in the industry.
- Growth in Aluminium Foil Demand: Aluminium foil production has surged, reaching 2 million tonnes in 2022. This growth is driven by the packaging industry's increasing need for lightweight and durable materials.
- Increased Focus on Recycling Initiatives: The 'National Circular Economy Development Strategy' updated in 2022 aims to improve aluminium recycling efforts. This initiative targets a 30% increase in recycled aluminium by 2025, supporting sustainable practices.
- Technological Advancements in Aluminium Processing: The 'Aluminium Industry Innovation and Development Plan' approved in 2020 aims to boost technological advancements in aluminium processing. This plan is expected to improve production efficiency by 2025.
Investment Opportunities in the China Industrial Aluminium Market
Some of the investment opportunities in the China Industrial Aluminium Market are mentioned below.
- Construction Firms Seeking Aluminium Solutions: With over 40% of aluminium demand from the construction sector, firms need reliable aluminium suppliers. The Guangdong province offers a strong industrial base for partnerships, facilitating market entry.
- Automotive Industry's Growing Aluminium Needs: The automotive industry is projected to consume 10 million tonnes of aluminium by 2025, creating opportunities for suppliers. Collaboration with vehicle manufacturers can facilitate market entry and expand reach.
- Rising Demand for Packaging Materials: The packaging industry requires more aluminium, with production reaching 2 million tonnes in 2022. Suppliers can target this sector by establishing local partnerships for distribution and logistics.
- Investment in Recycling Infrastructure: The push for increased aluminium recycling presents a notable opportunity. Investing in recycling facilities in urban areas can cater to the growing demand for sustainable materials, enhancing supply chain efficiency.
Government Initiatives in the China Industrial Aluminium Market
The 'Green Manufacturing Standard' introduced in 2023 by the Ministry of Ecology and Environment encourages environmentally friendly aluminium production methods. This measure builds on the '14th Five-Year Plan for the Development of the Aluminium Industry' launched in 2021, which promotes sustainable practices across the sector. Together, these initiatives aim to improve the industry's environmental performance and reduce its carbon footprint, benefiting producers and buyers alike.
The Ministry of Industry and Information Technology oversees the implementation of the 'National Circular Economy Development Strategy', which improves aluminium recycling efforts. This strategy targets a 30% increase in recycled aluminium by 2025, benefiting manufacturers who adopt sustainable practices. Additionally, the '2023 National Aluminium Industry Conference' attracted over 1,000 professionals, fostering collaboration and innovation in the sector, enhancing knowledge sharing and partnerships.
Future Insight of the China Industrial Aluminium Market
The China Industrial Aluminium Market is set for significant changes by 2032, driven by advancements in recycling technologies and increasing domestic demand. The construction sector is expected to consume over 40% of aluminium production, prompting suppliers to enhance their offerings. New ISO 9001 standards will improve quality control across the industry, ensuring better compliance and operational efficiency. Government initiatives supporting aluminium recycling will create a more sustainable supply chain, providing long-term benefits for both buyers and suppliers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Product Type – Rolled Aluminium Dominated, Aluminium Foil Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, the largest product type category in 2025 was Rolled Aluminium, with a 43% share of total revenue. Rolled Aluminium holds the largest market share due to its extensive applications in construction and automotive sectors, where it is crucial for structural integrity and vehicle lightweighting. The construction sector alone accounts for over 40% of aluminium demand in China, highlighting its significance. The quickest growth will come from Aluminium Foil, forecast to expand at a CAGR of 8.5% between 2026 and 2032. Aluminium Foil is seeing rapid growth driven by its increasing use in packaging, particularly for food preservation. In 2022, production reached 2 million tonnes, indicating a strong upward trend in consumer goods packaging. Suppliers should focus on ramping up aluminium foil production to meet the surging demand in the packaging sector.
By Processing Form – Sheets & Plates Dominated, Thin Sheets Expected to Grow Fastest
In 2025, Sheets & Plates led the processing form split with a 46% share. Sheets & Plates dominate the market share as they are essential for various applications in construction and manufacturing. Their critical role in building projects ensures a steady demand from builders and manufacturers alike. Thin Sheets are projected to grow fastest, at a CAGR of 7.7% during 2026–2032. Thin Sheets are experiencing the fastest growth, largely due to their application in lightweight structures and packaging solutions. The trend towards efficiency is driving the demand for these materials significantly. Buyers should consider sourcing thin sheets to capitalise on the increasing trend for lightweight and efficient materials.
By Application Segment – Construction & Auto Dominated, Packaging Industry Expected to Grow Fastest
Construction & Auto accounted for a 52% market share by application segment in 2025. The Construction & Auto segment leads the market share, driven by substantial aluminium use in building projects and vehicle manufacturing. With aluminium sheets used in over 50% of new urban building projects, this segment remains robust and vital. Packaging Industry is set to record the highest CAGR in this split, 7.4% over 2026–2032. The Packaging Industry is the fastest-growing segment, largely due to rising demand for aluminium in food and consumer product packaging. This growth is supported by China's expanding population and consumer goods market. Suppliers should prioritise the packaging sector to align with the rapid growth in aluminium demand for packaging applications.
By End User – Vehicle Manufacturers Dominated, Food & Pharma Manufacturers Expected to Grow Fastest
Vehicle Manufacturers held a 51% share of the China Industrial Aluminium Market by end user in 2025. Vehicle Manufacturers represent the largest share of the market as they are primary users of aluminium in automotive production, leveraging it for lightweighting and fuel efficiency. This sector's growth is crucial for sustaining overall aluminium demand in the market. Over 2026–2032, Food & Pharma Manufacturers are expected to post the fastest growth, at a CAGR of 7.1%. Food & Pharma Manufacturers are the fastest-growing end user segment, primarily due to their increasing reliance on aluminium for specialised packaging solutions. As health and safety regulations tighten, this segment's demand is expected to rise significantly. Suppliers should explore partnerships with food and pharma manufacturers to tap into the expanding market for specialised aluminium packaging.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Aluminium Market Outlook
- Market Size of China Industrial Aluminium Market, 2025
- Forecast of China Industrial Aluminium Market, 2032
- Historical Data and Forecast of China Industrial Aluminium Revenues & Volume for the Period 2022 - 2032F
- China Industrial Aluminium Market Trend Evolution
- China Industrial Aluminium Market Drivers and Challenges
- China Industrial Aluminium Price Trends
- China Industrial Aluminium Porter's Five Forces
- China Industrial Aluminium Industry Life Cycle
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Rolled Aluminium for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Extruded Aluminium for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Cast Aluminium for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Aluminium Foil for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Processing Form for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Sheets & Plates for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Profiles & Tubes for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Foundry Products for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Thin Sheets for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Application Segment for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Construction & Auto for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Railways & Aerospace for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Machinery Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Packaging Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Infrastructure Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Vehicle Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Heavy Equipment OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Aluminium Market Revenues & Volume By Food & Pharma Manufacturers for the Period 2022 - 2032F
- China Industrial Aluminium Import Export Trade Statistics
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Processing Form
- Market Opportunity Assessment By Application Segment
- Market Opportunity Assessment By End User
- China Industrial Aluminium Top Companies Market Share
- China Industrial Aluminium Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Aluminium Company Profiles
- China Industrial Aluminium Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Product Type
- Rolled Aluminium
- Extruded Aluminium
- Cast Aluminium
- Aluminium Foil
By Processing Form
- Sheets & Plates
- Profiles & Tubes
- Foundry Products
- Thin Sheets
By Application Segment
- Construction & Auto
- Railways & Aerospace
- Machinery Components
- Packaging Industry
By End User
- Infrastructure Firms
- Vehicle Manufacturers
- Heavy Equipment OEMs
- Food & Pharma Manufacturers































