China Industrial Blasting Systems Market Size & Growth Rate
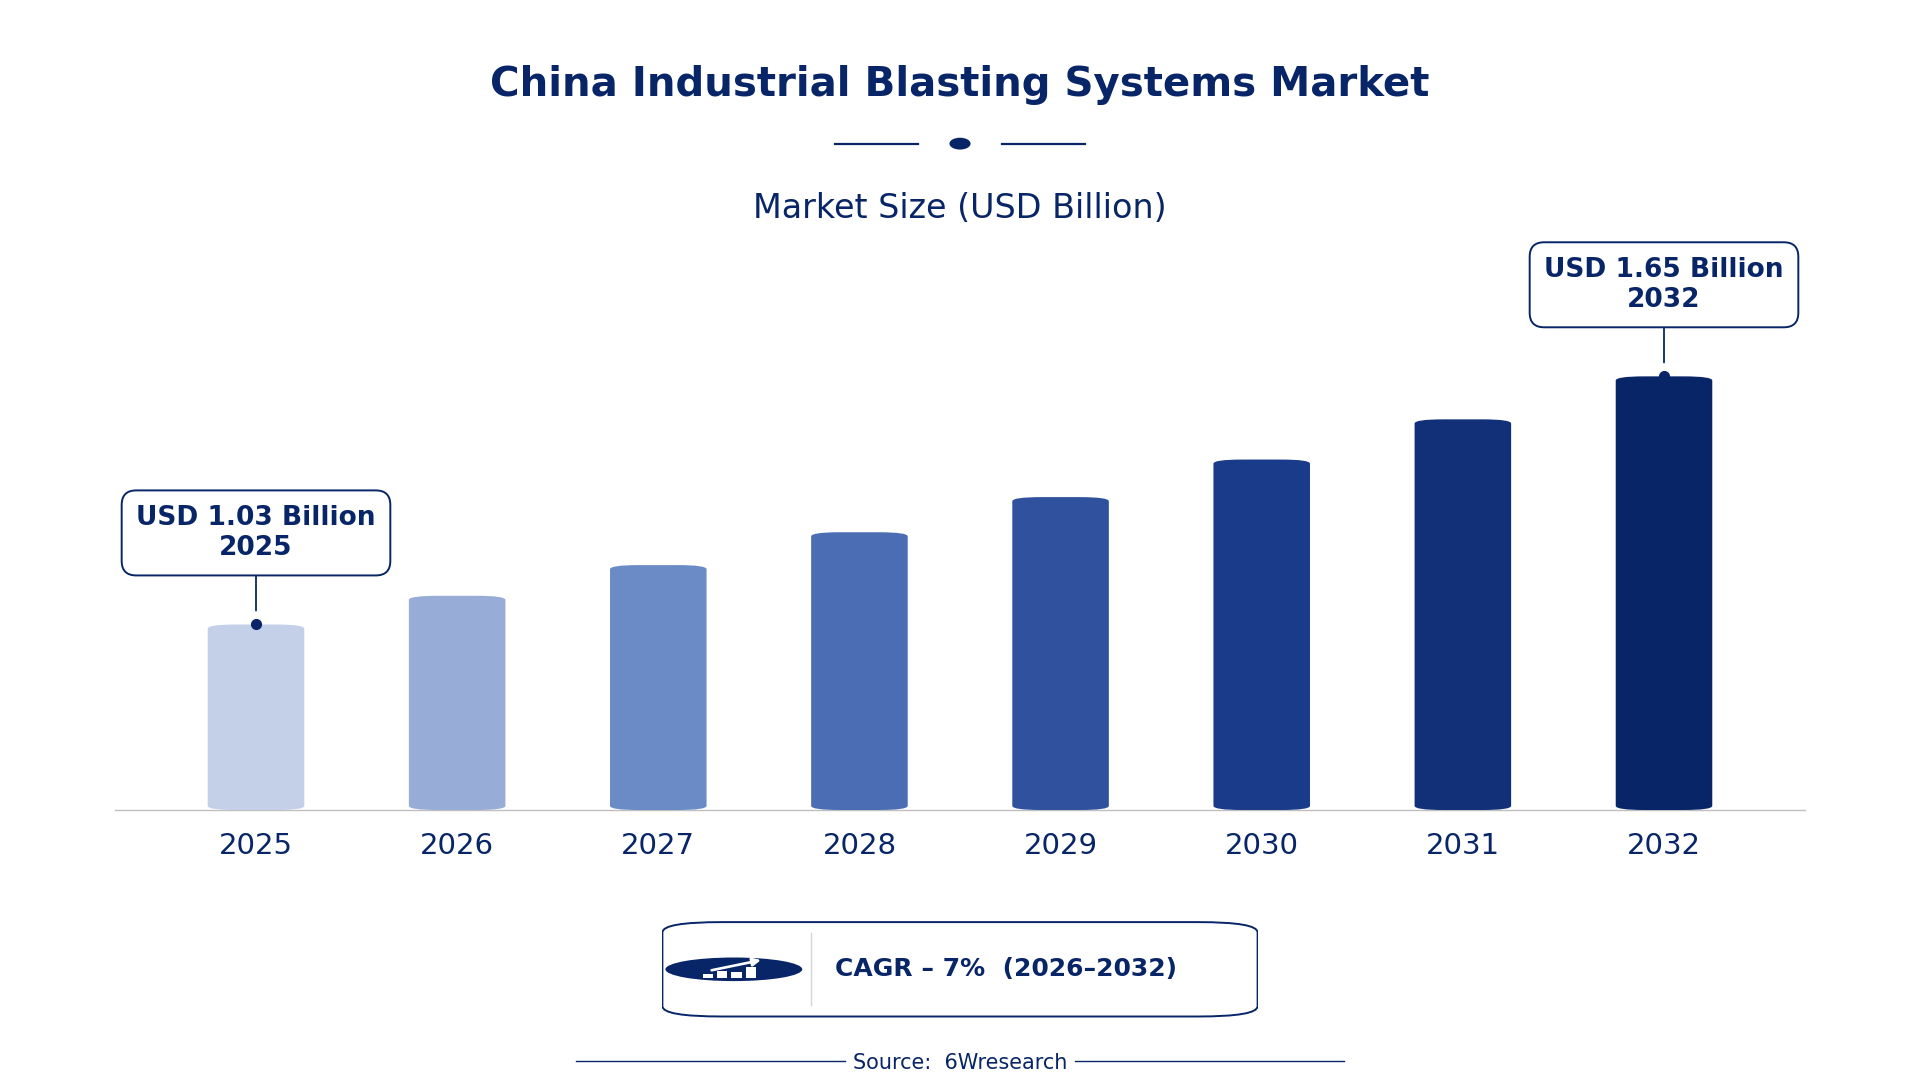
According to 6Wresearch internal database and industry insights, the China Industrial Blasting Systems Market was valued at USD 1.03 billion in 2025 and is projected to reach USD 1.65 billion by 2032, growing at a CAGR of approximately 7% during 2026–2032.
China Industrial Blasting Systems Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Blasting Systems Market |
| Market Size 2025 | USD 1.03 billion |
| Market Size 2032 | USD 1.65 billion |
| Absolute Growth 2025–2032 | USD 0.62 billion |
| CAGR 2026–2032 | 7% |
| Peak Annual Growth | 9.2% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Blasting Type, 2025 | Shot Blasting Machines (48% share) |
| Leading Media Used, 2025 | Silica (36% share) |
| Leading Operation Mode, 2025 | Manual or Automated (34% share) |
| Leading End User, 2025 | Shipbuilding Firms (34% share) |
| Fastest-Growing Blasting Type | Wet Blasting Systems (8.6% CAGR) |
| Fastest-Growing Media Used | Garnet (9.4% CAGR) |
| Fastest-Growing Operation Mode | Low Dust Applications (9.3% CAGR) |
| Fastest-Growing End User | Aerospace Components (9.7% CAGR) |
| Growing Sector | Shipbuilding |
| Key End Users | Shipbuilding Firms, Automotive Foundries, Aerospace Components, Art Restoration Units |
China Industrial Blasting Systems Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
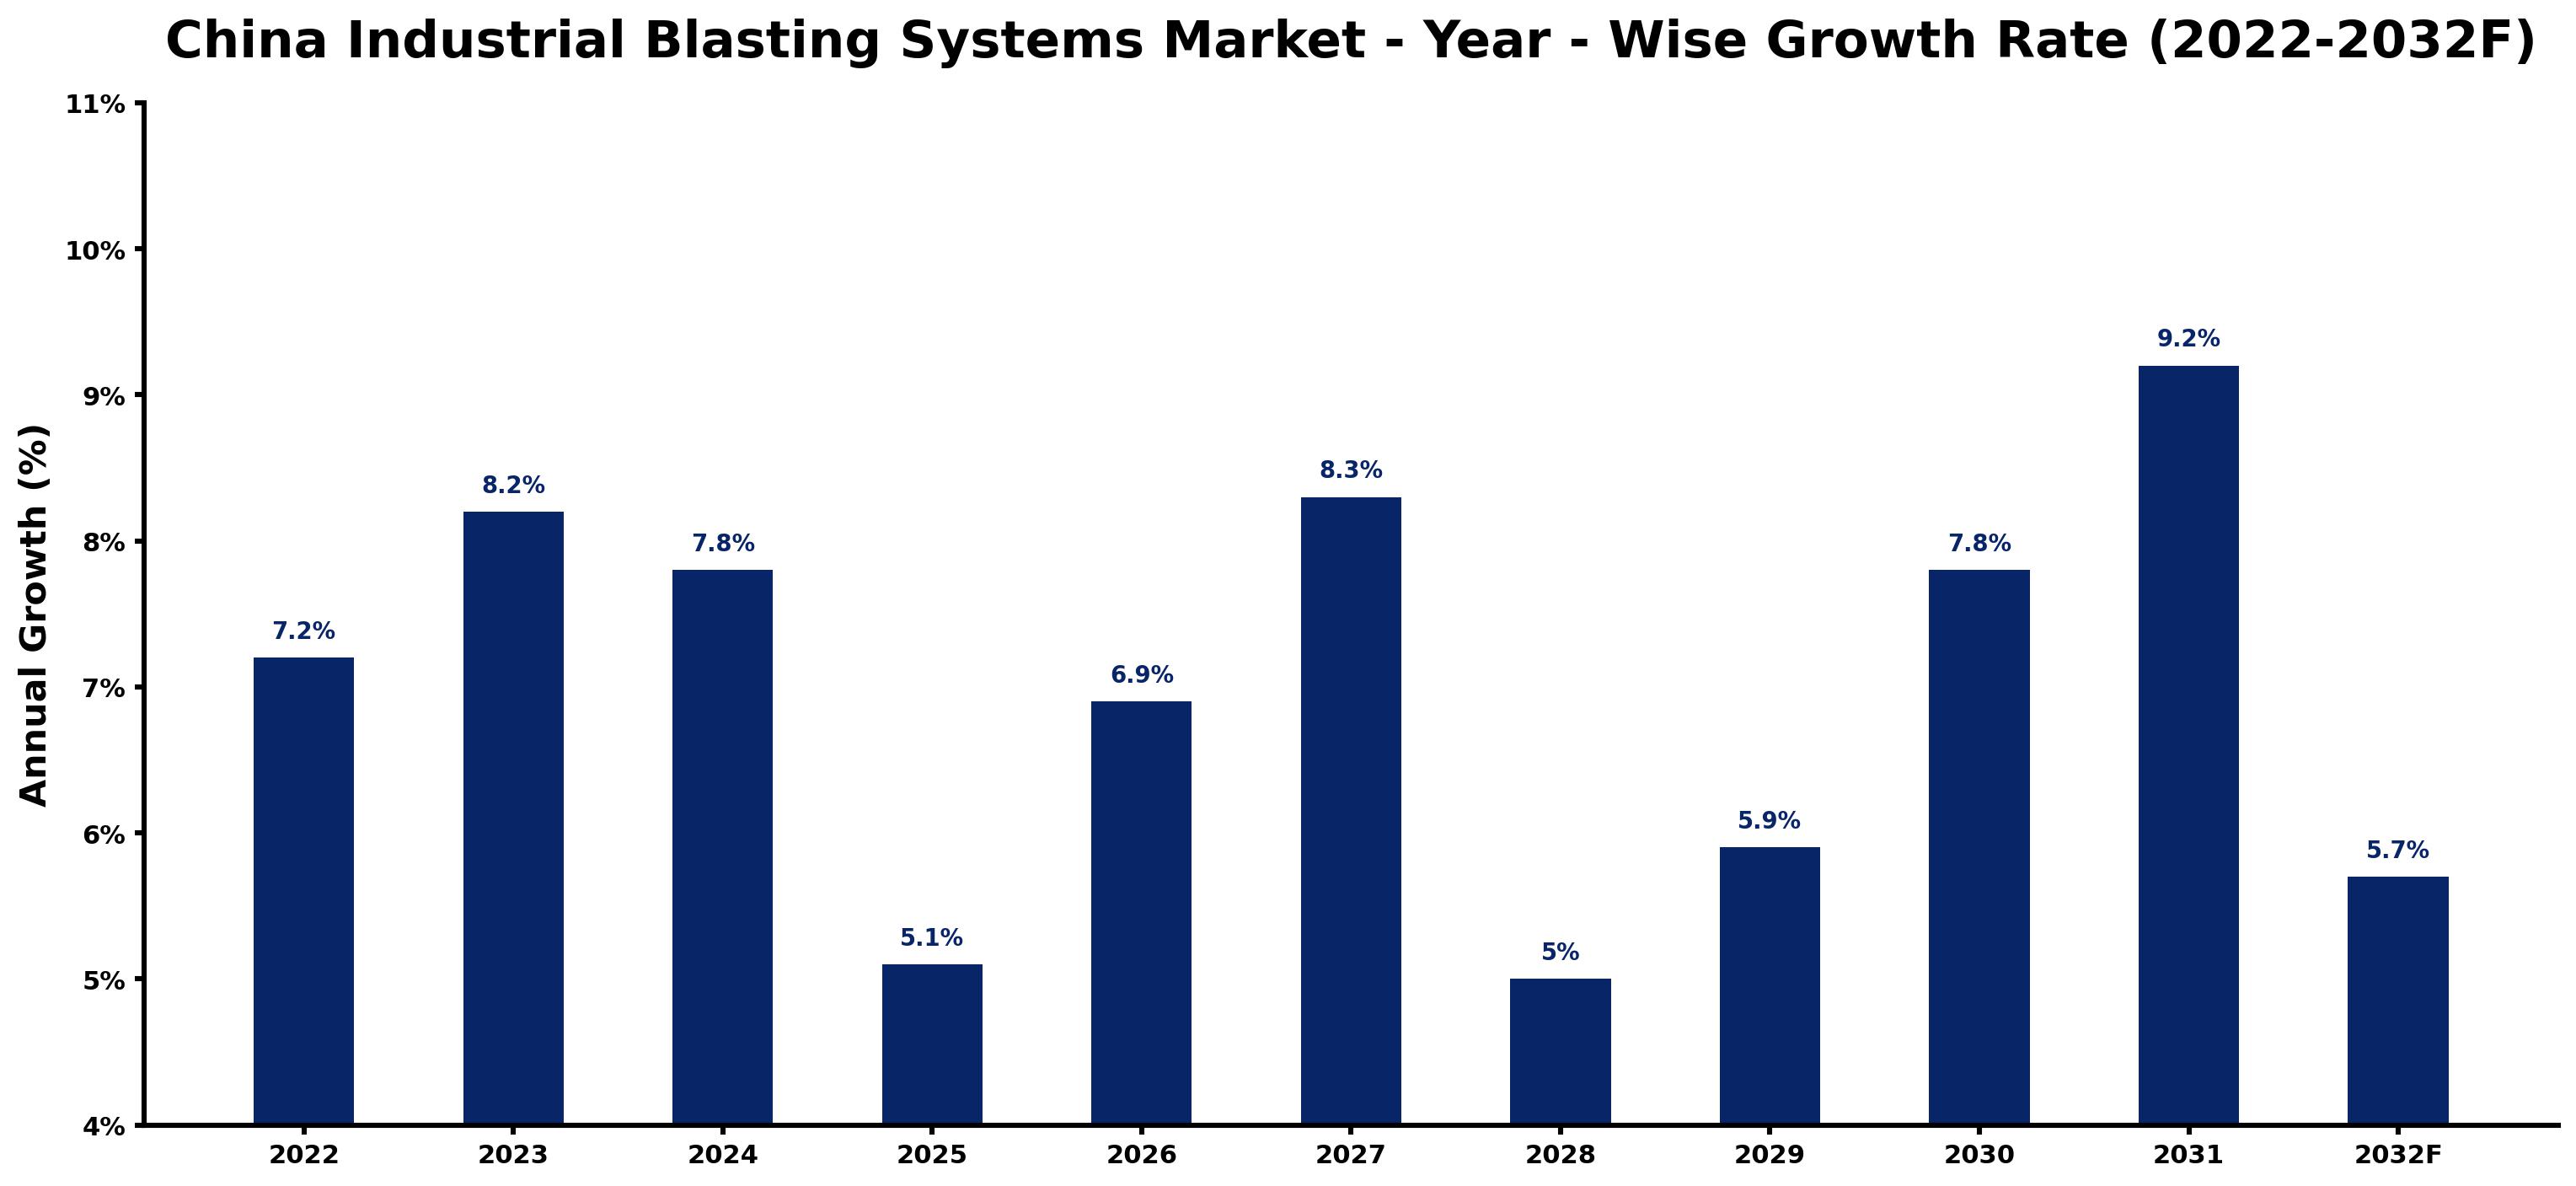
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.2 | The market showed steady activity, driven by ongoing demand from the shipbuilding sector. |
| 2023 | 8.2 | Growth accelerated due to increased production in the automotive industry, which boosted surface preparation needs. |
| 2024 | 7.8 | The market experienced a slowdown as demand stabilised after the previous year's surge in automotive production. |
| 2025 | 5.1 | Growth continued to decelerate as the market adjusted to previous high levels of activity. |
| 2026 | 6.9 | An uptick in growth occurred as investment in modernising industrial equipment is expected to gain momentum. |
| 2027 | 8.3 | Demand surged again, driven by rising orders from aerospace components manufacturing in key regions. |
| 2028 | 5.0 | The market slowed as growth stabilised following the previous year's rapid expansion due to increased production. |
| 2029 | 5.9 | A rebound in demand occurred as shipbuilding firms increased production capacity for new vessels. |
| 2030 | 7.8 | Growth accelerated again as stricter environmental regulations prompted upgrades to blasting systems. |
| 2031 | 9.2 | The market peaked due to heightened investments in advanced blasting technologies across industries. |
| 2032 | 5.7 | Growth slowed as the market adjusted to the peak levels of the previous year. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Blasting Systems Market Synopsis
Industrial Blasting Systems encompass technologies for surface preparation and cleaning in China, utilising abrasive materials like silica and garnet. These systems are essential in industries such as shipbuilding and automotive for tasks like paint removal and surface finishing. The China Industrial Blasting Systems Market is expanding due to increased production in shipbuilding, which generated over 1.2 million deadweight tons in 2022, and the automotive sector, producing over 25 million vehicles annually. Investment in modernising equipment, as seen in the 'Made in China 2025' initiative, further drives demand.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased production in the shipbuilding sector drives demand for surface preparation technologies. | Driver | High | Sandblasting Systems |
| Investment in modernising industrial equipment boosts the need for advanced blasting systems. | Driver | High | Shot Blasting Machines |
| Growing demand for eco-friendly blasting materials presents opportunities for suppliers. | Opportunity | High | Wet Blasting Systems |
| The rising automotive production creates a need for efficient surface cleaning solutions. | Opportunity | High | Automotive Foundries |
| Stricter environmental regulations may limit the use of certain abrasive materials. | Restraint | High | Silica |
| The high initial investment costs for advanced blasting systems can deter buyers. | Restraint | Medium | Shot Blasting Machines |
| Buyers face challenges in meeting stringent safety regulations for blasting operations. | Challenge | High | Wet Blasting Systems |
| Suppliers struggle with fluctuating raw material prices, impacting production costs. | Challenge | Medium | Sandblasting Systems |
Evaluation of Drivers in China Industrial Blasting Systems Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production in the shipbuilding industry drives demand for blasting systems. | Sandblasting Systems | China's shipbuilding industry produced over 1.2 million deadweight tons in 2022, leading to higher surface preparation needs. |
| Investment in modernising industrial equipment boosts the need for advanced blasting systems. | Shot Blasting Machines | In 2023, the government allocated 500 million CNY for upgrading industrial machinery, increasing demand for efficient systems. |
| Growing demand for eco-friendly blasting materials presents opportunities for suppliers. | Wet Blasting Systems | The use of garnet has increased to a 30% market share due to its environmental benefits, prompting more purchases. |
| The rising automotive production creates a need for efficient surface cleaning solutions. | Automotive Foundries | China's automotive sector produced over 25 million vehicles annually, necessitating advanced cleaning technologies. |
| Adoption of stricter environmental regulations encourages investment in cleaner blasting technologies. | Shot Blasting Machines | The 'Green Manufacturing System' initiative promotes sustainable practices, driving demand for compliant equipment. |
Market growth in China for Industrial Blasting Systems rests on increased production in the shipbuilding sector and investment in modernising industrial equipment. The shipbuilding industry produced over 1.2 million deadweight tons in 2022, leading to higher demand for surface preparation technologies. The automotive sector, producing over 25 million vehicles annually, necessitates advanced cleaning technologies.
Evaluation of Restraints in China Industrial Blasting Systems Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Stricter environmental regulations may limit the use of certain abrasive materials. | Silica | The 'Air Pollution Prevention and Control Action Plan' aims to reduce industrial dust emissions, affecting abrasive material choices. |
| The high initial investment costs for advanced blasting systems can deter buyers. | Shot Blasting Machines | Investment requirements can be substantial, impacting purchasing decisions for smaller firms. |
| Buyers face challenges in meeting stringent safety regulations for blasting operations. | Wet Blasting Systems | Compliance with updated safety standards increases operational costs for users. |
| Suppliers struggle with fluctuating raw material prices, impacting production costs. | Sandblasting Systems | Price volatility in raw materials affects the overall cost structure for manufacturers. |
| Limited availability of skilled technicians can hinder operational efficiency. | Shot Blasting Machines | The shortage of trained personnel affects maintenance and operation of advanced systems. |
China Industrial Blasting Systems Market Challenges
Buyers in the China Industrial Blasting Systems market face increased costs due to strict regulations like National Standard GB/T 21357-2008, which raises compliance expenses for manufacturers by approximately 10%. Suppliers struggle with pressure from low-cost imports, forcing local firms to cut profit margins by up to 15%. The automotive sector, producing over 25 million vehicles annually, experiences delays in surface preparation due to a shortage of skilled technicians, which can extend production timelines by weeks. Additionally, the shift towards environmentally friendly methods, such as wet blasting systems, requires significant investment, putting financial strain on smaller producers and hindering their market competitiveness.
Trends in the China Industrial Blasting Systems Market
The trends below show where the China Industrial Blasting Systems Market is heading.
- Shift towards Eco-Friendly Blasting Materials: The use of garnet as an abrasive has increased to a 30% market share due to its environmental benefits. This shift aligns with the 'Green Manufacturing System' initiative, prompting suppliers to adapt their offerings.
- Increased Adoption of Wet Blasting Systems: Wet blasting systems are gaining popularity due to stricter environmental regulations in urban areas. Adoption rates have risen as these systems reduce dust emissions and improve surface quality.
- Growing Demand for Automated Blasting Solutions: Automated blasting systems are becoming more prevalent as industries seek efficiency. The shift towards automation is reflected in the increasing share of automated systems in production processes.
- Expansion of Safety Regulations in Blasting Operations: The updated 'Regulations on the Safety of Industrial Equipment' in 2023 have tightened safety standards for blasting operations. Compliance is essential for manufacturers to maintain operational licenses.
Investment Opportunities in the China Industrial Blasting Systems Market
Below are the investment opportunities with the strongest case in the China Industrial Blasting Systems Market.
- Investment in Advanced Blasting Technologies: With the government's allocation of 500 million CNY for upgrading industrial machinery, there is an opportunity for suppliers of advanced blasting systems. Collaborating with local manufacturers can facilitate market entry.
- Supply of Eco-Friendly Abrasive Materials: The rising demand for eco-friendly blasting materials presents an opportunity, especially for suppliers of garnet. Engaging with manufacturers in the automotive sector can enhance market presence.
- Expansion into Aerospace Components Cleaning: The shift towards automation in blasting operations creates a demand for automated systems. Suppliers can enter the market by collaborating with technology firms to develop innovative solutions.
- Growth in Shipbuilding Sector: The shipbuilding industry is expected to continue expanding, with production increasing. This growth presents opportunities for suppliers to provide advanced blasting systems tailored to shipbuilding needs.
Government Initiatives in the China Industrial Blasting Systems Market
The 'Air Pollution Prevention and Control Action Plan' issued by the Ministry of Ecology and Environment in 2021 aims to reduce industrial dust emissions, impacting blasting operations. This measure requires producers to adopt cleaner technologies and materials. The '14th Five-Year Plan for Industrial Development' launched by the National Development and Reform Commission in 2021 emphasises cleaner production technologies, including blasting systems, which encourages investment in modern equipment. The 'Green Manufacturing System' initiative established by the Ministry of Industry and Information Technology in 2022 promotes sustainable practices in manufacturing, including the use of eco-friendly blasting materials. These laws collectively drive the industry towards more sustainable practices.
Buyers in the industrial blasting systems market benefit from the subsidy program announced by the Ministry of Finance in 2023, which allocates 300 million CNY for upgrading industrial machinery. This funding supports manufacturers in enhancing operational capabilities and adopting advanced technologies. The State Administration for Market Regulation oversees compliance with updated safety standards, ensuring that equipment meets stringent operational requirements. These initiatives provide a framework for improving safety and efficiency in blasting operations.
Future Insight of the China Industrial Blasting Systems Market
Several forward-looking factors should support the China Industrial Blasting Systems market in the coming years. The 'Made in China 2025' initiative will drive modernization, leading to improved manufacturing processes. Investment in industrial equipment upgrades is expected to rise, with over 500 million CNY allocated for enhancing operational capabilities. The increased focus on environmentally sustainable practices will accelerate the adoption of safer blasting methods, aligning with stricter regulations and attracting a wider range of buyers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Blasting Type – Shot Blasting Machines Dominated, Wet Blasting Systems Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, the largest blasting type category in 2025 was Shot Blasting Machines, with a 48% share of total revenue. Shot blasting machines hold the largest market share due to their critical function in cleaning and finishing metal parts, especially in the shipbuilding industry. With over 50,000 units installed across various facilities, they are integral to maintaining high operational standards. Over 2026–2032, Wet Blasting Systems are expected to post the fastest growth, at a CAGR of 8.6%. Wet blasting systems are experiencing rapid growth as urban areas implement stricter environmental regulations, necessitating effective dust control solutions. This trend is supported by increased investments aimed at promoting safer and more environmentally friendly blasting methods. Suppliers must prioritise the development of environmentally compliant blasting technologies to capitalise on the growing demand in the market.
By Media Used – Silica Dominated, Garnet Expected to Grow Fastest
In 2025, Silica led the media used split with a 36% share. Silica holds the largest market share as it is the most commonly used abrasive material in blasting processes, particularly in heavy industries. Its widespread availability and effectiveness make it a staple for many users. Garnet is set to record the highest CAGR in this split, 9.4% over 2026–2032. Garnet is rapidly gaining popularity due to its low dust generation and effectiveness, making it a preferred choice among environmentally conscious users. This trend is likely to accelerate as regulations become more stringent. Buyers may benefit from exploring alternative abrasives like garnet to align with environmental standards and improve operational safety.
By Operation Mode – Manual or Automated Dominated, Low Dust Applications Expected to Grow Fastest
Manual or Automated held a 34% share of the China Industrial Blasting Systems Market by operation mode in 2025. The manual or automated operation mode holds the largest share due to its versatility in meeting diverse operational needs across various industries. This is particularly evident in sectors like shipbuilding, where precision and efficiency are paramount for successful outcomes. The quickest growth will come from Low Dust Applications, forecast to expand at a CAGR of 9.3% between 2026 and 2032. Low dust applications are experiencing rapid growth as industries prioritise air quality during blasting processes, especially in urban settings. The increased focus on health and safety standards is likely to propel the adoption of these applications even further. Suppliers should prioritise the development of low dust technologies to meet the rising demand for cleaner and safer blasting solutions.
By End User – Shipbuilding Firms Dominated, Aerospace Components Expected to Grow Fastest
Shipbuilding Firms took a 34% share of end user in 2025, more than any other category. Shipbuilding firms represent the largest share of the market as they are major users of blasting systems for hull preparation and maintenance, reflecting the industry's scale and operational needs. Their substantial output in shipbuilding ensures consistent demand for these technologies. Aerospace Components are projected to grow fastest, at a CAGR of 9.7% during 2026–2032. Aerospace components are experiencing rapid growth as precision cleaning of parts becomes critical in this highly regulated sector. The increasing production of aerospace components in regions like Shanghai and Beijing will further fuel this growth. Suppliers should target aerospace manufacturers to capitalise on this growing segment and adapt their offerings to meet specific industry standards.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Blasting Systems Market Outlook
- Market Size of China Industrial Blasting Systems Market, 2025
- Forecast of China Industrial Blasting Systems Market, 2032
- Historical Data and Forecast of China Industrial Blasting Systems Revenues & Volume for the Period 2022 - 2032F
- China Industrial Blasting Systems Market Trend Evolution
- China Industrial Blasting Systems Market Drivers and Challenges
- China Industrial Blasting Systems Price Trends
- China Industrial Blasting Systems Porter's Five Forces
- China Industrial Blasting Systems Industry Life Cycle
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Blasting Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Sandblasting Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Shot Blasting Machines for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Wet Blasting Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Soda Blasting Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Media Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Silica, Garnet for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Steel Shots, Grit for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Water + Abrasive for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Sodium Bicarbonate for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Operation Mode for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Manual or Automated for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Tumblast/Spinner Hanger for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Low Dust Applications for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Surface Cleaning for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Shipbuilding Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Automotive Foundries for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Aerospace Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Blasting Systems Market Revenues & Volume By Art Restoration Units for the Period 2022 - 2032F
- China Industrial Blasting Systems Import Export Trade Statistics
- Market Opportunity Assessment By Blasting Type
- Market Opportunity Assessment By Media Used
- Market Opportunity Assessment By Operation Mode
- Market Opportunity Assessment By End User
- China Industrial Blasting Systems Top Companies Market Share
- China Industrial Blasting Systems Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Blasting Systems Company Profiles
- China Industrial Blasting Systems Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Blasting Type
- Sandblasting Systems
- Shot Blasting Machines
- Wet Blasting Systems
- Soda Blasting Systems
By Media Used
- Silica
- Garnet
- Steel Shots
- Grit
- Water + Abrasive
- Sodium Bicarbonate
By Operation Mode
- Manual or Automated
- Tumblast/Spinner Hanger
- Low Dust Applications
- Surface Cleaning
By End User
- Shipbuilding Firms
- Automotive Foundries
- Aerospace Components
- Art Restoration Units































