China Industrial Corrosion Protection Market Size & Growth Rate
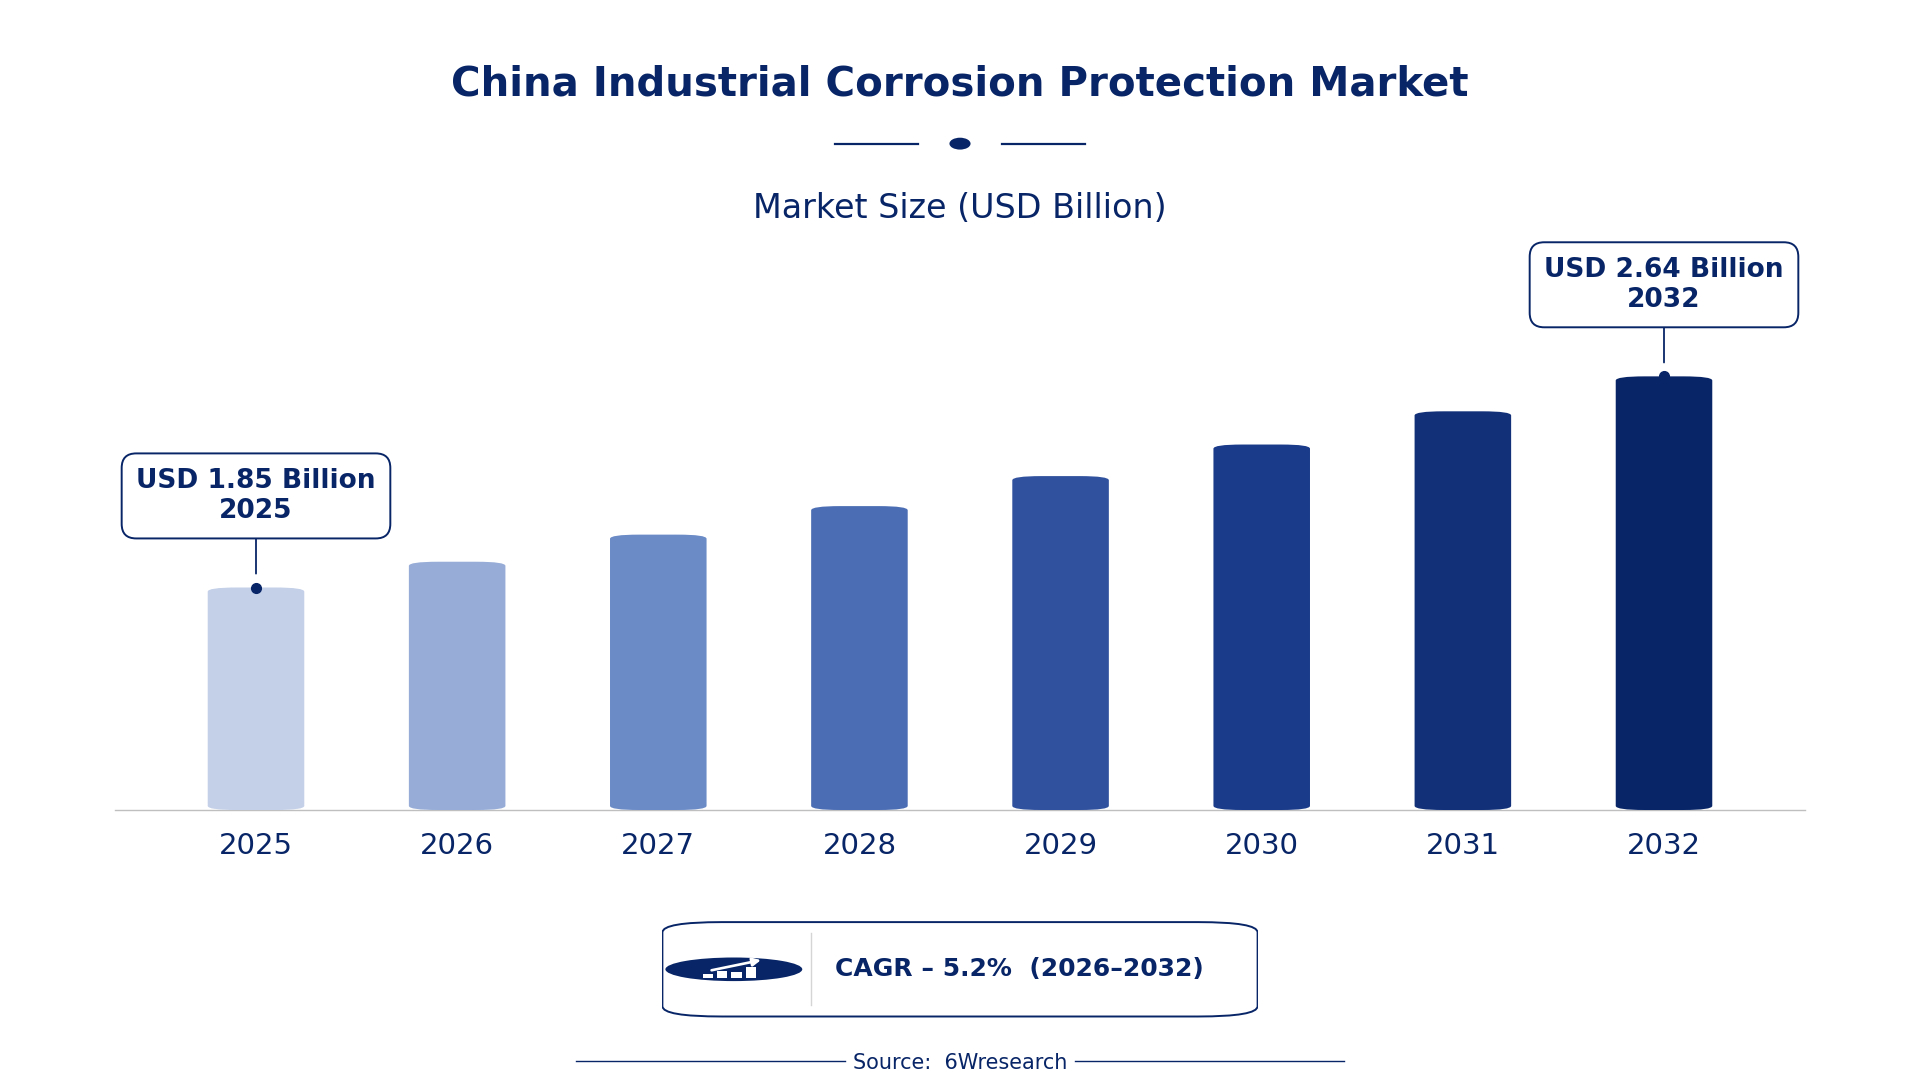
According to 6Wresearch internal database and industry insights, the China Industrial Corrosion Protection Market was valued at USD 1.85 billion in 2025 and is projected to reach USD 2.64 billion by 2032, growing at a CAGR of approximately 5.2% during 2026–2032.
China Industrial Corrosion Protection Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Corrosion Protection Market |
| Market Size 2025 | USD 1.85 billion |
| Market Size 2032 | USD 2.64 billion |
| Absolute Growth 2025–2032 | USD 0.79 billion |
| CAGR 2026–2032 | 5.2% |
| Peak Annual Growth | 7.5% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Protection Type, 2025 | Galvanization (37% share) |
| Leading Material Base, 2025 | Zinc/Alloy Coating (50% share) |
| Leading Coating Application, 2025 | Dipping/Spraying (42% share) |
| Leading End User, 2025 | Steel Fabrication (37% share) |
| Fastest-Growing Protection Type | Epoxy-Based Protection (6.8% CAGR) |
| Fastest-Growing Coating Application | Paint/Brush (6.7% CAGR) |
| Fastest-Growing End User | Marine Infrastructure (7.8% CAGR) |
| Growing Sector | Paint/Brush |
| Key End Users | Dipping/Spraying, Paint/Brush, Subsurface, Spray/Aerosol |
China Industrial Corrosion Protection Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
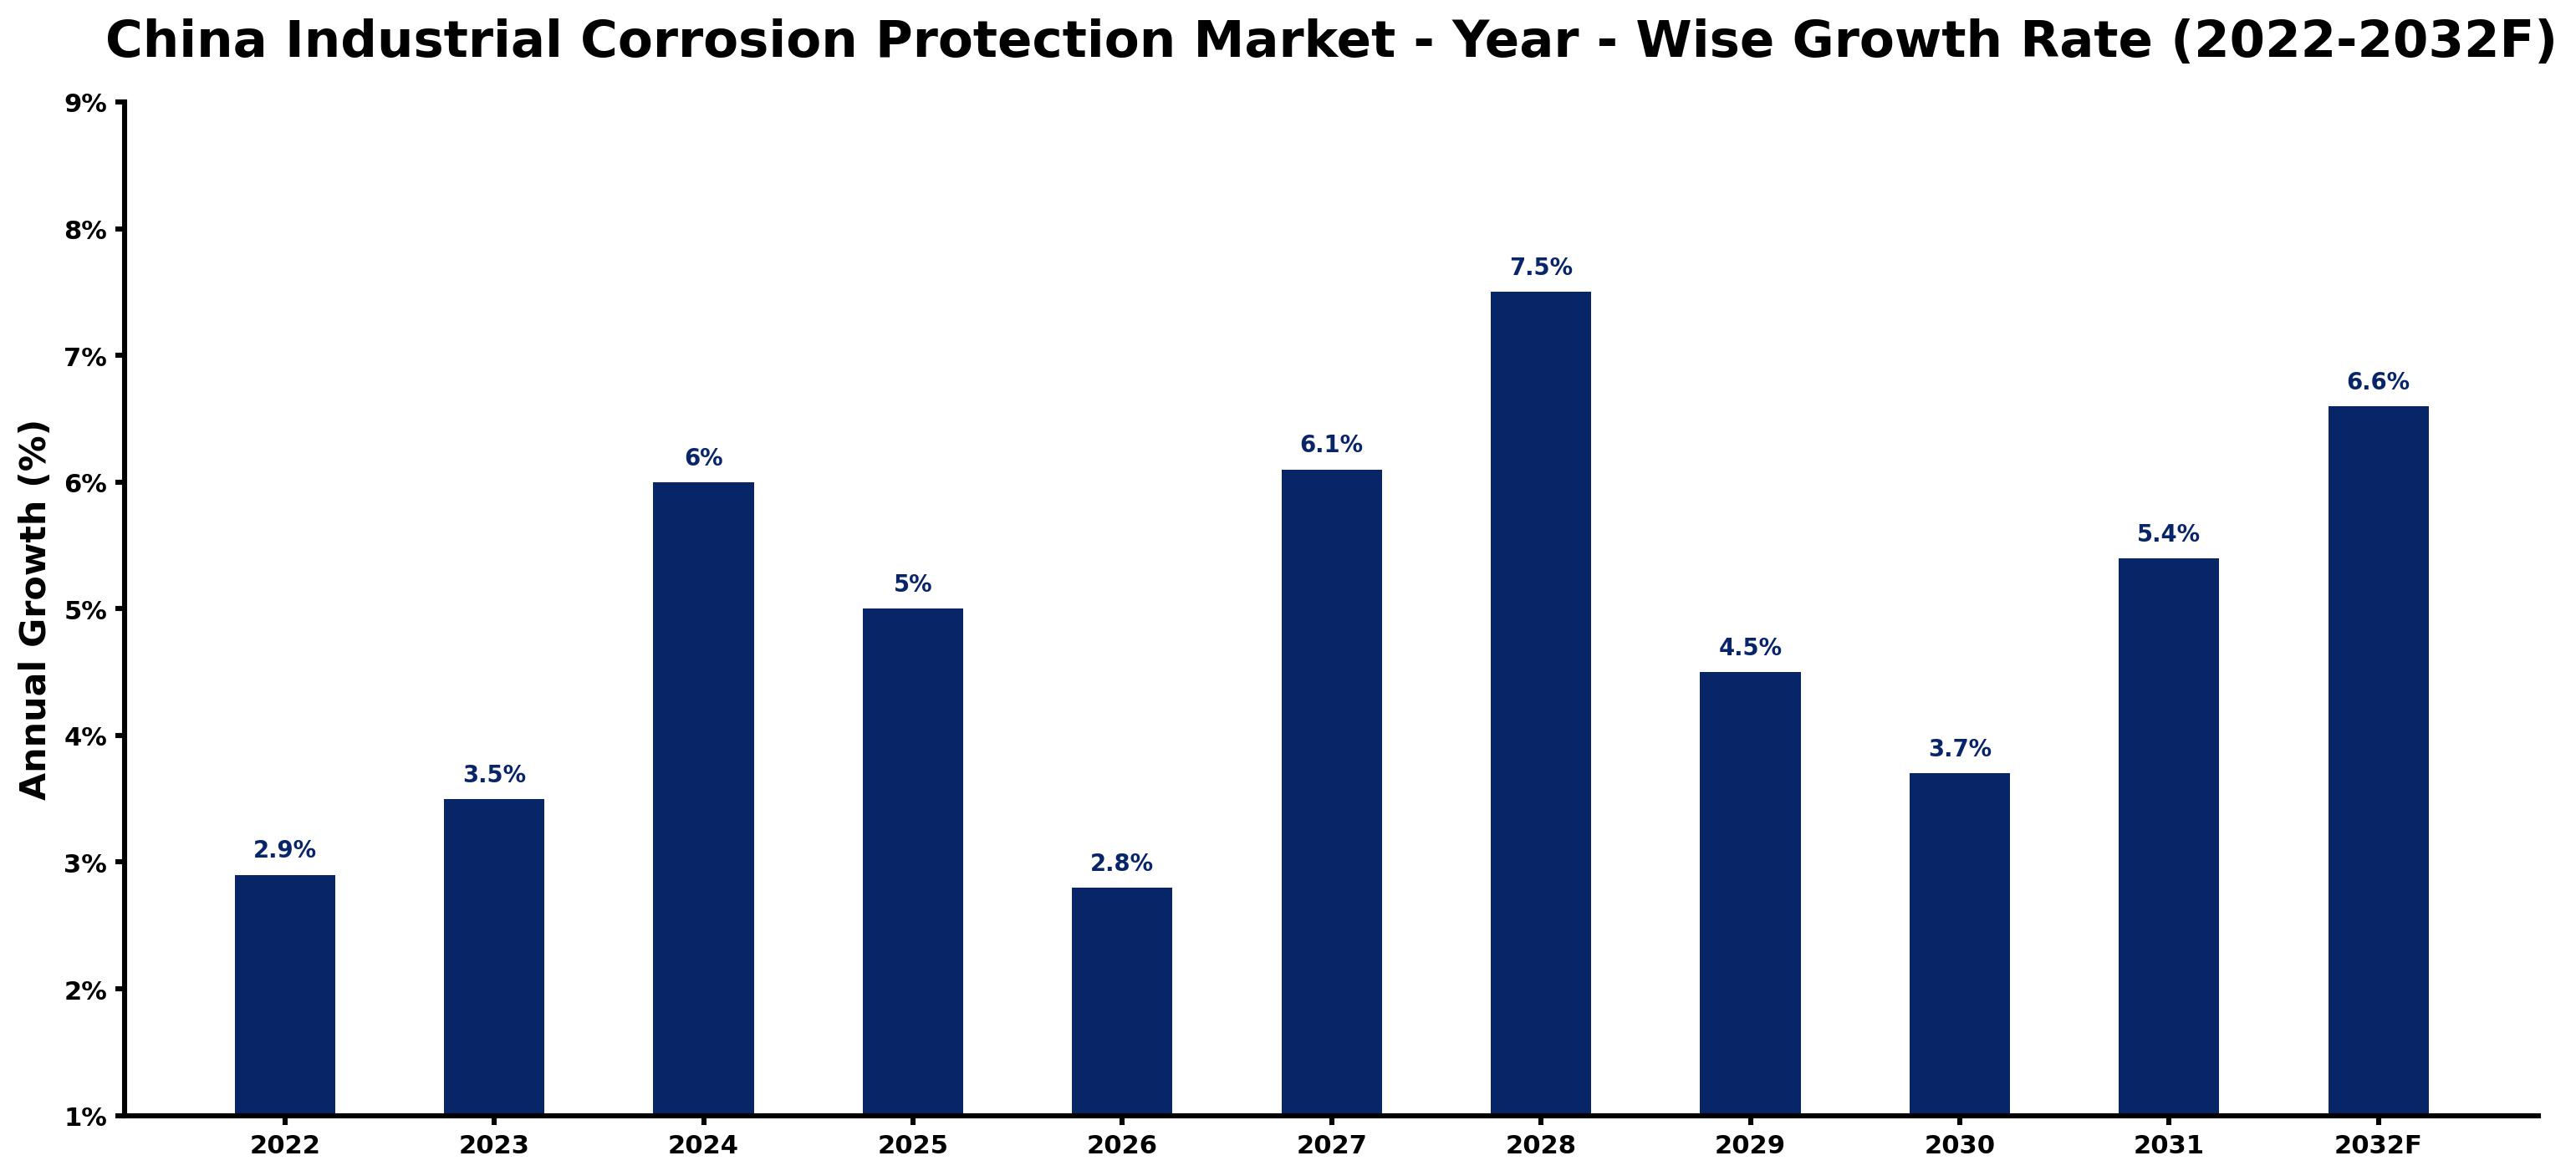
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 2.9 | Demand for corrosion protection was strong due to ongoing infrastructure projects. |
| 2023 | 3.5 | The market experienced growth driven by increased steel production and industrial activity. |
| 2024 | 6.0 | Infrastructure investments led to heightened requirements for corrosion protection solutions. |
| 2025 | 5.0 | Growth slowed as the market adjusted to previous rapid expansions in demand. |
| 2026 | 2.8 | A slowdown in growth occurred as new safety standards were implemented. |
| 2027 | 6.1 | Infrastructure development initiatives spurred renewed interest in corrosion protection technologies. |
| 2028 | 7.5 | The market peaked as investments in marine infrastructure surged significantly. |
| 2029 | 4.5 | Growth slowed as the market began to stabilise after peak investment years. |
| 2030 | 3.7 | Demand continued to grow, albeit at a slower pace than previous years. |
| 2031 | 5.4 | Increased focus on environmentally friendly solutions led to higher demand. |
| 2032 | 6.6 | The market is expected to grow as infrastructure projects continue to expand. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Corrosion Protection Market Synopsis
Industrial Corrosion Protection in China encompasses methods to prevent rust and degradation of metal surfaces, primarily through galvanization and protective coatings. Key applications include safeguarding steel structures, pipelines, and marine equipment. The China Industrial Corrosion Protection Market is expanding due to increasing demand from the steel fabrication and oil pipeline sectors. In 2022, China produced 1.1 billion tons of steel, driving the need for corrosion protection solutions. Marine infrastructure projects are projected to attract $200 billion in investments by 2025, further propelling market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising steel production drives demand for protective coatings and galvanization. | Driver | High | Galvanization |
| Increased investments in marine infrastructure enhance the need for corrosion protection. | Driver | High | Marine Infrastructure |
| Growing investments in oil and gas infrastructure create opportunities for corrosion protection solutions. | Opportunity | High | Oil Pipelines |
| The shift towards environmentally friendly coatings presents new market avenues. | Opportunity | Medium | Epoxy-Based Protection |
| High costs of advanced corrosion protection systems may deter some buyers. | Restraint | High | Cathodic Protection |
| Limited awareness of corrosion protection standards can restrict market growth. | Restraint | Medium | Zinc/Alloy Coating |
| Approval processes for new materials can delay market entry for suppliers. | Challenge | High | Epoxy-Based Protection |
| Competition from low-cost alternatives affects pricing strategies in the market. | Challenge | Medium | Galvanization |
Evaluation of Drivers in China Industrial Corrosion Protection Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased steel production requires protective coatings to prevent corrosion. | Zinc/Alloy Coating | China produced 1.1 billion tons of steel in 2022, driving demand for corrosion protection. |
| Investment in marine infrastructure boosts demand for corrosion protection solutions. | Marine Infrastructure | Marine infrastructure projects are expected to reach $200 billion by 2025. |
| Growing oil and gas sector necessitates effective corrosion protection for pipelines. | Oil Pipelines | The oil and gas sector has over 80,000 km of pipelines requiring corrosion protection. |
| Rising awareness of environmental standards promotes the use of eco-friendly coatings. | Epoxy-Based Protection | The Ministry of Ecology and Environment initiated the 'Green Coating Initiative' in 2022. |
| Technological advancements in corrosion protection enhance product offerings. | Cathodic Protection | Demand for cathodic protection systems increased by 15% in 2022 due to infrastructure growth. |
The Industrial Corrosion Protection market in China is growing on the back of rising steel production, increased investments in infrastructure, and the expanding oil and gas sector. In 2022, China produced 1.1 billion tons of steel, driving demand for protective coatings. Infrastructure investments are projected to reach $200 billion by 2025, further boosting the market. The oil and gas sector has over 80,000 km of pipelines requiring corrosion protection, creating substantial demand. Technological advancements in corrosion protection systems are improving product offerings, leading to increased purchases from key industries.
Evaluation of Restraints in China Industrial Corrosion Protection Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of advanced corrosion protection systems may deter some buyers. | Cathodic Protection | Advanced systems can be expensive, limiting access for smaller operators. |
| Limited awareness of corrosion protection standards can restrict market growth. | Zinc/Alloy Coating | Many manufacturers lack knowledge of updated standards, affecting compliance. |
| Long approval processes for new materials delay market entry for suppliers. | Epoxy-Based Protection | Regulatory hurdles can extend the time required to bring new products to market. |
| Competition from low-cost alternatives affects pricing strategies in the market. | Galvanization | Cheaper options can undermine the market for higher-quality protective solutions. |
| Supply chain disruptions can impact the availability of key materials. | Marine Infrastructure | Global supply chain issues have led to delays in material procurement. |
China Industrial Corrosion Protection Market Challenges
In China, a shortage of skilled workers hampers the industrial corrosion protection market, causing project delays for buyers in the steel fabrication sector. Fierce competition among suppliers drives prices down, leading many to compromise on quality, which results in increased maintenance costs of up to 20% for clients in the oil and gas industry. Recent updates to the National Standard for corrosion protection create compliance challenges that can delay product approvals, raising expenses for manufacturers by approximately 15%. Slow adoption of advanced technologies in corrosion protection restricts operational efficiency, preventing suppliers from winning contracts in marine infrastructure projects worth $200 billion by 2025.
Trends in the China Industrial Corrosion Protection Market
Four trends stand out in the China Industrial Corrosion Protection Market.
- Shift towards Eco-Friendly Corrosion Protection Solutions: There is a growing trend towards environmentally friendly corrosion protection solutions in China. The Ministry of Ecology and Environment's 'Green Coating Initiative' launched in 2022 promotes sustainable practices, reflecting a shift in industry standards.
- Increasing Adoption of Epoxy-Based Coatings: Since 2021, epoxy-based coatings have gained popularity due to their durability and effectiveness. They account for approximately 30% of the corrosion protection market, indicating a shift in preference among industrial users.
- Rising Demand for Cathodic Protection Systems: In 2022, the demand for cathodic protection systems increased by 15% due to rapid infrastructure growth. This trend highlights the critical need for effective corrosion prevention in pipeline applications.
- Expansion of Marine Infrastructure Projects: Marine infrastructure projects in China are expected to reach $200 billion by 2025, indicating a growing investment trend. This expansion is driving demand for advanced corrosion protection technologies.
Investment Opportunities in the China Industrial Corrosion Protection Market
Below are the investment opportunities with the strongest case in the China Industrial Corrosion Protection Market.
- Partnerships with Local Suppliers: Now is an ideal time to partner with local suppliers in the Yangtze River Delta, where steel fabrication is booming. This region produced 1.1 billion tons of steel in 2022, creating a market gap for corrosion protection solutions.
- Investment in Eco-Friendly Products: With the push for sustainability, investing in environmentally friendly corrosion protection solutions is timely. The 'Green Coating Initiative' launched in 2022 supports the development of such products.
- Focus on Oil Pipeline Infrastructure: The oil and gas sector's extensive pipeline network presents a significant opportunity. With over 80,000 km of pipelines, suppliers can target this market by offering advanced corrosion protection systems.
- Expansion into Marine Infrastructure: The anticipated $200 billion investment in marine infrastructure by 2025 creates a substantial opportunity. Suppliers can enter this market by collaborating with local construction firms.
Government Initiatives in the China Industrial Corrosion Protection Market
The 'Corrosion Prevention and Control Technology Development Plan' launched by the Ministry of Industry and Information Technology in 2021 aims to improve industry standards and practices. This initiative has led to enhanced quality in corrosion protection solutions. The 'National Strategy for Infrastructure Resilience' approved by the National Development and Reform Commission in 2022 emphasises the importance of corrosion protection in critical infrastructure. This strategy aims to strengthen the resilience of infrastructure against environmental challenges. In 2023, updated safety standards for corrosion protection products were introduced by the State Administration for Market Regulation, ensuring quality and reliability for producers and consumers.
The Ministry of Ecology and Environment initiated the 'Green Coating Initiative' in 2022, promoting environmentally friendly corrosion protection solutions. This initiative encourages manufacturers to adopt sustainable practices. The National Development and Reform Commission supports initiatives for advanced corrosion protection solutions, ensuring funding for innovative technologies. The China Coating Industry Association promotes standards for corrosion protection materials and practices, facilitating compliance and enhancing market growth.
Future Insight of the China Industrial Corrosion Protection Market
The China industrial corrosion protection market will evolve significantly by 2032, driven by advancements in protective coating technologies and rising investments in infrastructure. The oil and gas sector's extensive network of over 80,000 km of pipelines will require innovative corrosion protection solutions, benefiting both buyers and suppliers. Initiatives from the Ministry of Industry and Information Technology will improve the quality of corrosion protection systems, while the growing demand for effective solutions will stimulate market growth. The updated standards from the China Coating Industry Association will further enhance practices across the industry.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Protection Type – Galvanization Dominated, Epoxy-Based Protection Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, the largest protection type category in 2025 was Galvanization, with a 37% share of total revenue. Galvanization holds the largest share in the China Industrial Corrosion Protection Market due to its critical function in safeguarding steel structures, especially in construction and infrastructure initiatives. Its widespread application in the Yangtze River Delta, a vital area for steel fabrication, illustrates its importance. The quickest growth will come from Epoxy-Based Protection, forecast to expand at a CAGR of 6.8% between 2026 and 2032. Epoxy-based protection is experiencing rapid growth, attributed to its rising use in industrial applications as infrastructure projects expand. The 15% increase in demand for these coatings in 2022 indicates industries' need for long-lasting corrosion-resistant solutions. Suppliers should enhance their epoxy-based product offerings to meet the increasing demand from industrial users.
By Material Base – Zinc/Alloy Coating Dominated and Is Expected to Record the Fastest Growth
Zinc/Alloy Coating accounted for a 50% market share by material base in 2025. Zinc/alloy coating dominates the market share as it is the preferred choice for applying corrosion resistance to steel products, essential for various industries. Its widespread use in steel fabrication ensures that it remains the leading material base in corrosion protection. Zinc/Alloy Coating is also forecast to expand faster than any other category, at a CAGR of 6.9% over 2026–2032. The zinc/alloy coating segment is also the fastest-growing, benefiting from its established reputation and the increasing need for effective corrosion solutions in construction and manufacturing. This dual position as both leader and fastest will likely strengthen its market share further. Buyers can expect a steady supply of zinc/alloy coatings as manufacturers ramp up production to meet growing demand.
By Coating Application – Dipping/Spraying Dominated, Paint/Brush Expected to Grow Fastest
With a 42% revenue share in 2025, Dipping/Spraying was the largest coating application category. Dipping/spraying is the leading application method in the market, favoured for its efficiency in applying protective coatings uniformly across extensive surfaces. This method is particularly prevalent in sectors where large-scale coating is essential, such as automotive and industrial applications. Over 2026–2032, Paint/Brush is expected to post the fastest growth, at a CAGR of 6.7%. The paint/brush application method is rapidly gaining traction, mainly due to its effectiveness for smaller-scale applications, which are increasingly common across various sectors. This growth indicates a shift towards more adaptable application techniques as industry needs diversify. Suppliers should consider expanding their product lines to include paint/brush solutions to meet the rising demand from smaller projects.
By End User – Steel Fabrication Dominated, Marine Infrastructure Expected to Grow Fastest
Steel Fabrication took a 37% share of end user in 2025, more than any other category. Steel fabrication is the largest end user of corrosion protection solutions, primarily due to the extensive reliance on steel in construction and infrastructure across China. The sector's strong growth, highlighted by the production of 1.1 billion tons of steel in 2022, reinforces its leading position. Marine Infrastructure is set to record the highest CAGR in this split, 7.8% over 2026–2032. Marine infrastructure is the fastest-growing end user segment, driven by significant investments in marine projects, which are projected to reach $200 billion by 2025. This influx of funding underscores the urgent requirement for effective corrosion protection in demanding marine environments. Suppliers should target the marine infrastructure sector to capitalise on rapid growth and increasing investments in corrosion protection.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Corrosion Protection Market Outlook
- Market Size of China Industrial Corrosion Protection Market, 2025
- Forecast of China Industrial Corrosion Protection Market, 2032
- Historical Data and Forecast of China Industrial Corrosion Protection Revenues & Volume for the Period 2022 - 2032F
- China Industrial Corrosion Protection Market Trend Evolution
- China Industrial Corrosion Protection Market Drivers and Challenges
- China Industrial Corrosion Protection Price Trends
- China Industrial Corrosion Protection Porter's Five Forces
- China Industrial Corrosion Protection Industry Life Cycle
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Protection Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Galvanization for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Epoxy-Based Protection for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Cathodic Protection for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Rust Inhibitor Fluids for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Material Base for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Zinc/Alloy Coating for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Thermoset Resin for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Electrical/Anode-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Oil-Based Sprays for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Coating Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Dipping/Spraying for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Paint/Brush for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Subsurface for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Spray/Aerosol for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Steel Fabrication for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Oil Pipelines for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Marine Infrastructure for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Corrosion Protection Market Revenues & Volume By Machine Maintenance for the Period 2022 - 2032F
- China Industrial Corrosion Protection Import Export Trade Statistics
- Market Opportunity Assessment By Protection Type
- Market Opportunity Assessment By Material Base
- Market Opportunity Assessment By Coating Application
- Market Opportunity Assessment By End User
- China Industrial Corrosion Protection Top Companies Market Share
- China Industrial Corrosion Protection Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Corrosion Protection Company Profiles
- China Industrial Corrosion Protection Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Protection Type
- Galvanization
- Epoxy-Based Protection
- Cathodic Protection
- Rust Inhibitor Fluids
By Material Base
- Zinc/Alloy Coating
- Thermoset Resin
- Electrical/Anode-Based
- Oil-Based Sprays
By Coating Application
- Dipping/Spraying
- Paint/Brush
- Subsurface
- Spray/Aerosol
By End User
- Steel Fabrication
- Oil Pipelines
- Marine Infrastructure
- Machine Maintenance































