China Industrial Gas Production Market Size & Growth Rate
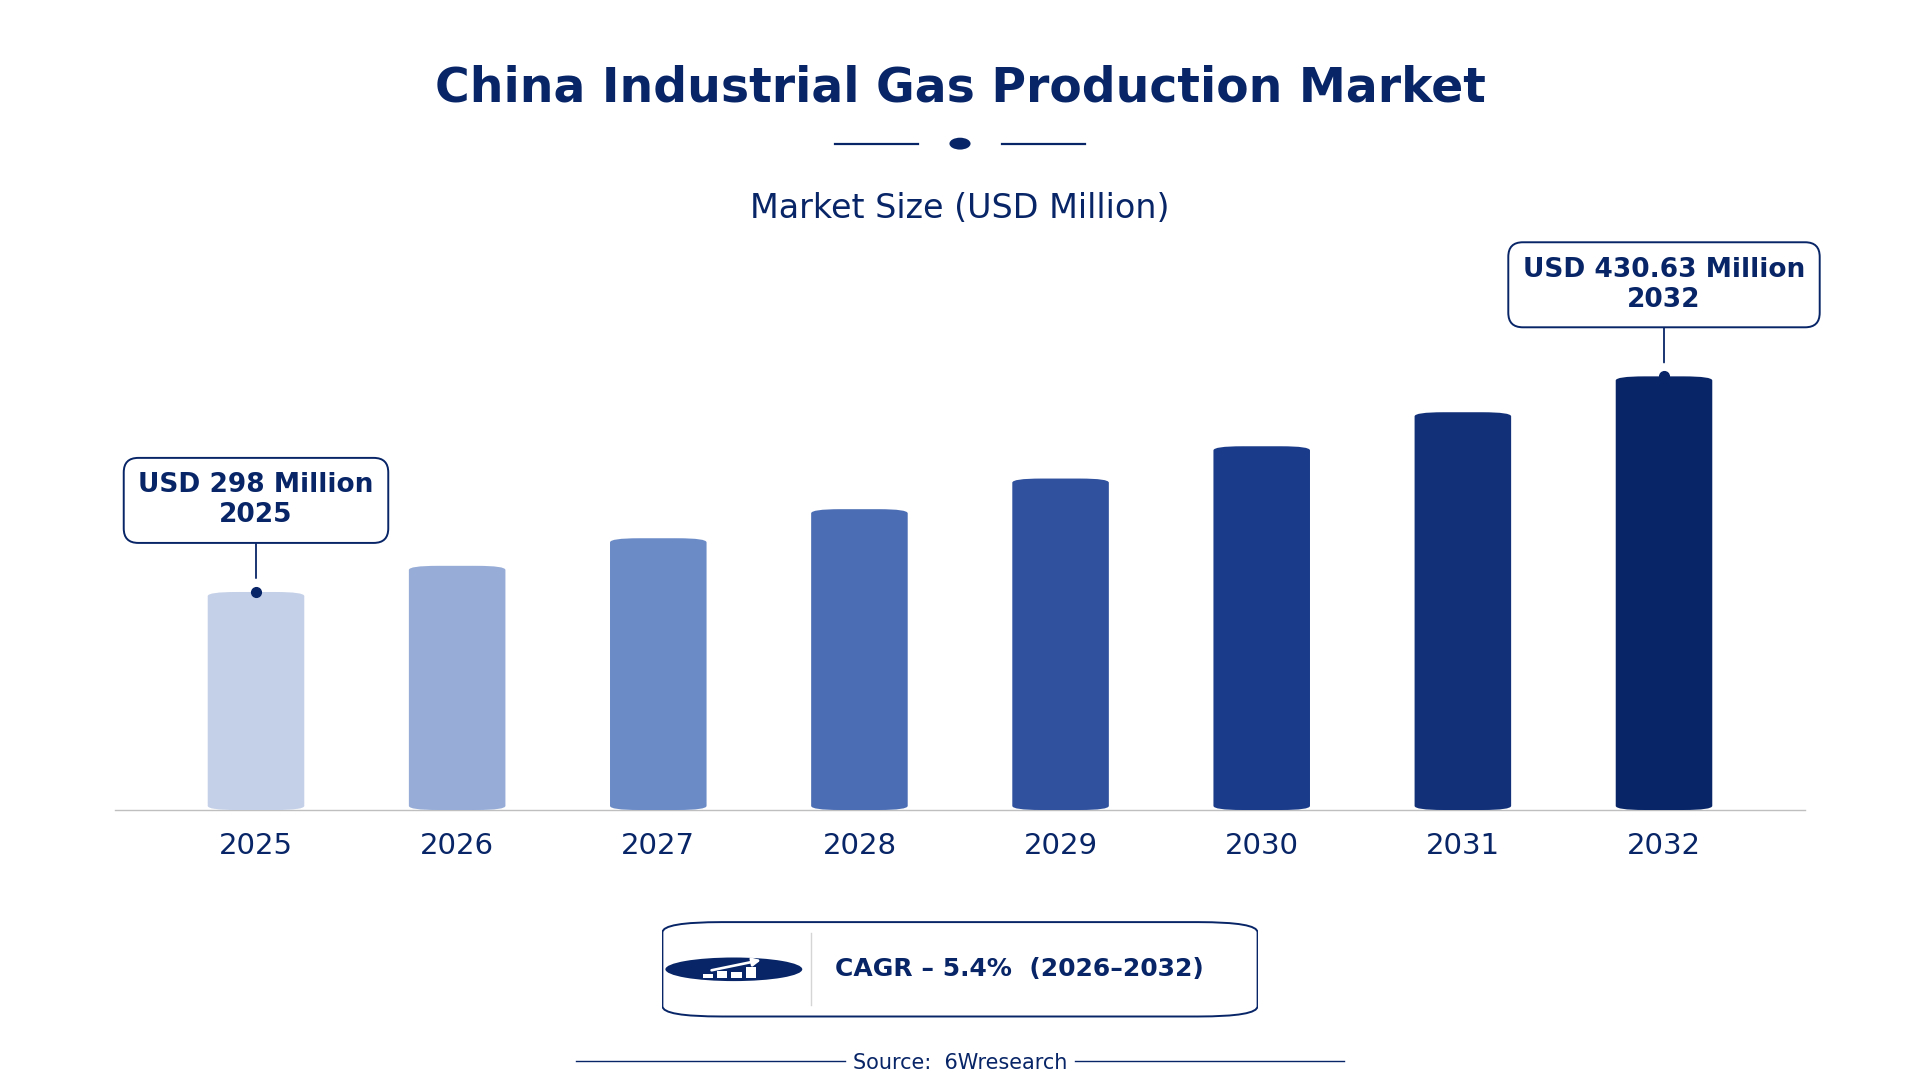
According to 6Wresearch internal database and industry insights, the China Industrial Gas Production Market was valued at USD 298.0 million in 2025 and is projected to reach USD 430.63 million by 2032, growing at a CAGR of approximately 5.4% during 2026–2032.
China Industrial Gas Production Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Gas Production Market |
| Market Size 2025 | USD 298.0 million |
| Market Size 2032 | USD 430.63 million |
| Absolute Growth 2025–2032 | USD 132.63 million |
| CAGR 2026–2032 | 5.4% |
| Peak Annual Growth | 8.2% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Gas Type, 2025 | Oxygen (47% share) |
| Leading Production Method, 2025 | Cryogenic Distillation (54% share) |
| Leading Storage Format, 2025 | Liquid / Cylinder (38% share) |
| Leading End User, 2025 | Steel & Welding Industry (50% share) |
| Fastest-Growing Gas Type | Hydrogen (7.3% CAGR) |
| Fastest-Growing Production Method | Electrolysis / Reforming (8.0% CAGR) |
| Fastest-Growing Storage Format | Pressurized / Gas Banks (6.7% CAGR) |
| Fastest-Growing End User | Energy & Fuel Applications (7.2% CAGR) |
| Growing Sector | Energy & Fuel Applications |
| Key End Users | Steel & Welding Industry, Energy & Fuel Applications, Electronics & Inerting Use, Beverage & Fire Control |
China Industrial Gas Production Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
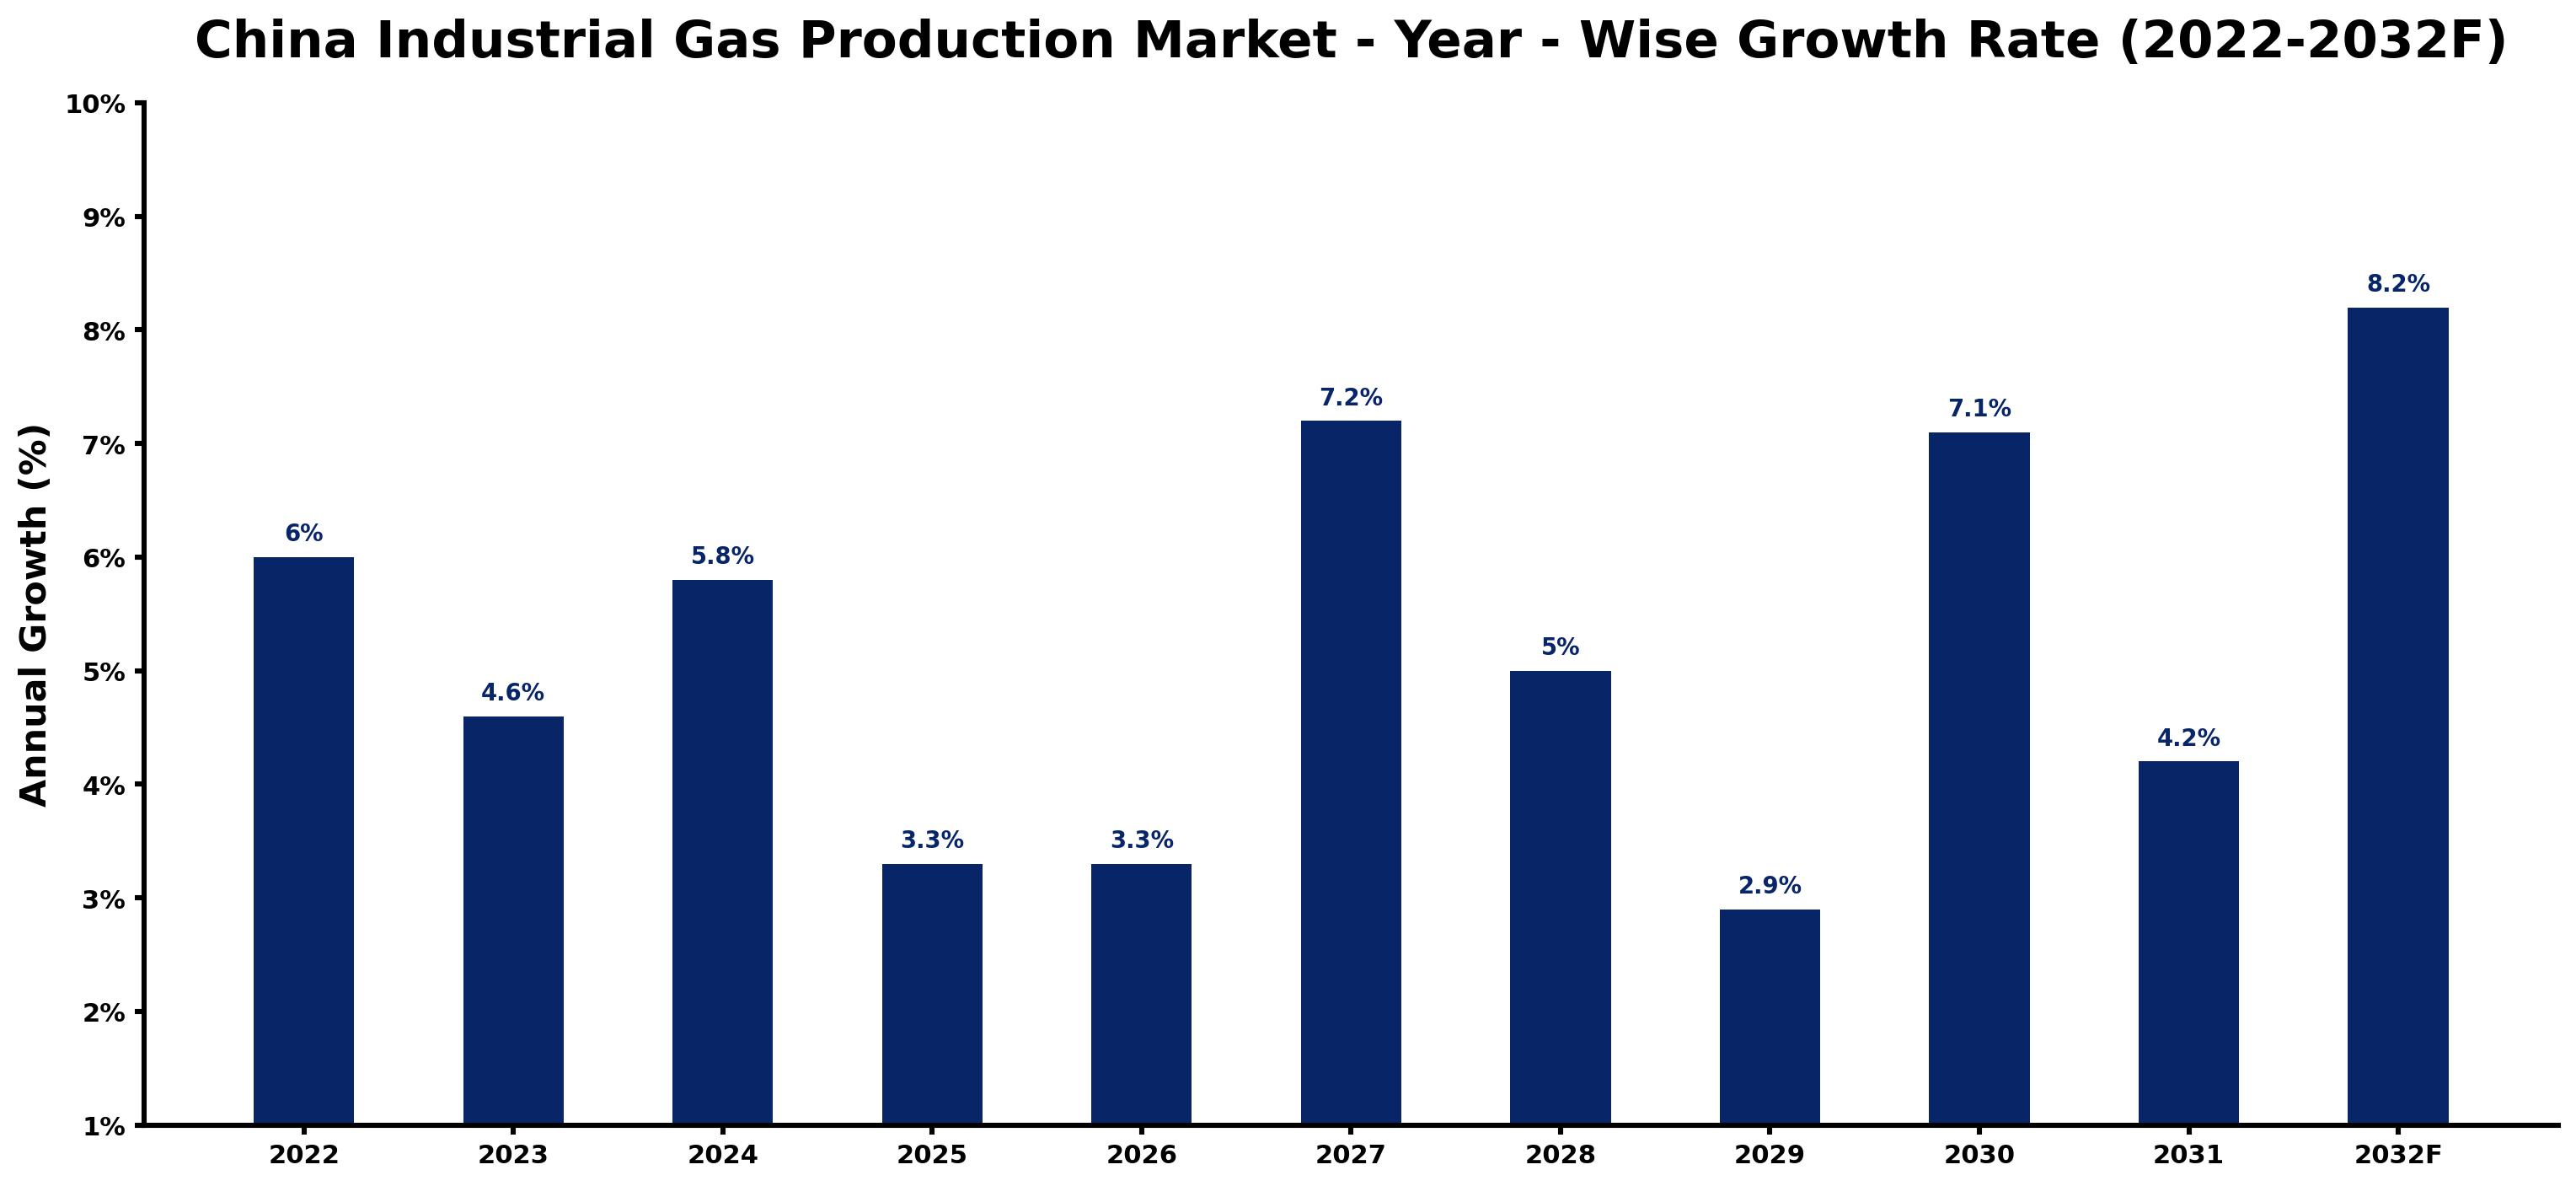
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.0 | The market experienced solid demand from heavy industries, particularly steel production. |
| 2023 | 4.6 | Growth slowed due to temporary disruptions in supply chains affecting production capacities. |
| 2024 | 5.8 | Increased investments in hydrogen infrastructure boosted production capabilities and demand. |
| 2025 | 3.3 | Demand growth slowed as the market adjusted to new regulatory standards and quality controls. |
| 2026 | 3.3 | The hydrogen production capacity is expected to stabilise as industries adapt to new regulations and improved production methods. |
| 2027 | 7.2 | A surge in hydrogen applications is projected to revitalise growth, particularly in energy sectors. |
| 2028 | 5.0 | Growth is anticipated to slow as the market faces challenges in meeting rising quality standards. |
| 2029 | 2.9 | Demand will continue to slow as production capacity reaches near saturation levels. |
| 2030 | 7.1 | A rebound in demand for industrial gases is expected to support growth driven by new energy projects. |
| 2031 | 4.2 | Growth is projected to slow again as the market adjusts to evolving consumer preferences and standards. |
| 2032 | 8.2 | A peak in growth is anticipated as investments in hydrogen technologies accelerate. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Gas Production Market Synopsis
The China Industrial Gas Production Market encompasses the manufacturing of vital gases such as oxygen, hydrogen, nitrogen, and carbon dioxide through processes like cryogenic distillation. These gases find crucial applications in industries including steel production and energy generation. The market is growing due to robust domestic demand from heavy industries, with the steel sector accounting for over 50% of total production. Government initiatives aimed at developing hydrogen infrastructure and reducing emissions are further stimulating investment in this sector.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising demand from the steel industry drives the need for oxygen and nitrogen. | Driver | High | Oxygen |
| Increased investments in hydrogen production technologies boost market growth. | Driver | High | Hydrogen |
| The beverage industry is expanding, creating a need for carbon dioxide for carbonation. | Opportunity | High | Carbon Dioxide |
| Growing energy applications for hydrogen present new market opportunities. | Opportunity | High | Hydrogen |
| Quality control measures may limit production flexibility and increase costs. | Restraint | Medium | Oxygen |
| Supply chain disruptions can lead to delays in gas availability for industries. | Restraint | Medium | Oxygen |
| Regulatory compliance costs can strain smaller producers financially. | Challenge | High | Oxygen |
| Technological advancements require continuous investment to remain competitive. | Challenge | High | Oxygen |
Evaluation of Drivers in China Industrial Gas Production Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing steel production drives demand for industrial gases, particularly oxygen. | Oxygen | The steel industry consumed over 50% of the total industrial gases produced in China. |
| Increased hydrogen production capacity supports energy applications. | Hydrogen | The total installed capacity for hydrogen production reached 3 million tons in 2023. |
| Rising beverage consumption leads to higher demand for carbon dioxide. | Carbon Dioxide | The beverage industry is projected to use 2 million tons of CO2 annually by 2025. |
| Investment in hydrogen infrastructure is expanding production capabilities. | Hydrogen | China's investment in hydrogen infrastructure is expected to exceed 100 billion yuan by 2025. |
| Quality standards drive improvements in production processes. | Oxygen | The National Standard for Industrial Gases was updated in 2022 to enhance quality control. |
The Industrial Gas Production market in China is expanding as end-use demand from heavy industries, particularly steel production, increases. The steel sector alone consumed over 50% of total industrial gases produced, prompting suppliers to boost their output. The installed capacity for hydrogen production reached 3 million tons in 2023, supporting energy applications. Investment in hydrogen infrastructure will exceed 100 billion yuan by 2025, driving production capabilities. The beverage industry is also increasing demand, with projections of 2 million tons of CO2 usage annually by 2025, leading to increased purchases from gas producers.
Evaluation of Restraints in China Industrial Gas Production Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Quality control measures may limit production flexibility and increase costs. | Oxygen | The updated National Standard for Industrial Gases in 2022 requires compliance that can strain smaller producers. |
| Supply chain disruptions can lead to delays in gas availability for industries. | Oxygen | Recent global supply chain issues have affected timely gas deliveries, impacting production schedules. |
| Regulatory compliance costs can strain smaller producers financially. | Oxygen | Compliance with updated regulations can impose financial burdens on smaller gas producers. |
| Technological advancements require continuous investment to remain competitive. | Oxygen | Producers must invest in new technologies to meet evolving industry standards, increasing operational costs. |
| Market saturation may limit growth opportunities for new entrants. | Oxygen | As production capacities reach near saturation, new entrants face challenges in gaining market share. |
China Industrial Gas Production Market Challenges
Buyers in the China Industrial Gas Production Market encounter supply constraints as the steel industry consumes over 50% of total output, limiting availability for other sectors and delaying gas supply for manufacturers. The slow adoption of advanced production technologies, particularly in hydrogen, which has a capacity of only 3 million tons in 2023, hampers operational efficiency and innovation for suppliers. Increased competition from imported specialised gases puts pressure on local producers, resulting in higher prices for buyers reliant on essential gases. Compliance with national standards such as GB/T 20079-2008 raises operational costs, impacting hospitals and clinics that rely on industrial gases for medical applications.
Trends in the China Industrial Gas Production Market
Four trends stand out in the China Industrial Gas Production Market.
- Hydrogen Economy Development Plan: The 'Hydrogen Economy Development Plan', launched in 2021, aims to boost hydrogen production and infrastructure. This initiative is set to increase hydrogen output, with investments expected to exceed 100 billion yuan by 2025.
- Sustainable Hydrogen Production Focus: China is increasingly prioritising sustainable hydrogen production methods. The 'Green Hydrogen Development Strategy', initiated in 2023, emphasises eco-friendly practices, aligning with global sustainability goals.
- Liquid Storage Formats Gaining Preference: Liquid storage formats are becoming the preferred choice for onsite gas supply in industrial applications. This shift is driven by the need for efficient gas distribution, with liquid formats holding a significant market share.
- Beverage Industry Expansion: The beverage industry in China is projected to consume 2 million tons of CO2 annually by 2025. This growth is resulting in increased demand for carbon dioxide from industrial gas producers.
Investment Opportunities in the China Industrial Gas Production Market
The following opportunities in the China Industrial Gas Production Market pair current demand with a clear way in.
- Hydrogen Infrastructure Investment: With an investment exceeding 100 billion yuan expected by 2025, there is an opportunity for suppliers of hydrogen production technologies. The energy sector is a key buyer group, seeking sustainable solutions.
- Beverage Production Expansion: The beverage industry is projected to require 2 million tons of CO2 annually by 2025. Suppliers can capitalise on this demand by forming partnerships with beverage manufacturers.
- Energy Applications for Hydrogen Growth: The energy sector's increasing reliance on hydrogen presents a timely opportunity for producers. Investment in hydrogen infrastructure will support this growing demand, particularly in energy applications.
- Advancements in Production Methods: The need for compliance with updated quality standards creates a demand for advanced production technologies. Suppliers of gas production solutions can enter the market by collaborating with local producers.
Government Initiatives in the China Industrial Gas Production Market
The '14th Five-Year Plan for the Development of Hydrogen Energy Industry', approved in 2021, aims to boost hydrogen production and infrastructure. This plan encourages investment in hydrogen technologies and promotes sustainable practices. Additionally, the 'Energy Conservation and Emission Reduction Action Plan' issued by the State Council in 2020 supports the use of industrial gases to improve energy efficiency across various sectors. These measures create a more favourable environment for industrial gas producers and buyers alike.
The 'National Hydrogen Energy Technology Innovation Center', established in 2022, supports research and development in hydrogen technologies. This centre funds projects aimed at improving hydrogen production methods and infrastructure. Furthermore, the 'Clean Energy Action Plan' promotes hydrogen use in energy applications, aligning with national goals for reducing carbon emissions. This governmental support is vital for advancing the industrial gas sector in China.
Future Insight of the China Industrial Gas Production Market
The China Industrial Gas Production Market will undergo notable changes by 2032, driven by government initiatives like the 'Hydrogen Economy Development Plan' that highlight hydrogen's role in energy applications. Investment in gas infrastructure is expected to exceed 100 billion yuan, which will improve production capabilities across the sector. Annual demand for industrial gases is projected to reach 50 million tons, reflecting growth across various industries. The electronics sector's increasing reliance on inert gases for semiconductor manufacturing will create new opportunities for suppliers and buyers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Gas Type – Oxygen Dominated, Hydrogen Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, the largest gas type category in 2025 was Oxygen, with a 47% share of total revenue. Oxygen holds the largest market share in China due to its critical role in steelmaking and medical applications. The steel industry alone consumed over 50% of the total industrial gases produced, highlighting the extensive demand for oxygen. Over 2026–2032, Hydrogen is expected to post the fastest growth, at a CAGR of 7.3%. Hydrogen is experiencing rapid growth as a result of initiatives like the 'Hydrogen Economy Development Plan' launched in 2021. With a production capacity reaching 3 million tons in 2023, hydrogen's applications in refining and fuel cells are driving this surge. This trend indicates that suppliers should focus on expanding hydrogen production capabilities to meet growing demand.
By Production Method – Cryogenic Distillation Dominated, Electrolysis / Reforming Expected to Grow Fastest
Cryogenic Distillation took a 54% share of production method in 2025, more than any other category. Cryogenic Distillation commands the largest share in China's industrial gas production market due to its effectiveness in large-scale gas separation, essential for producing significant volumes of oxygen and nitrogen. Its extensive application in industries such as steel and energy solidifies its dominant position. Electrolysis / Reforming is projected to grow fastest, at a CAGR of 8.0% during 2026–2032. Electrolysis and Reforming are rapidly gaining traction, especially for hydrogen production, as government policies encourage a shift towards cleaner energy sources. The projected investment of over 100 billion yuan by 2025 underscores the growing importance of these methods in meeting future energy demands. This indicates that suppliers must adapt their offerings to include advanced electrolysis technologies to remain relevant in the competitive landscape of industrial gas production.
By Storage Format – Liquid / Cylinder Dominated, Pressurized / Gas Banks Expected to Grow Fastest
With a 38% revenue share in 2025, Liquid / Cylinder was the largest storage format category. Liquid and Cylinder storage formats command the largest share due to their common use in industrial applications, providing efficient and reliable gas supply solutions. This format is particularly favoured for onsite gas supply in various sectors. The quickest growth will come from Pressurized / Gas Banks, forecast to expand at a CAGR of 6.7% between 2026 and 2032. Pressurized and Gas Banks are becoming the fastest-growing storage solution as they cater to bulk storage and distribution needs. The increasing demand for efficient gas management in industries is propelling this format's growth. Suppliers should consider investing in pressurized storage solutions to capitalise on this growing market segment.
By End User – Steel & Welding Industry Dominated, Energy & Fuel Applications Expected to Grow Fastest
In 2025, Steel & Welding Industry led the end user split with a 50% share. The Steel and Welding Industry is the foremost consumer of industrial gases, relying heavily on these gases for essential manufacturing processes. This sector's substantial market share is driven by the high demand for oxygen and other gases critical for steel production. Energy & Fuel Applications are set to record the highest CAGR in this split, 7.2% over 2026–2032. Energy and Fuel Applications are the fastest-growing segment, propelled by the rising adoption of hydrogen in energy generation and fuel cells. This trend aligns with national objectives to lower carbon emissions through increased hydrogen utilisation. This growth indicates that suppliers should prioritise the energy sector to capitalise on emerging opportunities in hydrogen applications.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Gas Production Market Outlook
- Market Size of China Industrial Gas Production Market, 2025
- Forecast of China Industrial Gas Production Market, 2032
- Historical Data and Forecast of China Industrial Gas Production Revenues & Volume for the Period 2022 - 2032F
- China Industrial Gas Production Market Trend Evolution
- China Industrial Gas Production Market Drivers and Challenges
- China Industrial Gas Production Price Trends
- China Industrial Gas Production Porter's Five Forces
- China Industrial Gas Production Industry Life Cycle
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Gas Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Oxygen for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Hydrogen for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Nitrogen for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Carbon Dioxide for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Production Method for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Cryogenic Distillation for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Electrolysis / Reforming for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Pressure Swing Adsorption for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Captured/Byproduct for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Storage Format for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Liquid / Cylinder for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Pressurized / Gas Banks for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Liquid / Onsite Plants for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Cylinders/Tankers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Steel & Welding Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Energy & Fuel Applications for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Electronics & Inerting Use for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Production Market Revenues & Volume By Beverage & Fire Control for the Period 2022 - 2032F
- China Industrial Gas Production Import Export Trade Statistics
- Market Opportunity Assessment By Gas Type
- Market Opportunity Assessment By Production Method
- Market Opportunity Assessment By Storage Format
- Market Opportunity Assessment By End User
- China Industrial Gas Production Top Companies Market Share
- China Industrial Gas Production Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Gas Production Company Profiles
- China Industrial Gas Production Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Gas Type
- Oxygen
- Hydrogen
- Nitrogen
- Carbon Dioxide
By Production Method
- Cryogenic Distillation
- Electrolysis / Reforming
- Pressure Swing Adsorption
- Captured/Byproduct
By Storage Format
- Liquid / Cylinder
- Pressurized / Gas Banks
- Liquid / Onsite Plants
- Cylinders/Tankers
By End User
- Steel & Welding Industry
- Energy & Fuel Applications
- Electronics & Inerting Use
- Beverage & Fire Control































