China Industrial Integration Solutions Market Size & Growth Rate
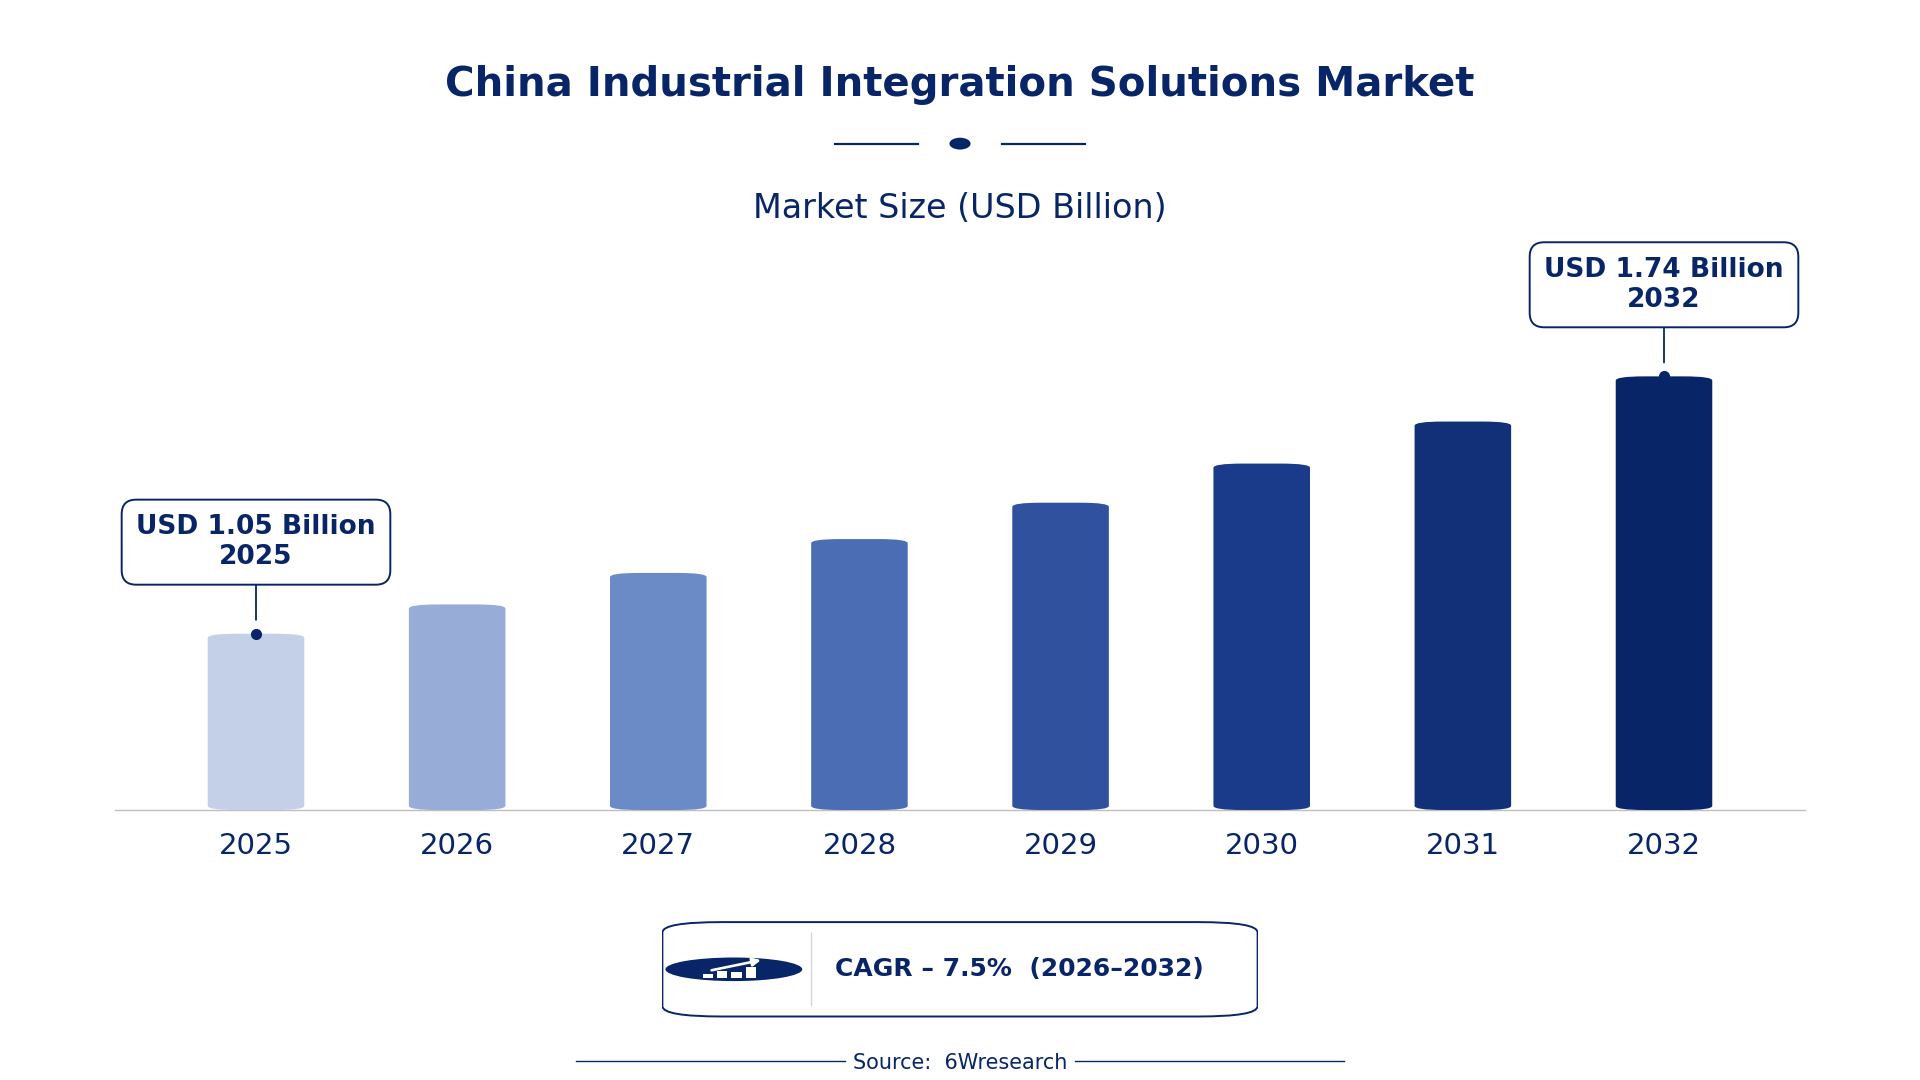
According to 6Wresearch internal database and industry insights, the China Industrial Integration Solutions Market was valued at USD 1.05 billion in 2025 and is projected to reach USD 1.74 billion by 2032, growing at a CAGR of approximately 7.5% during 2026–2032.
China Industrial Integration Solutions Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Integration Solutions Market |
| Market Size 2025 | USD 1.05 billion |
| Market Size 2032 | USD 1.74 billion |
| Absolute Growth 2025–2032 | USD 0.69 billion |
| CAGR 2026–2032 | 7.5% |
| Peak Annual Growth | 9.7% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Solution Type, 2025 | MES-ERP Integration (45% share) |
| Leading Integration Level, 2025 | Factory-to-Enterprise (44% share) |
| Leading Interface Type, 2025 | API/Web Services (46% share) |
| Leading End User, 2025 | Smart Manufacturing (39% share) |
| Fastest-Growing Solution Type | IoT Gateway Solutions (9.2% CAGR) |
| Fastest-Growing Integration Level | Real-Time Sync (10.0% CAGR) |
| Fastest-Growing End User | Industrial IoT (10.1% CAGR) |
| Growing Sector | Smart Manufacturing |
| Key End Users | Automotive Plants, Utilities & Energy Firms, Industrial IoT, Smart Manufacturing |
China Industrial Integration Solutions Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
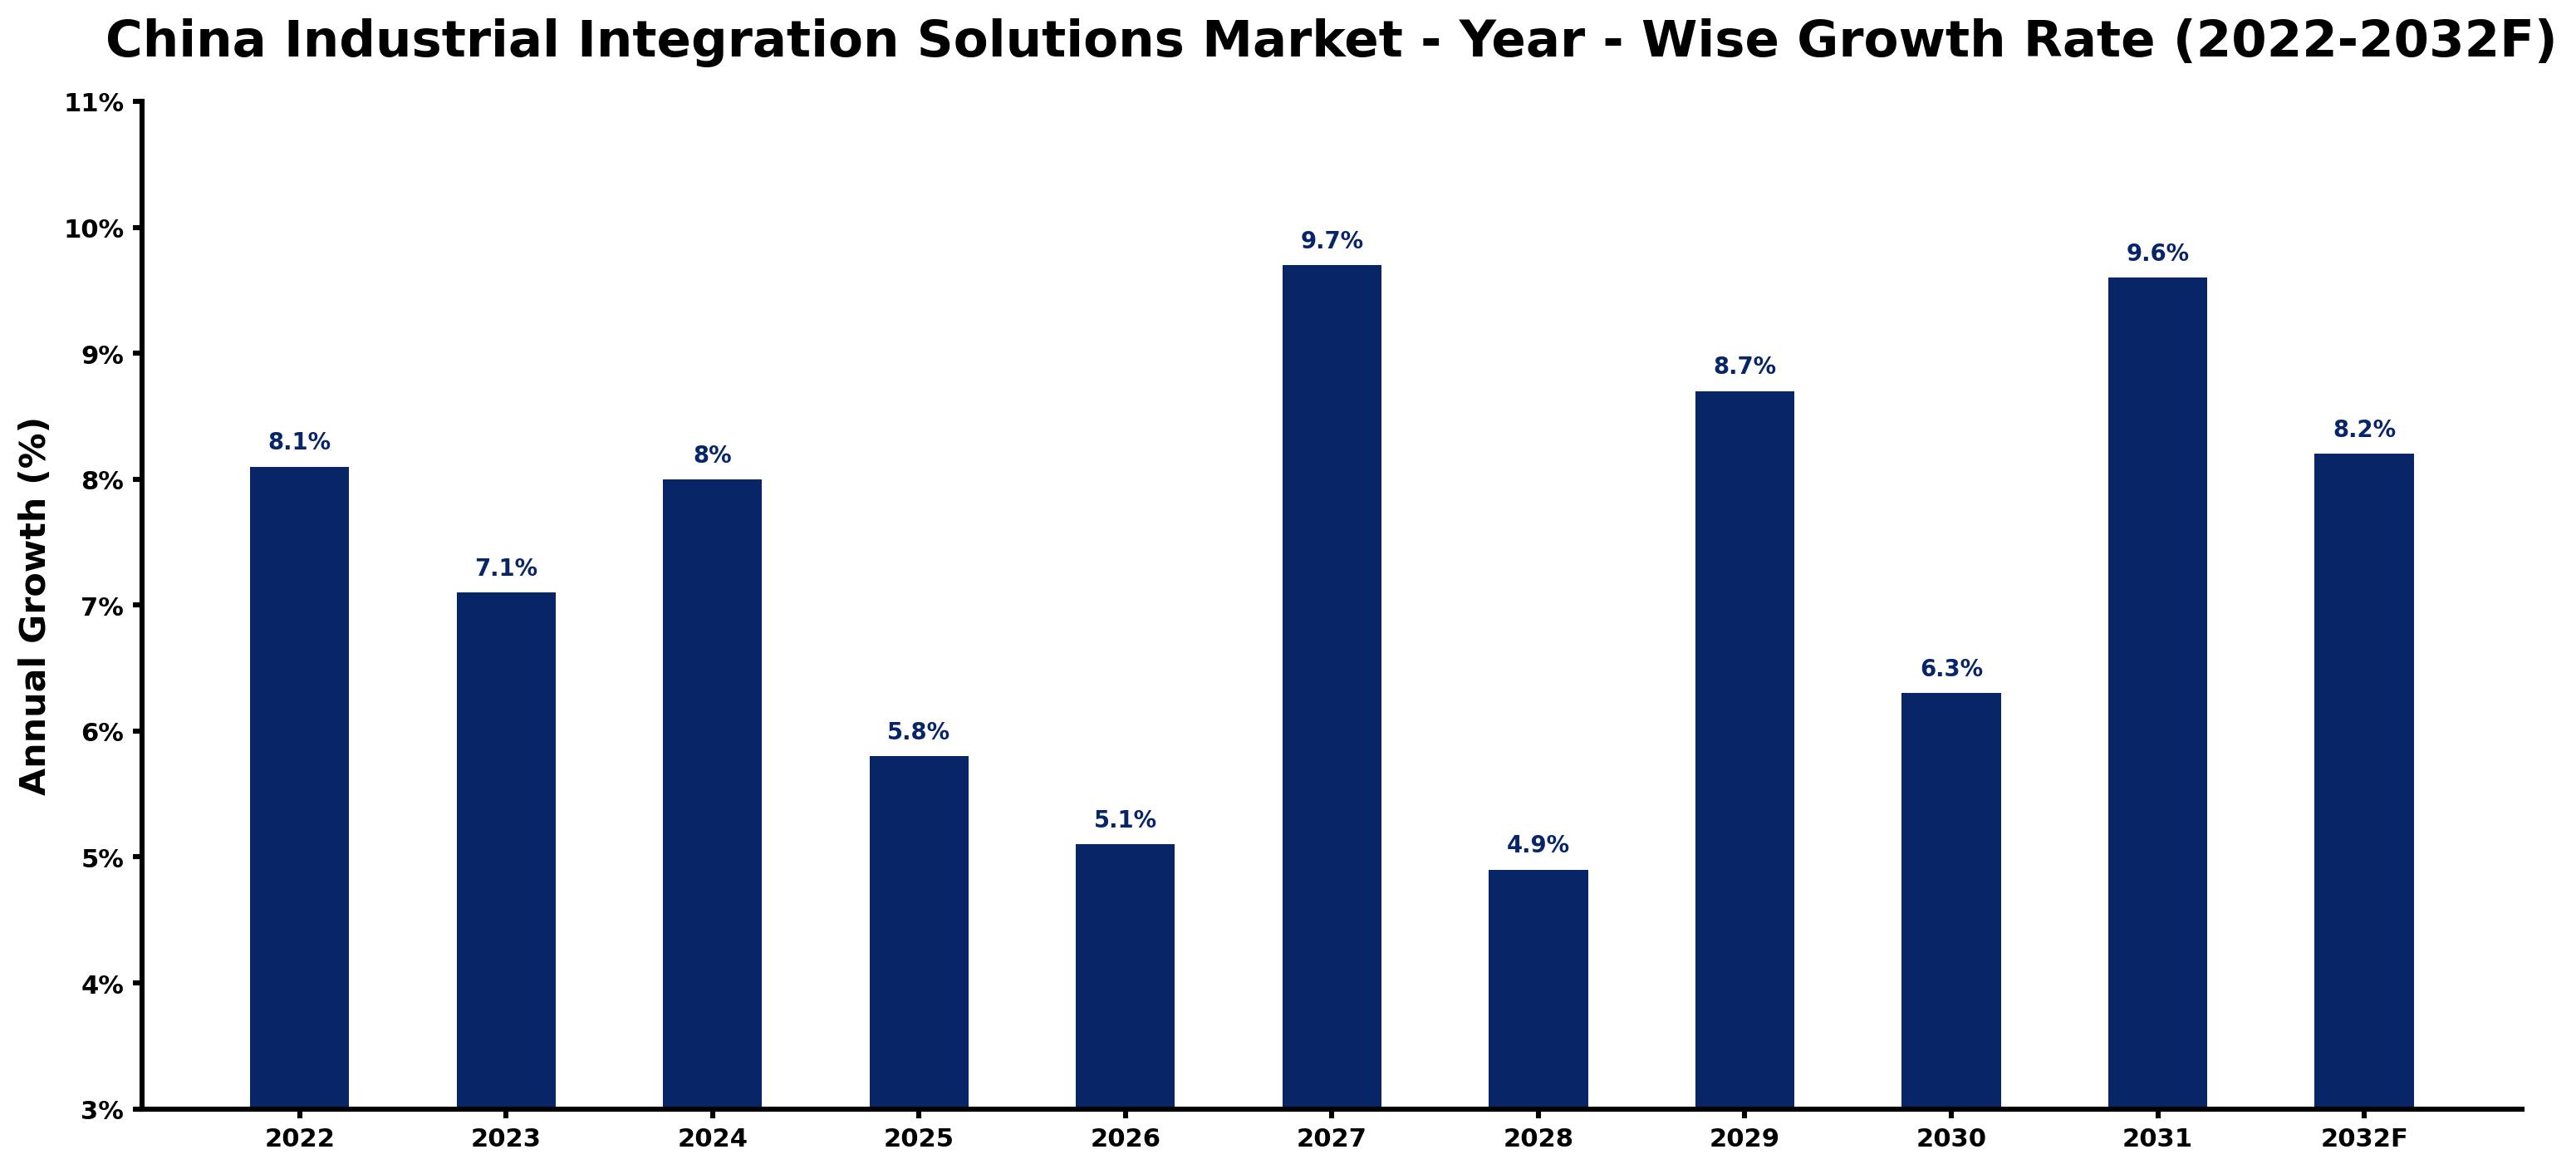
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 8.1 | The automotive sector invested heavily in Industry 4.0 technologies, boosting integration solutions demand. |
| 2023 | 7.1 | Growth slowed as the market adjusted to the previous year's investments in smart manufacturing. |
| 2024 | 8.0 | Increased adoption of IoT technologies led to a rise in integration solutions demand. |
| 2025 | 5.8 | Growth slowed as companies focused on optimizing existing systems rather than new investments. |
| 2026 | 5.1 | Investment in digital infrastructure is expected to decline, affecting integration solutions demand. |
| 2027 | 9.7 | Demand surged as integration solutions became essential for operational efficiency in factories. |
| 2028 | 4.9 | Growth slowed as companies consolidated their investments in existing integration systems. |
| 2029 | 8.7 | A renewed focus on smart manufacturing initiatives will spur growth in integration solutions. |
| 2030 | 6.3 | Growth slowed as market participants reassess their strategies amidst changing technologies. |
| 2031 | 9.6 | Demand increased with the launch of new smart manufacturing projects across sectors. |
| 2032 | 8.2 | Growth slowed as the 'Digital Economy Development Plan' drives companies to optimize integration. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Integration Solutions Market Synopsis
Industrial Integration Solutions in China connect various industrial systems, improving operational efficiency and facilitating data exchange. These solutions arise from the integration of software and hardware, primarily serving manufacturing processes and optimising supply chains. The China Industrial Integration Solutions Market is growing due to investments in smart manufacturing and IoT technologies, with the installed base of IoT devices exceeding 1.5 billion units in 2022. Initiatives like 'Made in China 2025' further stimulate demand for these solutions.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Significant investments in smart manufacturing technologies are driving demand for integration solutions. | Driver | High | Smart Manufacturing |
| The automotive sector's shift towards Industry 4.0 technologies creates opportunities for integration solutions. | Driver | High | Automotive Plants |
| The rise of IoT devices presents a gap in integration solutions for data management. | Opportunity | High | IoT Gateway Solutions |
| The Yangtze River Delta region is becoming a hub for smart manufacturing initiatives. | Opportunity | Medium | Factory-to-Enterprise |
| Limited awareness of integration solutions among smaller manufacturers restrains market growth. | Restraint | High | Machine Data Connectors |
| High initial investment costs deter some companies from adopting integration solutions. | Restraint | Medium | SCADA-PLC Integration |
| The fast pace of technological change poses challenges for integration solution providers. | Challenge | High | IoT Gateway Solutions |
| Integration solutions must comply with evolving standards, complicating market entry. | Challenge | Medium | MES-ERP Integration |
Evaluation of Drivers in China Industrial Integration Solutions Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Investment in smart manufacturing technologies is increasing demand for integration solutions. | Smart Manufacturing | The automotive sector's focus on integration solutions aims to improve production efficiency, projected to increase operational efficiency by 30%. |
| The automotive sector's shift towards Industry 4.0 technologies drives integration needs. | Automotive Plants | This sector's investment in integration solutions is expected to streamline production processes and reduce downtime. |
| The growing number of IoT devices necessitates effective integration solutions. | IoT Gateway Solutions | With over 1.5 billion IoT devices in 2022, demand for effective data management is critical. |
| The push for real-time data analytics is driving integration solutions adoption. | Factory-to-Enterprise | Real-time data exchange is essential for maintaining competitive advantage in manufacturing. |
| Government initiatives promote the adoption of integration solutions across industries. | Smart Manufacturing | The 'Digital Economy Development Plan' aims to boost industrial IoT adoption and integration solutions. |
Market growth for Industrial Integration Solutions in China is driven by increasing investments in smart manufacturing, the automotive sector's shift to Industry 4.0 technologies, and the rising number of IoT devices. In 2022, the installed base of IoT devices surpassed 1.5 billion units, creating a strong demand for effective integration solutions. The automotive sector alone is projected to enhance operational efficiency by 30% through integration. The need for real-time data analytics also propels the demand for effective integration across various industrial processes.
Evaluation of Restraints in China Industrial Integration Solutions Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Limited awareness among smaller manufacturers about integration solutions. | Machine Data Connectors | This lack of awareness restricts potential buyers from investing in necessary technologies, stalling market growth. |
| High initial investment costs for integration solutions deter adoption. | SCADA-PLC Integration | Many companies find the upfront costs prohibitive, leading to slower integration rates. |
| The rapid pace of technological change makes it difficult for providers to keep up. | IoT Gateway Solutions | Providers face challenges in adapting to new technologies, affecting their market competitiveness. |
| Evolving standards complicate compliance for integration solutions. | MES-ERP Integration | Manufacturers must navigate complex regulations, which can delay implementation timelines. |
| Integration solutions may require extensive training for effective use. | Factory-to-Enterprise | This requirement can deter companies from investing in new technologies. |
China Industrial Integration Solutions Market Challenges
Producers in the China Industrial Integration Solutions market face a skills shortage, as educational institutions cannot keep up with the rapid pace of technological change, which delays project timelines for manufacturers. Rising costs are another challenge, with integration solutions often requiring upfront investments that can exceed 20% of total project budgets, straining financial resources for buyers. Increased competition from international firms forces local producers to lower prices, potentially compromising product quality and reliability. Outdated infrastructure in many facilities restricts technology adoption, resulting in operational inefficiencies and extended project completion times for manufacturers.
Trends in the China Industrial Integration Solutions Market
Below mentioned are some of the trends shaping the China Industrial Integration Solutions Market growth.
- Shift towards Real-Time Data Analytics: In 2022, demand for real-time data analytics surged, as companies sought integration solutions to boost operational efficiency. The automotive sector's emphasis on integration is expected to drive a 30% increase in efficiency.
- Increased Adoption of IoT Technologies: Smart Manufacturing initiatives are propelling the adoption of IoT technologies, with over 1.5 billion devices installed in 2022. This trend is reshaping operational strategies across various industries.
- Growth of Smart Manufacturing Initiatives: The Yangtze River Delta region is emerging as a hub for smart manufacturing, with substantial investments in integration solutions. This area is anticipated to lead the market in the coming years.
- Expansion of Industry 4.0 Technologies: The automotive sector is swiftly adopting Industry 4.0 technologies, enhancing production efficiency through integration solutions. This trend is expected to continue growing in the next few years.
Investment Opportunities in the China Industrial Integration Solutions Market
Several openings in the China Industrial Integration Solutions Market merit attention from investors.
- Investment in Integration Solutions: The automotive sector is currently making substantial investments in integration solutions, projected to reach USD 1.05 billion by 2025. This presents a valuable opportunity for suppliers to enter the market.
- Gap in IoT Integration Solutions: With the installed base of IoT devices exceeding 1.5 billion units, a notable gap in integration solutions exists. Suppliers can address this demand by developing tailored solutions for manufacturers.
- Focus on Smart Manufacturing: The Yangtze River Delta region prioritises smart manufacturing initiatives, generating demand for integration solutions. Suppliers can forge partnerships with local manufacturers to fulfil this need.
- Timing for New Technologies: The ongoing push for digital transformation creates an immediate opportunity for integration solutions. Companies aiming to enhance their operational efficiency can benefit from adopting these technologies now.
Government Initiatives in the China Industrial Integration Solutions Market
The '13th Five-Year Plan for the Development of the Manufacturing Sector' by the National Development and Reform Commission emphasizes the need for improved industrial integration technologies, aiming for a 50% increase in adoption by 2025. Additionally, the 'Digital China Initiative' allocates $300 billion by 2025 to integrate advanced technologies in manufacturing. These measures are designed to improve operational efficiency and promote the adoption of integration solutions across various sectors.
Manufacturers can benefit from the 'Smart Manufacturing Development Plan' launched by the Ministry of Industry and Information Technology in 2021, which aims to increase the adoption of integration solutions by 50% by 2025. The National Development and Reform Commission is also funding projects aimed at enhancing industrial connectivity, ensuring that manufacturers receive support for implementing these technologies.
Future Insight of the China Industrial Integration Solutions Market
The China Industrial Integration Solutions market will undergo significant changes by 2032, primarily due to the 'Digital Economy Development Plan' which aims to enhance industrial IoT adoption. The installed base of IoT devices is projected to exceed 3 billion units, facilitating improved data exchange across systems. As the automotive sector intensifies its investment in Industry 4.0 technologies, integration solutions will advance, driving operational efficiency improvements. The Yangtze River Delta region will emerge as a key innovation hub, fostering collaboration between technology providers and manufacturers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Solution Type – MES-ERP Integration Dominated, IoT Gateway Solutions Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, MES-ERP Integration took a 45% share of solution type in 2025, more than any other category. MES-ERP Integration leads the market due to its critical role in synchronising manufacturing processes with enterprise resource planning systems. This is particularly vital in sectors like automotive, where operational efficiency is paramount for maintaining competitiveness. IoT Gateway Solutions are set to record the highest CAGR in this split, 9.2% over 2026–2032. IoT Gateway Solutions are experiencing rapid growth as they facilitate the connection of numerous devices to the cloud for effective data collection and analysis. With over 1.5 billion IoT devices in China, the demand for these solutions is surging, especially in smart manufacturing. Suppliers should focus on developing advanced IoT Gateway Solutions to meet the increasing demand for connectivity in industrial applications.
By Integration Level – Factory-to-Enterprise Dominated, Real-Time Sync Expected to Grow Fastest
Factory-to-Enterprise held a 44% share of the China Industrial Integration Solutions Market by integration level in 2025. Factory-to-Enterprise integration holds the largest market share as it ensures seamless data flow from factory operations to enterprise systems, essential for large-scale manufacturers. This integration is particularly crucial in regions like the Yangtze River Delta, renowned for its smart manufacturing initiatives. Over 2026–2032, Real-Time Sync is expected to post the fastest growth, at a CAGR of 10.0%. Real-Time Sync is the fastest-growing segment, driven by the rising need for up-to-date information across various systems. As industries adopt more smart technologies, the demand for real-time data synchronisation is becoming increasingly vital for operational success. Buyers must invest in real-time synchronisation technologies to maintain competitive advantages in rapidly changing industrial environments.
By Interface Type – API/Web Services Dominated and Is Expected to Record the Fastest Growth
The largest interface type category in 2025 was API/Web Services, with a 46% share of total revenue. API/Web Services dominate the market due to their essential role in enabling communication between diverse software applications, which is crucial for modern industrial operations. This interface type is widely adopted by manufacturers aiming to improve operational efficiency and integration. Its lead should widen, with a projected CAGR of 9.7% during 2026–2032, the highest in this split. API/Web Services are also the fastest-growing segment, as their flexibility allows for quick adaptation to new technologies and systems. This growth is propelled by the increasing complexity of industrial operations that require seamless integration. Vendors should enhance API/Web Services capabilities to align with the evolving integration needs of industrial clients.
By End User – Smart Manufacturing Dominated, Industrial IoT Expected to Grow Fastest
In 2025, Smart Manufacturing led the end user split with a 39% share. Smart Manufacturing represents the largest market share, encompassing a wide range of industries that leverage integration solutions to optimise processes and enhance productivity. The sector's growth is bolstered by initiatives like 'Made in China 2025', which promotes advanced manufacturing technologies. The quickest growth will come from Industrial IoT, forecast to expand at a CAGR of 10.1% between 2026 and 2032. Industrial IoT is the fastest-growing end-user segment, driven by the rising adoption of connected devices and the demand for real-time data analytics. With the industrial IoT market projected for significant growth, this segment is poised for rapid expansion. Suppliers should tailor their offerings to meet the specific needs of the Industrial IoT sector, ensuring compatibility with emerging technologies.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Integration Solutions Market Outlook
- Market Size of China Industrial Integration Solutions Market, 2025
- Forecast of China Industrial Integration Solutions Market, 2032
- Historical Data and Forecast of China Industrial Integration Solutions Revenues & Volume for the Period 2022 - 2032F
- China Industrial Integration Solutions Market Trend Evolution
- China Industrial Integration Solutions Market Drivers and Challenges
- China Industrial Integration Solutions Price Trends
- China Industrial Integration Solutions Porter's Five Forces
- China Industrial Integration Solutions Industry Life Cycle
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By Solution Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By MES-ERP Integration for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By IoT Gateway Solutions for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By SCADA-PLC Integration for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By Machine Data Connectors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By Integration Level for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By Factory-to-Enterprise for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By Device-Level for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By Control Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By Real-Time Sync for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By Interface Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By API/Web Services for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By Edge/Cloud for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By Modbus/OPC UA for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By Ethernet/IP for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By Smart Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By Industrial IoT for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By Utilities & Energy Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Integration Solutions Market Revenues & Volume By Automotive Plants for the Period 2022 - 2032F
- China Industrial Integration Solutions Import Export Trade Statistics
- Market Opportunity Assessment By Solution Type
- Market Opportunity Assessment By Integration Level
- Market Opportunity Assessment By Interface Type
- Market Opportunity Assessment By End User
- China Industrial Integration Solutions Top Companies Market Share
- China Industrial Integration Solutions Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Integration Solutions Company Profiles
- China Industrial Integration Solutions Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Solution Type
- MES-ERP Integration
- IoT Gateway Solutions
- SCADA-PLC Integration
- Machine Data Connectors
By Integration Level
- Factory-to-Enterprise
- Device-Level
- Control Systems
- Real-Time Sync
By Interface Type
- API/Web Services
- Edge/Cloud
- Modbus/OPC UA
- Ethernet/IP
By End User
- Smart Manufacturing
- Industrial IoT
- Utilities & Energy Firms
- Automotive Plants































