China Industrial IoT Solutions Market Size & Growth Rate
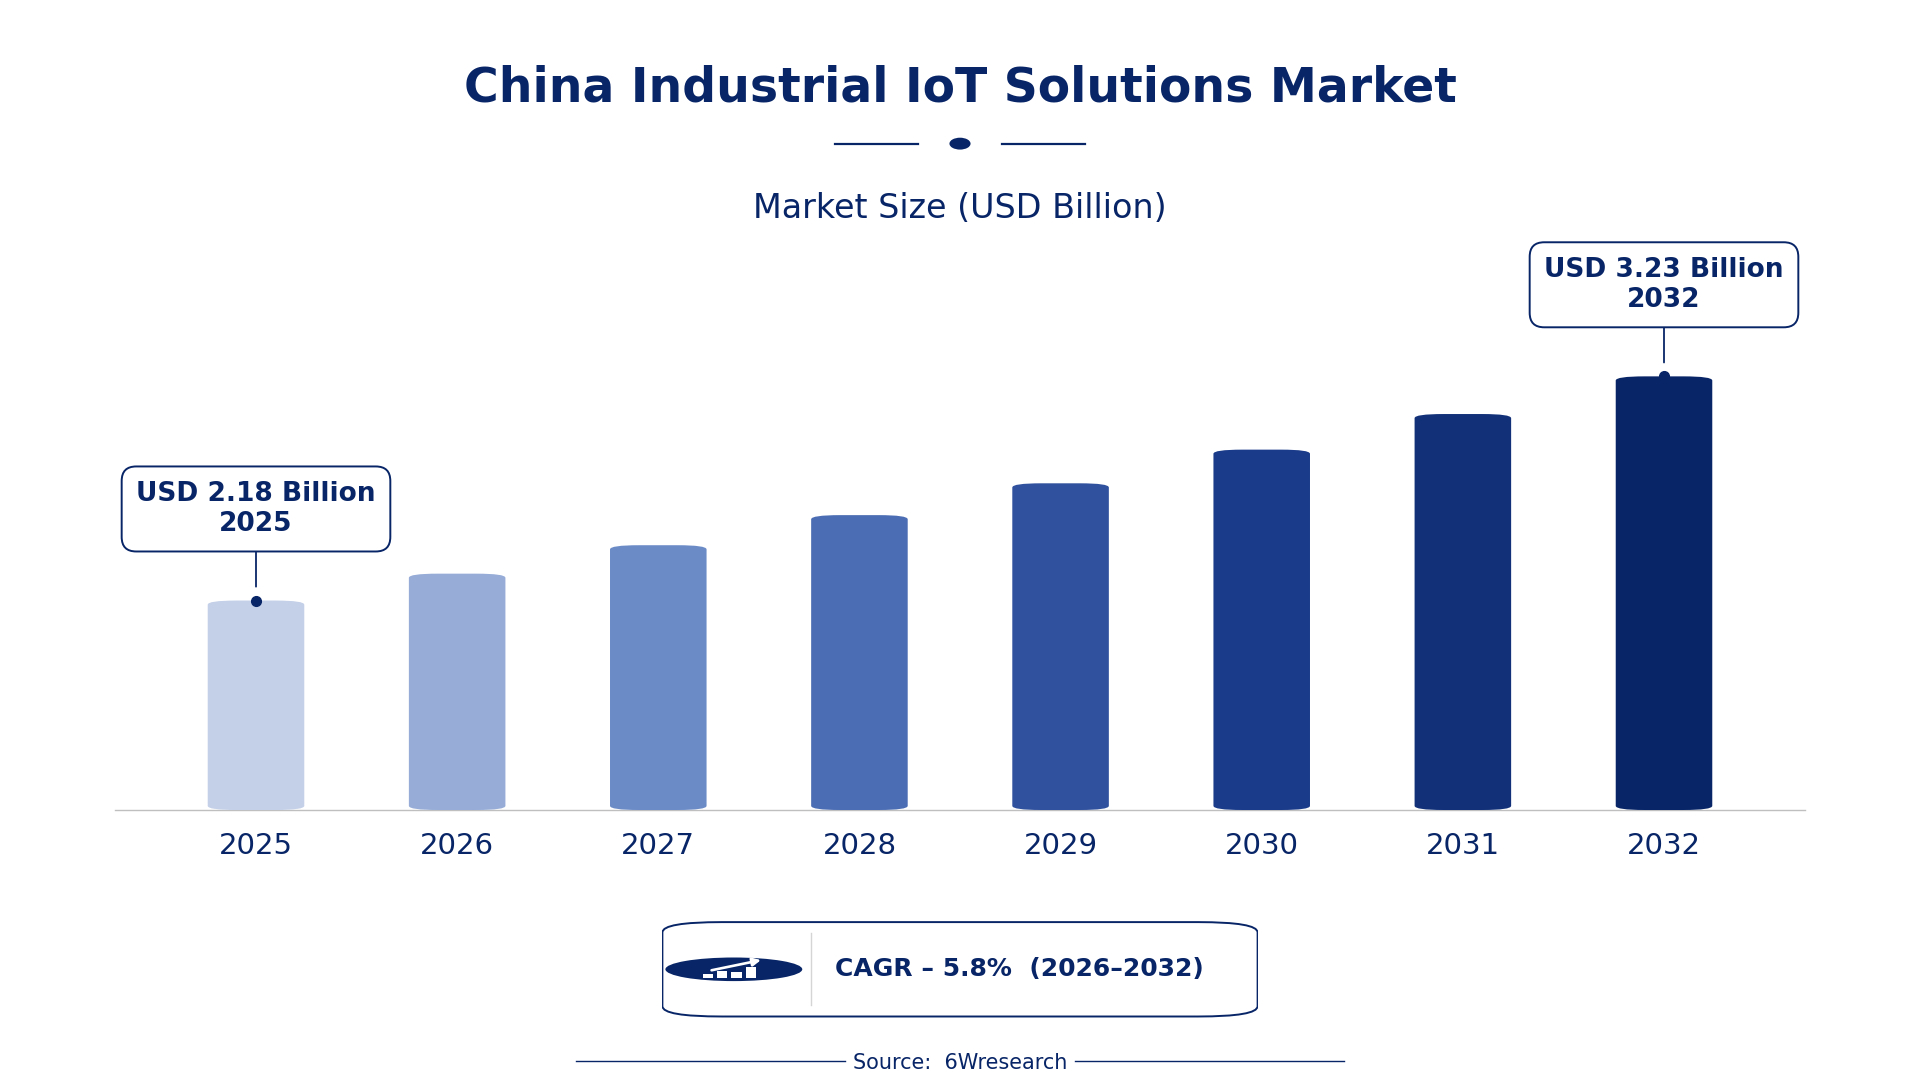
According to 6Wresearch internal database and industry insights, the China Industrial IoT Solutions Market was valued at USD 2.18 billion in 2025 and is projected to reach USD 3.23 billion by 2032, growing at a CAGR of approximately 5.8% during 2026–2032.
China Industrial IoT Solutions Market Highlights
| Report Metric | Details |
| Report Name | China Industrial IoT Solutions Market |
| Market Size 2025 | USD 2.18 billion |
| Market Size 2032 | USD 3.23 billion |
| Absolute Growth 2025–2032 | USD 1.05 billion |
| CAGR 2026–2032 | 5.8% |
| Peak Annual Growth | 8.0% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Solution Type, 2025 | Condition Monitoring (38% share) |
| Leading AI Integration, 2025 | Cloud-Based (36% share) |
| Leading Monitoring Type, 2025 | Real-Time (51% share) |
| Leading End User, 2025 | Logistics & Supply Chain (42% share) |
| Fastest-Growing Solution Type | Smart Asset Tracking (7.1% CAGR) |
| Fastest-Growing AI Integration | Edge AI (8.1% CAGR) |
| Fastest-Growing End User | Smart Factories (7.0% CAGR) |
| Growing Sector | Smart Factories |
| Key End Users | Logistics & Supply Chain, Heavy Equipment, Smart Factories, Oil & Gas Sites |
China Industrial IoT Solutions Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
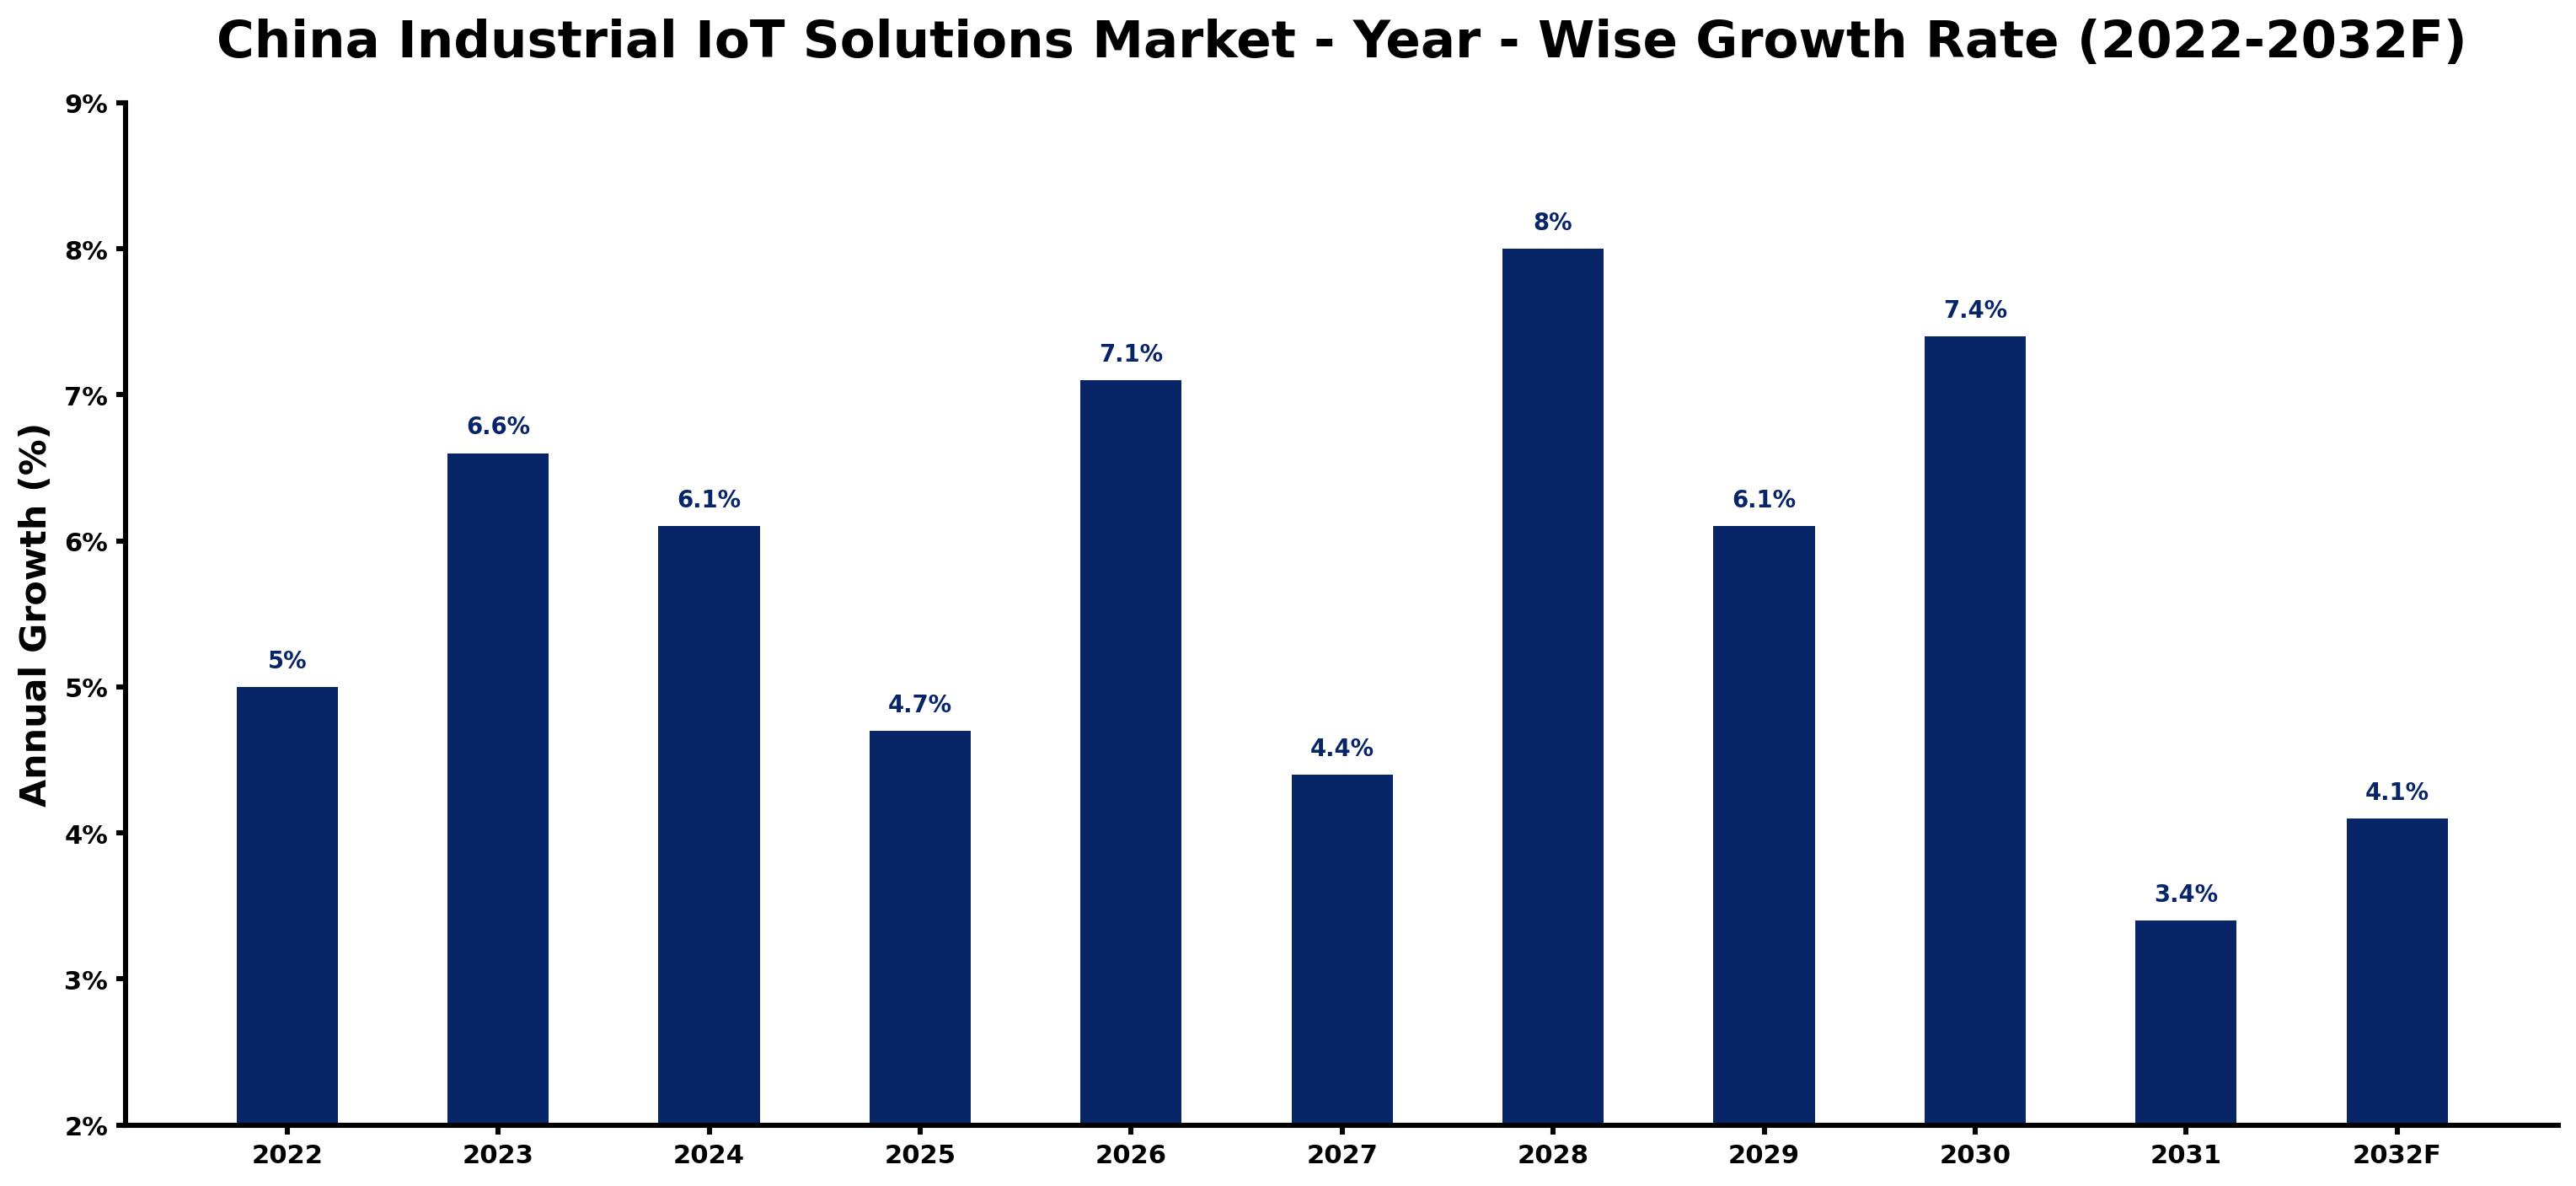
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.0 | The market exhibited steady growth due to increased adoption of IoT technologies in manufacturing and logistics. |
| 2023 | 6.6 | Demand surged as the installed base of IoT devices in manufacturing reached 200 million units. |
| 2024 | 6.1 | Growth slowed as companies adjusted their strategies to integrate IoT solutions more effectively. |
| 2025 | 4.7 | A continued slowdown occurred as industries focused on optimising existing IoT implementations. |
| 2026 | 7.1 | Growth is expected to accelerate again, driven by the Smart Manufacturing Pilot Program promoting IoT adoption in factories. |
| 2027 | 4.4 | A slowdown is projected as firms face challenges in scaling their IoT infrastructure. |
| 2028 | 8.0 | The market is expected to peak in growth as investments in IoT infrastructure reach 500 billion yuan in 2023. |
| 2029 | 6.1 | A slowdown will occur as companies consolidate their IoT strategies post-peak growth. |
| 2030 | 7.4 | Growth is projected to accelerate again due to the ongoing push for smart manufacturing technologies. |
| 2031 | 3.4 | A slowdown is anticipated as market dynamics stabilise following rapid expansion. |
| 2032 | 4.1 | Growth is expected to rise as the Digital China initiative integrates IoT across industries. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial IoT Solutions Market Synopsis
Industrial IoT Solutions in China encompass technologies that enable connectivity and data exchange among industrial devices. These solutions improve operational efficiency, predictive maintenance, and real-time monitoring across sectors like logistics and manufacturing. The China Industrial IoT Solutions Market is projected to reach 1 trillion yuan by 2025, driven by the increasing adoption of smart manufacturing technologies. Key demand sources include logistics and supply chain sectors, with over 60% of logistics companies already utilising IoT solutions for asset tracking. The ongoing 'Made in China 2025' initiative further fuels this growth by emphasising the importance of smart technologies.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing adoption of IoT technologies in manufacturing sectors enhances operational efficiency. | Driver | High | Condition Monitoring |
| The demand for real-time data processing in logistics drives investment in IoT solutions. | Driver | High | Real-Time |
| Growing logistics companies require advanced tracking solutions to optimise operations. | Opportunity | High | Smart Asset Tracking |
| The push for energy efficiency in industries creates demand for smart energy management solutions. | Opportunity | Medium | Smart Energy Management |
| Limited integration capabilities of existing systems hinder IoT adoption in some sectors. | Restraint | High | Remote Operations Solution |
| High initial investment costs for IoT infrastructure can deter smaller companies from adoption. | Restraint | Medium | Cloud-Based |
| Complex regulatory requirements can slow down the deployment of IoT solutions. | Challenge | High | IoT + SCADA |
| The rapid pace of technological change can lead to obsolescence of existing solutions. | Challenge | Medium | Predictive Algorithms |
Evaluation of Drivers in China Industrial IoT Solutions Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investment in smart manufacturing technologies drives demand for IoT solutions. | Condition Monitoring | The 'Made in China 2025' initiative aims to promote smart manufacturing, leading to higher IoT adoption. |
| The need for real-time data analytics boosts demand for IoT solutions in logistics. | Real-Time | Over 60% of logistics companies in China utilise IoT for asset tracking, increasing purchases. |
| Demand for predictive maintenance solutions is rising in various industrial sectors. | Remote Operations Solution | The installed base of IoT devices in manufacturing reached 200 million units in 2022. |
| Growing focus on energy efficiency drives investment in smart energy management solutions. | Smart Energy Management | The total investment in IoT infrastructure was reported at 500 billion yuan in 2023. |
| The expansion of logistics networks necessitates smart asset tracking solutions. | Smart Asset Tracking | Logistics & Supply Chain is the largest end-user segment, accounting for 42% market share. |
Market growth for Industrial IoT Solutions in China is underpinned by increasing adoption among logistics and manufacturing sectors, with demand for real-time data analytics driving purchases. In 2022, the installed base of IoT devices in manufacturing reached 200 million units, which allowed companies to improve their operational processes. Total investment in IoT infrastructure was reported at 500 billion yuan in 2023, expanding market capabilities. Logistics companies increasingly utilise IoT for asset tracking, further boosting demand.
Evaluation of Restraints in China Industrial IoT Solutions Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Limited availability of skilled workforce hampers IoT implementation. | Condition Monitoring | Only 30% of the workforce is trained in advanced IoT technologies, increasing operational costs. |
| Supply chain disruptions affect component availability for IoT devices. | Smart Asset Tracking | Dependence on specific components sourced from limited regions can delay project timelines by up to six months. |
| High competition in the market leads to price pressures. | Remote Operations Solution | With over 200 companies competing, smaller players often lower prices, sacrificing margins. |
| Rapid technological advancements create obsolescence risks. | Smart Energy Management | 40% of firms struggle to keep pace with innovations, limiting their ability to adapt effectively. |
| Regulatory compliance challenges increase operational complexity. | Real-Time | New guidelines require extensive testing and certification, adding to project timelines. |
China Industrial IoT Solutions Market Challenges
Producers in the China Industrial IoT Solutions market face supply chain disruptions due to dependency on specific components sourced from limited regions, which can delay project timelines by up to six months. Skills shortages hinder growth, as only 30% of the workforce is trained in advanced IoT technologies, resulting in increased operational costs for manufacturers. Importers encounter fierce competition, with over 200 companies vying for market share, forcing smaller firms to lower prices and erode profit margins. Technology adoption lags, as 40% of companies struggle to keep pace with rapid advancements, risking obsolescence and limiting their ability to innovate effectively.
Trends in the China Industrial IoT Solutions Market
Below mentioned are some of the trends shaping the China Industrial IoT Solutions Market growth.
- Shift towards Real-Time Monitoring: The Smart Manufacturing Pilot Program initiated in 2020 has accelerated the adoption of real-time monitoring solutions in factories. By 2023, over 60% of logistics companies have integrated IoT for asset tracking, improving their operational processes.
- Transition from Traditional to Smart Manufacturing: Since 2021, the 'Industrial Internet Innovation and Development Strategy' has driven the shift towards smart manufacturing in China. This transition is expected to increase the market size to 1 trillion yuan by 2025.
- Emergence of Edge AI Solutions: The adoption of Edge AI solutions is gaining traction, particularly in manufacturing. By 2026, this segment is projected to grow at a CAGR of 8.1%, driven by the need for real-time data processing.
- Prioritisation of Energy Management Solutions: The focus on energy efficiency has led to increased investment in smart energy management solutions. By 2023, total investment in IoT infrastructure reached 500 billion yuan, facilitating this trend.
Investment Opportunities in the China Industrial IoT Solutions Market
Investors looking at the China Industrial IoT Solutions Market should consider the following areas.
- Logistics Companies Seeking IoT Solutions: Logistics companies in China are increasingly adopting IoT solutions for asset tracking, with over 60% already utilising these technologies. This presents an opportunity for suppliers to provide tailored IoT solutions to improve operational efficiency.
- Manufacturing Facilities Adopting Smart Technologies: Manufacturing facilities are prioritising the integration of smart technologies to improve productivity. With the market projected to reach 1 trillion yuan by 2025, suppliers can enter through partnerships with local manufacturers.
- Investment in Smart Energy Management Solutions: There is a growing demand for smart energy management solutions in various industrial sectors. Suppliers can target this opportunity by collaborating with energy-intensive industries to optimise their operations.
- Entry into the Edge AI Market: The Edge AI segment is anticipated to grow rapidly, with a projected CAGR of 8.1% from 2026 to 2032. Suppliers can enter this market through joint ventures with technology firms focusing on AI integration.
Government Initiatives in the China Industrial IoT Solutions Market
The '14th Five-Year Plan for Economic and Social Development', issued by the National Development and Reform Commission in 2021, emphasises the role of IoT in industrial transformation. This plan aims to facilitate the integration of IoT technologies across various sectors. The 'National Standard for Internet of Things (IoT) - General Requirements', approved by the Standardization Administration of China in 2022, enhances compliance for IoT solutions, ensuring that producers meet necessary standards. The 'Smart Manufacturing Development Plan', launched in 2020 by the Ministry of Industry and Information Technology, promotes IoT integration in manufacturing processes, driving innovation and efficiency. The 'China IoT Industry Development Action Plan', updated in 2021, aims for a 30% increase in IoT application in key industries by 2025, further supporting market growth.
The National Development and Reform Commission is responsible for approving and funding IoT innovation projects. In 2023, a budget of 300 million yuan was announced to support these initiatives across various sectors. The Ministry of Industry and Information Technology also plays a significant role in funding IoT development, ensuring that key projects receive the necessary financial backing. This support enables producers to invest in advanced technologies, fostering growth in the Industrial IoT Solutions market. The National Standard for IoT in Manufacturing, updated in 2022, streamlines compliance processes for manufacturers.
Future Insight of the China Industrial IoT Solutions Market
The China Industrial IoT Solutions market will undergo significant changes by 2032, driven by the 'Digital China' initiative that aims to integrate IoT technologies across various sectors. By 2025, the installed base of IoT devices in manufacturing is expected to reach 500 million units, which will improve operational efficiencies. The Smart Manufacturing Pilot Program will encourage broader adoption of smart technologies in factories, prompting suppliers to innovate. Updated guidelines from the National Standard for IoT in Manufacturing will streamline processes, providing clear advantages for both buyers and suppliers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Solution Type – Condition Monitoring Dominated, Smart Asset Tracking Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, Condition Monitoring accounted for a 38% market share by solution type in 2025. Condition Monitoring holds the largest share as it is crucial for predictive maintenance and operational efficiency in industries such as manufacturing. The extensive installed base of IoT devices, reaching 200 million units, highlights its widespread adoption and importance. Smart Asset Tracking is set to record the highest CAGR in this split, 7.1% over 2026–2032. Smart Asset Tracking is experiencing rapid growth due to the increasing adoption of IoT solutions by logistics companies, with over 60% currently using these technologies. This trend is expected to continue as demand for efficient supply chain management rises. Suppliers should focus on enhancing their Smart Asset Tracking solutions to capitalise on the growing market share.
By AI Integration – Cloud-Based Dominated, Edge AI Expected to Grow Fastest
Cloud-Based took a 36% share of ai integration in 2025, more than any other category. Cloud-Based solutions dominate the market by facilitating essential data storage and analysis for IoT applications, which are vital for operational efficiency. The significant investment of 500 billion yuan in IoT infrastructure in 2023 further solidifies this segment's leading position. Edge AI is projected to grow fastest, at a CAGR of 8.1% during 2026–2032. Edge AI is rapidly growing as it enables data processing at the source, making it suitable for real-time applications. This segment's growth is driven by the increasing need for immediate data insights across various industrial sectors. Buyers should consider integrating Edge AI to improve data processing capabilities and enhance operational responsiveness.
By Monitoring Type – Real-Time Dominated and Is Expected to Record the Fastest Growth
The largest monitoring type category in 2025 was Real-Time, with a 51% share of total revenue. Real-Time monitoring is essential for immediate data processing and response, making it the leading type in the market. The emphasis on real-time solutions aligns with initiatives like the 'Digital China' initiative, which aims to integrate IoT technologies across multiple industries. Real-Time is also forecast to expand faster than any other category, at a CAGR of 6.9% over 2026–2032. As Real-Time monitoring is already the leader, its growth will continue to widen as industries increasingly demand immediate insights for operational efficiency. This demand is reinforced by the ongoing push for smart manufacturing technologies. Suppliers must ensure their solutions support real-time capabilities to meet the rising expectations of industrial clients.
By End User – Logistics & Supply Chain Dominated, Smart Factories Expected to Grow Fastest
With a 42% revenue share in 2025, Logistics & Supply Chain was the largest end user category. Logistics & Supply Chain is the leading end user, benefiting greatly from IoT technologies that enhance operational efficiency and asset management. With over 60% of logistics companies utilising IoT solutions, this sector's market share is well-established. Over 2026–2032, Smart Factories are expected to post the fastest growth, at a CAGR of 7.0%. Smart Factories are the fastest-growing segment due to their essential role in improving manufacturing processes. The rising demand for automation and efficiency in production is propelling this growth. Buyers in the manufacturing sector should invest in Smart Factory solutions to ensure they remain competitive.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial IoT Solutions Market Outlook
- Market Size of China Industrial IoT Solutions Market, 2025
- Forecast of China Industrial IoT Solutions Market, 2032
- Historical Data and Forecast of China Industrial IoT Solutions Revenues & Volume for the Period 2022 - 2032F
- China Industrial IoT Solutions Market Trend Evolution
- China Industrial IoT Solutions Market Drivers and Challenges
- China Industrial IoT Solutions Price Trends
- China Industrial IoT Solutions Porter's Five Forces
- China Industrial IoT Solutions Industry Life Cycle
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Solution Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Condition Monitoring for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Smart Asset Tracking for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Remote Operations Solution for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Smart Energy Management for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By AI Integration for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Edge AI for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Cloud-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By IoT + SCADA for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Predictive Algorithms for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Monitoring Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Real-Time for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Location-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Distributed for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Load Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Heavy Equipment for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Logistics & Supply Chain for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Oil & Gas Sites for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial IoT Solutions Market Revenues & Volume By Smart Factories for the Period 2022 - 2032F
- China Industrial IoT Solutions Import Export Trade Statistics
- Market Opportunity Assessment By Solution Type
- Market Opportunity Assessment By AI Integration
- Market Opportunity Assessment By Monitoring Type
- Market Opportunity Assessment By End User
- China Industrial IoT Solutions Top Companies Market Share
- China Industrial IoT Solutions Competitive Benchmarking By Technical and Operational Parameters
- China Industrial IoT Solutions Company Profiles
- China Industrial IoT Solutions Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Solution Type
- Condition Monitoring
- Smart Asset Tracking
- Remote Operations Solution
- Smart Energy Management
By AI Integration
- Edge AI
- Cloud-Based
- IoT + SCADA
- Predictive Algorithms
By Monitoring Type
- Real-Time
- Location-Based
- Distributed
- Load Control
By End User
- Heavy Equipment
- Logistics & Supply Chain
- Oil & Gas Sites
- Smart Factories































