China Industrial Manufacturing Market Size & Growth Rate
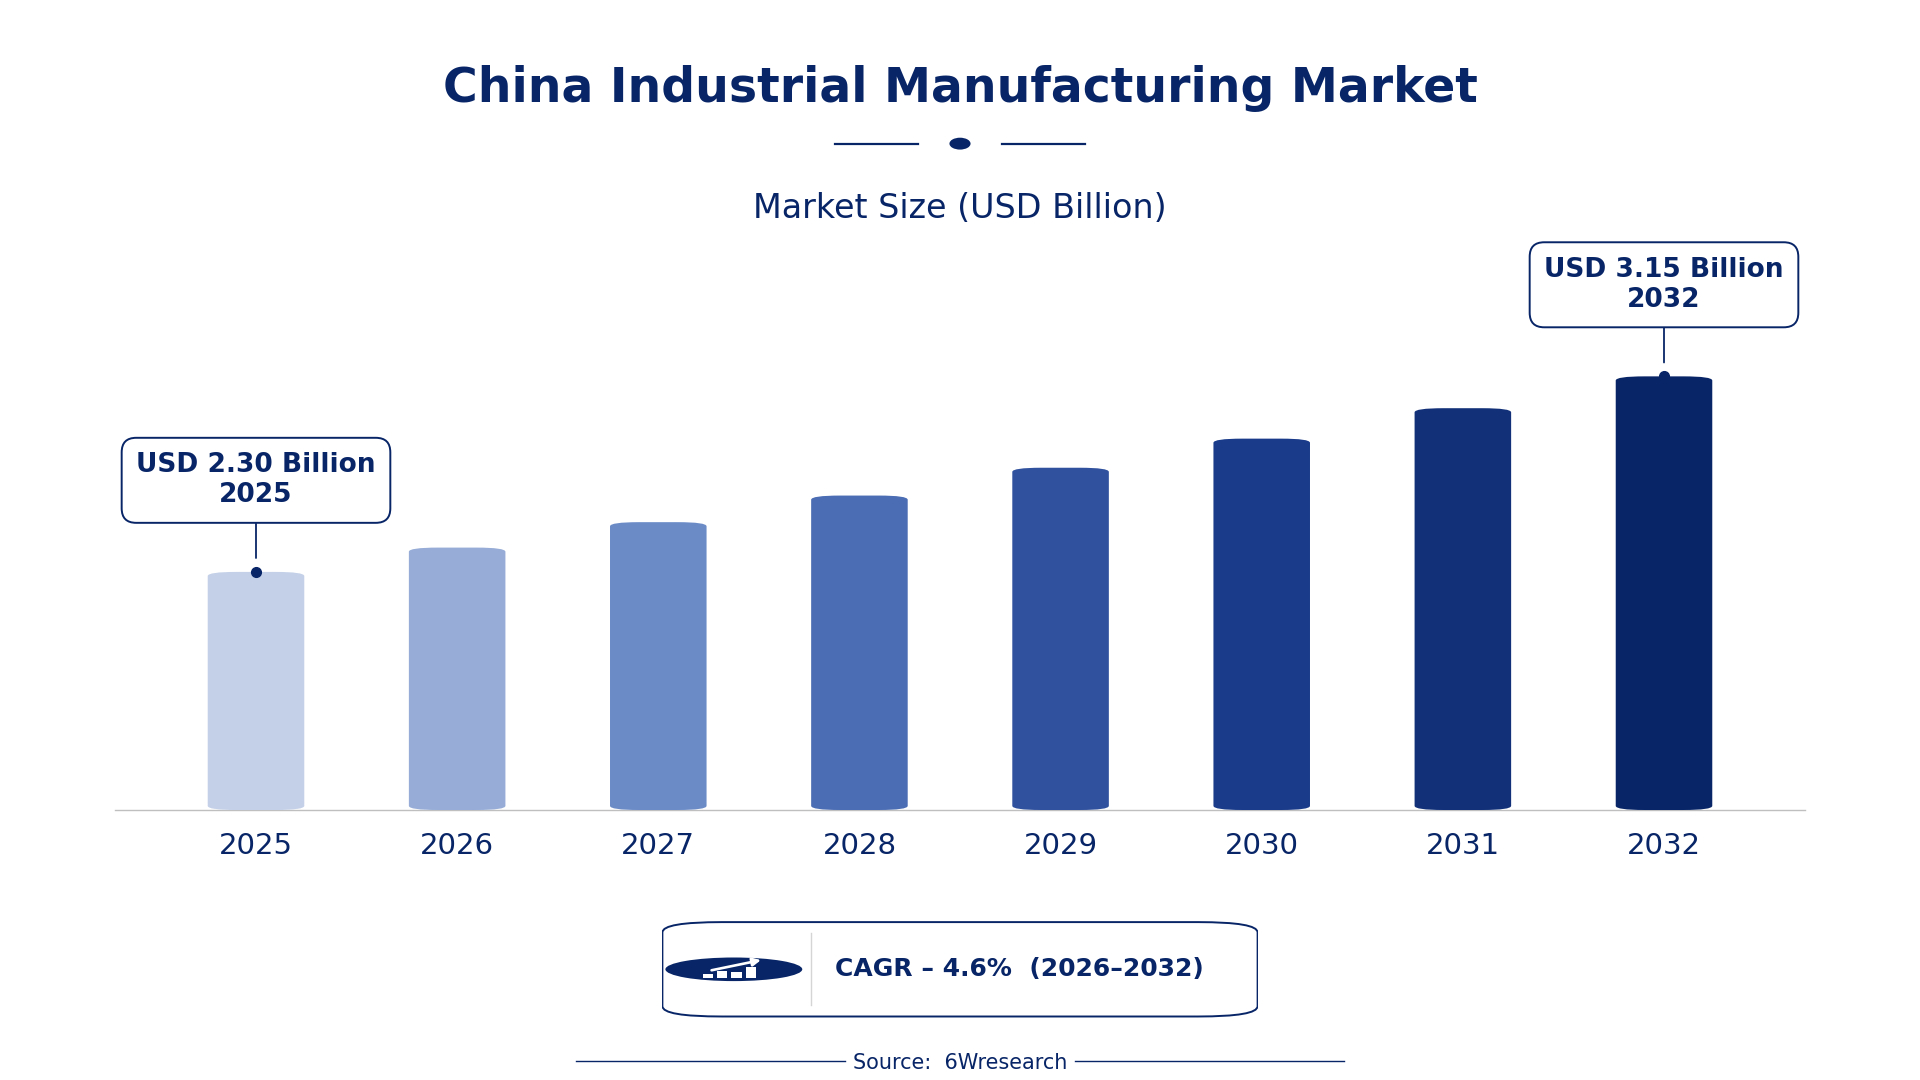
According to 6Wresearch internal database and industry insights, the China Industrial Manufacturing Market was valued at USD 2.30 billion in 2025 and is projected to reach USD 3.15 billion by 2032, growing at a CAGR of approximately 4.6% during 2026–2032.
China Industrial Manufacturing Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Manufacturing Market |
| Market Size 2025 | USD 2.30 billion |
| Market Size 2032 | USD 3.15 billion |
| Absolute Growth 2025–2032 | USD 0.85 billion |
| CAGR 2026–2032 | 4.6% |
| Peak Annual Growth | 6.8% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Manufacturing Type, 2025 | Process Manufacturing (35% share) |
| Leading Process Category, 2025 | Chemical/Batch (34% share) |
| Leading Automation Level, 2025 | Integrated (43% share) |
| Leading End User, 2025 | Electronics Production (42% share) |
| Fastest-Growing Manufacturing Type | Additive Manufacturing (6.5% CAGR) |
| Fastest-Growing Process Category | 3D Printing/Prototyping (5.8% CAGR) |
| Fastest-Growing End User | R&D Labs (6.9% CAGR) |
| Growing Sector | Electronics Production |
| Key End Users | Manufacturers, R&D Labs, Electronics Producers, Food & Beverage Companies |
China Industrial Manufacturing Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
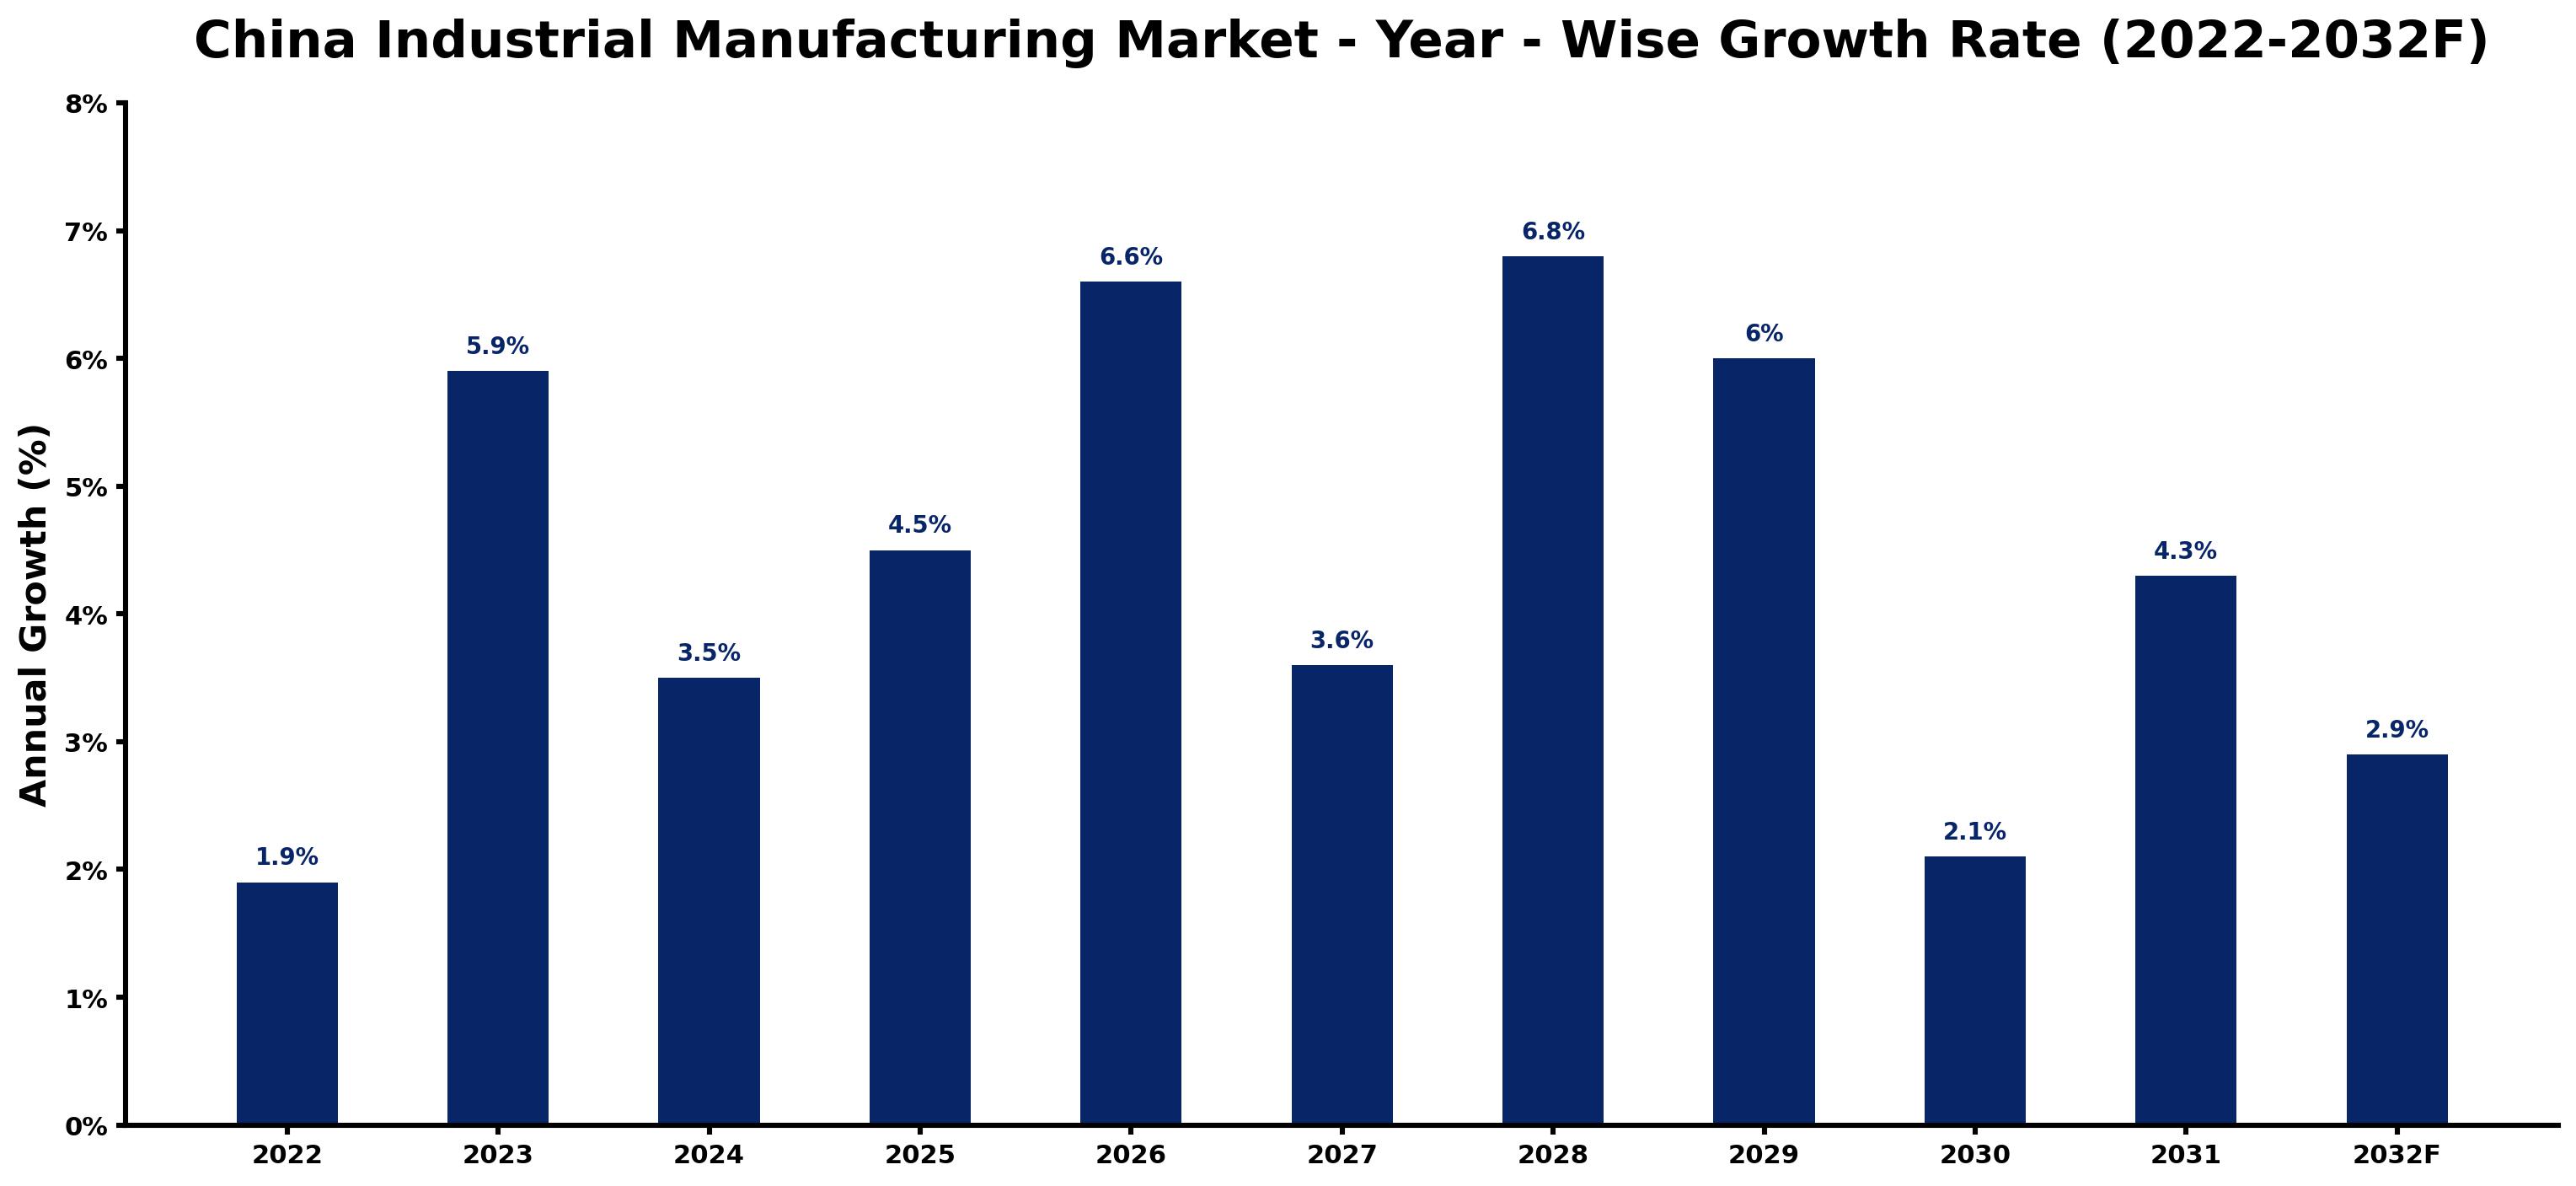
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 1.9 | The industrial manufacturing sector showed steady performance, reflecting ongoing demand from various industries. |
| 2023 | 5.9 | Growth accelerated due to increased investments in automation and smart manufacturing technologies. |
| 2024 | 3.5 | The market experienced a slowdown as firms adjusted to previous rapid expansions and demand stabilised. |
| 2025 | 4.5 | A resurgence in production activities boosted growth, particularly in electronics and machinery sectors. |
| 2026 | 6.6 | The market is expected to grow as integrated systems enhance efficiency in production. |
| 2027 | 3.6 | Demand growth is expected to slow as manufacturers face challenges in sourcing raw materials. |
| 2028 | 6.8 | A peak in growth is anticipated, driven by investments in advanced manufacturing technologies. |
| 2029 | 6.0 | Growth is projected to decelerate as the market stabilises after reaching a peak in the previous year. |
| 2030 | 2.1 | The market will continue to grow, albeit at a slower pace, as firms focus on efficiency improvements. |
| 2031 | 4.3 | A renewed interest in automation technologies is expected to drive growth in the manufacturing sector. |
| 2032 | 2.9 | Growth is anticipated to slow as the market matures, with a focus on sustainable practices. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Manufacturing Market Synopsis
Industrial Manufacturing in China encompasses various processes and technologies aimed at producing goods efficiently. It involves the use of machinery, tools, and labour to transform raw materials into finished products. The China Industrial Manufacturing Market is expanding due to robust domestic demand and investments in automation technologies. In 2022, the sector contributed over 30% to the national GDP, underscoring its importance. Key drivers include the 'Made in China 2025' initiative and the growth of smart manufacturing capabilities, which are boosting productivity and innovation.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased investments in automation technologies are driving demand for advanced manufacturing solutions. | Driver | High | Integrated |
| The rapid growth of the electronics production sector is creating opportunities for manufacturers. | Opportunity | High | Electronics Production |
| Quality control challenges in manufacturing processes are restraining operational efficiency. | Restraint | High | Chemical/Batch |
| The need for skilled labor in advanced manufacturing is a significant challenge for suppliers. | Challenge | High | Additive Manufacturing |
| The adoption of robotics in manufacturing is enhancing productivity and efficiency. | Driver | Medium | Process Manufacturing |
| The growing demand for 3D printing technologies presents opportunities for innovation. | Opportunity | Medium | 3D Printing/Prototyping |
| Regulatory compliance costs are impacting profitability for manufacturers. | Restraint | Medium | Discrete Manufacturing |
| Competition from low-cost manufacturing countries poses a challenge for local producers. | Challenge | Medium | Process Manufacturing |
Evaluation of Drivers in China Industrial Manufacturing Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Investment in automation technologies is improving production efficiency and capacity. | Integrated | China's manufacturing investment reached 5 trillion yuan in 2022, boosting automation adoption. |
| The rapid growth of the electronics production sector is driving demand for advanced manufacturing solutions. | Electronics Production | In 2022, China's electronics production reached approximately 1.5 trillion yuan, increasing demand. |
| The 'Made in China 2025' initiative promotes innovation and technology in manufacturing processes. | Process Manufacturing | Launched in 2015, this initiative aims to upgrade manufacturing capabilities across sectors. |
| The increasing focus on quality management systems is driving demand for ISO 9001 certification services. | Chemical/Batch | ISO 9001 is widely adopted, ensuring quality and reliability in manufacturing processes. |
| The expansion of R&D labs is driving innovation in manufacturing technologies. | R&D Labs | Supported by the National Natural Science Foundation, over 30,000 projects are funded annually. |
Growth in the Industrial Manufacturing market in China is anchored in increased investments in automation technologies, the rapid expansion of the electronics production sector, and a focus on quality management systems. In 2022, China's manufacturing investment reached 5 trillion yuan, greatly improving production efficiency. The electronics production sector generated approximately 1.5 trillion yuan, driving demand for advanced manufacturing solutions. The expansion of R&D labs, supported by the National Natural Science Foundation, is advancing manufacturing technologies.
Evaluation of Restraints in China Industrial Manufacturing Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Quality control challenges in manufacturing processes impact operational efficiency. | Chemical/Batch | New standards for quality control were implemented in 2023, increasing compliance costs for manufacturers. |
| Regulatory compliance costs are affecting profitability for manufacturers. | Discrete Manufacturing | Manufacturers must adhere to stringent regulations, leading to increased operational expenses. |
| The need for skilled labor in advanced manufacturing poses challenges for suppliers. | Additive Manufacturing | The sector requires highly skilled workers, which are in short supply, delaying production timelines. |
| Competition from low-cost manufacturing countries reduces market share for local producers. | Process Manufacturing | Local manufacturers face pressure from overseas competitors offering lower prices. |
| Supply chain disruptions are affecting the availability of raw materials and components. | Integrated | Global supply chain issues have led to delays in sourcing essential materials for production. |
China Industrial Manufacturing Market Challenges
The China industrial manufacturing market faces a skills shortage, as many workers lack training in modern technologies. This gap arises because educational institutions have not adapted their programmes to meet industry demands, resulting in delays that can extend project timelines by up to six months for producers. Buyers experience increased costs due to fluctuating raw material prices, which can raise production expenses by approximately 15%, forcing them to adjust pricing strategies. Regulatory challenges complicate operations, as navigating complex compliance standards can elevate operational costs and expose suppliers to potential fines, impacting their profitability.
Trends in the China Industrial Manufacturing Market
Below mentioned are some of the trends shaping the China Industrial Manufacturing Market growth.
- Shift towards Automation in Manufacturing: Manufacturers are increasingly adopting automation technologies to improve efficiency and reduce costs. The 'Made in China 2025' initiative has accelerated this trend, with automation investments reaching 5 trillion yuan in 2022.
- Growing Adoption of 3D Printing Technologies: 3D printing is becoming a mainstream manufacturing method, particularly in prototyping and production. This shift is evidenced by the projected annual production of 3D printing materials exceeding 1 million tons by 2025.
- Increased Focus on Quality Management: Manufacturers are prioritising quality management systems to meet regulatory standards. The widespread adoption of ISO 9001 has become essential for maintaining product quality and safety in the market.
- Expansion of R&D Labs: R&D labs are expanding their capabilities to drive innovation in manufacturing processes. Supported by the National Natural Science Foundation, over 30,000 projects are funded annually, leading to advancements in technology.
Investment Opportunities in the China Industrial Manufacturing Market
Several openings in the China Industrial Manufacturing Market merit attention from investors.
- Timing for Investment in Automation: Now is an opportune time to invest in automation technologies, with manufacturing investment reaching 5 trillion yuan in 2022. Buyers in the electronics production sector are seeking advanced solutions to improve efficiency.
- Supply of 3D Printing Materials: The demand for 3D printing materials is projected to exceed 1 million tons by 2025. Suppliers can target the growing R&D labs and prototyping sectors to meet this demand effectively.
- Support for Quality Management Systems: With the increasing focus on quality management, there is an opportunity for suppliers of ISO 9001 certification services. Manufacturers in the food and beverage sector require compliance to ensure product safety.
- Investment in Robotics: The robotics sector is expected to grow by 20% annually through 2025. Manufacturers in various sectors are looking to integrate robotics to improve productivity and efficiency.
Government Initiatives in the China Industrial Manufacturing Market
The 'Made in China 2025' initiative, launched by the Ministry of Industry and Information Technology in 2015, aims to upgrade the manufacturing sector by promoting innovation and technology adoption. The '14th Five-Year Plan for Economic and Social Development', introduced in 2021, further develops manufacturing capabilities and encourages green technologies. Additionally, the 'Action Plan for Promoting Intelligent Manufacturing' by the National Development and Reform Commission in 2022 targets a 30% increase in smart manufacturing adoption by 2025, ensuring competitiveness in the global market.
The Ministry of Industry and Information Technology oversees the implementation of new quality control standards in manufacturing processes, ensuring product safety and reliability. This agency's efforts support manufacturers in meeting compliance requirements, which is essential for maintaining market access. The National Development and Reform Commission also funds initiatives aimed at increasing robotics adoption, targeting a 20% annual growth through 2025. These measures collectively empower manufacturers to innovate and improve their operational efficiency.
Future Insight of the China Industrial Manufacturing Market
The China industrial manufacturing market is set to evolve by 2032, driven by the 'Made in China 2025' initiative that prioritises automation and smart technologies. Investment in robotics is projected to increase, with a goal to enhance usage by 20% by 2025, streamlining processes for suppliers. Additionally, China's annual production of 3D printing materials is expected to exceed 1 million tons, providing buyers with advanced manufacturing capabilities. Enhanced research and development, supported by the National Natural Science Foundation, will further innovate the sector, creating opportunities for both buyers and suppliers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Manufacturing Type – Process Manufacturing Dominated, Additive Manufacturing Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, Process Manufacturing accounted for a 35% market share by manufacturing type in 2025. Process manufacturing holds the largest market share due to its essential role in producing goods through chemical or physical processes, particularly in the food and beverage sector. For instance, this segment benefits from the robust workforce of over 10 million employed in food and beverage manufacturing. Additive Manufacturing is projected to grow fastest, at a CAGR of 6.5% during 2026–2032. Additive manufacturing is experiencing rapid growth, fuelled by the increasing adoption of technologies like 3D printing for creating components layer by layer. The anticipated production of over 1 million tons of 3D printing materials by 2025 indicates a strong upward trend in this area. Suppliers should focus on enhancing their additive manufacturing capabilities to capture the growing market share.
By Process Category – Chemical/Batch Dominated, 3D Printing/Prototyping Expected to Grow Fastest
The largest process category category in 2025 was Chemical/Batch, with a 34% share of total revenue. The chemical/batch process category leads the market as it is vital for producing chemicals in batches, a key requirement for various manufacturing sectors. This process significantly contributes to China's industrial output, ensuring consistent demand for its products. 3D Printing/Prototyping is set to record the highest CAGR in this split, 5.8% over 2026–2032. 3D printing/prototyping is the fastest-growing segment, driven by its expanding use in rapid prototyping and production across diverse industries. This technology allows manufacturers to quickly adapt to market changes, further boosting its popularity. Buyers should consider investing in 3D printing technologies to stay competitive and responsive to evolving production needs.
By Automation Level – Integrated Dominated and Is Expected to Record the Fastest Growth
Integrated took a 43% share of automation level in 2025, more than any other category. Integrated systems dominate the automation level segment because they enhance efficiency and coordination in manufacturing processes, which is essential for maintaining competitiveness. The substantial investment of 5 trillion yuan in automation in 2022 underscores the significance of this trend in China's manufacturing sector. The same category is also set to grow fastest, at a CAGR of 6.1% during 2026–2032. Integrated systems are also the fastest-growing segment, as their benefits in streamlining operations are increasingly recognised. This trend towards automation and smart manufacturing will likely reinforce the position of integrated systems in the market. Suppliers must prioritise integrated solutions to align with the industry's shift towards greater automation.
By End User – Electronics Production Dominated, R&D Labs Expected to Grow Fastest
With a 42% revenue share in 2025, Electronics Production was the largest end user category. Electronics production leads the end user segment, heavily relying on advanced manufacturing techniques to meet the high demand for electronic goods. China's electronics production reached approximately 1.5 trillion yuan in 2022, reflecting the sector's substantial market share. Over 2026–2032, R&D Labs are expected to post the fastest growth, at a CAGR of 6.9%. R&D labs are the fastest-growing end user, utilising manufacturing technologies for product development and innovation. The support from the National Natural Science Foundation funding over 30,000 projects annually highlights the increasing importance of R&D in manufacturing. Suppliers should target R&D labs to capitalise on their growing need for advanced manufacturing technologies.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Manufacturing Market Outlook
- Market Size of China Industrial Manufacturing Market, 2025
- Forecast of China Industrial Manufacturing Market, 2032
- Historical Data and Forecast of China Industrial Manufacturing Revenues & Volume for the Period 2022 - 2032F
- China Industrial Manufacturing Market Trend Evolution
- China Industrial Manufacturing Market Drivers and Challenges
- China Industrial Manufacturing Price Trends
- China Industrial Manufacturing Porter's Five Forces
- China Industrial Manufacturing Industry Life Cycle
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By Manufacturing Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By Discrete Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By Process Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By Additive Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By Continuous Flow Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By Process Category for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By Cutting/Assembly for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By Chemical/Batch for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By 3D Printing/Prototyping for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By Conveyor/Batch Mixing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By Automation Level for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By Semi/Full for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By PLC/SCADA for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By CNC-Controlled for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By Integrated for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By Aerospace Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By Food & Beverage Plants for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By R&D Labs for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Manufacturing Market Revenues & Volume By Electronics Production for the Period 2022 - 2032F
- China Industrial Manufacturing Import Export Trade Statistics
- Market Opportunity Assessment By Manufacturing Type
- Market Opportunity Assessment By Process Category
- Market Opportunity Assessment By Automation Level
- Market Opportunity Assessment By End User
- China Industrial Manufacturing Top Companies Market Share
- China Industrial Manufacturing Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Manufacturing Company Profiles
- China Industrial Manufacturing Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Manufacturing Type
- Discrete Manufacturing
- Process Manufacturing
- Additive Manufacturing
- Continuous Flow Systems
By Process Category
- Cutting/Assembly
- Chemical/Batch
- 3D Printing/Prototyping
- Conveyor/Batch Mixing
By Automation Level
- Semi/Full
- PLC/SCADA
- CNC-Controlled
- Integrated
By End User
- Aerospace Components
- Food & Beverage Plants
- R&D Labs
- Electronics Production































