China Industrial Metal Market Size & Growth Rate
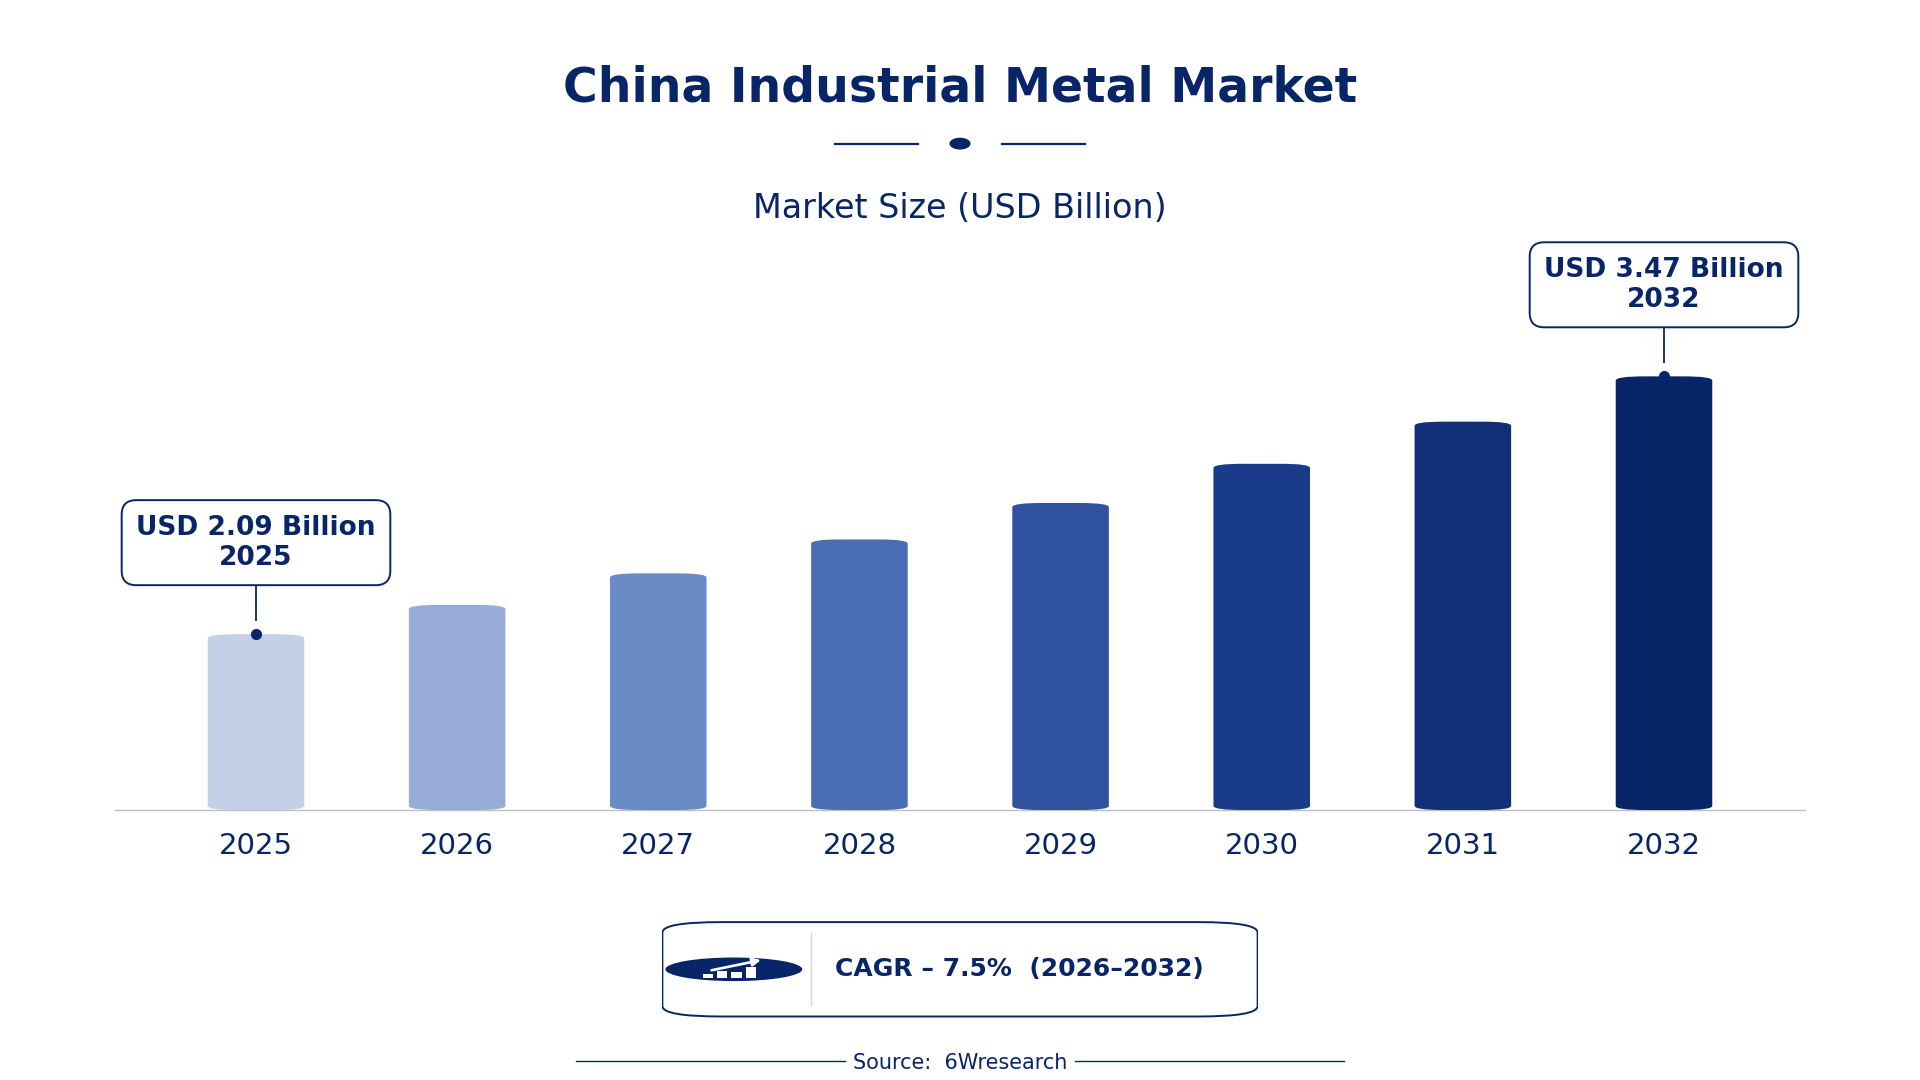
According to 6Wresearch internal database and industry insights, the China Industrial Metal Market was valued at USD 2.09 billion in 2025 and is projected to reach USD 3.47 billion by 2032, growing at a CAGR of approximately 7.5% during 2026–2032.
China Industrial Metal Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Metal Market |
| Market Size 2025 | USD 2.09 billion |
| Market Size 2032 | USD 3.47 billion |
| Absolute Growth 2025–2032 | USD 1.38 billion |
| CAGR 2026–2032 | 7.5% |
| Peak Annual Growth | 10.0% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Product Type, 2025 | Sheet Metal (41% share) |
| Leading Metal Type, 2025 | Steel (51% share) |
| Leading Application Area, 2025 | Construction Components (44% share) |
| Leading Distribution Channel, 2025 | Direct Sales (37% share) |
| Leading End User Industry, 2025 | Heavy Industry (51% share) |
| Fastest-Growing Product Type | Forged Products (10.0% CAGR) |
| Fastest-Growing Metal Type | Aluminum (10.1% CAGR) |
| Fastest-Growing Application Area | Machinery Manufacturing (8.6% CAGR) |
| Fastest-Growing Distribution Channel | Distributors (9.8% CAGR) |
| Fastest-Growing End User Industry | Electronics (9.4% CAGR) |
| Growing Sector | Construction |
| Key End Users | Construction firms, automotive manufacturers, aerospace companies, electronics producers |
China Industrial Metal Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
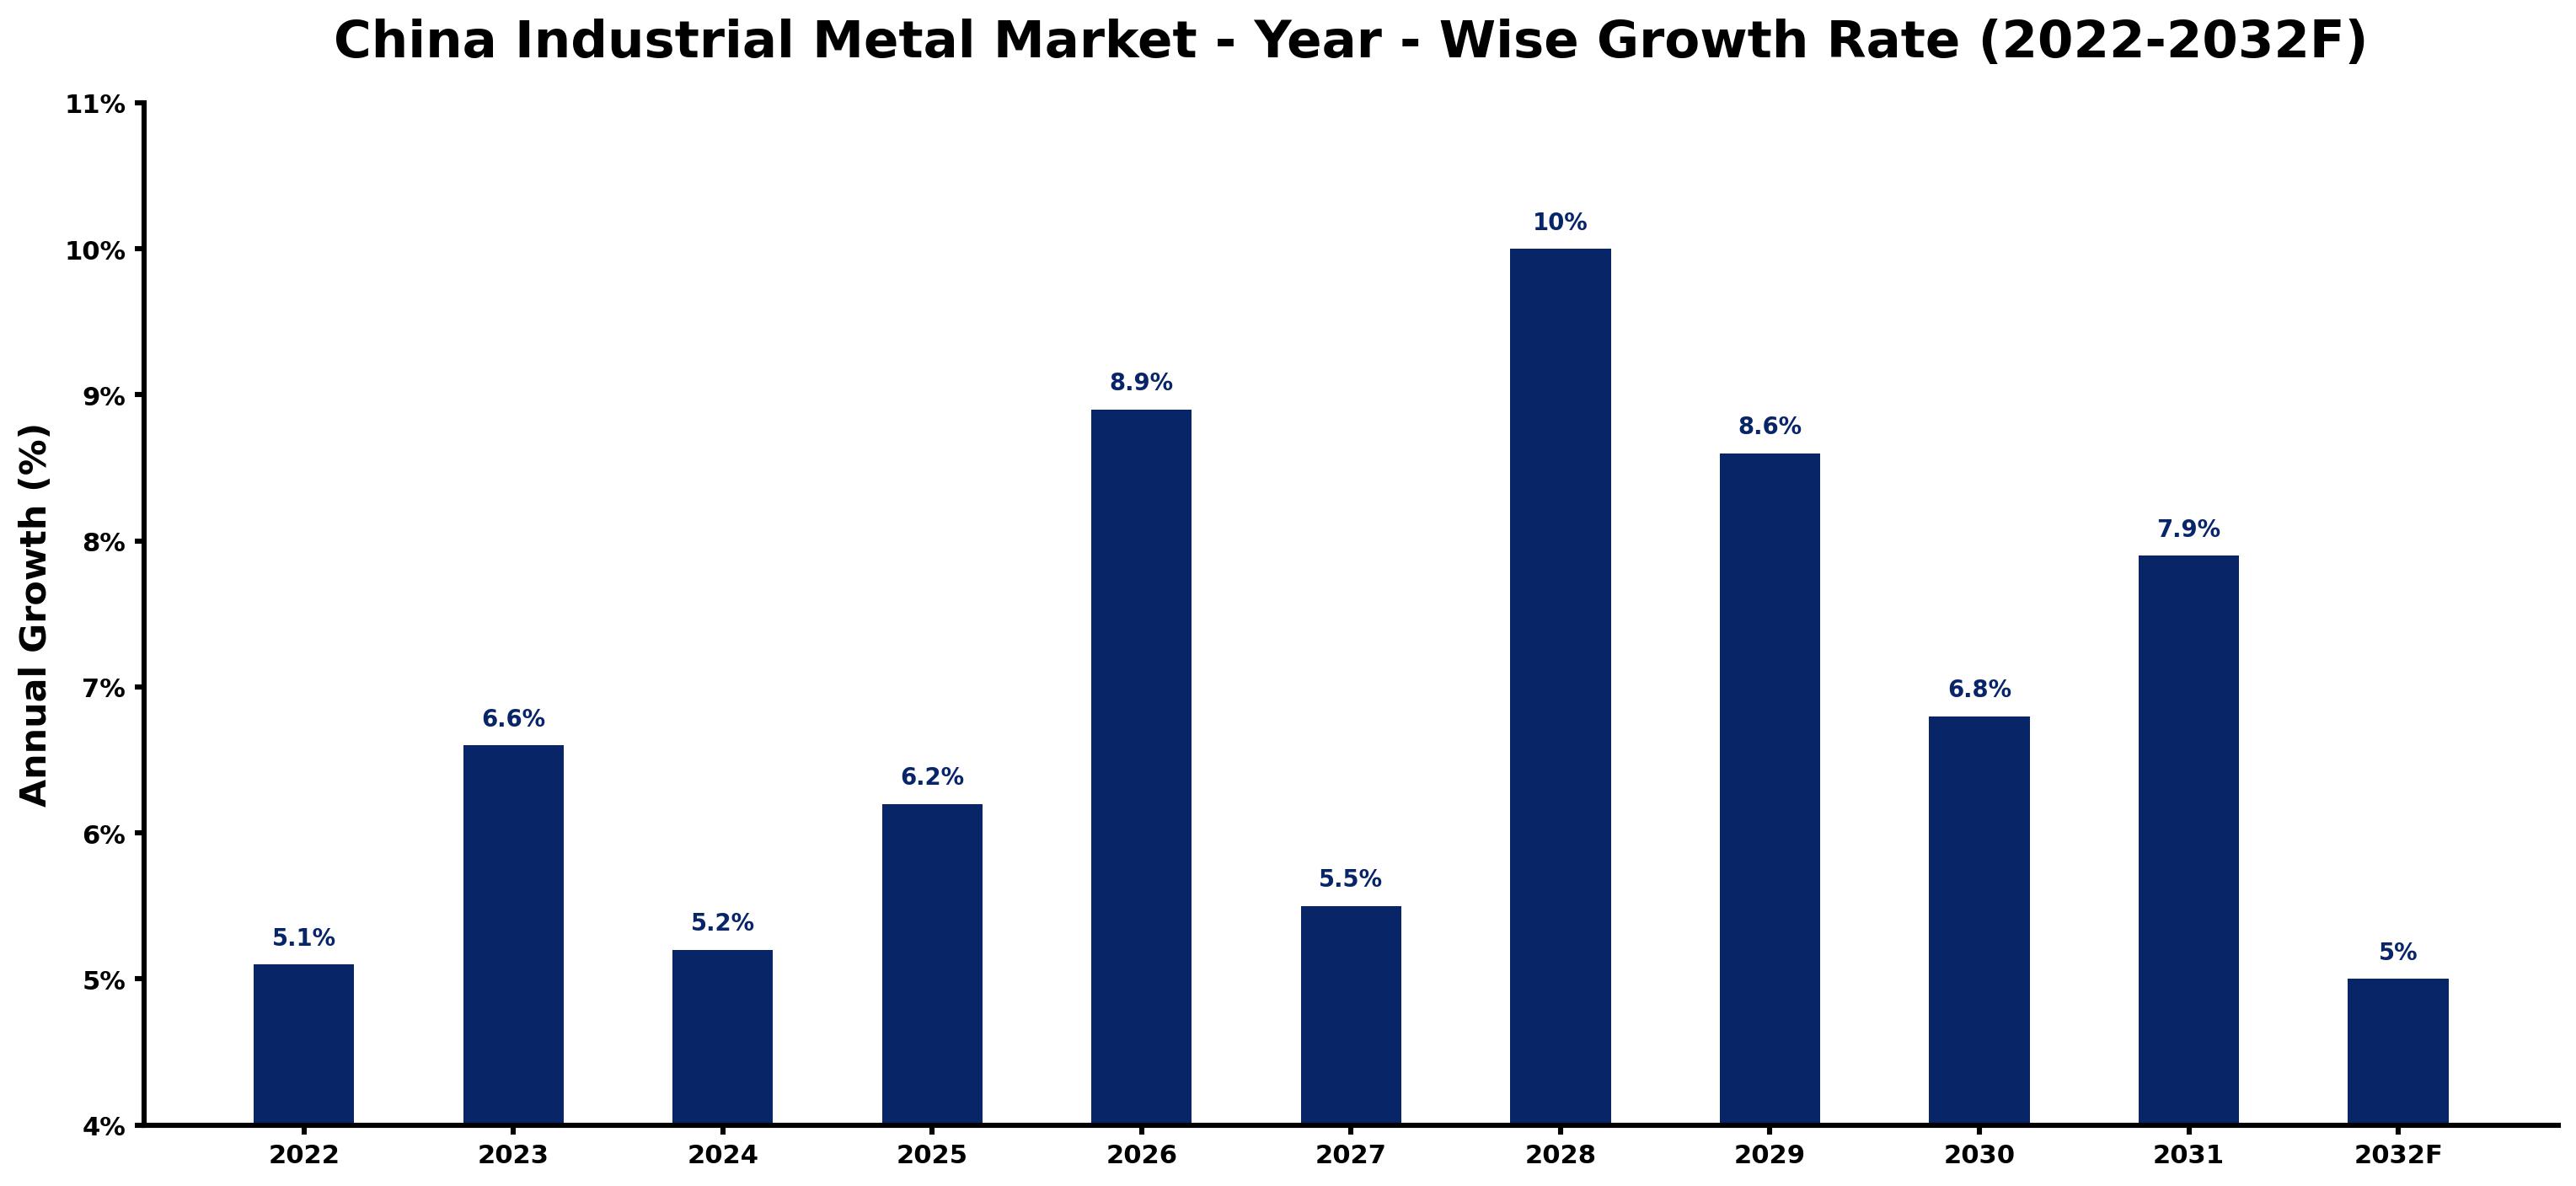
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.1 | The market experienced steady growth, driven by strong demand from the construction sector, particularly for steel and aluminum. |
| 2023 | 6.6 | Growth accelerated due to increased steel consumption in infrastructure projects across the country, especially under the 'Made in China 2025' initiative. |
| 2024 | 5.2 | A slight slowdown occurred as construction activity stabilised after a rapid expansion, impacting steel demand. |
| 2025 | 6.2 | Demand surged again, supported by ongoing investments in heavy industry and automotive production, particularly in aluminum. |
| 2026 | 8.9 | Growth picked up as the aerospace sector began to expand its metal requirements, necessitating more specialized products. |
| 2027 | 5.5 | The market faced a slowdown as demand from the electronics sector normalised after rapid growth in mobile phone production. |
| 2028 | 10.0 | A peak in growth was reached, driven by the booming construction and automotive industries, particularly for steel. |
| 2029 | 8.6 | Growth slowed as the market adjusted to the previous year's high demand levels, particularly in construction components. |
| 2030 | 6.8 | A further slowdown occurred, influenced by a temporary dip in automotive production, affecting aluminum demand. |
| 2031 | 7.9 | Demand rebounded as heavy industry ramped up production in response to market needs, particularly for forged products. |
| 2032 | 5.0 | Growth is expected to stabilise as the market matures and demand levels off, especially in the construction sector. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Metal Market Synopsis
The China Industrial Metal Market encompasses various metal products essential for manufacturing and construction. These metals are primarily produced through processes like casting and forging, serving critical roles in infrastructure development and machinery production. The market is growing due to strong demand from sectors such as construction, automotive, and electronics, with the construction sector accounting for approximately 40% of total steel consumption in 2022. The ongoing 'Made in China 2025' initiative further fuels investment in manufacturing capabilities, driving increased purchases of industrial metals.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Strong demand from the construction sector drives metal purchases for infrastructure projects. | Driver | High | Construction Components |
| The automotive industry's growth creates significant demand for steel and aluminum. | Driver | High | Automotive |
| Investment in green manufacturing practices opens new opportunities for sustainable metal production. | Opportunity | High | Aluminum |
| The increasing production of mobile phones presents a growing market for copper and other metals. | Opportunity | High | Electronics |
| Environmental regulations may limit production capacities for certain metals. | Restraint | Medium | Steel |
| Fluctuating raw material prices can affect the overall cost structure for manufacturers. | Restraint | Medium | Aluminum |
| The Industrial Metal Market in China faces challenges related to regulatory compliance and environmental standards. | Challenge | High | Steel |
| Supply chain disruptions can delay the availability of critical metal products for manufacturers. | Challenge | High | Construction Components |
Evaluation of Drivers in China Industrial Metal Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased construction activities drive demand for steel and aluminum. | Steel | The construction sector accounted for approximately 40% of total steel consumption in 2022. |
| The automotive industry's expansion boosts the need for industrial metals. | Aluminum | Over 26 million vehicles were produced in China in 2022, increasing metal demand. |
| Growing aerospace requirements lead to higher demand for specialized metals. | Forged Products | The aerospace industry is expected to require over 1 million tons of specialized metals by 2025. |
| Rising mobile phone production increases the need for copper and aluminum. | Electronics | China is projected to produce over 1.4 billion mobile phones in 2023. |
| Government initiatives encourage investment in advanced manufacturing technologies. | Sheet Metal | The 'Made in China 2025' initiative aims to enhance manufacturing capabilities. |
Growth in the Industrial Metal market in China comes from strong end-use demand, particularly in construction and automotive sectors. The construction sector accounted for approximately 40% of total steel consumption in 2022, driving demand for industrial metals. The automotive industry's production of over 26 million vehicles in 2022 has further increased the need for metals like steel and aluminum. The aerospace sector will require over 1 million tons of specialized metals by 2025, boosting demand for forged products.
Evaluation of Restraints in China Industrial Metal Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Environmental regulations may impose restrictions on metal production processes. | Steel | Compliance with standards can increase operational costs for manufacturers, impacting profitability. |
| Fluctuating raw material prices can create uncertainty in production costs. | Aluminum | Price volatility affects budgeting and financial planning for producers, complicating pricing strategies. |
| Supply chain disruptions can delay the availability of essential metal products. | Construction Components | Manufacturers may face delays in project timelines due to material shortages, affecting delivery schedules. |
| Increased competition from international markets can pressure local producers. | Forged Products | Local manufacturers may struggle to compete with lower-priced imports, impacting market share. |
| Technological advancements may require significant investment to keep up. | Electronics | Staying competitive in the electronics sector necessitates ongoing capital expenditure, straining budgets. |
China Industrial Metal Market Challenges
The China Industrial Metal Market encounters several practical issues, starting with rising costs for buyers. The construction sector, which is responsible for around 40% of total steel consumption in 2022, has driven prices up, straining budgets for contractors. Producers are also facing supply chain disruptions, as reliance on specific raw materials can delay production timelines and increase costs for manufacturers. Regulatory compliance presents another challenge, with standards like GB/T 1591-2018 requiring investments in quality control that can burden smaller manufacturers. A shortage of skilled workers also limits innovation and efficiency, particularly in advanced manufacturing processes, making it more difficult for suppliers to compete.
Trends in the China Industrial Metal Market
Buyers and suppliers in the China Industrial Metal Market are adjusting to the following trends.
- Shift towards Sustainable Manufacturing Practices: The 'Green Manufacturing Program' launched in 2022 promotes eco-friendly practices in the industrial metals sector. This initiative aims to reduce emissions and improve production standards, encouraging manufacturers to adopt sustainable methods.
- Growth in Aerospace Metal Requirements: The aerospace industry is increasingly demanding specialized metals, with expectations of over 1 million tons needed by 2025. This trend highlights the growing importance of high-strength materials in aircraft manufacturing.
- Rising Demand for Aluminum in Automotive Applications: Aluminum is becoming a preferred material in automotive manufacturing due to its lightweight properties. In 2022, the automotive industry significantly increased its consumption of aluminum, driving further investments in this metal.
- Expansion of Mobile Phone Production: China's electronics sector is set to produce over 1.4 billion mobile phones in 2023. This surge in production is creating a higher demand for metals like copper, essential for electrical components.
Investment Opportunities in the China Industrial Metal Market
Some of the investment opportunities in the China Industrial Metal Market are mentioned below.
- Investment in Green Manufacturing Technologies: The 'Green Manufacturing Program' launched in 2022 presents opportunities for investment in eco-friendly production methods. With the emphasis on sustainability, manufacturers can boost their competitiveness while lowering emissions.
- Growing Market for Aerospace Components: The aerospace sector's anticipated need for over 1 million tons of specialised metals by 2025 offers a promising opportunity. Suppliers can concentrate on developing high-strength materials to satisfy this demand.
- Increased Demand for Electronics Metals: With the electronics sector expected to produce over 1.4 billion mobile phones in 2023, there is a strong opportunity for suppliers of copper and aluminium. Engaging with manufacturers in this sector can yield considerable returns.
- Expansion of Construction Projects: The ongoing growth of the construction sector, accounting for around 40% of steel consumption, creates a timely opportunity for suppliers. Collaborating with construction firms can lead to increased sales and market penetration.
Government Initiatives in the China Industrial Metal Market
The 'Made in China 2025' initiative by the Ministry of Industry and Information Technology, launched in 2020, aims to improve the competitiveness of the manufacturing sector, including industrial metals. This initiative encourages investment in advanced technologies and sustainable practices, providing a framework for manufacturers to enhance their production capabilities. Additionally, the National Development and Reform Commission approved the 'Steel Industry Adjustment and Upgrading Plan' in 2021, focusing on improving production efficiency and reducing emissions. These measures support buyers by ensuring access to high-quality, compliant metal products while promoting environmentally friendly practices.
The Ministry of Ecology and Environment initiated the 'Green Manufacturing Program' in 2022, which provides funding for projects aimed at reducing emissions in the industrial metals sector. This program assists manufacturers in adopting sustainable practices while ensuring compliance with regulatory standards. The China Nonferrous Metals Industry Association plays a vital role in supporting the development of the aluminum sector, facilitating approvals for innovative projects. These initiatives help buyers access high-quality, environmentally friendly metal products while ensuring compliance with regulatory standards.
Future Insight of the China Industrial Metal Market
The Industrial Metal Market in China is set for substantial changes by 2032, driven by the 'Made in China 2025' initiative aimed at upgrading manufacturing capabilities. By 2025, the aerospace industry will require over 1 million tons of specialised metals, creating new opportunities for producers. The government's subsidy program for green manufacturing practices will encourage sustainable production methods throughout the sector. As the electronics industry expands, with over 1.4 billion mobile phones expected to be produced in 2023, suppliers must adapt to meet the growing demand for advanced metal products.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Product Type – Sheet Metal Dominated, Forged Products Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, in 2025, Sheet Metal led the product type split with a 41% share. Sheet metal commands the largest share in China's industrial metal market due to its extensive application in construction and manufacturing for structural purposes. The construction sector accounted for approximately 40% of total steel consumption in 2022, underscoring the robust demand for sheet metal. Forged Products are set to record the highest CAGR in this split, 10.0% over 2026–2032. Forged products are experiencing rapid growth, primarily due to their essential role in the aerospace and automotive sectors where high-strength applications are crucial. The automotive industry, producing over 26 million vehicles in 2022, significantly drives this demand. Suppliers should focus on expanding their offerings in forged products to seize opportunities in this growing market.
By Metal Type – Steel Dominated, Aluminum Expected to Grow Fastest
With a 51% revenue share in 2025, Steel was the largest metal type category. Steel holds the largest market share as the primary material used in construction and manufacturing, recognised for its strength and versatility. With China's steel production exceeding 1 billion tons annually, it is clear why steel remains the leader in the industrial metal market. Over 2026–2032, Aluminum is expected to post the fastest growth, at a CAGR of 10.1%. Aluminum is witnessing the fastest growth, largely due to its lightweight properties that are increasingly preferred in the automotive and aerospace sectors. The projected production of over 1.4 billion mobile phones in 2023 further supports the rising demand for aluminum. Buyers should consider increasing their procurement of aluminum to meet the growing needs for lightweight applications across various industries.
By Application Area – Construction Components Dominated, Machinery Manufacturing Expected to Grow Fastest
Construction Components took a 44% share of application area in 2025, more than any other category. Construction components represent the largest share of the market, as industrial metals are essential for building infrastructure. This sector's prominence is underscored by its critical role in overall industrial metal consumption in China. The quickest growth will come from Machinery Manufacturing, forecast to expand at a CAGR of 8.6% between 2026 and 2032. Machinery manufacturing is the fastest-growing application area, driven by the rising demand for industrial metals to produce advanced machinery and tools. This growth aligns with China's ongoing industrialisation and technological advancements. Suppliers should target machinery manufacturers to capture growth opportunities in this expanding application area.
By Distribution Channel – Direct Sales Dominated, Distributors Expected to Grow Fastest
Direct Sales held a 37% share of the China Industrial Metal Market by distribution channel in 2025. Direct sales lead the market share as a prevalent distribution channel for industrial metals, enabling manufacturers to forge strong relationships with suppliers. This approach ensures that manufacturers receive tailored products that meet their specific requirements. Distributors are projected to grow fastest, at a CAGR of 9.8% during 2026–2032. Distributors are rapidly gaining market share, as they play a crucial role in reaching a broader audience across various industries. Their significance is highlighted by the need for efficient supply chains to satisfy the diverse demands of the industrial metal market. Suppliers should enhance collaborations with distributors to improve market reach and service delivery.
By End User Industry – Heavy Industry Dominated, Electronics Expected to Grow Fastest
The largest end user industry category in 2025 was Heavy Industry, with a 51% share of total revenue. Heavy industry is the largest consumer of industrial metals, primarily utilising them for manufacturing and construction purposes. The robust demand from this sector solidifies its position as the leader in the market. Electronics is set to record the highest CAGR in this split, 9.4% over 2026–2032. The electronics sector is growing swiftly, driven by the increasing need for components that require metals like copper. As the electronics industry continues to expand, this segment's growth is likely to accelerate further. Suppliers should adapt their strategies to meet the escalating needs of the electronics sector.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Metal Market Outlook
- Market Size of China Industrial Metal Market, 2025
- Forecast of China Industrial Metal Market, 2032
- Historical Data and Forecast of China Industrial Metal Revenues & Volume for the Period 2022 - 2032F
- China Industrial Metal Market Trend Evolution
- China Industrial Metal Market Drivers and Challenges
- China Industrial Metal Price Trends
- China Industrial Metal Porter's Five Forces
- China Industrial Metal Industry Life Cycle
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Sheet Metal for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Rods and Bars for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Cast Metal Products for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Forged Products for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Metal Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Aluminum for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Copper for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Nickel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Construction Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Machinery Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Electrical Equipment for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Aerospace Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Industrial Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Heavy Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Automotive for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Electronics for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Metal Market Revenues & Volume By Aerospace and Defense for the Period 2022 - 2032F
- China Industrial Metal Import Export Trade Statistics
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Metal Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- China Industrial Metal Top Companies Market Share
- China Industrial Metal Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Metal Company Profiles
- China Industrial Metal Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Product Type
- Sheet Metal
- Rods and Bars
- Cast Metal Products
- Forged Products
By Metal Type
- Steel
- Aluminum
- Copper
- Nickel
By Application Area
- Construction Components
- Machinery Manufacturing
- Electrical Equipment
- Aerospace Components
By Distribution Channel
- Direct Sales
- Distributors
- Online Platforms
- Industrial Suppliers
By End User Industry
- Heavy Industry
- Automotive
- Electronics
- Aerospace and Defense































