China Industrial Monomers Market Size & Growth Rate
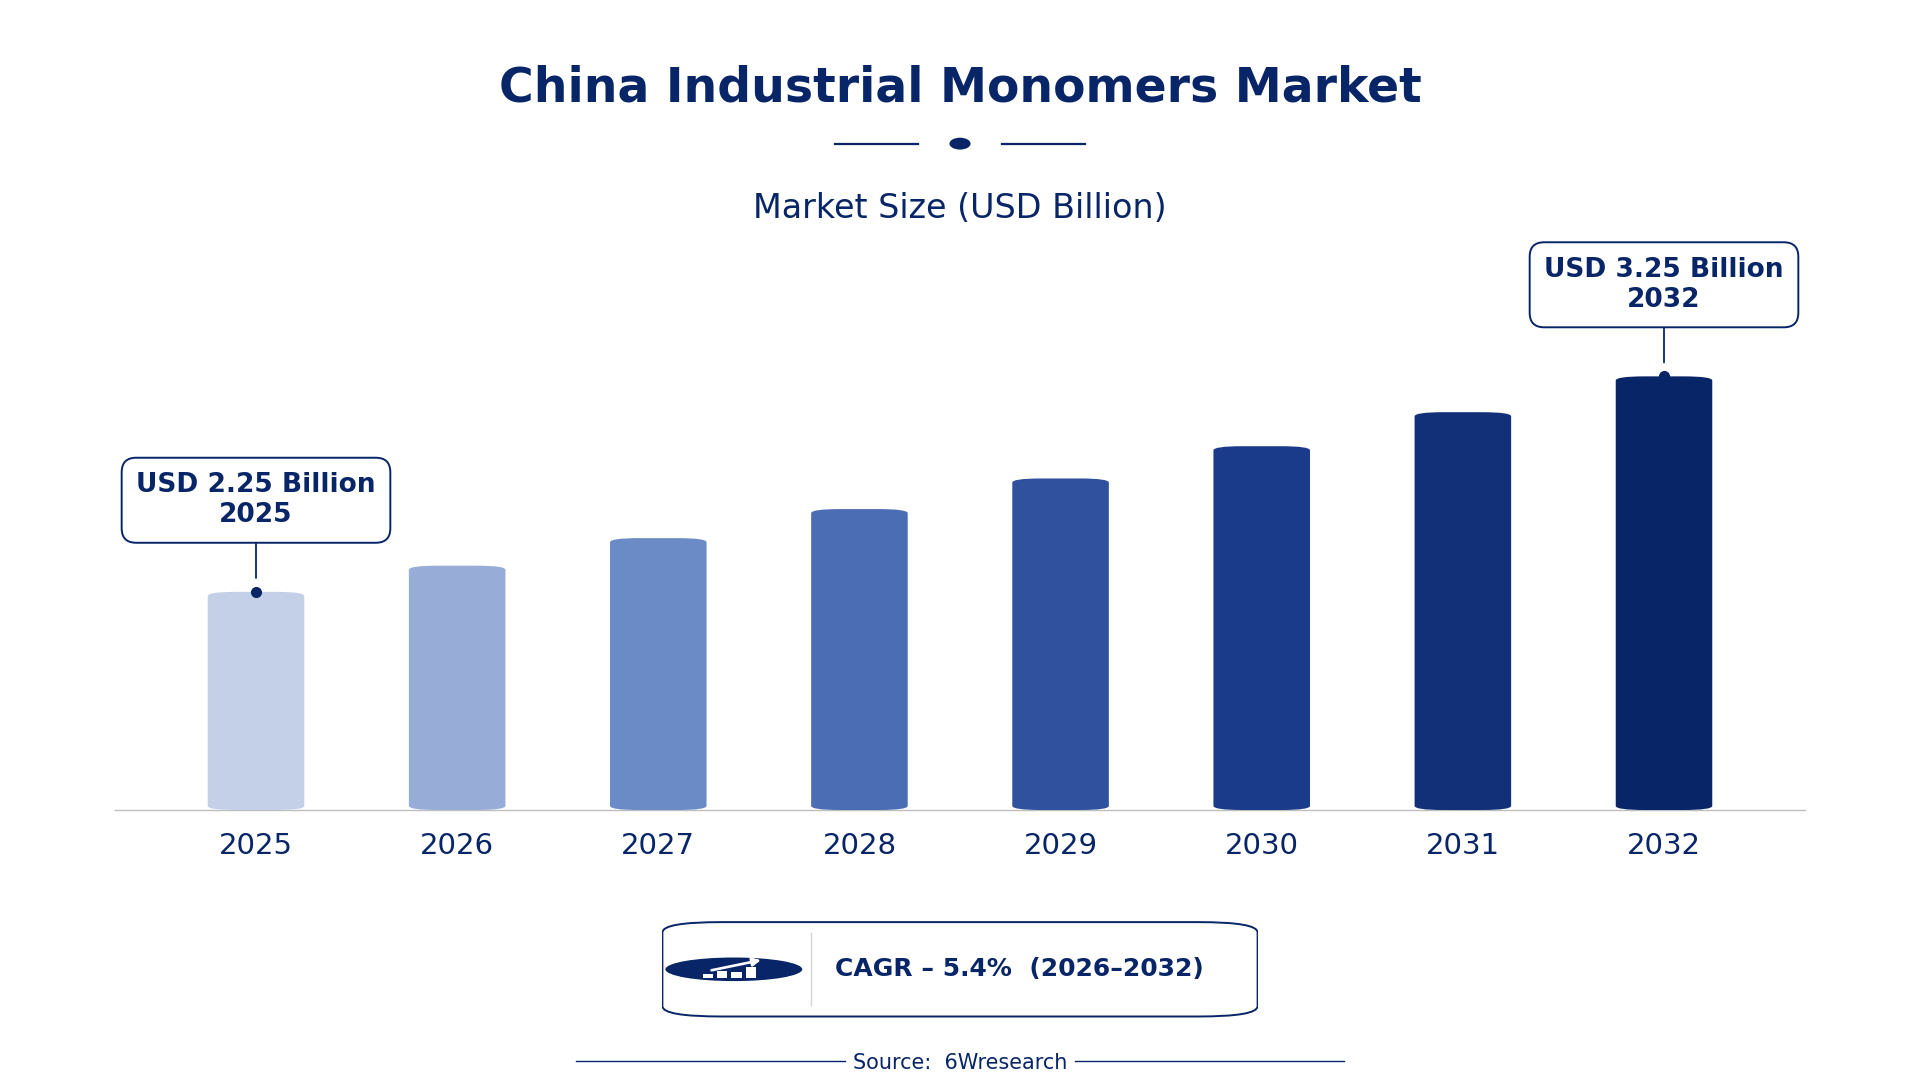
According to 6Wresearch internal database and industry insights, the China Industrial Monomers Market was valued at USD 2.25 billion in 2025 and is projected to reach USD 3.25 billion by 2032, growing at a CAGR of approximately 5.4% during 2026–2032.
China Industrial Monomers Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Monomers Market |
| Market Size 2025 | USD 2.25 billion |
| Market Size 2032 | USD 3.25 billion |
| Absolute Growth 2025–2032 | USD 1 billion |
| CAGR 2026–2032 | 5.4% |
| Peak Annual Growth | 8.1% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Monomer Type, 2025 | Ethylene (41% share) |
| Leading Chemical Class, 2025 | Olefin (42% share) |
| Leading Form, 2025 | Liquid (54% share) |
| Leading Application Area, 2025 | Polymer Manufacturing (44% share) |
| Leading End User Industry, 2025 | Automotive (39% share) |
| Fastest-Growing Monomer Type | Methyl Methacrylate (6.5% CAGR) |
| Fastest-Growing Chemical Class | Acrylate (6.5% CAGR) |
| Fastest-Growing Application Area | Synthetic Rubber (7.5% CAGR) |
| Fastest-Growing End User Industry | Healthcare (7.8% CAGR) |
| Growing Sector | Synthetic Rubber |
| Key End Users | Polymer Manufacturing, Plastic Production, Synthetic Rubber, Paints & Coatings |
China Industrial Monomers Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
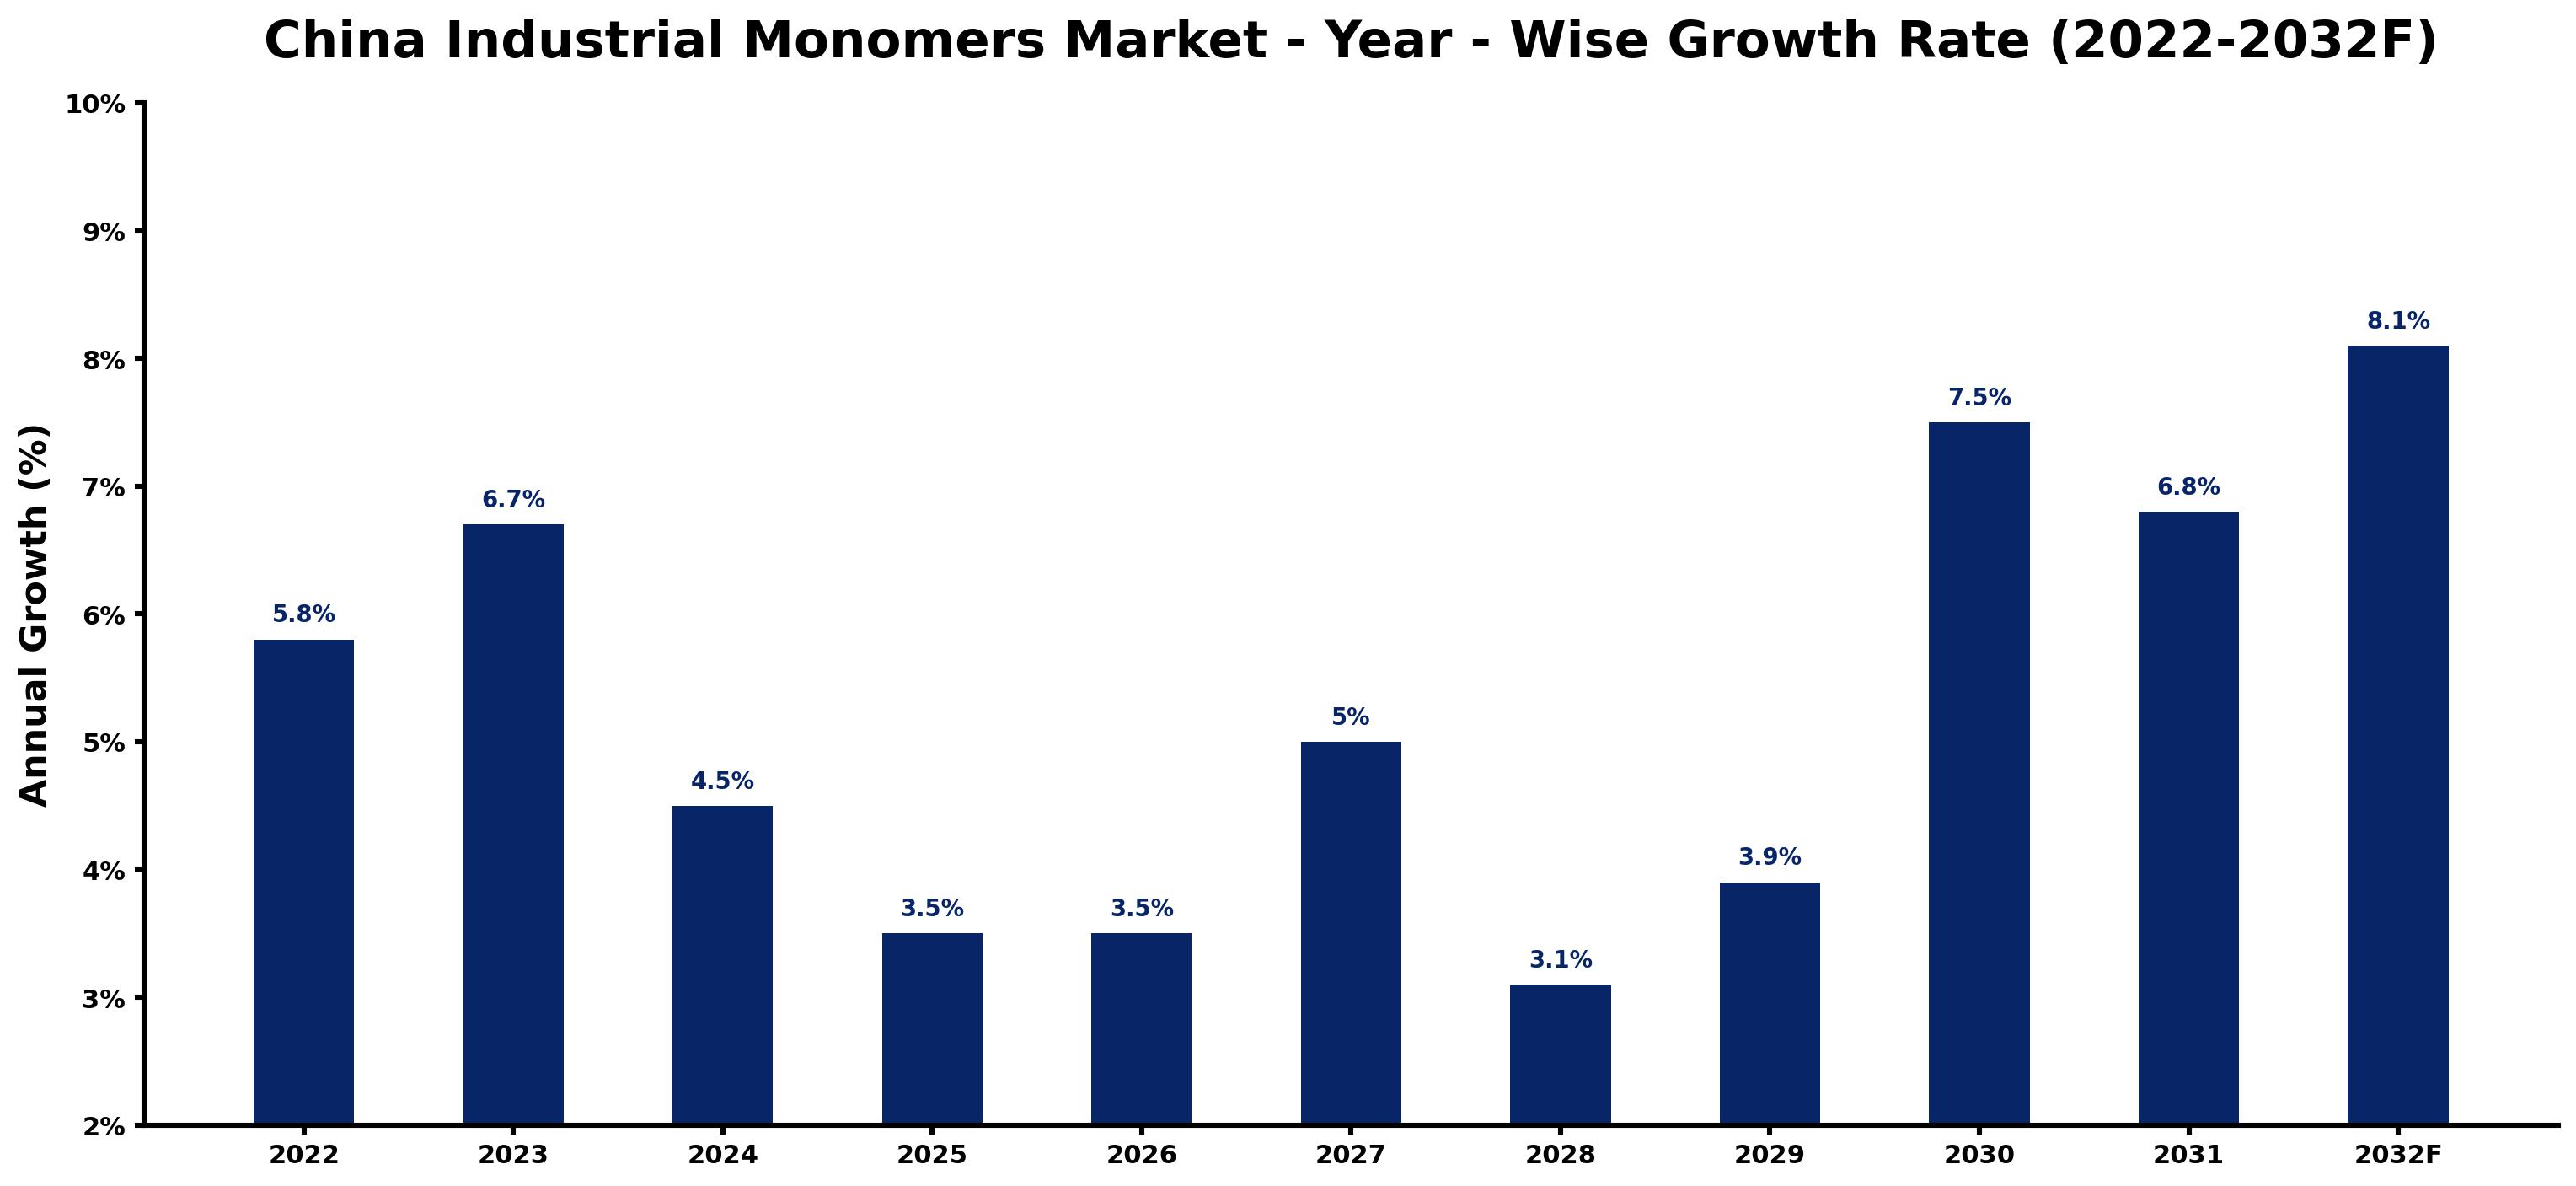
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.8 | The market experienced steady demand from the automotive sector, which relies heavily on synthetic rubber. |
| 2023 | 6.7 | Demand surged due to increased production of polystyrene, driven by the growing construction industry. |
| 2024 | 4.5 | The market growth slowed as the '14th Five-Year Plan for Chemical Industry' stabilised production following the peak in automotive demand. |
| 2025 | 3.5 | Demand continued to decelerate as the market adjusted to new sustainability practices and standards. |
| 2026 | 3.5 | Growth is expected to remain consistent as the automotive sector maintains its demand for synthetic rubber. |
| 2027 | 5.0 | The market is projected to rebound with increased investments in polymer manufacturing facilities across the country. |
| 2028 | 3.1 | Growth is anticipated to slow again as the market faces challenges in meeting new environmental regulations. |
| 2029 | 3.9 | Demand is expected to increase as the healthcare sector ramps up its use of polymers for medical devices. |
| 2030 | 7.5 | The market will accelerate due to rising investments in sustainable practices and recycling initiatives. |
| 2031 | 6.8 | Growth is projected to moderate as the market adjusts to the effects of new environmental policies. |
| 2032 | 8.1 | Demand is expected to peak as the market responds to the 14th Five-Year Plan's focus on innovation in the chemical industry. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Monomers Market Synopsis
Industrial Monomers in China are essential building blocks for various polymers and chemicals. These monomers, derived from processes like cracking and polymerization, are vital for producing plastics, synthetic rubber, and coatings. The China Industrial Monomers Market is growing due to strong demand from the automotive sector, which consumes around 5 million tons of synthetic rubber annually, and ongoing investments in sustainable practices. For instance, the National Development and Reform Commission's initiatives are driving further growth in the industry.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising demand from the automotive sector for synthetic rubber and plastics | Driver | High | Synthetic Rubber |
| Increased production of polystyrene driven by construction projects | Driver | High | Plastic Production |
| Investment in sustainable practices in chemical production | Opportunity | High | Polymer Manufacturing |
| Growing healthcare sector demand for polymers in medical devices | Opportunity | High | Healthcare |
| Challenges in meeting new environmental regulations | Restraint | High | Ethylene |
| Fluctuations in raw material prices affecting production costs | Restraint | Medium | Ethylene |
| Supply chain disruptions impacting availability of raw materials | Challenge | High | Ethylene |
| Technological advancements requiring significant investment | Challenge | Medium | Ethylene |
Evaluation of Drivers in China Industrial Monomers Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production of ethylene for polyethylene manufacturing | Ethylene | China produced 30 million tons of ethylene in 2022, boosting plastic production. |
| Rising demand for styrene in polystyrene production | Styrene | Polystyrene production reached 8 million tons in 2022, driven by construction needs. |
| Growing usage of butadiene in synthetic rubber manufacturing | Butadiene | The automotive sector's demand for synthetic rubber is approximately 5 million tons annually. |
| Expansion of methyl methacrylate for acrylic plastics | Methyl Methacrylate | Acrylics consumption in construction is projected to reach 3 million tons by 2025. |
| Increased production of acrylates for coatings and adhesives | Acrylate | The production of acrylic monomers increased by 10% in 2023, enhancing supply. |
Market growth in China for Industrial Monomers rests on strong end-use demand from the automotive and construction sectors. The automotive sector's demand for synthetic rubber, approximately 5 million tons annually, drives production of butadiene. The construction industry is projected to consume 3 million tons of acrylics by 2025, boosting methyl methacrylate usage. Investment in ethylene production reached 30 million tons in 2022, supporting polyethylene manufacturing. The production of polystyrene reached 8 million tons in 2022, contributing to overall market growth.
Evaluation of Restraints in China Industrial Monomers Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Challenges in sourcing raw materials due to global supply chain disruptions | Ethylene | Supply chain issues have led to increased production costs and delays in delivery. |
| Fluctuations in raw material prices affecting profitability | Gas | Rising costs of crude oil and natural gas impact the pricing of monomers. |
| Regulatory compliance costs associated with environmental standards | Ethylene | New regulations require investment in compliance measures for producers. |
| Limited availability of skilled workforce in chemical manufacturing | Ethylene | The industry faces challenges in attracting and retaining qualified talent. |
| Technological barriers in adopting sustainable practices | Ethylene | Transitioning to greener technologies requires substantial capital investment. |
China Industrial Monomers Market Challenges
Buyers and suppliers in the China Industrial Monomers market encounter several challenges, starting with raw material sourcing. Limited access to diverse inputs can lead to production delays and increased costs for manufacturers, impacting their competitiveness. Price volatility affects buyers, especially in the automotive sector, which requires 5 million tons of synthetic rubber annually, complicating financial planning. Technology adoption remains inconsistent, as many producers do not fully comply with ISO 9001 standards, resulting in quality variations that can disadvantage suppliers. Competition is fierce, pushing established suppliers to innovate or risk losing market share to emerging players.
Trends in the China Industrial Monomers Market
Buyers and suppliers in the China Industrial Monomers Market are adjusting to the following trends.
- Shift towards Sustainable Practices in Chemical Production: The National Development and Reform Commission's '14th Five-Year Plan for Chemical Industry' launched in 2023 promotes sustainability. This initiative aims to improve resource efficiency and reduce emissions, impacting production methods across the sector.
- Increase in Demand for Acrylics in Construction: Starting in 2023, the construction industry is projected to consume 3 million tons of acrylics for coatings and adhesives. This shift reflects a growing preference for durable and eco-friendly materials in building projects.
- Growing Adoption of ISO 9001 Standards: Since 2021, the chemical manufacturing sector in China has increasingly adopted ISO 9001 standards for quality management. This trend ensures that producers meet safety and environmental compliance, improving product reliability.
- Expansion of Polymer Manufacturing Facilities: In 2023, investments in new polymer manufacturing facilities surged, with over $100 billion projected by 2025. This expansion supports the increasing demand for various polymers across multiple industries.
Investment Opportunities in the China Industrial Monomers Market
The following opportunities in the China Industrial Monomers Market pair current demand with a clear way in.
- Investment in Polymer Manufacturing Facilities: The Shanghai Chemical Industry Park is a key hub for monomer production, with investments exceeding $100 billion by 2025. Suppliers can enter through joint ventures with local manufacturers.
- Focus on Sustainable Chemical Production: The Ministry of Ecology and Environment's 'Plastic Waste Reduction Initiative' promotes recycling, creating opportunities for suppliers of eco-friendly materials. With a target of 20% recycled content by 2025, this is a timely investment area.
- Healthcare Sector Demand for Polymers: The healthcare sector's projected demand for polymers is expected to reach 2 million tons by 2025. Suppliers can engage with medical device manufacturers to meet this growing need.
- Expansion of Acrylics in Construction: The construction industry is expected to consume 3 million tons of acrylics by 2025. Suppliers should consider partnerships with construction firms to tap into this expanding market.
Government Initiatives in the China Industrial Monomers Market
The '14th Five-Year Plan for Chemical Industry' launched by the Ministry of Industry and Information Technology in 2021 aims to enhance innovation and sustainability in chemical production. This plan encourages the adoption of eco-friendly technologies and practices among producers of industrial monomers. Additionally, the 'Chemical Industry Green Development Action Plan' approved by the National Development and Reform Commission in 2022 focuses on reducing emissions and improving resource efficiency. These measures are crucial for manufacturers as they must align their operations with these sustainability goals to remain competitive in the market. The target is to significantly lower carbon footprints by 2025, impacting production processes and material sourcing.
The Ministry of Ecology and Environment plays a vital role in implementing the 'Plastic Waste Reduction Initiative', which promotes the recycling of plastic materials in industrial applications. This initiative is designed to support manufacturers in adopting sustainable practices by providing funding and resources for recycling technologies. Furthermore, the State Administration for Market Regulation oversees the updated 'National Standards for Chemical Products', ensuring compliance with safety and environmental regulations. This agency's approval is essential for producers, as adherence to these standards is mandatory for market access and consumer confidence. These frameworks help shape a more sustainable industrial landscape in China.
Future Insight of the China Industrial Monomers Market
The China Industrial Monomers market will undergo significant changes by 2032, influenced by the '14th Five-Year Plan for Chemical Industry' and the 'Green Chemical Industry Development Plan'. These initiatives will encourage sustainable practices, with a target to increase the use of recycled materials in plastics. The healthcare sector's demand for polymers is projected to reach 2 million tons by 2025, reflecting a growing focus on medical applications. Investment in the chemical sector is expected to exceed $120 billion by 2025, driving technological advancements that will reshape the market landscape.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Monomer Type – Ethylene Dominated, Methyl Methacrylate Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, Ethylene accounted for a 41% market share by monomer type in 2025. Ethylene holds the largest share in the China Industrial Monomers Market due to its essential role in producing polyethylene and various plastics, widely used in multiple applications. With a production of 30 million tons in 2022, it has solidified its position as a key player in the global market. Over 2026–2032, Methyl Methacrylate is expected to post the fastest growth, at a CAGR of 6.5%. Methyl Methacrylate is experiencing rapid growth, largely due to its increasing application in acrylic plastics and coatings, which are crucial for many industries. The anticipated rise in demand for acrylics in coatings and adhesives is expected to drive this segment's expansion further. Suppliers should focus on enhancing their production capabilities for Methyl Methacrylate to meet the growing demand in the coatings sector.
By Chemical Class – Olefin Dominated, Acrylate Expected to Grow Fastest
Olefin took a 42% share of chemical class in 2025, more than any other category. Olefin leads the market due to its role as a precursor for various chemical products, making it indispensable in the production of numerous materials. This widespread application across multiple industries ensures a strong and consistent demand for olefins in China. The quickest growth will come from Acrylate, forecast to expand at a CAGR of 6.5% between 2026 and 2032. Acrylate is the fastest-growing segment, driven by its essential use in coatings, adhesives, and paints, which are increasingly in demand as industries focus on sustainability. The push for eco-friendly materials is likely to fuel further growth in the acrylate market. Buyers should consider sourcing more acrylate-based products to meet the rising demand for sustainable materials in coatings and adhesives.
By Form – Liquid Dominated and Is Expected to Record the Fastest Growth
In 2025, Liquid led the form split with a 54% share. Liquid monomers dominate the market as they are commonly used in various chemical processes, providing versatility and ease of handling. The preference for liquid forms in production processes solidifies their leading position in the China Industrial Monomers Market. Its lead should widen, with a projected CAGR of 7.2% during 2026–2032, the highest in this split. Liquid monomers also represent the fastest-growing segment, as their application in chemical processes continues to expand with increasing industrial activity. The simultaneous growth in demand for liquid forms ensures that their market share will continue to rise. Suppliers must ensure a steady supply of liquid monomers to meet the growing industrial demand and maintain competitive advantage.
By Application Area – Polymer Manufacturing Dominated, Synthetic Rubber Expected to Grow Fastest
The largest application area category in 2025 was Polymer Manufacturing, with a 44% share of total revenue. Polymer Manufacturing is the leading application area for industrial monomers, as they are vital in creating various polymer products that play a significant role in everyday life. The high demand for monomers in this sector ensures its dominant market share. Synthetic Rubber is projected to grow fastest, at a CAGR of 7.5% during 2026–2032. Synthetic Rubber is the fastest-growing application area, primarily due to its critical role in the automotive industry, where the demand for tires and other rubber products continues to increase. The ongoing growth of the automotive sector is likely to further boost the synthetic rubber segment. Investments in synthetic rubber production will be crucial for suppliers aiming to capture the rising demand from the automotive industry.
By End User Industry – Automotive Dominated, Healthcare Expected to Grow Fastest
Automotive held a 39% share of the China Industrial Monomers Market by end user industry in 2025. The Automotive industry is the largest end-user of industrial monomers, particularly for synthetic rubber and plastics used in vehicle manufacturing. This sector's substantial demand guarantees it maintains a strong market share in the overall industrial monomers landscape. Over 2026–2032, Healthcare is expected to post the fastest growth, at a CAGR of 7.8%. Healthcare is emerging as the fastest-growing end-user industry, driven by the increasing need for polymers in medical device manufacturing. As healthcare demands expand, the requirement for monomers in this sector is projected to rise significantly. Suppliers should explore opportunities in the healthcare sector to diversify their customer base and capitalise on the growing demand for medical-grade polymers.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Monomers Market Outlook
- Market Size of China Industrial Monomers Market, 2025
- Forecast of China Industrial Monomers Market, 2032
- Historical Data and Forecast of China Industrial Monomers Revenues & Volume for the Period 2022 - 2032F
- China Industrial Monomers Market Trend Evolution
- China Industrial Monomers Market Drivers and Challenges
- China Industrial Monomers Price Trends
- China Industrial Monomers Porter's Five Forces
- China Industrial Monomers Industry Life Cycle
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Monomer Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Ethylene for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Styrene for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Butadiene for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Methyl Methacrylate for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Chemical Class for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Olefin for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Aromatic for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Diene for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Acrylate for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Form for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Liquid for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Solid Crystals for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Gas for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Liquid for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Polymer Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Plastic Production for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Synthetic Rubber for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Paints & Coatings for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Automotive for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Consumer Staples for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Healthcare for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Monomers Market Revenues & Volume By Construction Industry for the Period 2022 - 2032F
- China Industrial Monomers Import Export Trade Statistics
- Market Opportunity Assessment By Monomer Type
- Market Opportunity Assessment By Chemical Class
- Market Opportunity Assessment By Form
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By End User Industry
- China Industrial Monomers Top Companies Market Share
- China Industrial Monomers Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Monomers Company Profiles
- China Industrial Monomers Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Monomer Type
- Ethylene
- Styrene
- Butadiene
- Methyl Methacrylate
By Chemical Class
- Olefin
- Aromatic
- Diene
- Acrylate
By Form
- Liquid
- Solid Crystals
- Gas
By Application Area
- Polymer Manufacturing
- Plastic Production
- Synthetic Rubber
- Paints & Coatings
By End User Industry
- Automotive
- Consumer Staples
- Healthcare
- Construction Industry































