China Industrial Packaging Films Market Size & Growth Rate
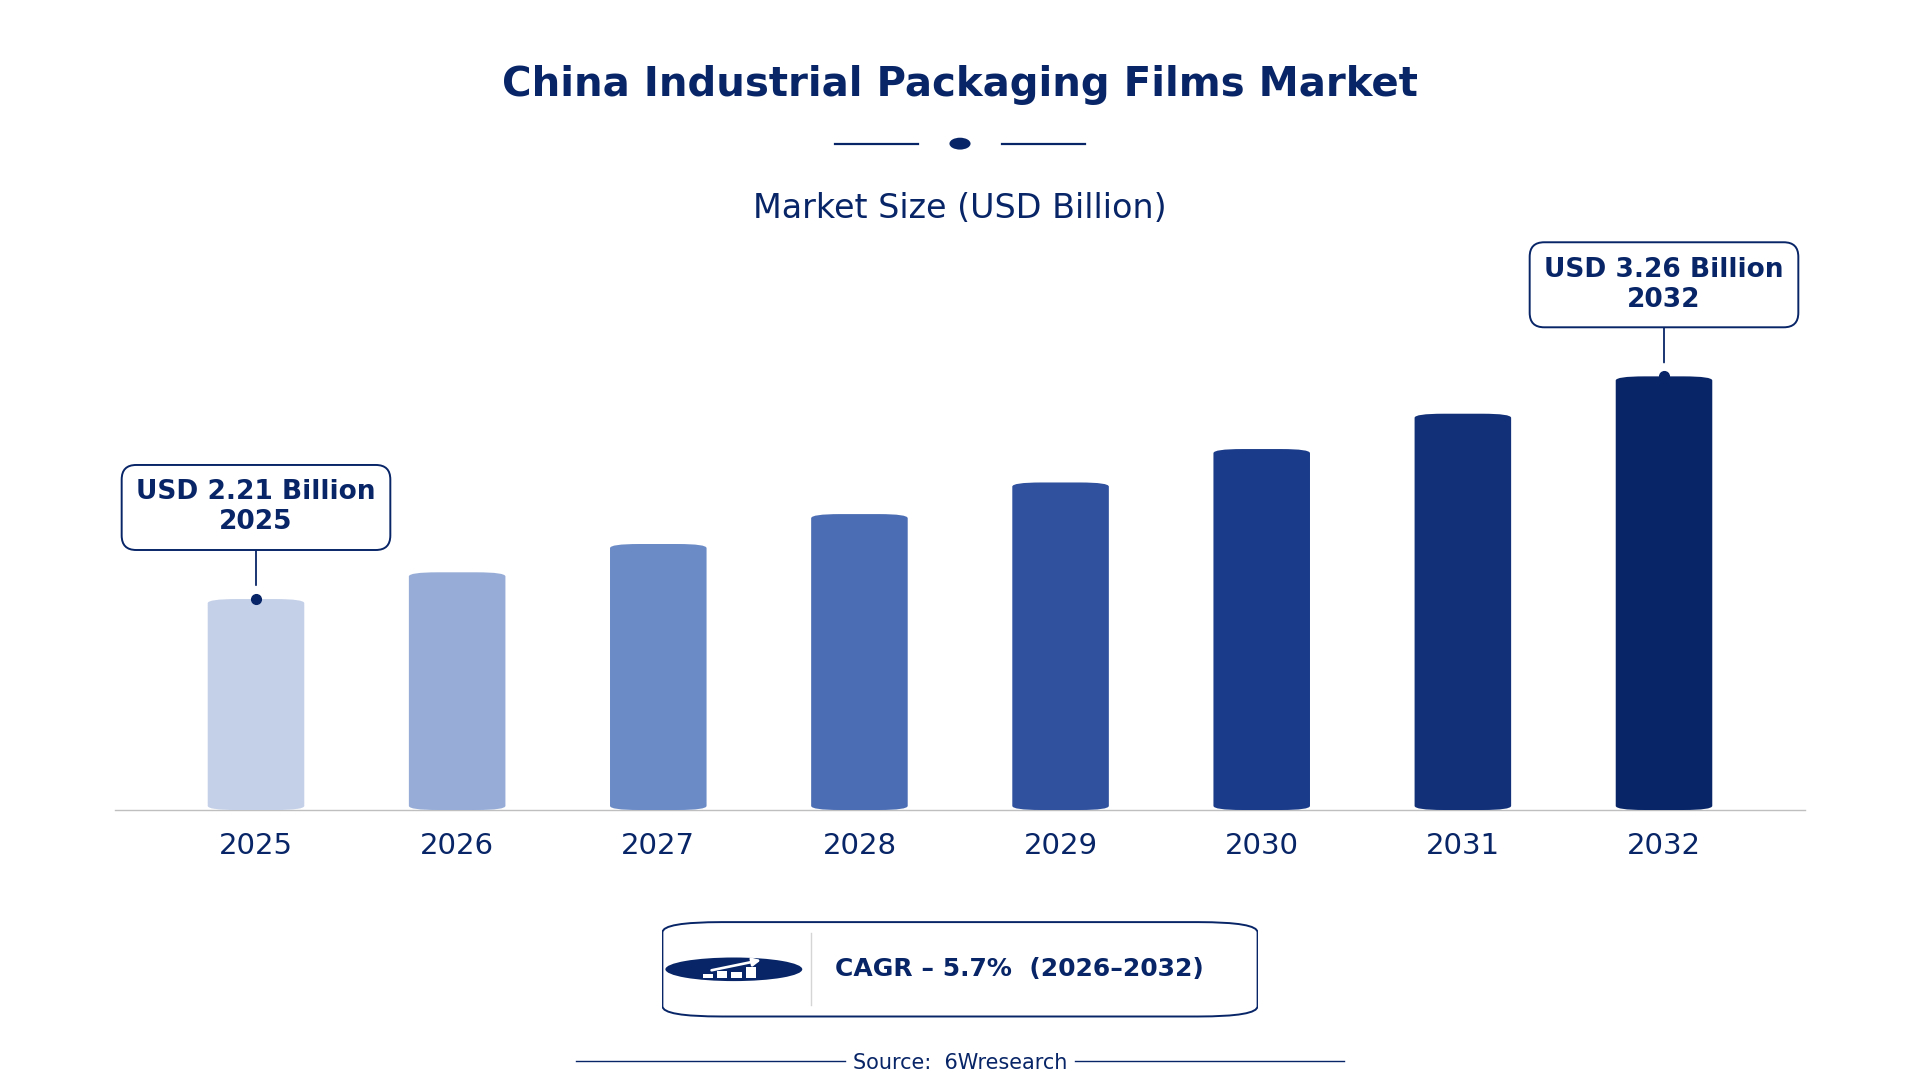
According to 6Wresearch internal database and industry insights, the China Industrial Packaging Films Market was valued at USD 2.21 billion in 2025 and is projected to reach USD 3.26 billion by 2032, growing at a CAGR of approximately 5.7% during 2026–2032.
China Industrial Packaging Films Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Packaging Films Market |
| Market Size 2025 | USD 2.21 billion |
| Market Size 2032 | USD 3.26 billion |
| Absolute Growth 2025–2032 | USD 1.05 billion |
| CAGR 2026–2032 | 5.7% |
| Peak Annual Growth | 7.9% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Film Type, 2025 | Stretch Films (49% share) |
| Leading Material Type, 2025 | Polyethylene (45% share) |
| Leading Application Area, 2025 | Pallet Wrapping (38% share) |
| Leading Distribution Channel, 2025 | Distributors (52% share) |
| Leading End User Industry, 2025 | Food & Beverage Industry (39% share) |
| Fastest-Growing Film Type | Shrink Films (8.1% CAGR) |
| Fastest-Growing Material Type | PVC (8.1% CAGR) |
| Fastest-Growing Application Area | Bundling & Sealing (6.8% CAGR) |
| Fastest-Growing Distribution Channel | Direct Sales (8.1% CAGR) |
| Fastest-Growing End User Industry | Consumer Goods (8.4% CAGR) |
| Growing Sector | Food & Beverage Industry |
| Key End Users | Food & Beverage Industry, Healthcare, Consumer Goods, E-commerce |
China Industrial Packaging Films Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
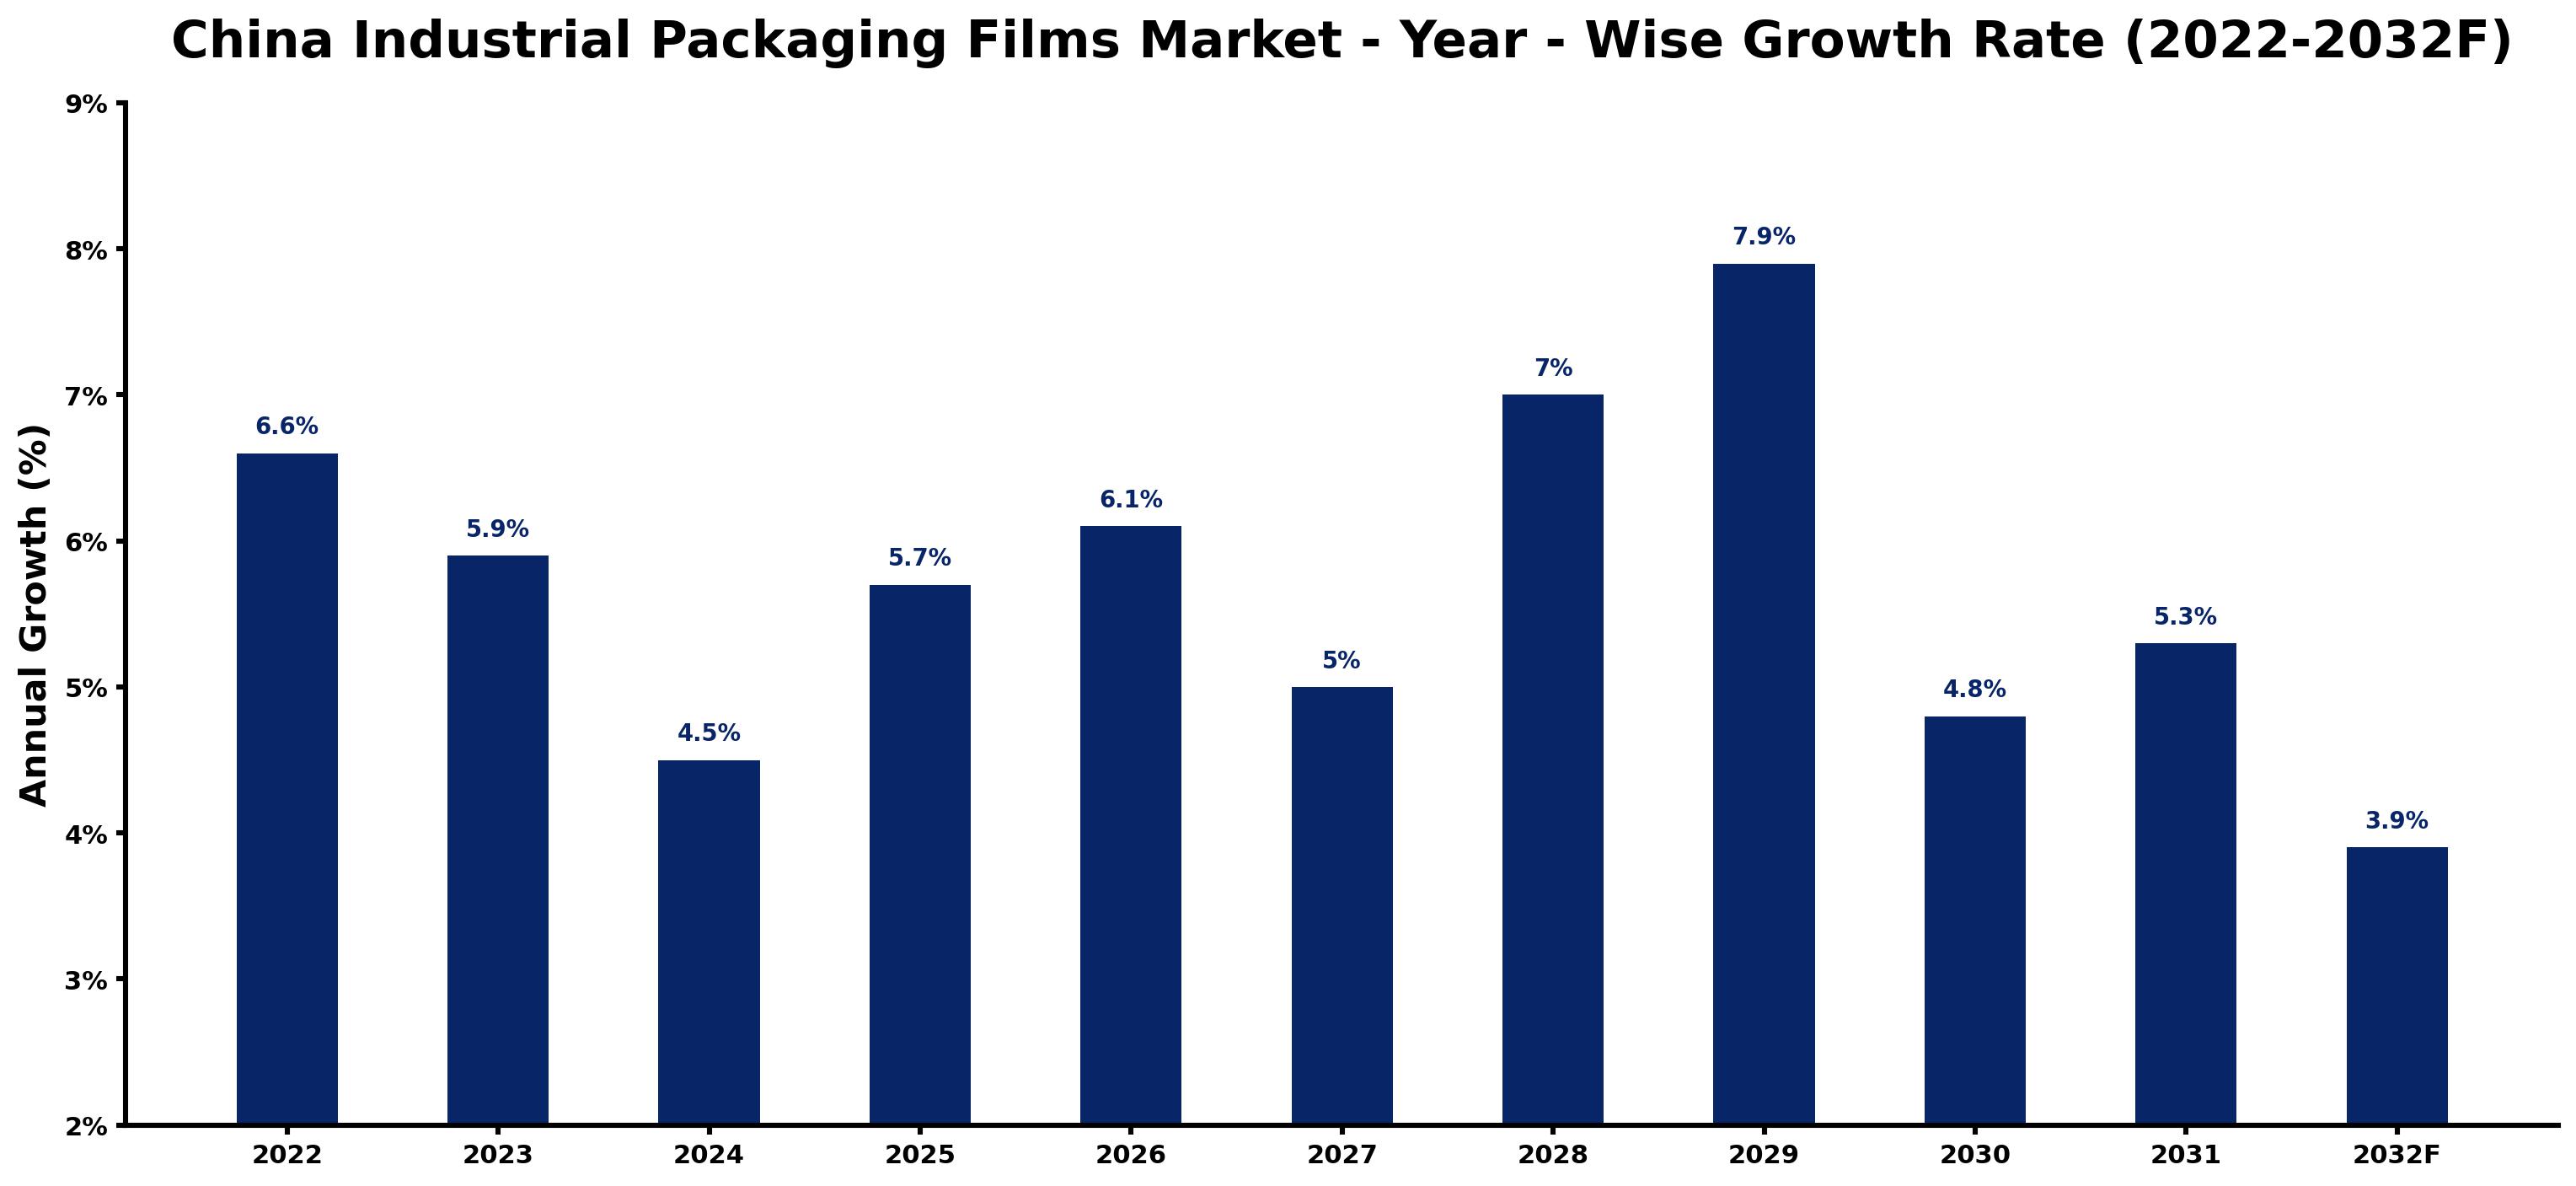
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.6 | The market experienced strong demand from the food and beverage sector, driving growth. |
| 2023 | 5.9 | Demand slowed due to the impact of the 'Plastic Waste Reduction Initiative' on packaging materials. |
| 2024 | 4.5 | Focus shifted towards sustainable packaging solutions, affecting growth rates. |
| 2025 | 5.7 | A resurgence in demand from the food and beverage industry accelerated growth rates. |
| 2026 | 6.1 | Investments in biodegradable packaging technologies are expected to spur market expansion. |
| 2027 | 5.0 | Growth is projected to slow as competition among suppliers intensifies. |
| 2028 | 7.0 | Rising demand for barrier films in food packaging is expected to boost growth rates. |
| 2029 | 7.9 | The market is projected to peak as the food and beverage sector expands. |
| 2030 | 4.8 | Growth is expected to slow due to market saturation in certain applications. |
| 2031 | 5.3 | A renewed focus on sustainability in packaging will drive growth rates higher. |
| 2032 | 3.9 | Demand is expected to stabilise as the market adjusts to evolving regulatory standards. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Packaging Films Market Synopsis
The China Industrial Packaging Films Market encompasses thin plastic materials used for protecting and preserving goods. These films are primarily made from polymers like polyethylene and PVC, serving critical roles in shipping and food preservation. The market is projected to grow, driven by the food and beverage industry, which alone has a market size exceeding 3 trillion yuan. The healthcare sector's increasing reliance on packaging solutions further fuels demand, with approximately 15% of films utilized for medical supplies.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Strong demand from the food and beverage sector drives growth in packaging films. | Driver | High | Barrier Films |
| The growing healthcare sector increases the need for sterile packaging solutions. | Driver | High | Shrink Films |
| The healthcare industry is increasingly focusing on sustainable packaging solutions, creating investment opportunities. | Opportunity | High | Specialty Films |
| E-commerce growth necessitates innovative packaging solutions for online sales. | Opportunity | Medium | Pallet Wrapping |
| Regulatory pressures on plastic waste management may limit production capabilities. | Restraint | High | Polyethylene |
| Competition from alternative packaging materials could hinder market growth. | Restraint | Medium | PVC |
| Buyers face challenges in sourcing sustainable materials due to limited availability. | Challenge | High | Barrier Films |
| Suppliers struggle with rising costs of raw materials affecting pricing strategies. | Challenge | Medium | Shrink Films |
Evaluation of Drivers in China Industrial Packaging Films Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing investments in sustainable packaging technologies. | Barrier Films | This trend supports demand as companies seek eco-friendly solutions, with the healthcare sector utilizing approximately 15% of films for medical supplies. |
| Demand from the food and beverage industry is increasing. | Pallet Wrapping | The food sector's market size of over 3 trillion yuan drives higher purchases of packaging films. |
| Expansion of e-commerce platforms necessitating protective packaging. | Shrink Films | China's online retail sales reached 13 trillion yuan in 2022, boosting the need for efficient packaging solutions. |
| Compliance with food safety standards is essential. | Specialty Films | National Standard GB/T 10004-2021 mandates quality assurance in food packaging, increasing demand for compliant films. |
| Consumer awareness of product safety and quality is rising. | Multilayer Laminates | The emphasis on maintaining product freshness in the food sector drives demand for advanced packaging solutions. |
Growth in the Industrial Packaging Films market in China comes from increasing investments in sustainable packaging technologies, particularly in the healthcare sector, which utilized approximately 15% of films for medical supplies. The food and beverage industry contributes to demand, with a market size exceeding 3 trillion yuan, driving higher purchases of packaging solutions. E-commerce growth, with online retail sales reaching 13 trillion yuan in 2022, necessitates protective packaging. Compliance with National Standard GB/T 10004-2021 increases demand for quality films, while rising consumer awareness of product safety drives the need for advanced solutions.
Evaluation of Restraints in China Industrial Packaging Films Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory pressures on plastic waste management limit production capabilities. | Polyethylene | The 'Plastic Waste Reduction Initiative' aims to reduce plastic waste, affecting production processes. |
| Competition from alternative packaging materials could hinder market growth. | PVC | As biodegradable options gain traction, demand for conventional PVC films may decline. |
| Sourcing challenges for sustainable materials affect supply chains. | Barrier Films | Limited availability of eco-friendly materials restricts production capabilities. |
| Rising costs of raw materials impact pricing strategies. | Shrink Films | Fluctuations in polymer prices affect the overall cost structure for producers. |
| Market saturation in certain packaging applications limits growth potential. | Pallet Wrapping | Increased competition has led to price wars, reducing profitability for suppliers. |
China Industrial Packaging Films Market Challenges
Buyers in the China industrial packaging films market encounter rising costs due to stringent regulations such as National Standard GB/T 10004-2021, which enforces high-quality standards for food packaging. Adhering to these regulations can raise production costs by 15%, affecting profit margins for producers. Distributors face supply chain challenges, as the concentration of manufacturing in East China means local disruptions can delay shipments, potentially leading to sales losses of up to 20%. Many producers grapple with outdated technology, risking a 10% decline in competitiveness, while a shortage of skilled workers may prolong production timelines, costing buyers valuable market opportunities.
Trends in the China Industrial Packaging Films Market
The trends below show where the China Industrial Packaging Films Market is heading.
- Shift towards Sustainable Packaging Solutions: The 'Plastic Waste Reduction Initiative' launched in 2021 promotes recyclable materials, driving demand for sustainable solutions. This initiative aligns with growing consumer preference for eco-friendly products, influencing purchasing decisions.
- Increase in E-commerce Packaging Demand: The East China region, including Shanghai, is experiencing a surge in e-commerce, significantly increasing the demand for protective packaging. Online retail sales reached 13 trillion yuan in 2022, necessitating innovative solutions.
- Growing Adoption of Barrier Films in Food Packaging: Barrier films are increasingly being adopted in the food sector, with a projected growth rate of 8% annually through 2025. This trend is driven by the need for extended shelf life and product safety.
- Regulatory Compliance Driving Quality Improvements: The National Standard GB/T 10004-2021, updated in 2022, enhances safety and quality in food packaging. Compliance with this standard is becoming essential for producers to maintain market access.
Investment Opportunities in the China Industrial Packaging Films Market
Some of the investment opportunities in the China Industrial Packaging Films Market are mentioned below.
- Food and Beverage Sector's Growing Need for Packaging: The food and beverage industry, with a market size exceeding 3 trillion yuan, requires effective packaging solutions. Suppliers can enter this market by partnering with distributors to meet rising demand.
- Investment in Biodegradable Packaging Technologies: With the government's subsidy program for biodegradable packaging technologies, companies can invest in this area. The healthcare sector's focus on sustainability presents a substantial opportunity for growth.
- Expanding E-commerce Market Requires Protective Solutions: As online retail sales reached 13 trillion yuan in 2022, there is a pressing need for protective packaging solutions. Suppliers can target e-commerce platforms to meet this demand effectively.
- Healthcare Sector's Demand for Sterile Packaging: The healthcare sector's increasing reliance on sterile packaging solutions creates a significant opportunity. Companies can invest in specialized technologies to cater to this growing market.
Government Initiatives in the China Industrial Packaging Films Market
The 'Circular Economy Promotion Law' updated in 2020 encourages the recycling of packaging materials, including industrial films, to reduce environmental impact. This law mandates that producers implement recycling practices, which can lower waste disposal costs by up to 20%. The 'Green Packaging Development Plan' initiated in 2020 by the National Development and Reform Commission aims to promote sustainable practices in the packaging industry by 2025. By 2025, this plan targets a 30% increase in the use of recyclable materials in packaging films. The 'National Standard for Plastic Films' was updated in 2022 by the State Administration for Market Regulation to enhance safety and quality in food packaging, ensuring compliance with health standards.
Buyers in the food and beverage industry benefit from the 'Plastic Waste Reduction Initiative' launched by the Ministry of Ecology and Environment in 2021, which promotes recyclable packaging materials. This initiative provides funding for companies transitioning to sustainable packaging, with an allocation of 500 million yuan for projects aimed at reducing plastic waste. The Ministry of Industry and Information Technology introduced a subsidy program in 2023 for companies investing in biodegradable packaging technologies, facilitating the adoption of eco-friendly solutions. These measures help buyers access innovative packaging options while complying with new regulations.
Future Insight of the China Industrial Packaging Films Market
Several forward-looking factors should support the China industrial packaging films market in the coming years. The government's 'Plastic Waste Reduction Initiative' will promote sustainable packaging solutions, enhancing market appeal. By 2025, the Ministry of Industry and Information Technology aims to boost plastic film recycling by 30%, creating new opportunities for suppliers. The rising focus on packaging safety in the healthcare sector will drive demand for high-quality films, while the robust food and beverage industry will continue to sustain market growth.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Film Type – Stretch Films Dominated, Shrink Films Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, Stretch Films held a 49% share of the China Industrial Packaging Films Market by film type in 2025. Stretch films dominate the market share due to their critical function in securing products on pallets during transport, particularly for the food and beverage industry. The extensive logistics network in East China, which includes major hubs like Shanghai, significantly drives their demand. Shrink Films are projected to grow fastest, at a CAGR of 8.1% during 2026–2032. Shrink films are experiencing the fastest growth as they are increasingly utilised for tightly wrapping products to prevent damage during shipping, especially in the expanding e-commerce sector. The remarkable rise in online retail sales, which reached 13 trillion yuan in 2022, is a key factor behind this growth. Suppliers should focus on enhancing production capabilities for shrink films to effectively address the rising demand in the e-commerce market.
By Material Type – Polyethylene Dominated, PVC Expected to Grow Fastest
The largest material type category in 2025 was Polyethylene, with a 45% share of total revenue. Polyethylene captures the largest market share as it is the most prevalent material used for various film types, especially within the food and beverage sector. Its versatility and cost-effectiveness make it the preferred choice for manufacturers across China. The quickest growth will come from PVC, forecast to expand at a CAGR of 8.1% between 2026 and 2032. PVC is witnessing the fastest growth due to its specific applications in packaging, particularly in sectors that require durable and protective films. As market trends shift towards more specialised solutions, the demand for PVC is anticipated to rise significantly. Buyers may need to adjust their sourcing strategies to include PVC options as its popularity continues to grow.
By Application Area – Pallet Wrapping Dominated, Bundling & Sealing Expected to Grow Fastest
With a 38% revenue share in 2025, Pallet Wrapping was the largest application area category. Pallet wrapping leads the application area due to its critical role in securing loads during transport, particularly in the food and beverage industry. This segment's strong performance is supported by the high volume of goods shipped across China. Over 2026–2032, Bundling & Sealing is expected to post the fastest growth, at a CAGR of 6.8%. Bundling and sealing are the fastest-growing applications as they are essential for grouping products for shipping, especially with the rise of e-commerce. The increasing volume of packaged goods being shipped is driving this growth. Suppliers should invest in bundling and sealing solutions to meet the rising demand from the e-commerce sector.
By Distribution Channel – Distributors Dominated, Direct Sales Expected to Grow Fastest
Distributors accounted for a 52% market share by distribution channel in 2025. Distributors lead the market as a crucial channel for reaching end users, effectively linking manufacturers with various industries, particularly in the food and beverage sector. Their established networks facilitate efficient distribution across China's vast market, reinforcing their dominant position. Direct Sales is set to record the highest CAGR in this split, 8.1% over 2026–2032. Direct sales are rapidly gaining traction as they cater to large volume buyers who prefer purchasing directly from manufacturers. This trend is particularly noticeable in sectors that require bulk packaging solutions, indicating a shift in purchasing preferences. Manufacturers should enhance their direct sales strategies to effectively capture the increasing demand from large buyers.
By End User Industry – Food & Beverage Industry Dominated, Consumer Goods Expected to Grow Fastest
Food & Beverage Industry took a 39% share of end user industry in 2025, more than any other category. The food and beverage industry is the largest consumer of packaging films, driven by its substantial market size of over 3 trillion yuan. This sector's continuous growth ensures a steady demand for various packaging solutions. Consumer Goods are projected to grow fastest, at a CAGR of 8.4% during 2026–2032. Consumer goods are the fastest-growing end user industry as the demand for product packaging surges with the rise of online retail. The increasing population and consumer spending are key factors driving this segment's growth. Suppliers must adapt their offerings to meet the evolving needs of the consumer goods sector.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Packaging Films Market Outlook
- Market Size of China Industrial Packaging Films Market, 2025
- Forecast of China Industrial Packaging Films Market, 2032
- Historical Data and Forecast of China Industrial Packaging Films Revenues & Volume for the Period 2022 - 2032F
- China Industrial Packaging Films Market Trend Evolution
- China Industrial Packaging Films Market Drivers and Challenges
- China Industrial Packaging Films Price Trends
- China Industrial Packaging Films Porter's Five Forces
- China Industrial Packaging Films Industry Life Cycle
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Film Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Stretch Films for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Shrink Films for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Barrier Films for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Specialty Films for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Polyethylene for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By PVC for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Nylon for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Multilayer Laminates for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Pallet Wrapping for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Bundling & Sealing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Perishable Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Corrosion Protection for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Industrial Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Food & Beverage Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Consumer Goods for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Healthcare for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Packaging Films Market Revenues & Volume By Chemical Industry for the Period 2022 - 2032F
- China Industrial Packaging Films Import Export Trade Statistics
- Market Opportunity Assessment By Film Type
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- China Industrial Packaging Films Top Companies Market Share
- China Industrial Packaging Films Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Packaging Films Company Profiles
- China Industrial Packaging Films Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Film Type
- Stretch Films
- Shrink Films
- Barrier Films
- Specialty Films
By Material Type
- Polyethylene
- PVC
- Nylon
- Multilayer Laminates
By Application Area
- Pallet Wrapping
- Bundling & Sealing
- Perishable Packaging
- Corrosion Protection
By Distribution Channel
- Distributors
- Direct Sales
- Online Platforms
- Industrial Suppliers
By End User Industry
- Food & Beverage Industry
- Consumer Goods
- Healthcare
- Chemical Industry































