China Industrial Tooling Market Size & Growth Rate
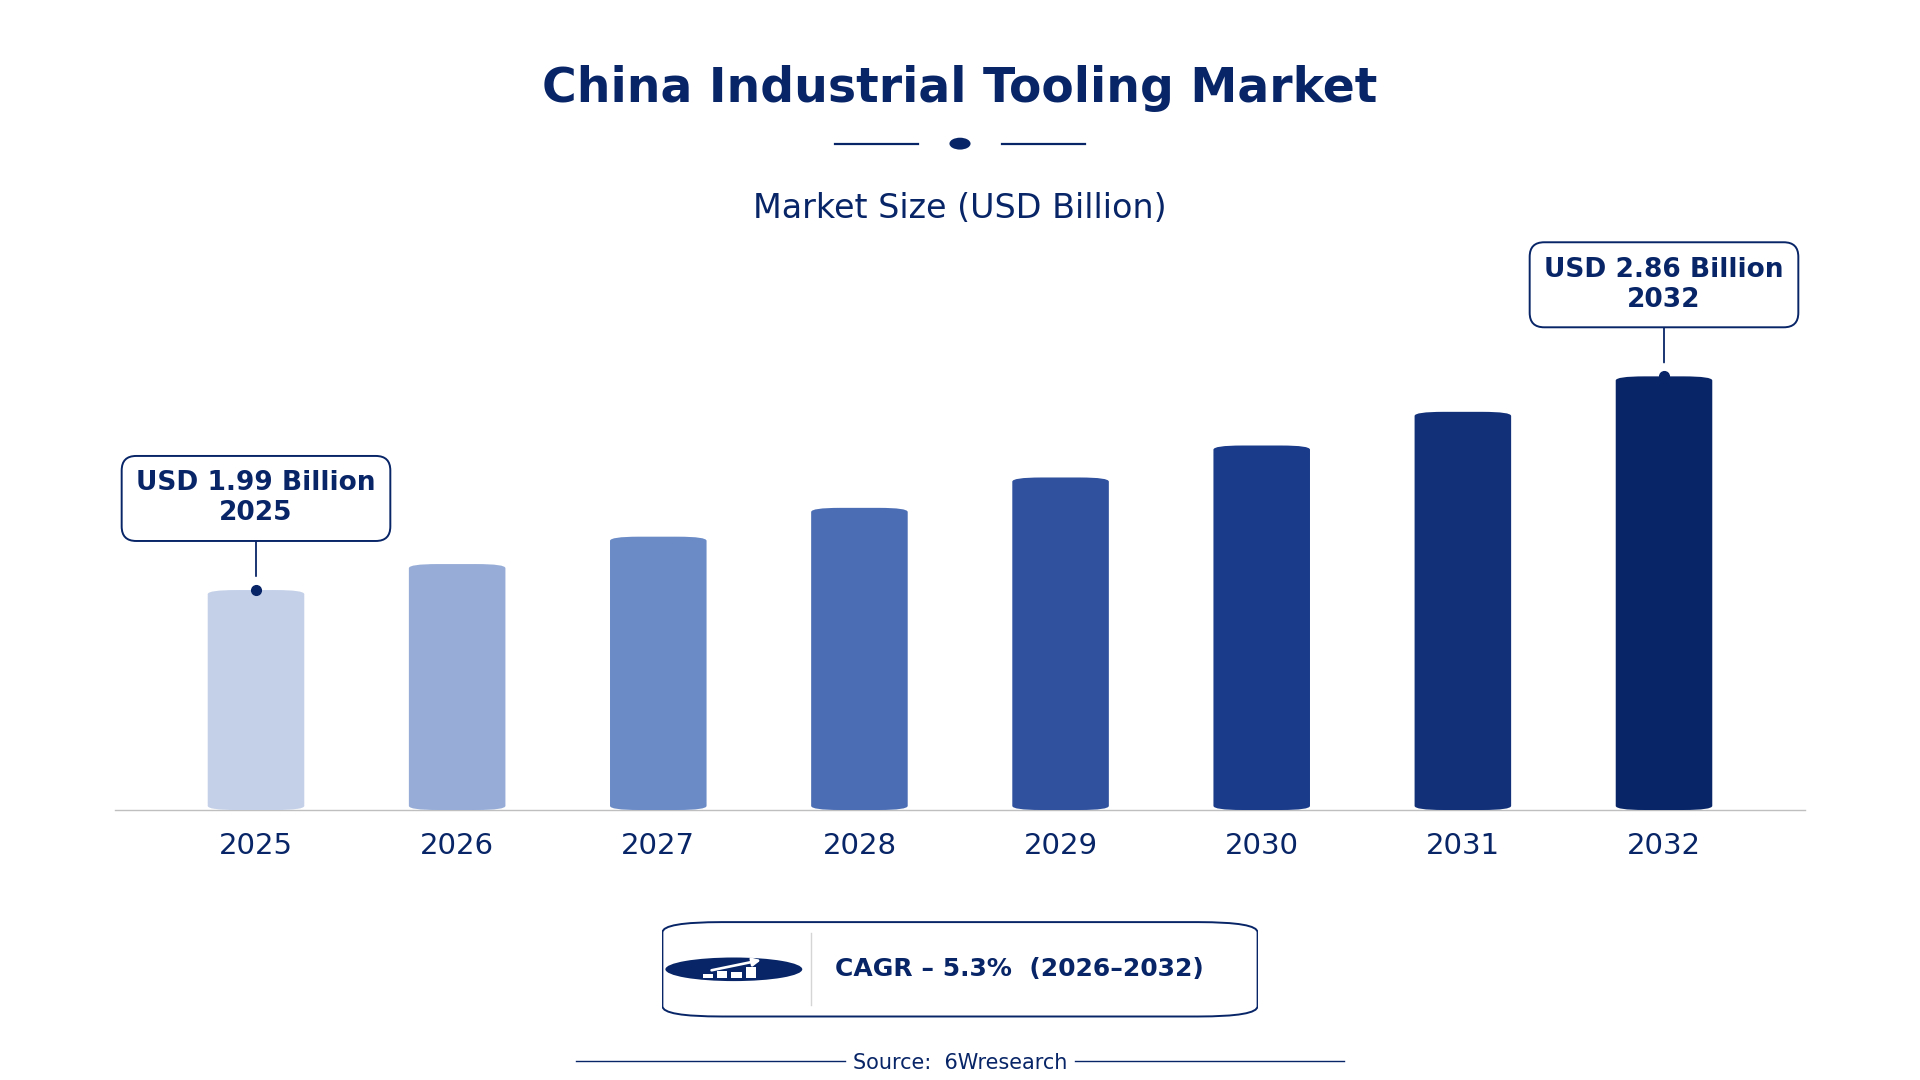
According to 6Wresearch internal database and industry insights, the China Industrial Tooling Market was valued at USD 1.99 billion in 2025 and is projected to reach USD 2.86 billion by 2032, growing at a CAGR of approximately 5.3% during 2026–2032.
China Industrial Tooling Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Tooling Market |
| Market Size 2025 | USD 1.99 billion |
| Market Size 2032 | USD 2.86 billion |
| Absolute Growth 2025–2032 | USD 0.87 billion |
| CAGR 2026–2032 | 5.3% |
| Peak Annual Growth | 7.9% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Tool Type, 2025 | Cutting Tools (43% share) |
| Leading Material Type, 2025 | Carbide/Steel (53% share) |
| Leading Application, 2025 | CNC Machining (41% share) |
| Leading Distribution Channel, 2025 | Tooling Distributors (38% share) |
| Fastest-Growing Tool Type | Molding Tools (6.5% CAGR) |
| Fastest-Growing Material Type | Hardened Steel (6.3% CAGR) |
| Fastest-Growing Application | Plastic Part Production (6.6% CAGR) |
| Fastest-Growing Distribution Channel | Online Tooling Platforms (6.9% CAGR) |
| Growing Sector | Plastic Part Production |
| Key End Users | CNC Machining, Plastic Part Production, Metal Forming, Automotive Assembly |
China Industrial Tooling Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
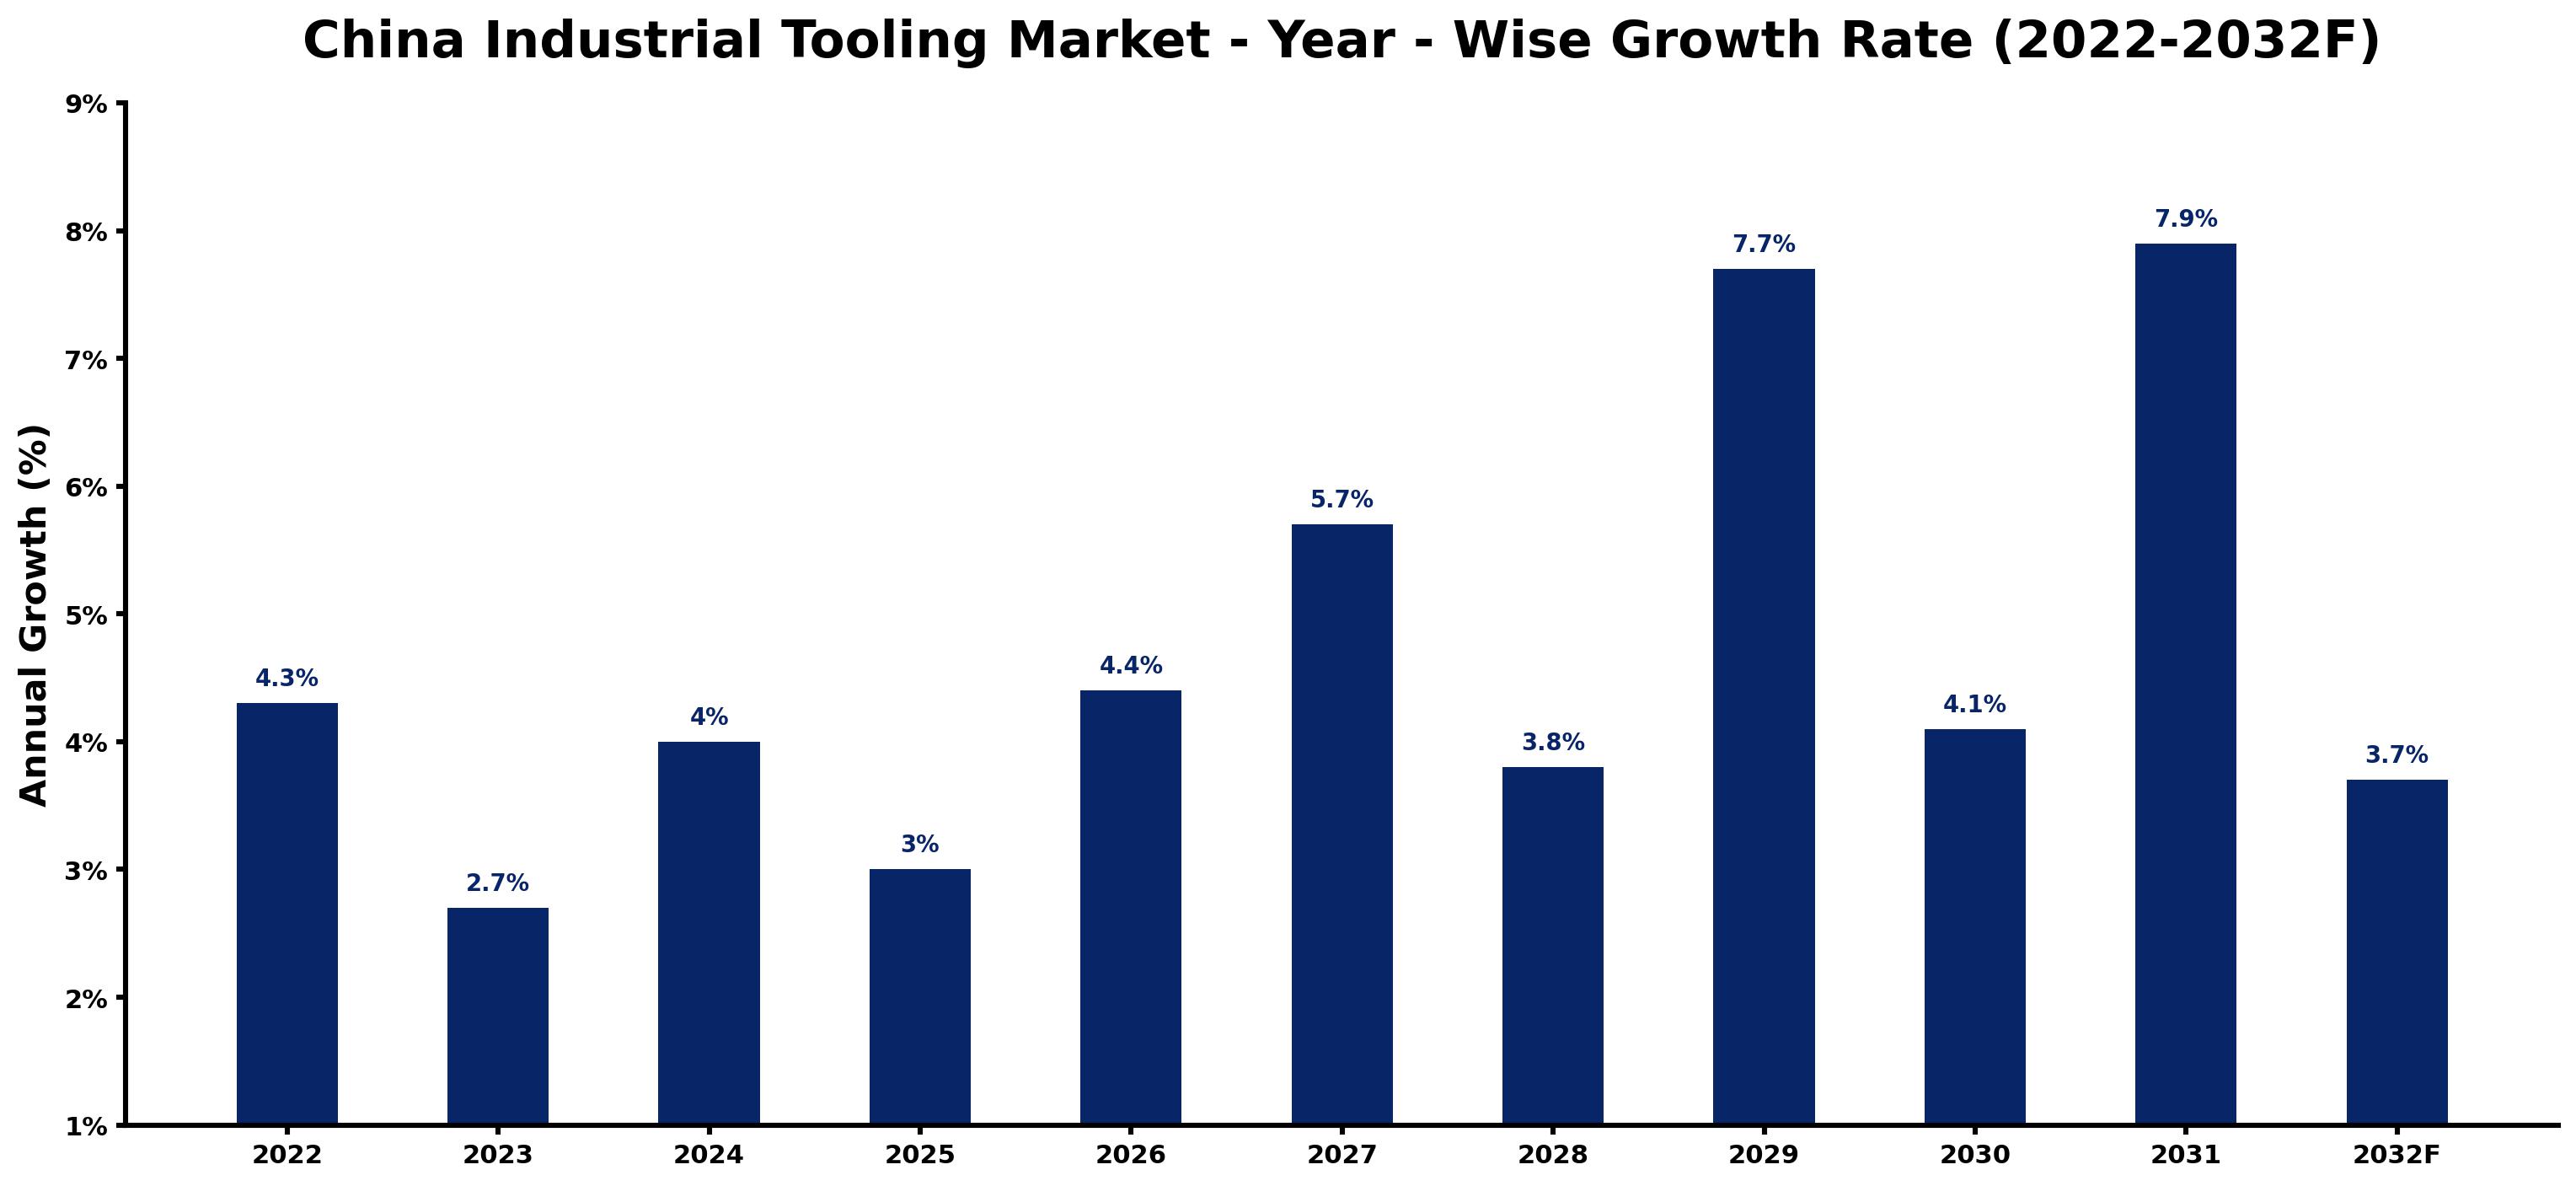
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.3 | The market showed strong activity in various manufacturing sectors, particularly automotive tooling requirements. |
| 2023 | 2.7 | Demand growth slowed due to temporary supply chain disruptions affecting production schedules for tooling. |
| 2024 | 4.0 | Increased investments in CNC machining technology spurred faster growth in tooling demand across sectors. |
| 2025 | 3.0 | The automotive sector's ongoing expansion continued to drive tooling requirements, albeit at a slower pace than before. |
| 2026 | 4.4 | Revitalised interest in advanced manufacturing techniques will lead to a rise in tooling demand from various industries. |
| 2027 | 5.7 | The growing automotive assembly sector will further stimulate the need for industrial tooling solutions. |
| 2028 | 3.8 | A slowdown is expected as manufacturers adjust to new production standards and technologies in tooling. |
| 2029 | 7.7 | Heightened demand for plastic part production tools will contribute to significant growth in the tooling market. |
| 2030 | 4.1 | The market is projected to experience slower growth as manufacturers face challenges in sourcing materials for tooling. |
| 2031 | 7.9 | Strong demand from automotive and aerospace sectors will drive peak growth in tooling requirements and innovations. |
| 2032 | 3.7 | The market is expected to stabilise as production capacities align with the automotive sector's evolving needs. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Tooling Market Synopsis
Industrial Tooling in China encompasses tools essential for manufacturing and assembly processes, primarily made from steel and carbide. These tools are produced through forging, machining, and heat treatment, with applications in automotive, aerospace, and machinery sectors. The China Industrial Tooling Market is valued at approximately $10 billion as of 2023, driven by strong demand from the automotive sector, which accounts for over 30% of tooling needs. Continuous advancements in CNC machining technology and government initiatives to improve tooling capabilities are further fuelling market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Strong demand from the automotive sector drives tooling requirements. | Driver | High | Cutting Tools |
| Increasing adoption of CNC machining technology boosts tooling demand. | Driver | High | CNC Machining |
| Growing need for plastic part production tools presents significant opportunities. | Opportunity | High | Molding Tools |
| Expansion of online tooling platforms offers new market entry points. | Opportunity | Medium | Online Tooling Platforms |
| Supply chain disruptions can hinder production schedules for manufacturers. | Restraint | High | Die & Punch Tools |
| Quality compliance costs may limit smaller manufacturers' participation in the market. | Restraint | Medium | Fixtures & Jigs |
| High competition among tooling suppliers can lead to price pressures. | Challenge | High | Tooling Distributors |
| Technological advancements require continuous investment, straining budgets. | Challenge | Medium | Direct Tool Suppliers |
Evaluation of Drivers in China Industrial Tooling Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising automotive production increases demand for cutting tools. | Cutting Tools | The automotive sector in China accounts for over 30% of tooling demand, driving purchases of cutting tools. |
| The installation of over 1 million CNC machining centers boosts tooling requirements. | CNC Machining | CNC machining is a widely used process requiring specialized tooling, leading to increased demand from manufacturers. |
| Government investments in advanced manufacturing technologies support tooling capabilities. | Molding Tools | The government has invested $500 million in advanced manufacturing technologies since 2022, enhancing tooling production. |
| Growing production of plastic parts drives demand for molding tools. | Molding Tools | Plastic part production tooling is projected to grow by 6.6% in the next five years, encouraging supplier investment. |
| Increased focus on quality standards promotes tooling innovation. | Fixtures & Jigs | ISO 9001 is a prevalent quality standard among tooling manufacturers in China, driving improvements in product quality. |
The automotive sector accounts for over 30% of tooling demand, prompting manufacturers to invest in cutting tools. The installation of over 1 million CNC machining centers increases the need for specialized tooling, driving further purchases. As plastic part production grows, demand for molding tools is expected to rise, encouraging suppliers to focus on this segment.
Evaluation of Restraints in China Industrial Tooling Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions hinder timely production of die and punch tools. | Die & Punch Tools | Manufacturers face challenges in sourcing materials, delaying production schedules by several weeks. |
| Compliance with quality standards increases costs for fixtures and jigs. | Fixtures & Jigs | Smaller manufacturers may struggle to meet ISO 9001 requirements, incurring costs that limit market access. |
| High competition among tooling suppliers leads to price pressures. | Tooling Distributors | Intense competition can force suppliers to lower prices by 10%, impacting their profitability and sustainability. |
| Technological advancements require continuous investment in tooling capabilities. | Direct Tool Suppliers | Manufacturers must invest heavily to keep up with evolving technologies, often exceeding $200,000 per upgrade. |
| Market consolidation may reduce options for local tool dealers. | Local Tool Dealers | Larger suppliers acquiring smaller firms can limit choices for buyers, impacting procurement flexibility. |
China Industrial Tooling Market Challenges
Buyers in the China industrial tooling market encounter technological challenges as many manufacturers grapple with outdated machinery, leading to production delays that can extend timelines by up to 20%. The cost of raw materials, particularly steel and carbide, surged by 15% in 2023, squeezing profit margins for producers. Increased competition from international suppliers has compelled local manufacturers to reduce prices by 10%, directly impacting their profitability. Compliance with ISO 9001 standards adds complexity, with certification costs reaching approximately $200,000 for tooling companies, affecting their operational efficiency.
Trends in the China Industrial Tooling Market
Below mentioned are some of the trends shaping the China Industrial Tooling Market growth.
- Shift towards Advanced CNC Machining Techniques: The Ministry of Industry and Information Technology's 2021 programme promotes advanced CNC machining techniques, improving productivity. CNC machining centres have surpassed 1 million units installed in China, reflecting this shift.
- Growing Demand for Plastic Part Production Tools: The automotive and electronics sectors increasingly require plastic part production tooling, projected to grow by 6.6% over the next five years, driving suppliers to adapt their offerings.
- Rise of Online Tooling Platforms: Online tooling platforms are becoming a preferred channel for procurement, with a projected CAGR of 6.9% from 2026 to 2032, reflecting a shift in buyer behaviour towards digital solutions.
- Increased Focus on Quality Standards: ISO 9001 certification is becoming essential for tooling manufacturers, improving product quality and competitiveness in the market, as compliance becomes a key factor for buyers.
Investment Opportunities in the China Industrial Tooling Market
Some of the investment opportunities in the China Industrial Tooling Market are mentioned below.
- Eastern Provinces as Manufacturing Hubs: The eastern provinces, such as Jiangsu and Zhejiang, are key manufacturing hubs, presenting opportunities for tooling suppliers to establish local partnerships and improve distribution channels, with a market value of $10 billion.
- Automotive Assembly Sector Growth: With over 30% of tooling demand coming from the automotive sector, suppliers can focus on providing cutting tools tailored for automotive assembly, capitalising on this substantial market share.
- Investment in Advanced Manufacturing Technologies: The government's investment in advanced manufacturing technologies creates opportunities for suppliers to offer innovative tooling solutions that meet evolving industry standards, supported by a $500 million funding initiative.
- Rising Demand for Molding Tools: The projected growth in plastic part production tooling highlights a gap in the market, encouraging suppliers to invest in moulding tools to meet increasing demand, with growth expected at 6.6%.
Government Initiatives in the China Industrial Tooling Market
The Ministry of Industry and Information Technology launched the Advanced Manufacturing Technology Promotion Plan in 2021, which aims to enhance the capabilities of the industrial tooling sector. This initiative builds on previous laws such as the Manufacturing Power Strategy of 2025, which set a framework for improving production efficiency and innovation. These measures require tooling manufacturers to invest in new technologies and adhere to updated quality standards, fostering a more competitive environment. As a result, producers are incentivised to upgrade their machinery and processes, ensuring they meet both domestic and international quality benchmarks. The government's focus on advanced manufacturing has led to increased funding and support for tooling innovation, benefiting the entire industry.
The government has allocated $500 million since 2022 to support advanced manufacturing initiatives through the Ministry of Industry and Information Technology. This funding is directed towards projects that enhance tooling technology and improve production processes. The National Tooling Association of China plays a crucial role in promoting standards and innovation, working closely with the government to ensure compliance with new regulations. By facilitating workshops and training programmes, this association helps manufacturers adapt to evolving market demands. These efforts aim to strengthen the local tooling industry, ensuring it remains competitive in the global market.
Future Insight of the China Industrial Tooling Market
The China industrial tooling market will evolve significantly by 2032, driven by advancements in CNC machining technology and substantial government investment in manufacturing. The Ministry of Industry and Information Technology's 2021 programme will improve tooling capabilities, enhancing production efficiency. Carbide cutting tools, which represent 40% of the market, will see increased demand as industries transition to high-performance materials. Growth in plastic part production tooling will present new opportunities for suppliers, fostering innovation and expanding their market presence.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Tool Type – Cutting Tools Dominated, Molding Tools Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, Cutting Tools took a 43% share of tool type in 2025, more than any other category. Cutting tools command the largest market share as they are crucial for material removal in manufacturing processes across diverse sectors. The automotive industry, which constitutes over 30% of tooling demand, relies heavily on cutting tools for streamlined production. Over 2026–2032, Molding Tools are expected to post the fastest growth, at a CAGR of 6.5%. Molding tools are witnessing rapid growth due to the surging demand for plastic parts, particularly in consumer goods and electronics. This growth is underpinned by projections indicating significant expansion in plastic part production tooling over the next five years. Suppliers should consider diversifying their offerings to include more molding tools to align with the rising market demand.
By Material Type – Carbide/Steel Dominated, Hardened Steel Expected to Grow Fastest
In 2025, Carbide/Steel led the material type split with a 53% share. Carbide and steel materials dominate the market share owing to their superior durability and performance in manufacturing applications. These materials are favoured for their ability to endure high-stress conditions, particularly in sectors like automotive and aerospace. Hardened Steel is set to record the highest CAGR in this split, 6.3% over 2026–2032. Hardened steel is gaining traction for high-stress applications, as manufacturers seek robust tooling solutions. The ongoing investments in advanced manufacturing technologies are further propelling this segment's growth. Buyers should focus on sourcing hardened steel tools to meet the demands of high-performance applications.
By Application – CNC Machining Dominated, Plastic Part Production Expected to Grow Fastest
CNC Machining accounted for a 41% market share by application in 2025. CNC machining holds the largest market share as it is a widely utilised process that necessitates specialised tooling across various manufacturing sectors. The installed base of over 1 million CNC machining centres in China underscores the reliance on this application for effective production. The quickest growth will come from Plastic Part Production, forecast to expand at a CAGR of 6.6% between 2026 and 2032. Plastic part production is set to grow significantly, driven by the increasing demand for consumer goods and electronics that require high-quality plastic components. This trend is bolstered by substantial investments in molding technology and production capabilities. Manufacturers should invest in tooling solutions tailored for plastic part production to enhance their competitive edge.
By Distribution Channel – Tooling Distributors Dominated, Online Tooling Platforms Expected to Grow Fastest
Tooling Distributors held a 38% share of the China Industrial Tooling Market by distribution channel in 2025. Tooling distributors capture the largest market share as they are the primary channel for supplying tools to manufacturers across multiple industries. Their established networks and relationships with manufacturers facilitate efficient distribution and access to a diverse range of tooling products. Online Tooling Platforms are projected to grow fastest, at a CAGR of 6.9% during 2026–2032. Online tooling platforms are emerging as the fastest-growing distribution channel, spurred by the rising trend of e-commerce in procurement. More buyers are opting for the convenience and accessibility of online platforms for acquiring tooling solutions. Suppliers must strengthen their online presence to effectively engage with the growing segment of buyers seeking tools through digital channels.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Tooling Market Outlook
- Market Size of China Industrial Tooling Market, 2025
- Forecast of China Industrial Tooling Market, 2032
- Historical Data and Forecast of China Industrial Tooling Revenues & Volume for the Period 2022 - 2032F
- China Industrial Tooling Market Trend Evolution
- China Industrial Tooling Market Drivers and Challenges
- China Industrial Tooling Price Trends
- China Industrial Tooling Porter's Five Forces
- China Industrial Tooling Industry Life Cycle
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Tool Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Cutting Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Molding Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Die & Punch Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Fixtures & Jigs for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Carbide/Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Hardened Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Alloy Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Modular Tool Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By CNC Machining for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Plastic Part Production for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Metal Forming for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Automotive Assembly for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Tooling Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Online Tooling Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Direct Tool Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Tooling Market Revenues & Volume By Local Tool Dealers for the Period 2022 - 2032F
- China Industrial Tooling Import Export Trade Statistics
- Market Opportunity Assessment By Tool Type
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Application
- Market Opportunity Assessment By Distribution Channel
- China Industrial Tooling Top Companies Market Share
- China Industrial Tooling Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Tooling Company Profiles
- China Industrial Tooling Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Tool Type
- Cutting Tools
- Molding Tools
- Die & Punch Tools
- Fixtures & Jigs
By Material Type
- Carbide/Steel
- Hardened Steel
- Alloy Steel
- Modular Tool Steel
By Application
- CNC Machining
- Plastic Part Production
- Metal Forming
- Automotive Assembly
By Distribution Channel
- Tooling Distributors
- Online Tooling Platforms
- Direct Tool Suppliers
- Local Tool Dealers































