China Renewable Integration Storage Market Size & Growth Rate
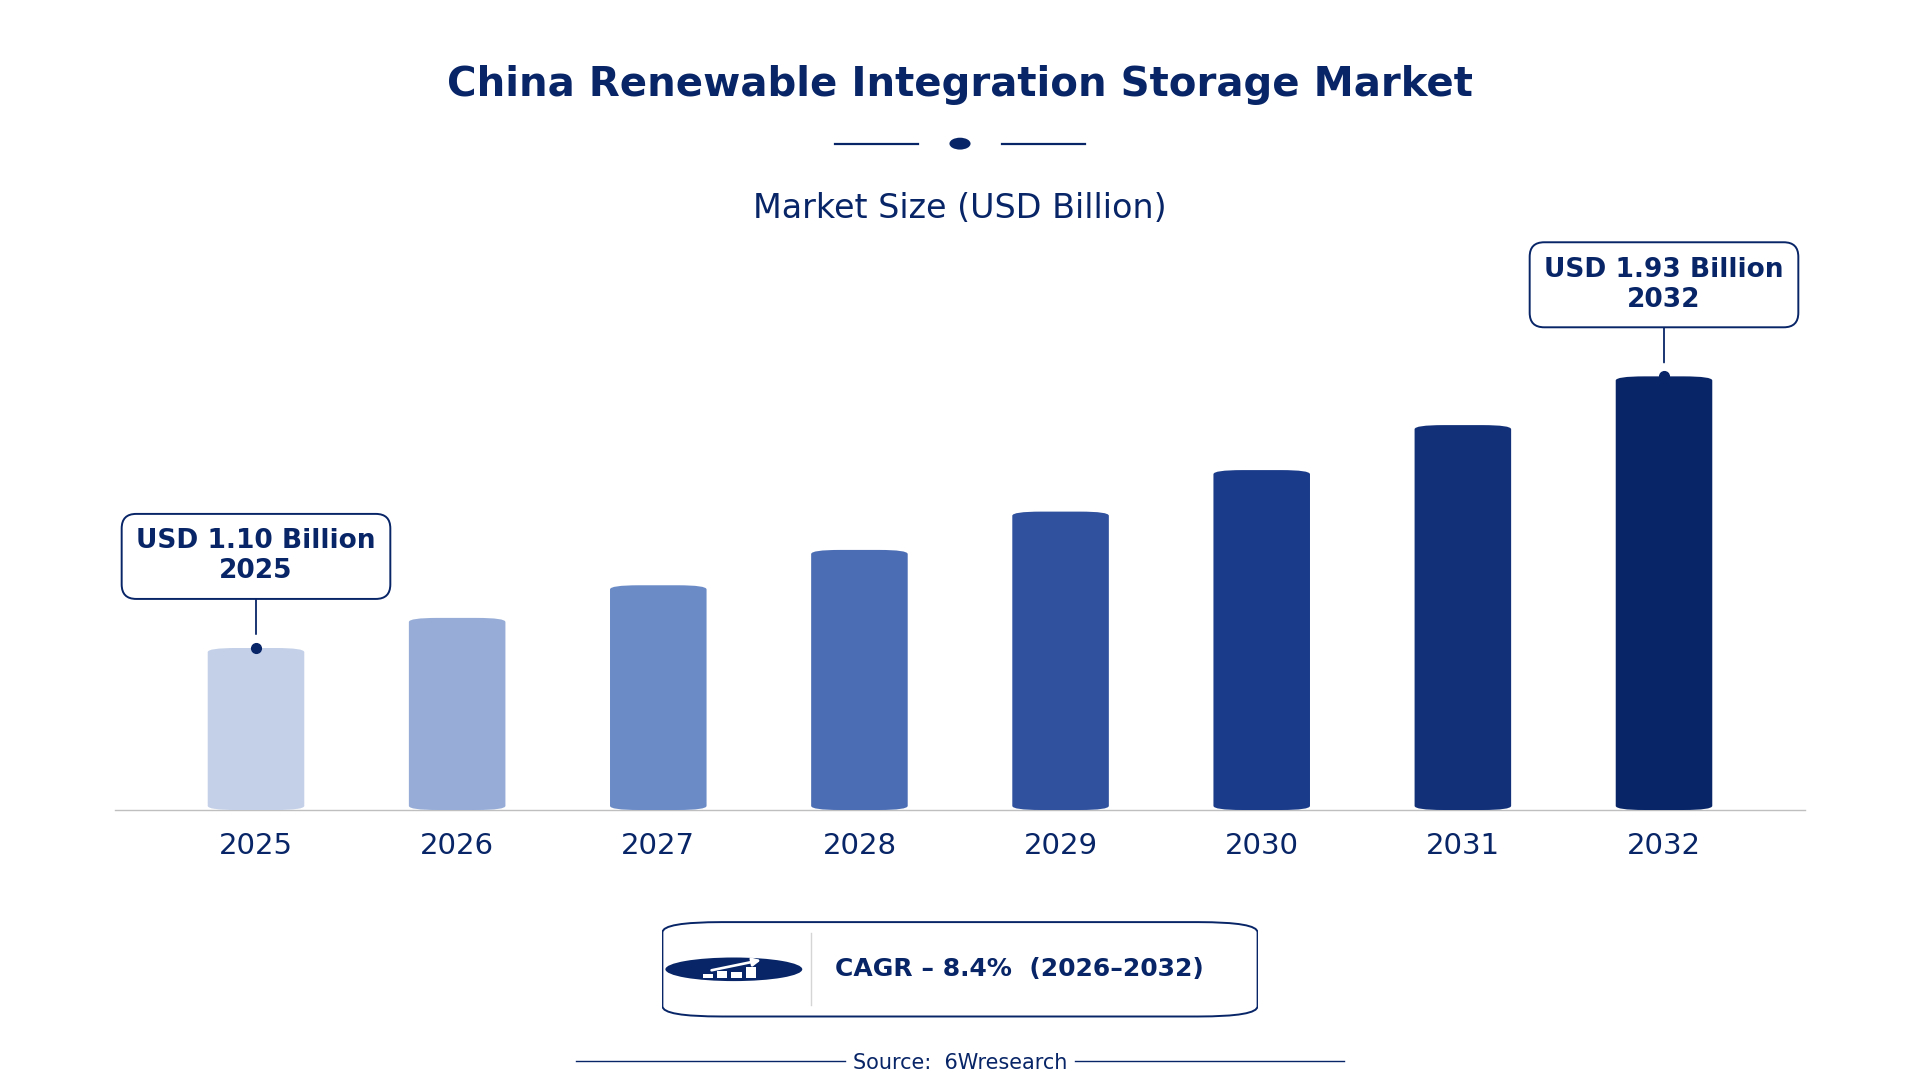
According to 6Wresearch internal database and industry insights, the China Renewable Integration Storage Market was valued at USD 1.10 billion in 2025 and is projected to reach USD 1.93 billion by 2032, growing at a CAGR of approximately 8.4% during 2026–2032.
China Renewable Integration Storage Market Highlights
| Report Metric | Details |
| Report Name | China Renewable Integration Storage Market |
| Market Size 2025 | USD 1.10 billion |
| Market Size 2032 | USD 1.93 billion |
| Absolute Growth 2025–2032 | USD 0.83 billion |
| CAGR 2026–2032 | 8.4% |
| Peak Annual Growth | 10.5% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Storage Type, 2025 | Battery Energy Storage (40% share) |
| Leading Application, 2025 | PV/Wind + BESS (41% share) |
| Leading Integration Mode, 2025 | Grid-Tied (44% share) |
| Leading End User, 2025 | Grid Operators (46% share) |
| Fastest-Growing Storage Type | Hybrid Systems (10.6% CAGR) |
| Fastest-Growing Application | CSP & Microgrids (10.1% CAGR) |
| Fastest-Growing Integration Mode | Smart Grid (11.2% CAGR) |
| Fastest-Growing End User | Distributed Energy Resources (10.9% CAGR) |
| Growing Sector | Energy Storage Solutions |
| Key End Users | Grid Operators, Renewable Gas Utilities, Distributed Energy Resources |
China Renewable Integration Storage Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
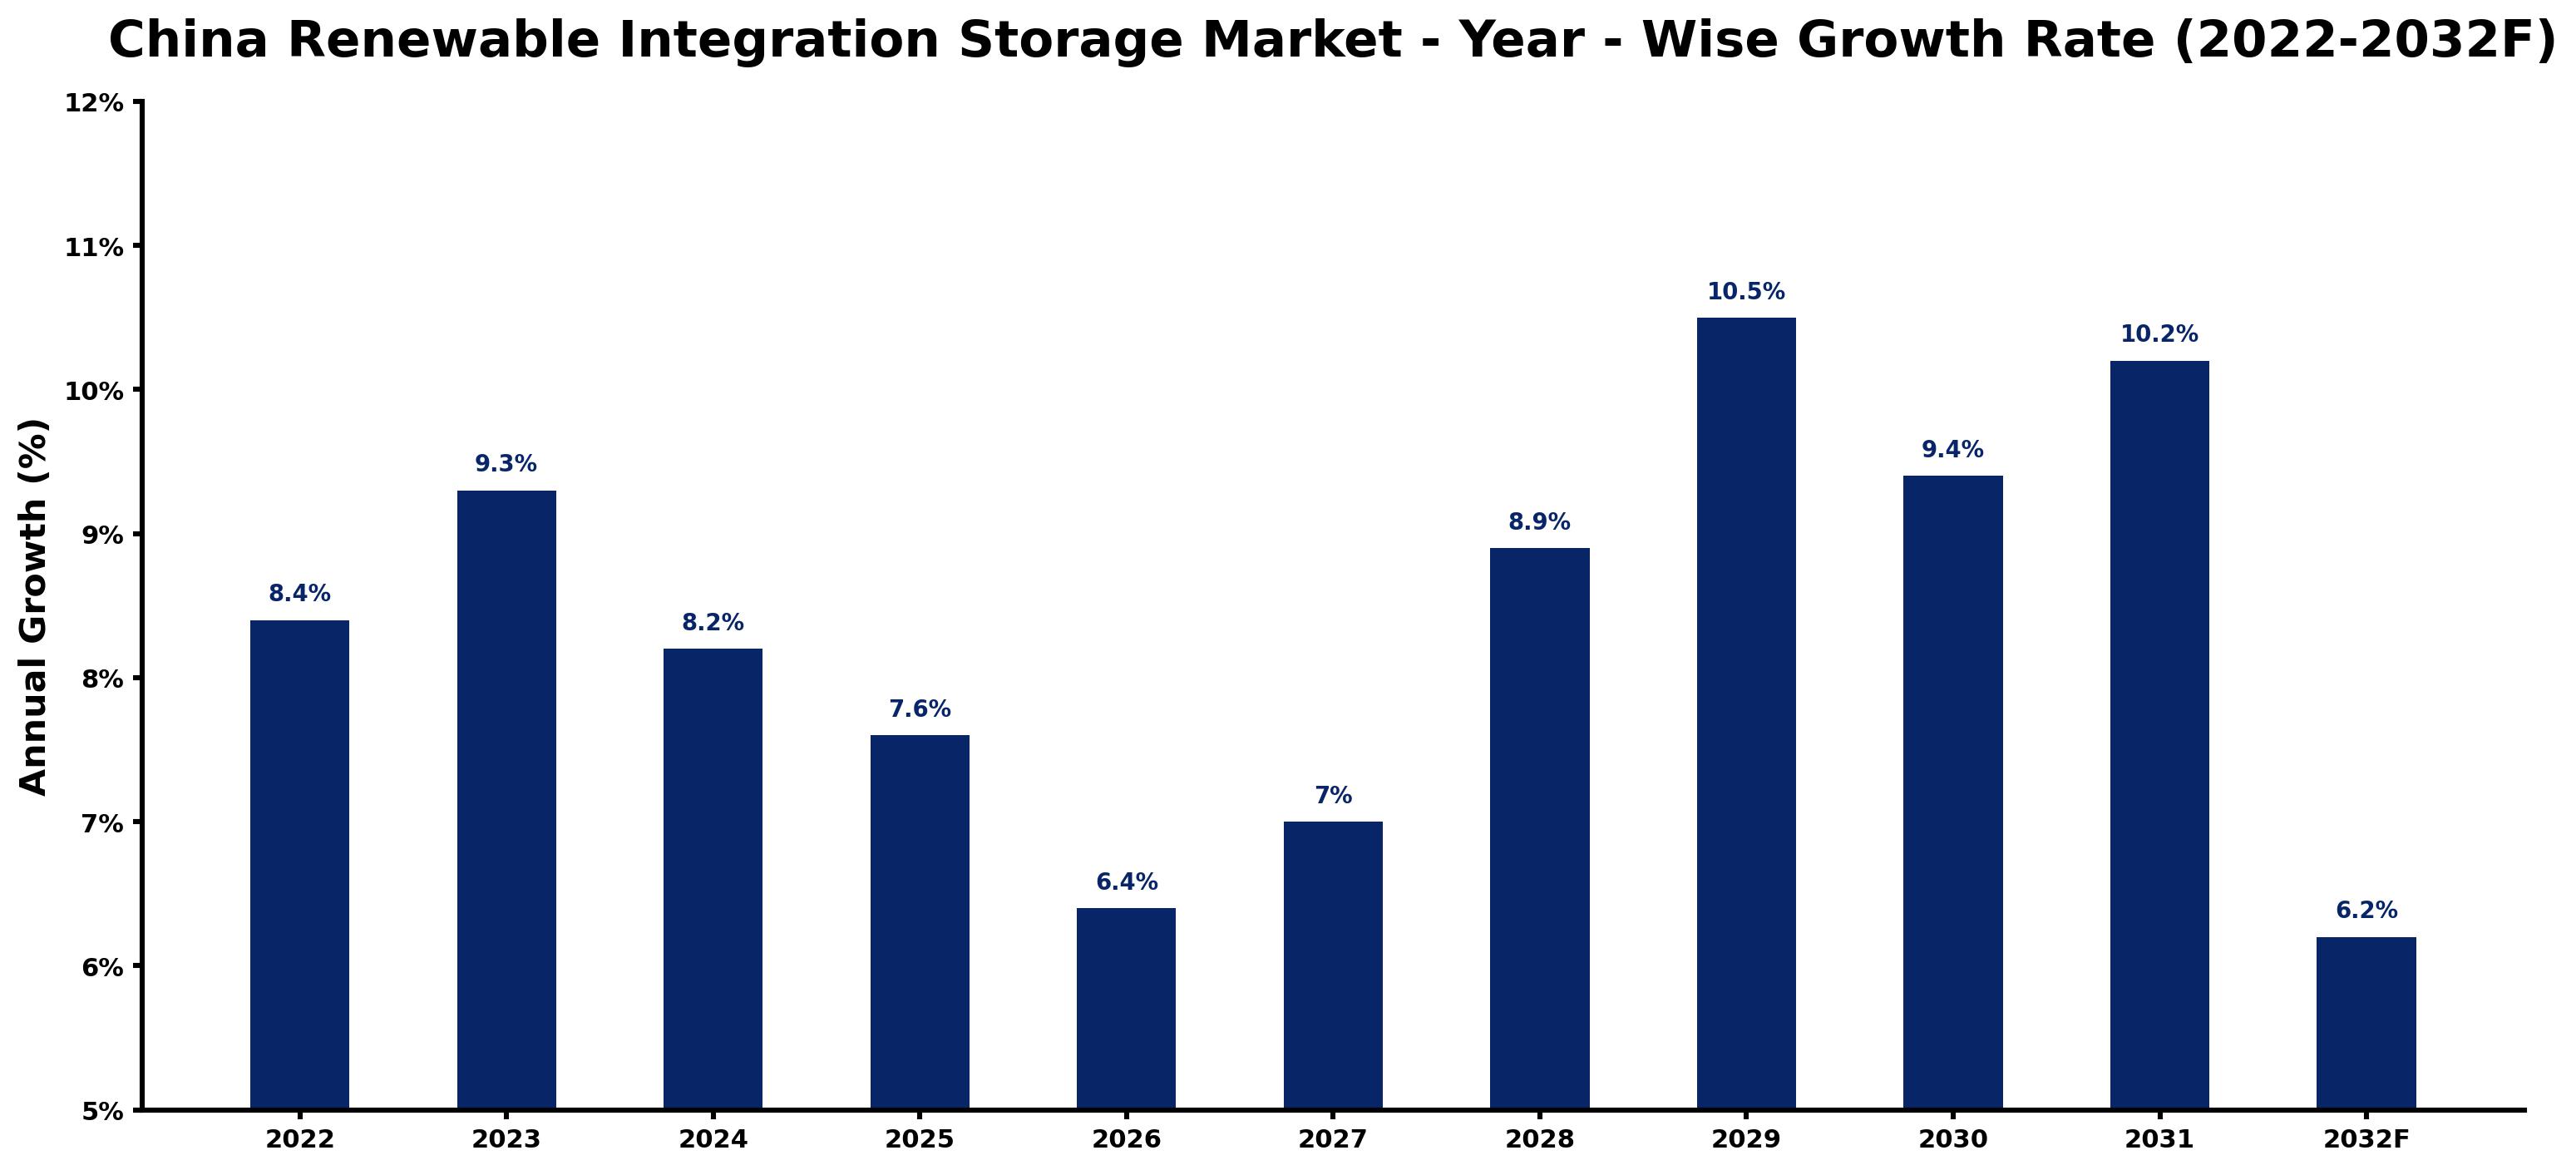
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 8.4 | The market experienced steady growth due to increasing investments in renewable energy technologies. |
| 2023 | 9.3 | Growth accelerated as the government launched the 'Energy Storage Development Action Plan' to support energy storage deployment. |
| 2024 | 8.2 | The market saw a slowdown as energy storage projects faced implementation challenges due to regulatory compliance. |
| 2025 | 7.6 | Growth continued to slow as the market adjusted to evolving technology standards and project timelines. |
| 2026 | 6.4 | A further slowdown is expected as the market adapts to new integration requirements for energy storage systems. |
| 2027 | 7.0 | Growth is projected to pick up again as demand for energy storage solutions increases among grid operators. |
| 2028 | 8.9 | The market is expected to experience a resurgence as smart grid initiatives expand across provinces. |
| 2029 | 10.5 | Peak growth is anticipated driven by substantial investments in battery energy storage systems and grid reliability improvements. |
| 2030 | 9.4 | Growth is expected to slow again as market conditions stabilise following peak demand and project completions. |
| 2031 | 10.2 | A faster growth rate will return as new energy storage projects gain traction and funding support. |
| 2032 | 6.2 | The market is projected to grow at a slower rate as competition increases among suppliers. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Renewable Integration Storage Market Synopsis
Renewable Integration Storage in China refers to technologies that store energy generated from renewable sources for later use. This includes advanced battery technologies and thermal storage systems, essential for stabilising energy supply and ensuring grid reliability. The China Renewable Integration Storage Market is expanding due to substantial investments in renewable energy and government initiatives like the 'Energy Storage Development Action Plan'. With over 300 GW of installed renewable energy capacity, demand continues to rise as grid operators seek reliable energy management solutions.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing investments in Battery Energy Storage Systems (BESS) enhance grid reliability. | Driver | High | Battery Energy Storage |
| The increasing integration of renewable sources drives demand for thermal storage solutions. | Driver | High | Thermal Storage |
| The expansion of smart grid initiatives presents opportunities for energy storage providers. | Opportunity | High | Smart Grid |
| The need for hydrogen storage solutions is rising as renewable gas utilities expand. | Opportunity | Medium | Hydrogen Storage |
| Implementation challenges in energy storage projects can delay market growth. | Restraint | High | Battery Energy Storage |
| High initial costs of advanced storage technologies may limit market penetration. | Restraint | Medium | Thermal Storage |
| The Renewable Integration Storage Market in China faces regulatory compliance challenges. | Challenge | High | Hydrogen Storage |
| Technological advancements in energy storage are evolving rapidly, creating adaptation challenges. | Challenge | Medium | Battery Energy Storage |
Evaluation of Drivers in China Renewable Integration Storage Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investments in energy storage technologies support grid integration. | Battery Energy Storage | China's energy storage market is expected to see investments exceeding 100 billion CNY by 2025. |
| Growing demand for renewable energy sources drives the need for thermal storage. | Thermal Storage | The installed base of thermal storage systems is projected to reach 10 GW by 2025. |
| The push for carbon neutrality encourages the adoption of hydrogen storage solutions. | Hydrogen Storage | Hydrogen production capacity from renewable sources is targeted to reach 1 million tons by 2030. |
| Smart grid initiatives are enhancing the reliability of energy management systems. | Smart Grid | Smart grid initiatives are being implemented in 15 provinces to improve grid reliability. |
| The integration of PV/Wind with Battery Energy Storage Systems enhances energy stability. | PV/Wind + BESS | Battery Energy Storage Systems are crucial for integrating 200 GW of wind energy by 2025. |
The Renewable Integration Storage market in China is growing on the back of rising end-use demand for energy storage solutions, driven by increased investments in renewable energy technologies. The National Energy Administration plans to boost energy storage capacity to 30 GW by 2025, improving grid reliability and stability. The installed base of thermal storage systems is set to reach 10 GW by 2025, encouraging further adoption among grid operators. With hydrogen production capacity from renewable sources targeted to hit 1 million tons by 2030, demand for hydrogen storage solutions will rise.
Evaluation of Restraints in China Renewable Integration Storage Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory compliance challenges can delay project implementation. | Battery Energy Storage | The Renewable Energy Law mandates integration of storage solutions, complicating project timelines and approvals. |
| High initial costs of advanced storage technologies may limit market penetration. | Thermal Storage | Investments in thermal storage systems require substantial capital, impacting adoption rates among smaller projects. |
| Limited public awareness about energy storage benefits affects market growth. | Hydrogen Storage | A lack of understanding among consumers can hinder the adoption of hydrogen storage solutions and technologies. |
| Supply chain disruptions can impact the availability of storage components. | Smart Grid | Global supply chain issues have affected the timely delivery of essential smart grid technology components. |
| Technological complexities in integrating storage systems can slow down deployment. | PV/Wind + BESS | Challenges in ensuring compatibility with existing infrastructure can delay installations and project timelines. |
China Renewable Integration Storage Market Challenges
The China Renewable Integration Storage market encounters several practical issues, starting with high initial costs for energy storage systems, which can exceed 1 million CNY per installation, making financing difficult for smaller projects. Intense competition among suppliers results in price wars that may compromise quality and reliability, ultimately jeopardising project outcomes for buyers. Rising raw material costs for storage technologies have increased production expenses, causing project delays and squeezing profit margins for suppliers. Regulatory changes, particularly mandates from the Renewable Energy Law, create compliance hurdles that can slow project approvals and restrict market growth for producers.
Trends in the China Renewable Integration Storage Market
Four trends stand out in the China Renewable Integration Storage Market.
- Shift towards Smart Grid Integration: The implementation of smart grid initiatives in 15 provinces is expected to improve energy distribution efficiency, with investments surpassing 100 billion CNY by 2025.
- Expansion of Hydrogen Storage Solutions: The focus on hydrogen storage is increasing as renewable gas utilities expand. The target of achieving 1 million tons of hydrogen production capacity by 2030 marks a shift towards cleaner energy storage solutions.
- Increased Adoption of Thermal Storage Systems: Thermal storage systems are becoming a reliable energy management solution. The installed base is anticipated to reach 10 GW by 2025, supporting the integration of renewable energy sources.
- Growth in Battery Energy Storage Systems: Battery Energy Storage Systems are becoming crucial for integrating renewable energy sources. With plans to integrate 200 GW of wind energy by 2025, demand for BESS is expected to surge.
Investment Opportunities in the China Renewable Integration Storage Market
Investors looking at the China Renewable Integration Storage Market should consider the following areas.
- Investment in Smart Grid Facilities: Smart grid facilities are currently expanding across 15 provinces, creating opportunities for investment in energy storage technologies. With a projected investment of over 100 billion CNY by 2025, suppliers can enter through local partnerships and collaborations.
- Demand for Hydrogen Storage Solutions: As renewable gas utilities expand, the need for hydrogen storage solutions is increasing. With a target of 1 million tons of hydrogen production capacity by 2030, companies can invest in technology development and certification processes.
- Expansion of Thermal Storage Systems: The growing focus on thermal storage systems presents an opportunity for suppliers. With the installed base projected to reach 10 GW by 2025, entering through partnerships with grid operators can be advantageous for market entry.
- Growth in Battery Energy Storage Systems: The demand for Battery Energy Storage Systems is rising as the market integrates more renewable energy. Suppliers can target grid operators looking to improve energy reliability and system performance.
Government Initiatives in the China Renewable Integration Storage Market
The Renewable Integration Storage market is shaped by various government measures. The 'Renewable Energy Law' mandates the integration of storage solutions in new projects, while the '14th Five-Year Plan for Energy' emphasises enhancing energy storage capabilities. Additionally, the 'Energy Storage Development Action Plan' launched in 2021 aims to support the deployment of 30 GW of energy storage by 2025. These policies create a supportive environment for producers and buyers alike, ensuring compliance and encouraging innovation.
In 2023, funding for 50 pilot energy storage projects was approved across various provinces by the National Development and Reform Commission. The Ministry of Industry and Information Technology initiated a subsidy programme for energy storage technologies to promote innovation and adoption. These initiatives aim to facilitate the deployment of energy storage systems and encourage research and development in the sector, benefiting both producers and consumers.
Future Insight of the China Renewable Integration Storage Market
The China Renewable Integration Storage market will experience notable changes by 2032, driven by government initiatives and technological advancements. The National Energy Administration plans to increase energy storage capacity to 30 GW by 2025, facilitating the integration of renewable sources. Investments in the energy storage market are expected to exceed 100 billion CNY by 2025, opening new opportunities for buyers and suppliers. The promotion of hydrogen production from renewable sources is set to reach 1 million tons by 2030, further diversifying the market.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Storage Type – Battery Energy Storage Dominated, Hybrid Systems Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, the largest storage type category in 2025 was Battery Energy Storage, with a 40% share of total revenue. Battery Energy Storage holds the largest share because it plays a critical role in storing excess energy generated from renewable sources, particularly in regions with high solar and wind capacity. This technology is essential for the anticipated integration of 200 GW of wind energy by 2025, highlighting its significance in the market. Over 2026–2032, Hybrid Systems are expected to post the fastest growth, at a CAGR of 10.6%. Hybrid Systems are experiencing rapid growth as they combine various storage technologies, enhancing efficiency and reliability in energy management. The increasing demand for flexible solutions in energy storage applications across China is a key factor driving this expansion. Suppliers should prioritise the development of hybrid solutions to meet the rising need for efficient energy storage technologies.
By Application – PV/Wind + BESS Dominated, CSP & Microgrids Expected to Grow Fastest
With a 41% revenue share in 2025, PV/Wind + BESS was the largest application category. The PV/Wind + BESS segment leads the market as it effectively combines solar and wind energy generation with battery storage, ensuring a stable energy supply. This integration is vital for supporting China's ambitious renewable energy targets and installed capacity goals. The quickest growth will come from CSP & Microgrids, forecast to expand at a CAGR of 10.1% between 2026 and 2032. CSP & Microgrids are growing quickly due to the rising interest in concentrated solar power systems and the need for localised energy solutions. The government's push for energy storage in microgrids aligns with the increasing demand for decentralised energy management. Buyers should consider investing in CSP and microgrid technologies to capitalise on the rapid growth in this application area.
By Integration Mode – Grid-Tied Dominated, Smart Grid Expected to Grow Fastest
Grid-Tied held a 44% share of the China Renewable Integration Storage Market by integration mode in 2025. Grid-Tied systems dominate the market as they connect storage solutions directly to the grid, facilitating effective energy management and distribution. This direct connection is vital for supporting China's extensive renewable energy capacity, ensuring grid stability and reliability. Smart Grid is projected to grow fastest, at a CAGR of 11.2% during 2026–2032. Smart Grid solutions are rapidly gaining traction as they enhance grid intelligence and efficiency, allowing for improved integration of renewable energy sources. The government's initiatives to implement smart grids across 15 provinces significantly contribute to this growth. Suppliers must focus on smart grid technologies to satisfy the increasing demand for efficient energy integration.
By End User – Grid Operators Dominated, Distributed Energy Resources Expected to Grow Fastest
In 2025, Grid Operators led the end user split with a 46% share. Grid Operators represent the largest share of the market since they rely on energy storage systems to balance supply and demand effectively. Their crucial role is vital in managing the extensive renewable energy infrastructure being developed throughout the country. Distributed Energy Resources are set to record the highest CAGR in this split, 10.9% over 2026–2032. Distributed Energy Resources are witnessing the fastest growth as they facilitate the shift towards decentralised energy generation and storage solutions. This trend is fuelled by the growing adoption of localised energy systems that enhance resilience and efficiency. Buyers should explore opportunities in distributed energy resources to leverage the growing trend towards decentralised energy solutions.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Renewable Integration Storage Market Outlook
- Market Size of China Renewable Integration Storage Market, 2025
- Forecast of China Renewable Integration Storage Market, 2032
- Historical Data and Forecast of China Renewable Integration Storage Revenues & Volume for the Period 2022 - 2032F
- China Renewable Integration Storage Market Trend Evolution
- China Renewable Integration Storage Market Drivers and Challenges
- China Renewable Integration Storage Price Trends
- China Renewable Integration Storage Porter's Five Forces
- China Renewable Integration Storage Industry Life Cycle
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By Storage Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By Battery Energy Storage for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By Thermal Storage for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By Hybrid Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By Hydrogen Storage for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By PV/Wind + BESS for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By CSP & Microgrids for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By Solar-Wind-Battery for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By H2 from Surplus RE for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By Integration Mode for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By Co-Located Installations for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By Grid-Tied for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By Smart Grid for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By Power-to-Gas for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By Grid Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By Solar Thermal Plants for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By Distributed Energy Resources for the Period 2022 - 2032F
- Historical Data and Forecast of China Renewable Integration Storage Market Revenues & Volume By Renewable Gas Utilities for the Period 2022 - 2032F
- China Renewable Integration Storage Import Export Trade Statistics
- Market Opportunity Assessment By Storage Type
- Market Opportunity Assessment By Application
- Market Opportunity Assessment By Integration Mode
- Market Opportunity Assessment By End User
- China Renewable Integration Storage Top Companies Market Share
- China Renewable Integration Storage Competitive Benchmarking By Technical and Operational Parameters
- China Renewable Integration Storage Company Profiles
- China Renewable Integration Storage Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Storage Type
- Battery Energy Storage
- Thermal Storage
- Hybrid Systems
- Hydrogen Storage
By Application
- PV/Wind + BESS
- CSP & Microgrids
- Solar-Wind-Battery
- H2 from Surplus RE
By Integration Mode
- Co-Located Installations
- Grid-Tied
- Smart Grid
- Power-to-Gas
By End User
- Grid Operators
- Solar Thermal Plants
- Distributed Energy Resources
- Renewable Gas Utilities































