China Satellite 5G Connectivity Market Size & Growth Rate
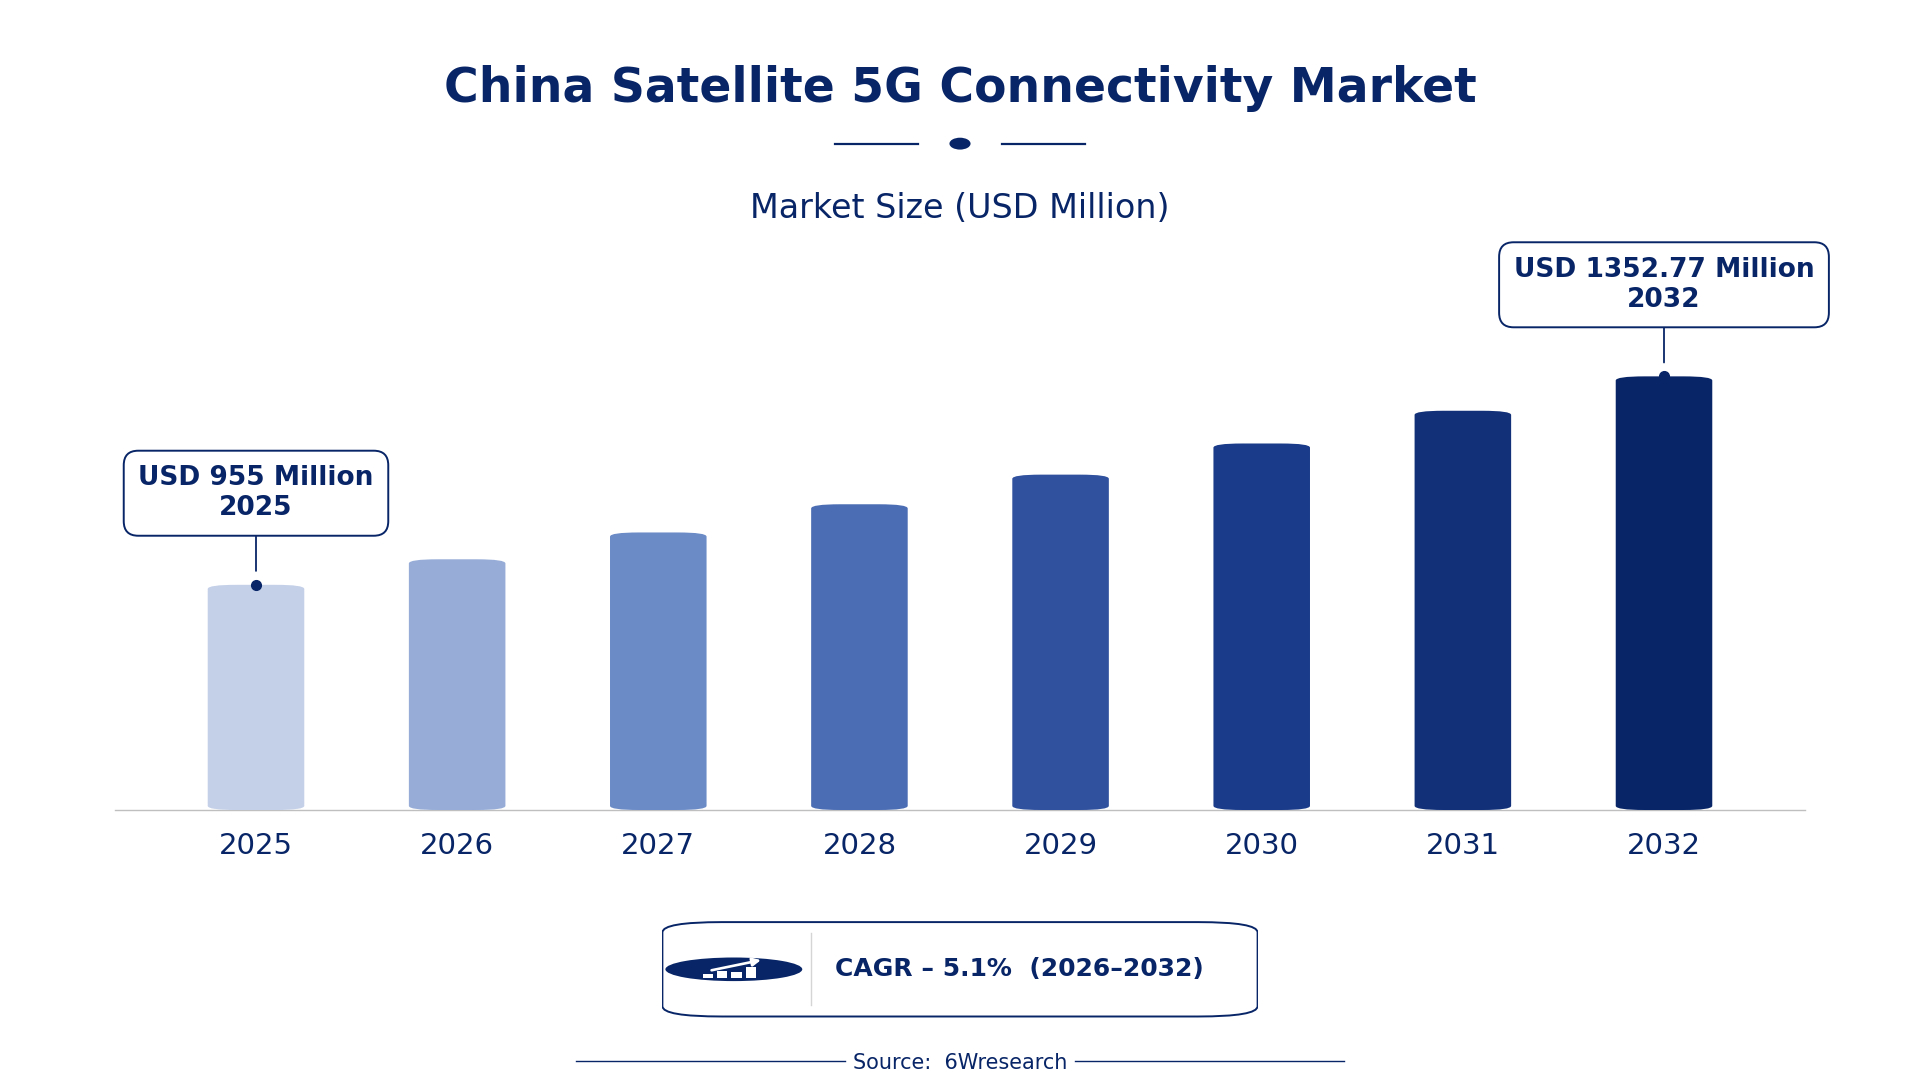
According to 6Wresearch internal database and industry insights, the China Satellite 5G Connectivity Market was valued at USD 955.0 million in 2025 and is projected to reach USD 1,352.77 million by 2032, growing at a CAGR of approximately 5.1% during 2026–2032.
China Satellite 5G Connectivity Market Highlights
| Report Metric | Details |
| Report Name | China Satellite 5G Connectivity Market |
| Market Size 2025 | USD 955.0 million |
| Market Size 2032 | USD 1,352.77 million |
| Absolute Growth 2025–2032 | USD 397.77 million |
| CAGR 2026–2032 | 5.1% |
| Peak Annual Growth | 7.4% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Connectivity Type, 2025 | Non-Terrestrial Networks (NTN) (35% share) |
| Leading Satellite Type, 2025 | LEO (45% share) |
| Leading Network Architecture, 2025 | Integrated Core (41% share) |
| Leading End User, 2025 | Mobile Network Operators (36% share) |
| Fastest-Growing Connectivity Type | IoT over Satellite (7.7% CAGR) |
| Fastest-Growing Network Architecture | Edge Connectivity (6.4% CAGR) |
| Fastest-Growing End User | Agriculture Tech Providers (7.7% CAGR) |
| Growing Sector | Agriculture |
| Key End Users | Mobile Network Operators, Remote Area ISPs, Agriculture Tech Providers |
China Satellite 5G Connectivity Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
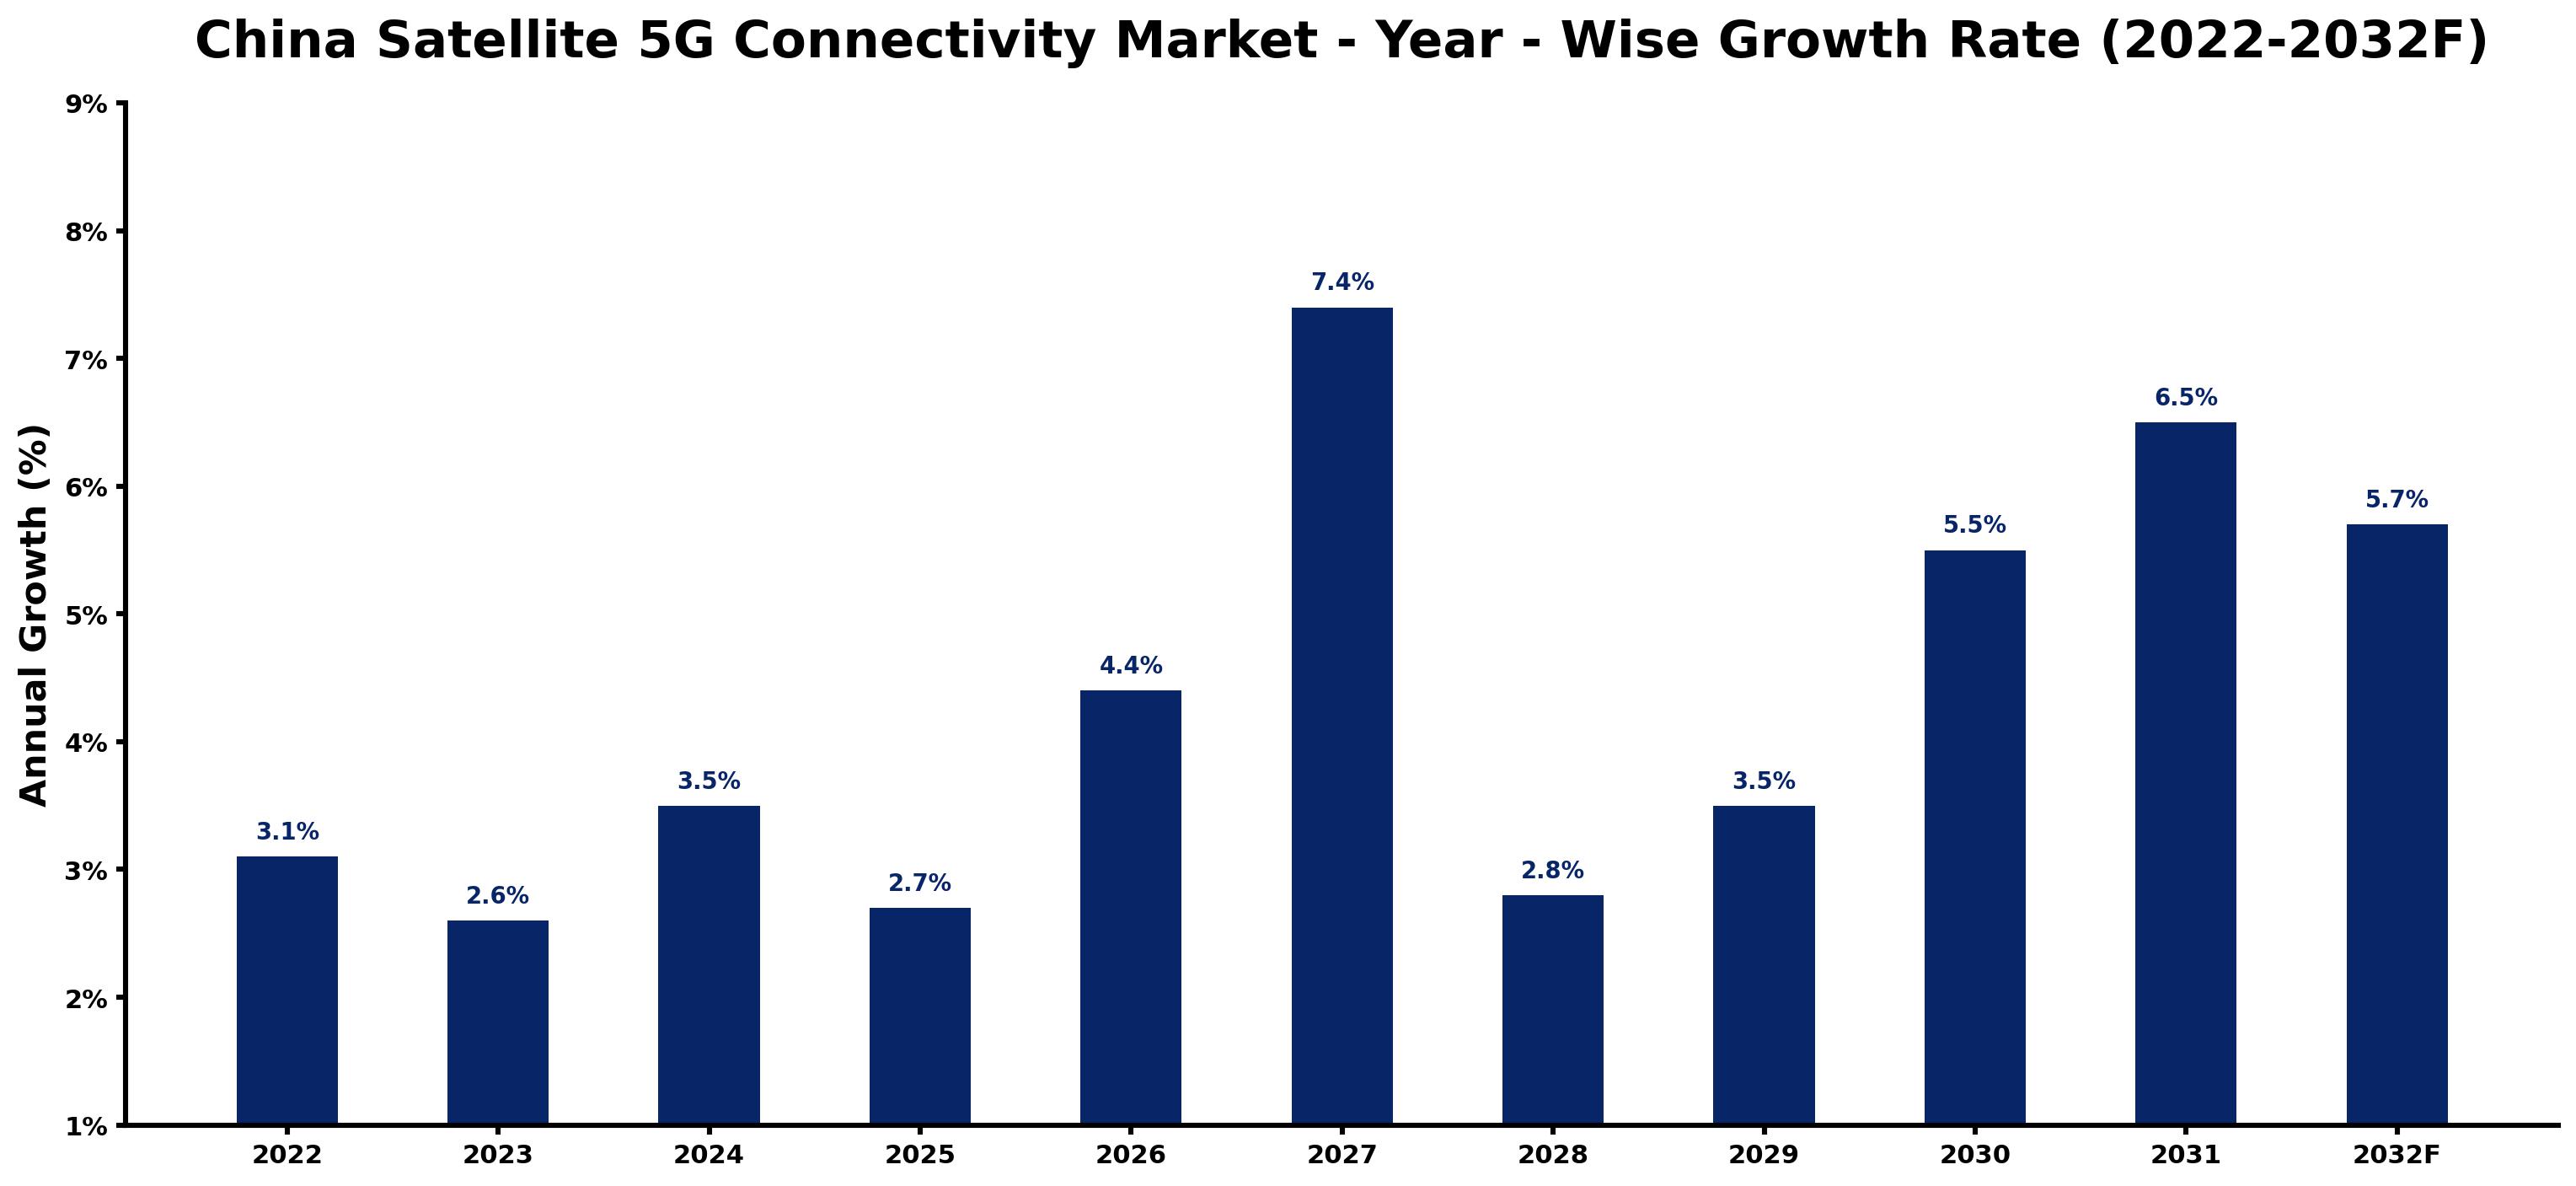
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.1 | The market showed steady growth due to increasing satellite internet users. |
| 2023 | 2.6 | Growth slowed as the market adjusted to new technology standards. |
| 2024 | 3.5 | Demand accelerated with the launch of new satellite services. |
| 2025 | 2.7 | Growth slowed again as competition intensified among providers. |
| 2026 | 4.4 | Expansion in rural connectivity initiatives spurred market growth. |
| 2027 | 7.4 | The peak growth was driven by significant investments in satellite infrastructure. |
| 2028 | 2.8 | Growth slowed as market saturation began in urban areas. |
| 2029 | 3.5 | Demand increased again as IoT applications expanded in agriculture. |
| 2030 | 5.5 | Growth continued with rising adoption of satellite technology in rural regions. |
| 2031 | 6.5 | The market grew further as government initiatives supported connectivity. |
| 2032 | 5.7 | Growth slowed slightly as the market approached maturity. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Satellite 5G Connectivity Market Synopsis
Satellite 5G Connectivity in China merges satellite communication with 5G networks to provide high-speed internet access, especially in remote regions. This technology improves connectivity for rural areas and supports IoT applications. The China Satellite 5G Connectivity Market is expanding due to rising demand from mobile network operators and initiatives outlined in the National Development and Reform Commission's 14th Five-Year Plan. With a goal to connect 90% of rural households to high-speed internet by 2025, the market is set for robust growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing rural connectivity initiatives drive demand for satellite services. | Driver | High | Non-Terrestrial Networks (NTN) |
| Growing adoption of IoT applications in agriculture boosts satellite connectivity needs. | Driver | High | IoT over Satellite |
| Investment in satellite infrastructure development presents opportunities for suppliers. | Opportunity | High | LEO |
| The demand for enhanced connectivity in remote areas creates a market gap. | Opportunity | High | Hybrid 5G-Satellite |
| Limited infrastructure in rural areas restricts service availability. | Restraint | High | Direct-to-Device (D2D) |
| High costs associated with satellite technology deployment can deter new entrants. | Restraint | Medium | IoT over Satellite |
| Regulatory hurdles can delay satellite deployment and approvals. | Challenge | High | Hybrid 5G-Satellite |
| Technological complexities in integrating satellite and terrestrial networks pose challenges. | Challenge | Medium | Non-Terrestrial Networks (NTN) |
Evaluation of Drivers in China Satellite 5G Connectivity Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising demand for high-speed internet access in rural areas. | Non-Terrestrial Networks (NTN) | This demand is driven by the need for reliable connectivity, with 40% of rural households lacking internet access. |
| Increased investment in IoT applications for agriculture. | IoT over Satellite | Agriculture tech providers are adopting satellite solutions for smart farming, reflecting a growing sector. |
| Government initiatives promoting satellite communication technologies. | LEO | The 14th Five-Year Plan aims to boost satellite communication capabilities, driving market growth. |
| Expansion of satellite internet user base in China. | Hybrid 5G-Satellite | In 2022, satellite internet users reached 1 million, indicating growing adoption. |
| Development of a large-scale LEO satellite constellation. | Direct-to-Device (D2D) | China's plan to launch over 12,000 satellites by 2030 will broaden connectivity options. |
Approximately 40% of rural areas lack dependable internet, prompting mobile network operators to seek satellite solutions. The 14th Five-Year Plan aims to strengthen satellite communication capabilities, with a $200 million allocation for infrastructure development in 2023. In 2022, satellite internet users reached 1 million, showing growing adoption. The planned launch of over 12,000 LEO satellites by 2030 will broaden connectivity options.
Evaluation of Restraints in China Satellite 5G Connectivity Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Limited infrastructure in rural areas restricts service availability. | Direct-to-Device (D2D) | With 40% of rural households lacking reliable internet, service providers face challenges in reaching these areas. |
| High costs associated with satellite technology deployment can deter new entrants. | IoT over Satellite | The investment required for satellite infrastructure can be a barrier for smaller providers. |
| Regulatory hurdles can delay satellite deployment and approvals. | Hybrid 5G-Satellite | Complex approval processes can slow down the introduction of new services. |
| Technological complexities in integrating satellite and terrestrial networks pose challenges. | Non-Terrestrial Networks (NTN) | The integration process requires advanced expertise and can lead to delays. |
| Competition among providers may lead to price wars, affecting profitability. | LEO | As more players enter the market, maintaining competitive pricing becomes challenging. |
China Satellite 5G Connectivity Market Challenges
The China Satellite 5G Connectivity market still has to solve a few problems, and the first is cost. High infrastructure expenses, driven by the need for advanced technology, can delay project timelines for producers, impacting their ability to scale operations efficiently. Technology limitations present a hurdle; the integration of satellite systems with terrestrial 5G networks remains complex, hindering progress for importers reliant on sophisticated components. Supply chain disruptions complicate matters, as delays in component imports can stall deployment efforts for buyers, especially in rural areas where 40% lack reliable internet access. Competition from terrestrial connectivity options pressures prices, forcing producers to lower costs while maintaining quality, which can squeeze their profit margins.
Trends in the China Satellite 5G Connectivity Market
Several trends are reshaping the China Satellite 5G Connectivity Market; the most important are set out below.
- Shift from Traditional to Satellite-Based Connectivity: In 2021, the National Development and Reform Commission launched the 'Satellite Internet Development Plan', promoting satellite communication for rural connectivity. This shift is vital as many rural areas lack reliable internet access.
- Transition to IoT-Driven Agriculture: The agriculture sector is increasingly adopting IoT over Satellite for smart farming solutions. In 2023, the Ministry of Agriculture and Rural Affairs supported this trend with initiatives targeting a $300 million budget.
- Emergence of LEO Satellites: China's LEO satellite constellation is set to launch over 12,000 satellites by 2030. This initiative aims to provide low latency and high-speed connectivity, significantly improving internet access in underserved areas.
- Prioritisation of Rural Connectivity: The government targets connecting 90% of rural households to high-speed internet by 2025. This ambitious goal is part of broader efforts to strengthen satellite communication capabilities across the country.
Investment Opportunities in the China Satellite 5G Connectivity Market
Several openings in the China Satellite 5G Connectivity Market merit attention from investors.
- Investment in Satellite Infrastructure Development: With a $200 million government allocation in 2023, there is an opportunity for suppliers to invest in satellite communication infrastructure, particularly in rural areas.
- Supply of IoT Solutions for Agriculture: The agriculture sector is increasingly adopting IoT over Satellite. Suppliers can target agriculture tech providers to meet this growing demand.
- Expansion of Hybrid 5G-Satellite Services: As demand for enhanced connectivity grows, there is an opportunity to supply hybrid solutions. The market is expected to expand in the coming years.
- Development of Direct-to-Device Solutions: The increasing need for direct satellite communication creates a gap in the market. Suppliers can focus on developing innovative D2D solutions.
Government Initiatives in the China Satellite 5G Connectivity Market
In 2021, the National Development and Reform Commission launched the 'Satellite Internet Development Plan', which aims to connect 90% of rural households by 2025 and outlines specific targets for satellite deployment and infrastructure investment. This plan builds on previous initiatives to improve internet access in underserved areas, providing a clear framework for future developments. It enhances the capabilities of satellite communication and focuses on rural connectivity, ensuring comprehensive coverage across the country.
The Ministry of Industry and Information Technology oversees the implementation of the '14th Five-Year Plan for the Development of the Satellite Industry', which funds satellite communication projects. This plan allocates significant resources to improve connectivity, with a budget of $300 million announced in 2023. Additionally, the China Satellite Network Group is responsible for developing satellite communication networks, ensuring alignment with national standards and enhancing service delivery for users.
Future Insight of the China Satellite 5G Connectivity Market
The China Satellite 5G Connectivity market will see substantial advancements by 2032, primarily focusing on expanding coverage. The government targets connecting 90% of rural households to high-speed internet by 2025, which will drive demand for satellite solutions. With plans to launch over 12,000 satellites by 2030, suppliers will enhance their capacity to meet connectivity needs. The rise of IoT applications in agriculture will further accelerate, enabling smarter farming practices and increasing market adoption.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Connectivity Type – Non-Terrestrial Networks (NTN) Dominated, IoT over Satellite Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, with a 35% revenue share in 2025, Non-Terrestrial Networks (NTN) was the largest connectivity type category. Non-Terrestrial Networks (NTN) hold the largest market share as they are vital for providing connectivity in areas lacking terrestrial infrastructure. The government's goal to connect 90% of rural households to high-speed internet by 2025 highlights NTN's essential role in bridging the connectivity gap. The quickest growth will come from IoT over Satellite, forecast to expand at a CAGR of 7.7% between 2026 and 2032. IoT over Satellite is the fastest-growing segment, largely due to agriculture tech providers increasingly adopting it for smart farming solutions. This growth is fuelled by the agriculture sector's urgent need for reliable connectivity to support IoT applications in rural regions, ensuring efficient farming practices. Suppliers should focus on enhancing NTN capabilities to effectively meet the rising demand for connectivity solutions in underserved areas.
By Satellite Type – LEO Dominated and Is Expected to Record the Fastest Growth
The largest satellite type category in 2025 was LEO, with a 45% share of total revenue. LEO satellites dominate the market share because they offer low latency and high-speed connectivity, which are essential for users in remote locations. Their ability to support numerous simultaneous connections makes them especially valuable for expanding satellite internet access across China. LEO is also forecast to expand faster than any other category, at a CAGR of 7.0% over 2026–2032. LEO is also the fastest-growing segment, driven by the government's ambitious plan to launch over 12,000 satellites by 2030, significantly boosting capacity and coverage. This extensive expansion will further solidify LEO's position as the backbone of satellite 5G connectivity in the country. Investors should prioritise LEO satellite initiatives to capitalise on the anticipated growth and increasing demand for high-speed connectivity.
By Network Architecture – Integrated Core Dominated, Edge Connectivity Expected to Grow Fastest
Integrated Core held a 41% share of the China Satellite 5G Connectivity Market by network architecture in 2025. The Integrated Core segment leads the market share as it is essential for supporting network management in satellite 5G connectivity. The significance of this architecture is underscored by the Ministry of Industry and Information Technology's efforts to establish standards for satellite communication technologies. Edge Connectivity is set to record the highest CAGR in this split, 6.4% over 2026–2032. Edge Connectivity is the fastest-growing segment, primarily due to its application in specific use cases that require low latency. As more applications leveraging edge computing emerge, this segment is expected to gain traction, although it remains less prevalent than Integrated Core. Network architects must integrate edge connectivity solutions to meet specific application demands while ensuring robust core network management.
By End User – Mobile Network Operators Dominated, Agriculture Tech Providers Expected to Grow Fastest
In 2025, Mobile Network Operators led the end user split with a 36% share. Mobile Network Operators command the largest market share as they are the primary users of satellite 5G connectivity, utilising it to expand their service offerings in rural areas. Their established infrastructure and extensive customer base enable them to effectively leverage satellite technology for improved connectivity. Agriculture Tech Providers are projected to grow fastest, at a CAGR of 7.7% during 2026–2032. Agriculture Tech Providers represent the fastest-growing segment, driven by the increasing adoption of IoT solutions for precision agriculture. The agriculture sector's focus on enhancing efficiency through technology is propelling this segment's growth, distinguishing it from the broader mobile network operator market. Suppliers should tailor their offerings to meet the specific needs of agriculture tech providers, tapping into the growing demand for satellite-based IoT solutions.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Satellite 5G Connectivity Market Outlook
- Market Size of China Satellite 5G Connectivity Market, 2025
- Forecast of China Satellite 5G Connectivity Market, 2032
- Historical Data and Forecast of China Satellite 5G Connectivity Revenues & Volume for the Period 2022 - 2032F
- China Satellite 5G Connectivity Market Trend Evolution
- China Satellite 5G Connectivity Market Drivers and Challenges
- China Satellite 5G Connectivity Price Trends
- China Satellite 5G Connectivity Porter's Five Forces
- China Satellite 5G Connectivity Industry Life Cycle
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By Connectivity Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By Non-Terrestrial Networks (NTN) for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By Hybrid 5G-Satellite for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By Direct-to-Device (D2D) for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By IoT over Satellite for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By Satellite Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By LEO for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By GEO + 5G NR for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By MEO for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By LEO for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By Network Architecture for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By Integrated Core for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By Backhaul Integration for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By Edge Connectivity for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By Narrowband Architecture for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By Mobile Network Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By Remote Area ISPs for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By Handset Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Satellite 5G Connectivity Market Revenues & Volume By Agriculture Tech Providers for the Period 2022 - 2032F
- China Satellite 5G Connectivity Import Export Trade Statistics
- Market Opportunity Assessment By Connectivity Type
- Market Opportunity Assessment By Satellite Type
- Market Opportunity Assessment By Network Architecture
- Market Opportunity Assessment By End User
- China Satellite 5G Connectivity Top Companies Market Share
- China Satellite 5G Connectivity Competitive Benchmarking By Technical and Operational Parameters
- China Satellite 5G Connectivity Company Profiles
- China Satellite 5G Connectivity Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Connectivity Type
- Non-Terrestrial Networks (NTN)
- Hybrid 5G-Satellite
- Direct-to-Device (D2D)
- IoT over Satellite
By Satellite Type
- LEO
- GEO + 5G NR
- MEO
By Network Architecture
- Integrated Core
- Backhaul Integration
- Edge Connectivity
- Narrowband Architecture
By End User
- Mobile Network Operators
- Remote Area ISPs
- Handset Manufacturers
- Agriculture Tech Providers































