China Semiconductor Backend Process Market Size & Growth Rate
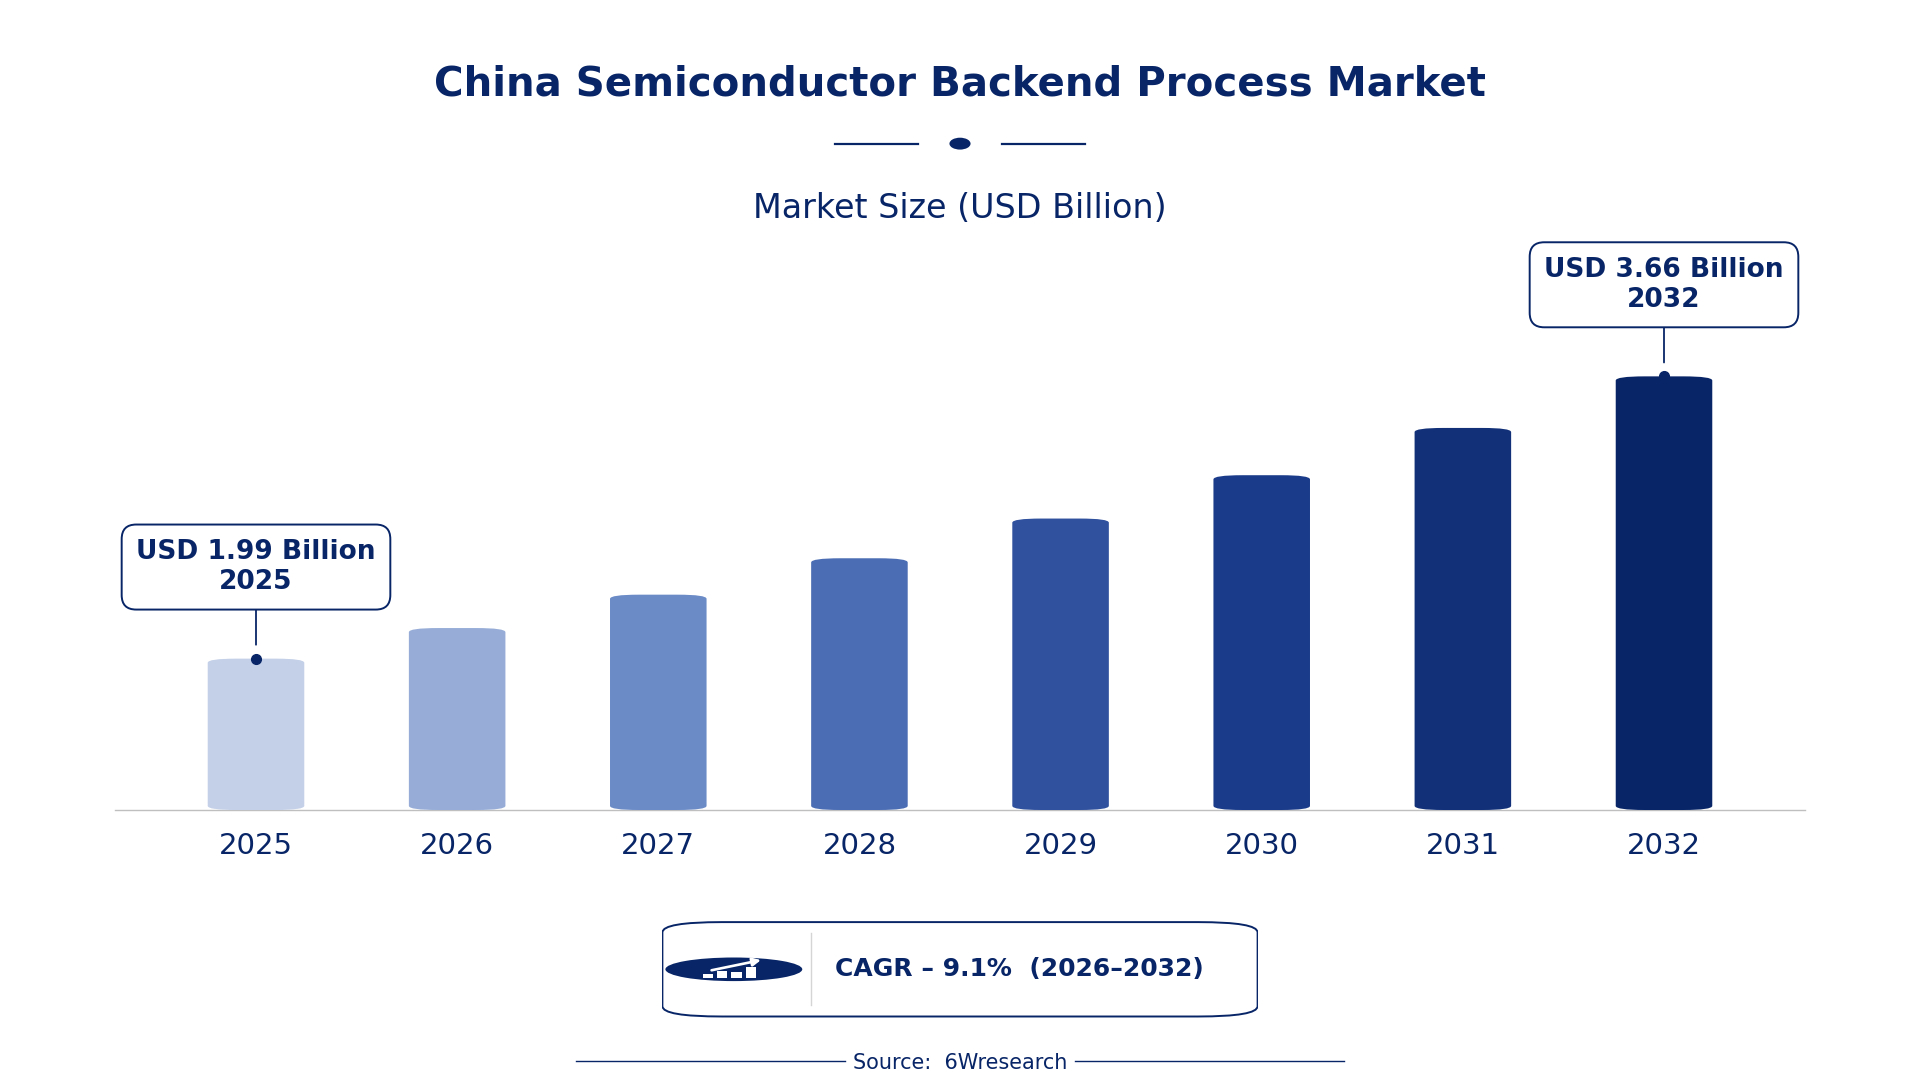
According to 6Wresearch internal database and industry insights, the China Semiconductor Backend Process Market was valued at USD 1.99 billion in 2025 and is projected to reach USD 3.66 billion by 2032, growing at a CAGR of approximately 9.1% during 2026–2032.
China Semiconductor Backend Process Market Highlights
| Report Metric | Details |
| Report Name | China Semiconductor Backend Process Market |
| Market Size 2025 | USD 1.99 billion |
| Market Size 2032 | USD 3.66 billion |
| Absolute Growth 2025–2032 | USD 1.67 billion |
| CAGR 2026–2032 | 9.1% |
| Peak Annual Growth | 11.3% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Process Type, 2025 | Wafer Dicing (36% share) |
| Leading Equipment Used, 2025 | Laser/Cutting Tools (44% share) |
| Leading Output Function, 2025 | Wafer Segmentation (41% share) |
| Leading End User, 2025 | Foundries (47% share) |
| Fastest-Growing Process Type | Die Bonding (11.7% CAGR) |
| Fastest-Growing Equipment Used | Bonding Equipment (10.6% CAGR) |
| Fastest-Growing Output Function | Die Placement (11.2% CAGR) |
| Fastest-Growing End User | OSAT Providers (11.9% CAGR) |
| Growing Sector | OSAT Providers |
| Key End Users | Foundries, OSAT Providers, IC Package Assemblers, IDMs |
China Semiconductor Backend Process Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
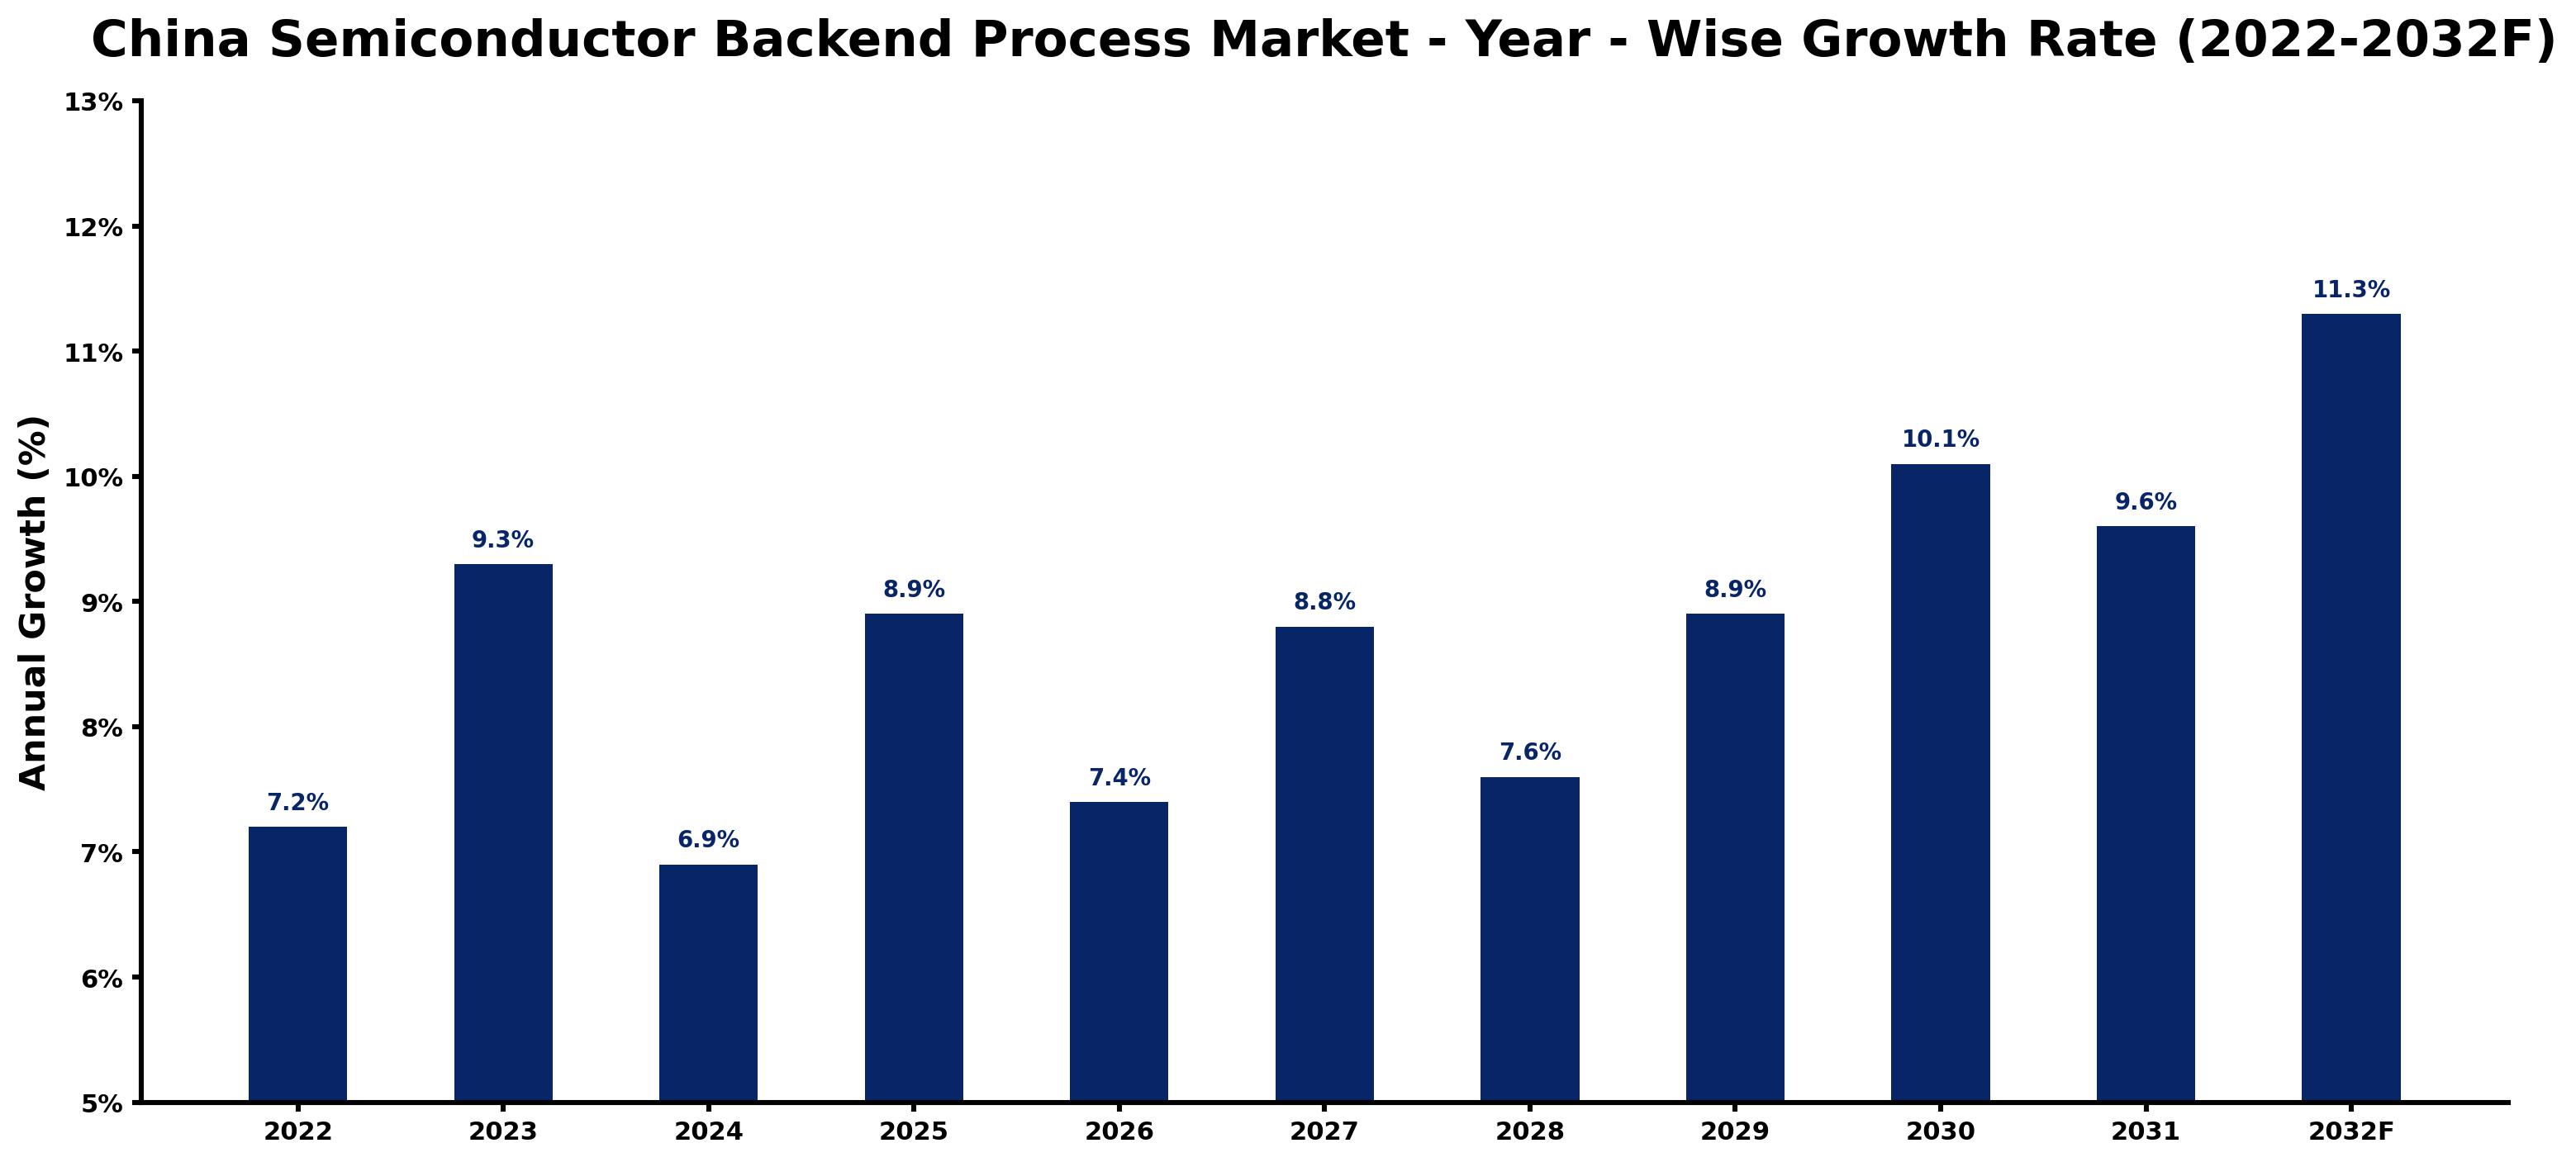
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.2 | The market experienced steady growth due to increasing domestic semiconductor production. |
| 2023 | 9.3 | Growth accelerated as demand surged from over 200 semiconductor foundries in the country. |
| 2024 | 6.9 | The growth rate slowed as some foundries adjusted production capacities. |
| 2025 | 8.9 | Demand increased again as the government pushed for local semiconductor production. |
| 2026 | 7.4 | A slight slowdown occurred as the market began to stabilise after rapid growth. |
| 2027 | 8.8 | Growth picked up again due to rising demand from OSAT providers. |
| 2028 | 7.6 | The market saw a slowdown as production adjustments were made in response to demand. |
| 2029 | 8.9 | Demand surged again as foundries expanded their production capabilities. |
| 2030 | 10.1 | Growth continued as advancements in backend processes were implemented. |
| 2031 | 9.6 | The market experienced a slowdown as it approached stabilisation. |
| 2032 | 11.3 | Growth peaked as the market reached maturity with increased domestic production. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Semiconductor Backend Process Market Synopsis
The Semiconductor Backend Process Market in China includes the final stages of semiconductor manufacturing, such as wafer dicing, die bonding, wire bonding, and encapsulation. This process is crucial for preparing chips for integration into electronic devices. The market is expanding due to robust demand from over 200 semiconductor foundries and government initiatives aimed at enhancing local production. The "Made in China 2025" initiative seeks to raise domestic semiconductor production to 70% by 2025.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising demand from foundries for backend processing capabilities | Driver | High | Foundries |
| Increased government support for semiconductor production | Driver | High | OSAT Providers |
| Emerging opportunities in the Yangtze River Delta for new facilities | Opportunity | High | Wafer Dicing |
| Growing need for advanced packaging solutions in IC production | Opportunity | High | IC Package Assemblers |
| High competition among OSAT providers may limit margins | Restraint | Medium | OSAT Providers |
| Dependence on imported technology for advanced processes | Restraint | Medium | Foundries |
| Challenges in meeting international quality standards | Challenge | High | IC Package Assemblers |
| Shortage of skilled workforce in semiconductor backend processes | Challenge | High | Foundries |
Evaluation of Drivers in China Semiconductor Backend Process Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Strong end-use demand from foundries | Foundries | This demand drives investments in backend processes, with over 200 foundries in China contributing significantly to the market. |
| Government initiatives supporting local production | OSAT Providers | The "Made in China 2025" initiative aims to increase domestic semiconductor production to 70% by 2025, boosting demand for backend services. |
| Investment in semiconductor infrastructure | Bonding Equipment | The 2023 allocation of 100 billion yuan for semiconductor industry support enhances capabilities in backend processes. |
| Emerging manufacturing hubs | Wafer Dicing | This region is attracting substantial investments, increasing the need for advanced backend processing capabilities. |
| Technological advancements in packaging | Die Bonding | Innovations in die bonding processes are improving efficiency and quality, driving demand from IC package assemblers. |
Market growth in China for Semiconductor Backend Process rests on strong end-use demand from foundries and OSAT providers, alongside a responsive supply chain. In 2022, the semiconductor industry was valued at approximately 1 trillion yuan, driving investments in backend processes. Over 50 OSAT companies operating in China are driving demand for advanced packaging solutions. The Yangtze River Delta region is emerging as a key manufacturing hub, attracting substantial investments and increasing the need for backend processing capabilities.
Evaluation of Restraints in China Semiconductor Backend Process Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High competition among OSAT providers | OSAT Providers | This competition can limit profit margins, affecting overall market stability and profitability for providers in a crowded market. |
| Dependence on imported technology for advanced processes | Foundries | This reliance can delay the adoption of new technologies, impacting production efficiency and competitiveness in the global market. |
| Challenges in meeting international quality standards | IC Package Assemblers | Failure to meet these standards can result in reduced export opportunities and market access for assemblers, limiting growth potential. |
| Shortage of skilled workforce in semiconductor backend processes | Foundries | This shortage can hinder production capabilities and slow down growth, limiting operational efficiency across the sector. |
| Regulatory compliance costs for new facilities | Wafer Dicing | High compliance costs can deter investment in new backend processing facilities, affecting market expansion and competitiveness. |
China Semiconductor Backend Process Market Challenges
Buyers in the China Semiconductor Backend Process market face intense competition, as over 200 foundries drive prices down and squeeze margins. This competition stems from a saturated market, where producers often cut costs to attract buyers, leading to quality inconsistencies in the final products. Skills shortages hinder progress, with the workforce of over 1 million lacking specialised training in advanced backend technologies, resulting in project delays for producers. Supply chain disruptions frequently occur due to reliance on specific regions like Guangdong, causing material availability delays that impact buyers' production schedules and lead to increased operational costs.
Trends in the China Semiconductor Backend Process Market
Four trends stand out in the China Semiconductor Backend Process Market.
- Emergence of the Yangtze River Delta as a Semiconductor Hub: The Yangtze River Delta is becoming a key area for semiconductor manufacturing, with over 50 OSAT companies established there. This region is attracting investment, contributing to the growth of backend processes, with production capabilities increasing.
- Adoption of ISO/IEC 17025 Standards: ISO/IEC 17025 standards are widely adopted in semiconductor testing and quality assurance in China. This shift improves the reliability of semiconductor products, supporting export growth and enhancing market competitiveness.
- Increase in Domestic Semiconductor Production: The Chinese government aims to boost domestic semiconductor production to 70% by 2025. This initiative drives investments in backend processing capabilities across the country, fostering local industry growth.
- Growth in Advanced Packaging Solutions: There is a growing need for advanced packaging solutions in integrated circuit production. This trend is supported by the Semiconductor Innovation Action Plan, which promotes R&D in backend processes, enhancing production quality.
Investment Opportunities in the China Semiconductor Backend Process Market
Several openings in the China Semiconductor Backend Process Market merit attention from investors.
- Timing for Investment: With the semiconductor market projected to reach USD 3.66 billion by 2032, there is a significant opportunity for investment in backend processing equipment in the Guangdong province.
- Gap in Advanced Packaging: As the demand for advanced packaging solutions rises, OSAT providers are seeking innovative technologies, creating a gap for suppliers to introduce cutting-edge equipment.
- Supply of Bonding Equipment: The growth of die bonding as a leading process type presents an opportunity to supply bonding equipment to semiconductor manufacturers in Jiangsu province.
- Facility Development in Emerging Regions: The Beijing-Tianjin-Hebei region is emerging as a center for backend services, providing opportunities for investment in new facilities and partnerships.
Government Initiatives in the China Semiconductor Backend Process Market
In 2023, the Ministry of Industry and Information Technology launched the "14th Five-Year Plan for the Semiconductor Industry" to enhance domestic backend processing capabilities. This plan builds on previous initiatives, including the "National Semiconductor Industry Development Plan" from 2020, which aimed to boost local production and reduce reliance on imports. The new plan sets ambitious targets for increasing production capacity and improving technology standards, ensuring that the semiconductor industry remains competitive globally. The government allocated 100 billion yuan for semiconductor industry support in 2023, which will significantly benefit producers and buyers alike.
The National Development and Reform Commission oversees a subsidy program approved in 2022, providing 50 billion yuan to support semiconductor equipment manufacturers. This funding is vital for companies involved in backend processes, enabling them to invest in advanced technologies and improve production efficiency. Additionally, the Ministry of Finance's tax incentive scheme, introduced in 2020, reduces corporate tax rates by 15% for qualifying semiconductor companies, further encouraging investment in the sector. This support allows producers to enhance their capabilities and expand their operations effectively.
Future Insight of the China Semiconductor Backend Process Market
The China Semiconductor Backend Process market will undergo notable changes by 2032, driven by key developments. The government's "Made in China 2025" initiative aims to elevate domestic production capabilities, significantly reducing reliance on foreign technology. Investment in semiconductor infrastructure is set to increase, with 100 billion yuan allocated in 2023 to enhance backend processes. The establishment of the National Integrated Circuit Industry Investment Fund will encourage innovation in backend technologies, while advancements in ISO/IEC 17025 standards will improve quality assurance in testing, benefiting both producers and buyers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Process Type – Wafer Dicing Dominated, Die Bonding Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, the largest process type category in 2025 was Wafer Dicing, with a 36% share of total revenue. Wafer Dicing holds the largest share in the China Semiconductor Backend Process Market because it is essential for cutting wafers into individual chips, a critical step in semiconductor device production. The presence of over 200 semiconductor foundries in China, particularly in Guangdong, drives substantial demand for this process. Die Bonding is set to record the highest CAGR in this split, 11.7% over 2026–2032. Die Bonding is the fastest-growing segment in this market, propelled by the increasing need for efficient chip attachment as production scales up. Government initiatives aimed at boosting local semiconductor production further enhance the importance of die bonding in backend operations. Suppliers should focus on advancing die bonding technologies to capitalise on the growing demand from semiconductor foundries.
By Equipment Used – Laser/Cutting Tools Dominated, Bonding Equipment Expected to Grow Fastest
In 2025, Laser/Cutting Tools led the equipment used split with a 44% share. Laser/Cutting Tools dominate the market share as they are vital for precise wafer dicing, ensuring high-quality production standards in semiconductor manufacturing. Their widespread adoption across China's semiconductor foundries underscores their importance in the backend process. The quickest growth will come from Bonding Equipment, forecast to expand at a CAGR of 10.6% between 2026 and 2032. Bonding Equipment is the fastest-growing segment, primarily due to the rising demand for efficient die attachment solutions in semiconductor packaging. As the industry expands, the need for advanced bonding techniques will continue to increase, driving further investments in this equipment. Buyers should consider investing in advanced bonding equipment to stay competitive in the rapidly evolving semiconductor backend process market.
By Output Function – Wafer Segmentation Dominated, Die Placement Expected to Grow Fastest
With a 41% revenue share in 2025, Wafer Segmentation was the largest output function category. Wafer Segmentation commands the largest share as it is integral to the initial processing steps of semiconductor manufacturing, directly influencing the efficiency of subsequent operations. This foundational role is particularly evident in the Yangtze River Delta, a key area for semiconductor equipment manufacturing. Over 2026–2032, Die Placement is expected to post the fastest growth, at a CAGR of 11.2%. Die Placement is the fastest-growing output function, driven by the need for precise chip placement as production volumes increase. The focus on accuracy in semiconductor manufacturing processes underscores the critical role of die placement in overall production efficiency. Suppliers must innovate in die placement technologies to meet the rising demands of semiconductor manufacturers.
By End User – Foundries Dominated, OSAT Providers Expected to Grow Fastest
Foundries held a 47% share of the China Semiconductor Backend Process Market by end user in 2025. Foundries represent the largest share of the market as they are the primary users of backend processes for chip production, significantly driving demand for all associated services. The concentration of over 200 foundries in China ensures a steady market for backend processes. OSAT Providers are projected to grow fastest, at a CAGR of 11.9% during 2026–2032. OSAT Providers are experiencing the fastest growth, largely due to their essential role in providing packaging services that utilise backend processes. As the semiconductor industry expands, the reliance on OSAT Providers for efficient packaging solutions will continue to increase. Buyers should strengthen partnerships with OSAT Providers to secure access to advanced packaging solutions in the semiconductor market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Semiconductor Backend Process Market Outlook
- Market Size of China Semiconductor Backend Process Market, 2025
- Forecast of China Semiconductor Backend Process Market, 2032
- Historical Data and Forecast of China Semiconductor Backend Process Revenues & Volume for the Period 2022 - 2032F
- China Semiconductor Backend Process Market Trend Evolution
- China Semiconductor Backend Process Market Drivers and Challenges
- China Semiconductor Backend Process Price Trends
- China Semiconductor Backend Process Porter's Five Forces
- China Semiconductor Backend Process Industry Life Cycle
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By Process Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By Wafer Dicing for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By Die Bonding for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By Wire Bonding for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By Encapsulation for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By Equipment Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By Laser/Cutting Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By Bonding Equipment for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By Gold/Aluminum Wires for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By Molding/Sealing Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By Output Function for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By Wafer Segmentation for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By Die Placement for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By Electrical Interconnect for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By Chip Protection for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By Foundries for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By OSAT Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By IC Package Assemblers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Backend Process Market Revenues & Volume By IDMs for the Period 2022 - 2032F
- China Semiconductor Backend Process Import Export Trade Statistics
- Market Opportunity Assessment By Process Type
- Market Opportunity Assessment By Equipment Used
- Market Opportunity Assessment By Output Function
- Market Opportunity Assessment By End User
- China Semiconductor Backend Process Top Companies Market Share
- China Semiconductor Backend Process Competitive Benchmarking By Technical and Operational Parameters
- China Semiconductor Backend Process Company Profiles
- China Semiconductor Backend Process Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Process Type
- Wafer Dicing
- Die Bonding
- Wire Bonding
- Encapsulation
By Equipment Used
- Laser/Cutting Tools
- Bonding Equipment
- Gold/Aluminum Wires
- Molding/Sealing Systems
By Output Function
- Wafer Segmentation
- Die Placement
- Electrical Interconnect
- Chip Protection
By End User
- Foundries
- OSAT Providers
- IC Package Assemblers
- IDMs































