China Semiconductor Cleaning Market Size & Growth Rate
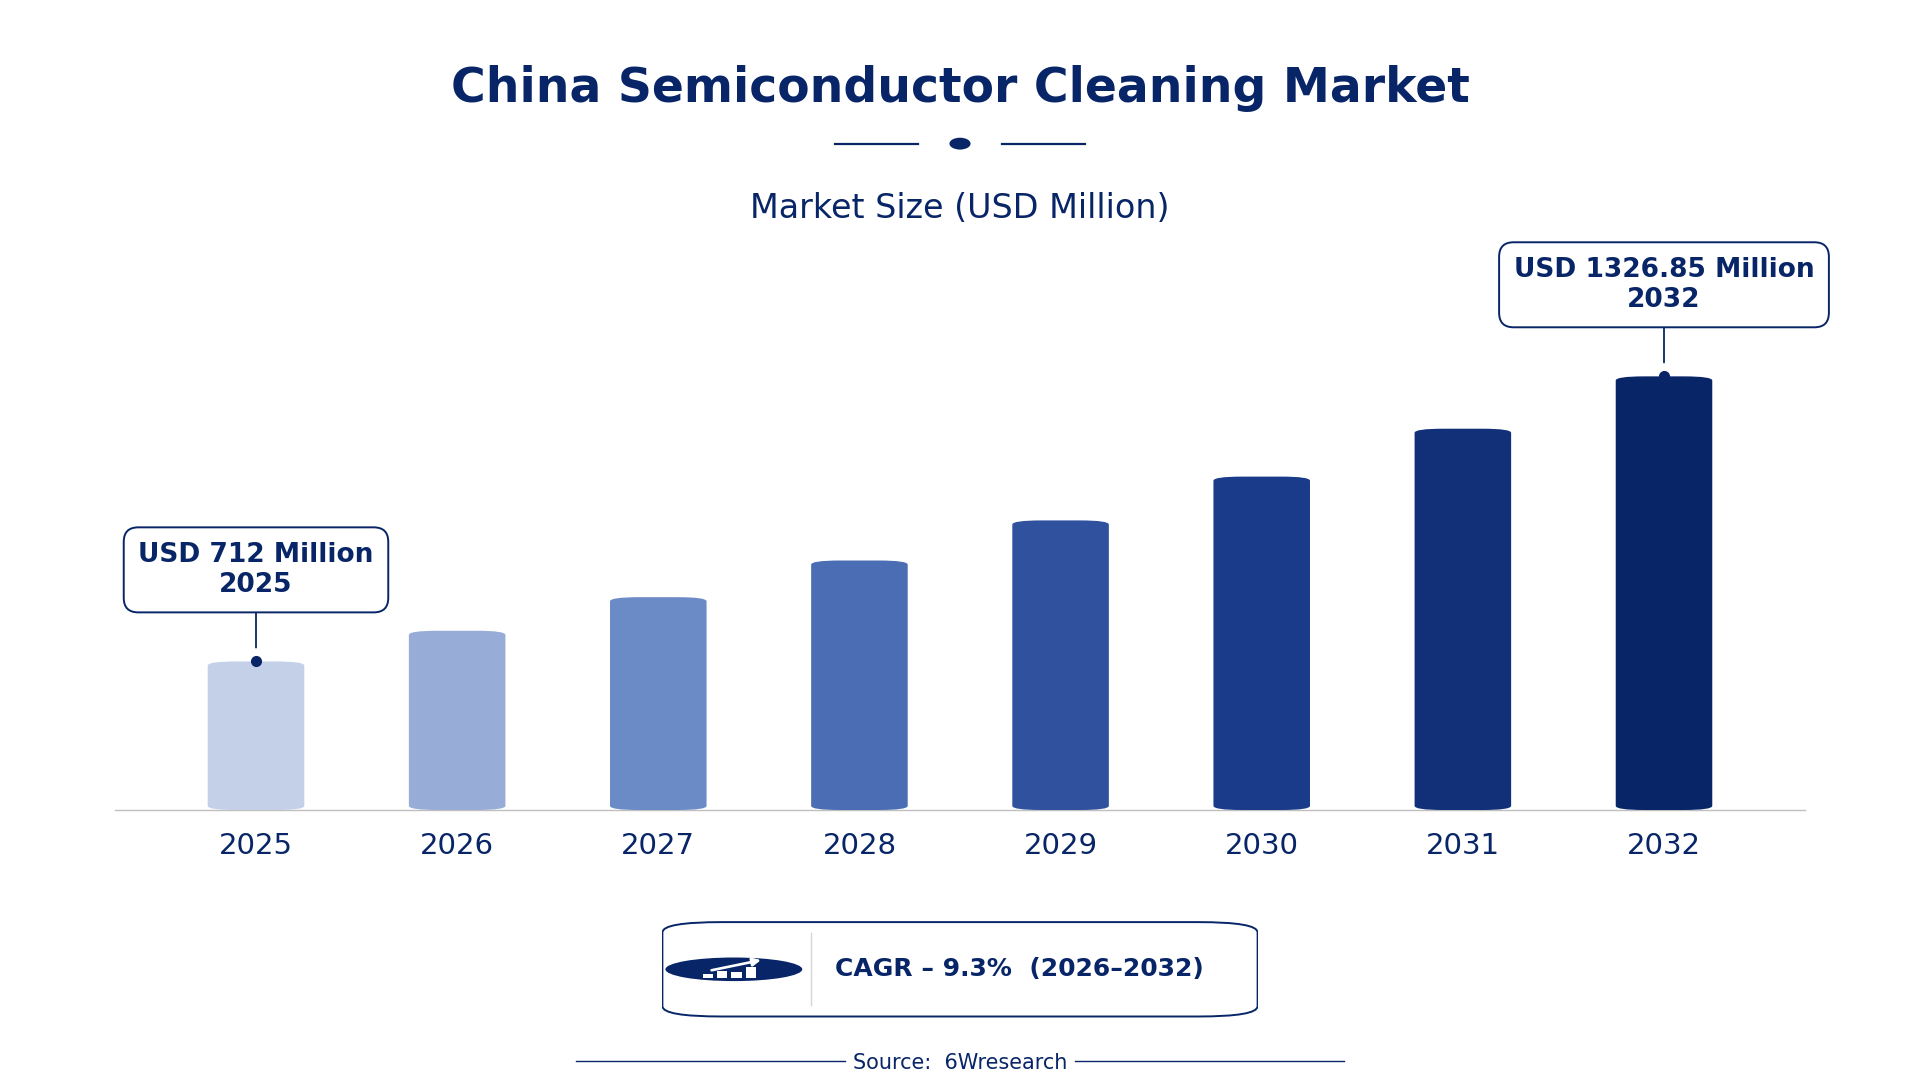
According to 6Wresearch internal database and industry insights, the China Semiconductor Cleaning Market was valued at USD 712.0 million in 2025 and is projected to reach USD 1,326.85 million by 2032, growing at a CAGR of approximately 9.3% during 2026–2032.
China Semiconductor Cleaning Market Highlights
| Report Metric | Details |
| Report Name | China Semiconductor Cleaning Market |
| Market Size 2025 | USD 712.0 million |
| Market Size 2032 | USD 1,326.85 million |
| Absolute Growth 2025–2032 | USD 614.85 million |
| CAGR 2026–2032 | 9.3% |
| Peak Annual Growth | 10.7% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Cleaning Type, 2025 | Wet Cleaning (48% share) |
| Leading Equipment Used, 2025 | Acid/Base Baths (42% share) |
| Leading Process Application, 2025 | Pre-Lithography (44% share) |
| Leading End User, 2025 | Wafer Fabs (51% share) |
| Fastest-Growing Cleaning Type | Plasma Cleaning (11.0% CAGR) |
| Fastest-Growing Equipment Used | Plasma Chambers (10.5% CAGR) |
| Fastest-Growing Process Application | Post-Etch Residue Removal (10.6% CAGR) |
| Fastest-Growing End User | Foundries & OSATs (11.2% CAGR) |
| Growing Sector | Wafer Fabrication |
| Key End Users | Wafer Fabs, IC Packaging Facilities, Foundries & OSATs |
China Semiconductor Cleaning Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
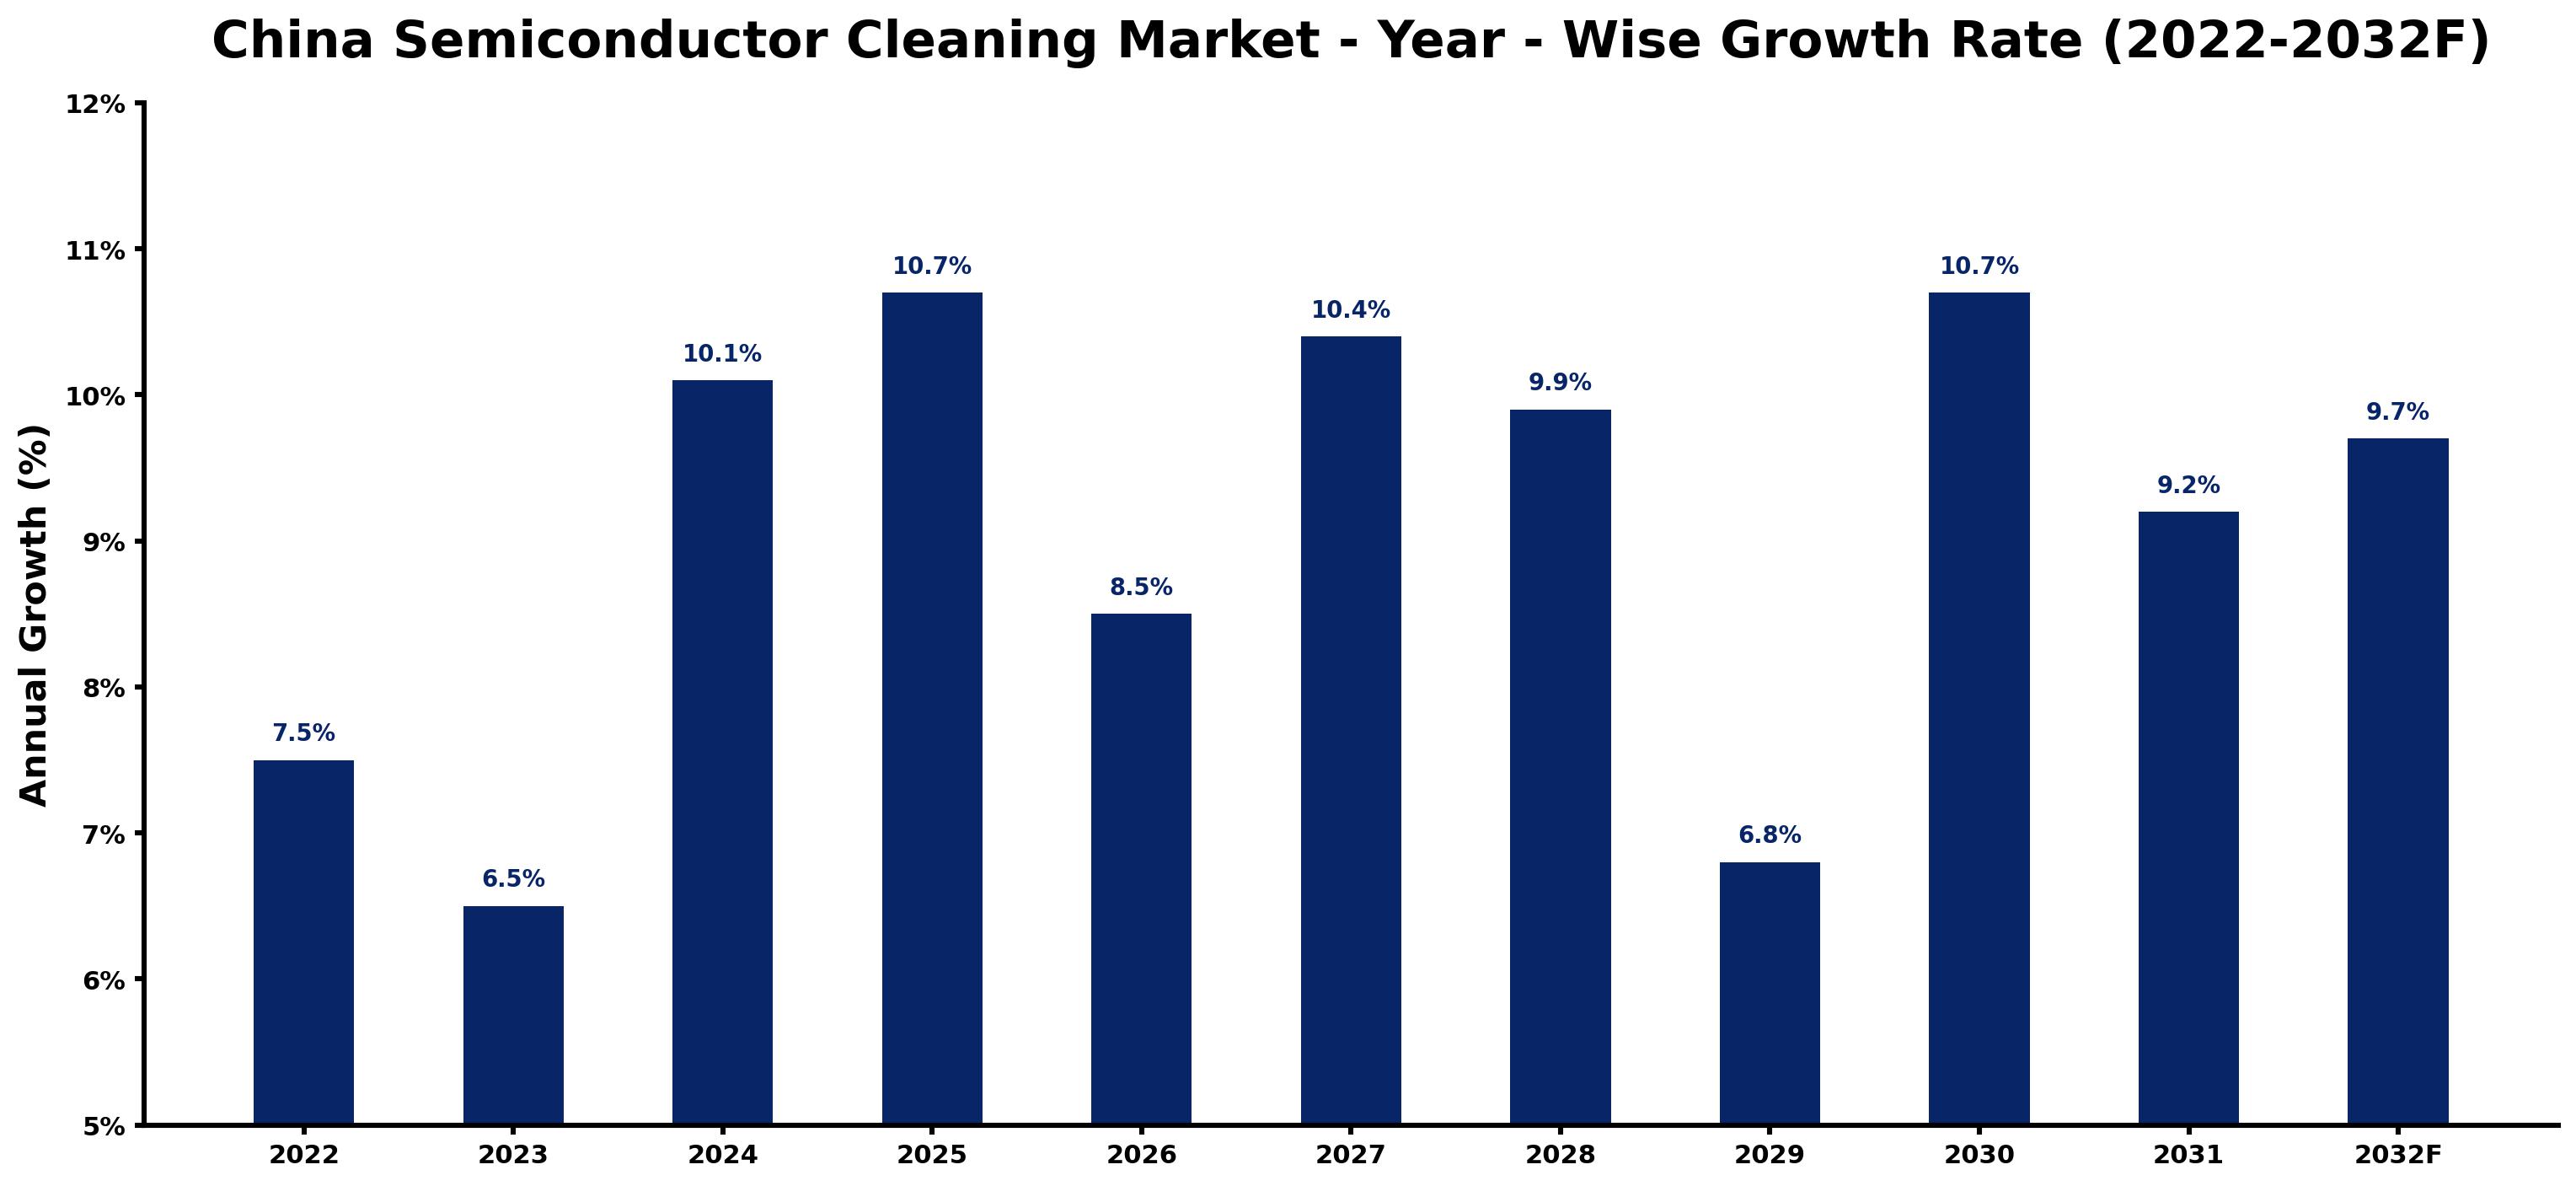
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.5 | The market experienced steady growth due to increasing domestic demand for semiconductor technologies. |
| 2023 | 6.5 | Growth slowed as manufacturers adjusted to the 2021 Semiconductor Industry Development Plan's new cleaning standards. |
| 2024 | 10.1 | An uptick in production capacity led to faster growth as cleaning solutions became essential for wafer fabrication. |
| 2025 | 10.7 | The market peaked as major investments in semiconductor facilities boosted cleaning demand. |
| 2026 | 8.5 | Growth slowed as manufacturers faced challenges in sourcing advanced cleaning technologies outlined in the 2022 National Semiconductor Technology Roadmap. |
| 2027 | 10.4 | Increased demand from foundries drove a resurgence in cleaning process investments as production expanded. |
| 2028 | 9.9 | A slight slowdown occurred as market adjustments took place in response to the 2023 Cleanroom Standards Revision. |
| 2029 | 6.8 | Growth slowed as manufacturers focused on optimizing existing cleaning processes to meet higher standards. |
| 2030 | 10.7 | A rapid increase in demand occurred as new technologies were adopted in cleaning processes, enhancing efficiency. |
| 2031 | 9.2 | Growth slowed as the market began to stabilise after a period of rapid expansion driven by investment. |
| 2032 | 9.7 | The market is expected to grow steadily as investments in cleaning technologies continue to rise. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Semiconductor Cleaning Market Synopsis
Semiconductor Cleaning in China involves removing contaminants from surfaces to ensure optimal performance. This is achieved through methods like wet and plasma cleaning, which are essential in wafer fabrication and IC packaging. The China Semiconductor Cleaning Market is expanding due to rising domestic demand and investments in advanced cleaning technologies. In 2023, there was a reported 15% increase in domestic demand for cleaning solutions, driven by the need for higher cleanliness standards in semiconductor manufacturing. The ongoing development of the semiconductor industry further supports this growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing domestic demand for cleaning solutions in semiconductor production. | Driver | High | Wet Cleaning |
| Investment in advanced cleaning technologies by manufacturers. | Driver | High | Plasma Cleaning |
| Growing need for high cleanliness standards in wafer fabrication facilities. | Opportunity | High | IC Packaging Facilities |
| Emerging demand for sustainable cleaning processes in semiconductor manufacturing. | Opportunity | Medium | Foundries & OSATs |
| Challenges in sourcing advanced cleaning technologies. | Restraint | High | Acid/Base Baths |
| High costs associated with implementing new cleaning standards. | Restraint | Medium | Plasma Chambers |
| Buyers face delays in acquiring advanced cleaning equipment. | Challenge | High | Wafer Fabs |
| Suppliers struggle with competition in the cleaning technology market. | Challenge | Medium | MEMS Manufacturers |
Evaluation of Drivers in China Semiconductor Cleaning Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising demand for semiconductor production drives the need for effective cleaning solutions. | Wet Cleaning | In 2023, domestic demand for cleaning solutions increased by 15%, prompting manufacturers to enhance cleaning processes. |
| Investments in advanced cleaning technologies boost production efficiency. | Plasma Cleaning | The National Integrated Circuit Industry Investment Fund allocated $20 billion to improve cleaning technologies. |
| The emphasis on cleanliness in semiconductor manufacturing increases cleaning process adoption. | IC Packaging Facilities | The 2021 Semiconductor Industry Development Plan aims to enhance cleaning standards, leading to higher demand. |
| The growth of wafer fabrication facilities necessitates improved cleaning solutions. | Foundries & OSATs | China has over 200 wafer fabs, primarily located in Jiangsu and Guangdong provinces. |
| Technological advancements in cleaning methods create new market opportunities. | Acid/Base Baths | The 2022 National Semiconductor Technology Roadmap highlights the importance of advanced cleaning technologies. |
Growth in the Semiconductor Cleaning market in China comes from increased investment in semiconductor production, which drives the need for effective cleaning solutions. In 2023, domestic demand for cleaning solutions increased by 15%, prompting manufacturers to improve cleaning processes. Investments in advanced cleaning technologies boost production efficiency, with the National Integrated Circuit Industry Investment Fund allocating $20 billion to support cleaning technologies. The emphasis on cleanliness in semiconductor manufacturing increases cleaning process adoption, as the 2021 Semiconductor Industry Development Plan aims to improve cleaning standards. The growth of wafer fabrication facilities necessitates improved cleaning solutions, with over 200 wafer fabs concentrated in Jiangsu and Guangdong provinces.
Evaluation of Restraints in China Semiconductor Cleaning Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Challenges in sourcing advanced cleaning technologies hinder market growth. | Wet Cleaning | Manufacturers face difficulties in acquiring state-of-the-art cleaning equipment, delaying production timelines by several months. |
| High costs associated with implementing new cleaning standards limit adoption. | Plasma Cleaning | The financial burden of upgrading equipment to meet standards affects smaller manufacturers' capabilities, restricting market entry. |
| Limited awareness of advanced cleaning methods restricts market expansion. | IC Packaging Facilities | Many facilities are slow to adopt new technologies, affecting overall cleaning efficiency and production quality. |
| Supply chain disruptions impact the availability of cleaning materials. | Foundries & OSATs | Recent global supply chain issues have delayed the procurement of essential cleaning supplies, increasing operational costs. |
| Regulatory compliance challenges create barriers for new entrants. | Acid/Base Baths | Stringent regulations make it difficult for new suppliers to enter the market, limiting competition. |
China Semiconductor Cleaning Market Challenges
Buyers in the China Semiconductor Cleaning market encounter outdated technology, as many processes do not align with the latest cleanliness standards. This issue arises from a lack of investment in modern solutions, causing semiconductor manufacturers to face production delays of up to four weeks. Suppliers must navigate complex regulatory requirements, as compliance with ISO 14644 standards demands costly upgrades to cleanroom environments, often taking six months to implement. Buyers also experience increased costs, with a 15% rise in domestic demand for cleaning solutions in 2023, forcing them to allocate more budget towards essential cleaning processes.
Trends in the China Semiconductor Cleaning Market
Several trends are reshaping the China Semiconductor Cleaning Market; the most important are set out below.
- Shift from Traditional to Advanced Cleaning Methods: Wafer fabs are increasingly adopting advanced cleaning technologies, such as plasma cleaning, to improve efficiency. In 2023, the Ministry of Industry and Information Technology launched a program to enhance cleaning processes, reflecting a notable rise in demand.
- Transition from Manual to Automated Cleaning Processes: The semiconductor industry is transitioning towards automated cleaning solutions to improve consistency and reduce human error. The 2022 National Semiconductor Technology Roadmap highlights this shift, projecting an increase in automation adoption by 2025.
- Emergence of Sustainable Cleaning Solutions: Manufacturers are prioritising eco-friendly cleaning methods to comply with regulations and meet consumer expectations. The National Development and Reform Commission's initiatives support sustainable practices, aiming for a reduction in chemical usage by 2025.
- Growing Demand for Cleaning in IC Packaging: IC packaging facilities are increasingly focusing on cleaning technologies to enhance product quality. With over 200 facilities in Jiangsu, demand for advanced cleaning solutions is expected to rise significantly, with growth projected by 2025.
Investment Opportunities in the China Semiconductor Cleaning Market
Below are the investment opportunities with the strongest case in the China Semiconductor Cleaning Market.
- Current Demand for Advanced Cleaning Technologies: Now is an ideal time to invest in advanced cleaning technologies, as the market is projected to reach USD 712 million by 2025. Wafer fabs are seeking solutions to improve cleaning efficiency, creating opportunities for new suppliers.
- Investment in Sustainable Cleaning Solutions: With a growing emphasis on sustainability, suppliers can invest in eco-friendly cleaning technologies. The National Development and Reform Commission's initiatives aim for a reduction in chemical usage, presenting opportunities for new products.
- Expansion of Wafer Fabrication Facilities: The increasing number of wafer fabs in China, with over 200 located in Jiangsu, presents a significant opportunity for suppliers of cleaning solutions. Collaborating with local manufacturers can facilitate market entry and strengthen supply chains.
- Adoption of Automated Cleaning Systems: The shift towards automation in cleaning processes offers a timely opportunity for investment. The 2022 National Semiconductor Technology Roadmap underscores the need for automated solutions, encouraging partnerships with technology providers.
Government Initiatives in the China Semiconductor Cleaning Market
The 2023 Cleanroom Standards Revision by the Standardization Administration of China updates cleanliness requirements for semiconductor manufacturing environments. This measure builds on previous regulations, specifically the 2021 Semiconductor Industry Development Plan, which aimed to improve cleaning standards. The updated standards require manufacturers to meet higher cleanliness levels, which are vital for maintaining product quality in semiconductor production. Compliance with these standards will necessitate investment in advanced cleaning technologies and processes, driving market growth.
In 2020, the National Integrated Circuit Industry Investment Fund was established with a budget of $20 billion to support semiconductor cleaning technologies. The Ministry of Industry and Information Technology oversees this fund, which aims to improve cleaning processes in semiconductor fabs. The fund provides financial assistance for projects focused on increasing cleaning efficiency and standards. This support is projected to accelerate the adoption of advanced cleaning technologies across the industry.
Future Insight of the China Semiconductor Cleaning Market
The China Semiconductor Cleaning market is set to evolve significantly by 2032, driven by advancements in cleaning technologies and supportive regulatory frameworks. The 2023 initiative from the Ministry of Industry and Information Technology will introduce new cleaning solutions that enhance operational efficiency. The National Semiconductor Technology Roadmap will encourage the adoption of advanced cleaning methods, improving production quality. By 2025, initiatives from the National Development and Reform Commission will promote sustainable practices, positively impacting both buyers and suppliers in the semiconductor industry.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Cleaning Type – Wet Cleaning Dominated, Plasma Cleaning Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, Wet Cleaning held a 48% share of the China Semiconductor Cleaning Market by cleaning type in 2025. Wet cleaning holds the largest share in the China Semiconductor Cleaning Market due to its critical role in removing contaminants from wafers. Its widespread application across over 200 wafer fabs in Jiangsu and Guangdong provinces highlights its necessity in semiconductor manufacturing processes. Over 2026–2032, Plasma Cleaning is expected to post the fastest growth, at a CAGR of 11.0%. Plasma cleaning is rapidly gaining traction, driven by its efficiency in surface treatment and contamination removal, as emphasised by the 2022 National Semiconductor Technology Roadmap. This focus on advanced cleaning technologies positions plasma cleaning for continued growth in the market. Suppliers should invest in plasma cleaning advancements to meet the increasing demand from semiconductor manufacturers.
By Equipment Used – Acid/Base Baths Dominated, Plasma Chambers Expected to Grow Fastest
Acid/Base Baths accounted for a 42% market share by equipment used in 2025. Acid/base baths hold the largest market share in the China Semiconductor Cleaning Market due to their widespread application in cleaning and etching processes essential for semiconductor fabrication. Their extensive use across over 200 wafer fabs, particularly in Jiangsu and Guangdong provinces, highlights their critical role in maintaining cleanliness standards. Plasma Chambers are projected to grow fastest, at a CAGR of 10.5% during 2026–2032. Plasma chambers are experiencing the fastest growth, attributed to their essential role in plasma cleaning and surface modification, which is increasingly demanded as semiconductor technologies advance. The Ministry of Industry and Information Technology's recent programme to enhance cleaning technologies further fuels this segment's rapid expansion. Suppliers should invest in plasma chamber technologies to meet the increasing demand for advanced cleaning solutions in semiconductor manufacturing.
By Process Application – Pre-Lithography Dominated, Post-Etch Residue Removal Expected to Grow Fastest
The largest process application category in 2025 was Pre-Lithography, with a 44% share of total revenue. Pre-lithography processes dominate the market share as they are essential for ensuring clean surfaces before lithography, a pivotal step in semiconductor manufacturing. This importance is evident in the operational practices of wafer fabs, which prioritise cleanliness to achieve optimal results. The quickest growth will come from Post-Etch Residue Removal, forecast to expand at a CAGR of 10.6% between 2026 and 2032. Post-etch residue removal is the fastest-growing application, driven by the critical need to remove residues after etching, which is vital for maintaining high product quality. The growing focus on quality control in semiconductor production is propelling this segment's rapid growth. Suppliers should concentrate on developing efficient solutions for post-etch residue removal to address the increasing quality demands of semiconductor manufacturers.
By End User – Wafer Fabs Dominated, Foundries & OSATs Expected to Grow Fastest
With a 51% revenue share in 2025, Wafer Fabs was the largest end user category. Wafer fabs represent the largest share in the China Semiconductor Cleaning Market as they are the primary users of cleaning technologies in semiconductor production. Their extensive operations across the country necessitate high standards of cleanliness, solidifying their market position. Foundries & OSATs are set to record the highest CAGR in this split, 11.2% over 2026–2032. Foundries and OSATs are the fastest-growing end users, driven by their need for high cleanliness standards to meet increasing domestic demand for cleaning solutions. This trend is supported by the 15% increase in demand reported by the Semiconductor Industry Association of China in 2023. Suppliers must tailor their offerings to meet the specific cleanliness requirements of foundries and OSATs to capitalise on this growth opportunity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Semiconductor Cleaning Market Outlook
- Market Size of China Semiconductor Cleaning Market, 2025
- Forecast of China Semiconductor Cleaning Market, 2032
- Historical Data and Forecast of China Semiconductor Cleaning Revenues & Volume for the Period 2022 - 2032F
- China Semiconductor Cleaning Market Trend Evolution
- China Semiconductor Cleaning Market Drivers and Challenges
- China Semiconductor Cleaning Price Trends
- China Semiconductor Cleaning Porter's Five Forces
- China Semiconductor Cleaning Industry Life Cycle
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By Cleaning Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By Wet Cleaning for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By Plasma Cleaning for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By Vapor Cleaning for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By Cryogenic Cleaning for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By Equipment Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By Acid/Base Baths for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By Plasma Chambers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By Solvent-Based Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By CO Ice Blast for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By Process Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By Pre-Lithography for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By Post-Etch Residue Removal for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By Substrate Pre-Bonding for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By Sensitive Surface Cleaning for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By Wafer Fabs for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By IC Packaging Facilities for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By MEMS Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Cleaning Market Revenues & Volume By Foundries & OSATs for the Period 2022 - 2032F
- China Semiconductor Cleaning Import Export Trade Statistics
- Market Opportunity Assessment By Cleaning Type
- Market Opportunity Assessment By Equipment Used
- Market Opportunity Assessment By Process Application
- Market Opportunity Assessment By End User
- China Semiconductor Cleaning Top Companies Market Share
- China Semiconductor Cleaning Competitive Benchmarking By Technical and Operational Parameters
- China Semiconductor Cleaning Company Profiles
- China Semiconductor Cleaning Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Cleaning Type
- Wet Cleaning
- Plasma Cleaning
- Vapor Cleaning
- Cryogenic Cleaning
By Equipment Used
- Acid/Base Baths
- Plasma Chambers
- Solvent-Based Systems
- CO₂ Ice Blast
By Process Application
- Pre-Lithography
- Post-Etch Residue Removal
- Substrate Pre-Bonding
- Sensitive Surface Cleaning
By End User
- Wafer Fabs
- IC Packaging Facilities
- MEMS Manufacturers
- Foundries & OSATs































