China Semiconductor Fabrication Equipment Market Size & Growth Rate
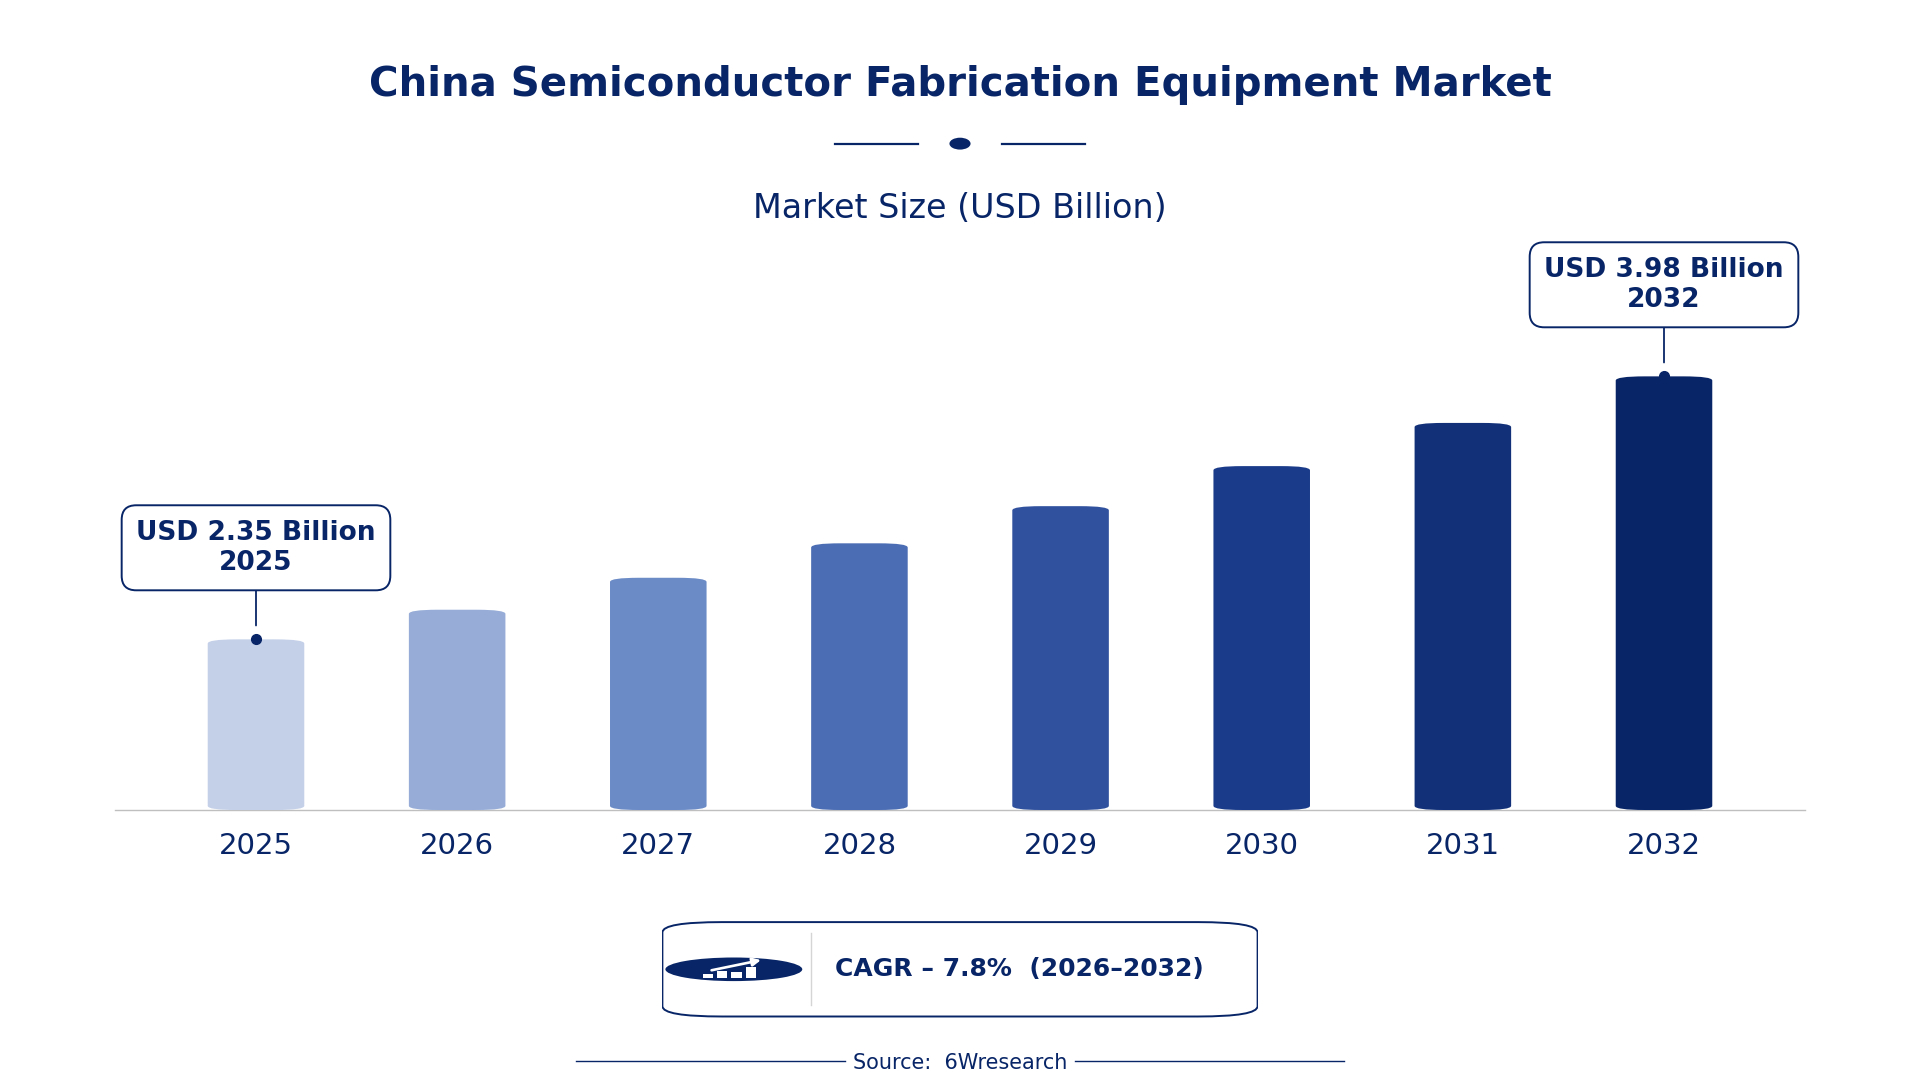
According to 6Wresearch internal database and industry insights, the China Semiconductor Fabrication Equipment Market was valued at USD 2.35 billion in 2025 and is projected to reach USD 3.98 billion by 2032, growing at a CAGR of approximately 7.8% during 2026–2032.
China Semiconductor Fabrication Equipment Market Highlights
| Report Metric | Details |
| Report Name | China Semiconductor Fabrication Equipment Market |
| Market Size 2025 | USD 2.35 billion |
| Market Size 2032 | USD 3.98 billion |
| Absolute Growth 2025–2032 | USD 1.63 billion |
| CAGR 2026–2032 | 7.8% |
| Peak Annual Growth | 10.3% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Equipment Type, 2025 | Lithography Systems (52% share) |
| Leading Process Step, 2025 | Pattern Transfer (38% share) |
| Leading Automation Level, 2025 | Fully Automated (37% share) |
| Leading End User, 2025 | Foundries (41% share) |
| Fastest-Growing Equipment Type | Metrology Tools (10.4% CAGR) |
| Fastest-Growing Process Step | Defect Inspection (9.6% CAGR) |
| Fastest-Growing End User | Chip Fabricators (10.6% CAGR) |
| Growing Sector | semiconductor foundries |
| Key End Users | foundries, IDM players, chip fabricators, equipment integrators |
China Semiconductor Fabrication Equipment Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
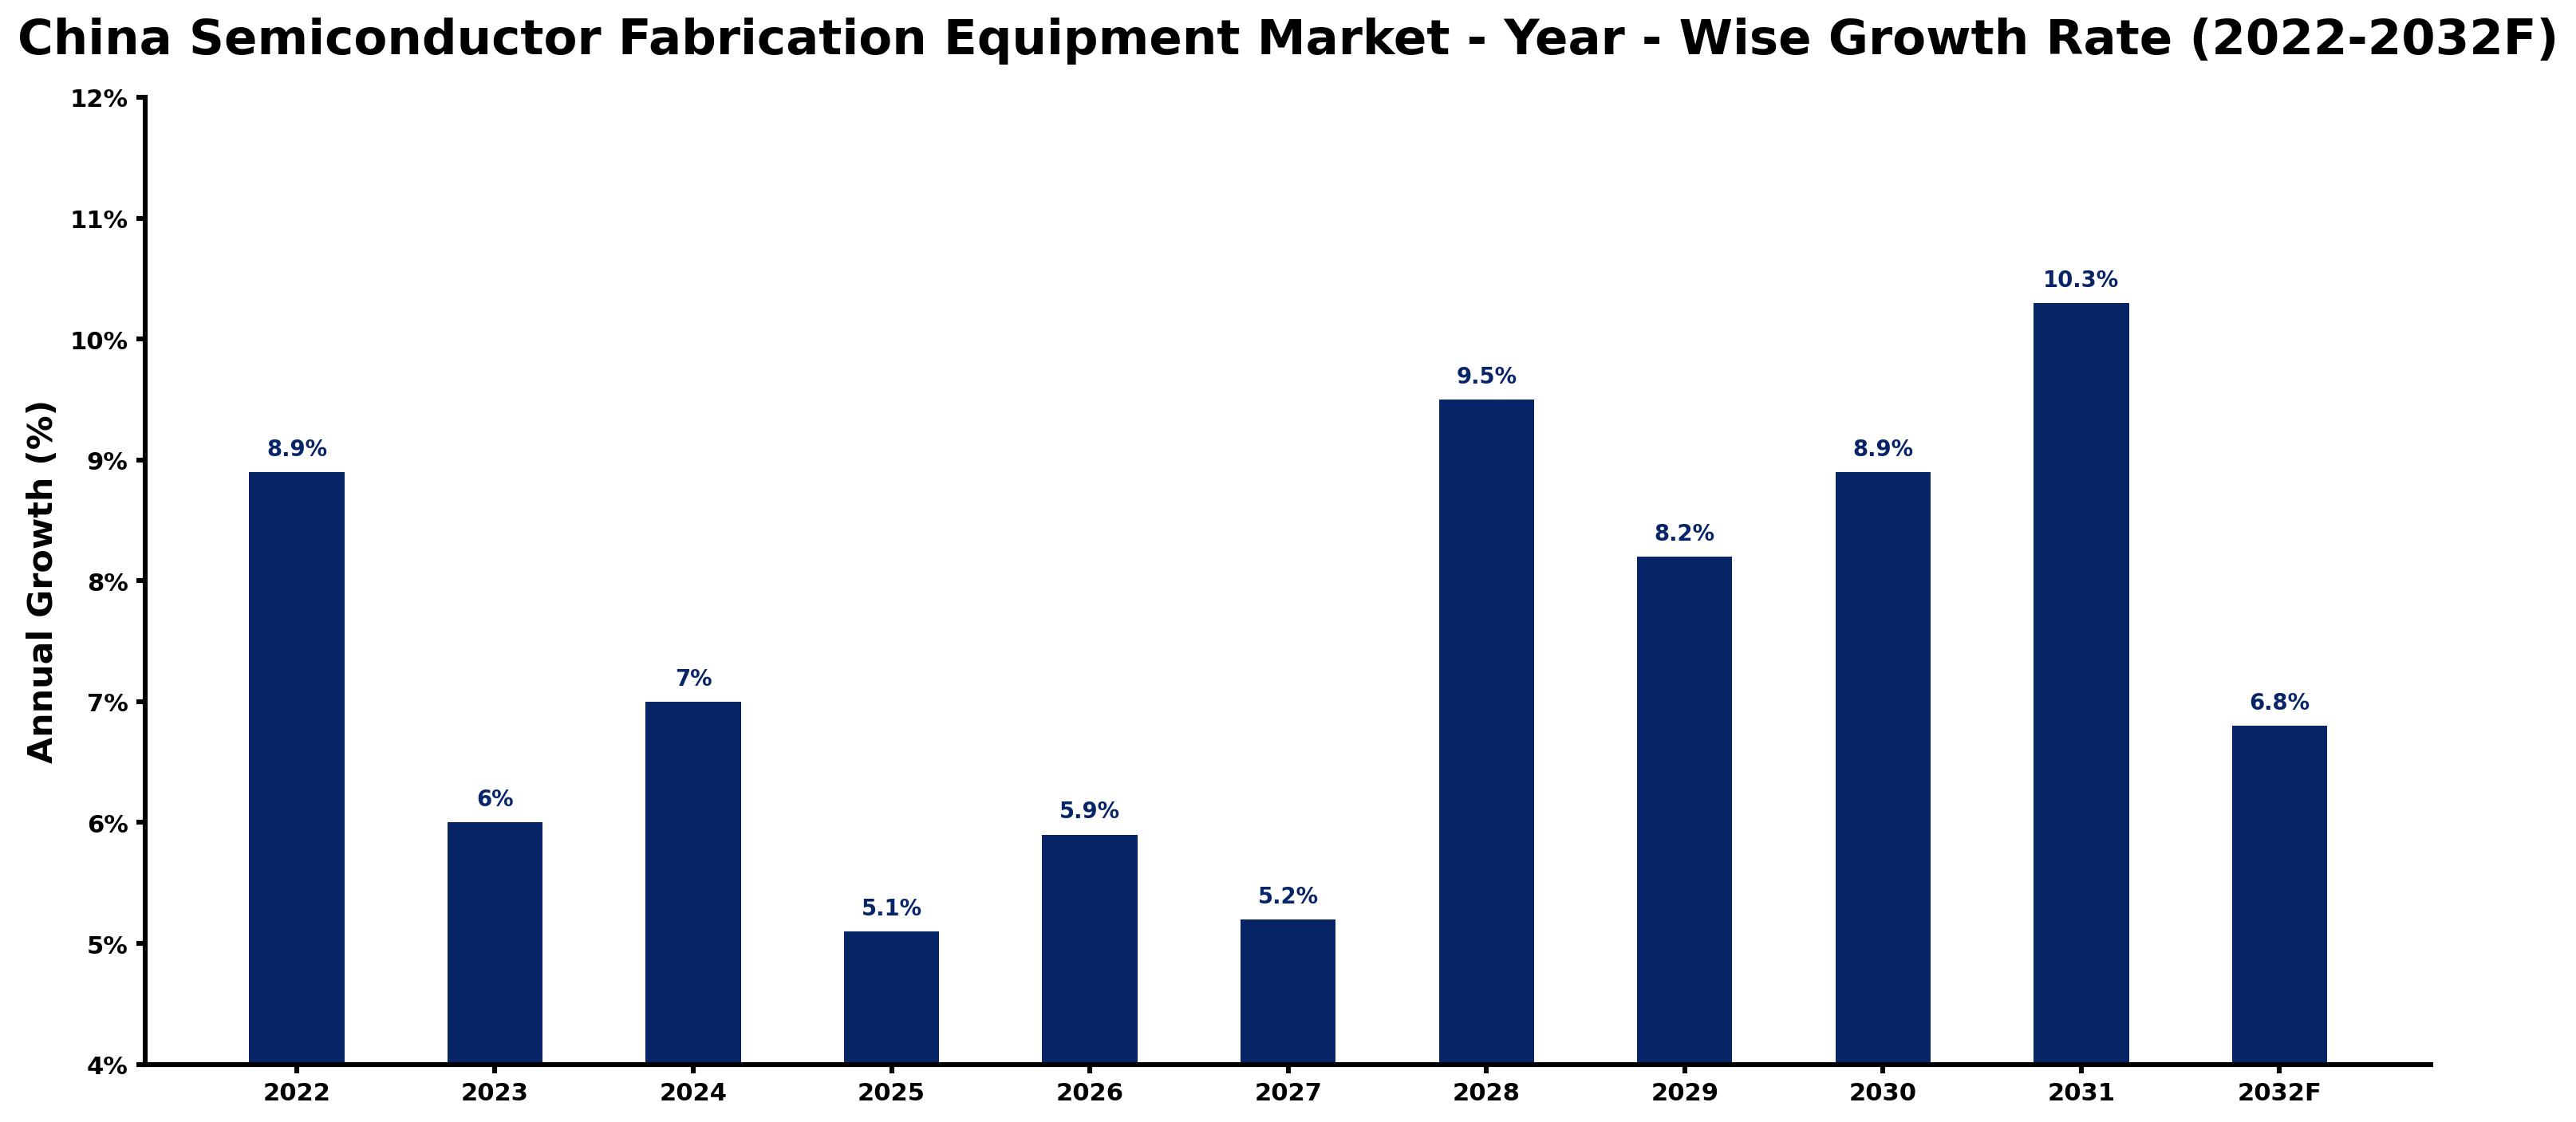
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 8.9 | The market experienced strong activity due to high domestic demand from semiconductor foundries. |
| 2023 | 6.0 | Growth slowed as the market adjusted to new investment strategies and technology developments. |
| 2024 | 7.0 | Increased demand for advanced manufacturing processes contributed to a faster growth rate. |
| 2025 | 5.1 | Growth slowed again as the market faced challenges in scaling production capacity. |
| 2026 | 5.9 | Demand is expected to rise as investments in semiconductor R&D begin to materialise. |
| 2027 | 5.2 | Growth is projected to slow as market saturation sets in for certain equipment types. |
| 2028 | 9.5 | A surge in demand for new technologies is anticipated to drive growth significantly. |
| 2029 | 8.2 | Growth is expected to moderate as the market stabilises after rapid expansion. |
| 2030 | 8.9 | Increased investments in semiconductor infrastructure will support a faster growth rate. |
| 2031 | 10.3 | The market is projected to peak due to heightened demand for advanced fabrication technologies. |
| 2032 | 6.8 | Growth is expected to slow as the market reaches a more mature phase. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Semiconductor Fabrication Equipment Market Synopsis
Semiconductor Fabrication Equipment Market in China includes tools crucial for the production of semiconductor devices, such as lithography systems and deposition equipment. The market benefits from robust domestic output, with over 1.3 billion semiconductor units manufactured in 2022. The 'National Semiconductor Innovation Strategy' introduced in 2023 seeks to strengthen local capabilities and stimulate further investments. Furthermore, the semiconductor workforce exceeds 1 million professionals, reflecting a strong talent pool. These elements contribute to the market's growth and shifting demand patterns.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| High domestic production of semiconductor units drives demand for fabrication equipment. | Driver | High | Foundries |
| Investment in advanced semiconductor technologies creates opportunities for equipment suppliers. | Driver | High | Metrology Tools |
| Foundries are increasingly investing in automation to enhance production efficiency. | Opportunity | High | Fully Automated |
| The ongoing semiconductor workforce development programme creates demand for advanced equipment. | Opportunity | High | Pattern Transfer |
| Challenges in scaling production capacity may limit market growth. | Restraint | High | Etching Equipment |
| International competition may hinder local manufacturers' market share. | Restraint | Medium | Deposition Equipment |
| The Semiconductor Fabrication Equipment market in China faces high production costs. | Challenge | High | Metrology Tools |
| Technological advancements require continuous investment, posing a challenge for smaller players. | Challenge | Medium | Lithography Systems |
Evaluation of Drivers in China Semiconductor Fabrication Equipment Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| High domestic production of semiconductor units | Foundries | In 2022, China produced over 1.3 billion semiconductor units, increasing demand for fabrication equipment. |
| Investment in advanced semiconductor technologies | Metrology Tools | The Shanghai Integrated Circuit Research Institute focuses on advanced technologies, boosting demand for metrology tools. |
| Growing demand for automation in production processes | Fully Automated | With a projected 37% share in 2025, fully automated systems improve efficiency and reduce errors. |
| Increased focus on quality assurance in semiconductor manufacturing | Defect Inspection | The need for high-quality standards drives demand for defect inspection tools in production. |
| Expansion of semiconductor foundries in key regions | Pattern Transfer | The Beijing-Tianjin-Hebei region is a major hub, increasing the need for pattern transfer equipment. |
Expansion of the Semiconductor Fabrication Equipment market in China is driven by increasing end-use demand from foundries and ongoing investments in technology development. In 2023, the State Council announced a $30 billion investment in semiconductor R&D, which heightens the need for advanced fabrication tools. The emphasis on quality assurance in semiconductor manufacturing is boosting demand for defect inspection tools, as manufacturers aim to meet rigorous standards. The projected 37% share of fully automated systems by 2025 underscores the move towards automation in production processes. With the semiconductor workforce surpassing 1 million professionals, the need for skilled labour further propels market growth.
Evaluation of Restraints in China Semiconductor Fabrication Equipment Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High production costs limit the ability of manufacturers to scale operations. | Metrology Tools | Rising costs in raw materials and labour impact the profitability of metrology tool production. |
| International competition may hinder local manufacturers' market share. | Deposition Equipment | Local manufacturers face challenges from established global players, affecting their market position. |
| Challenges in scaling production capacity may limit market growth. | Etching Equipment | As demand increases, existing facilities may struggle to meet production targets. |
| Technological advancements require continuous investment, posing a challenge for smaller players. | Lithography Systems | Smaller manufacturers may find it difficult to keep up with rapid technological changes. |
| Regulatory compliance can increase operational costs for producers. | Pattern Transfer | Adhering to international standards such as ISO 9001 raises production costs for local manufacturers. |
China Semiconductor Fabrication Equipment Market Challenges
In the China Semiconductor Fabrication Equipment Market, rising costs of raw materials pose a critical challenge, with prices increasing by 15% over the past year, which raises production expenses for foundries. Local manufacturers encounter technological barriers, as many struggle to adopt advanced processes, delaying product development timelines for buyers and impacting their competitiveness. Buyers also face fluctuating demand, leading to excess inventory that can cost them up to 20% in unsold stock. A persistent skills gap exists, with over 1 million professionals needed, limiting production efficiency and reducing output for semiconductor manufacturers.
Trends in the China Semiconductor Fabrication Equipment Market
Below mentioned are some of the trends shaping the China Semiconductor Fabrication Equipment Market growth.
- National Semiconductor Innovation Strategy Launched: In 2023, the Ministry of Industry and Information Technology initiated the 'National Semiconductor Innovation Strategy', aiming to boost local capabilities. This strategy is set to lead to increased investments in semiconductor fabrication equipment, focusing on innovation.
- Foundries Increasing Automation: Foundries are increasingly adopting fully automated systems to improve production efficiency. This shift is reflected in a projected 37% share in 2025, indicating a strong trend towards automation in semiconductor manufacturing.
- Demand for Advanced Defect Inspection Tools Rising: As quality assurance becomes paramount in semiconductor production, demand for advanced defect inspection tools is increasing. This trend reflects the industry's commitment to maintaining high standards in manufacturing processes.
- Shift Towards Self-Sufficiency in Semiconductor Production: The updated 'Made in China 2025' initiative in 2023 emphasises self-sufficiency in semiconductor technology. This shift aims for 70% domestic production by 2025, driving demand for local fabrication equipment.
Investment Opportunities in the China Semiconductor Fabrication Equipment Market
Below are the investment opportunities with the strongest case in the China Semiconductor Fabrication Equipment Market.
- Foundries Seeking Advanced Equipment: Foundries in China are currently investing in advanced fabrication equipment to improve production capabilities. With over 200 operational foundries, the demand for new technologies is estimated to reach $30 billion in R&D investments.
- Timing for Investment in Automation: Now is an ideal time for suppliers to invest in automation technologies, given the projected growth in the fully automated segment. The focus on efficiency and quality is driving demand for these systems.
- Gap in Advanced Metrology Tools: There is a growing gap in the availability of advanced metrology tools, with demand expected to rise. Suppliers can enter this market by partnering with local manufacturers to meet the needs of foundries.
- Entry into Semiconductor Equipment Market: Local partners can facilitate entry into the semiconductor equipment market, especially in regions like Guangdong. Collaborating with established manufacturers can streamline the approval process and improve market access.
Government Initiatives in the China Semiconductor Fabrication Equipment Market
The '14th Five-Year Plan for the Development of the Integrated Circuit Industry', approved in 2021, targets a 20% annual growth in the semiconductor sector. This plan outlines specific strategies to improve domestic production capabilities and encourage innovation within the industry. Additionally, the 'National Semiconductor Industry Development Fund' launched in 2022, with a budget of $50 billion, aims to support local manufacturers in upgrading their technology and expanding production capacities. These measures create a favourable environment for semiconductor fabrication equipment producers and buyers, promoting growth and investment in the sector.
The 'Semiconductor Equipment Subsidy Program', introduced by the National Development and Reform Commission in 2022, incentivises local production of fabrication equipment. This program provides financial support to manufacturers, enabling them to invest in advanced technologies and improve their competitiveness. The 'Semiconductor Talent Development Program', initiated by the Ministry of Science and Technology in 2023, aims to train 100,000 professionals by 2025, ensuring a skilled workforce for the semiconductor industry. These initiatives are essential for improving the capabilities of local manufacturers and meeting the rising demand for semiconductor fabrication equipment.
Future Insight of the China Semiconductor Fabrication Equipment Market
Several forward-looking factors should support the China Semiconductor Fabrication Equipment Market over the coming years. The National Semiconductor Innovation Strategy will drive investment in advanced technologies, improving manufacturing capabilities. The anticipated $30 billion investment in semiconductor R&D will stimulate innovation and elevate production processes. The Shanghai Integrated Circuit Research Institute is set to develop next-generation tools, which will ultimately benefit buyers through improved product quality and create increased demand for advanced fabrication equipment among suppliers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Equipment Type – Lithography Systems Dominated, Metrology Tools Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, Lithography Systems took a 52% share of equipment type in 2025, more than any other category. Lithography systems lead the China semiconductor fabrication equipment market as they are crucial for the patterning of semiconductor wafers. Their importance is underscored by the reliance of over 200 operational semiconductor foundries on these systems for integrated circuit production. The quickest growth will come from Metrology Tools, forecast to expand at a CAGR of 10.4% between 2026 and 2032. Metrology tools are experiencing rapid growth due to the increasing demand for precise measurements and inspections in semiconductor production. This growth is supported by substantial investments in advanced technologies at facilities like the Shanghai Integrated Circuit Research Institute. Suppliers should focus on enhancing metrology tool capabilities to meet the rising demand for quality assurance in semiconductor manufacturing.
By Process Step – Pattern Transfer Dominated, Defect Inspection Expected to Grow Fastest
In 2025, Pattern Transfer led the process step split with a 38% share. Pattern transfer is the foremost process step in semiconductor fabrication, essential for accurately transferring designs onto wafers. This step is critical for creating the intricate patterns required for integrated circuits during production. Over 2026–2032, Defect Inspection is expected to post the fastest growth, at a CAGR of 9.6%. Defect inspection is the fastest-growing process step, driven by the heightened emphasis on quality control in semiconductor production. The urgency for rigorous defect detection is highlighted by the $30 billion investment in semiconductor R&D announced by the State Council in 2023. Buyers should invest in advanced defect inspection technologies to enhance production quality and minimise waste.
By Automation Level – Fully Automated Dominated and Is Expected to Record the Fastest Growth
With a 37% revenue share in 2025, Fully Automated was the largest automation level category. The fully automated segment dominates the market due to its ability to improve efficiency and significantly reduce human error in production processes. Manufacturers are increasingly adopting these systems to achieve higher productivity levels. The same category is also set to grow fastest, at a CAGR of 9.5% during 2026–2032. Fully automated systems are also the fastest-growing segment, as the push for operational efficiency and cost reduction accelerates. The continuous advancements in automation technologies will likely widen the lead of fully automated systems in the market. Suppliers must concentrate on developing fully automated solutions to align with the industry's shift towards greater efficiency and reduced operational risks.
By End User – Foundries Dominated, Chip Fabricators Expected to Grow Fastest
Foundries accounted for a 41% market share by end user in 2025. Foundries are the primary users of semiconductor fabrication equipment, commanding the largest market share due to their vital role in semiconductor device manufacturing. Their extensive operational scale and ongoing investments in technology reinforce their dominant position. Chip Fabricators are set to record the highest CAGR in this split, 10.6% over 2026–2032. Chip fabricators represent the fastest-growing end user segment, propelled by the increasing demand for custom semiconductor solutions. This trend mirrors the broader shift towards specialised chip production as the market continues to evolve. Suppliers should tailor their offerings to meet the specific needs of chip fabricators, who are increasingly seeking advanced fabrication solutions.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Semiconductor Fabrication Equipment Market Outlook
- Market Size of China Semiconductor Fabrication Equipment Market, 2025
- Forecast of China Semiconductor Fabrication Equipment Market, 2032
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Revenues & Volume for the Period 2022 - 2032F
- China Semiconductor Fabrication Equipment Market Trend Evolution
- China Semiconductor Fabrication Equipment Market Drivers and Challenges
- China Semiconductor Fabrication Equipment Price Trends
- China Semiconductor Fabrication Equipment Porter's Five Forces
- China Semiconductor Fabrication Equipment Industry Life Cycle
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Equipment Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Lithography Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Etching Equipment for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Deposition Equipment for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Metrology Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Process Step for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Pattern Transfer for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Pattern Etch for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Film Coating for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Defect Inspection for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Automation Level for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Fully Automated for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Dry/Wet Etching for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By ALD/CVD/PVD for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Inline Measurement for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Foundries for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By IDM Players for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Chip Fabricators for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Fabrication Equipment Market Revenues & Volume By Equipment Integrators for the Period 2022 - 2032F
- China Semiconductor Fabrication Equipment Import Export Trade Statistics
- Market Opportunity Assessment By Equipment Type
- Market Opportunity Assessment By Process Step
- Market Opportunity Assessment By Automation Level
- Market Opportunity Assessment By End User
- China Semiconductor Fabrication Equipment Top Companies Market Share
- China Semiconductor Fabrication Equipment Competitive Benchmarking By Technical and Operational Parameters
- China Semiconductor Fabrication Equipment Company Profiles
- China Semiconductor Fabrication Equipment Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Equipment Type
- Lithography Systems
- Etching Equipment
- Deposition Equipment
- Metrology Tools
By Process Step
- Pattern Transfer
- Pattern Etch
- Film Coating
- Defect Inspection
By Automation Level
- Fully Automated
- Dry/Wet Etching
- ALD/CVD/PVD
- Inline Measurement
By End User
- Foundries
- IDM Players
- Chip Fabricators
- Equipment Integrators































