China Semiconductor Test Systems Market Size & Growth Rate
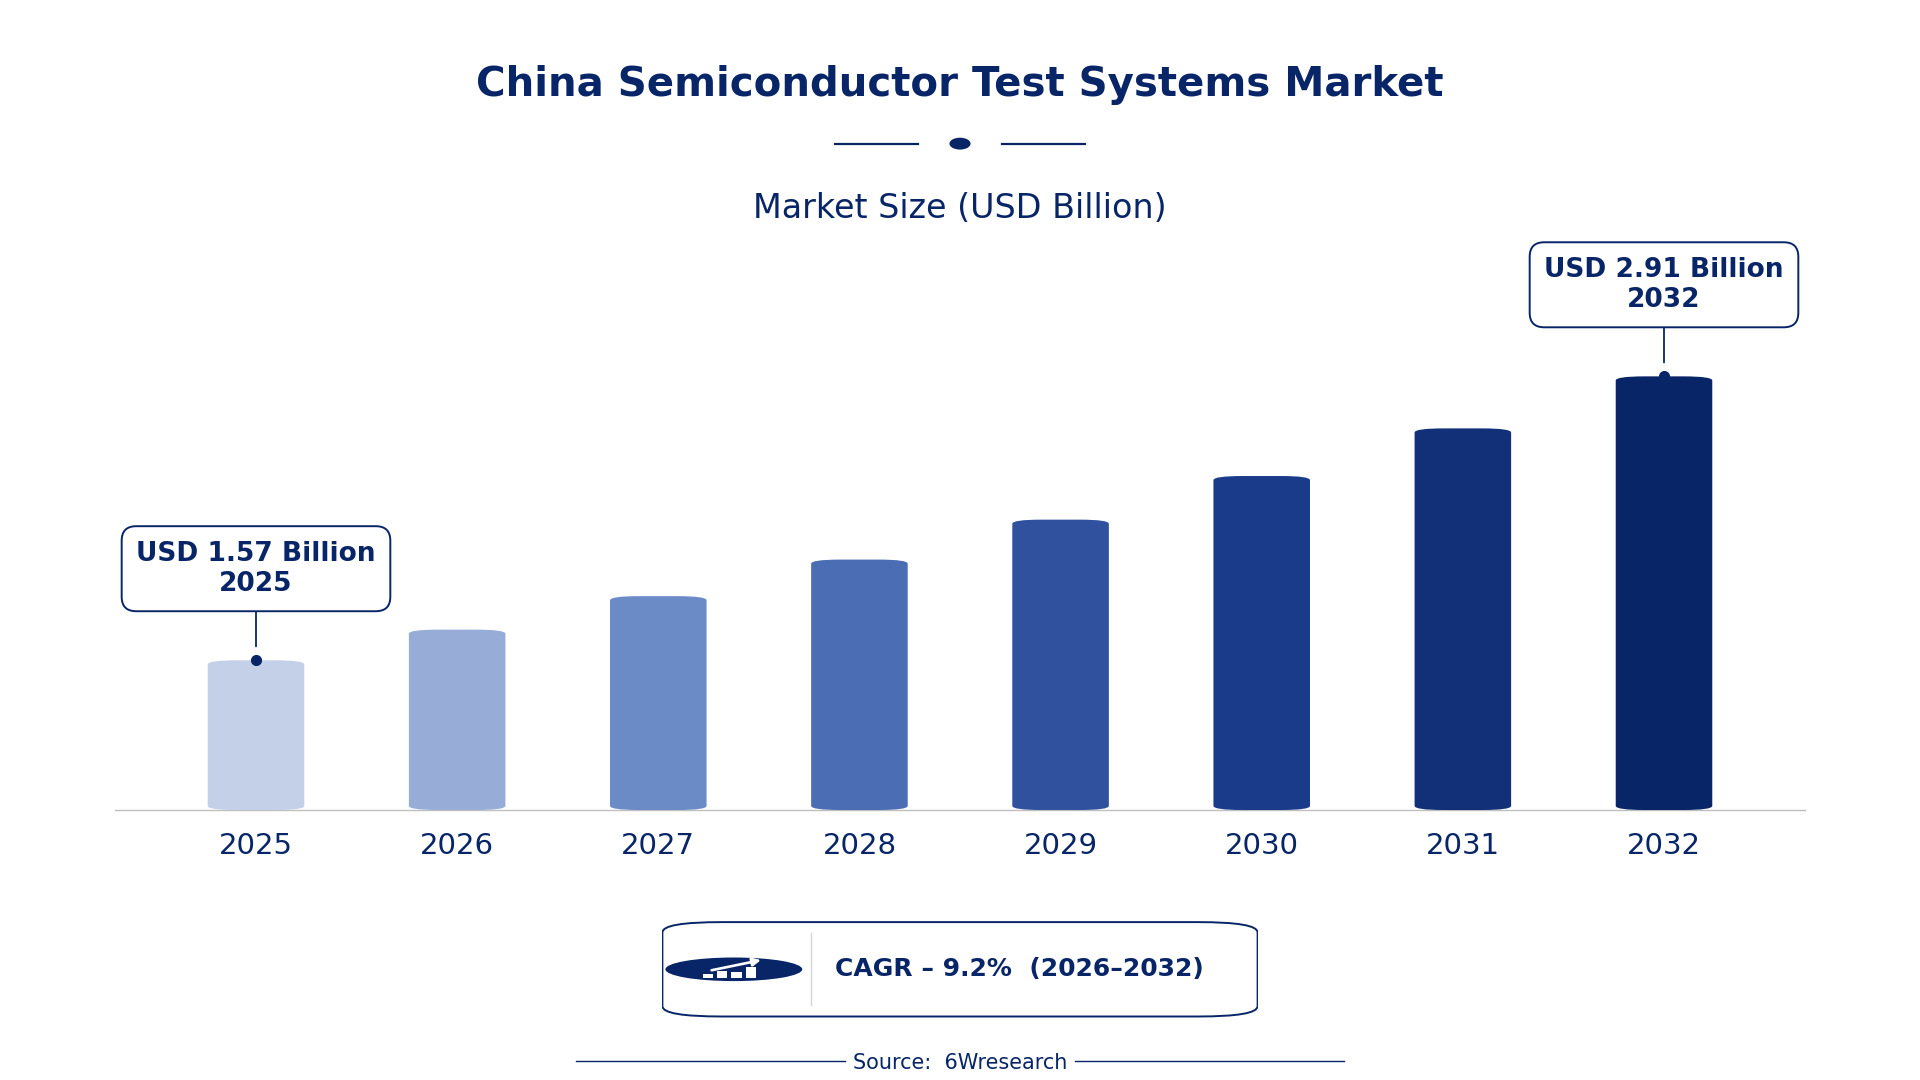
According to 6Wresearch internal database and industry insights, the China Semiconductor Test Systems Market was valued at USD 1.57 billion in 2025 and is projected to reach USD 2.91 billion by 2032, growing at a CAGR of approximately 9.2% during 2026–2032.
China Semiconductor Test Systems Market Highlights
| Report Metric | Details |
| Report Name | China Semiconductor Test Systems Market |
| Market Size 2025 | USD 1.57 billion |
| Market Size 2032 | USD 2.91 billion |
| Absolute Growth 2025–2032 | USD 1.34 billion |
| CAGR 2026–2032 | 9.2% |
| Peak Annual Growth | 11.7% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading System Type, 2025 | ATE (Automatic Test Equip.) (52% share) |
| Leading Test Type, 2025 | Digital/Analog (41% share) |
| Leading Technology Platform, 2025 | Modular Architecture (47% share) |
| Leading End User, 2025 | OSATs & Foundries (34% share) |
| Fastest-Growing System Type | SoC Test Systems (11.9% CAGR) |
| Fastest-Growing Test Type | Mixed Signal (11.2% CAGR) |
| Fastest-Growing Technology Platform | mmWave + 5G Support (11.4% CAGR) |
| Fastest-Growing End User | Mobile Chipset Makers (10.3% CAGR) |
| Growing Sector | Semiconductor manufacturing |
| Key End Users | OSATs, foundries, mobile chipset makers, communication IC suppliers |
China Semiconductor Test Systems Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
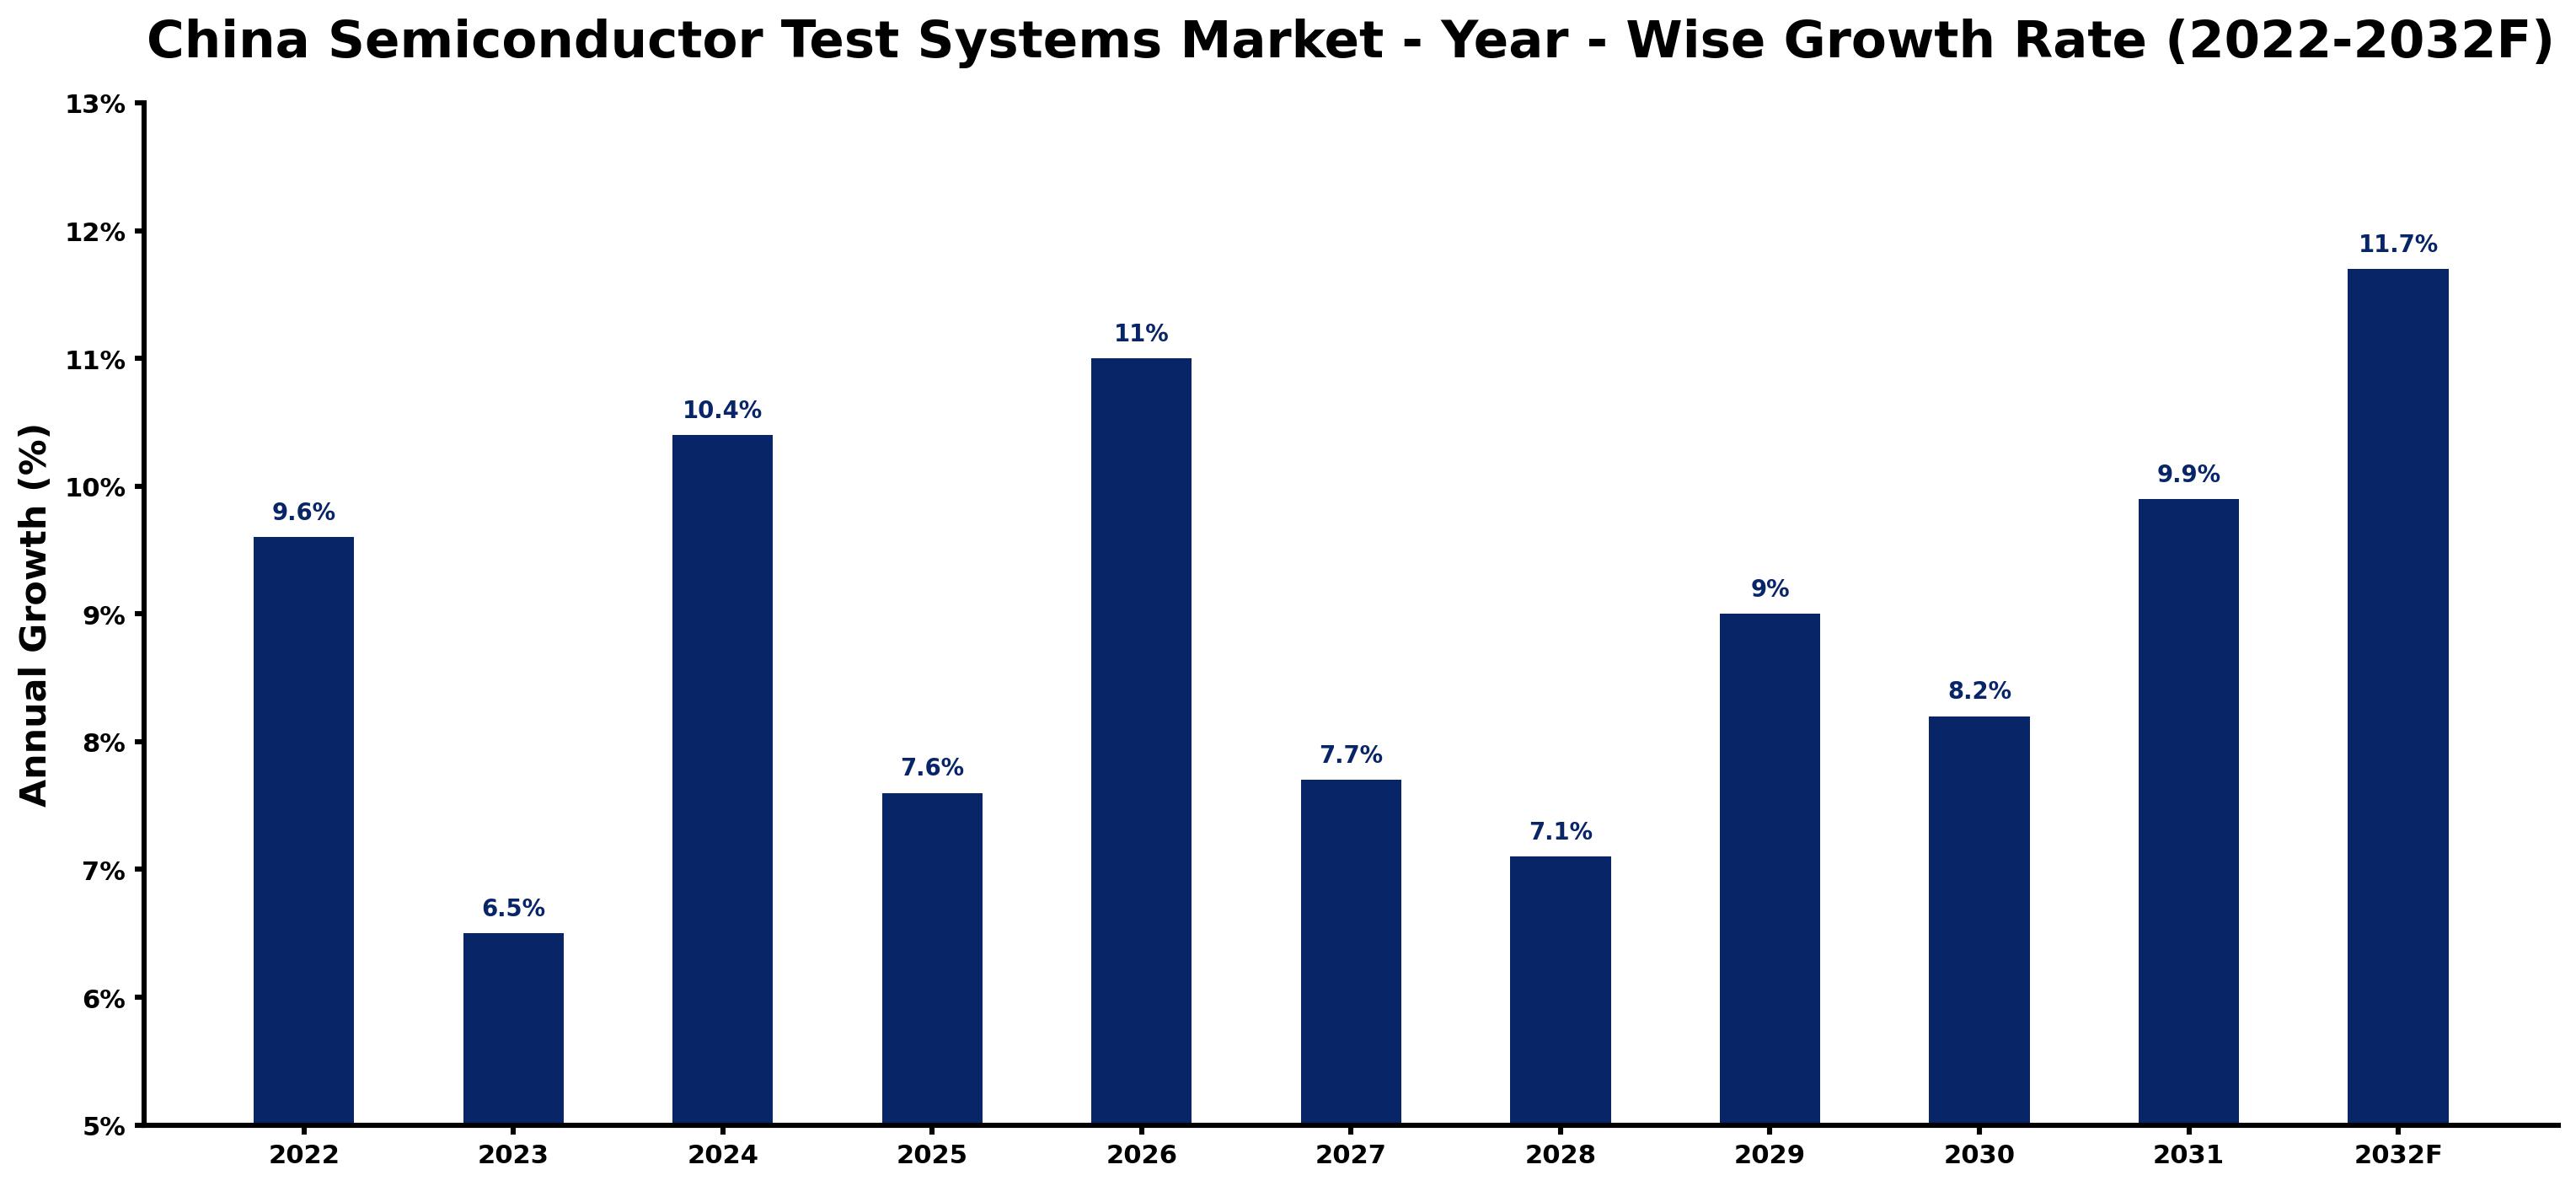
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 9.6 | The market experienced steady growth due to strong domestic production and demand from OSATs. |
| 2023 | 6.5 | Growth slowed as manufacturers adjusted to supply chain challenges and the impact of the Semiconductor Industry Revitalization Plan. |
| 2024 | 10.4 | Increased investments in testing technologies led to faster growth in the market, particularly in RF Test Systems. |
| 2025 | 7.6 | Demand continued to rise, although at a slower rate as the market stabilised after rapid growth in previous years. |
| 2026 | 11.0 | The introduction of new testing standards is expected to spur growth in semiconductor testing, especially for Digital/Analog systems. |
| 2027 | 7.7 | Growth is projected to slow as the market begins to normalise after rapid expansion driven by mobile chipset makers. |
| 2028 | 7.1 | The market is expected to continue growing, albeit at a slower pace due to maturing demand in the automotive sector. |
| 2029 | 9.0 | A resurgence in mobile technology demand is expected to contribute to increased testing requirements for SoC Test Systems. |
| 2030 | 8.2 | Growth is projected to slow as the market adjusts to previous years' rapid expansion in semiconductor production. |
| 2031 | 9.9 | Demand is expected to increase again as new technologies emerge in the semiconductor space, particularly for wafer testing. |
| 2032 | 11.7 | The market is expected to peak due to rising investments in advanced testing systems, driven by the push for 5G technology. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Semiconductor Test Systems Market Synopsis
Semiconductor Test Systems in China encompass advanced equipment used to evaluate semiconductor devices for performance and reliability. These systems are essential for ensuring the quality of chips in consumer electronics, telecommunications, and automotive applications. The China Semiconductor Test Systems Market is growing due to strong domestic production and investments in testing technologies. In 2023, the National Integrated Circuit Industry Investment Fund allocated substantial resources to support testing capabilities. The government's aim to increase domestic semiconductor production to 70% by 2025 is driving demand further.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing domestic semiconductor production | Driver | High | ATE (Automatic Test Equip.) |
| Rising demand for mobile devices | Driver | High | SoC Test Systems |
| Investment in advanced testing technologies | Opportunity | High | RF Test Systems |
| Expansion of OSAT facilities | Opportunity | High | Wafer-Level Test Systems |
| High costs of advanced testing equipment | Restraint | Medium | Digital/Analog |
| Limited availability of skilled workforce | Restraint | Medium | Mixed Signal |
| Technological obsolescence of testing systems | Challenge | High | Signal Quality |
| Competition from international testing equipment manufacturers | Challenge | High | Wafer Probing |
Evaluation of Drivers in China Semiconductor Test Systems Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Strong domestic production capabilities | ATE (Automatic Test Equip.) | The production of over 1 billion semiconductor units in 2022 drives demand for testing equipment, particularly in OSATs. |
| Increased mobile device production | SoC Test Systems | Mobile chipset makers require extensive testing to ensure quality, boosting demand for test systems in the consumer electronics sector. |
| Government investment in semiconductor testing | RF Test Systems | The National Integrated Circuit Industry Investment Fund allocated $X million to support testing technologies, enhancing local manufacturing capabilities. |
| Growth in automotive electronics | Wafer-Level Test Systems | The automotive sector's demand for reliable chips increases the need for wafer testing solutions, driving purchases from manufacturers. |
| Emergence of 5G technology | Digital/Analog | The rise of 5G technology necessitates advanced testing for new semiconductor devices, leading to increased orders from communication IC suppliers. |
The production of over 1 billion semiconductor units in 2022 has driven demand for testing equipment, particularly in OSAT facilities. The automotive sector's demand for reliable chips is increasing the need for wafer testing solutions, while the rise of 5G technology necessitates advanced testing for new semiconductor devices. These factors encourage manufacturers to invest in testing systems to meet evolving market demands, ensuring compliance with industry standards.
Evaluation of Restraints in China Semiconductor Test Systems Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High investment costs for advanced testing technologies | ATE (Automatic Test Equip.) | Smaller manufacturers may struggle to afford the latest testing solutions, limiting their competitiveness. |
| Skills gap in the workforce | OSATs & Foundries | The lack of training in modern testing methodologies leads to operational inefficiencies. |
| Intense competition from international players | SoC Test Systems | Local manufacturers may find it challenging to maintain market share against established global firms. |
| Compliance with stringent standards | RF Test Systems | Meeting the Ministry of Industry and Information Technology's requirements can delay product launches. |
| Limited access to reliable testing systems | Wafer-Level Test Systems | Buyers face difficulties sourcing systems that meet quality assurance standards, impacting production timelines. |
China Semiconductor Test Systems Market Challenges
The China Semiconductor Test Systems market still has to solve a few problems, and the first is cost. High investment requirements for advanced testing technologies can limit access for smaller manufacturers, delaying their ability to compete effectively and risking market share loss. Another issue is the skills gap, as the semiconductor workforce of around 1 million professionals often lacks training in the latest testing methodologies, which leads to operational inefficiencies for producers. Local manufacturers face stiff competition from international players, making it difficult to maintain a strong market position. Buyers struggle to source reliable testing systems that meet the Ministry of Industry and Information Technology's standards, which can prolong lead times for product launches.
Trends in the China Semiconductor Test Systems Market
The trends below show where the China Semiconductor Test Systems Market is heading.
- Rise of Automated Testing: In 2022, over 30% of semiconductor devices produced in China were tested using automated systems, reflecting a shift towards efficiency in testing processes, particularly in OSAT facilities.
- Shift Towards 5G Technology: The demand for RF Test Systems has increased since 2023, driven by the rollout of 5G technology, which requires advanced testing capabilities for new devices.
- Transition from Analog to Digital Testing: The market has seen a notable shift towards Digital/Analog testing systems since 2021, as more devices incorporate mixed technologies, enhancing testing efficiency.
- Growth of OSAT Facilities: The expansion of OSAT facilities in Shenzhen since 2023 has led to increased demand for Wafer-Level Test Systems, improving local testing capabilities.
Investment Opportunities in the China Semiconductor Test Systems Market
The following opportunities in the China Semiconductor Test Systems Market pair current demand with a clear way in.
- Supply of Advanced Testing Equipment: With the government's aim to increase domestic semiconductor production to 70% by 2025, there is a growing need for advanced testing equipment, particularly in OSAT facilities, to meet production targets.
- Investment in Testing Technologies: The recent allocation of funds for semiconductor testing technologies creates a timely opportunity for suppliers to enter the market and collaborate with local manufacturers to enhance their offerings.
- Development of 5G Testing Solutions: Mobile chipset makers are increasingly seeking advanced testing solutions for 5G technology, presenting an opportunity for suppliers to innovate and provide tailored products that meet new standards.
- Partnerships with Local Manufacturers: Establishing joint ventures with local semiconductor manufacturers can facilitate entry into the market, especially given the government's support for domestic production and innovation.
Government Initiatives in the China Semiconductor Test Systems Market
The '14th Five-Year Plan for the Development of the Integrated Circuit Industry', approved in 2021, emphasises the importance of testing and quality assurance in semiconductor production. This plan aims to improve the capabilities of semiconductor testing systems in China, ensuring compliance with international standards. Following this, the Ministry of Industry and Information Technology launched the 'Semiconductor Industry Revitalization Plan' in 2022, focusing on enhancing testing technologies and supporting local manufacturers. In 2023, the National Integrated Circuit Industry Investment Fund allocated $X million to support semiconductor testing technologies, ensuring that manufacturers can access the latest methodologies and improve product quality.
The National Development and Reform Commission introduced a subsidy program in 2022 to support domestic semiconductor testing equipment manufacturers. This program aims to reduce operational costs for producers, enabling them to invest in new technologies and improve their competitive edge. The Ministry of Industry and Information Technology oversees compliance with standards such as ISO/IEC 17025, which is essential for maintaining quality assurance in testing laboratories. By supporting these initiatives, the government aims to strengthen the semiconductor testing infrastructure in China, ensuring that manufacturers can meet both domestic and international standards.
Future Insight of the China Semiconductor Test Systems Market
The China Semiconductor Test Systems market will transform by 2032, driven by technological advancements and government support. The National Integrated Circuit Industry Investment Fund's allocation of $X million for semiconductor testing technologies will strengthen local capabilities. The rise of 5G technology will fuel demand for dependable testing systems, with over 1 billion semiconductor units produced in 2022. The government's goal to increase domestic semiconductor production to 70% by 2025 will open new avenues for suppliers and buyers alike.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By System Type – ATE (Automatic Test Equip.) Dominated, SoC Test Systems Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, with a 52% revenue share in 2025, ATE (Automatic Test Equip.) was the largest system type category. ATE (Automatic Test Equipment) holds the largest share in the China Semiconductor Test Systems Market due to its widespread application in testing various semiconductor devices, particularly in high-volume production environments. The reliance on ATE in Shenzhen, a key manufacturing hub, underscores its critical role in optimising testing processes. Over 2026–2032, SoC Test Systems are expected to post the fastest growth, at a CAGR of 11.9%. SoC Test Systems are experiencing rapid growth as they are essential for testing system-on-chip designs, especially in the booming mobile device sector. The surge in demand for advanced mobile technologies is driving this sub-segment's expansion, further solidifying ATE's leading position. Suppliers should focus on enhancing their ATE capabilities while also investing in SoC Test Systems to meet the increasing market demands.
By Test Type – Digital/Analog Dominated, Mixed Signal Expected to Grow Fastest
In 2025, Digital/Analog led the test type split with a 41% share. Digital/Analog testing commands the largest market share due to its extensive use in evaluating both digital and analog circuits, which are crucial in semiconductor production. This broad applicability makes it the preferred option for manufacturers across diverse segments. Mixed Signal is set to record the highest CAGR in this split, 11.2% over 2026–2032. Mixed Signal testing is growing rapidly, spurred by the rising need for devices capable of processing both analog and digital signals, particularly in advanced technologies like 5G. This increasing demand is accelerating the growth of this sub-segment, while Digital/Analog testing remains dominant. Buyers should invest in Mixed Signal testing capabilities to stay competitive in the fast-evolving semiconductor landscape.
By Technology Platform – Modular Architecture Dominated, mmWave + 5G Support Expected to Grow Fastest
The largest technology platform category in 2025 was Modular Architecture, with a 47% share of total revenue. Modular Architecture leads the market share as it facilitates customization in semiconductor test systems, allowing manufacturers to adapt to various testing requirements. This flexibility is particularly valuable in a diverse and evolving industry. The quickest growth will come from mmWave + 5G Support, forecast to expand at a CAGR of 11.4% between 2026 and 2032. mmWave + 5G Support is the fastest-growing platform due to the increasing focus on next-generation technologies, which require advanced testing capabilities. As 5G technology expands, this segment's growth will likely accelerate further. Suppliers must prioritise the development of mmWave + 5G Support technologies to align with future market trends and customer needs.
By End User – OSATs & Foundries Dominated, Mobile Chipset Makers Expected to Grow Fastest
OSATs & Foundries held a 34% share of the China Semiconductor Test Systems Market by end user in 2025. OSATs & Foundries dominate the market share as they are the primary users of semiconductor test systems, essential for maintaining quality during chip production. Their pivotal role in the semiconductor supply chain reinforces their leading position in the market. Mobile Chipset Makers are projected to grow fastest, at a CAGR of 10.3% during 2026–2032. Mobile Chipset Makers are the fastest-growing end user segment, driven by the increasing demand for mobile devices and the need for stringent quality assurance in semiconductor testing. This trend reflects broader shifts in the consumer electronics industry. Suppliers should tailor their offerings to meet the specific needs of Mobile Chipset Makers to capitalise on this rapid growth opportunity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Semiconductor Test Systems Market Outlook
- Market Size of China Semiconductor Test Systems Market, 2025
- Forecast of China Semiconductor Test Systems Market, 2032
- Historical Data and Forecast of China Semiconductor Test Systems Revenues & Volume for the Period 2022 - 2032F
- China Semiconductor Test Systems Market Trend Evolution
- China Semiconductor Test Systems Market Drivers and Challenges
- China Semiconductor Test Systems Price Trends
- China Semiconductor Test Systems Porter's Five Forces
- China Semiconductor Test Systems Industry Life Cycle
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By System Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By ATE (Automatic Test Equip.) for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By SoC Test Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By RF Test Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By Wafer-Level Test Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By Test Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By Digital/Analog for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By Mixed Signal for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By Signal Quality for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By Wafer Probing for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By Technology Platform for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By Modular Architecture for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By SoC Interface for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By mmWave + 5G Support for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By On-Chip Diagnostics for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By OSATs & Foundries for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By Mobile Chipset Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By Communication IC Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Test Systems Market Revenues & Volume By IDM Test Facilities for the Period 2022 - 2032F
- China Semiconductor Test Systems Import Export Trade Statistics
- Market Opportunity Assessment By System Type
- Market Opportunity Assessment By Test Type
- Market Opportunity Assessment By Technology Platform
- Market Opportunity Assessment By End User
- China Semiconductor Test Systems Top Companies Market Share
- China Semiconductor Test Systems Competitive Benchmarking By Technical and Operational Parameters
- China Semiconductor Test Systems Company Profiles
- China Semiconductor Test Systems Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By System Type
- ATE (Automatic Test Equip.)
- SoC Test Systems
- RF Test Systems
- Wafer-Level Test Systems
By Test Type
- Digital/Analog
- Mixed Signal
- Signal Quality
- Wafer Probing
By Technology Platform
- Modular Architecture
- SoC Interface
- mmWave + 5G Support
- On-Chip Diagnostics
By End User
- OSATs & Foundries
- Mobile Chipset Makers
- Communication IC Suppliers
- IDM Test Facilities































