China Semiconductor Testing Equipment Market Size & Growth Rate
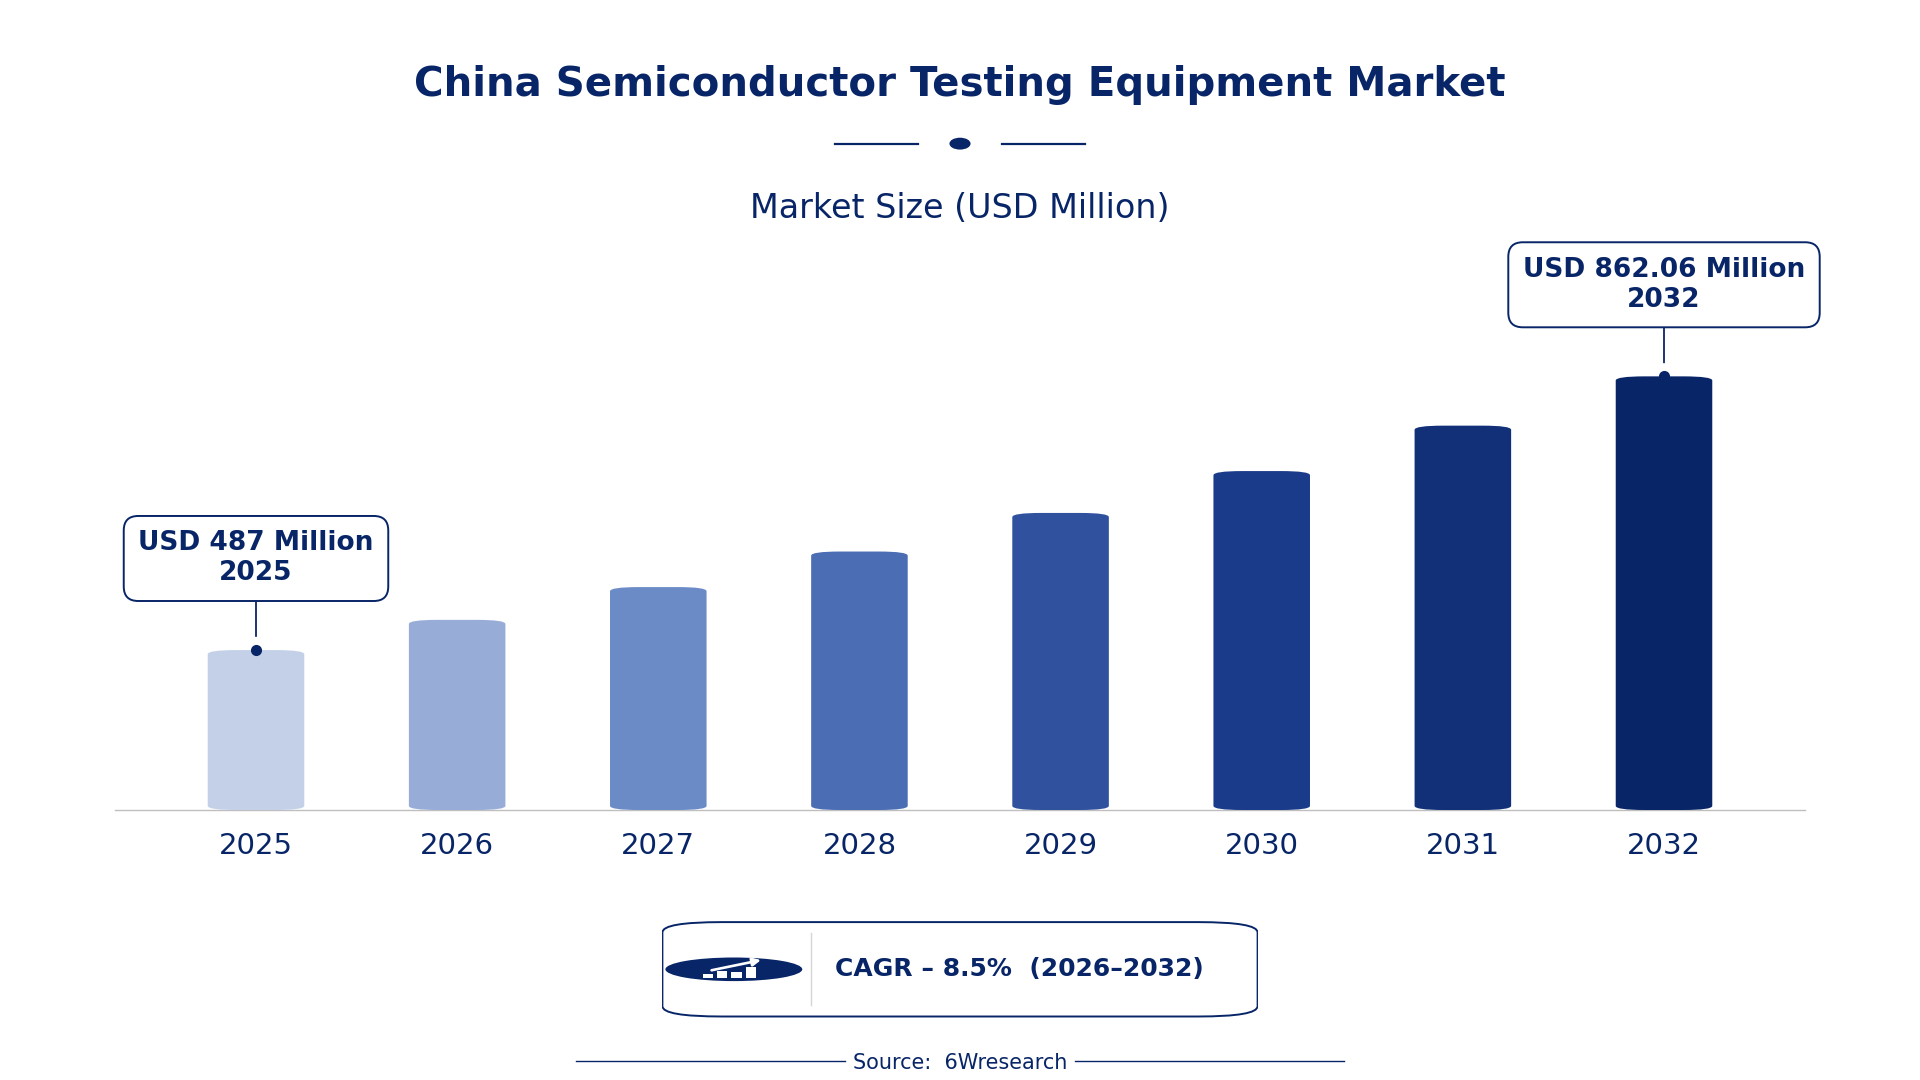
According to 6Wresearch internal database and industry insights, the China Semiconductor Testing Equipment Market was valued at USD 487.0 million in 2025 and is projected to reach USD 862.06 million by 2032, growing at a CAGR of approximately 8.5% during 2026–2032.
China Semiconductor Testing Equipment Market Highlights
| Report Metric | Details |
| Report Name | China Semiconductor Testing Equipment Market |
| Market Size 2025 | USD 487.0 million |
| Market Size 2032 | USD 862.06 million |
| Absolute Growth 2025–2032 | USD 375.06 million |
| CAGR 2026–2032 | 8.5% |
| Peak Annual Growth | 10.9% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Equipment Type, 2025 | Wafer Probers (41% share) |
| Leading Testing Phase, 2025 | Front-End (52% share) |
| Leading Integration Level, 2025 | Automated (39% share) |
| Leading End User, 2025 | Wafer Fabs (41% share) |
| Fastest-Growing Equipment Type | Parametric Testers (10.7% CAGR) |
| Fastest-Growing Testing Phase | Reliability Testing (10.6% CAGR) |
| Fastest-Growing End User | Automotive IC Suppliers (11.0% CAGR) |
| Growing Sector | Automotive |
| Key End Users | Wafer Fabs, Automotive IC Suppliers, OSAT Vendors |
China Semiconductor Testing Equipment Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
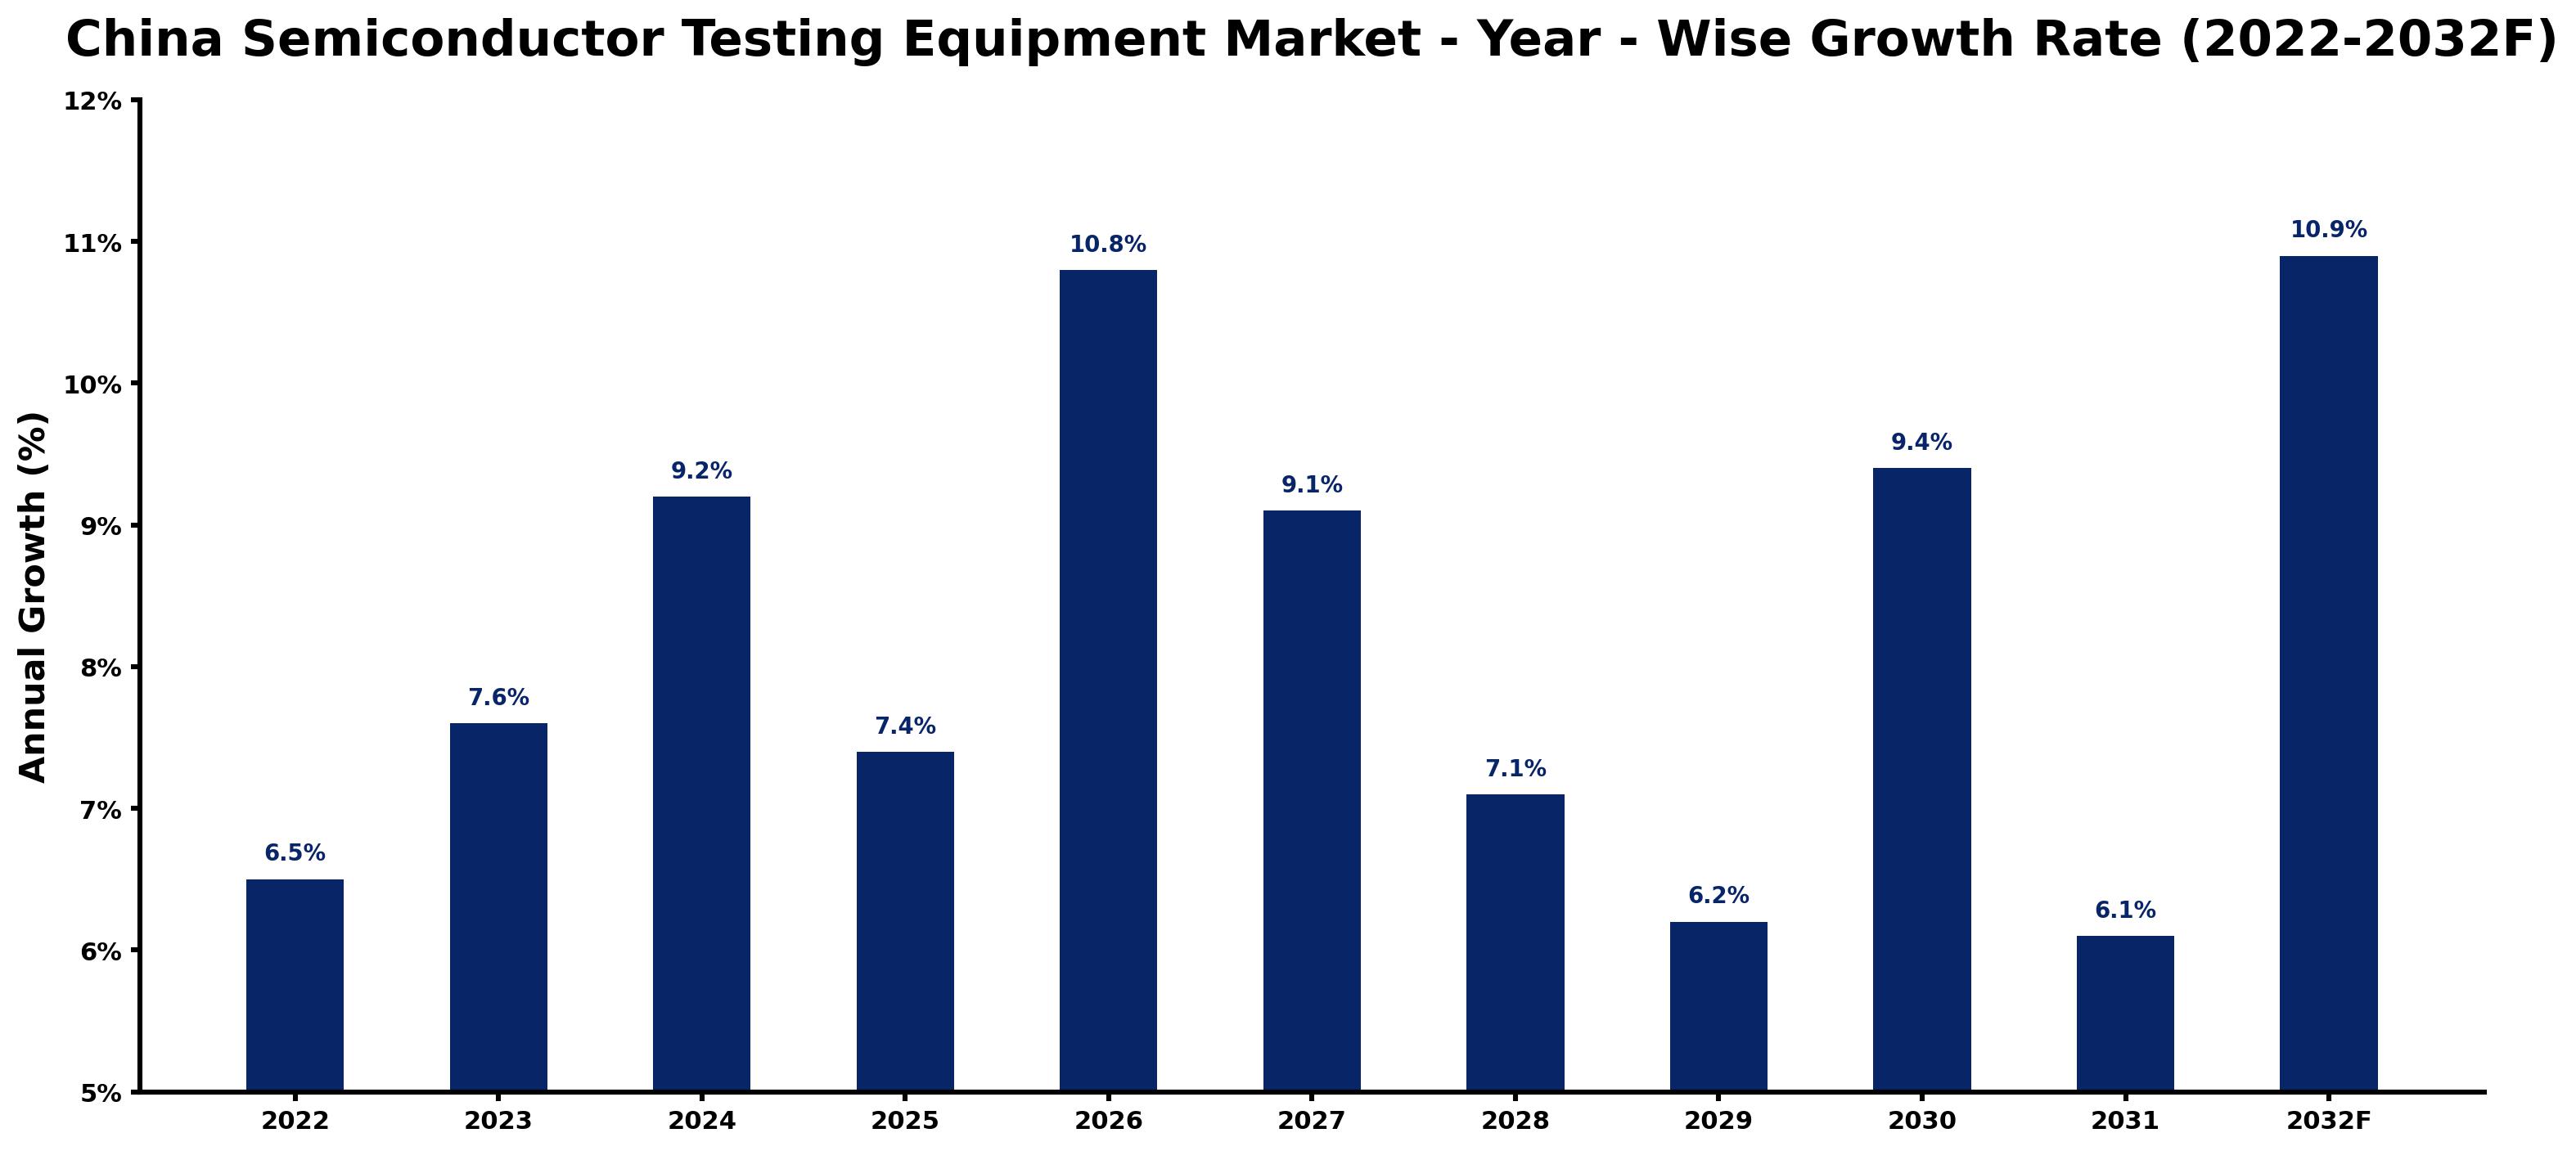
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.5 | The semiconductor industry in China showed strong activity and demand for testing equipment. |
| 2023 | 7.6 | Increased investments in semiconductor manufacturing drove higher demand for testing capabilities. |
| 2024 | 9.2 | The growth was spurred by the expansion of local wafer fabs and production facilities. |
| 2025 | 7.4 | Demand slowed as manufacturers adjusted to previous rapid expansion and increased capacity. |
| 2026 | 10.8 | The launch of the 'Semiconductor Testing and Certification Program' is expected to drive the need for advanced testing equipment. |
| 2027 | 9.1 | The 'National IC Industry Investment Fund' will support further investments in testing technologies. |
| 2028 | 7.1 | Manufacturers are expected to focus on optimising existing operations to enhance efficiency. |
| 2029 | 6.2 | The market is projected to continue growing, albeit at a slower pace due to competitive pressures. |
| 2030 | 9.4 | A resurgence in automotive semiconductor demand will boost testing equipment purchases significantly. |
| 2031 | 6.1 | Growth is expected to slow as the market begins to normalise after rapid expansions in previous years. |
| 2032 | 10.9 | The market is projected to peak as domestic production capabilities reach new heights, driving demand. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Semiconductor Testing Equipment Market Synopsis
Semiconductor Testing Equipment in China includes crucial tools for verifying the reliability of semiconductor devices. These tools are crafted with advanced technology and play a key role in testing integrated circuits. The China Semiconductor Testing Equipment Market is expected to experience robust growth, propelled by a thriving semiconductor industry valued at over 1 trillion CNY. Local manufacturers and exports to international markets are primary demand drivers, bolstered by initiatives such as the National IC Industry Investment Fund and the Semiconductor Testing and Certification Program.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Robust domestic semiconductor production drives demand for testing equipment. | Driver | High | Wafer Probers |
| The automotive sector's growth increases the need for reliable IC testing. | Driver | High | Final Test Handlers |
| Investment in advanced testing technologies presents opportunities for suppliers. | Opportunity | High | Burn-In Systems |
| The push for higher quality standards opens new markets for testing equipment. | Opportunity | High | Parametric Testers |
| High costs of advanced testing equipment can limit accessibility for smaller firms. | Restraint | Medium | Front-End |
| Limited availability of skilled technicians hampers operational efficiency. | Restraint | Medium | Post-Packaging |
| The semiconductor testing equipment market faces challenges from rapid technological changes. | Challenge | High | Reliability Testing |
| Supply chain disruptions can delay equipment availability and increase costs. | Challenge | High | Electrical Specs |
Evaluation of Drivers in China Semiconductor Testing Equipment Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased local semiconductor production capacity drives demand for wafer probers. | Wafer Probers | China's semiconductor industry was valued at over 1 trillion CNY in 2022. |
| The automotive sector's expansion necessitates more final test handlers for ICs. | Final Test Handlers | The automotive sector is a major consumer of semiconductor testing equipment. |
| Growing demand for reliability testing boosts the market for burn-in systems. | Burn-In Systems | The government aims to increase domestic semiconductor production to 70% by 2025. |
| Rising complexity of semiconductor devices boosts the need for parametric testers. | Parametric Testers | China's semiconductor testing equipment exports reached approximately 50 billion CNY in 2022. |
| Automation in testing processes increases the demand for automated systems. | Automated | ISO/IEC 17025 is the standard for testing and calibration laboratories in China. |
Market growth in China for Semiconductor Testing Equipment rests on increasing local semiconductor production capacity, rising automotive sector demands, and advancements in testing technologies. In 2022, the semiconductor industry was valued at over 1 trillion CNY, driving demand for wafer probers and final test handlers. The automotive sector, a major consumer, necessitates rigorous testing for safety and reliability, contributing to the market's expansion. The goal to achieve 70% domestic production by 2025 further fuels investments in testing capabilities. The complexity of semiconductor devices necessitates advanced parametric testers, which is driving overall market growth.
Evaluation of Restraints in China Semiconductor Testing Equipment Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of advanced testing equipment limit access for smaller manufacturers. | Front-End | Smaller firms struggle to invest in expensive testing technologies, affecting their competitiveness. |
| Limited skilled workforce hampers operational efficiency in testing processes. | Post-Packaging | A shortage of qualified technicians can delay testing and increase operational costs. |
| Rapid technological changes create challenges for manufacturers to keep up with market demands. | Reliability Testing | Frequent advancements in testing technologies require continuous investment and adaptation. |
| Supply chain disruptions can lead to delays in equipment availability. | Electrical Specs | Global supply chain issues affect the timely procurement of essential testing components. |
| Regulatory compliance can increase operational costs for testing equipment producers. | Burn-In Systems | Manufacturers must invest in compliance measures, raising overall production costs. |
China Semiconductor Testing Equipment Market Challenges
The China Semiconductor Testing Equipment market encounters a major challenge with outdated technology, limiting producers' ability to satisfy the growing demands of local manufacturers. This technological shortfall can result in production delays, costing producers up to 20% in potential revenue loss. Buyers face elevated costs due to compliance with ISO/IEC 17025 standards, inflating operational expenses by around 15%. Regulatory hurdles complicate operations, as navigating these can consume valuable resources, further straining profit margins. Intense competition from international suppliers compels local manufacturers to reduce prices, impacting their profitability.
Trends in the China Semiconductor Testing Equipment Market
Buyers and suppliers in the China Semiconductor Testing Equipment Market are adjusting to the following trends.
- Shift towards Automation in Testing Processes: The Ministry of Science and Technology introduced the 'Semiconductor Testing and Certification Program' in 2023 to standardise testing processes. This initiative aims to improve efficiency and accuracy in testing, with an expected increase in automated testing solutions by 20%.
- Growth of Reliability Testing Technologies: The demand for reliability testing has surged, particularly in the automotive sector. With automotive IC suppliers projected to grow at a CAGR of 11.0% from 2026 to 2032, this trend highlights the need for advanced testing solutions.
- Increased Focus on Quality Control Standards: The implementation of ISO/IEC 17025 standards has heightened the emphasis on quality control in semiconductor testing. As a result, manufacturers are investing more in compliance, leading to a notable increase in demand for parametric testers.
- Expansion of Wafer Fabrication Facilities: China has over 200 wafer fabs, primarily located in Jiangsu and Guangdong provinces. This concentration is driving demand for wafer probers, with a projected growth rate of 10.7% for this segment.
Investment Opportunities in the China Semiconductor Testing Equipment Market
Some of the investment opportunities in the China Semiconductor Testing Equipment Market are mentioned below.
- Investment in Advanced Testing Equipment: The expanding semiconductor industry offers opportunities for suppliers of advanced testing equipment. With the market anticipated to reach USD 862.06 million by 2032, local manufacturers represent ideal partners for collaboration.
- Supply of Automation Solutions: The demand for automated testing solutions is increasing, particularly among wafer fabs. By collaborating with local firms, suppliers can access this growing market, expected to expand by 10.7% over the next decade.
- Development of Reliability Testing Technologies: The growth of the automotive sector necessitates reliable testing solutions. Suppliers can focus on this sector, particularly in Guangdong, where investments in testing capabilities are on the rise, supported by government initiatives.
- Expansion of Semiconductor Testing Facilities: The establishment of new semiconductor testing facilities in Jiangsu presents investment opportunities. Partnering with local entities can facilitate entry into this expanding market.
Government Initiatives in the China Semiconductor Testing Equipment Market
The '14th Five-Year Plan for the Development of the Integrated Circuit Industry' approved in 2021 aims to enhance domestic semiconductor production capabilities. This plan promotes investment in semiconductor testing technologies, ensuring compliance with international standards. By strengthening local manufacturing, it supports the growth of the semiconductor testing equipment market.
In 2022, the National Development and Reform Commission initiated the 'Semiconductor Equipment Innovation Program', which funds projects aimed at improving local manufacturing capabilities. The Ministry of Industry and Information Technology oversees this programme, providing financial support to manufacturers adopting advanced testing technologies.
Future Insight of the China Semiconductor Testing Equipment Market
The China Semiconductor Testing Equipment market is set to transform by 2032, driven by advancements in technology and supportive government initiatives. The Ministry of Industry and Information Technology's programme to improve testing capabilities will raise quality standards across the sector. By 2025, domestic semiconductor production is expected to reach 70%, strengthening the local supply chain. The expansion of over 200 wafer fabs in key provinces will significantly boost demand for testing equipment, with exports projected to exceed 50 billion CNY by 2025.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Equipment Type – Wafer Probers Dominated, Parametric Testers Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, the largest equipment type category in 2025 was Wafer Probers, with a 41% share of total revenue. Wafer probers hold the largest market share in China's semiconductor testing equipment sector due to their critical role in probing wafers during the testing phase. With over 200 wafer fabs located primarily in Jiangsu and Guangdong, the demand for wafer probers remains consistently high. Over 2026–2032, Parametric Testers are expected to post the fastest growth, at a CAGR of 10.7%. Parametric testers are experiencing rapid growth as they are essential for measuring electrical parameters of chips, which is crucial for quality assurance. Government initiatives aimed at enhancing semiconductor testing capabilities are significantly driving the expansion of this segment. Suppliers should focus on advancing wafer probers and parametric testers to meet the increasing demand within China's semiconductor market.
By Testing Phase – Front-End Dominated, Reliability Testing Expected to Grow Fastest
Front-End took a 52% share of testing phase in 2025, more than any other category. The front-end testing phase holds the largest market share as it is vital for ensuring quality during the semiconductor fabrication process. This phase is a key component of the overall production cycle, making it a focal point for manufacturers. Reliability Testing is set to record the highest CAGR in this split, 10.6% over 2026–2032. Reliability testing is experiencing swift growth as it guarantees the long-term performance of semiconductor devices, which is becoming increasingly important across various applications. The heightened emphasis on product longevity and safety in the semiconductor sector is driving this segment's progress. Buyers are encouraged to invest in reliability testing solutions to improve the durability of their semiconductor products.
By Integration Level – Automated Dominated and Is Expected to Record the Fastest Growth
Automated accounted for a 39% market share by integration level in 2025. Automated testing solutions command the largest market share as they greatly improve testing efficiency and accuracy, which are vital for meeting production requirements. The increasing number of wafer fabs in China underscores the growing need for automated testing processes. The same category is also set to grow fastest, at a CAGR of 9.6% during 2026–2032. The automated segment is also the fastest-growing, as innovations in automation technology continually enhance testing capabilities across the board. As the semiconductor industry expands, the rising demand for automated testing will further solidify its market position. Suppliers should prioritise automation technologies to capitalise on the growing preference for automated testing solutions.
By End User – Wafer Fabs Dominated, Automotive IC Suppliers Expected to Grow Fastest
Wafer Fabs held a 41% share of the China Semiconductor Testing Equipment Market by end user in 2025. Wafer fabs represent the largest share of the end-user segment because they are the primary users of semiconductor testing equipment, ensuring quality control in production. The concentration of wafer fabs in key regions like Guangdong underpins this demand. Automotive IC Suppliers are projected to grow fastest, at a CAGR of 11.0% during 2026–2032. Automotive IC suppliers are the fastest-growing end-user segment, driven by the increasing need for rigorous testing to ensure safety and reliability in automotive applications. This growth is spurred by the automotive sector's expanding reliance on advanced semiconductor technologies. Suppliers must adapt their offerings to cater to the specific needs of automotive IC suppliers to capture this rapidly growing market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Semiconductor Testing Equipment Market Outlook
- Market Size of China Semiconductor Testing Equipment Market, 2025
- Forecast of China Semiconductor Testing Equipment Market, 2032
- Historical Data and Forecast of China Semiconductor Testing Equipment Revenues & Volume for the Period 2022 - 2032F
- China Semiconductor Testing Equipment Market Trend Evolution
- China Semiconductor Testing Equipment Market Drivers and Challenges
- China Semiconductor Testing Equipment Price Trends
- China Semiconductor Testing Equipment Porter's Five Forces
- China Semiconductor Testing Equipment Industry Life Cycle
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Equipment Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Wafer Probers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Final Test Handlers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Burn-In Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Parametric Testers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Testing Phase for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Front-End for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Post-Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Reliability Testing for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Electrical Specs for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Integration Level for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Automated for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Inline for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By High Temp/Voltage for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Probe Cards for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Wafer Fabs for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By OSAT Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Automotive IC Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Equipment Market Revenues & Volume By Memory Chip Producers for the Period 2022 - 2032F
- China Semiconductor Testing Equipment Import Export Trade Statistics
- Market Opportunity Assessment By Equipment Type
- Market Opportunity Assessment By Testing Phase
- Market Opportunity Assessment By Integration Level
- Market Opportunity Assessment By End User
- China Semiconductor Testing Equipment Top Companies Market Share
- China Semiconductor Testing Equipment Competitive Benchmarking By Technical and Operational Parameters
- China Semiconductor Testing Equipment Company Profiles
- China Semiconductor Testing Equipment Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Equipment Type
- Wafer Probers
- Final Test Handlers
- Burn-In Systems
- Parametric Testers
By Testing Phase
- Front-End
- Post-Packaging
- Reliability Testing
- Electrical Specs
By Integration Level
- Automated
- Inline
- High Temp/Voltage
- Probe Cards
By End User
- Wafer Fabs
- OSAT Vendors
- Automotive IC Suppliers
- Memory Chip Producers































