China Shipboard Water Treatment Market Size & Growth Rate
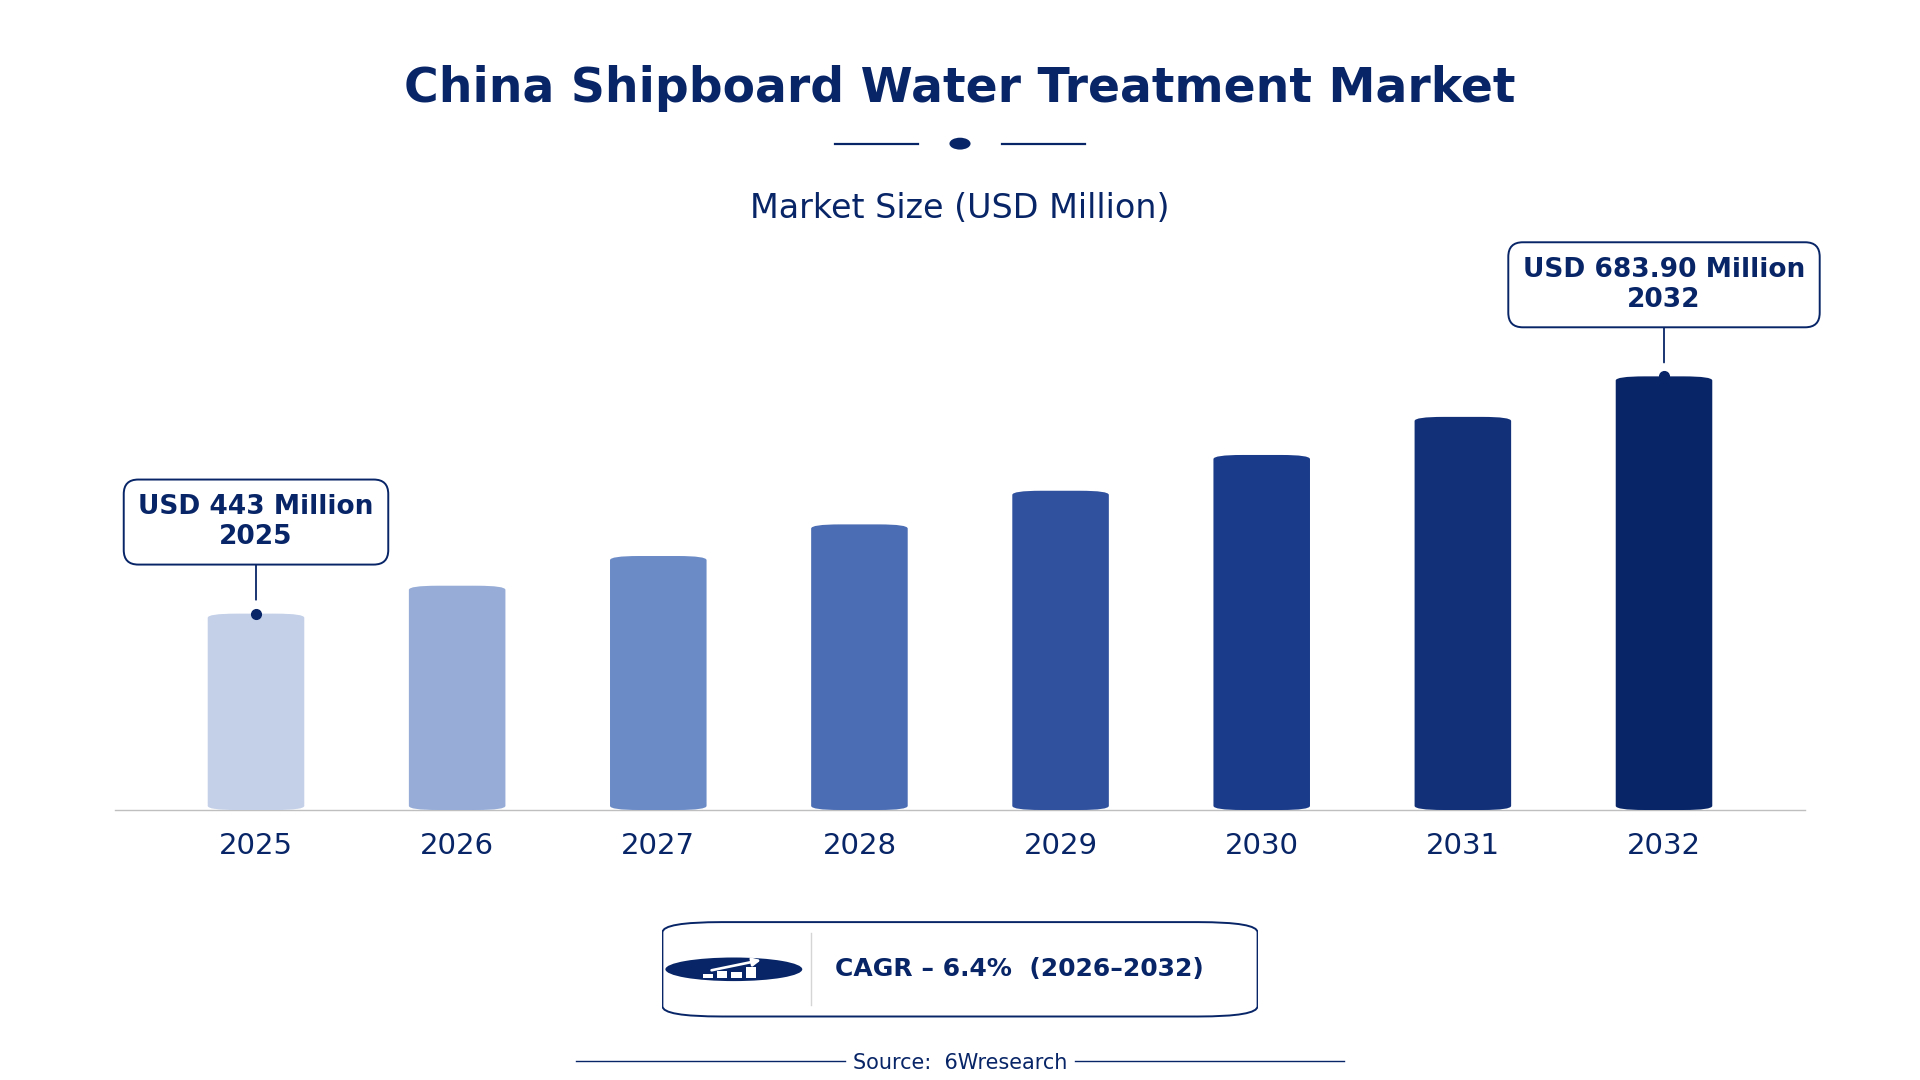
According to 6Wresearch internal database and industry insights, the China Shipboard Water Treatment Market was valued at USD 443.0 million in 2025 and is projected to reach USD 683.90 million by 2032, growing at a CAGR of approximately 6.4% during 2026–2032.
China Shipboard Water Treatment Market Highlights
| Report Metric | Details |
| Report Name | China Shipboard Water Treatment Market |
| Market Size 2025 | USD 443.0 million |
| Market Size 2032 | USD 683.90 million |
| Absolute Growth 2025–2032 | USD 240.90 million |
| CAGR 2026–2032 | 6.4% |
| Peak Annual Growth | 8.6% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Treatment Type, 2025 | Desalination Units (47% share) |
| Leading System Component, 2025 | Reverse Osmosis (48% share) |
| Leading Water Source, 2025 | Seawater (41% share) |
| Leading End User, 2025 | Commercial Ships (40% share) |
| Fastest-Growing Treatment Type | Wastewater Treatment (8.6% CAGR) |
| Fastest-Growing System Component | Membrane Bioreactor (7.9% CAGR) |
| Fastest-Growing Water Source | Gray/Black Water (7.9% CAGR) |
| Fastest-Growing End User | Passenger Ships (7.5% CAGR) |
| Growing Sector | Passenger Ships |
| Key End Users | Commercial Ships, Passenger Ships, Offshore Vessels, Marine Service Companies |
China Shipboard Water Treatment Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
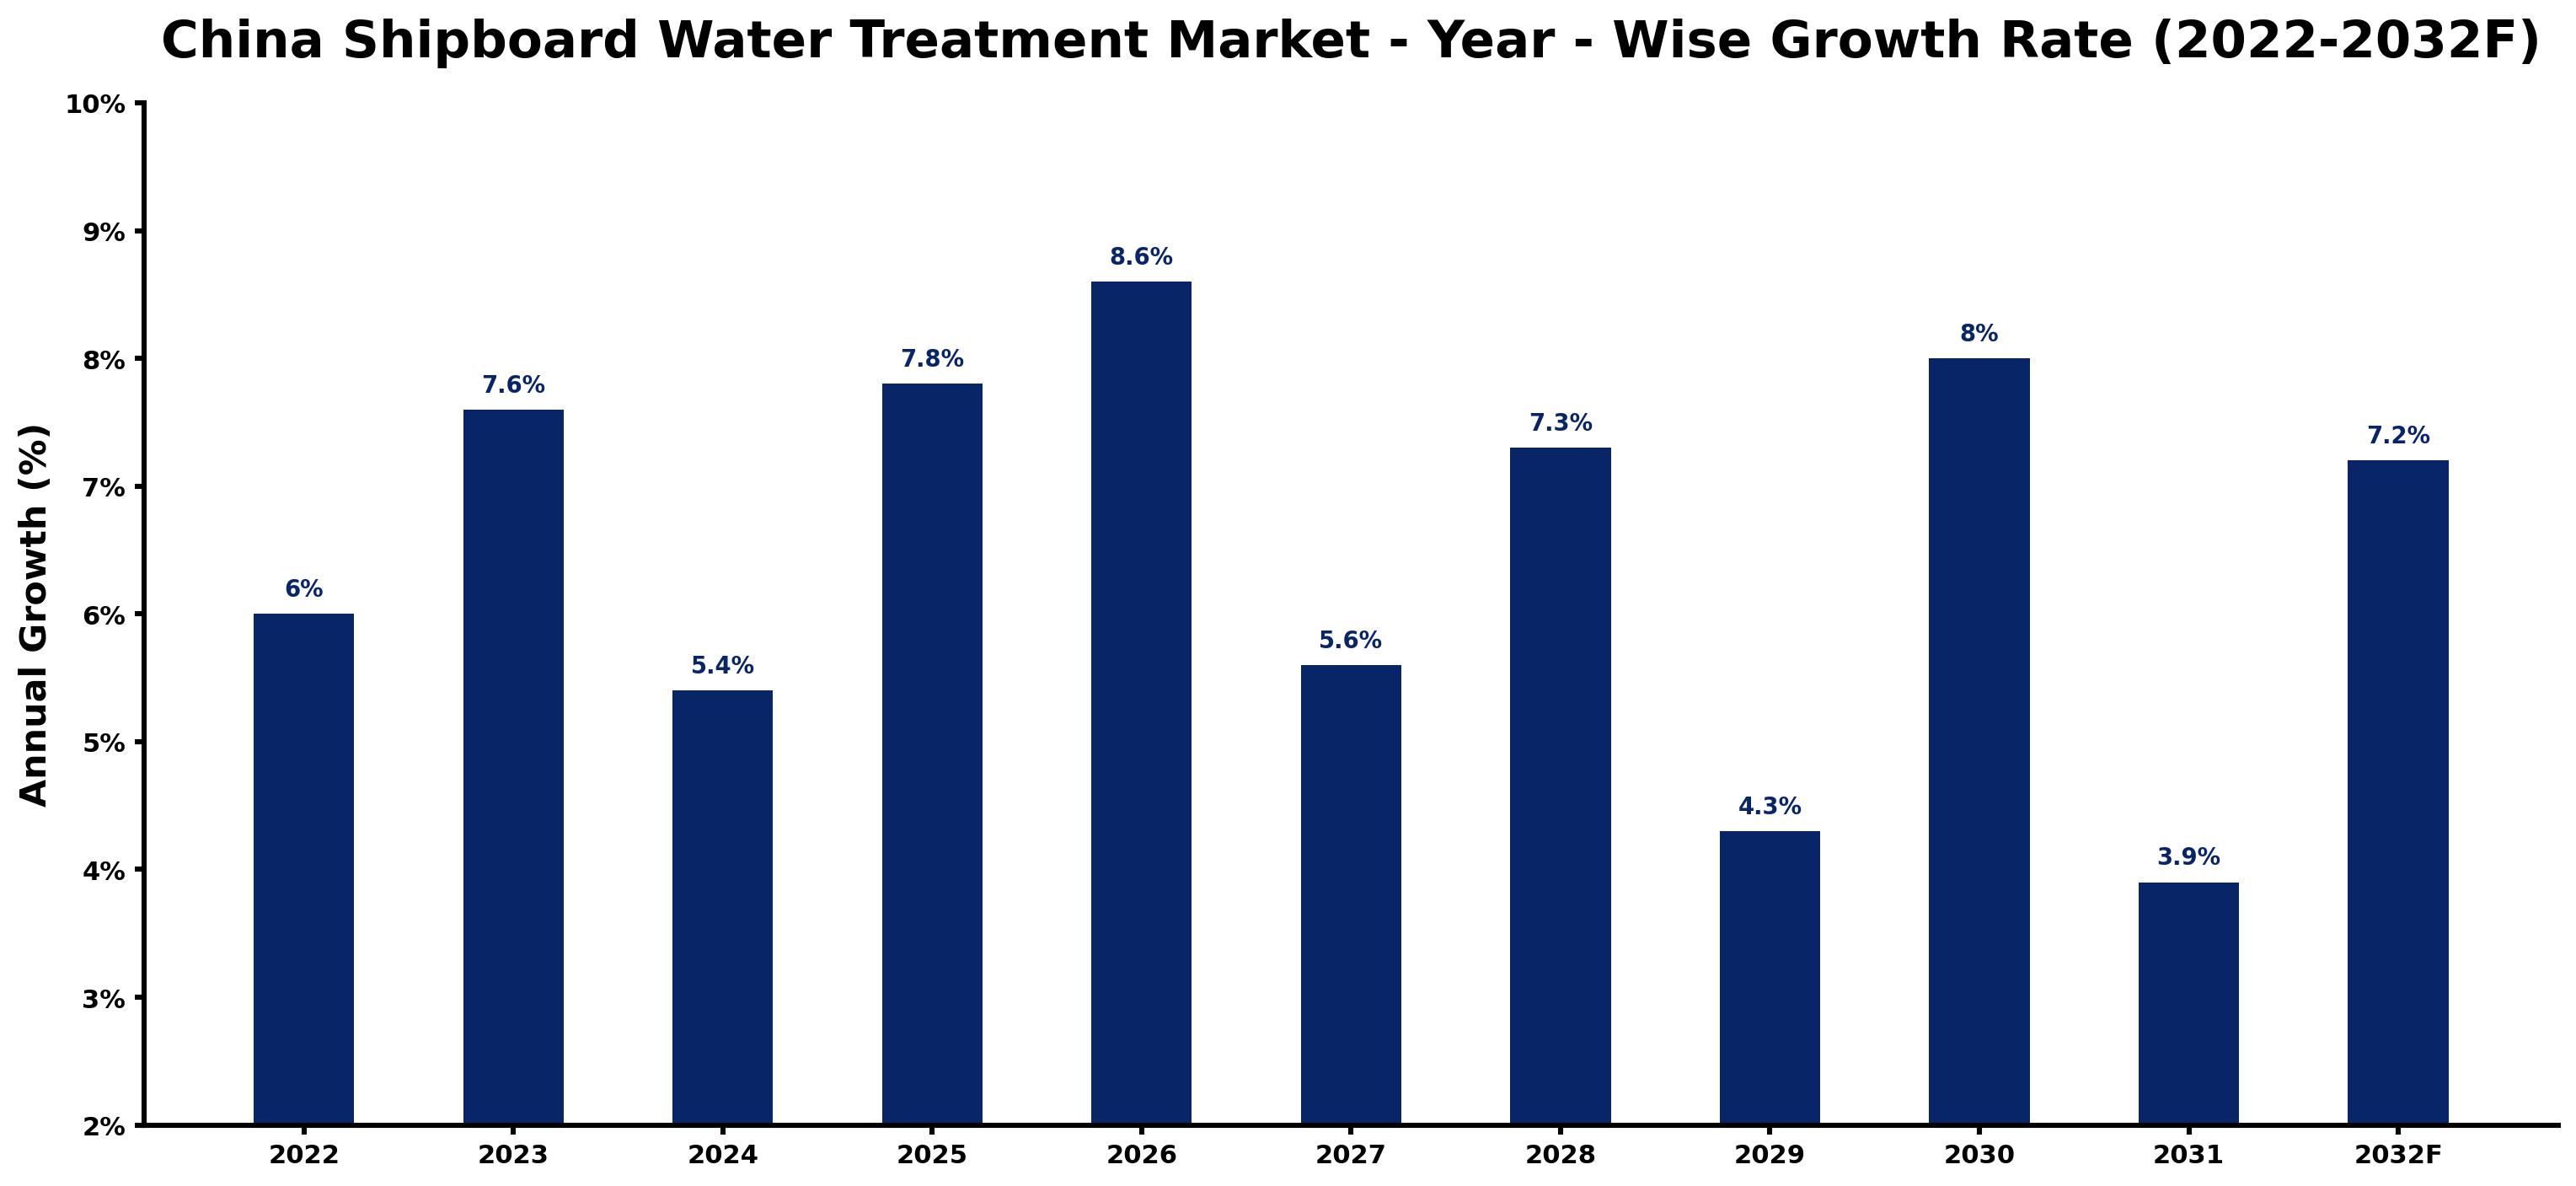
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.0 | The market experienced steady growth, driven by increasing demand for shipboard water treatment systems from commercial ships. |
| 2023 | 7.6 | Growth accelerated due to rising investments in shipbuilding projects in the Yangtze River Delta region. |
| 2024 | 5.4 | Growth slowed as regulatory compliance challenges affected the adoption of new technologies in the market. |
| 2025 | 7.8 | Demand surged again as commercial shipping expanded and stricter environmental regulations were enforced. |
| 2026 | 8.6 | The market peaked with substantial investments in advanced water treatment technologies and systems. |
| 2027 | 5.6 | Growth decelerated as the market adjusted to previous high levels of investment and demand. |
| 2028 | 7.3 | An increase in passenger ships drove demand for sophisticated water treatment solutions, enhancing system installations. |
| 2029 | 4.3 | Growth slowed again as market saturation began to limit new investments in technology. |
| 2030 | 8.0 | Demand rebounded with new regulations promoting advanced water treatment systems for compliance. |
| 2031 | 3.9 | Growth slowed as the market stabilised and competition intensified among suppliers in the sector. |
| 2032 | 7.2 | Demand increased again as coastal provinces invested more in shipboard water treatment infrastructure. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Shipboard Water Treatment Market Synopsis
Shipboard Water Treatment in China includes technologies that ensure water quality on vessels, such as desalination and wastewater treatment. These systems are crucial for providing potable water and managing wastewater on both commercial and military ships. The China Shipboard Water Treatment Market is expanding due to increasing domestic demand from the shipping industry and investments in advanced technologies. The Yangtze River Delta, a prominent industrial region, is a key driver of this growth, with over 1,000 commercial ships requiring these systems. Government initiatives like the 'Green Shipping Development Plan' are promoting sustainable practices within the sector.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing domestic demand from the shipping industry drives the need for advanced water treatment systems. | Driver | High | Desalination Units |
| Growing investments in shipbuilding and water treatment technologies create opportunities for suppliers. | Driver | High | Wastewater Treatment |
| The need for compliance with stricter environmental regulations presents a significant opportunity for suppliers. | Opportunity | High | Filtration Systems |
| Investment in coastal provinces for water treatment infrastructure opens new markets for technology providers. | Opportunity | Medium | Oil-Water Separators |
| High costs associated with advanced water treatment technologies may limit accessibility for smaller operators. | Restraint | High | Reverse Osmosis |
| Regulatory compliance challenges can hinder the adoption of new technologies in the market. | Restraint | Medium | Wastewater Treatment |
| Buyers face delays in project approvals due to stringent environmental regulations, impacting timelines. | Challenge | High | Filtration Systems |
| Suppliers struggle with high competition in the market, affecting pricing strategies and profitability. | Challenge | Medium | Desalination Units |
Evaluation of Drivers in China Shipboard Water Treatment Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising domestic demand for potable water on commercial vessels boosts the need for desalination units, with approximately 300 units installed in 2023. | Desalination Units | This creates a strong market for advanced water treatment systems. |
| Increased investments in shipbuilding projects in the Yangtze River Delta region are driving demand for wastewater treatment solutions. | Wastewater Treatment | This leads to higher purchases of advanced treatment technologies. |
| Stricter environmental regulations compel shipping companies to invest in filtration systems to ensure compliance, with a projected increase in demand. | Filtration Systems | This results in greater demand for effective water purification technologies. |
| The expansion of offshore vessels in the South China Sea increases the need for oil-water separators for environmental compliance, with growing installations. | Oil-Water Separators | This creates a consistent demand for reliable treatment solutions. |
| The growing passenger ship segment necessitates advanced water treatment systems to ensure safe drinking water for approximately 2,000 passengers. | Reverse Osmosis | This drives the market for dependable water purification technologies. |
Approximately 300 desalination units were installed on Chinese vessels by 2023, driving the need for advanced water treatment systems. The Yangtze River Delta has seen a surge in investments, leading to higher purchases of wastewater treatment technologies. The offshore vessel segment is also increasing the need for oil-water separators, ensuring compliance with environmental standards.
Evaluation of Restraints in China Shipboard Water Treatment Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of advanced water treatment technologies can deter smaller shipping operators from investing. | Reverse Osmosis | This limits the market size as only larger operators can afford these systems. |
| Regulatory compliance challenges can create delays in the adoption of new technologies, impacting market growth. | Wastewater Treatment | This impacts the timely implementation of necessary water treatment solutions. |
| Limited availability of skilled technicians for maintenance of advanced systems affects operational efficiency, causing delays. | Filtration Systems | This can lead to increased downtime and operational costs for ship operators. |
| Market saturation in certain regions may limit growth opportunities for new entrants, affecting competition. | Desalination Units | This creates a highly competitive environment, making it difficult for new suppliers. |
| Fluctuating raw material prices for water treatment systems can affect overall production costs, impacting profitability. | Oil-Water Separators | This impacts pricing strategies and profit margins for manufacturers. |
China Shipboard Water Treatment Market Challenges
In China, over 1,000 commercial ships require shipboard water treatment systems, yet buyers encounter rising costs due to compliance with National Standard GB/T 18920-2002, potentially increasing operational expenses by up to 15%. Regulatory pressures are mounting as stricter environmental regulations demand upgraded filtration systems, forcing importers to navigate complex compliance processes that can delay deliveries by several weeks. A shortage of skilled technicians in marine service companies hampers the effective implementation of advanced technologies, leading to inefficiencies that can result in increased downtime for vessels, costing operators substantial revenue. Competition among suppliers for limited advanced technologies raises prices, impacting buyers' budgets and operational planning.
Trends in the China Shipboard Water Treatment Market
Several trends are reshaping the China Shipboard Water Treatment Market; the most important are set out below.
- Shift Towards Advanced Filtration Systems: The 'Marine Environmental Protection Law' encourages the adoption of advanced filtration systems in the shipping industry. In 2023, demand for these systems increased, reflecting a shift towards more sustainable practices in water treatment.
- Transition from Conventional to Membrane Bioreactor Systems: A noticeable transition is occurring from conventional wastewater treatment methods to membrane bioreactor systems. With a projected CAGR of 7.9% from 2026 to 2032, this shift highlights a growing focus on efficiency and environmental compliance.
- Emergence of Smart Water Treatment Technologies: Demand for smart water treatment technologies is rising among commercial ships. In 2023, approximately 30% of new installations featured smart capabilities, underscoring a trend towards automation and data-driven management.
- Prioritisation of Environmental Compliance: Shipping companies are prioritising environmental compliance in their operations. The 'Green Shipping Development Plan' aims to promote sustainable practices, leading to increased investments in water treatment technologies.
Investment Opportunities in the China Shipboard Water Treatment Market
Several openings in the China Shipboard Water Treatment Market merit attention from investors.
- Investment in Coastal Provinces: Coastal provinces are ramping up investments in shipboard water treatment infrastructure, with funding surpassing USD 50 million in 2023. Suppliers can enter this market through local partnerships to provide advanced technologies.
- Supply of Advanced Desalination Units: The market gap for advanced desalination units is evident, with only 300 units installed by 2023. Suppliers can target commercial ships in the Yangtze River Delta to address this demand.
- Expansion of Passenger Ship Water Treatment: The growing passenger ship segment necessitates advanced water treatment solutions, with a projected increase in installations by 20% by 2026. Suppliers should focus on this market to seize new opportunities.
- Development of Wastewater Treatment Technologies: There is a strong demand for innovative wastewater treatment technologies, particularly with updated regulations. Suppliers can collaborate with marine service companies to develop tailored solutions.
Government Initiatives in the China Shipboard Water Treatment Market
The 'Marine Environmental Protection Law', updated in 2020, imposes stricter regulations on wastewater discharge from ships, compelling producers to adopt advanced treatment systems. Additionally, the 'Shipbuilding Industry Development Plan' by the Ministry of Industry and Information Technology in 2020 encourages the adoption of advanced water treatment systems in new vessels. These measures ensure that producers meet environmental standards while improving the overall quality of water treatment in the industry.
The Ministry of Ecology and Environment oversees the 'Marine Pollution Prevention Strategy', which aims to enhance water quality standards for vessels. In 2023, the government allocated funds for the 'Marine Environmental Protection Initiative' to support the development of innovative solutions. This initiative ensures compliance with environmental regulations, benefiting both producers and buyers in the market.
Future Insight of the China Shipboard Water Treatment Market
By 2032, buyers and suppliers in the China shipboard water treatment market can expect substantial advancements driven by the 'Green Shipping Development Plan' and the 'Marine Environmental Protection Initiative', which will accelerate technology adoption. Demand for filtration systems is projected to rise due to stricter environmental regulations, creating opportunities for innovative solutions. Increased investment in shipboard water treatment infrastructure across coastal provinces will support this growth, while the adoption of ISO 14001 certification by marine service companies will improve environmental management practices, promoting a more sustainable industry.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Treatment Type – Desalination Units Dominated, Wastewater Treatment Expected to Grow Fastest
According to Dhaval Chaurasia, Assistant Manager at 6Wresearch, with a 47% revenue share in 2025, Desalination Units was the largest treatment type category. Desalination units command the largest share in the China shipboard water treatment market due to their critical function in transforming seawater into potable water for vessels. With over 1,000 commercial ships requiring these systems in 2022, regions like the Yangtze River Delta showcase their importance. Wastewater Treatment is projected to grow fastest, at a CAGR of 8.6% during 2026–2032. Wastewater treatment is rapidly expanding, propelled by stricter environmental regulations that demand effective management of onboard wastewater. The 'Green Shipping Development Plan' initiated by the Chinese government in 2021 further accelerates this segment, promoting sustainable practices across the shipping sector. Suppliers should prioritise advancements in wastewater treatment technologies to meet regulatory requirements and seize emerging market opportunities.
By System Component – Reverse Osmosis Dominated, Membrane Bioreactor Expected to Grow Fastest
In 2025, Reverse Osmosis led the system component split with a 48% share. Reverse osmosis systems dominate the market due to their extensive use in purifying water on vessels, crucial for providing safe drinking water. This technology is essential for the operational efficiency of commercial ships, which account for a significant portion of the installed base. Over 2026–2032, Membrane Bioreactor is expected to post the fastest growth, at a CAGR of 7.9%. Membrane bioreactor systems are witnessing rapid growth as they become integral to advanced wastewater treatment solutions, enhancing operational efficiency. The increasing stringency of environmental regulations is expected to further accelerate the demand for these sophisticated systems. Suppliers should prioritise the development of membrane bioreactor technologies to meet regulatory demands and improve wastewater management on vessels.
By Water Source – Seawater Dominated, Gray/Black Water Expected to Grow Fastest
Seawater held a 41% share of the China Shipboard Water Treatment Market by water source in 2025. Seawater is the leading source for desalination processes, making it a critical component of shipboard water treatment systems. With China's vast coastline and a large fleet of commercial vessels, the reliance on seawater is vital for ensuring a consistent supply of potable water. Gray/Black Water is set to record the highest CAGR in this split, 7.9% over 2026–2032. Gray and black water are the fastest-growing sources for onboard wastewater treatment, as effective waste management becomes increasingly necessary before discharge. The focus on environmental sustainability initiatives will likely drive the adoption of technologies designed for treating these water sources. Suppliers need to innovate in gray and black water treatment solutions to align with environmental regulations and cater to the evolving needs of marine vessels.
By End User – Commercial Ships Dominated, Passenger Ships Expected to Grow Fastest
The largest end user category in 2025 was Commercial Ships, with a 40% share of total revenue. Commercial ships represent the largest share of the market due to their substantial demand for advanced water treatment systems to ensure compliance and safety. The shipping industry's growth in China directly correlates with the need for effective water management solutions. The quickest growth will come from Passenger Ships, forecast to expand at a CAGR of 7.5% between 2026 and 2032. Passenger ships are experiencing the fastest growth as they require advanced water treatment systems to ensure the safety and health of passengers. With an average population of around 2,000 served by these systems, the demand for high-quality water treatment is critical. Suppliers should tailor their offerings to meet the specific needs of passenger ships, focusing on safety and compliance to capture this growing market segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Shipboard Water Treatment Market Outlook
- Market Size of China Shipboard Water Treatment Market, 2025
- Forecast of China Shipboard Water Treatment Market, 2032
- Historical Data and Forecast of China Shipboard Water Treatment Revenues & Volume for the Period 2022 - 2032F
- China Shipboard Water Treatment Market Trend Evolution
- China Shipboard Water Treatment Market Drivers and Challenges
- China Shipboard Water Treatment Price Trends
- China Shipboard Water Treatment Porter's Five Forces
- China Shipboard Water Treatment Industry Life Cycle
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Treatment Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Desalination Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Wastewater Treatment for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Filtration Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Oil-Water Separators for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By System Component for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Reverse Osmosis for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Membrane Bioreactor for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By UV/Cartridge for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Bilge Water Management for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Water Source for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Seawater for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Gray/Black Water for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Potable Supply for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Engine Room Effluents for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Offshore Vessels for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Commercial Ships for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Passenger Ships for the Period 2022 - 2032F
- Historical Data and Forecast of China Shipboard Water Treatment Market Revenues & Volume By Marine Service Companies for the Period 2022 - 2032F
- China Shipboard Water Treatment Import Export Trade Statistics
- Market Opportunity Assessment By Treatment Type
- Market Opportunity Assessment By System Component
- Market Opportunity Assessment By Water Source
- Market Opportunity Assessment By End User
- China Shipboard Water Treatment Top Companies Market Share
- China Shipboard Water Treatment Competitive Benchmarking By Technical and Operational Parameters
- China Shipboard Water Treatment Company Profiles
- China Shipboard Water Treatment Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Treatment Type
- Desalination Units
- Wastewater Treatment
- Filtration Systems
- Oil-Water Separators
By System Component
- Reverse Osmosis
- Membrane Bioreactor
- UV/Cartridge
- Bilge Water Management
By Water Source
- Seawater
- Gray/Black Water
- Potable Supply
- Engine Room Effluents
By End User
- Offshore Vessels
- Commercial Ships
- Passenger Ships
- Marine Service Companies































