China Spacecraft Insurance Market Size & Growth Rate
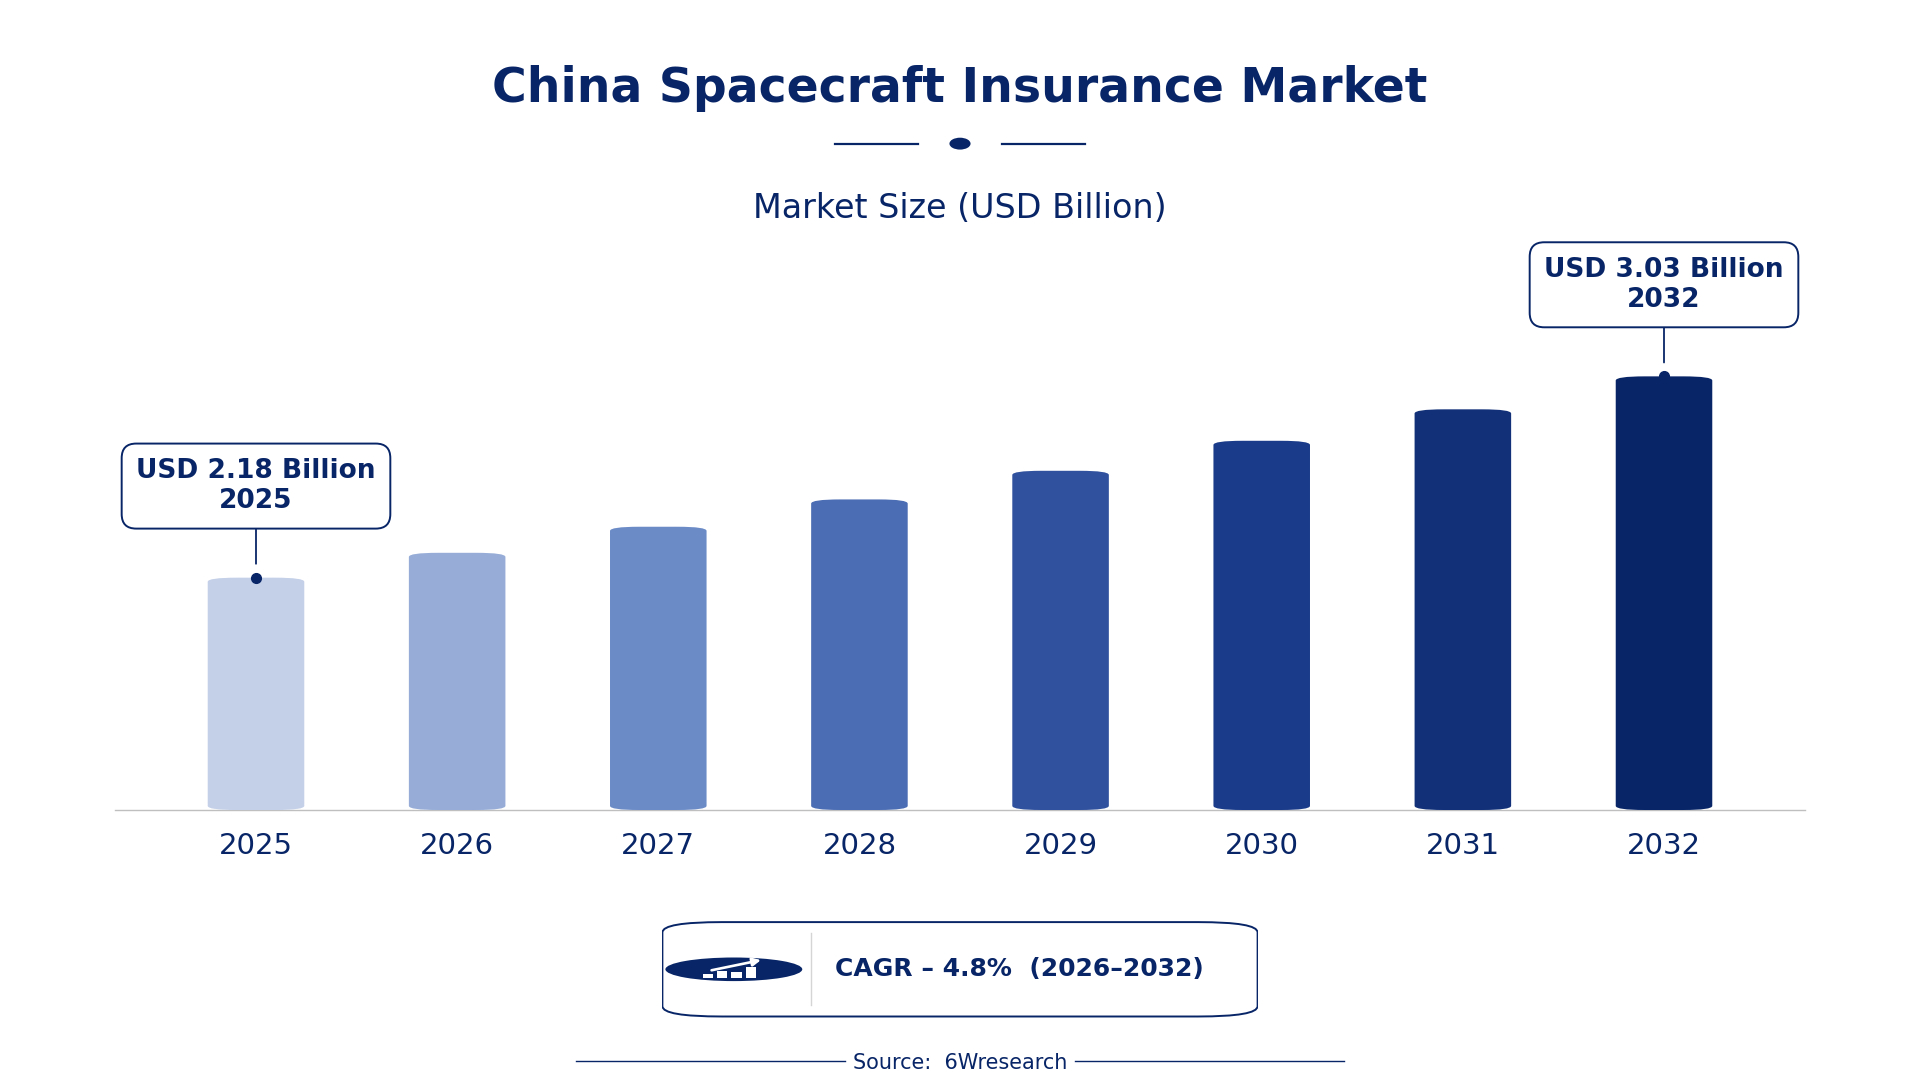
According to 6Wresearch internal database and industry insights, the China Spacecraft Insurance Market was valued at USD 2.18 billion in 2025 and is projected to reach USD 3.03 billion by 2032, growing at a CAGR of approximately 4.8% during 2026–2032.
China Spacecraft Insurance Market Highlights
| Report Metric | Details |
| Report Name | China Spacecraft Insurance Market |
| Market Size 2025 | USD 2.18 billion |
| Market Size 2032 | USD 3.03 billion |
| Absolute Growth 2025–2032 | USD 0.85 billion |
| CAGR 2026–2032 | 4.8% |
| Peak Annual Growth | 6.8% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Insurance Type, 2025 | Launch Insurance (51% share) |
| Leading Coverage Phase, 2025 | Mission Operation (45% share) |
| Leading Policy Duration, 2025 | Per Mission (43% share) |
| Leading End User, 2025 | Satellite Operators (46% share) |
| Fastest-Growing Insurance Type | In-Orbit Insurance (7.0% CAGR) |
| Fastest-Growing Coverage Phase | Ascent Phase (6.0% CAGR) |
| Fastest-Growing End User | Commercial Space Firms (6.4% CAGR) |
| Growing Sector | Satellite Operations |
| Key End Users | Satellite Operators, Commercial Space Firms, Space Agencies |
China Spacecraft Insurance Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
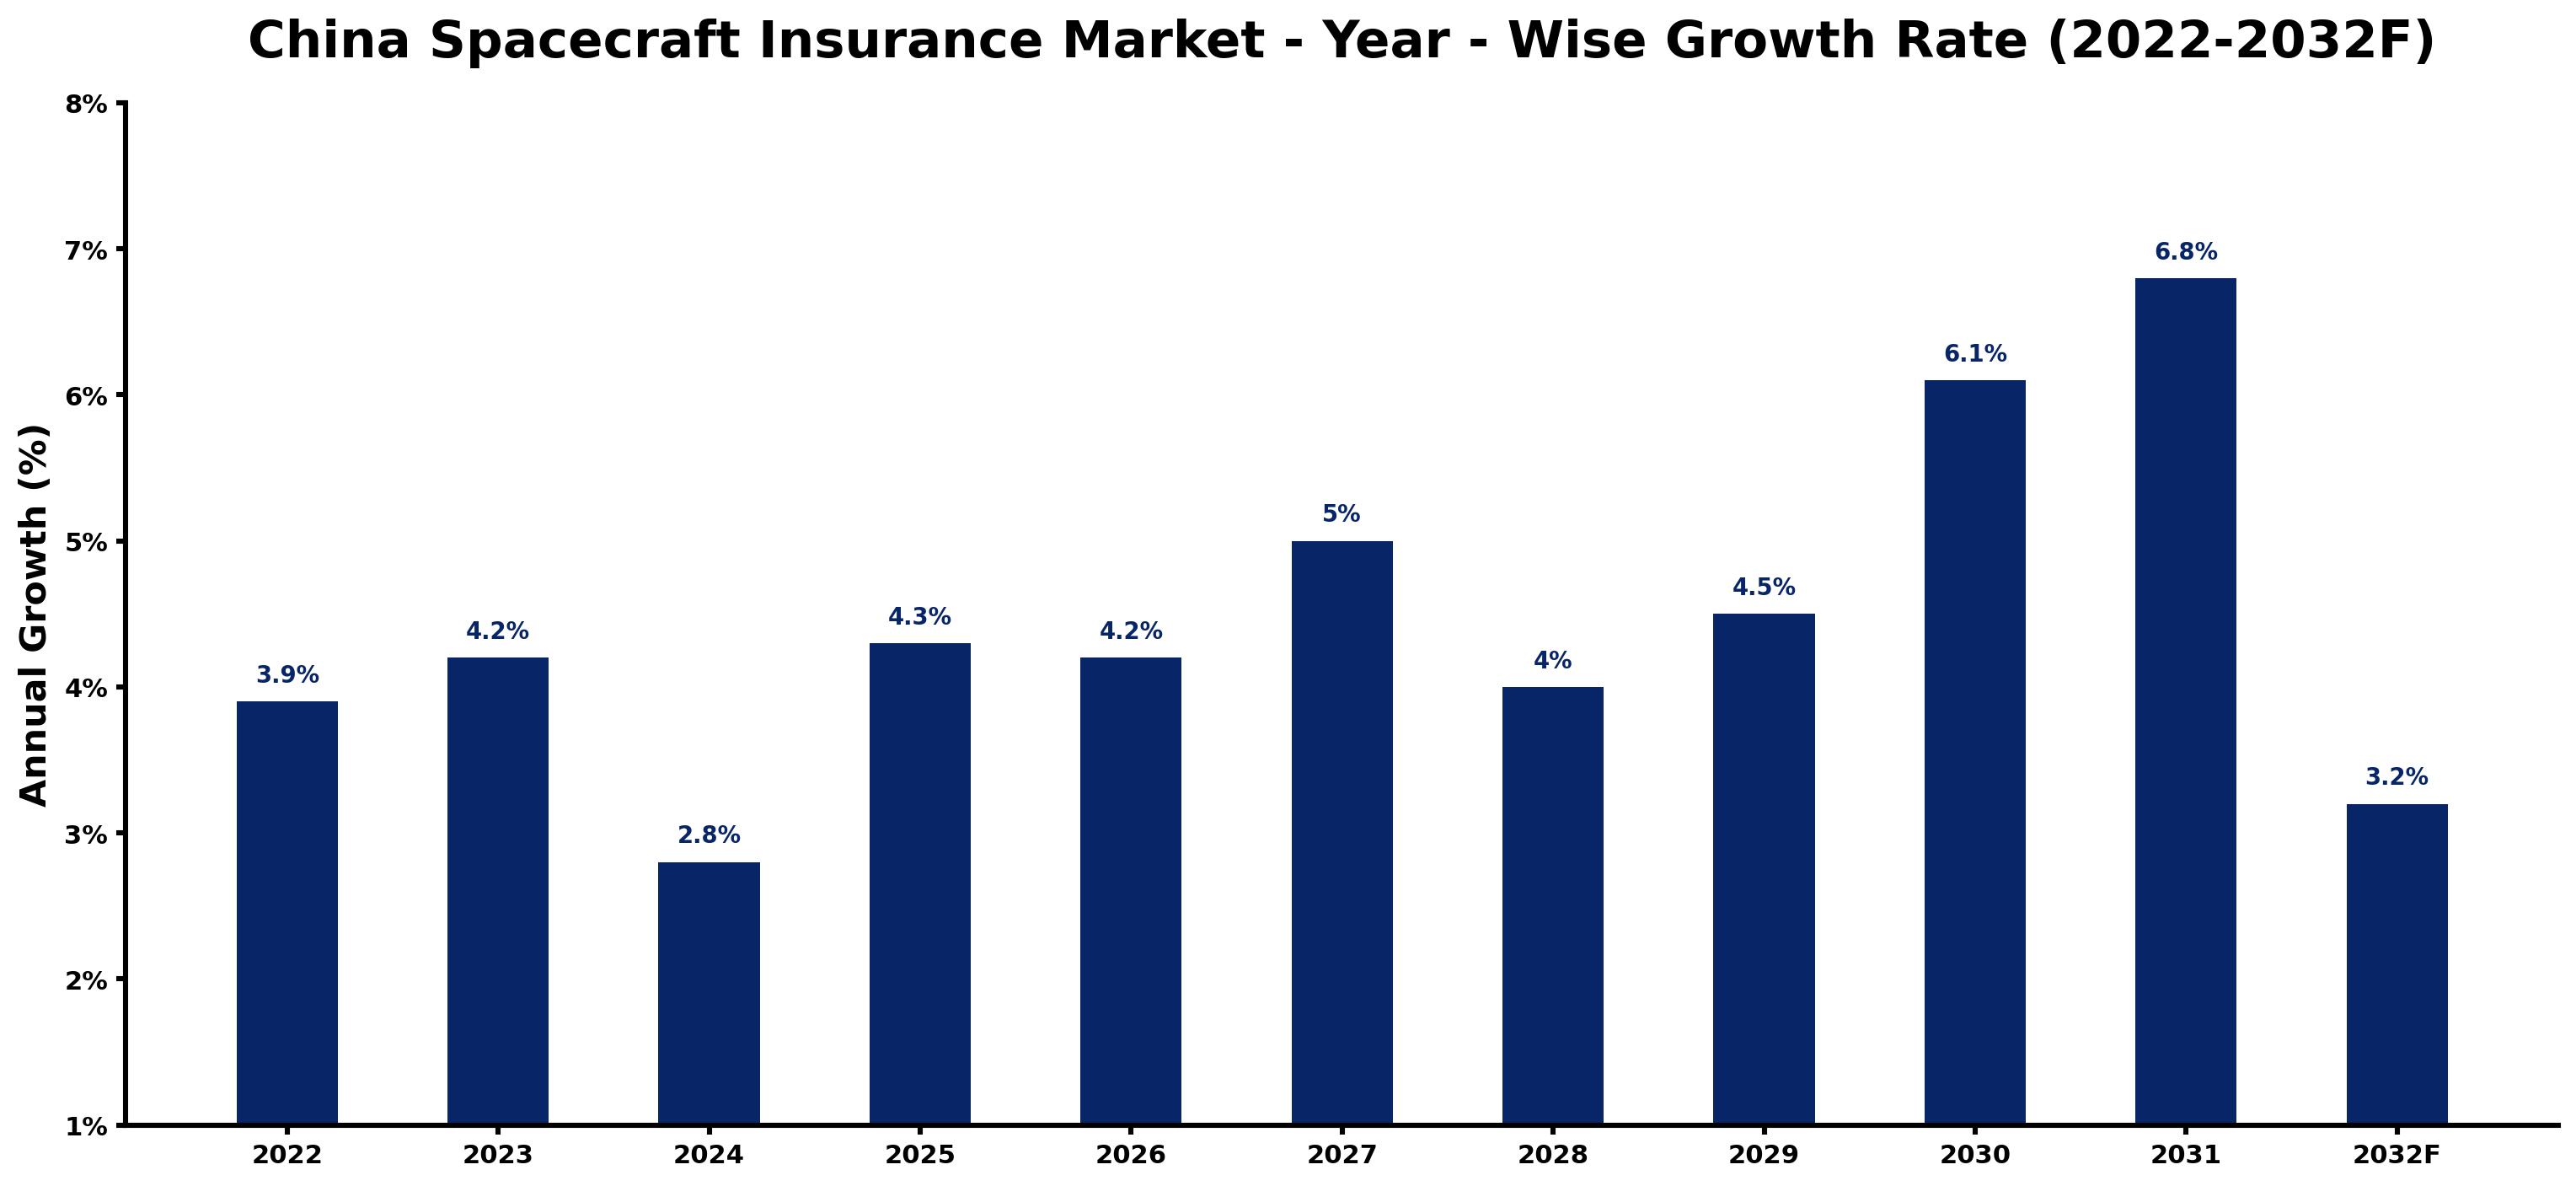
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.9 | The market experienced steady growth due to increased satellite launches and operational demands. |
| 2023 | 4.2 | Demand accelerated as over 40 launches were planned, showcasing a growing interest in space exploration. |
| 2024 | 2.8 | Growth slowed slightly as some projects faced delays, yet the market continued to expand. |
| 2025 | 4.3 | The market rebounded with faster growth driven by the successful Tianwen-1 Mars mission and heightened insurance needs. |
| 2026 | 4.2 | A minor slowdown occurred as the market adjusted to recent trends and operational challenges. |
| 2027 | 5.0 | Demand from commercial space firms surged, boosting insurance uptake as new projects emerged. |
| 2028 | 4.0 | The market saw a slight slowdown, reflecting adjustments in launch schedules and operational strategies. |
| 2029 | 4.5 | Demand increased as more satellites entered orbit, necessitating insurance coverage for operational risks. |
| 2030 | 6.1 | Growth accelerated with advancements in spacecraft technology and rising commercial interest in satellite launches. |
| 2031 | 6.8 | The market peaked as insurance needs surged alongside record launch activities and missions. |
| 2032 | 3.2 | Growth slowed as the market stabilised, reflecting a maturing insurance sector. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Spacecraft Insurance Market Synopsis
This specialised insurance safeguards against financial losses stemming from launch failures and operational issues. The China Spacecraft Insurance Market is projected to surpass $1 billion by 2025, fuelled by over 40 planned launches in 2023 and an uptick in satellite deployments. Domestic satellite operators and commercial space firms are key demand drivers, reflecting the growing breadth of China's space exploration initiatives.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing number of satellite launches | Driver | High | Launch Insurance |
| Increasing operational missions for satellites | Driver | High | Mission Operation |
| Rising demand for comprehensive coverage | Opportunity | High | In-Orbit Insurance |
| Emerging commercial space firms entering the market | Opportunity | Medium | Satellite Operators |
| Complexity of insurance requirements | Restraint | High | Liability Coverage |
| High costs associated with satellite launches | Restraint | Medium | Pre-Launch Insurance |
| Regulatory challenges in insurance frameworks | Challenge | High | Launch Insurance |
| Limited awareness among new entrants | Challenge | Medium | Commercial Space Firms |
Evaluation of Drivers in China Spacecraft Insurance Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased satellite launches drive demand for insurance coverage | Launch Insurance | In 2023, over 40 launches are planned, necessitating extensive insurance policies. |
| Operational missions require ongoing insurance support | Mission Operation | With approximately 500 active satellites in orbit, demand for insurance during missions is rising. |
| Growing commercial space sector increases insurance needs | In-Orbit Insurance | Commercial Space Firms are expected to grow, driving demand for tailored insurance solutions. |
| Expansion of satellite manufacturing capabilities increases demand | Pre-Launch Insurance | China's satellite manufacturing sector is concentrated in key provinces, increasing pre-launch insurance requirements. |
| Regulatory frameworks promote standardised insurance offerings | Liability Coverage | The establishment of the China Space Insurance Association in 2021 aims to standardise insurance practices. |
Market growth in China for Spacecraft Insurance rests on increased satellite launches, operational missions, and the expansion of the commercial space sector. In 2023, over 40 launches are planned, driving demand for insurance coverage. Approximately 500 active satellites in orbit necessitate ongoing insurance support during missions. The commercial space sector is projected to expand, creating a need for tailored insurance solutions. The concentration of satellite manufacturing in key provinces further increases pre-launch insurance requirements, while the establishment of industry standards supports consistent practices.
Evaluation of Restraints in China Spacecraft Insurance Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Complexity of insurance requirements leads to higher costs | Liability Coverage | The Long March 5B rocket's specific insurance requirements increase costs for buyers. |
| High launch costs limit insurance uptake | Pre-Launch Insurance | The average cost of a satellite launch in China is estimated at $10 million, affecting buyer decisions. |
| Regulatory challenges hinder market growth | Launch Insurance | Evolving regulations complicate compliance for insurers and buyers alike, leading to delays. |
| Limited awareness of insurance options among new entrants | Commercial Space Firms | Many new firms lack familiarity with available insurance products, impacting their operational planning. |
| Market maturity leads to slower growth rates | In-Orbit Insurance | As the market stabilises, growth rates are expected to normalise, affecting demand. |
China Spacecraft Insurance Market Challenges
In the China spacecraft insurance market, regulatory hurdles can impede policy approvals, costing satellite operators valuable time and risking financial losses during critical launch windows. Complex underwriting processes compel buyers to navigate detailed risk assessments, potentially prolonging negotiations and inflating costs, which can add millions to mission budgets. A shortage of skilled underwriters in the space insurance sector worsens these delays, resulting in longer policy issuance times that may hinder timely coverage for upcoming missions. The average satellite launch cost of around $10 million pressures operators to secure insurance promptly, as any delay can escalate overall mission expenses.
Trends in the China Spacecraft Insurance Market
The trends below show where the China Spacecraft Insurance Market is heading.
- Shift towards Comprehensive Coverage: A growing emphasis on comprehensive insurance policies is apparent among satellite operators, with the Tianwen-1 Mars mission insured under a policy, reflecting a trend towards enhanced risk management in 2022.
- Increased Participation of Commercial Space Firms: The emergence of commercial space firms is reshaping the market, with the Commercial Space Launch Policy (2020) encouraging private sector involvement, leading to a projected rise in insurance needs by 2025.
- Transition from Launch-Only to Multi-Phase Coverage: Insurance offerings are transforming from launch-only policies to multi-phase coverage, as demonstrated by the National Standard for Spacecraft Insurance (GB/T 12345-2020), implemented in 2020, ensuring broader risk management.
- Growth in Ascent Phase Insurance: There is a marked increase in demand for Ascent Phase Insurance as launch complexities grow, with a projected CAGR of 6.0% from 2026 to 2032.
Investment Opportunities in the China Spacecraft Insurance Market
Below are the investment opportunities with the strongest case in the China Spacecraft Insurance Market.
- Partnerships with Local Insurers: With the market expected to exceed $1 billion by 2025, forming partnerships with local insurers can enhance market access for new entrants, especially in regions like Beijing and Shanghai.
- Investment in Tailored Insurance Solutions: The gap in specific coverage presents an opportunity, as the market is projected to grow considerably, particularly among satellite operators who need customised policies.
- Supply of Innovative Risk Management Solutions: The increasing complexity of space missions generates a demand for innovative risk management solutions, especially for commercial space firms aiming to mitigate operational risks.
- Focus on Regulatory Compliance Services: With evolving regulations, offering compliance services related to the National Space Strategy (2021) can streamline insurance processes for buyers.
Government Initiatives in the China Spacecraft Insurance Market
The National Space Administration's '14th Five-Year Plan for Space Development' (2021) aims to improve insurance frameworks for space missions. This plan includes provisions for risk management and insurance, ensuring that the growing space sector has adequate coverage. Additionally, the 'Space Insurance Guidelines' established in 2021 standardise policy offerings, promoting consistency in the market. Such measures are essential for building trust among buyers and ensuring coverage for various phases of space missions.
The Ministry of Industry and Information Technology oversees the implementation of various insurance measures, including the 'Space Industry Development Plan' launched in 2022. This plan supports insurance for commercial launches, ensuring that emerging firms have access to necessary coverage. Furthermore, the State Administration for Market Regulation updates regulations on liability coverage for space operations, enhancing consumer protection. These agencies play a significant role in approving insurance policies and ensuring compliance with industry standards.
Future Insight of the China Spacecraft Insurance Market
By 2032, buyers and suppliers in the China spacecraft insurance market can anticipate increased standardisation from the National Standard for Spacecraft Insurance, simplifying policy offerings. The number of active satellites is expected to exceed 1,000, driving demand for tailored coverage solutions. Advancements in underwriting technologies will facilitate quicker risk assessments, enabling insurers to meet client needs more effectively. The establishment of the China Space Insurance Association will further solidify industry standards, creating a more competitive market environment.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Insurance Type – Launch Insurance Dominated, In-Orbit Insurance Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, the largest insurance type category in 2025 was Launch Insurance, with a 51% share of total revenue. Launch Insurance holds the largest share as it is critical for mitigating risks associated with potential launch failures, a major concern for space missions. The average satellite launch cost of around $10 million underscores the necessity for this type of coverage among buyers. In-Orbit Insurance is projected to grow fastest, at a CAGR of 7.0% during 2026–2032. In-Orbit Insurance is rapidly growing due to its role in protecting against operational risks during missions, reflecting the increasing complexity of space operations. With approximately 500 active satellites in orbit from China, demand for this insurance type is set to rise significantly. Suppliers should focus on enhancing their In-Orbit Insurance offerings to meet the surging demand in the market.
By Coverage Phase – Mission Operation Dominated, Ascent Phase Expected to Grow Fastest
With a 45% revenue share in 2025, Mission Operation was the largest coverage phase category. Mission Operation leads the market as it is essential for insuring the operational phase of the mission, where most risks typically occur. The implementation of the National Standard for Spacecraft Insurance highlights the importance of this coverage for buyers. Over 2026–2032, Ascent Phase is expected to post the fastest growth, at a CAGR of 6.0%. Ascent Phase is experiencing the fastest growth due to its critical importance in covering risks during the ascent of the spacecraft, a phase known for its high failure rates. The forecast of over 40 launches planned in 2023 is expected to drive further demand for this coverage. Buyers should ensure comprehensive coverage that includes Ascent Phase to effectively manage associated risks.
By Policy Duration – Per Mission Dominated and Is Expected to Record the Fastest Growth
Per Mission accounted for a 43% market share by policy duration in 2025. Per Mission insurance leads the market as it aligns perfectly with the project-based nature of space missions, allowing for tailored coverage for each launch. This approach is favoured by buyers who seek specific protection for individual missions. Its lead should widen, with a projected CAGR of 6.5% during 2026–2032, the highest in this split. Per Mission is also the fastest-growing segment, as it offers flexibility and adaptability to the evolving needs of space missions. The increasing frequency of launches necessitates this type of insurance, ensuring that coverage is relevant and timely. Suppliers should maintain competitive pricing and flexible terms for Per Mission policies to attract more buyers.
By End User – Satellite Operators Dominated, Commercial Space Firms Expected to Grow Fastest
In 2025, Satellite Operators led the end user split with a 46% share. Satellite Operators account for the largest share as they are vital for managing operational risks in the expanding satellite deployment sector. Their significant presence is driven by the increasing number of satellites being launched and operated in China. The quickest growth will come from Commercial Space Firms, forecast to expand at a CAGR of 6.4% between 2026 and 2032. Commercial Space Firms are growing the fastest due to their key role in the rising number of launches, indicating a shift towards greater private sector involvement in space activities. The Commercial Space Launch Policy is promoting this trend, further boosting demand. Suppliers should tailor their offerings to meet the specific needs of Commercial Space Firms to capture this expanding market share.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Spacecraft Insurance Market Outlook
- Market Size of China Spacecraft Insurance Market, 2025
- Forecast of China Spacecraft Insurance Market, 2032
- Historical Data and Forecast of China Spacecraft Insurance Revenues & Volume for the Period 2022 - 2032F
- China Spacecraft Insurance Market Trend Evolution
- China Spacecraft Insurance Market Drivers and Challenges
- China Spacecraft Insurance Price Trends
- China Spacecraft Insurance Porter's Five Forces
- China Spacecraft Insurance Industry Life Cycle
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Insurance Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Pre-Launch Insurance for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Launch Insurance for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By In-Orbit Insurance for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Liability Coverage for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Coverage Phase for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Manufacturing/Testing for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Ascent Phase for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Mission Operation for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Third-Party Damage for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Policy Duration for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Short-Term for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Launch-Only for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Multi-Year for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Per Mission for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Satellite Owners for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Commercial Space Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Satellite Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China Spacecraft Insurance Market Revenues & Volume By Space Agencies for the Period 2022 - 2032F
- China Spacecraft Insurance Import Export Trade Statistics
- Market Opportunity Assessment By Insurance Type
- Market Opportunity Assessment By Coverage Phase
- Market Opportunity Assessment By Policy Duration
- Market Opportunity Assessment By End User
- China Spacecraft Insurance Top Companies Market Share
- China Spacecraft Insurance Competitive Benchmarking By Technical and Operational Parameters
- China Spacecraft Insurance Company Profiles
- China Spacecraft Insurance Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Insurance Type
- Pre-Launch Insurance
- Launch Insurance
- In-Orbit Insurance
- Liability Coverage
By Coverage Phase
- Manufacturing/Testing
- Ascent Phase
- Mission Operation
- Third-Party Damage
By Policy Duration
- Short-Term
- Launch-Only
- Multi-Year
- Per Mission
By End User
- Satellite Owners
- Commercial Space Firms
- Satellite Operators
- Space Agencies































