China Spark Ignition System Market Size & Growth Rate
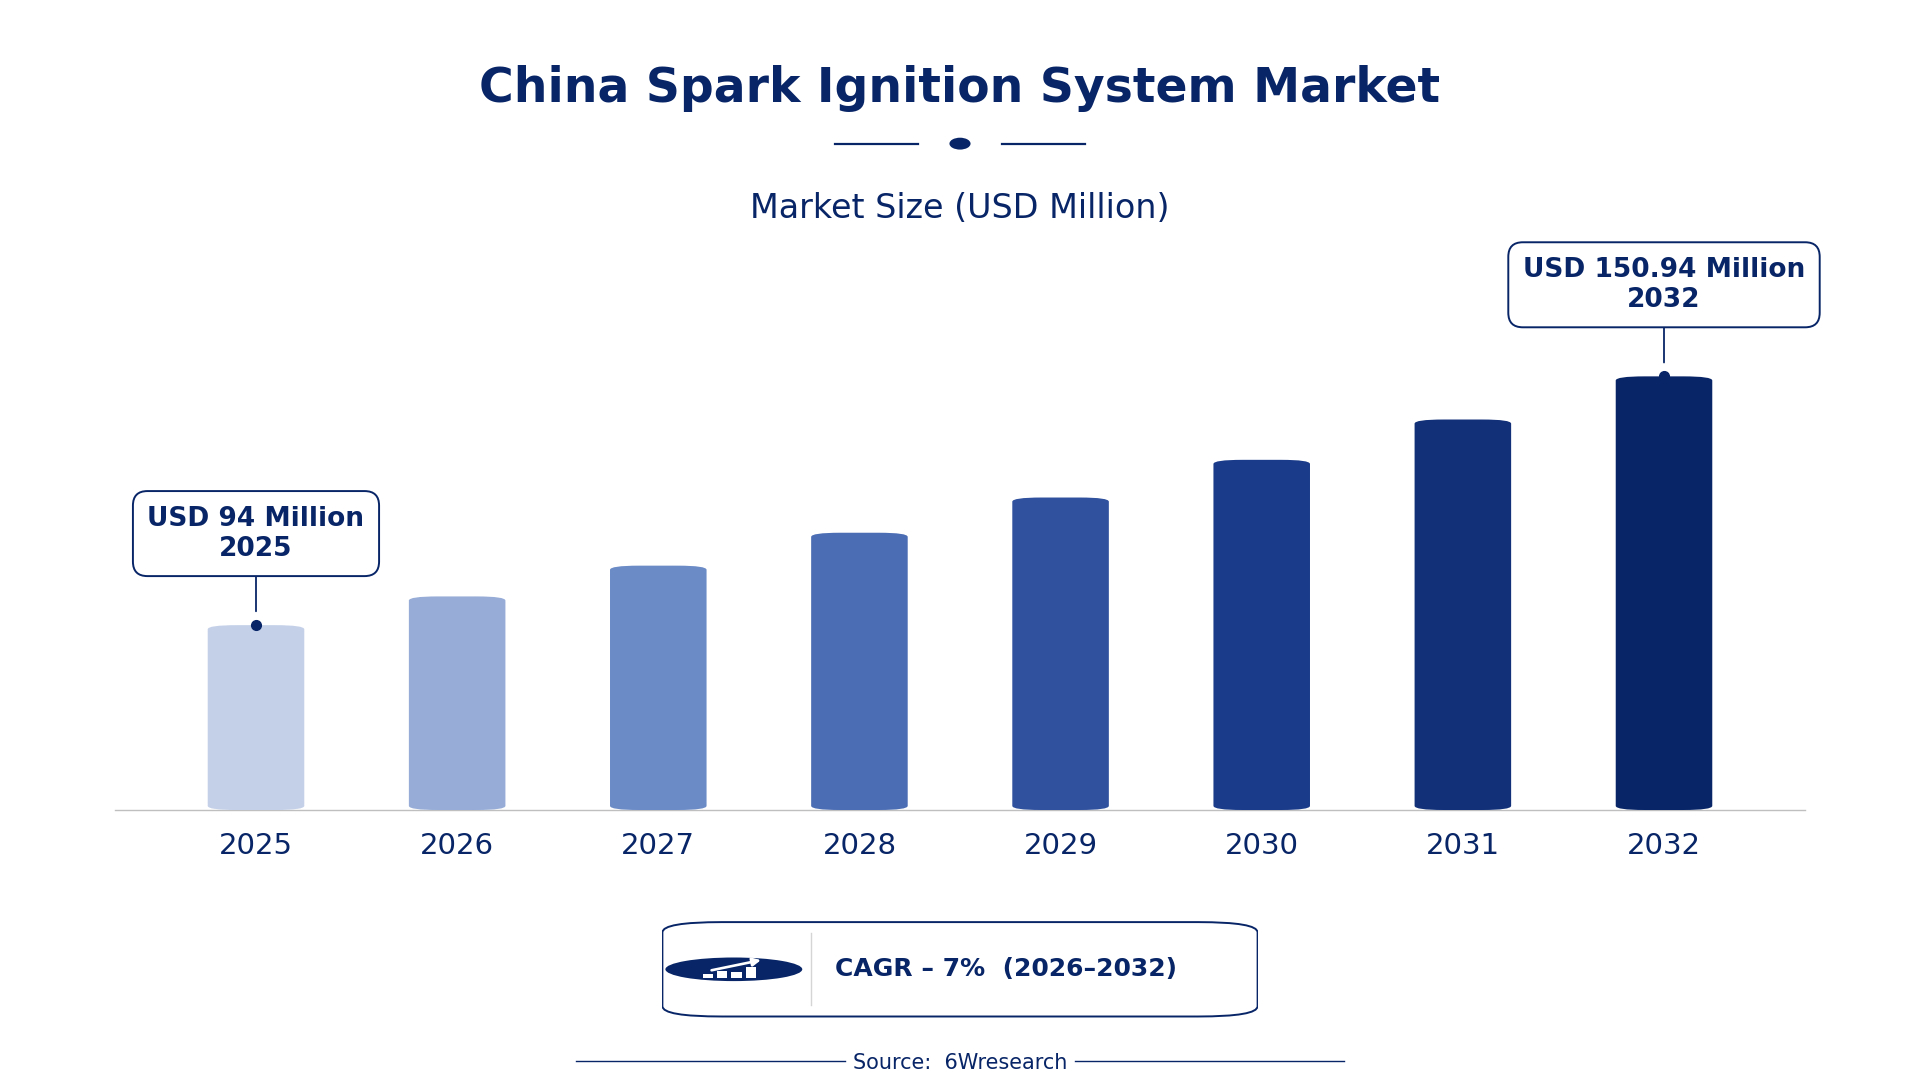
According to 6Wresearch internal database and industry insights, the China Spark Ignition System Market was valued at USD 94.0 million in 2025 and is projected to reach USD 150.94 million by 2032, growing at a CAGR of approximately 7% during 2026–2032.
China Spark Ignition System Market Highlights
| Report Metric | Details |
| Report Name | China Spark Ignition System Market |
| Market Size 2025 | USD 94.0 million |
| Market Size 2032 | USD 150.94 million |
| Absolute Growth 2025–2032 | USD 56.94 million |
| CAGR 2026–2032 | 7% |
| Peak Annual Growth | 8.8% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading System Type, 2025 | Coil-On-Plug (COP) (45% share) |
| Leading Fuel Compatibility, 2025 | Petrol/Gasoline (39% share) |
| Leading Cylinder Configuration, 2025 | Multi-Cylinder (46% share) |
| Leading End User, 2025 | Car OEMs (41% share) |
| Fastest-Growing System Type | Digital Ignition (8.6% CAGR) |
| Fastest-Growing Fuel Compatibility | LPG/CNG (9.5% CAGR) |
| Fastest-Growing Cylinder Configuration | Variable Timing (8.9% CAGR) |
| Fastest-Growing End User | Fleet Operators (8.1% CAGR) |
| Growing Sector | automotive |
| Key End Users | Car OEMs, Fleet Operators, Performance Car Makers, Motorcycles/Boats |
China Spark Ignition System Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
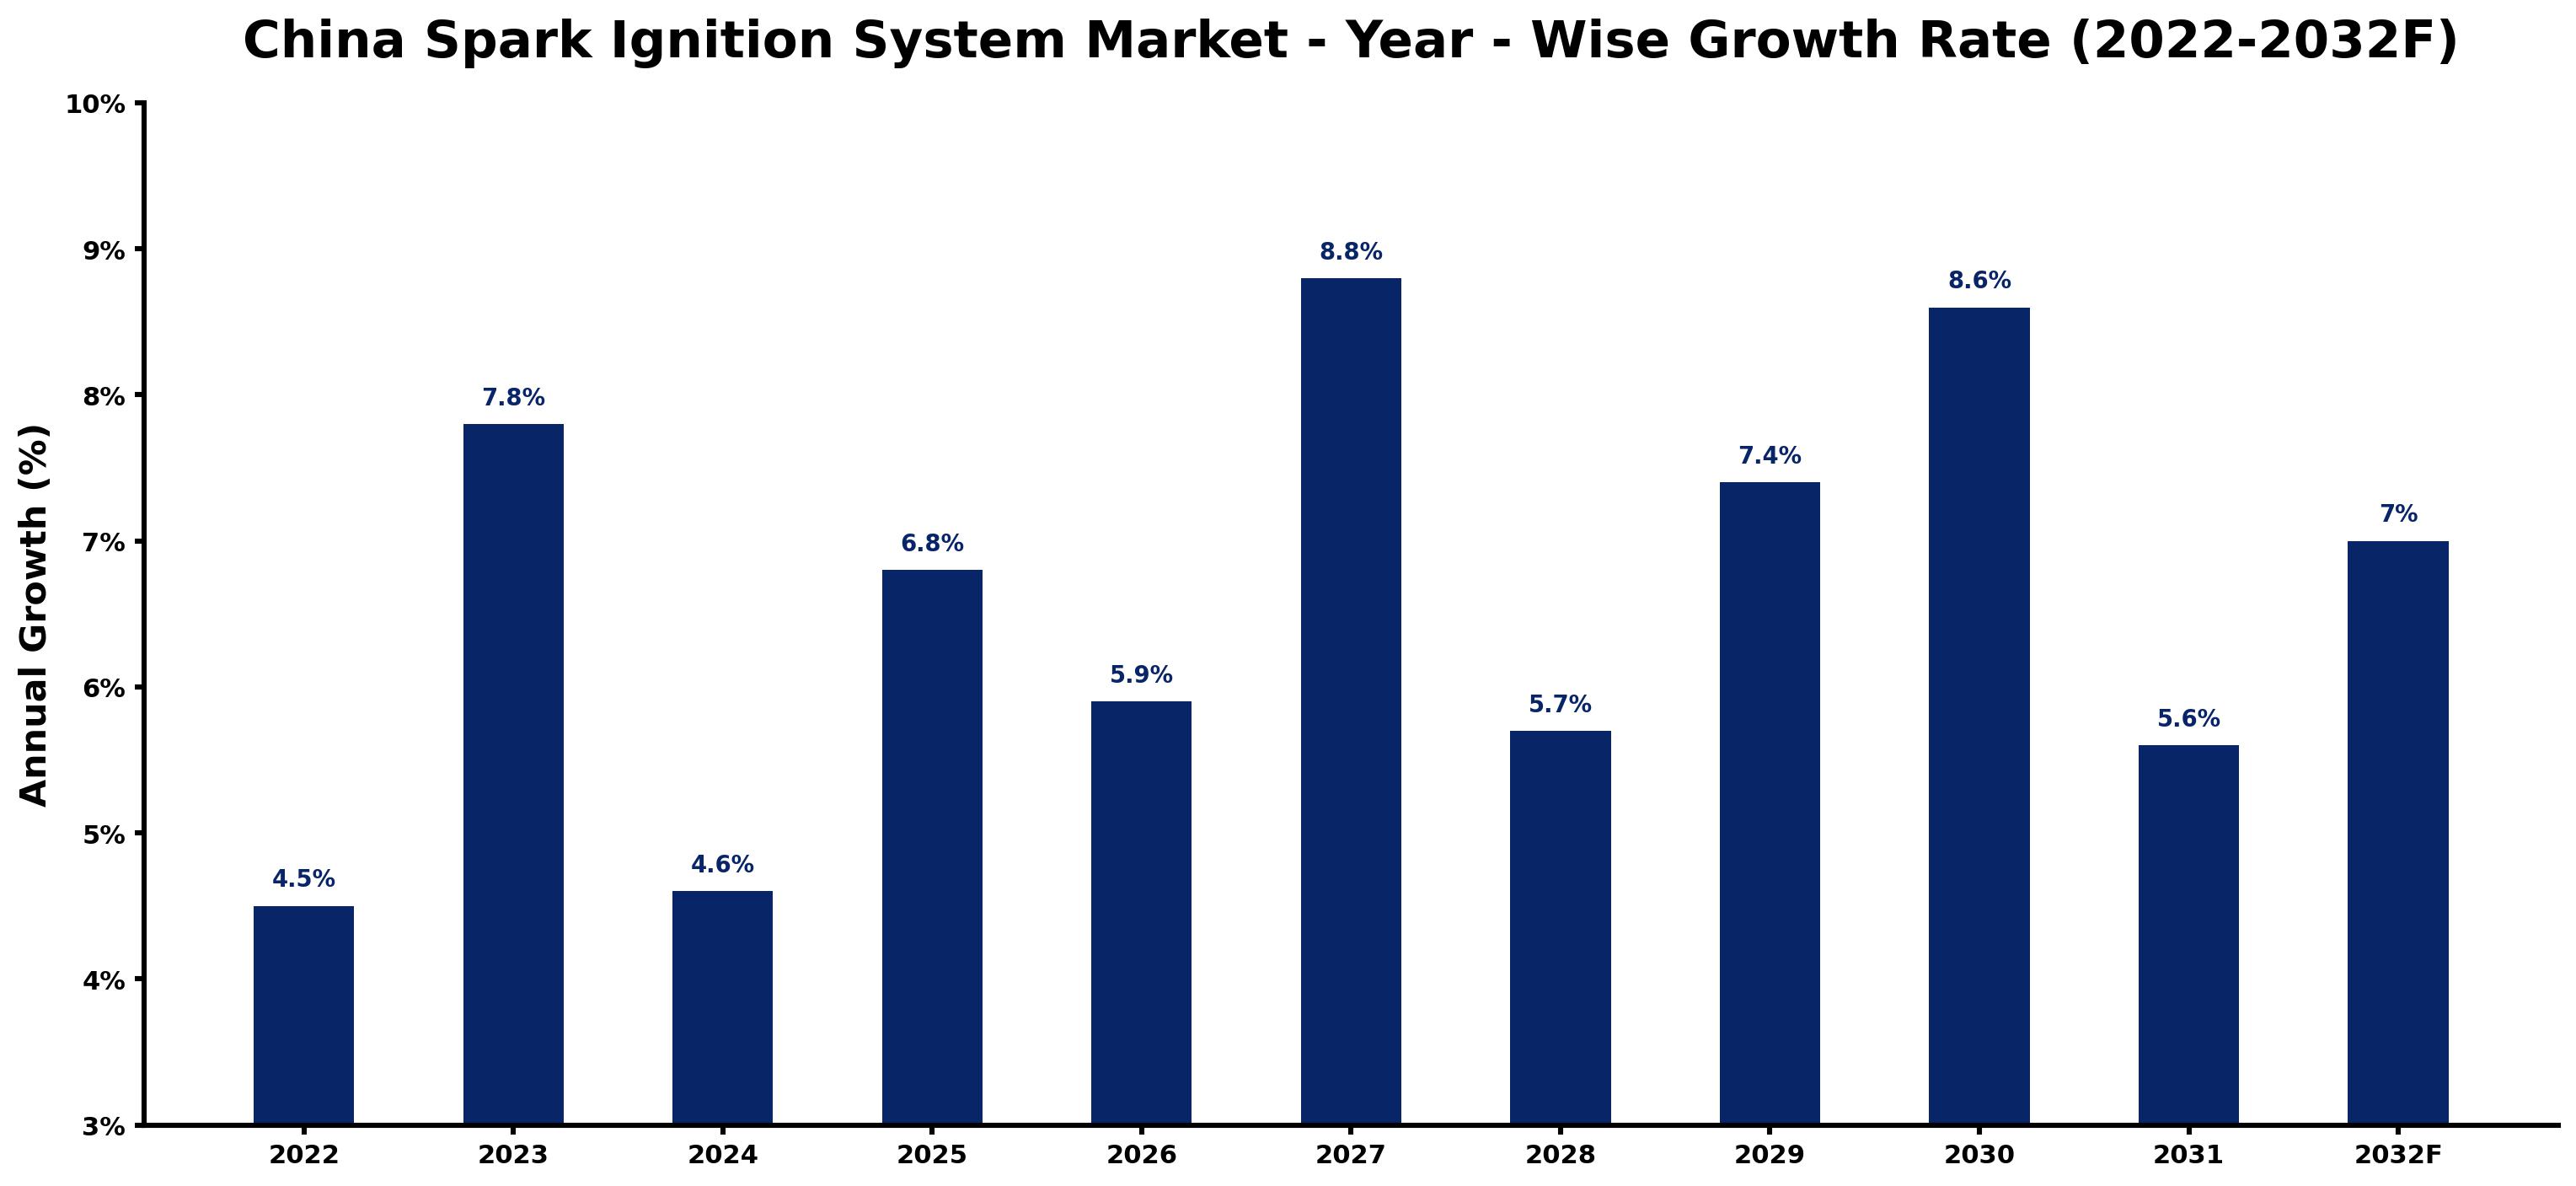
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.5 | Demand remained steady as the automotive sector continued to operate effectively. |
| 2023 | 7.8 | Vehicle production surged, contributing to a notable increase in ignition system demand. |
| 2024 | 4.6 | Growth slowed slightly as the market adjusted to previous highs in production. |
| 2025 | 6.8 | A resurgence in vehicle manufacturing boosted demand for ignition systems significantly due to the Automotive Industry Development Plan. |
| 2026 | 5.9 | The market is expected to experience a slowdown as competition intensifies among manufacturers. |
| 2027 | 8.8 | A peak in demand is projected due to rising production rates and new vehicle launches. |
| 2028 | 5.7 | Growth is anticipated to decelerate as the market begins to stabilise after the previous peak. |
| 2029 | 7.4 | Increased vehicle production will lead to renewed demand for ignition systems. |
| 2030 | 8.6 | A rise in high-performance vehicle production is expected to spur further demand for advanced systems. |
| 2031 | 5.6 | Market growth will slow as manufacturers focus on efficiency and cost reduction. |
| 2032 | 7.0 | Demand is projected to rise again as new standards and technologies are adopted. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Spark Ignition System Market Synopsis
The Spark Ignition System Market in China covers technologies that ignite air-fuel mixtures in internal combustion engines. These systems are primarily made from copper, plastics, and ceramics, and are essential in automotive engines and motorcycles. The market is growing due to the automotive industry's expansion, with over 25 million vehicles produced in 2022. Key regions like Shanghai and Guangdong drive this demand, while government initiatives promote cleaner technologies. This growth reflects substantial investment and innovation in the sector.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased vehicle production in key regions drives demand for ignition systems. | Driver | High | Car OEMs |
| The shift towards high-performance vehicles creates a demand for advanced ignition technologies. | Driver | High | Performance Car Makers |
| The automotive aftermarket is expanding, focusing on ignition system upgrades. | Opportunity | High | Fleet Operators |
| The growth of electric vehicles presents opportunities for ignition system innovations. | Opportunity | Medium | Car OEMs |
| Intense competition among manufacturers limits pricing power. | Restraint | High | Digital Ignition |
| Transition to alternative fuels may reduce demand for traditional ignition systems. | Restraint | Medium | Petrol/Gasoline |
| Supply chain disruptions can delay production and delivery of ignition systems. | Challenge | High | Coil-On-Plug (COP) |
| Regulatory changes may require costly adaptations for compliance. | Challenge | Medium | Distributor-Based |
Evaluation of Drivers in China Spark Ignition System Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Surge in vehicle production drives demand for spark ignition systems. | Car OEMs | China produced over 25 million vehicles in 2022, increasing the need for ignition systems. |
| Growth of high-performance vehicles boosts demand for advanced ignition technologies. | Performance Car Makers | The automotive sector is projected to reach a market size of 7 trillion yuan by 2025. |
| Expansion of the automotive aftermarket increases demand for ignition system upgrades. | Fleet Operators | The installed base of vehicles in China surpassed 300 million units in 2023. |
| Government initiatives support cleaner technologies, influencing ignition system designs. | Car OEMs | The 'New Energy Vehicle Development Plan' was launched in 2023. |
| Rising demand for motorcycles and small engines drives ignition system sales. | Motorcycles/Boats | The automotive industry in China employs over 5 million people, highlighting its significance. |
The Spark Ignition System market in China is expanding as vehicle production surges, high-performance vehicle demand rises, and aftermarket upgrades increase. In 2022, over 25 million vehicles were produced, intensifying the need for ignition systems. The automotive sector is projected to reach a market size of 7 trillion yuan by 2025, further driving demand. The installed base of vehicles surpassed 300 million units in 2023, creating a strong aftermarket for ignition system upgrades.
Evaluation of Restraints in China Spark Ignition System Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Intense competition among manufacturers limits pricing power. | Digital Ignition | As more players enter the market, profit margins are pressured, affecting suppliers. |
| Transition to alternative fuels may reduce demand for traditional ignition systems. | Petrol/Gasoline | The rise of electric vehicles is shifting focus away from conventional systems. |
| Regulatory changes may require costly adaptations for compliance. | Distributor-Based | New emission standards necessitate updates in ignition technology, impacting production costs. |
| Supply chain disruptions can delay production and delivery of ignition systems. | Coil-On-Plug (COP) | Global supply chain issues have affected the availability of key materials. |
| Market saturation in certain segments may limit growth opportunities. | Magneto Ignition | With limited applications, growth in this segment is constrained. |
China Spark Ignition System Market Challenges
The China Spark Ignition System Market faces several practical problems, starting with producers who grapple with outdated technology. Many manufacturers still rely on traditional ignition designs that do not meet modern efficiency standards, resulting in production costs increasing by up to 15% and reducing competitiveness. Regulatory hurdles also impede progress, as adherence to the national standard GB/T 18655-2020 can delay product launches, impacting market entry for new players and costing them valuable time. Competition remains intense, with numerous domestic and foreign firms vying for market share, forcing local producers to lower prices and squeeze profit margins by nearly 10%. Supply chain disruptions in sourcing quality materials like copper and ceramics can cause production delays, affecting timely delivery to buyers in the automotive sector who rely on just-in-time inventory.
Trends in the China Spark Ignition System Market
Below mentioned are some of the trends shaping the China Spark Ignition System Market growth.
- Shift from Traditional to Digital Ignition Systems: Car OEMs are increasingly adopting digital ignition systems to improve performance and efficiency. This trend began in 2023, with a projected CAGR of 8.6% for digital ignition systems through 2032.
- Transition to Cleaner Fuel Technologies: The automotive industry is moving towards cleaner fuel technologies, impacting ignition system designs. The 'Green Transport Development Strategy' initiated in 2022 aims to promote alternative fuels.
- Emergence of Advanced Ignition Systems: Performance car makers are prioritising advanced ignition systems to meet rising consumer expectations. This shift started in 2023, with a projected growth rate of 8.1% for fleet operators demanding these systems.
- Growth in the Aftermarket for Ignition Systems: The aftermarket for ignition systems is expanding as vehicle ownership increases. In 2023, the installed base of vehicles surpassed 300 million units, driving demand for upgrades.
Investment Opportunities in the China Spark Ignition System Market
Several openings in the China Spark Ignition System Market merit attention from investors.
- Automotive Manufacturing Hubs: Shanghai and Guangdong are key regions for automotive manufacturing, presenting opportunities for ignition system suppliers. With over 25 million vehicles produced in 2022, local partnerships can facilitate market entry.
- Joint Ventures for Technology Development: Now is an ideal time for joint ventures to develop advanced ignition technologies. The 'Made in China 2025' initiative encourages innovation in automotive technology, creating investment opportunities.
- Focus on Electric Vehicle Components: The rise of electric vehicles creates a need for innovative ignition system solutions. Suppliers can target car OEMs looking to comply with new energy vehicle standards.
- Expansion of the Aftermarket: The growing automotive aftermarket presents opportunities for ignition system upgrades. Suppliers can enter by collaborating with fleet operators, capitalising on the installed base of over 300 million vehicles.
Government Initiatives in the China Spark Ignition System Market
The 'Automotive Industry Development Plan (2021-2025)' launched by the Ministry of Industry and Information Technology aims to promote innovation and efficiency in vehicle technologies. This plan encourages manufacturers to invest in advanced ignition systems and improve overall vehicle performance. By focusing on innovation, the government supports the automotive sector's growth and competitiveness in the global market. Additionally, the plan outlines strategies for reducing emissions, which directly influences ignition system designs and applications. The State Council approved the 'New Energy Vehicle Development Plan' in 2022, aiming for 20% of vehicles to be electric or hybrid by 2025, affecting ignition technology.
In 2023, the National Development and Reform Commission implemented the 'Emission Standards for Light-duty Vehicles', which aims to reduce pollutants from vehicles. This regulation requires manufacturers to adapt their ignition systems to meet stricter emissions criteria. The Ministry of Ecology and Environment also introduced the 'Air Pollution Prevention and Control Action Plan' in 2020, promoting cleaner fuel technologies in vehicles. These measures ensure that producers must comply with new standards, impacting their production processes and costs. The Ministry of Transport initiated the 'Green Transport Development Strategy' in 2022 to encourage the adoption of alternative fuels, influencing ignition system applications.
Future Insight of the China Spark Ignition System Market
The China Spark Ignition System Market is set to evolve significantly by 2032, driven by several key factors. The push for electric and hybrid vehicles, backed by the government's 'New Energy Vehicle Industry Development Plan', will transform ignition system designs for cleaner technologies. The automotive aftermarket will expand, concentrating on ignition system upgrades to improve vehicle performance and reliability. The 'Made in China 2025' initiative will stimulate advancements in automotive technology, fostering innovation in ignition systems. By 2025, the automotive sector is expected to reach a market size of 7 trillion yuan, presenting substantial growth opportunities for suppliers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By System Type – Coil-On-Plug (COP) Dominated, Digital Ignition Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, Coil-On-Plug (COP) took a 45% share of system type in 2025, more than any other category. The Coil-On-Plug (COP) system holds the largest market share due to its widespread use in modern engines, which enhances efficiency and performance. This technology is essential for manufacturers in major automotive hubs like Shanghai and Guangdong, where vehicle production is substantial. Digital Ignition is projected to grow fastest, at a CAGR of 8.6% during 2026–2032. Digital Ignition is experiencing rapid growth as it becomes increasingly popular in high-performance vehicles, reflecting the industry's shift towards advanced ignition technologies. With the automotive sector projected to reach a market size of 7 trillion yuan by 2025, this trend is expected to maintain momentum. Suppliers should focus on developing advanced ignition systems to meet the rising demand from automotive manufacturers.
By Fuel Compatibility – Petrol/Gasoline Dominated, LPG/CNG Expected to Grow Fastest
The largest fuel compatibility category in 2025 was Petrol/Gasoline, with a 39% share of total revenue. Petrol/Gasoline dominates the market share as the primary fuel type for vehicles in China, driven by the extensive installed base of over 300 million vehicles. This fuel type is integral to the operations of car OEMs, who rely on it for the majority of their production. Over 2026–2032, LPG/CNG is expected to post the fastest growth, at a CAGR of 9.5%. LPG/CNG is emerging as the fastest-growing segment due to the increasing interest in alternative fuels and government initiatives promoting cleaner technologies. The 'New Energy Vehicle Industry Development Plan' launched in 2023 is expected to accelerate this growth. Buyers should consider diversifying their fuel options to include LPG/CNG, aligning with environmental regulations and market trends.
By Cylinder Configuration – Multi-Cylinder Dominated, Variable Timing Expected to Grow Fastest
Multi-Cylinder held a 46% share of the China Spark Ignition System Market by cylinder configuration in 2025. Multi-Cylinder configurations command the largest market share as they are standard in most modern vehicles, delivering superior performance and efficiency. The production of over 25 million vehicles in 2022 underscores the dominance of multi-cylinder engines in the automotive landscape. The quickest growth will come from Variable Timing, forecast to expand at a CAGR of 8.9% between 2026 and 2032. Variable Timing is the fastest-growing configuration, as it significantly enhances engine performance and efficiency in contemporary designs. The automotive industry's transition towards advanced technologies is a crucial factor driving this growth. Suppliers need to invest in technologies that improve variable timing systems to take advantage of the increasing demand for high-performance engines.
By End User – Car OEMs Dominated, Fleet Operators Expected to Grow Fastest
Car OEMs accounted for a 41% market share by end user in 2025. Car OEMs hold the largest market share, being the primary users of spark ignition systems essential for vehicle production. Their critical role is highlighted by the automotive industry employing over 5 million people, underscoring its economic significance. Fleet Operators are set to record the highest CAGR in this split, 8.1% over 2026–2032. Fleet Operators represent the fastest-growing segment, driven by the increasing demand for commercial vehicles that necessitate reliable ignition systems. The anticipated growth in the automotive aftermarket further reinforces this trend. Suppliers should customise their offerings to meet the specific requirements of fleet operators, ensuring compatibility and reliability in their ignition systems.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Spark Ignition System Market Outlook
- Market Size of China Spark Ignition System Market, 2025
- Forecast of China Spark Ignition System Market, 2032
- Historical Data and Forecast of China Spark Ignition System Revenues & Volume for the Period 2022 - 2032F
- China Spark Ignition System Market Trend Evolution
- China Spark Ignition System Market Drivers and Challenges
- China Spark Ignition System Price Trends
- China Spark Ignition System Porter's Five Forces
- China Spark Ignition System Industry Life Cycle
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By System Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By Coil-On-Plug (COP) for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By Distributor-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By Magneto Ignition for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By Digital Ignition for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By Fuel Compatibility for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By Petrol/Gasoline for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By LPG/CNG for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By Ethanol for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By Flex Fuel for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By Cylinder Configuration for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By Multi-Cylinder for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By 2 6 Cylinders for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By Single-Cylinder for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By Variable Timing for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By Car OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By Fleet Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By Motorcycles/Boats for the Period 2022 - 2032F
- Historical Data and Forecast of China Spark Ignition System Market Revenues & Volume By Performance Car Makers for the Period 2022 - 2032F
- China Spark Ignition System Import Export Trade Statistics
- Market Opportunity Assessment By System Type
- Market Opportunity Assessment By Fuel Compatibility
- Market Opportunity Assessment By Cylinder Configuration
- Market Opportunity Assessment By End User
- China Spark Ignition System Top Companies Market Share
- China Spark Ignition System Competitive Benchmarking By Technical and Operational Parameters
- China Spark Ignition System Company Profiles
- China Spark Ignition System Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By System Type
- Coil-On-Plug (COP)
- Distributor-Based
- Magneto Ignition
- Digital Ignition
By Fuel Compatibility
- Petrol/Gasoline
- LPG/CNG
- Ethanol
- Flex Fuel
By Cylinder Configuration
- Multi-Cylinder
- 2–6 Cylinders
- Single-Cylinder
- Variable Timing
By End User
- Car OEMs
- Fleet Operators
- Motorcycles/Boats
- Performance Car Makers































