China Specialty Chemical Catalyst Market Size & Growth Rate
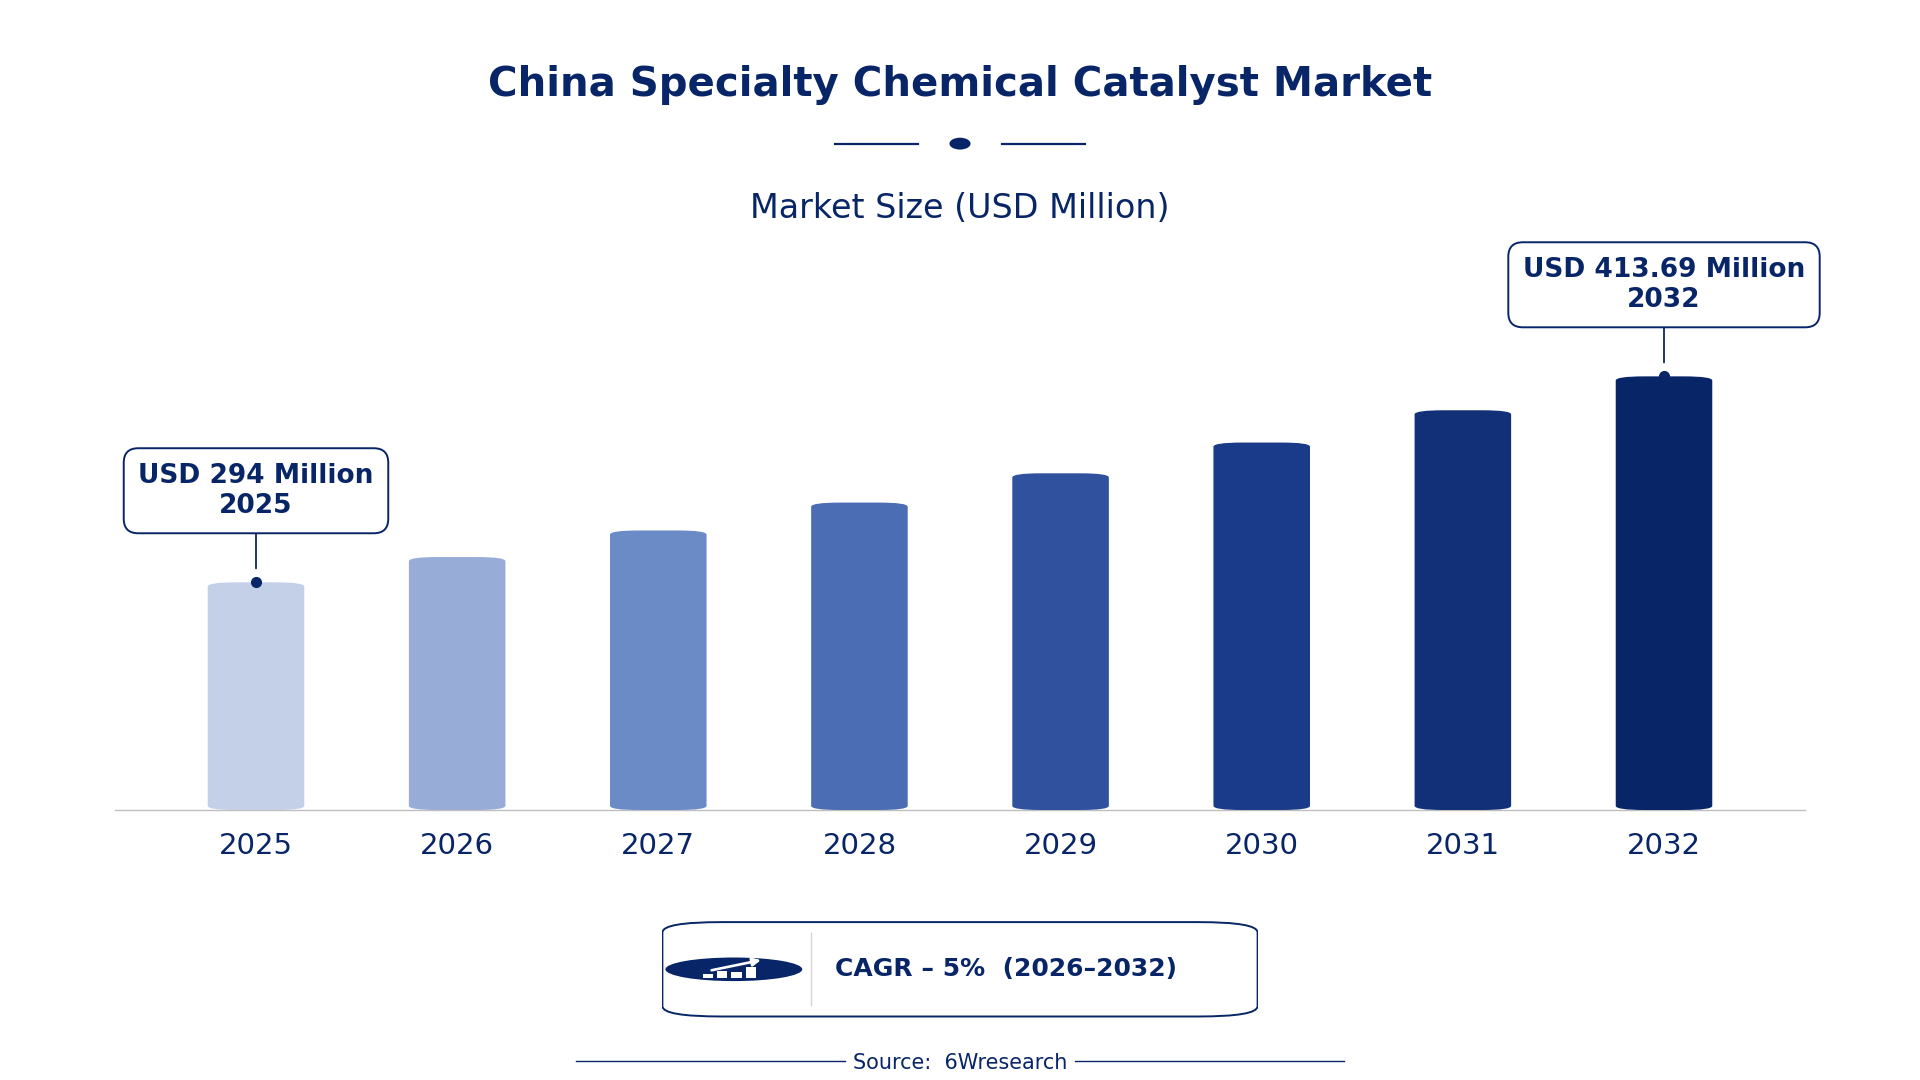
According to 6Wresearch internal database and industry insights, the China Specialty Chemical Catalyst Market was valued at USD 294.0 million in 2025 and is projected to reach USD 413.69 million by 2032, growing at a CAGR of approximately 5% during 2026–2032.
China Specialty Chemical Catalyst Market Highlights
| Report Metric | Details |
| Report Name | China Specialty Chemical Catalyst Market |
| Market Size 2025 | USD 294.0 million |
| Market Size 2032 | USD 413.69 million |
| Absolute Growth 2025–2032 | USD 119.69 million |
| CAGR 2026–2032 | 5% |
| Peak Annual Growth | 7.4% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Catalyst Category, 2025 | Supported Catalysts (36% share) |
| Leading Reaction Type, 2025 | Esterification (38% share) |
| Leading Process Type, 2025 | Batch/Continuous (36% share) |
| Leading End User, 2025 | Petrochemical Companies (46% share) |
| Fastest-Growing Reaction Type | Biodiesel Production (7.1% CAGR) |
| Fastest-Growing Process Type | Heterogeneous (7.2% CAGR) |
| Fastest-Growing End User | Fine Chemical Makers (6.2% CAGR) |
| Growing Sector | Fine Chemical Makers |
| Key End Users | Petrochemical Companies, Fine Chemical Makers, Agrochemical Firms, Biofuel Companies |
China Specialty Chemical Catalyst Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
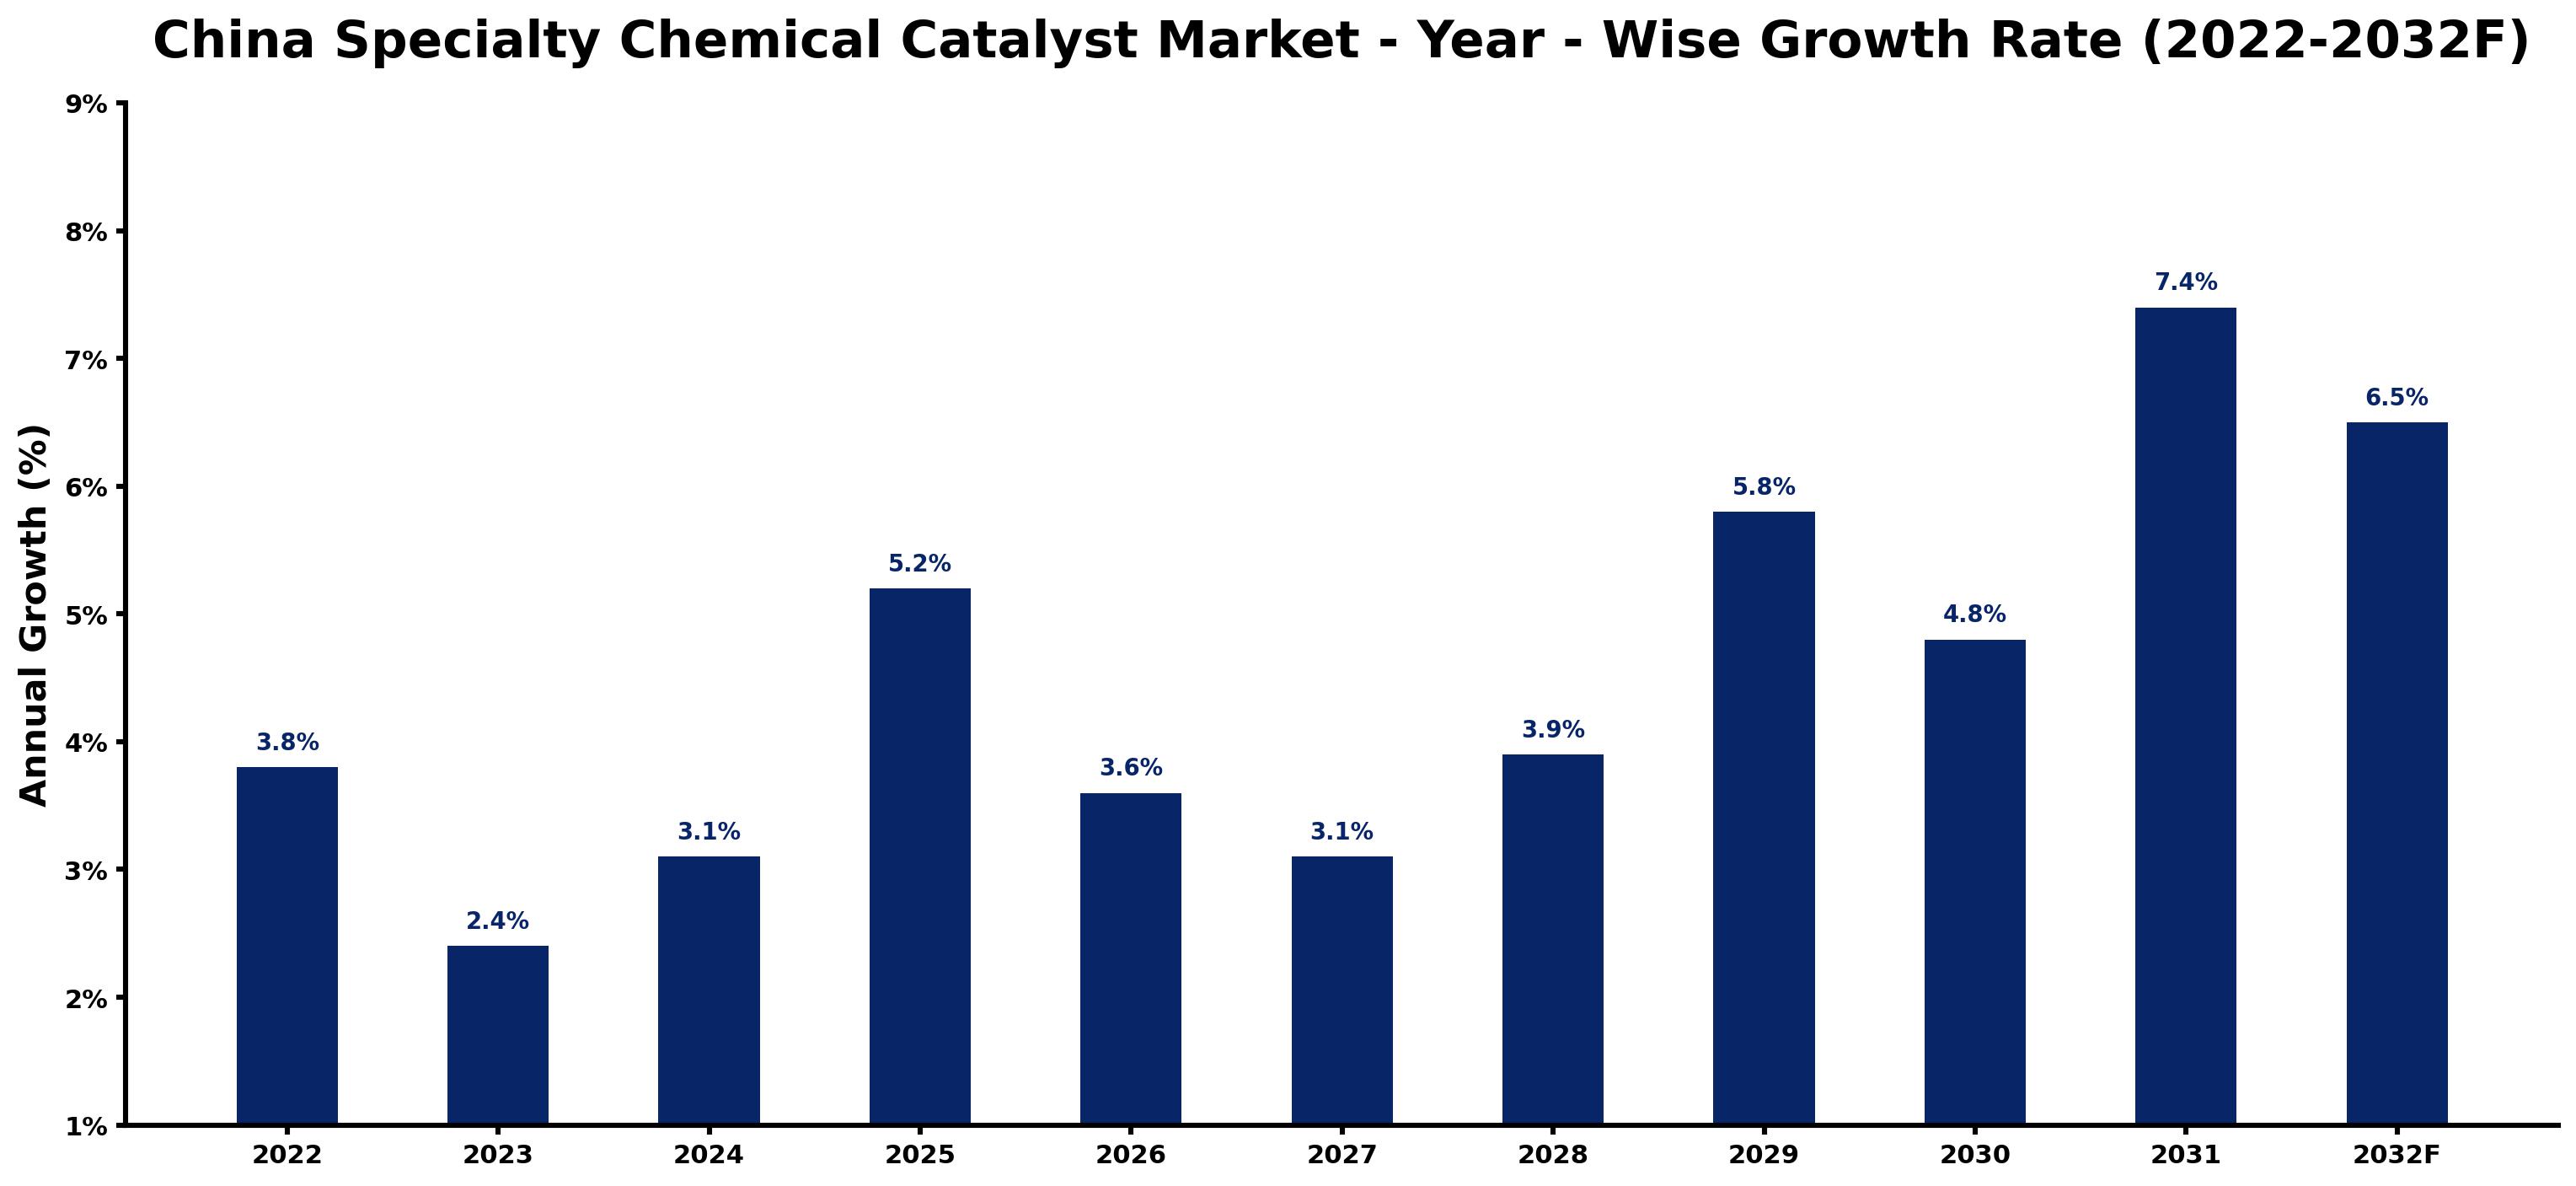
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.8 | The market experienced steady growth due to ongoing demand from the petrochemical sector. |
| 2023 | 2.4 | Growth slowed as manufacturers adjusted to new environmental regulations and standards. |
| 2024 | 3.1 | An increase in biodiesel production spurred demand for catalysts in the renewable energy sector. |
| 2025 | 5.2 | The market peaked as the petrochemical industry ramped up production to meet rising export needs. |
| 2026 | 3.6 | Growth decelerated as the market faced challenges from fluctuating raw material prices. |
| 2027 | 3.1 | Demand continued to grow, albeit at a slower pace, driven by innovations in chemical processes. |
| 2028 | 3.9 | A resurgence in fine chemical production contributed to an uptick in catalyst demand. |
| 2029 | 5.8 | The market grew faster, supported by increased investment in biodiesel production facilities. |
| 2030 | 4.8 | Growth slowed as manufacturers faced supply chain disruptions affecting catalyst availability. |
| 2031 | 7.4 | The market peaked again as new standards drove demand for advanced catalysts in various applications. |
| 2032 | 6.5 | Growth decelerated but remained strong, supported by ongoing investments in sustainable practices. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Specialty Chemical Catalyst Market Synopsis
The Specialty Chemical Catalyst Market in China encompasses substances that accelerate chemical reactions, primarily used in petrochemicals, fine chemicals, and biofuels. These catalysts are produced through methods such as impregnation and co-precipitation. The market is expanding due to rising domestic demand from local manufacturing and exports, particularly in the petrochemical sector. In 2022, China produced over 12 million tons of specialty chemicals, with the Yangtze River Delta serving as a key industrial hub for production. The government's focus on sustainable practices, through the Green Chemistry Initiative, is further driving market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising biodiesel production drives demand for catalysts, as over 50% are sourced domestically, increasing purchases from biofuel companies. | Driver | High | Biodiesel Production |
| Increased output in petrochemical industries necessitates more catalysts, leading to higher purchases from petrochemical companies. | Driver | High | Petrochemical Companies |
| The growing focus on sustainable practices creates opportunities for eco-friendly catalyst solutions, attracting investment from agrochemical firms. | Opportunity | High | Agrochemical Firms |
| Government funding for research in chemical catalysis opens avenues for innovation, appealing to fine chemical makers. | Opportunity | High | Fine Chemical Makers |
| Skills shortages in the workforce hinder production timelines, affecting suppliers' ability to meet demand in the market. | Restraint | High | Supported Catalysts |
| Fluctuating supply levels of catalysts sourced domestically create vulnerabilities for buyers in biodiesel production. | Restraint | High | Biodiesel Production |
| Rising costs of raw materials force suppliers to increase prices, impacting operational expenses for buyers in the petrochemical sector. | Challenge | High | Petrochemical Companies |
| Compliance with updated safety regulations leads to longer approval times for new products, complicating market entry for manufacturers. | Challenge | High | Supported Catalysts |
Evaluation of Drivers in China Specialty Chemical Catalyst Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising biodiesel production increases demand for catalysts essential in the conversion process, with over 50% sourced domestically. | Biodiesel Production | This trend encourages local manufacturers to invest in catalyst technologies. |
| Growing petrochemical output drives the need for efficient catalysts in production processes, employing over 1 million workers in 2022. | Petrochemical Companies | Increased production capacity leads to higher catalyst purchases. |
| The Green Chemistry Initiative promotes sustainable practices, boosting demand for eco-friendly catalysts. | Supported Catalysts | This initiative encourages manufacturers to adopt advanced catalyst solutions. |
| The National Standards for Catalysts ensure quality, driving demand for compliant products in the market. | Acid Catalysts | Manufacturers need to meet these standards to maintain competitiveness. |
| Investment in research and development improves catalyst performance, leading to increased adoption in various industries. | Fine Chemical Makers | Improved catalyst efficiency drives higher demand from manufacturers. |
In 2022, over 12 million tons of specialty chemicals were produced, with notable contributions from the Yangtze River Delta. The focus on sustainable practices is encouraging manufacturers to invest in advanced catalyst solutions, with more than 50% of biodiesel catalysts sourced domestically. The National Standards for Catalysts ensure compliance, further driving market growth. This combination of elements is boosting purchases across various sectors, particularly petrochemicals and fine chemicals.
Evaluation of Restraints in China Specialty Chemical Catalyst Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Environmental regulations impose stricter compliance measures, increasing operational costs for manufacturers. | Supported Catalysts | This affects pricing and availability of catalysts in the market. |
| Fluctuating raw material prices create uncertainty in production costs for catalyst suppliers. | Acid Catalysts | This can lead to instability in pricing for end-users. |
| Technological advancements in catalysts may outpace traditional manufacturing capabilities, causing market shifts. | Redox Catalysts | Suppliers may struggle to keep up with innovation demands. |
| Competition from international suppliers can pressure local manufacturers to lower prices. | Supported Catalysts | This affects profit margins for domestic producers. |
| Supply chain disruptions can delay catalyst availability, impacting production schedules. | Biodiesel Production | Manufacturers may face challenges in meeting demand. |
China Specialty Chemical Catalyst Market Challenges
The China Specialty Chemical Catalyst Market still has to solve a few problems, starting with skills shortages in the workforce. Many chemical manufacturers struggle to find qualified personnel due to a lack of specialised training programs, which delays production timelines for suppliers. Buyers also face challenges with fluctuating supply levels, as over 50% of catalysts used in biodiesel production are sourced domestically, making them vulnerable to local supply disruptions. Rising costs of raw materials impact suppliers, forcing them to increase prices, which can lead to a 10% hike in operational expenses for buyers. Compliance with updated safety regulations complicates the market, resulting in longer approval times for new products and increased costs for manufacturers.
Trends in the China Specialty Chemical Catalyst Market
Buyers and suppliers in the China Specialty Chemical Catalyst Market are adjusting to the following trends.
- Shift towards Sustainable Catalysts: In 2023, the Green Chemistry Initiative is promoting the use of eco-friendly catalysts in production processes, focusing on reducing environmental impact. This shift is prompting manufacturers to invest in sustainable technologies, aligning with global trends.
- Increase in Biodiesel Production: Biodiesel production in China is experiencing substantial growth, with a projected increase of 7.1% in catalyst demand. This trend is driven by the need for renewable energy sources and government support for biofuel initiatives.
- Adoption of Advanced Catalyst Technologies: The National Standards for Catalysts, revised in 2020, are pushing manufacturers to adopt advanced technologies for improved efficiency. This is leading to increased investments in R&D to meet these standards and enhance product offerings.
- Expansion of Petrochemical Production: The petrochemical industry is expanding, employing over 1 million workers in 2022. This growth is driving demand for catalysts, particularly in the Yangtze River Delta, a major industrial hub.
Investment Opportunities in the China Specialty Chemical Catalyst Market
The following opportunities in the China Specialty Chemical Catalyst Market pair current demand with a clear way in.
- Joint Ventures for Catalyst Development: With the increasing demand for advanced catalysts, forming joint ventures with local firms can facilitate market entry. The Guangdong province is a key area for specialty chemical production, offering opportunities for collaboration.
- Investment in Eco-Friendly Catalysts: The Green Chemistry Initiative creates a strong market for eco-friendly catalysts, presenting an opportunity for suppliers to invest in sustainable products. This aligns with the growing demand from petrochemical companies seeking compliance.
- Research Funding for Catalyst Innovation: The Specialty Chemicals Innovation Fund, with a budget of 500 million RMB, supports R&D in catalyst technologies. This funding presents an opportunity for firms to develop advanced solutions and enhance their market presence.
- Expansion in Fine Chemical Production: As fine chemical makers grow, there is a significant opportunity to supply specialised catalysts. The projected growth of 6.2% for this sector indicates a strong demand for advanced catalyst solutions.
Government Initiatives in the China Specialty Chemical Catalyst Market
The "Green Chemistry Promotion Plan" launched in 2022 by the Ministry of Ecology and Environment aims to reduce environmental impacts in chemical manufacturing. This plan encourages manufacturers to adopt sustainable practices and invest in eco-friendly catalysts. Additionally, the "National Chemical Industry Development Plan" approved in 2021 focuses on enhancing competitiveness in the specialty chemicals sector by 2025, promoting innovation and efficiency in production processes.
The State Administration for Market Regulation oversees the implementation of the updated "Chemical Safety Regulation" from 2023, which improves safety standards in chemical handling. This agency ensures that manufacturers comply with safety protocols, thereby protecting workers and the environment. Furthermore, the National Development and Reform Commission supports innovation in chemical processes, providing funding and resources to enhance production capabilities.
Future Insight of the China Specialty Chemical Catalyst Market
Several forward-looking factors should support the China Specialty Chemical Catalyst Market in the coming years. The launch of the "Green Chemistry Initiative" in 2023 aims to promote sustainable practices, encouraging innovation among suppliers. Government funding of 200 million RMB for research in chemical catalysis will drive advancements in catalyst technology. The National Development and Reform Commission's support for innovation will improve production efficiency. Consequently, buyers can expect better product availability and potentially lower costs as the market evolves.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Catalyst Category – Supported Catalysts Dominated and Is Expected to Record the Fastest Growth
According to Summon Dutta, Assistant Manager at 6Wresearch, Supported Catalysts took a 36% share of catalyst category in 2025, more than any other category. Supported catalysts dominate China's specialty chemical catalyst market because they are vital for enhancing reaction efficiency in diverse industrial applications. Their prevalent use in the Yangtze River Delta, a key industrial hub, reinforces their leading market share. Its lead should widen, with a projected CAGR of 6.5% during 2026–2032, the highest in this split. The growth of supported catalysts is propelled by the increasing demand for efficient chemical processes, particularly in biodiesel production. Their compliance with initiatives like the Green Chemistry Initiative will further strengthen their market position. Suppliers must focus on advancing supported catalysts to meet the rising demand in China's specialty chemical catalyst market.
By Reaction Type – Esterification Dominated, Biodiesel Production Expected to Grow Fastest
The largest reaction type category in 2025 was Esterification, with a 38% share of total revenue. Esterification leads the reaction type segment due to its crucial function in producing esters from acids and alcohols, widely utilised in various chemical industries. Its established role in the petrochemical sector contributes significantly to its market share. Over 2026–2032, Biodiesel Production is expected to post the fastest growth, at a CAGR of 7.1%. Biodiesel production is experiencing rapid growth, driven by the rising focus on sustainable energy sources and the domestic sourcing of catalysts. Government backing for biodiesel initiatives is expected to further accelerate this segment's growth. Buyers in the biodiesel sector should prioritise sourcing catalysts that enhance production efficiency to capitalise on the expanding market.
By Process Type – Batch/Continuous Dominated, Heterogeneous Expected to Grow Fastest
With a 36% revenue share in 2025, Batch/Continuous was the largest process type category. Batch/continuous processes are prevalent as they are versatile and applicable in both batch and continuous production settings, making them indispensable in the specialty chemical industry. This adaptability contributes to their substantial market share. Heterogeneous is projected to grow fastest, at a CAGR of 7.2% during 2026–2032. Heterogeneous processes are gaining traction due to their effectiveness in reactions involving solid catalysts, which are increasingly favoured in modern chemical manufacturing. This trend indicates a shift towards more efficient production methods. Suppliers must innovate heterogeneous catalysts to align with the industry's move towards more efficient process types.
By End User – Petrochemical Companies Dominated, Fine Chemical Makers Expected to Grow Fastest
Petrochemical Companies accounted for a 46% market share by end user in 2025. Petrochemical companies command the largest share as they heavily depend on specialty chemical catalysts for producing a diverse range of petrochemicals. The employment of over 1 million workers in this sector underscores its importance in the market. The quickest growth will come from Fine Chemical Makers, forecast to expand at a CAGR of 6.2% between 2026 and 2032. Fine chemical makers are experiencing rapid growth as they increasingly incorporate specialty chemical catalysts for synthesising fine chemicals and intermediates. This expansion is driven by the rising demand for high-purity chemicals in various applications. Suppliers should concentrate on fine chemical makers to capitalise on the growing demand for specialty chemical catalysts in this sector.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Specialty Chemical Catalyst Market Outlook
- Market Size of China Specialty Chemical Catalyst Market, 2025
- Forecast of China Specialty Chemical Catalyst Market, 2032
- Historical Data and Forecast of China Specialty Chemical Catalyst Revenues & Volume for the Period 2022 - 2032F
- China Specialty Chemical Catalyst Market Trend Evolution
- China Specialty Chemical Catalyst Market Drivers and Challenges
- China Specialty Chemical Catalyst Price Trends
- China Specialty Chemical Catalyst Porter's Five Forces
- China Specialty Chemical Catalyst Industry Life Cycle
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Catalyst Category for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Acid Catalysts for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Base Catalysts for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Redox Catalysts for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Supported Catalysts for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Reaction Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Esterification for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Biodiesel Production for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Oxidation/Reduction for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Surface-Specific Activity for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Process Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Batch/Continuous for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Heterogeneous for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Homogeneous for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Fixed Bed for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Agrochemical Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Biofuel Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Fine Chemical Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Chemical Catalyst Market Revenues & Volume By Petrochemical Companies for the Period 2022 - 2032F
- China Specialty Chemical Catalyst Import Export Trade Statistics
- Market Opportunity Assessment By Catalyst Category
- Market Opportunity Assessment By Reaction Type
- Market Opportunity Assessment By Process Type
- Market Opportunity Assessment By End User
- China Specialty Chemical Catalyst Top Companies Market Share
- China Specialty Chemical Catalyst Competitive Benchmarking By Technical and Operational Parameters
- China Specialty Chemical Catalyst Company Profiles
- China Specialty Chemical Catalyst Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Catalyst Category
- Acid Catalysts
- Base Catalysts
- Redox Catalysts
- Supported Catalysts
By Reaction Type
- Esterification
- Biodiesel Production
- Oxidation/Reduction
- Surface-Specific Activity
By Process Type
- Batch/Continuous
- Heterogeneous
- Homogeneous
- Fixed Bed
By End User
- Agrochemical Firms
- Biofuel Companies
- Fine Chemical Makers
- Petrochemical Companies































