China Specialty Solvents Market Size & Growth Rate
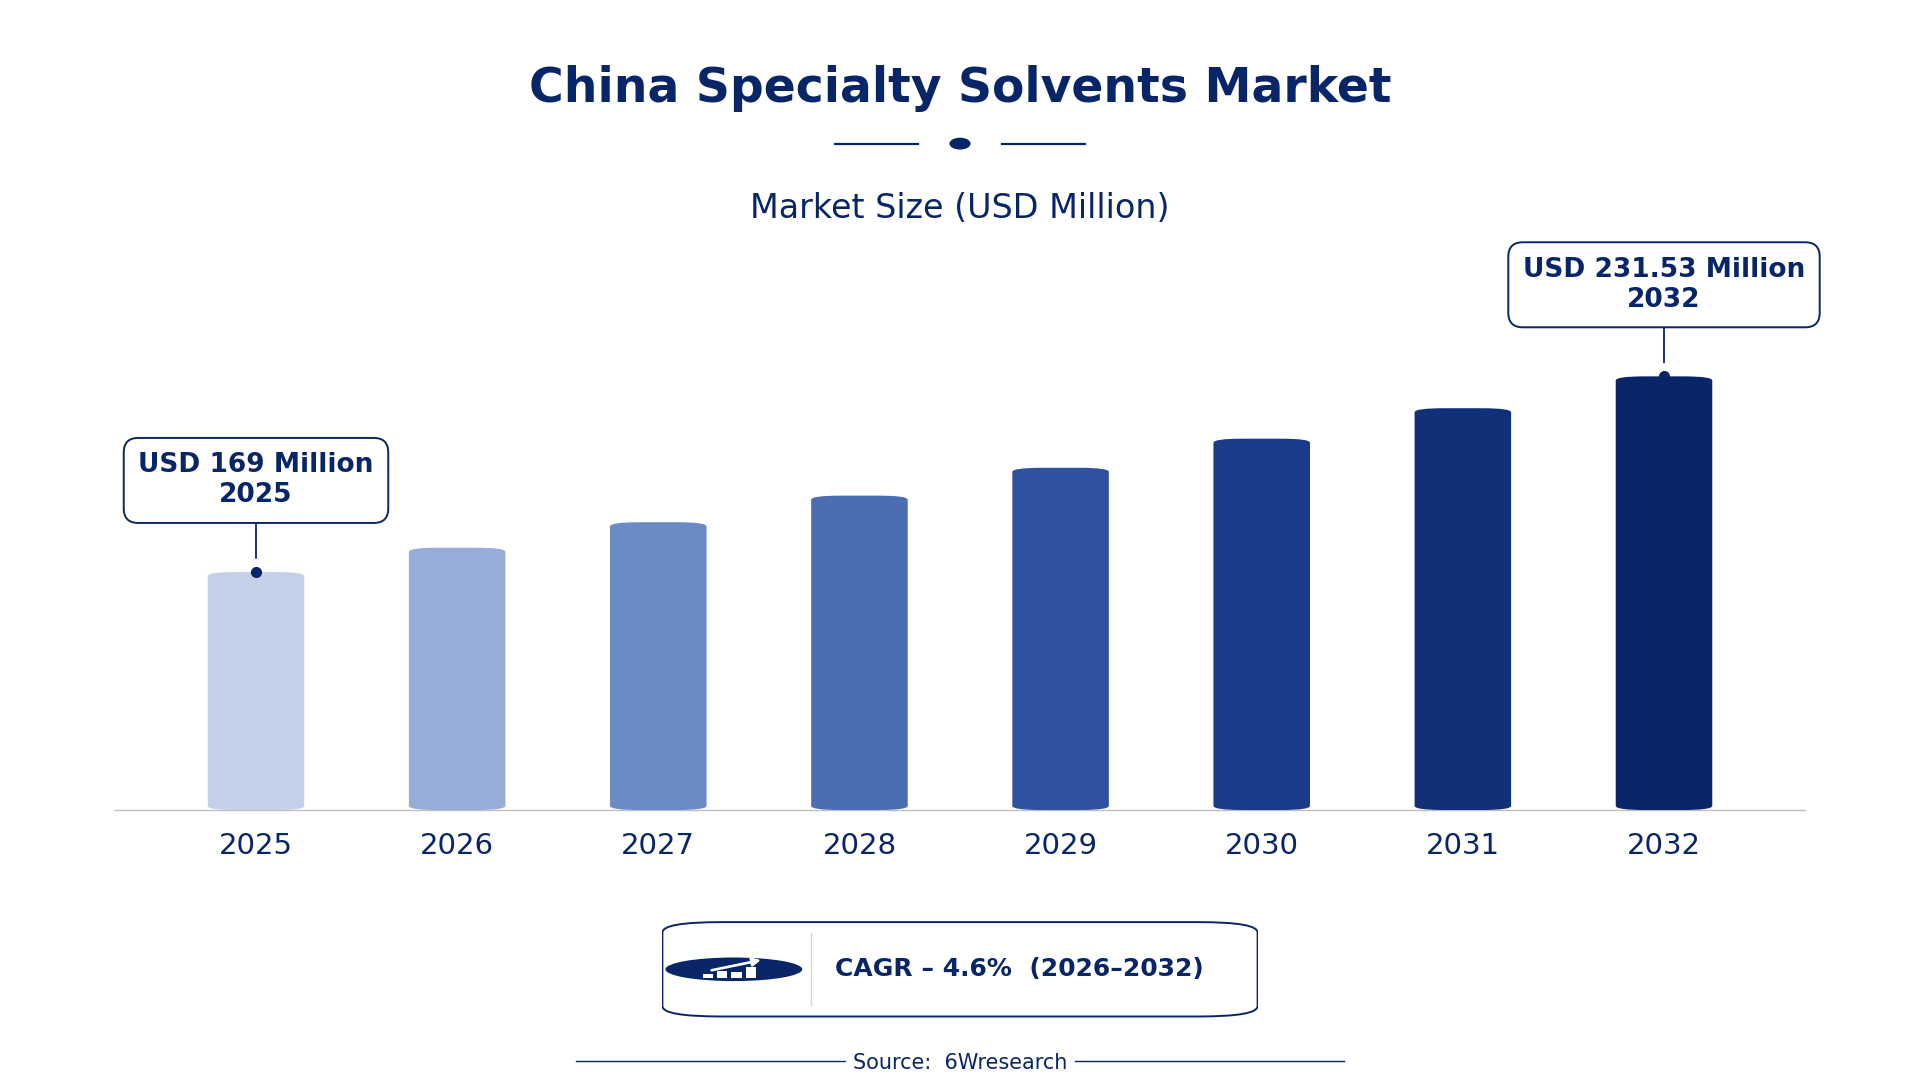
According to 6Wresearch internal database and industry insights, the China Specialty Solvents Market was valued at USD 169.0 million in 2025 and is projected to reach USD 231.53 million by 2032, growing at a CAGR of approximately 4.6% during 2026–2032.
China Specialty Solvents Market Highlights
| Report Metric | Details |
| Report Name | China Specialty Solvents Market |
| Market Size 2025 | USD 169.0 million |
| Market Size 2032 | USD 231.53 million |
| Absolute Growth 2025–2032 | USD 62.53 million |
| CAGR 2026–2032 | 4.6% |
| Peak Annual Growth | 6.8% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Solvent Type, 2025 | Glycol Ethers (46% share) |
| Leading Chemical Base, 2025 | Petroleum Derived (43% share) |
| Leading Use Case, 2025 | Paints & Coatings (41% share) |
| Leading End User, 2025 | Drug Manufacturers (48% share) |
| Fastest-Growing Solvent Type | Lactate Esters (7.0% CAGR) |
| Fastest-Growing Chemical Base | Bio-Based (7.2% CAGR) |
| Fastest-Growing Use Case | Green Cleaning (7.1% CAGR) |
| Fastest-Growing End User | Eco-Friendly Cleaners (5.8% CAGR) |
| Growing Sector | Eco-Friendly Cleaners |
| Key End Users | Drug Manufacturers, Industrial Paint Firms, Packaging Adhesive Makers, Eco-Friendly Cleaners |
China Specialty Solvents Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
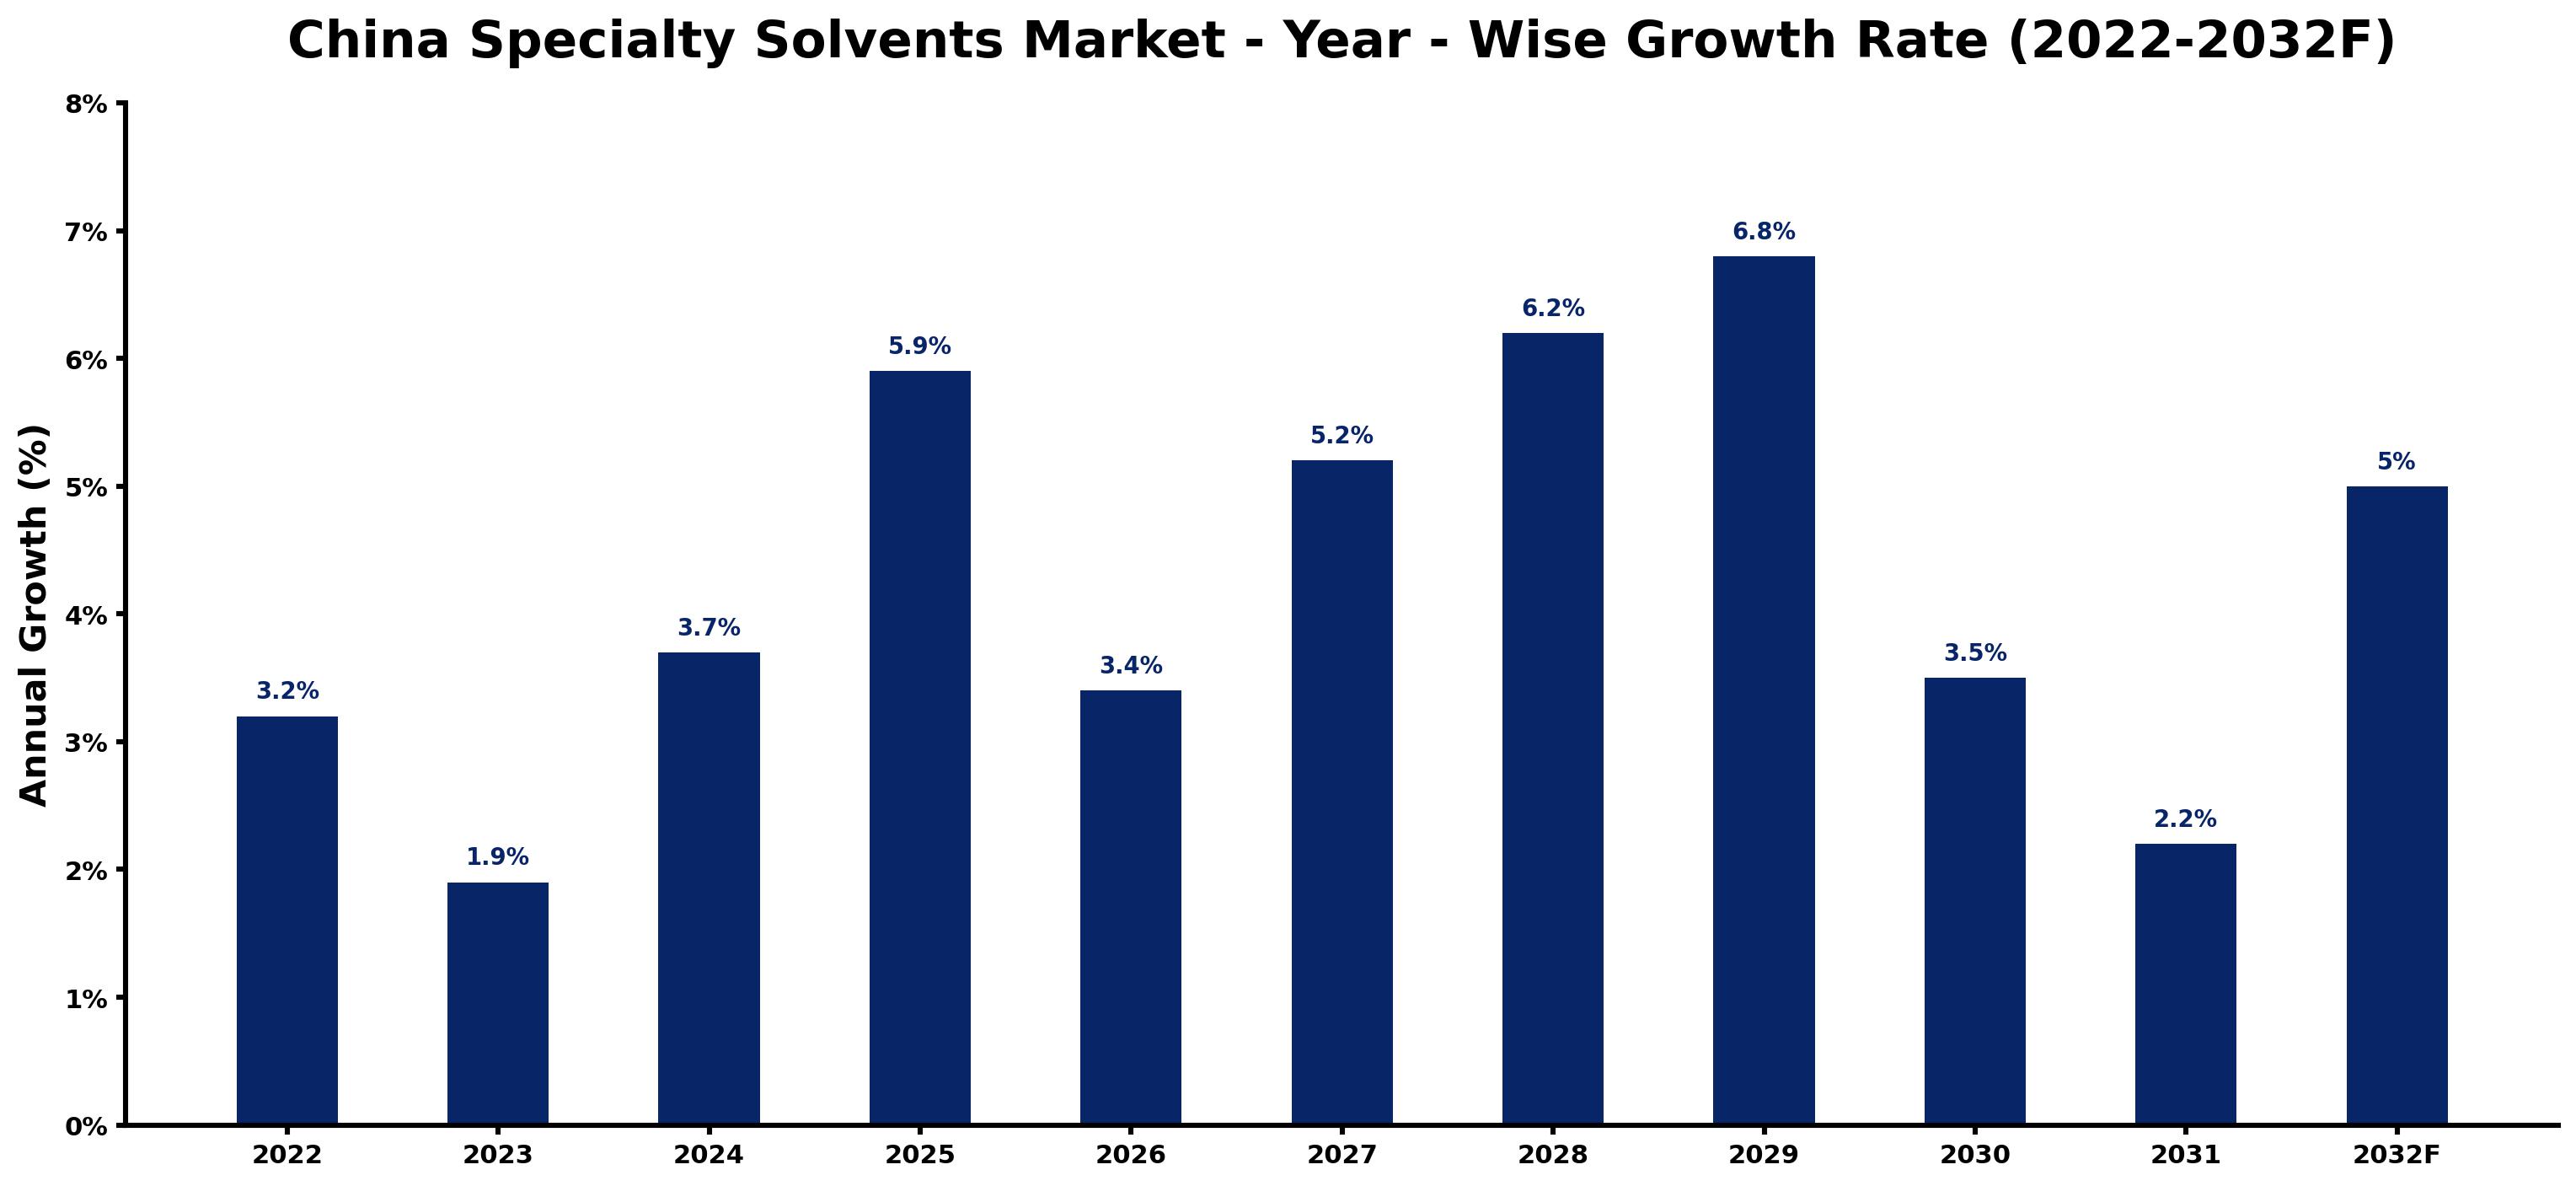
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.2 | The market experienced steady growth due to rising demand from the pharmaceutical sector. |
| 2023 | 1.9 | Growth slowed as the market adjusted to changing consumer preferences and stricter environmental standards. |
| 2024 | 3.7 | A resurgence in demand for eco-friendly products, particularly from the Green Cleaning sector, boosted growth in specialty solvents. |
| 2025 | 5.9 | Demand from drug manufacturers contributed to accelerated growth, requiring substantial specialty solvents for production. |
| 2026 | 3.4 | Growth slowed as manufacturers faced challenges in sourcing sustainable materials for production. |
| 2027 | 5.2 | Rising demand for bio-based solvents, driven by environmental initiatives, is expected to support market expansion. |
| 2028 | 6.2 | Increased investment in green technologies will enhance growth in the specialty solvents sector. |
| 2029 | 6.8 | The market is projected to peak as demand surges for high-performance specialty solvents across various applications. |
| 2030 | 3.5 | Growth is expected to slow as the market adjusts to new regulations and stabilises after the peak. |
| 2031 | 2.2 | A decrease in growth rate reflects market adjustments to updated safety guidelines for chemical products. |
| 2032 | 5.0 | Growth is projected to rebound as manufacturers adapt to evolving consumer preferences for sustainable products. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Specialty Solvents Market Synopsis
Specialty solvents in China are chemical compounds used primarily in industrial applications. They are produced from petroleum derivatives, bio-based sources, or alcohol/ether compounds, with primary uses in paints, coatings, and pharmaceuticals. The China Specialty Solvents Market is expanding due to strong demand from the pharmaceutical sector and increasing adoption of eco-friendly solvents. The population exceeding 1.4 billion drives substantial consumption of consumer products utilizing these solvents. The Green Solvent Initiative launched in 2023 promotes sustainable practices in the industry.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand for bio-based solvents driven by environmental regulations | Driver | High | Bio-Based |
| Increased production capabilities in the pharmaceutical sector | Driver | High | Drug Manufacturers |
| Emerging opportunities in eco-friendly cleaning products | Opportunity | High | Green Cleaning |
| Investment in research for bio-based solvent technologies | Opportunity | High | Bio-Based |
| Stringent regulations on VOC emissions affecting production | Restraint | High | Petroleum Derived |
| Challenges in sourcing sustainable materials for production | Restraint | Medium | Lactate Esters |
| Supply chain disruptions affecting timely deliveries | Challenge | High | Hydrocarbon Solvents |
| Competition from alternative solvent technologies impacting market share | Challenge | Medium | Polar Aprotic Solvents |
Evaluation of Drivers in China Specialty Solvents Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising demand for glycol ethers in coatings applications | Glycol Ethers | The annual demand for glycol ethers in China is estimated at 300,000 tons, primarily driven by the coatings industry. |
| Increased focus on eco-friendly solvents | Lactate Esters | The demand for bio-based solvents is expected to grow by 15% annually due to environmental regulations. |
| Strong growth in the pharmaceutical sector | Polar Aprotic Solvents | The pharmaceutical sector in China is projected to require over 500,000 tons of specialty solvents by 2025. |
| Expansion of the adhesive industry | Adhesives | The adhesive industry in China is worth over 100 billion RMB, with specialty solvents playing a critical role. |
| Support from government initiatives for sustainable chemicals | Bio-Based | The 'Green Chemical Industry Development Plan' aims to increase the market share of bio-based solvents by 30% by 2025. |
The Specialty Solvents market in China is expanding as end-use demand rises from various sectors, particularly pharmaceuticals and coatings. The pharmaceutical sector's projected requirement for substantial specialty solvents by 2025 drives manufacturers to increase production capacity. The annual demand for glycol ethers, estimated at significant tons, is primarily fuelled by the coatings industry. The adhesive industry's worth, exceeding 100 billion RMB, highlights the critical role specialty solvents play in formulation processes.
Evaluation of Restraints in China Specialty Solvents Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Compliance with strict regulations on solvent use in food contact materials delays product approvals for manufacturers. | Petroleum Derived | The National Standard GB 2760-2014 imposes limits on solvent use. |
| Competition from bio-based solvents pressures traditional solvent producers to innovate or risk losing market share. | Bio-Based | Bio-based solvents are projected to grow significantly annually. |
| Supply chain disruptions in eastern provinces delay delivery for buyers. | Glycol Ethers | Production hubs in Jiangsu and Zhejiang struggle to meet increasing demand. |
| Fluctuating costs of petroleum derivatives impact pricing strategies for producers. | Hydrocarbon Solvents | Rising crude oil prices affect production costs. |
| Limited awareness of eco-friendly solvent options among manufacturers restricts market growth. | Lactate Esters | Many manufacturers are still reliant on traditional solvents. |
China Specialty Solvents Market Challenges
Buyers and suppliers in the China Specialty Solvents Market face regulatory challenges, as compliance with the National Standard GB 2760-2014 restricts solvent use in food contact materials. This can lead to product approval delays exceeding six months. Competition is intense, particularly from the bio-based segment, projected to grow by 15% annually, pushing traditional solvent manufacturers to adapt or risk losing market share. Supply chain disruptions are common, especially in eastern provinces like Jiangsu and Zhejiang, where production issues can cause delivery delays. Rising costs of petroleum derivatives are also straining producers, compelling them to raise prices, which may deter price-sensitive clients from purchasing.
Trends in the China Specialty Solvents Market
Below mentioned are some of the trends shaping the China Specialty Solvents Market growth.
- Transition from Traditional to Eco-Friendly Solvents: Manufacturers are increasingly adopting bio-based solvents in response to environmental regulations. The Green Solvent Initiative launched in 2023 aims to promote sustainable practices, with bio-based solvent adoption expected to grow substantially each year.
- Shift in Demand Towards Green Cleaning Products: The demand for eco-friendly cleaning products is on the rise, with the Green Cleaning sector projected to grow at a CAGR of 7.1%. This trend is reflected in the increasing use of lactate esters in formulations.
- Growth of Pharmaceutical Applications: The pharmaceutical sector is driving demand for specialty solvents, with a projected need for substantial amounts by 2025. This increase is mainly due to the production of active pharmaceutical ingredients.
- Expansion of Coatings Industry: The coatings industry continues to grow, with glycol ethers being a key component. The annual demand for glycol ethers is estimated at significant tons, primarily driven by industrial paint firms.
Investment Opportunities in the China Specialty Solvents Market
The following opportunities in the China Specialty Solvents Market pair current demand with a clear way in.
- Joint Ventures for Bio-Based Solvent Production: With the anticipated annual growth in bio-based solvents, forming joint ventures with local manufacturers can facilitate entry into this market. The eastern provinces are key production hubs.
- Investment in Green Technologies: The government allocated significant funds for research on bio-based solvent technologies, presenting an opportunity for investment in sustainable practices. Companies focusing on eco-friendly products can benefit greatly.
- Partnerships with Eco-Friendly Cleaners: As demand for green cleaning products rises, partnerships with eco-friendly cleaner manufacturers can provide lucrative opportunities. The market for these products is expanding rapidly, requiring innovative solvent solutions.
- Certification for Sustainable Practices: Obtaining ISO 14001 certification can enhance market competitiveness. Manufacturers aiming to produce eco-friendly solvents can use this certification to attract environmentally conscious buyers.
Government Initiatives in the China Specialty Solvents Market
The regulatory environment for specialty solvents in China is shaped by several key measures. The National Standard GB 2760-2014, revised in 2020, establishes safety regulations for solvents used in food packaging. The Green Chemical Industry Development Plan, initiated in 2021, aims to increase the market share of bio-based solvents by 30% by 2025. These regulations compel manufacturers to ensure compliance, impacting production processes and market strategies. The Specialty Chemicals Innovation Strategy, launched in 2022, focuses on strengthening domestic production capabilities, further influencing market conditions.
In 2023, the Ministry of Ecology and Environment allocated 200 million RMB for research on bio-based solvent technologies. The State Administration for Market Regulation oversees the updated Regulations on the Safety of Chemical Products, which enforce stricter guidelines for specialty solvents. These measures ensure that manufacturers adhere to safety standards, creating a more sustainable and compliant market environment. The National Development and Reform Commission's initiatives also support the growth of the specialty solvents sector by promoting innovation and sustainability.
Future Insight of the China Specialty Solvents Market
The China Specialty Solvents Market is set for substantial evolution by 2032, driven by several transformative factors. The 'Green Solvent Initiative', launched in 2023, will encourage the adoption of eco-friendly alternatives, aligning with global sustainability efforts. By 2025, the pharmaceutical sector's demand for over 500,000 tons of specialty solvents will require advancements in production techniques. The 'Made in China 2025' plan will prioritise the development of high-performance chemicals, promoting innovation and strengthening the market's competitiveness.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Solvent Type – Glycol Ethers Dominated, Lactate Esters Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, with a 46% revenue share in 2025, Glycol Ethers was the largest solvent type category. Glycol ethers hold the largest market share in China due to their extensive use in paints and coatings, which are critical for various industries. For instance, the annual demand for glycol ethers is estimated at 300,000 tons, primarily driven by the coatings sector. Over 2026–2032, Lactate Esters are expected to post the fastest growth, at a CAGR of 7.0%. Lactate esters are experiencing rapid growth as they are increasingly utilized in eco-friendly cleaning products, aligning with the rising consumer preference for sustainable options. The government's 'Green Solvent Initiative' further supports this trend by promoting biodegradable solvents. Suppliers should focus on developing and marketing eco-friendly solvent options to meet the growing demand from environmentally conscious consumers.
By Chemical Base – Petroleum Derived Dominated, Bio-Based Expected to Grow Fastest
Petroleum Derived took a 43% share of chemical base in 2025, more than any other category. Petroleum derived solvents hold the largest share in the China specialty solvents market due to their long-standing production methods and widespread applications across various sectors. They are essential for traditional uses, particularly in paints and coatings, which significantly contribute to their dominance. Bio-Based is set to record the highest CAGR in this split, 7.2% over 2026–2032. The bio-based segment is experiencing rapid growth, propelled by strict environmental regulations that promote the use of sustainable products. This segment's anticipated annual growth of 15% indicates a shift in market dynamics, as manufacturers increasingly seek eco-friendly alternatives. This trend suggests that suppliers must adapt by expanding their bio-based offerings to align with the growing demand for environmentally friendly solvents.
By Use Case – Paints & Coatings Dominated, Green Cleaning Expected to Grow Fastest
Paints & Coatings accounted for a 41% market share by use case in 2025. Paints and coatings represent the largest application area for specialty solvents in China, accounting for a substantial share of market demand. This sector benefits from the booming construction and automotive industries, which require high-quality coatings. The quickest growth will come from Green Cleaning, forecast to expand at a CAGR of 7.1% between 2026 and 2032. The green cleaning segment is rapidly expanding as consumers and businesses increasingly prefer eco-friendly cleaning products. This shift is supported by growing awareness of environmental issues and the push for sustainable solutions in everyday products. Manufacturers should invest in developing green cleaning formulations to capture the growing market share in eco-friendly applications.
By End User – Drug Manufacturers Dominated, Eco-Friendly Cleaners Expected to Grow Fastest
In 2025, Drug Manufacturers led the end user split with a 48% share. Drug manufacturers are the leading end users of specialty solvents, relying heavily on these compounds for pharmaceutical synthesis. This sector's substantial demand is driven by the ongoing growth of the pharmaceutical industry in China, which is projected to require over 500,000 tons by 2025. Eco-Friendly Cleaners are projected to grow fastest, at a CAGR of 5.8% during 2026–2032. Eco-friendly cleaners are experiencing the fastest growth as manufacturers shift towards sustainable cleaning solutions in response to consumer preferences. This trend is supported by increased regulatory pressures and a growing market for environmentally friendly products. Suppliers must adapt their offerings to include eco-friendly options to align with the evolving preferences of end users.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Specialty Solvents Market Outlook
- Market Size of China Specialty Solvents Market, 2025
- Forecast of China Specialty Solvents Market, 2032
- Historical Data and Forecast of China Specialty Solvents Revenues & Volume for the Period 2022 - 2032F
- China Specialty Solvents Market Trend Evolution
- China Specialty Solvents Market Drivers and Challenges
- China Specialty Solvents Price Trends
- China Specialty Solvents Porter's Five Forces
- China Specialty Solvents Industry Life Cycle
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Solvent Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Glycol Ethers for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Lactate Esters for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Hydrocarbon Solvents for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Polar Aprotic Solvents for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Chemical Base for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Alcohol/Ether for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Bio-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Petroleum Derived for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By High Boiling Point for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Use Case for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Paints & Coatings for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Green Cleaning for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Adhesives for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Pharmaceutical Synthesis for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Industrial Paint Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Eco-Friendly Cleaners for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Packaging Adhesive Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Solvents Market Revenues & Volume By Drug Manufacturers for the Period 2022 - 2032F
- China Specialty Solvents Import Export Trade Statistics
- Market Opportunity Assessment By Solvent Type
- Market Opportunity Assessment By Chemical Base
- Market Opportunity Assessment By Use Case
- Market Opportunity Assessment By End User
- China Specialty Solvents Top Companies Market Share
- China Specialty Solvents Competitive Benchmarking By Technical and Operational Parameters
- China Specialty Solvents Company Profiles
- China Specialty Solvents Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Solvent Type
- Glycol Ethers
- Lactate Esters
- Hydrocarbon Solvents
- Polar Aprotic Solvents
By Chemical Base
- Alcohol/Ether
- Bio-Based
- Petroleum Derived
- High Boiling Point
By Use Case
- Paints & Coatings
- Green Cleaning
- Adhesives
- Pharmaceutical Synthesis
By End User
- Industrial Paint Firms
- Eco-Friendly Cleaners
- Packaging Adhesive Makers
- Drug Manufacturers































