China Stamping Metal Panels Market Size & Growth Rate
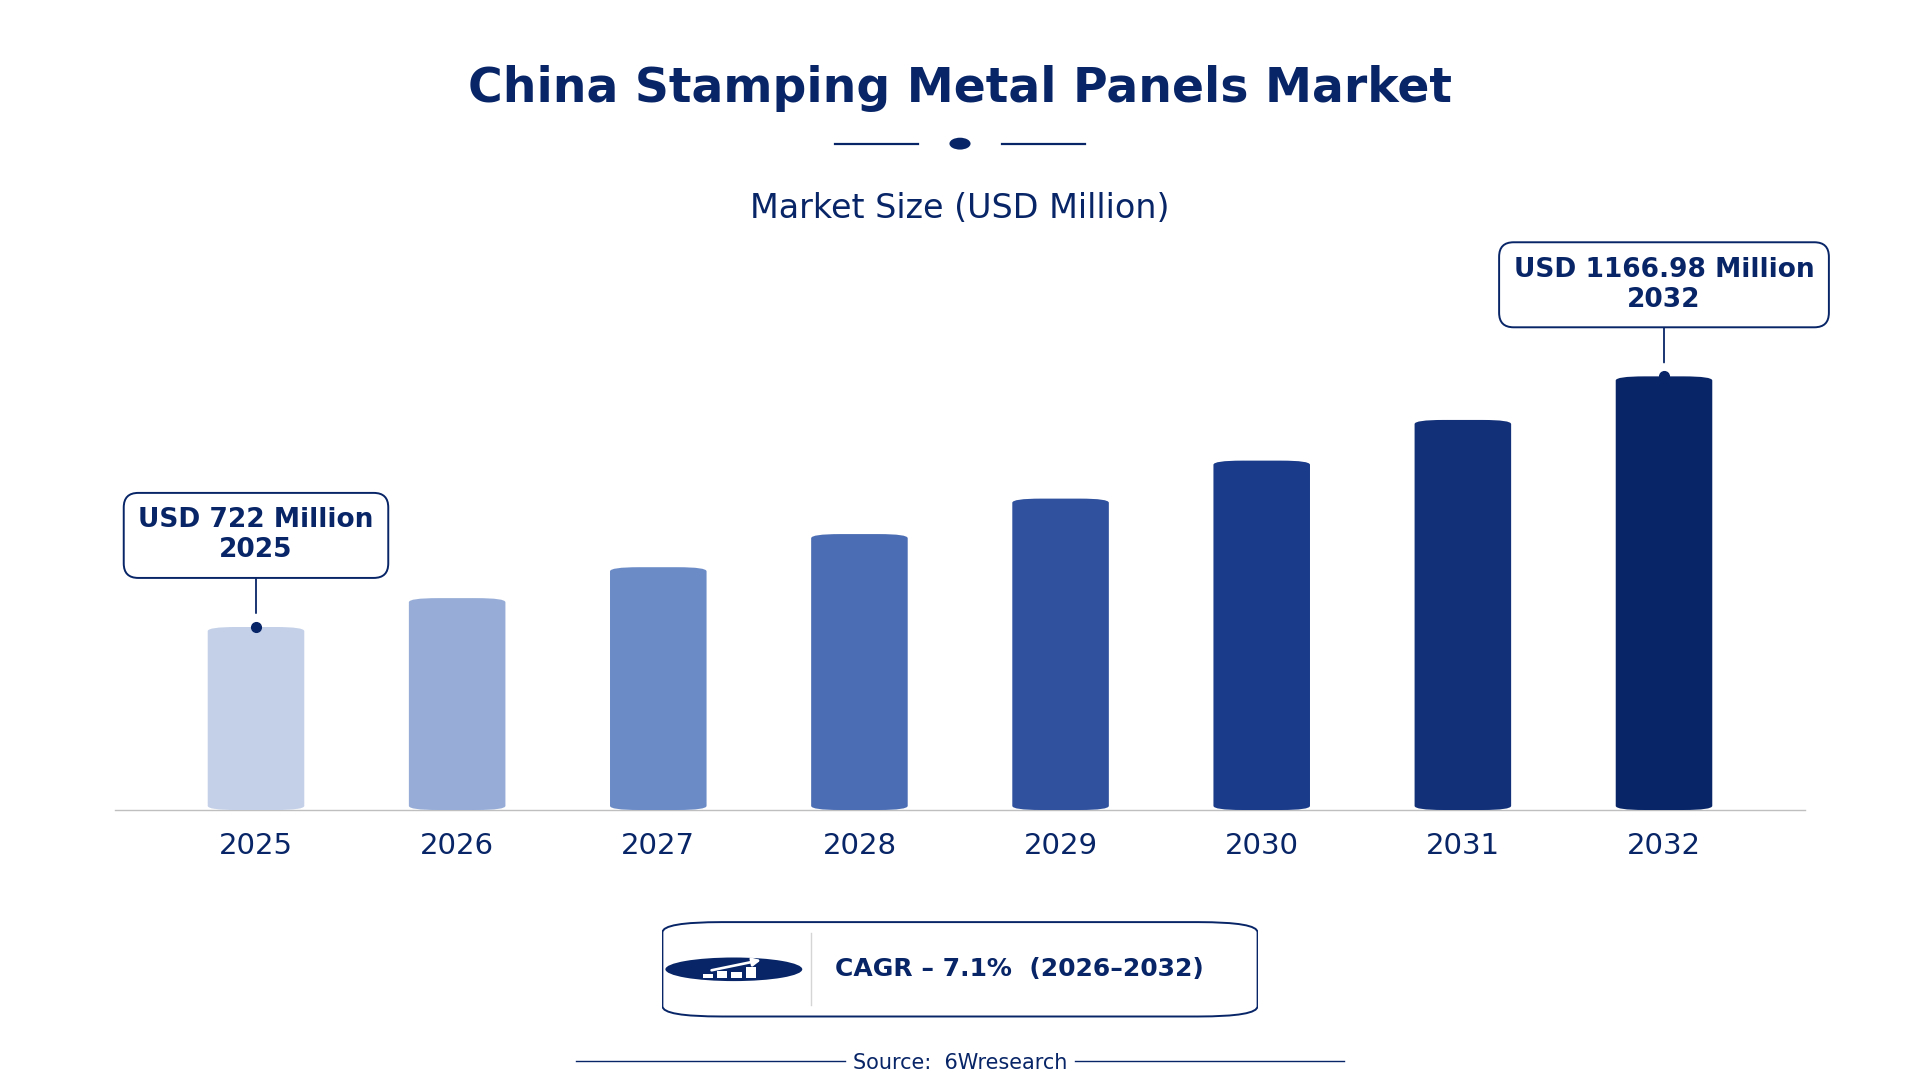
According to 6Wresearch internal database and industry insights, the China Stamping Metal Panels Market was valued at USD 722.0 million in 2025 and is projected to reach USD 1,166.98 million by 2032, growing at a CAGR of approximately 7.1% during 2026–2032.
China Stamping Metal Panels Market Highlights
| Report Metric | Details |
| Report Name | China Stamping Metal Panels Market |
| Market Size 2025 | USD 722.0 million |
| Market Size 2032 | USD 1,166.98 million |
| Absolute Growth 2025–2032 | USD 444.98 million |
| CAGR 2026–2032 | 7.1% |
| Peak Annual Growth | 9.2% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Panel Type, 2025 | Body Panels (38% share) |
| Leading Metal Used, 2025 | Aluminum/Steel (48% share) |
| Leading Process Type, 2025 | Deep Drawing (37% share) |
| Leading End User, 2025 | Auto OEMs (45% share) |
| Fastest-Growing Panel Type | Structural Panels (9.4% CAGR) |
| Fastest-Growing Metal Used | High-Strength Steel (8.5% CAGR) |
| Fastest-Growing Process Type | Progressive Die (9.3% CAGR) |
| Fastest-Growing End User | Tier 1 Suppliers (8.1% CAGR) |
| Growing Sector | Tier 1 Suppliers |
| Key End Users | Auto OEMs, Tier 1 Suppliers, Interior Component Makers, Vehicle Assembly Plants |
China Stamping Metal Panels Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
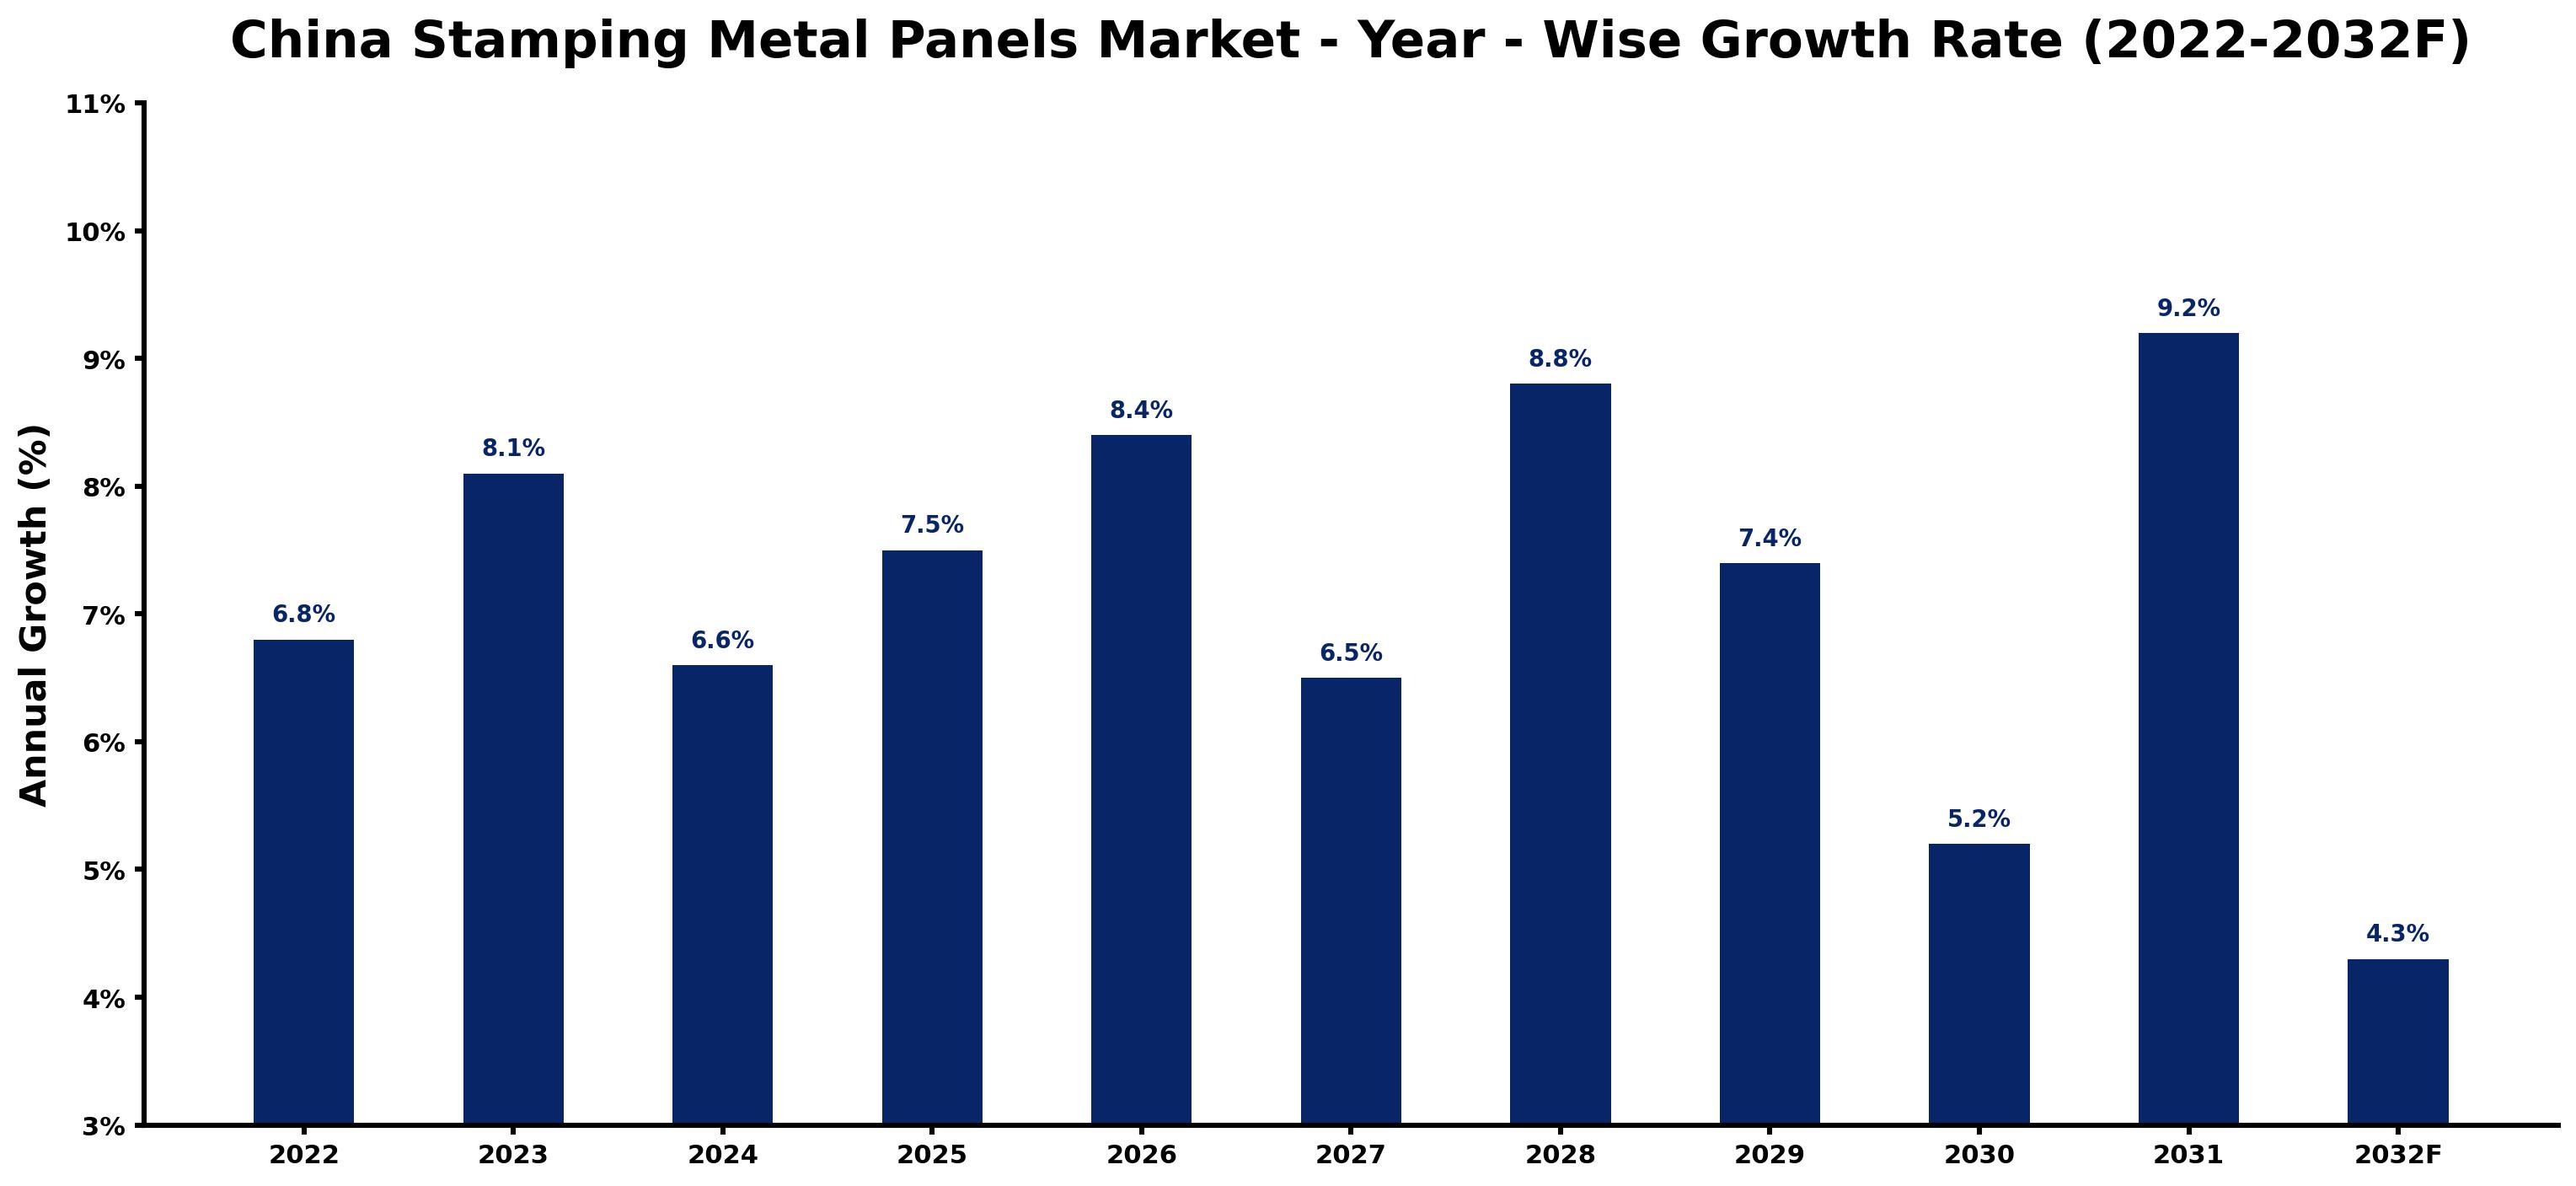
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.8 | The automotive sector maintained steady production levels, contributing to demand for stamping panels. |
| 2023 | 8.1 | Increased vehicle production, especially in the Guangdong province, drove higher demand for stamping metal panels. |
| 2024 | 6.6 | Production growth slowed as manufacturers adjusted to evolving consumer preferences and market conditions. |
| 2025 | 7.5 | Demand rose again due to improvements in vehicle designs and the introduction of new safety standards. |
| 2026 | 8.4 | The launch of new vehicle models is projected to boost the need for stamping panels in manufacturing. |
| 2027 | 6.5 | A slight slowdown is anticipated as manufacturers focus on efficiency and cost management. |
| 2028 | 8.8 | Increased investment in automotive technology parks is expected to spur demand for advanced stamping processes. |
| 2029 | 7.4 | The market may experience another slowdown as manufacturers navigate supply chain challenges. |
| 2030 | 5.2 | Demand is expected to continue growing, albeit at a slower pace, due to changing consumer preferences. |
| 2031 | 9.2 | A peak in growth will be driven by investments in electric vehicle production and related technologies. |
| 2032 | 4.3 | The market is projected to stabilise as manufacturers adapt to evolving automotive safety standards. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Stamping Metal Panels Market Synopsis
The China Stamping Metal Panels Market involves the production of metal components primarily used in vehicles. These panels are created through processes like deep drawing and precision stamping, using materials such as steel and aluminium. The market is growing due to the automotive sector, which produced over 25 million vehicles in 2022. Domestic auto manufacturers and assembly plants are key sources of demand, bolstered by ongoing investments in automotive technology and safety standards. The market is set for continued expansion as the need for high-quality components increases.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased vehicle production capacity | Driver | High | Body Panels |
| Growing adoption of high-strength steel | Driver | High | Structural Panels |
| Investment in automotive technology parks | Opportunity | High | Auto OEMs |
| Expansion of electric vehicle production | Opportunity | High | Vehicle Assembly Plants |
| Supply chain disruptions affecting material availability | Restraint | High | Engine Bay Panels |
| Rising costs of raw materials impacting pricing | Restraint | Medium | Decorative Panels |
| Stamping Metal Panels market in China faces regulatory challenges | Challenge | High | Body Panels |
| Technological advancements require constant adaptation | Challenge | Medium | Body Panels |
Evaluation of Drivers in China Stamping Metal Panels Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased vehicle production | Body Panels | Over 25 million vehicles produced in 2022 necessitate more body panels for assembly. |
| Adoption of high-strength steel | Structural Panels | High-strength steel is used in 60% of new vehicle models, improving safety and reducing weight. |
| Investment in automotive technology parks | Auto OEMs | Investments in Jiangsu province are boosting manufacturing capabilities and demand for stamping panels. |
| Focus on electric vehicle production | Vehicle Assembly Plants | A new policy promoting electric vehicles is driving demand for stamping panels. |
| Implementation of ISO 9001 standards | Body Panels | Adoption of quality management standards improves production efficiency and product reliability. |
Expansion of the Stamping Metal Panels market in China is backed by rising vehicle production and increasing investments in automotive technology. Over 25 million vehicles were produced in 2022, creating a strong demand for body panels. The introduction of new vehicle models will further boost the need for stamping panels in manufacturing. Investments in Jiangsu province are enhancing manufacturing capabilities, while the adoption of high-strength steel in 60% of new vehicle models improves safety and reduces weight.
Evaluation of Restraints in China Stamping Metal Panels Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions | Engine Bay Panels | Material shortages have delayed production schedules, impacting delivery timelines for manufacturers. |
| Rising raw material costs | Decorative Panels | Increased costs of steel and aluminum are affecting pricing strategies for stamping panels. |
| Regulatory compliance requirements | Body Panels | Stricter emissions regulations necessitate more investments in compliance, affecting operational costs. |
| Technological adaptation challenges | Body Panels | Rapid advancements in manufacturing technology require constant investment, straining budgets for smaller producers. |
| Market competition from alternative materials | Body Panels | Growing use of composite materials in vehicle manufacturing poses a threat to traditional stamping panels. |
China Stamping Metal Panels Market Challenges
The China Stamping Metal Panels market faces a critical skills shortage, as the automotive sector employs around 5 million people but lacks enough qualified workers for advanced manufacturing techniques. Buyers encounter rising costs because the demand for high-strength steel, used in 60% of new vehicle models, has driven up prices for stamping metal panels. Supply chain disruptions are prevalent, with over 1,000 Tier 1 suppliers affected by new policies promoting electric vehicle production, leading to delays in panel availability. Regulatory pressures are intensifying, as stricter emissions regulations from the Ministry of Ecology and Environment require costly adjustments in manufacturing practices for compliance.
Trends in the China Stamping Metal Panels Market
Below mentioned are some of the trends shaping the China Stamping Metal Panels Market growth.
- Shift towards High-Strength Steel: Since 2022, the automotive industry has increasingly adopted high-strength steel for vehicle production. This shift, with 60% of new models using this material, compels suppliers to adapt their offerings and improve safety.
- Transition to Electric Vehicle Production: In 2023, a new policy promoting electric vehicle production has transformed the automotive sector. This change is driving demand for stamping panels tailored to electric vehicle designs, prompting manufacturers to innovate their processes.
- Emergence of Advanced Manufacturing Techniques: Starting in 2023, automotive manufacturers are prioritising advanced manufacturing techniques, such as precision stamping. This trend is expected to improve production efficiency and product quality, benefiting suppliers who adopt these methods.
- Increase in Vehicle Weight Reduction Targets: By 2025, the average vehicle weight reduction target of 10% will necessitate the use of lighter stamping panels. This requirement is pushing manufacturers to invest in innovative materials and processes.
Investment Opportunities in the China Stamping Metal Panels Market
Several openings in the China Stamping Metal Panels Market merit attention from investors.
- Joint Ventures with Local Manufacturers: Partnering with local manufacturers in Jiangsu province can facilitate entry into the market. With investments in automotive technology parks, this region presents opportunities for suppliers to meet growing demand.
- Supply of High-Strength Steel Panels: There is a rising need for high-strength steel stamping panels as safety standards evolve. Suppliers can target auto OEMs, who are increasingly adopting these materials in new vehicle models.
- Investment in Automation Technologies: Investing in automation technologies for stamping processes can improve efficiency. This opportunity aligns with the trend towards advanced manufacturing in the automotive sector, particularly in major hubs like Guangdong.
- Development of Lightweight Panels: The demand for lightweight stamping panels is increasing due to vehicle weight reduction targets. Suppliers should focus on innovative materials to cater to auto OEMs looking to improve fuel efficiency.
Government Initiatives in the China Stamping Metal Panels Market
The regulatory framework for the Stamping Metal Panels market in China includes several key laws and standards. The National Development and Reform Commission's Green Manufacturing Initiative, launched in 2020, promotes sustainable practices in manufacturing. The Ministry of Industry and Information Technology's Automotive Industry Development Policy (2021) encourages technological advancements and safety improvements in vehicle production. These measures require manufacturers to invest in compliance and innovation, impacting their operational strategies. Additionally, the Ministry of Ecology and Environment has enforced stricter emissions regulations since 2023, necessitating further investments in compliance.
In 2023, the Ministry of Industry and Information Technology introduced a program to enhance automotive safety standards, driving demand for high-quality stamping panels. The agency is responsible for approving new automotive technologies and standards, ensuring that manufacturers align with evolving regulations. This program is part of a broader effort to modernise the automotive sector, with funding allocated to support research and development initiatives. The National Development and Reform Commission also provides financial support for green manufacturing projects, fostering innovation in the industry.
Future Insight of the China Stamping Metal Panels Market
The outlook for the China Stamping Metal Panels market by 2032 hinges on several forward-looking factors. The Ministry of Industry and Information Technology's new automotive safety standards will increase the need for higher quality panels. Investment in automotive technology parks in Jiangsu province will stimulate innovation in manufacturing processes. By 2025, the average vehicle weight reduction target of 10% will necessitate lighter stamping solutions. The annual demand for stamping panels is expected to reach 15 million tons, indicating robust growth potential.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Panel Type – Body Panels Dominated, Structural Panels Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, Body Panels took a 38% share of panel type in 2025, more than any other category. Body panels hold the largest market share in China because they are extensively used in vehicle structures, making them indispensable for the automotive industry. With over 25 million vehicles produced in 2022, domestic auto manufacturers heavily rely on these panels for their vehicles. Over 2026–2032, Structural Panels are expected to post the fastest growth, at a CAGR of 9.4%. Structural panels are growing rapidly due to their essential role in maintaining vehicle integrity, particularly with new safety standards being introduced. The automotive sector's goal of achieving a 10% weight reduction by 2025 is further accelerating the demand for these components. Suppliers should focus on enhancing their structural panel offerings to align with the automotive industry's increasing safety and efficiency requirements.
By Metal Used – Aluminum/Steel Dominated, High-Strength Steel Expected to Grow Fastest
Aluminum/Steel accounted for a 48% market share by metal used in 2025. Aluminum and steel dominate the market share as they are the primary materials used in manufacturing stamping metal panels for the automotive sector. Their extensive application is highlighted by the fact that high-strength steel is increasingly utilised in 60% of new vehicle models. High-Strength Steel is projected to grow fastest, at a CAGR of 8.5% during 2026–2032. High-strength steel is the fastest-growing segment, driven by its rising preference for safety and weight reduction in vehicle design. This trend aligns with the automotive industry's objective of achieving a 10% weight reduction by 2025. Buyers should focus on sourcing high-strength steel to comply with the evolving safety and efficiency requirements in vehicle manufacturing.
By Process Type – Deep Drawing Dominated, Progressive Die Expected to Grow Fastest
With a 37% revenue share in 2025, Deep Drawing was the largest process type category. Deep drawing is the leading process type, as it is a primary method for forming complex shapes that are crucial in automotive applications. This technique is essential for producing body panels, which are integral to the overall vehicle structure. Progressive Die is set to record the highest CAGR in this split, 9.3% over 2026–2032. Progressive die processes are experiencing rapid growth due to their importance in high-volume production, which is vital for meeting the demands of the automotive sector. As production capacity increases, the efficiency of this method will further enhance its adoption. Suppliers must consider investing in progressive die technologies to meet the rising demand for efficient, high-volume stamping solutions.
By End User – Auto OEMs Dominated, Tier 1 Suppliers Expected to Grow Fastest
The largest end user category in 2025 was Auto OEMs, with a 45% share of total revenue. Auto OEMs represent the largest consumer group for stamping panels, as they require these components for vehicle assembly. The automotive industry's scale, producing over 25 million vehicles annually, underscores the significance of this segment. The quickest growth will come from Tier 1 Suppliers, forecast to expand at a CAGR of 8.1% between 2026 and 2032. Tier 1 suppliers are the fastest-growing end user segment, as they provide essential components to OEMs and are increasingly involved in the supply chain. Their role becomes more critical with the rise of electric vehicle production and new automotive technologies. Suppliers should strengthen relationships with Tier 1 suppliers to capture the growing opportunities within the automotive supply chain.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Stamping Metal Panels Market Outlook
- Market Size of China Stamping Metal Panels Market, 2025
- Forecast of China Stamping Metal Panels Market, 2032
- Historical Data and Forecast of China Stamping Metal Panels Revenues & Volume for the Period 2022 - 2032F
- China Stamping Metal Panels Market Trend Evolution
- China Stamping Metal Panels Market Drivers and Challenges
- China Stamping Metal Panels Price Trends
- China Stamping Metal Panels Porter's Five Forces
- China Stamping Metal Panels Industry Life Cycle
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Panel Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Body Panels for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Structural Panels for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Decorative Panels for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Engine Bay Panels for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Metal Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Aluminum/Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By High-Strength Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Stainless Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Galvanized Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Process Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Deep Drawing for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Progressive Die for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Embossing for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Precision Stamping for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Auto OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Tier 1 Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Interior Component Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Stamping Metal Panels Market Revenues & Volume By Vehicle Assembly Plants for the Period 2022 - 2032F
- China Stamping Metal Panels Import Export Trade Statistics
- Market Opportunity Assessment By Panel Type
- Market Opportunity Assessment By Metal Used
- Market Opportunity Assessment By Process Type
- Market Opportunity Assessment By End User
- China Stamping Metal Panels Top Companies Market Share
- China Stamping Metal Panels Competitive Benchmarking By Technical and Operational Parameters
- China Stamping Metal Panels Company Profiles
- China Stamping Metal Panels Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Panel Type
- Body Panels
- Structural Panels
- Decorative Panels
- Engine Bay Panels
By Metal Used
- Aluminum/Steel
- High-Strength Steel
- Stainless Steel
- Galvanized Steel
By Process Type
- Deep Drawing
- Progressive Die
- Embossing
- Precision Stamping
By End User
- Auto OEMs
- Tier 1 Suppliers
- Interior Component Makers
- Vehicle Assembly Plants































