China Startup Funding Market Size & Growth Rate
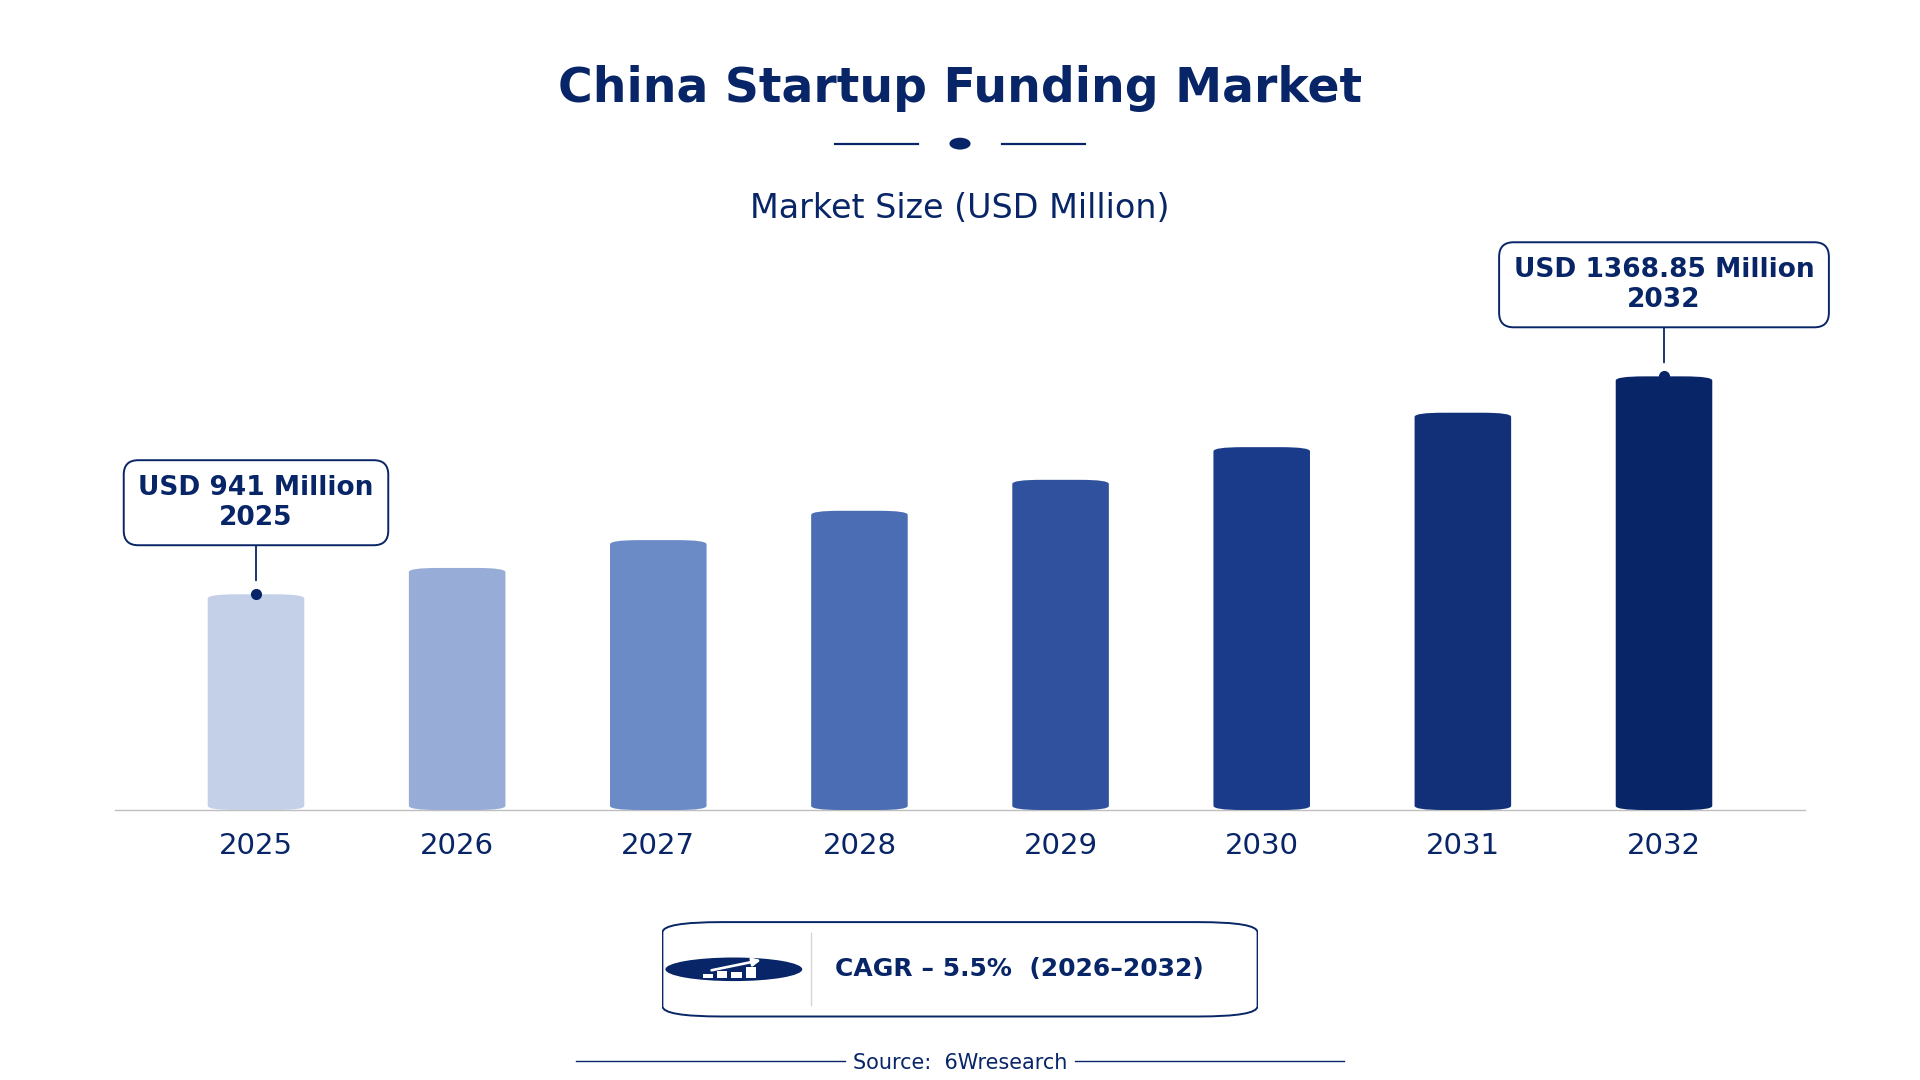
According to 6Wresearch internal database and industry insights, the China Startup Funding Market was valued at USD 941.0 million in 2025 and is projected to reach USD 1,368.85 million by 2032, growing at a CAGR of approximately 5.5% during 2026–2032.
China Startup Funding Market Highlights
| Report Metric | Details |
| Report Name | China Startup Funding Market |
| Market Size 2025 | USD 941.0 million |
| Market Size 2032 | USD 1,368.85 million |
| Absolute Growth 2025–2032 | USD 427.85 million |
| CAGR 2026–2032 | 5.5% |
| Peak Annual Growth | 7.5% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Funding Type, 2025 | Seed Funding (50% share) |
| Leading Stage Focus, 2025 | Early-Stage (45% share) |
| Leading Investor Type, 2025 | Angel Investors (42% share) |
| Leading End User, 2025 | Pre-Revenue Startups (50% share) |
| Fastest-Growing Funding Type | Series A/B Funding (7.5% CAGR) |
| Fastest-Growing Stage Focus | Growth Stage (6.7% CAGR) |
| Fastest-Growing Investor Type | Venture Capital Firms (7.3% CAGR) |
| Fastest-Growing End User | Scaling Startups (7.5% CAGR) |
| Growing Sector | Scaling Startups |
| Key End Users | Pre-Revenue Startups, Scaling Startups, High-Growth Startups, Tech & Consumer Startups |
China Startup Funding Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
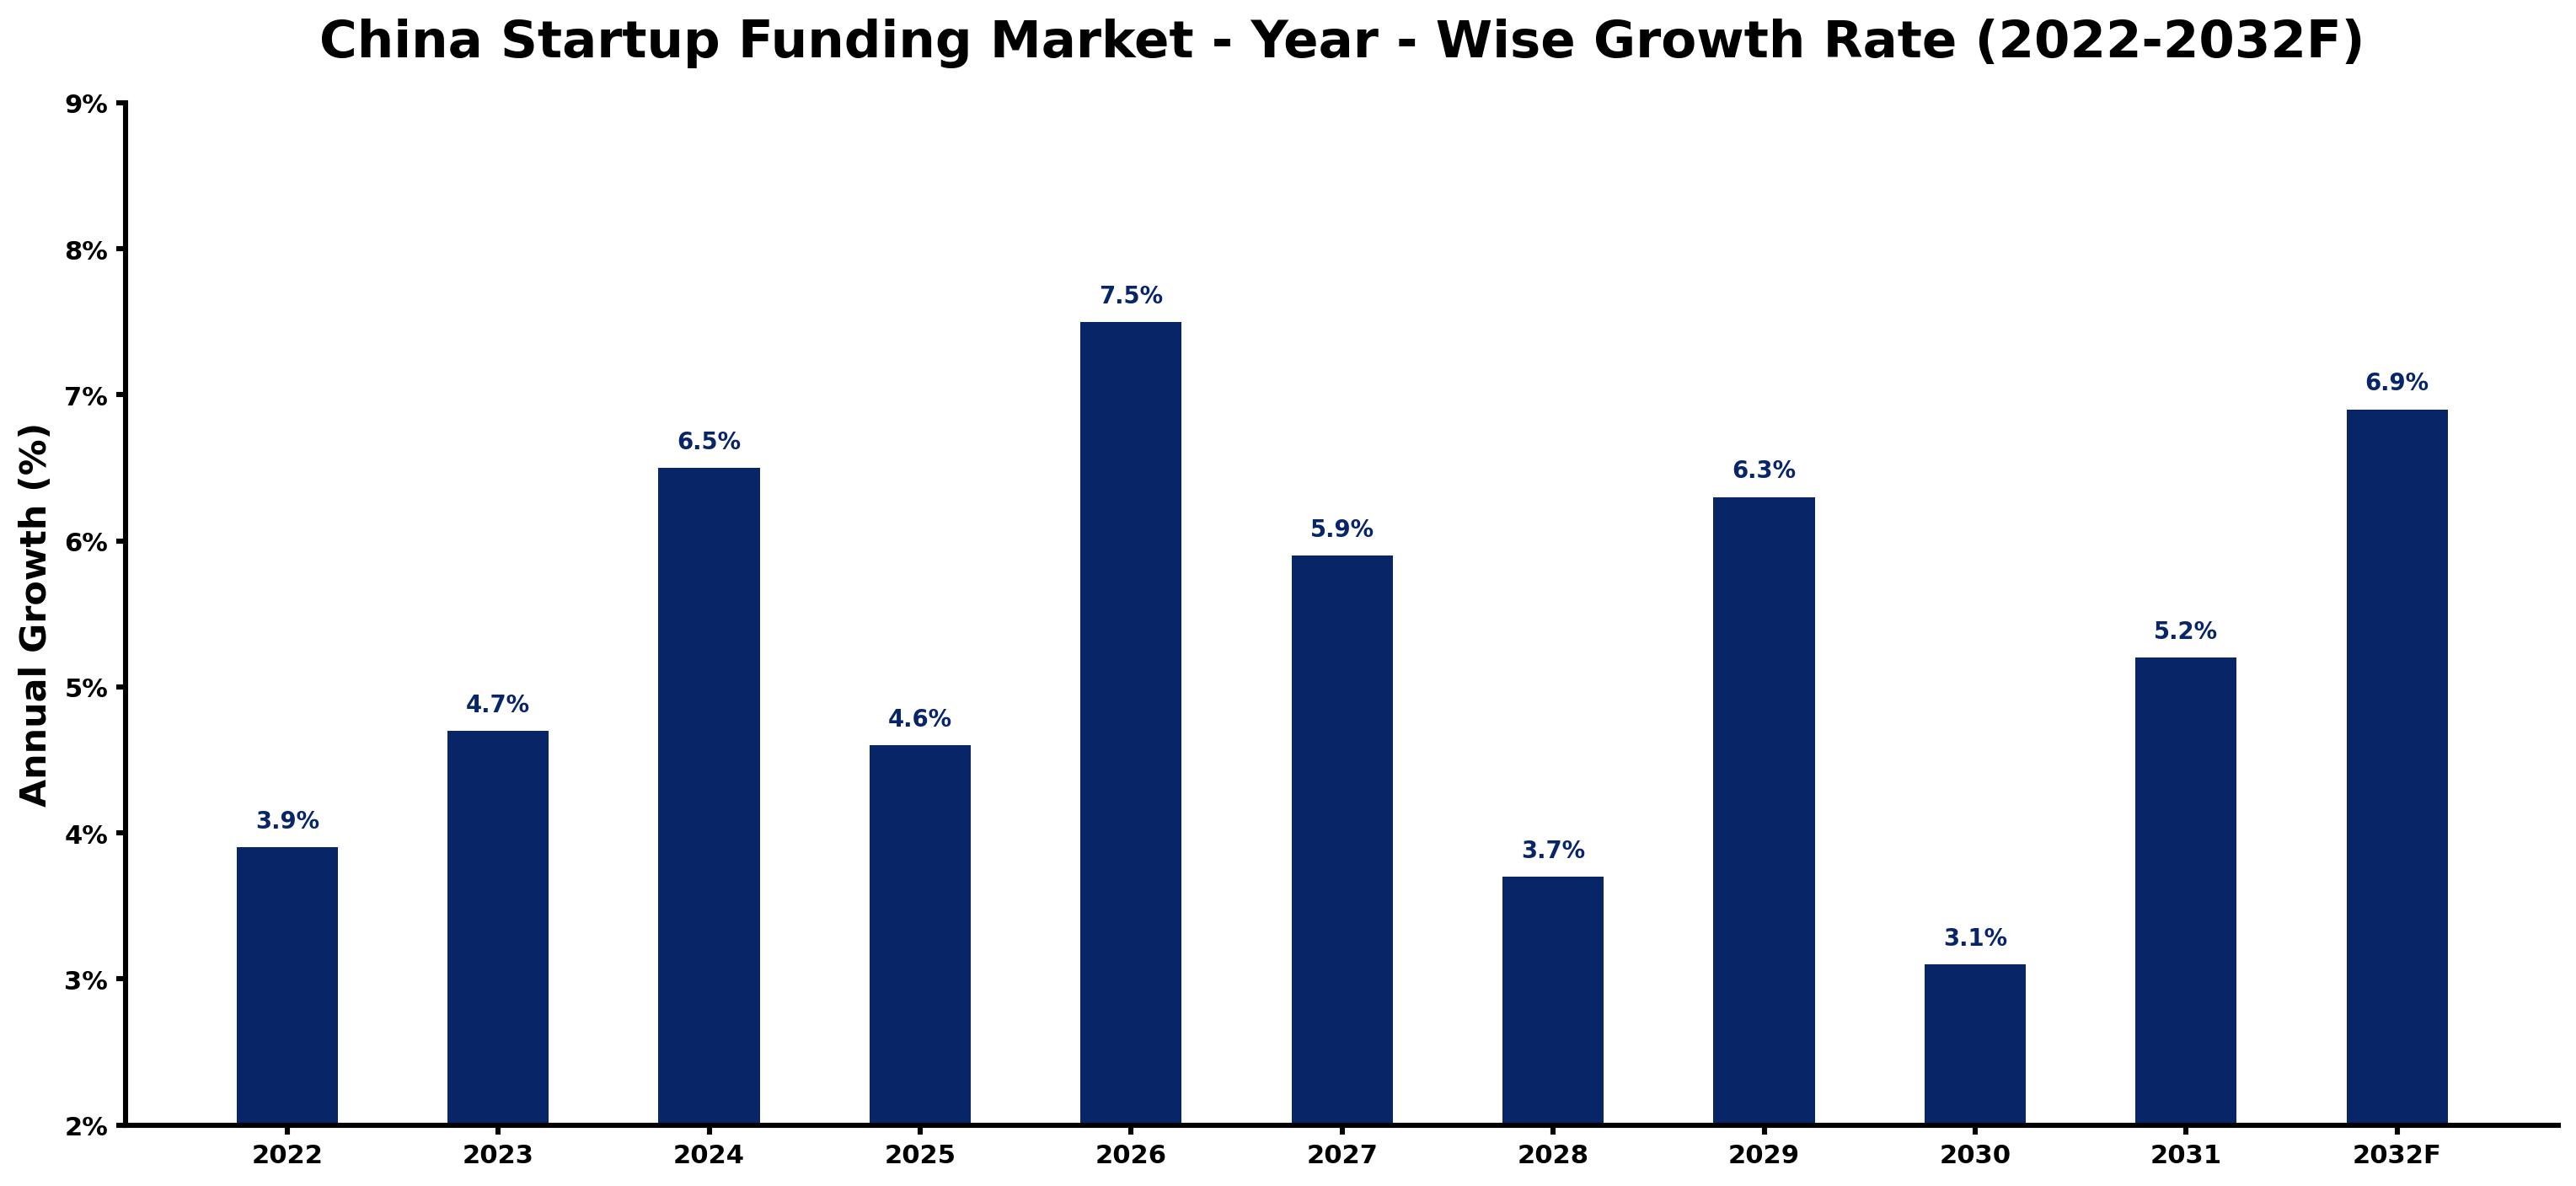
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.9 | The market showed steady growth with increasing activity from venture capital firms. |
| 2023 | 4.7 | Demand strengthened as more startups sought funding to scale their operations. |
| 2024 | 6.5 | Growth accelerated due to heightened investor interest in technology sectors. |
| 2025 | 4.6 | Funding growth slowed as the 'Innovation and Entrepreneurship Plan' began to take effect. |
| 2026 | 7.5 | The market rebounded with a surge in Series A funding rounds. |
| 2027 | 5.9 | Investment activity decelerated as the Beijing-Tianjin-Hebei region faced market saturation. |
| 2028 | 3.7 | Growth slowed again as economic uncertainties affected funding decisions. |
| 2029 | 6.3 | Investor confidence returned, boosting funding for high-growth startups in Shanghai. |
| 2030 | 3.1 | Market growth decelerated as funding became more selective among venture capital firms. |
| 2031 | 5.2 | Increased funding deals emerged as investor sentiment improved in the tech sector. |
| 2032 | 6.9 | The market is expected to grow steadily with new tech innovations from the 'Made in China 2025' initiative. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Startup Funding Market Synopsis
Startup Funding in China refers to financial support for new businesses, primarily in technology and consumer sectors. It encompasses various stages, including seed funding and Series A/B funding, essential for product development and market entry. The China Startup Funding Market is expanding due to a vibrant environment driven by over 1,000 active venture capital firms and significant contributions from angel investors. Major hubs like Beijing and Shanghai are central to this growth, with initiatives like the 'Innovation and Entrepreneurship Plan' adding new demand.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing number of active venture capital firms investing in startups | Driver | High | Venture Capital Firms |
| Growing interest in technology and consumer sectors | Driver | High | Tech & Consumer Startups |
| Emerging demand for innovative tech solutions | Opportunity | High | Seed Funding |
| Expansion of crowdfunding platforms attracting diverse investors | Opportunity | Medium | Crowdfunding |
| Market saturation in certain sectors limiting funding availability | Restraint | High | Growth Stage |
| Economic uncertainties affecting investor confidence | Restraint | Medium | Early-Stage |
| Buyers face challenges in securing funding due to market selectivity | Challenge | High | Pre-Revenue Startups |
| Suppliers struggle with fluctuating investor interest and competition | Challenge | Medium | Scaling Startups |
Evaluation of Drivers in China Startup Funding Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Venture capital firms are increasingly investing in high-potential startups | Venture Capital Firms | In 2022, over 1,000 active firms contributed to a vibrant funding environment. |
| Angel investors provide essential early-stage capital and mentorship | Angel Investors | They contributed around 15% of total startup funding in 2022. |
| Crowdfunding platforms are gaining traction for raising small amounts | Crowdfunding | In 2022, these platforms raised over 10 billion CNY, expanding funding avenues. |
| The 'Innovation and Entrepreneurship Plan' supports startup development | Early-Stage | Launched in 2021, it aims to promote innovation and entrepreneurship by funding startups. |
| Increased funding for tech startups driven by 'Made in China 2025' | Seed Funding | This initiative encourages investment in high-tech startups, boosting overall funding. |
The Startup Funding market in China is growing on the back of increasing interest from venture capital firms, angel investors, and crowdfunding platforms. In 2022, the average Series A funding round reached approximately 10 million CNY, indicating confidence in scaling startups. Additionally, the Beijing-Tianjin-Hebei region is seeing a rise in funding activity, with over 30 million registered startups creating a competitive landscape. This environment fosters innovation and attracts significant investment from various sources.
Evaluation of Restraints in China Startup Funding Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Market saturation in certain sectors limits funding opportunities | Growth Stage | In 2022, over 30 million startups created intense competition for limited funding. |
| Economic uncertainties lead to cautious investment behaviour | Early-Stage | In 2022, investors became more selective, impacting funding availability for new startups. |
| Fluctuating investor interest affects funding consistency | Scaling Startups | In 2022, changes in market sentiment delayed funding rounds for growing companies. |
| High operational costs can deter investment in startups | Pre-Revenue Startups | Startups faced challenges managing expenses while seeking funding, with costs consuming substantial resources. |
| Regulatory hurdles can slow down funding processes | Seed Funding | In 2022, compliance with local regulations delayed investment decisions for many startups. |
China Startup Funding Market Challenges
Startups in the China Startup Funding market face significant technology challenges, as rapid advancements can outstrip available funding, leading to delays in product development for new businesses. Regulatory hurdles arise from the China Securities Regulatory Commission's strict guidelines, which can extend the approval timeline for public funding platforms, restricting access to essential resources for startups. Compliance expenses can take up to 20% of a startup's initial funding, limiting the capital available for operational scaling. Intense competition among over 1,200 active venture capital firms inflates funding valuations, making it harder for startups to secure necessary capital without risking equity dilution.
Trends in the China Startup Funding Market
Four trends stand out in the China Startup Funding Market.
- Shift towards Crowdfunding: In 2022, crowdfunding platforms in China raised over 10 billion CNY, showcasing a notable trend. This shift enables startups to tap into a wider array of funding sources beyond traditional investors, facilitating the launch of more projects.
- Increase in Angel Investment: Angel investors represented 15% of total startup funding in 2022, indicating a growing trend. This increase bolsters early-stage startups, particularly in major hubs such as Beijing and Shanghai.
- Focus on Tech Startups: The 'Made in China 2025' initiative has shaped funding trends by promoting high-tech startups, resulting in heightened investments in innovative technologies that drive market growth.
- Growth in Series A Funding: The average Series A funding round in China reached about 10 million CNY in 2022, reflecting a trend towards larger investments. This growth demonstrates confidence in the scaling potential of startups and their prospects for success.
Investment Opportunities in the China Startup Funding Market
The following opportunities in the China Startup Funding Market pair current demand with a clear way in.
- Emerging Demand for Innovative Solutions: With over 30 million registered startups in China, there is a significant demand for tech solutions. Investors should focus on tech startups, particularly in the Beijing-Tianjin-Hebei region, to capitalize on this growing market.
- Crowdfunding as a Viable Investment Route: Crowdfunding platforms raised over 10 billion CNY in 2022, highlighting a gap in traditional funding. Investors can explore partnerships with these platforms to tap into a broader investor base.
- Support for High-Tech Startups: The 'Innovation and Entrepreneurship Plan' aims to support 100,000 startups annually by 2025. This presents an opportunity for investors to engage with emerging tech companies in major cities.
- Expansion of Venture Capital Investment: The Chinese government promotes venture capital investment in innovation, creating opportunities for investors. Collaborating with local venture capital firms can enhance access to promising startups.
Government Initiatives in the China Startup Funding Market
The 'Innovation and Entrepreneurship Plan' launched by the Ministry of Science and Technology in 2021 strengthens support for startups by providing funding and resources, building on earlier initiatives like the 'Made in China 2025' strategy. This framework seeks to simplify access to capital and promote innovation in high-tech sectors, ensuring startups receive necessary backing for growth and development.
In 2022, the China Securities Regulatory Commission approved over 200 public funding platforms, easing capital access for startups. The National Development and Reform Commission advocates for venture capital investments, having allocated 5 billion CNY to support innovation projects, ensuring startups can secure the funding needed to scale operations.
Future Insight of the China Startup Funding Market
The China Startup Funding market is set to evolve by 2032, propelled by the Ministry of Science and Technology's initiatives aimed at bolstering support for emerging businesses. Increased domestic investment will cultivate a more robust funding environment, allowing startups to flourish. The Shanghai Stock Exchange's revised regulations for tech IPOs will offer improved exit strategies for investors, promoting further capital influx. Crowdfunding platforms, which raised over 10 billion CNY in 2022, will maintain a crucial role in diversifying funding sources for startups.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Funding Type – Seed Funding Dominated, Series A/B Funding Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, Seed Funding accounted for a 50% market share by funding type in 2025. Seed funding dominates the market share in China due to its crucial role in enabling startups to develop their initial products and validate their business ideas. The average seed funding amount of approximately 1 million CNY in 2022 reflects its importance in the early stages of business development. Over 2026–2032, Series A/B Funding is expected to post the fastest growth, at a CAGR of 7.5%. Series A/B funding is experiencing the highest growth rate as it is essential for startups to scale their operations and achieve market entry, with average Series A funding rounds around 10 million CNY. As companies transition from seed funding to larger rounds, the demand for Series A/B funding will likely accelerate, further solidifying its position. Suppliers must focus on seed funding solutions while also gearing up for the anticipated rise in Series A/B funding opportunities.
By Stage Focus – Early-Stage Dominated, Growth Stage Expected to Grow Fastest
With a 45% revenue share in 2025, Early-Stage was the largest stage focus category. Early-stage funding commands the largest share as it is critical for startups just beginning their journey, providing the necessary capital to develop their concepts. This stage is vital for the survival of new businesses, especially in vibrant ecosystems like Beijing and Shanghai. Growth Stage is projected to grow fastest, at a CAGR of 6.7% during 2026–2032. Growth stage funding is the fastest-growing segment, as companies seek substantial investments to expand their operations and market presence. The increasing number of registered startups, over 30 million, indicates a rising need for funding at this stage to support their scaling efforts. Investors should prioritise early-stage opportunities while also preparing for the increasing demand for growth stage funding.
By Investor Type – Angel Investors Dominated, Venture Capital Firms Expected to Grow Fastest
The largest investor type category in 2025 was Angel Investors, with a 42% share of total revenue. Angel investors maintain the largest share of the market as they offer critical initial capital and mentorship, which are vital for startups during their formative stages. Their contribution, accounting for approximately 15% of total startup funding in 2022, underscores their pivotal role in fostering new ventures. The quickest growth will come from Venture Capital Firms, forecast to expand at a CAGR of 7.3% between 2026 and 2032. Venture capital firms are the fastest-growing investor type, driven by their focus on investing in high-potential startups for equity stakes. The reported 20% increase in funding deals in 2022 signals a strong demand for venture capital, indicating that this trend is likely to persist. Suppliers should create tailored approaches to engage both angel investors and venture capital firms to enhance their funding opportunities.
By End User – Pre-Revenue Startups Dominated, Scaling Startups Expected to Grow Fastest
Pre-Revenue Startups held a 50% share of the China Startup Funding Market by end user in 2025. Pre-revenue startups represent the largest market share as they heavily rely on funding to transition from concept to market-ready products, making them a key focus for investors. The active startup ecosystem in major urban centres like Beijing and Shanghai highlights the critical need for financial backing among these early-stage companies. Scaling Startups are set to record the highest CAGR in this split, 7.5% over 2026–2032. Scaling startups are the fastest-growing end user segment, as they require substantial funding to expand their operations and secure market presence. With an increasing number of startups aiming for rapid growth, this segment is expected to attract more investment in the coming years. Investors should adapt their strategies to effectively support both pre-revenue and scaling startups to capitalise on emerging opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Startup Funding Market Outlook
- Market Size of China Startup Funding Market, 2025
- Forecast of China Startup Funding Market, 2032
- Historical Data and Forecast of China Startup Funding Revenues & Volume for the Period 2022 - 2032F
- China Startup Funding Market Trend Evolution
- China Startup Funding Market Drivers and Challenges
- China Startup Funding Price Trends
- China Startup Funding Porter's Five Forces
- China Startup Funding Industry Life Cycle
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Funding Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Seed Funding for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Series A/B Funding for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Bridge Loans for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Crowdfunding for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Stage Focus for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Early-Stage for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Growth Stage for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Pre-Exit Stage for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Product Launch for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Investor Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Angel Investors for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Venture Capital Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Private Equity for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Public/Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Pre-Revenue Startups for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Scaling Startups for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By High-Growth Startups for the Period 2022 - 2032F
- Historical Data and Forecast of China Startup Funding Market Revenues & Volume By Tech & Consumer Startups for the Period 2022 - 2032F
- China Startup Funding Import Export Trade Statistics
- Market Opportunity Assessment By Funding Type
- Market Opportunity Assessment By Stage Focus
- Market Opportunity Assessment By Investor Type
- Market Opportunity Assessment By End User
- China Startup Funding Top Companies Market Share
- China Startup Funding Competitive Benchmarking By Technical and Operational Parameters
- China Startup Funding Company Profiles
- China Startup Funding Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Funding Type
- Seed Funding
- Series A/B Funding
- Bridge Loans
- Crowdfunding
By Stage Focus
- Early-Stage
- Growth Stage
- Pre-Exit Stage
- Product Launch
By Investor Type
- Angel Investors
- Venture Capital Firms
- Private Equity
- Public/Online Platforms
By End User
- Pre-Revenue Startups
- Scaling Startups
- High-Growth Startups
- Tech & Consumer Startups































