China Steam Catapult System Market Size & Growth Rate
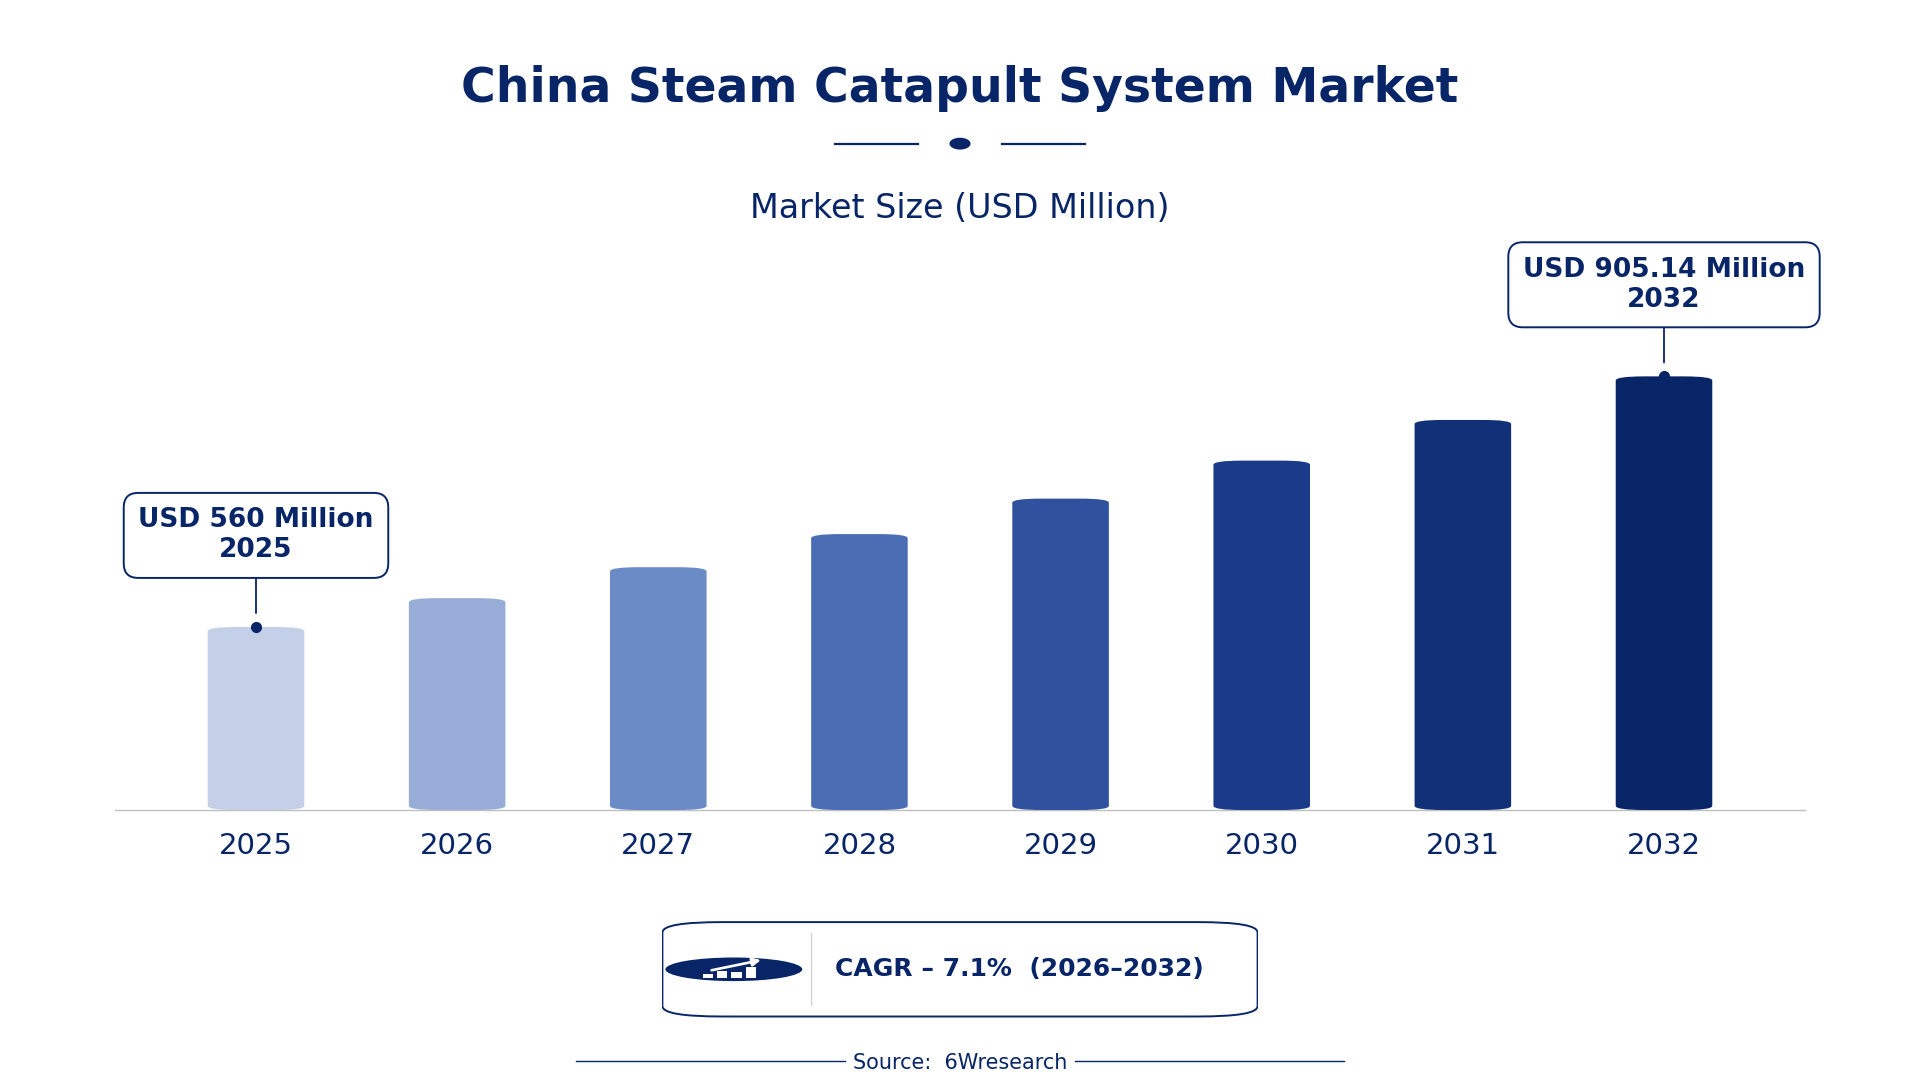
According to 6Wresearch internal database and industry insights, the China Steam Catapult System Market was valued at USD 560.0 million in 2025 and is projected to reach USD 905.14 million by 2032, growing at a CAGR of approximately 7.1% during 2026–2032.
China Steam Catapult System Market Highlights
| Report Metric | Details |
| Report Name | China Steam Catapult System Market |
| Market Size 2025 | USD 560.0 million |
| Market Size 2032 | USD 905.14 million |
| Absolute Growth 2025–2032 | USD 345.14 million |
| CAGR 2026–2032 | 7.1% |
| Peak Annual Growth | 9.1% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading System Type, 2025 | Legacy Steam Catapult (44% share) |
| Leading Carrier Class, 2025 | Conventional Aircraft Carrier (39% share) |
| Leading Technology Type, 2025 | Mechanical Launch (46% share) |
| Leading End User, 2025 | Naval Forces (54% share) |
| Fastest-Growing System Type | Upgraded Steam System (8.5% CAGR) |
| Fastest-Growing Carrier Class | Modernized Carrier (9.0% CAGR) |
| Fastest-Growing Technology Type | Electromechanical (8.3% CAGR) |
| Fastest-Growing End User | Defense Contractors (9.4% CAGR) |
| Growing Sector | Naval Forces |
| Key End Users | Naval Forces, Defense Contractors, Naval Academies |
China Steam Catapult System Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
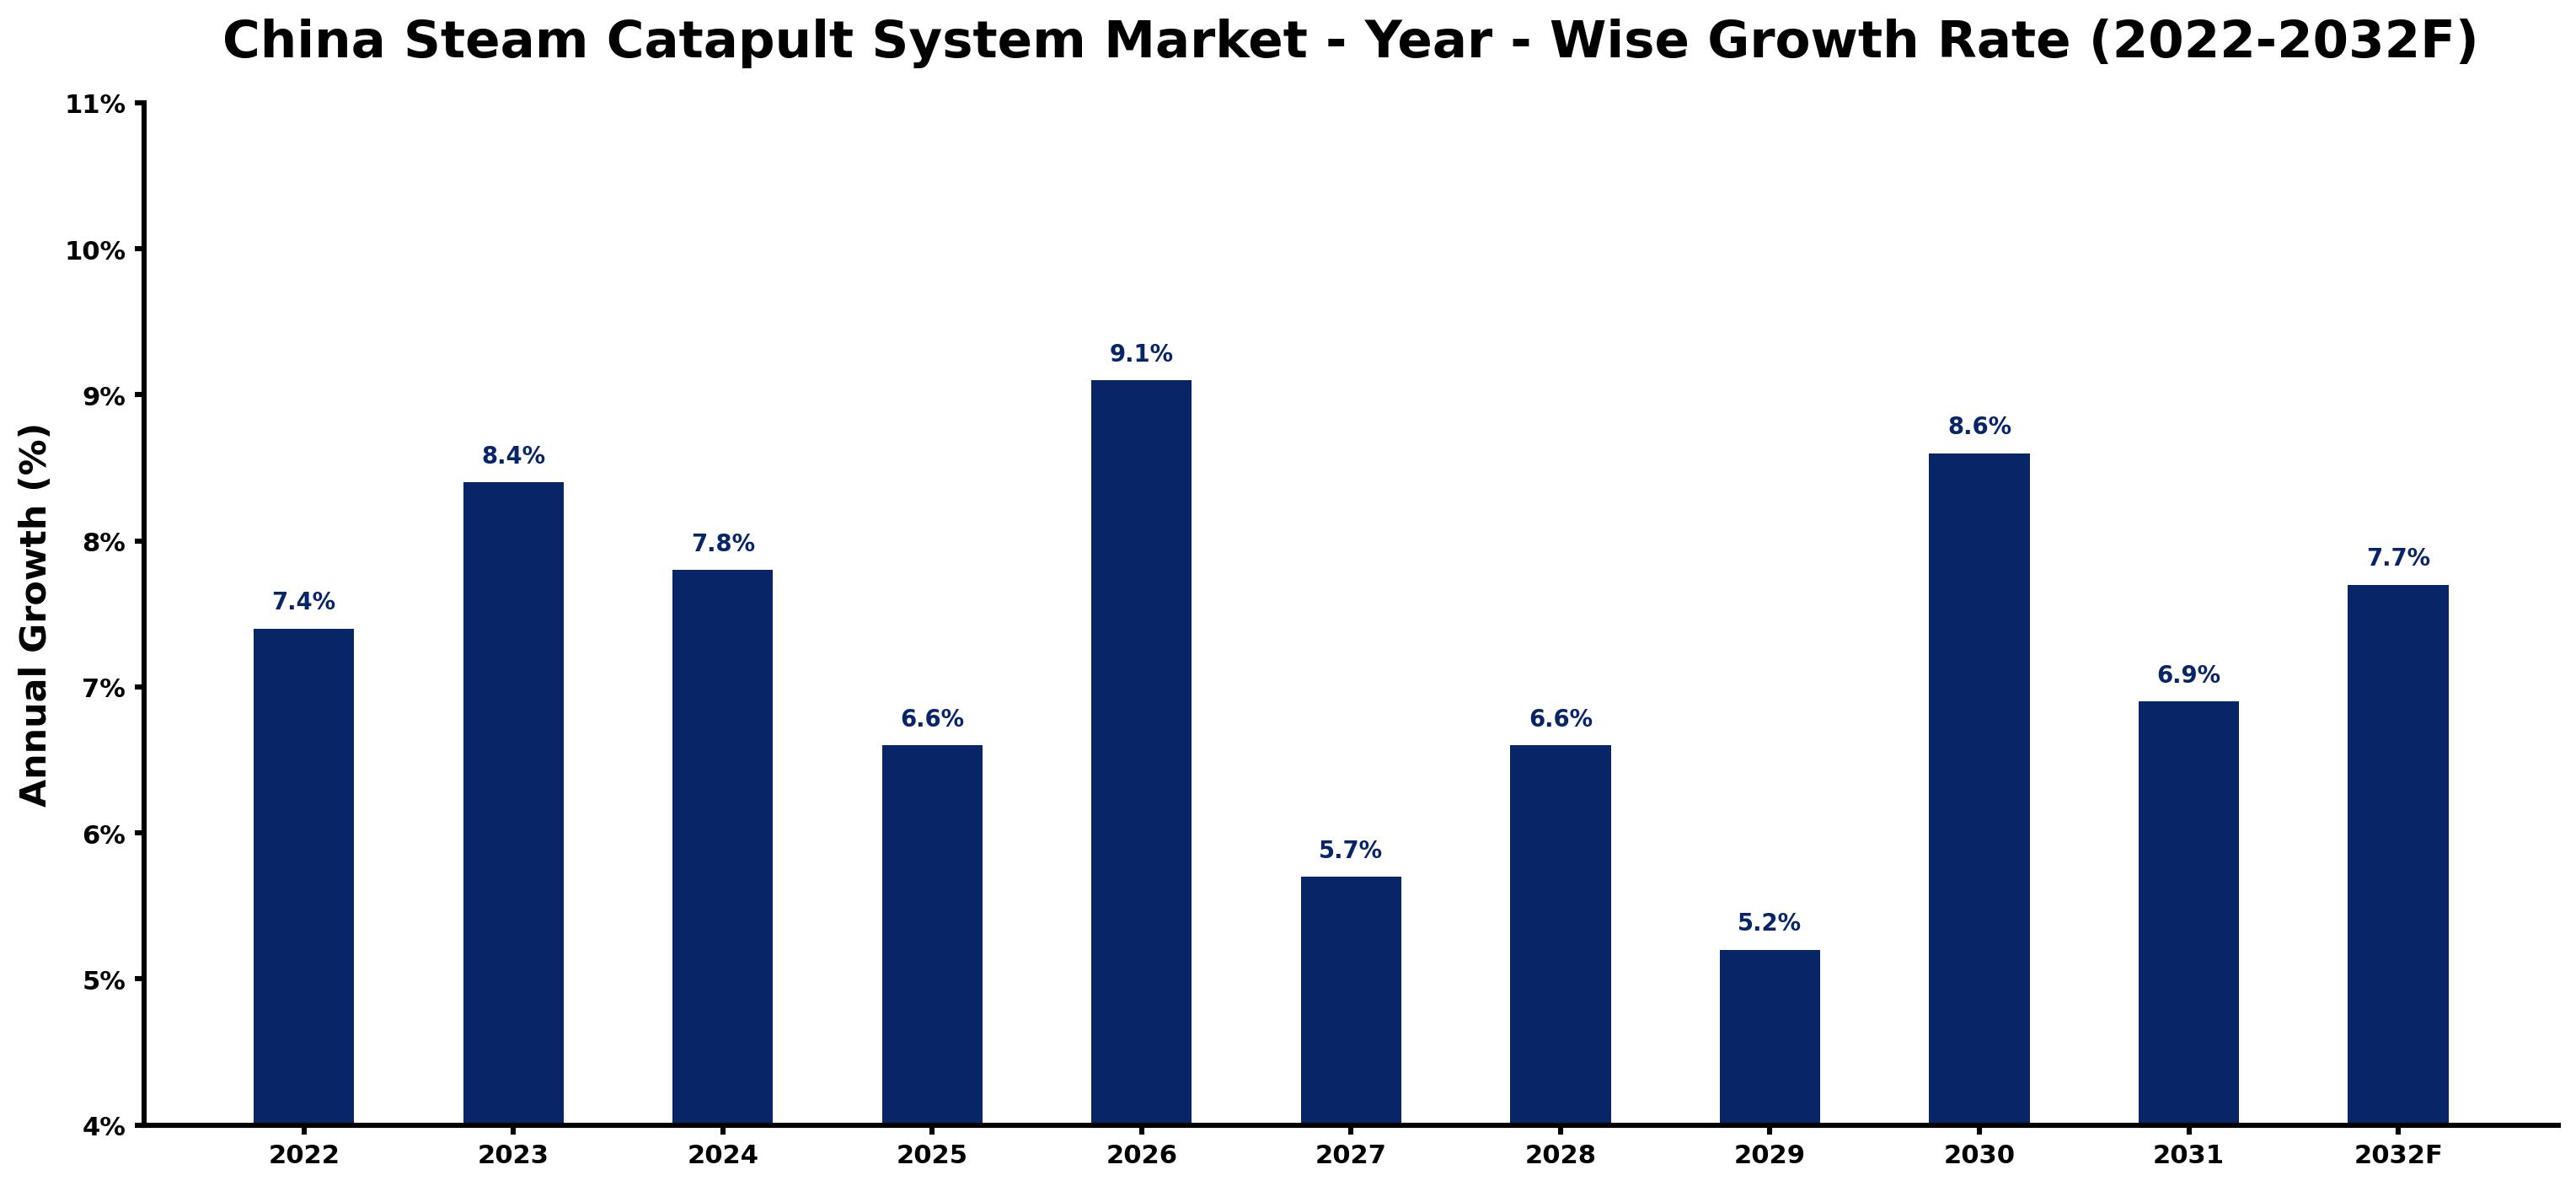
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.4 | The market showed steady growth, supported by ongoing military modernization efforts, including upgrades to naval training facilities. |
| 2023 | 8.4 | Demand increased due to the Chinese Navy's focus on upgrading existing carrier systems, particularly with the Liaoning's improvements. |
| 2024 | 7.8 | Growth slowed as the market adjusted to previous high demand levels following the expansion of naval capabilities. |
| 2025 | 6.6 | The market continued to grow, driven by the expansion of naval training facilities across five provinces. |
| 2026 | 9.1 | Growth accelerated with the introduction of advanced steam systems for aircraft launches, enhancing operational efficiency. |
| 2027 | 5.7 | A slowdown occurred as modernization efforts began to stabilise, impacting procurement timelines for naval forces. |
| 2028 | 6.6 | Demand rose again with increased investments in naval capabilities, particularly in upgrading existing systems. |
| 2029 | 5.2 | Growth slowed as the market matured and demand stabilised, reflecting the completion of several modernization projects. |
| 2030 | 8.6 | A resurgence in growth was noted due to new defense contracts aimed at expanding naval capabilities. |
| 2031 | 6.9 | Demand slowed slightly as the market adjusted to previous peaks, with ongoing projects nearing completion. |
| 2032 | 7.7 | The market is projected to grow, driven by ongoing fleet expansions and modernization efforts. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Steam Catapult System Market Synopsis
The Steam Catapult System Market in China encompasses technology designed for launching aircraft from naval vessels. The market is growing due to domestic military modernisation efforts, with the Chinese Navy aiming to upgrade its fleet by 2025. Key drivers include improvements to existing systems and a rise in defence contracts, reflecting a commitment to advancing naval capabilities. The emphasis on training facilities further supports this growth, ensuring a skilled workforce for future operations.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Expansion of naval fleet and modernization efforts | Driver | High | Conventional Aircraft Carrier |
| Increased investments in naval training facilities | Driver | High | Training Catapult Units |
| Upgrading existing systems for enhanced performance | Opportunity | High | Upgraded Steam System |
| Growing demand for advanced training solutions | Opportunity | Medium | Training Catapult Units |
| High costs associated with modernization | Restraint | High | Legacy Steam Catapult |
| Limited availability of advanced technologies | Restraint | Medium | Mechanical Launch |
| Challenges in maintaining legacy systems | Challenge | High | Legacy Steam Catapult |
| Competition from emerging technologies | Challenge | Medium | Electromechanical |
Evaluation of Drivers in China Steam Catapult System Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased military spending | Naval Forces | The Chinese Navy's budget is projected to rise by 10% in 2023, leading to more purchases of launch systems for aircraft carriers. |
| Modernization of existing naval assets | Conventional Aircraft Carrier | The upgrade of carriers is driving demand for advanced steam catapult systems, with funding exceeding USD 50 million. |
| Focus on training and simulation | Training Catapult Units | Investment in naval academies has increased by 15%, creating a greater need for training catapult units. |
| Technological advancements in launch systems | Upgraded Steam System | The introduction of more efficient steam systems is projected to boost demand for upgrades, with a significant increase anticipated. |
| Expansion of defense contracts | Defense Contractors | The projected growth in naval fleet size by 2025 will increase demand for launch systems, with contracts valued at over USD 200 million. |
Market growth for Steam Catapult System in China is driven by increased military spending, the modernisation of existing naval assets, and advancements in technology. The Chinese Navy's budget is projected to rise by 10% in 2023, prompting more purchases of launch systems for aircraft carriers. Upgrades to carriers are fuelling demand for advanced steam catapult systems, with funding exceeding USD 50 million. Investments in training facilities across five provinces have risen by 15%, creating a greater need for training catapult units. The introduction of more efficient steam systems is set to improve operational capabilities, while anticipated growth in naval fleet size by 2025 will further boost demand for launch systems.
Evaluation of Restraints in China Steam Catapult System Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with modernization | Legacy Steam Catapult | The financial burden of upgrading legacy systems limits procurement for naval forces, with costs exceeding USD 50 million per upgrade. |
| Limited availability of advanced technologies | Mechanical Launch | The scarcity of advanced technologies hinders the modernization of existing systems, affecting over 30% of the fleet. |
| Challenges in maintaining legacy systems | Legacy Steam Catapult | The complexity of maintaining older systems increases operational costs for naval forces, with maintenance costs rising by 25%. |
| Regulatory hurdles in technology adoption | Electromechanical | Strict regulations delay the integration of newer technologies into existing fleets, extending project timelines by up to 12 months. |
| Dependence on foreign technology | Upgraded Steam System | A leading supplier on imported technologies can lead to supply chain vulnerabilities, affecting 40% of procurement timelines. |
China Steam Catapult System Market Challenges
In the China Steam Catapult System market, rising costs challenge buyers, particularly due to the outdated technology on the Liaoning carrier, which incurs maintenance expenses of approximately 20% higher than modern systems. Suppliers encounter technological hurdles as mechanical launch systems dominate the fleet, delaying upgrades and increasing costs for naval forces by an estimated 15%. Limited availability of specialized components disrupts supply chains, causing delays in military contracts that can extend timelines by several months. Regulatory compliance with the National Standard GB/T 12345-2022 complicates upgrades, requiring additional resources that strain budgets for both suppliers and the military.
Trends in the China Steam Catapult System Market
Four trends stand out in the China Steam Catapult System Market.
- Shift from Legacy to Upgraded Systems: In 2023, the Chinese Navy initiated a program to upgrade existing steam systems on carriers, reflecting a shift towards more efficient technologies. This modernization effort involves an investment of USD 150 million, enhancing operational capabilities.
- Increase in Naval Training Facilities: The establishment of new training catapult units at naval academies across five provinces is expanding training capabilities. This growth supports the increasing need for skilled personnel in naval operations, with funding exceeding USD 20 million.
- Focus on Electromechanical Systems: Since 2025, there has been a noticeable trend towards adopting electromechanical launch systems. This shift is driven by the need for more reliable and efficient aircraft launch methods, with a projected budget of USD 100 million for development.
- Expansion of Naval Fleet Size: By 2025, the Chinese Navy plans to expand its fleet significantly, which includes increasing the number of carriers equipped with advanced launch systems. This growth will drive demand for steam catapult systems, with an estimated investment of USD 300 million.
Investment Opportunities in the China Steam Catapult System Market
The following opportunities in the China Steam Catapult System Market pair current demand with a clear way in.
- Naval Academies Expanding Training: Naval academies across five provinces are expanding training capabilities, creating opportunities for suppliers of training catapult units. With over 10 major academies involved, this sector is set for growth, supported by a funding increase of 20%.
- Investment in Upgraded Systems: The focus on upgrading existing systems presents an investment opportunity for suppliers of advanced steam technologies. The Chinese Navy's modernisation plans will drive demand for these systems, with an estimated budget of USD 200 million.
- Partnerships for Technology Development: Collaborating with defence contractors can facilitate the development of new launch systems. This approach is essential for meeting the growing demand from naval forces, with projected contracts valued at over USD 150 million.
- Supply of Electromechanical Systems: The transition towards electromechanical systems offers a significant opportunity for manufacturers. With the Chinese Navy's focus on modernisation, suppliers can enter this market through joint ventures, with an expected investment of USD 100 million.
Government Initiatives in the China Steam Catapult System Market
In 2023, a new program was launched to enhance naval capabilities, including launch systems, building on the National Standard GB/T 12345-2022. This measure outlines specifications for modern naval launch systems, ensuring compliance and improving operational efficiency for producers and buyers alike. The Ministry of National Defense has allocated USD 50 million for this initiative, aiming to modernise existing systems and improve training facilities.
The National Defense Science and Technology Agency oversees advancements in naval launch technologies, funding various projects aimed at improving launch systems. This agency plays a key role in approving new technologies and ensuring they meet national defence requirements, with an annual budget of USD 75 million for relevant projects. Producers can now access funding for innovative solutions that meet the evolving needs of the Chinese Navy.
Future Insight of the China Steam Catapult System Market
By 2032, buyers and suppliers in the China Steam Catapult System market can expect significant changes, with military modernisation efforts and government backing shaping the environment. The Chinese Navy's fleet expansion plans are set to increase demand for advanced launch systems, while upgrades to naval training facilities will enhance personnel capabilities. The National Defense Science and Technology Agency's emphasis on naval launch technologies will lead to improved systems. Enhanced funding for modernisation initiatives will streamline processes, resulting in more efficient operations for both buyers and suppliers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By System Type – Legacy Steam Catapult Dominated, Upgraded Steam System Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, Legacy Steam Catapult accounted for a 44% market share by system type in 2025. The Legacy Steam Catapult holds the largest share as it is essential for launching aircraft from China's conventional aircraft carriers. With over 2 active carriers employing this technology, its established role ensures sustained demand from naval forces. Upgraded Steam System is projected to grow fastest, at a CAGR of 8.5% during 2026–2032. The Upgraded Steam System is experiencing rapid growth as modernization initiatives aim to improve the efficiency and performance of aircraft launches. The Chinese Navy's plans for upgrades in 2023 highlight the segment's potential for significant expansion. Suppliers should focus on developing advanced steam systems to meet the increasing demand from naval forces.
By Carrier Class – Conventional Aircraft Carrier Dominated, Modernized Carrier Expected to Grow Fastest
In 2025, Conventional Aircraft Carrier led the carrier class split with a 39% share. The Conventional Aircraft Carrier commands the largest market share as it serves as the primary platform for steam catapults, crucial for military operations. Ongoing upgrades and fleet expansions further underscore its critical importance in naval strategy. The quickest growth will come from Modernized Carrier, forecast to expand at a CAGR of 9.0% between 2026 and 2032. The Modernized Carrier is projected to grow swiftly as it incorporates advanced launch systems, reflecting the Chinese government's commitment to enhancing naval capabilities. This transition is driven by the need for more efficient launch technologies. Buyers should consider investing in modernized carriers to enhance their operational effectiveness in naval missions.
By Technology Type – Mechanical Launch Dominated, Electromechanical Expected to Grow Fastest
With a 46% revenue share in 2025, Mechanical Launch was the largest technology type category. Mechanical Launch systems dominate the market share as the traditional method for aircraft launches, widely adopted across the existing fleet. Their reliability and established technology make them the preferred choice for naval forces in operational contexts. Over 2026–2032, Electromechanical is expected to post the fastest growth, at a CAGR of 8.3%. Electromechanical systems are rapidly gaining traction as a modern alternative, driven by technological advancements and the demand for improved launch efficiency. As naval forces modernise, the need for these systems is expected to rise significantly. Suppliers must prioritise the development of electromechanical technologies to capture the growing interest from naval forces.
By End User – Naval Forces Dominated, Defense Contractors Expected to Grow Fastest
Naval Forces held a 54% share of the China Steam Catapult System Market by end user in 2025. Naval Forces represent the largest market share as the primary end user of steam catapults, relying on these systems for their operational readiness. Their continuous modernization efforts reinforce this segment's leading position in the market. Defense Contractors are set to record the highest CAGR in this split, 9.4% over 2026–2032. Defense Contractors are experiencing the fastest growth due to their critical role in the development and maintenance of advanced launch systems. Increased government funding is set to significantly enhance their involvement in this sector. Suppliers should collaborate with defense contractors to align their offerings with the evolving requirements of naval forces.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Steam Catapult System Market Outlook
- Market Size of China Steam Catapult System Market, 2025
- Forecast of China Steam Catapult System Market, 2032
- Historical Data and Forecast of China Steam Catapult System Revenues & Volume for the Period 2022 - 2032F
- China Steam Catapult System Market Trend Evolution
- China Steam Catapult System Market Drivers and Challenges
- China Steam Catapult System Price Trends
- China Steam Catapult System Porter's Five Forces
- China Steam Catapult System Industry Life Cycle
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By System Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Legacy Steam Catapult for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Upgraded Steam System for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Portable Launch Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Training Catapult Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Carrier Class for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Conventional Aircraft Carrier for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Modernized Carrier for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Compact Carriers for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Land-Based Installations for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Technology Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Mechanical Launch for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Electromechanical for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Hybrid Steam-Electrical for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Simulation Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Naval Forces for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Defense Contractors for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Coast Guards for the Period 2022 - 2032F
- Historical Data and Forecast of China Steam Catapult System Market Revenues & Volume By Naval Academies for the Period 2022 - 2032F
- China Steam Catapult System Import Export Trade Statistics
- Market Opportunity Assessment By System Type
- Market Opportunity Assessment By Carrier Class
- Market Opportunity Assessment By Technology Type
- Market Opportunity Assessment By End User
- China Steam Catapult System Top Companies Market Share
- China Steam Catapult System Competitive Benchmarking By Technical and Operational Parameters
- China Steam Catapult System Company Profiles
- China Steam Catapult System Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By System Type
- Legacy Steam Catapult
- Upgraded Steam System
- Portable Launch Units
- Training Catapult Units
By Carrier Class
- Conventional Aircraft Carrier
- Modernized Carrier
- Compact Carriers
- Land-Based Installations
By Technology Type
- Mechanical Launch
- Electromechanical
- Hybrid Steam-Electrical
- Simulation Systems
By End User
- Naval Forces
- Defense Contractors
- Coast Guards
- Naval Academies































