China Steel Production Equipment Market Size & Growth Rate
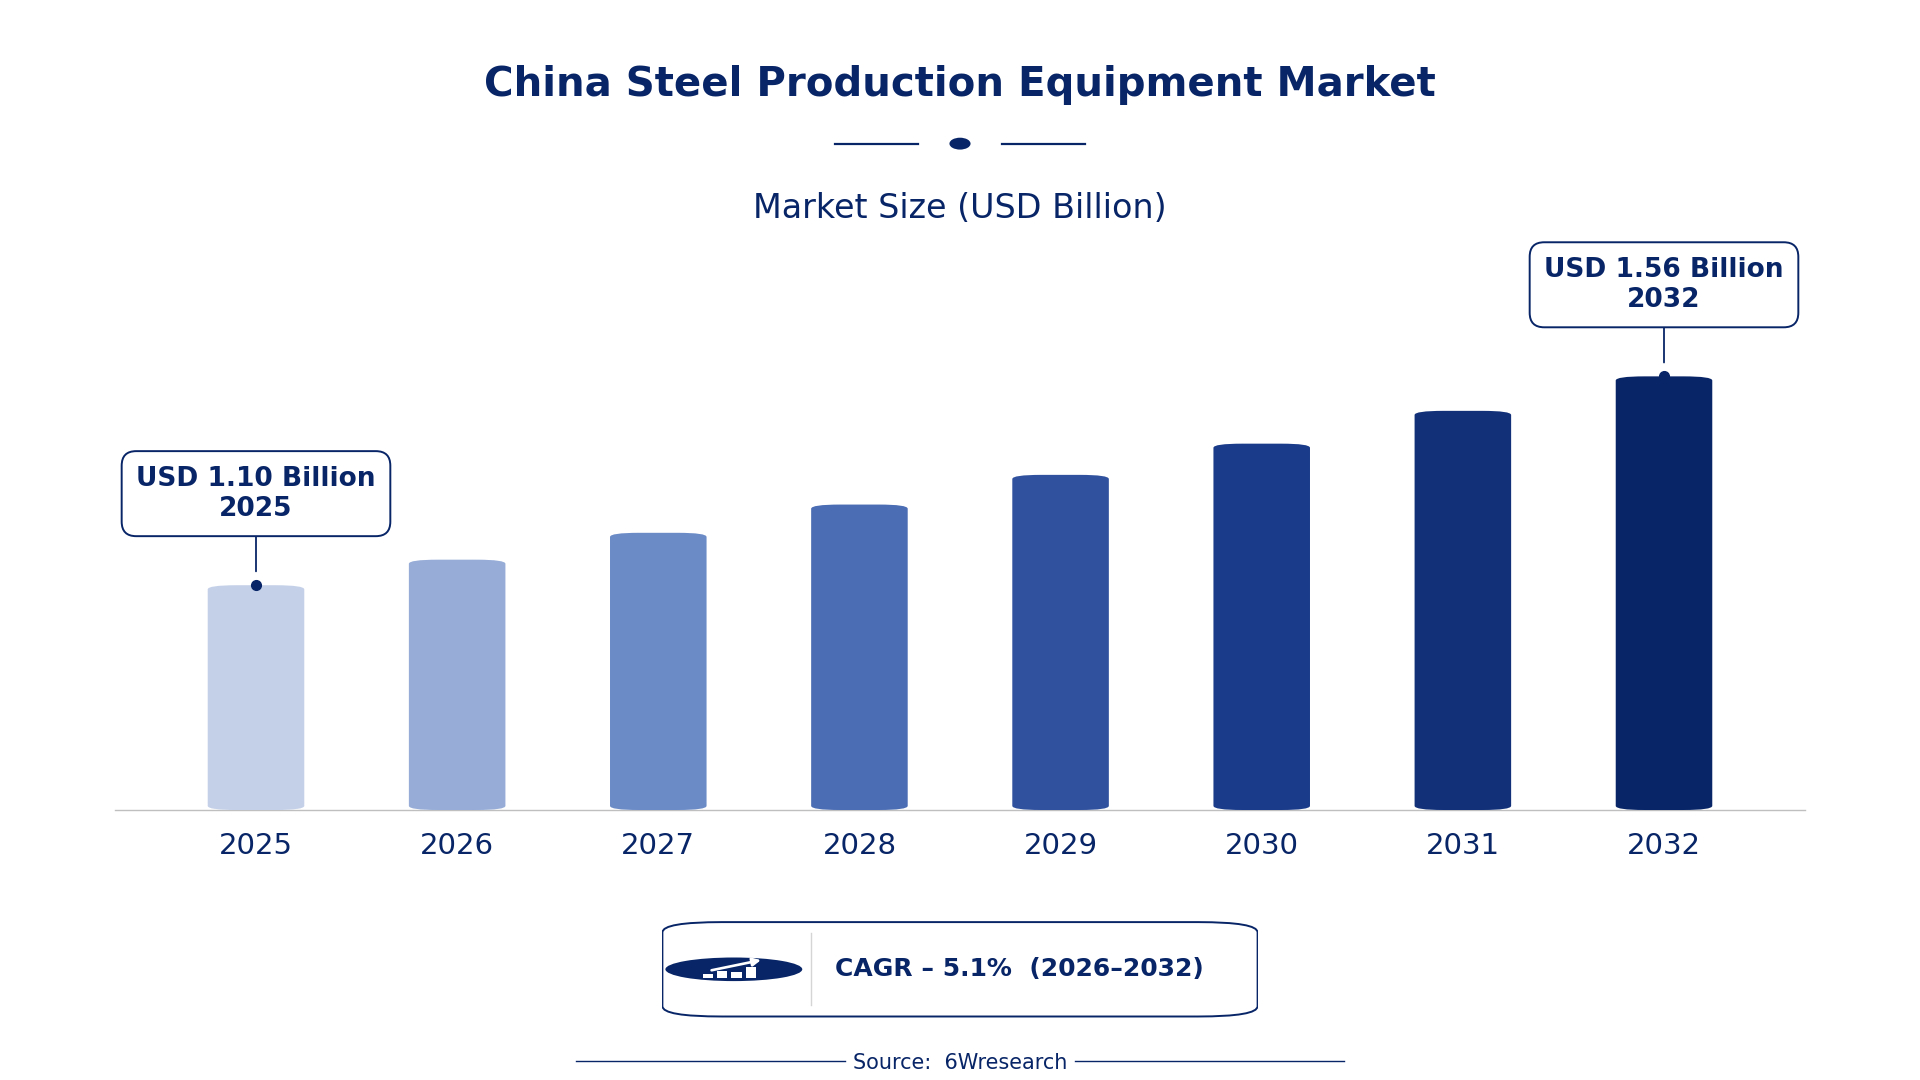
According to 6Wresearch internal database and industry insights, the China Steel Production Equipment Market was valued at USD 1.10 billion in 2025 and is projected to reach USD 1.56 billion by 2032, growing at a CAGR of approximately 5.1% during 2026–2032.
China Steel Production Equipment Market Highlights
| Report Metric | Details |
| Report Name | China Steel Production Equipment Market |
| Market Size 2025 | USD 1.10 billion |
| Market Size 2032 | USD 1.56 billion |
| Absolute Growth 2025–2032 | USD 0.46 billion |
| CAGR 2026–2032 | 5.1% |
| Peak Annual Growth | 7.2% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Equipment Type, 2025 | Blast Furnace Machinery (40% share) |
| Leading Process Stage, 2025 | Smelting (47% share) |
| Leading Automation Level, 2025 | Semi-Automated (41% share) |
| Leading End User, 2025 | Steel Manufacturing Plants (35% share) |
| Fastest-Growing Equipment Type | Casting Machines (6.9% CAGR) |
| Fastest-Growing Process Stage | Casting (7.4% CAGR) |
| Fastest-Growing Automation Level | Fully Automated (7.2% CAGR) |
| Fastest-Growing End User | Foundries (7.6% CAGR) |
| Growing Sector | Construction |
| Key End Users | Steel Manufacturing Plants, Foundries, Heavy Industry Units, Metal Fabrication Plants |
China Steel Production Equipment Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
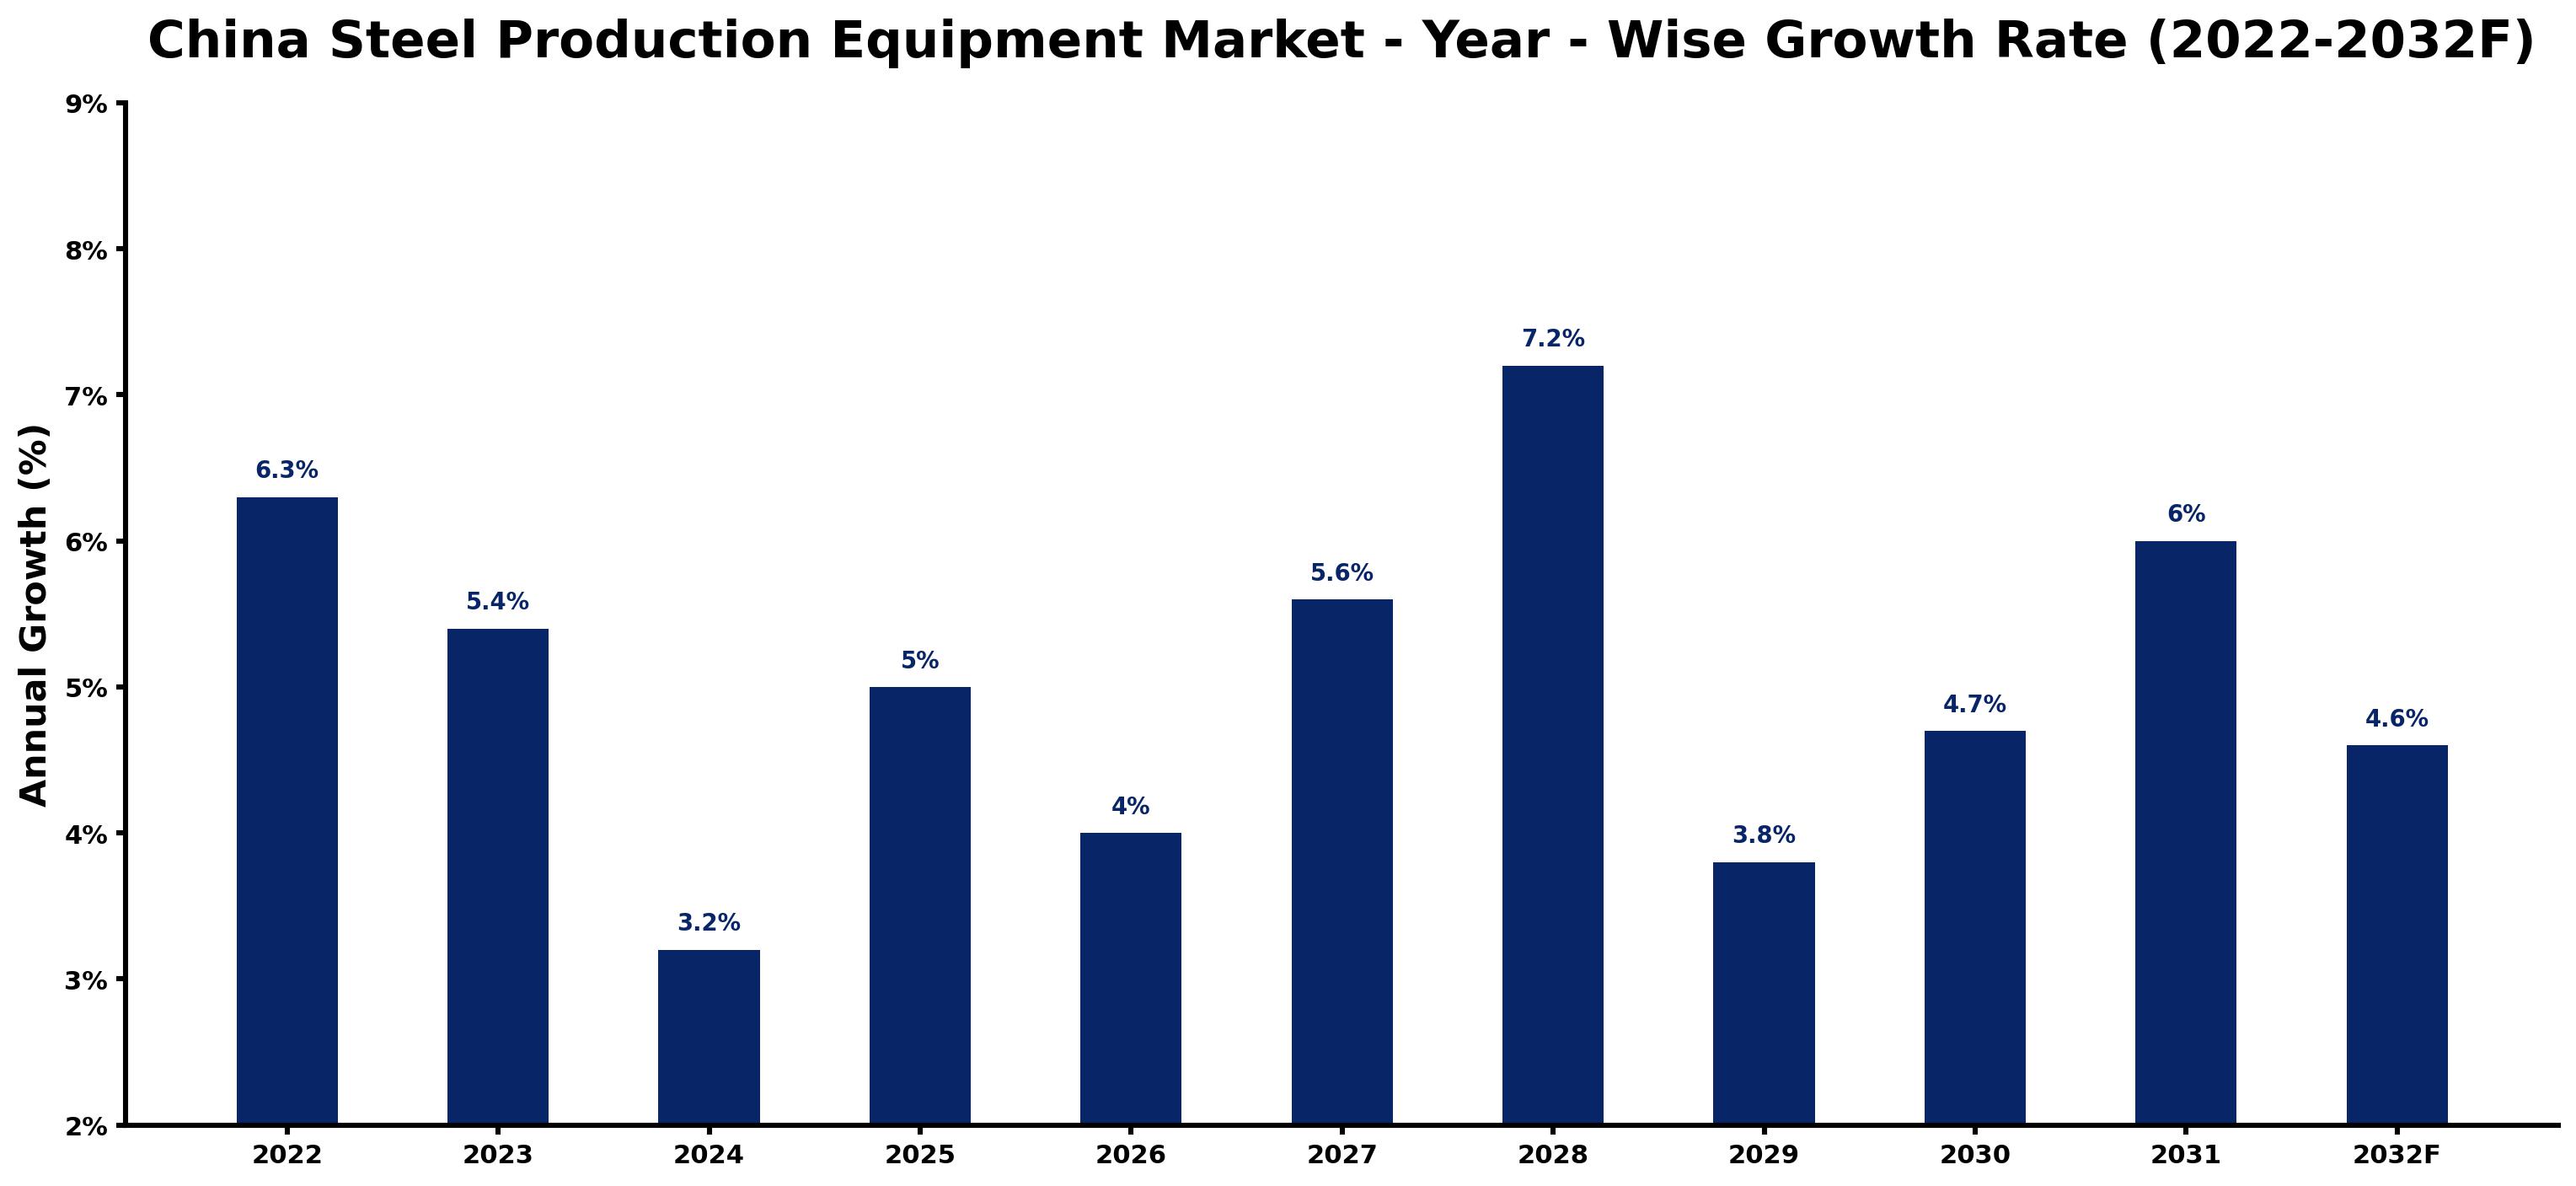
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.3 | The market experienced strong demand due to ongoing infrastructure projects in the country. |
| 2023 | 5.4 | Growth slowed as the market adjusted to the high production levels set by the Steel Industry Development Plan. |
| 2024 | 3.2 | Demand continued to moderate as the market faced challenges from the national standard GB/T 1591-2018. |
| 2025 | 5.0 | A resurgence in infrastructure investments led to faster growth in steel production equipment demand. |
| 2026 | 4.0 | Growth is expected to slow as the market faces challenges in meeting environmental standards and regulations. |
| 2027 | 5.6 | Increased investment in automation technologies is projected to spur demand for advanced steel production equipment. |
| 2028 | 7.2 | The market is expected to peak as major infrastructure projects reach completion, driving demand to new heights. |
| 2029 | 3.8 | Growth is projected to slow as the market adjusts to the peak demand levels of the previous year. |
| 2030 | 4.7 | A rebound in industrial activity is expected to lead to renewed interest in steel production equipment purchases. |
| 2031 | 6.0 | Demand is projected to increase as manufacturers seek to upgrade equipment to meet new efficiency standards. |
| 2032 | 4.6 | Growth is expected to slow as market saturation and competition begin to impact purchasing decisions. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Steel Production Equipment Market Synopsis
Steel Production Equipment in China encompasses machinery essential for manufacturing steel, including blast furnaces and rolling equipment. The equipment is produced through advanced engineering processes and is vital for industries like construction and automotive. The China Steel Production Equipment Market is growing due to domestic demand driven by infrastructure projects and industrial growth, with production reaching 1,000 million tons in 2022. The ongoing 'Steel Industry Development Plan' aims to modernise the sector and improve production efficiency, benefiting key buyers such as Steel Manufacturing Plants and Foundries.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Strong domestic demand from infrastructure projects | Driver | High | Steel Manufacturing Plants |
| Investment in automation technologies | Driver | High | Casting Machines |
| Growing need for efficient production methods | Opportunity | High | Fully Automated |
| Rising demand for sustainable steel production | Opportunity | Medium | Blast Furnace Machinery |
| Environmental regulations increasing operational costs | Restraint | High | Blast Furnace Machinery |
| Competition from lower-cost steel imports | Restraint | Medium | Rolling Equipment |
| Challenges in meeting environmental standards | Challenge | High | Finishing Equipment |
| Rising costs of raw materials impacting margins | Challenge | Medium | Smelting |
Evaluation of Drivers in China Steel Production Equipment Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased infrastructure spending | Steel Manufacturing Plants | This spending drives demand for steel, prompting higher purchases of production equipment, contributing to a significant rise in production levels. |
| Technological advancements in automation | Casting Machines | These advancements improve production efficiency, prompting manufacturers to invest in new equipment that enhances output and reduces costs. |
| Growing demand for high-quality steel | Rolling Equipment | As industries demand higher quality, manufacturers invest in advanced rolling technologies, leading to increased sales of specialized equipment. |
| Government initiatives promoting green steel production | Finishing Equipment | These initiatives encourage upgrades to equipment that meet sustainability standards, driving demand for innovative solutions in the market. |
| Expansion of the automotive sector | Blast Furnace Machinery | The automotive industry's growth increases the need for steel, driving equipment purchases and enhancing production capabilities. |
Market growth in China for Steel Production Equipment rests on increased infrastructure spending, technological advancements in automation, and the expansion of the automotive sector. In 2022, infrastructure projects contributed to the production of 1,000 million tons of steel, prompting higher demand for production equipment. The automotive sector's growth is expected to increase demand for blast furnace machinery as manufacturers seek to improve production capabilities. Additionally, advancements in automation technologies are projected to enhance efficiency, leading to increased investments in casting machines. These factors stimulate the market and encourage further investments in advanced technologies that support sustainable practices.
Evaluation of Restraints in China Steel Production Equipment Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing operational costs due to environmental regulations | Blast Furnace Machinery | Compliance with regulations raises costs for manufacturers, affecting their purchasing decisions by approximately 15%. |
| Competition from lower-cost imports | Rolling Equipment | Imported steel products at lower prices challenge local manufacturers, impacting equipment sales and reducing market share. |
| Rising raw material costs affecting profit margins | Smelting | Higher costs of raw materials reduce profitability, leading to cautious spending on new equipment by manufacturers. |
| Challenges in meeting stringent quality standards | Finishing Equipment | Manufacturers face difficulties in upgrading equipment to meet evolving quality requirements, impacting production capabilities. |
| Market saturation limiting new investments | Casting Machines | As the market matures, companies are hesitant to invest in new equipment without clear demand signals. |
China Steel Production Equipment Market Challenges
The China Steel Production Equipment Market encounters several practical issues, beginning with stringent regulations that raise compliance costs for manufacturers. The national standard GB/T 1591-2018 requires extensive quality checks, increasing operational expenses by as much as 15% for producers. Fierce competition among over 1,200 steel manufacturing plants leads to price wars, potentially reducing profit margins by around 10% for suppliers. Buyers face fluctuating steel prices, which can vary by 20% within a year, complicating budgeting for construction projects. Supply chain disruptions also delay equipment deliveries, affecting project timelines for construction firms.
Trends in the China Steel Production Equipment Market
Buyers and suppliers in the China Steel Production Equipment Market are adjusting to the following trends.
- Shift towards Fully Automated Production: In 2026, the steel industry began transitioning towards fully automated production processes. This shift is visible in the adoption of advanced technologies in Hebei province, where automation levels are increasing, resulting in a CAGR of 7.2% for fully automated equipment.
- Green Steel Initiatives Gain Traction: Since 2021, the Green Steel Initiative has gained traction, aiming for a 30% reduction in emissions by 2030. This initiative is particularly influential in regions with high steel production, prompting investments in cleaner technologies.
- Focus on Quality Control Intensifies: Beginning in 2023, the industry has prioritised quality control measures to meet international standards. The adoption of ISO 9001 certification is widespread, improving the competitiveness of domestic producers.
- Expansion of Steel Manufacturing Plants: In 2022, over 1,200 steel manufacturing plants were operational in China, reflecting the industry's growth. This expansion is driven by rising domestic demand and infrastructure projects, leading to increased equipment purchases.
Investment Opportunities in the China Steel Production Equipment Market
Some of the investment opportunities in the China Steel Production Equipment Market are mentioned below.
- Strategic Partnerships for Advanced Technology: Establishing joint ventures with local firms can facilitate entry into the market. Steel Manufacturing Plants are seeking advanced technologies, making this an opportune time for investment, especially with a projected market size of USD 1.10 billion by 2025.
- Investment in Automation Equipment: With strong demand for fully automated equipment, there is a significant opportunity for suppliers. Foundries are particularly interested in upgrading their facilities to improve production efficiency, especially as the market grows.
- Expansion in Hebei Province: Investing in production facilities in Hebei, the largest steel-producing region, is timely. The region's demand for efficient production methods presents significant opportunities for suppliers, particularly in light of recent infrastructure investments.
- Compliance with Green Initiatives: Now is the time to invest in equipment that meets green standards. The Green Steel Initiative is driving demand for sustainable production technologies among steel manufacturers, creating opportunities for innovative suppliers.
Government Initiatives in the China Steel Production Equipment Market
The 'Steel Industry Development Plan' launched in 2021 outlines strategies for modernising the steel sector and improving production efficiency. This plan mandates compliance with environmental standards and encourages investment in advanced technologies, impacting producers significantly. It aims to streamline operations and promote sustainable practices in the industry, ensuring that manufacturers adapt to evolving market demands. The plan also sets targets for emissions reductions, aligning with national sustainability goals, with an aim for a 30% reduction by 2030.
The Ministry of Industry and Information Technology oversees the implementation of the 'Green Steel Initiative', which aims for a 30% reduction in emissions by 2030. This initiative provides funding for projects that improve energy efficiency in steel production. The agency also approves technologies that meet sustainability criteria, encouraging manufacturers to invest in cleaner production methods. As of 2023, the ministry has allocated substantial funding to support these initiatives, fostering innovation in the sector.
Future Insight of the China Steel Production Equipment Market
The China Steel Production Equipment Market will undergo significant changes by 2032, driven by advancements in automation and sustainability initiatives. The 'Green Steel Initiative' targets a 30% reduction in emissions by 2030, prompting suppliers to embrace cleaner technologies. The 'Made in China 2025' plan will enhance manufacturing practices, boosting production efficiency. By 2025, the installed base of steel production equipment is projected to be valued at approximately 200 billion yuan, indicating robust demand for modern machinery.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Equipment Type – Blast Furnace Machinery Dominated, Casting Machines Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, with a 40% revenue share in 2025, Blast Furnace Machinery was the largest equipment type category. Blast furnace machinery holds the largest market share in China due to its critical role in primary steel production, particularly in the Hebei province, which is the largest steel-producing region. This equipment is essential for converting iron ore into molten iron, forming the backbone of steel manufacturing. Casting Machines are set to record the highest CAGR in this split, 6.9% over 2026–2032. Casting machines are experiencing rapid growth as they are crucial for shaping molten steel, with demand surging from sectors like automotive and construction. The ongoing infrastructure projects across China significantly fuel the expansion of this segment, ensuring its continued prominence. Suppliers should enhance their offerings in casting machines to capitalise on the growing demand in the market.
By Process Stage – Smelting Dominated, Casting Expected to Grow Fastest
The largest process stage category in 2025 was Smelting, with a 47% share of total revenue. Smelting leads the process stage segment in the China steel production equipment market, being integral to the steelmaking process and ensuring the transformation of raw materials into molten steel. This stage is vital for meeting the high production levels required by the industry, especially with China's output reaching 1,000 million tons in 2022. The quickest growth will come from Casting, forecast to expand at a CAGR of 7.4% between 2026 and 2032. Casting is the fastest-growing process stage, driven by its essential role in producing steel components for diverse applications, including construction and automotive. The increasing number of steel manufacturing plants operating in China supports this segment's rapid growth trajectory. Buyers should prioritise investments in casting technologies to maintain competitiveness in the market.
By Automation Level – Semi-Automated Dominated, Fully Automated Expected to Grow Fastest
In 2025, Semi-Automated led the automation level split with a 41% share. Semi-automated systems dominate the market as they are commonly used in less critical applications, offering a balance between cost and efficiency for many steel producers. This level of automation is particularly prevalent in smaller manufacturing plants that require operational flexibility to adapt to varying production demands. Over 2026–2032, Fully Automated is expected to post the fastest growth, at a CAGR of 7.2%. Fully automated systems are rapidly gaining traction due to their ability to significantly increase efficiency and precision in steel production processes. The push towards advanced manufacturing, as highlighted in the 'Made in China 2025' plan, is propelling this segment's growth forward. Suppliers must adapt to the rising demand for fully automated solutions to stay relevant in the market.
By End User – Steel Manufacturing Plants Dominated, Foundries Expected to Grow Fastest
Steel Manufacturing Plants held a 35% share of the China Steel Production Equipment Market by end user in 2025. Steel manufacturing plants represent the largest market share as they are the primary users of steel production equipment, essential for fulfilling the vast domestic demand driven by infrastructure and industrial growth. With over 1,200 plants operating in China, their need for efficient equipment is critical to support ongoing production requirements. Foundries are projected to grow fastest, at a CAGR of 7.6% during 2026–2032. Foundries are the fastest-growing end user segment, playing a key role in casting processes necessary for various industries. The increasing demand for custom steel components, driven by diverse applications, further accelerates this growth and highlights the importance of innovation in this sector. Buyers in the foundry sector should seek advanced equipment solutions to improve their production capabilities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Steel Production Equipment Market Outlook
- Market Size of China Steel Production Equipment Market, 2025
- Forecast of China Steel Production Equipment Market, 2032
- Historical Data and Forecast of China Steel Production Equipment Revenues & Volume for the Period 2022 - 2032F
- China Steel Production Equipment Market Trend Evolution
- China Steel Production Equipment Market Drivers and Challenges
- China Steel Production Equipment Price Trends
- China Steel Production Equipment Porter's Five Forces
- China Steel Production Equipment Industry Life Cycle
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Equipment Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Blast Furnace Machinery for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Casting Machines for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Rolling Equipment for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Finishing Equipment for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Process Stage for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Smelting for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Casting for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Forming for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Surface Treatment for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Automation Level for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Semi-Automated for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Fully Automated for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Manual for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Computer Controlled for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Steel Manufacturing Plants for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Foundries for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Heavy Industry Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Steel Production Equipment Market Revenues & Volume By Metal Fabrication Plants for the Period 2022 - 2032F
- China Steel Production Equipment Import Export Trade Statistics
- Market Opportunity Assessment By Equipment Type
- Market Opportunity Assessment By Process Stage
- Market Opportunity Assessment By Automation Level
- Market Opportunity Assessment By End User
- China Steel Production Equipment Top Companies Market Share
- China Steel Production Equipment Competitive Benchmarking By Technical and Operational Parameters
- China Steel Production Equipment Company Profiles
- China Steel Production Equipment Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Equipment Type
- Blast Furnace Machinery
- Casting Machines
- Rolling Equipment
- Finishing Equipment
By Process Stage
- Smelting
- Casting
- Forming
- Surface Treatment
By Automation Level
- Semi-Automated
- Fully Automated
- Manual
- Computer Controlled
By End User
- Steel Manufacturing Plants
- Foundries
- Heavy Industry Units
- Metal Fabrication Plants































