China Structural Casting Market Size & Growth Rate
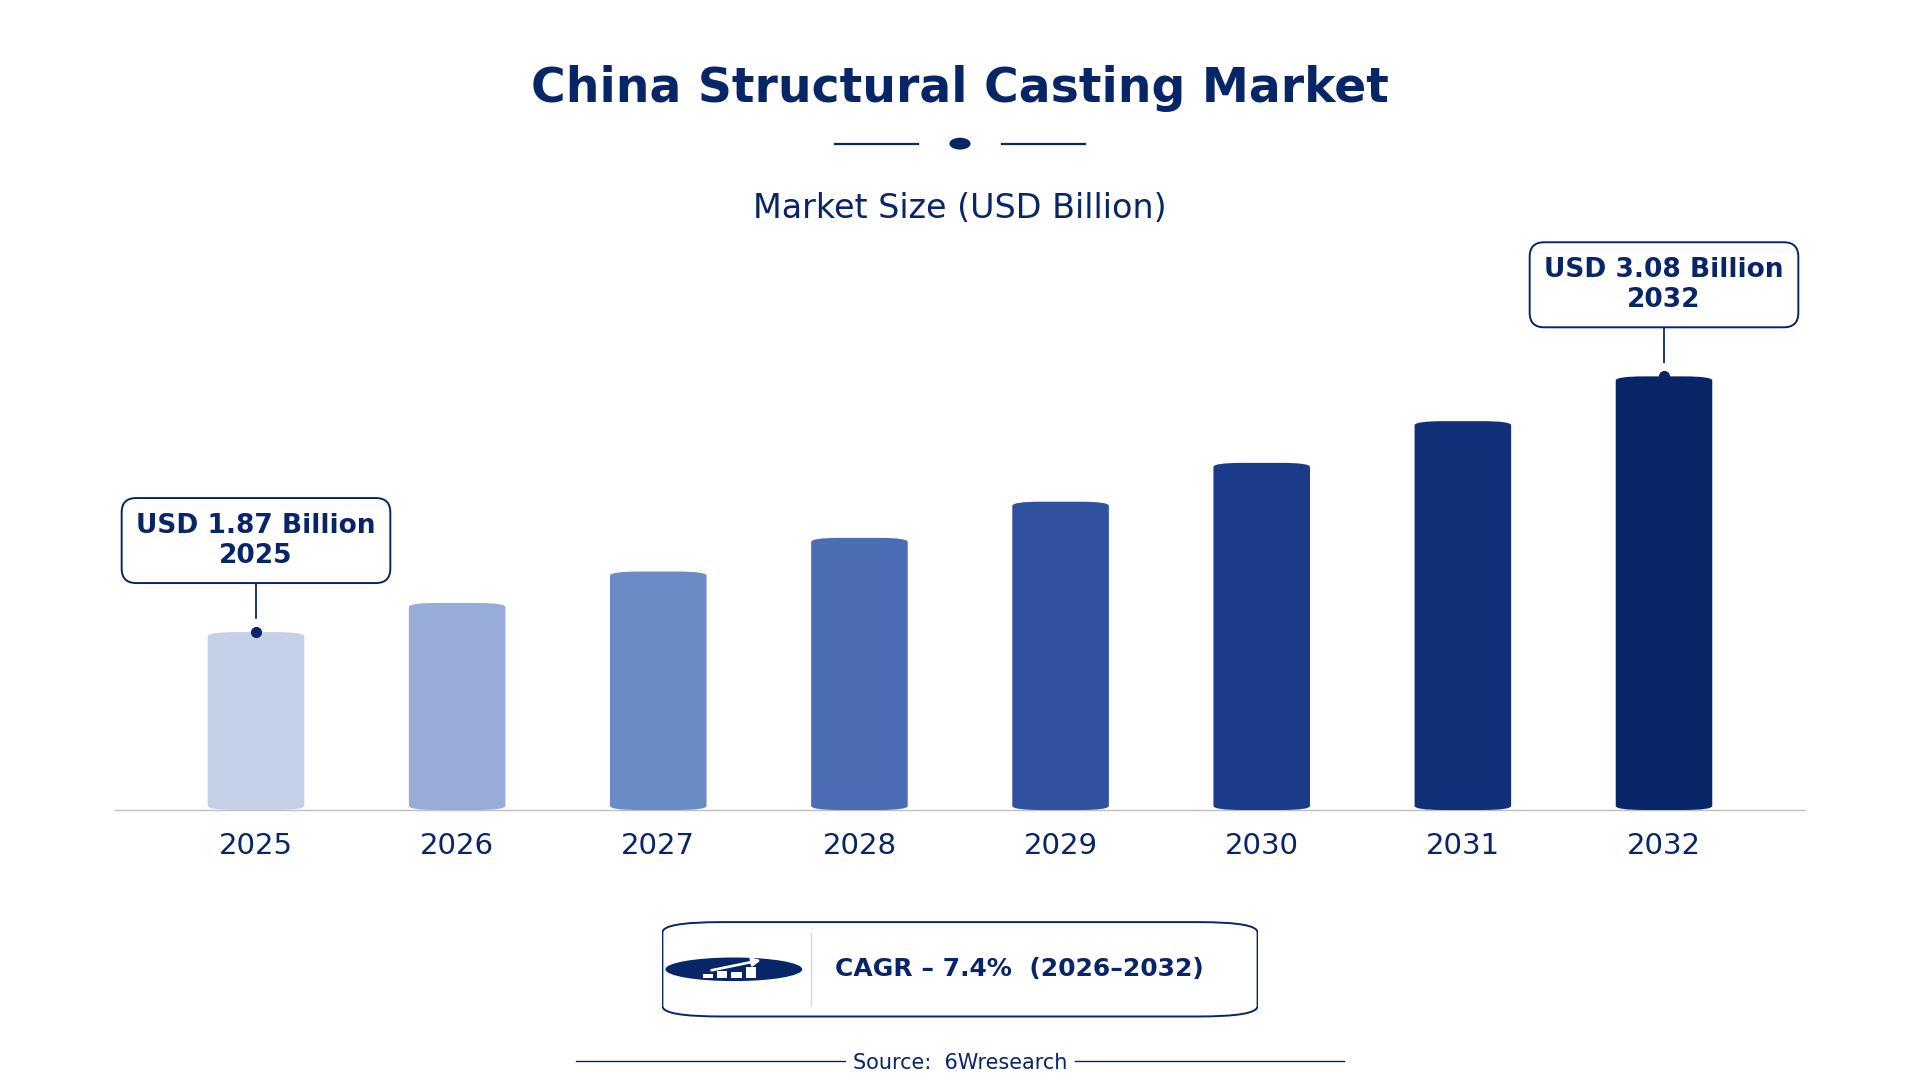
According to 6Wresearch internal database and industry insights, the China Structural Casting Market was valued at USD 1.87 billion in 2025 and is projected to reach USD 3.08 billion by 2032, growing at a CAGR of approximately 7.4% during 2026–2032.
China Structural Casting Market Highlights
| Report Metric | Details |
| Report Name | China Structural Casting Market |
| Market Size 2025 | USD 1.87 billion |
| Market Size 2032 | USD 3.08 billion |
| Absolute Growth 2025–2032 | USD 1.21 billion |
| CAGR 2026–2032 | 7.4% |
| Peak Annual Growth | 9.9% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Casting Type, 2025 | Sand Castings (40% share) |
| Leading Material Type, 2025 | Steel (49% share) |
| Leading Molding Method, 2025 | Green Sand Molding (53% share) |
| Leading End User, 2025 | Automotive Industry (40% share) |
| Fastest-Growing Casting Type | Investment Castings (10.1% CAGR) |
| Fastest-Growing Material Type | Aluminum (9.5% CAGR) |
| Fastest-Growing Molding Method | High-Pressure Die Casting (9.1% CAGR) |
| Fastest-Growing End User | Aerospace Suppliers (9.0% CAGR) |
| Growing Sector | Aerospace |
| Key End Users | Automotive Industry, Construction Equipment OEMs, Aerospace Suppliers, Shipbuilding Companies |
China Structural Casting Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
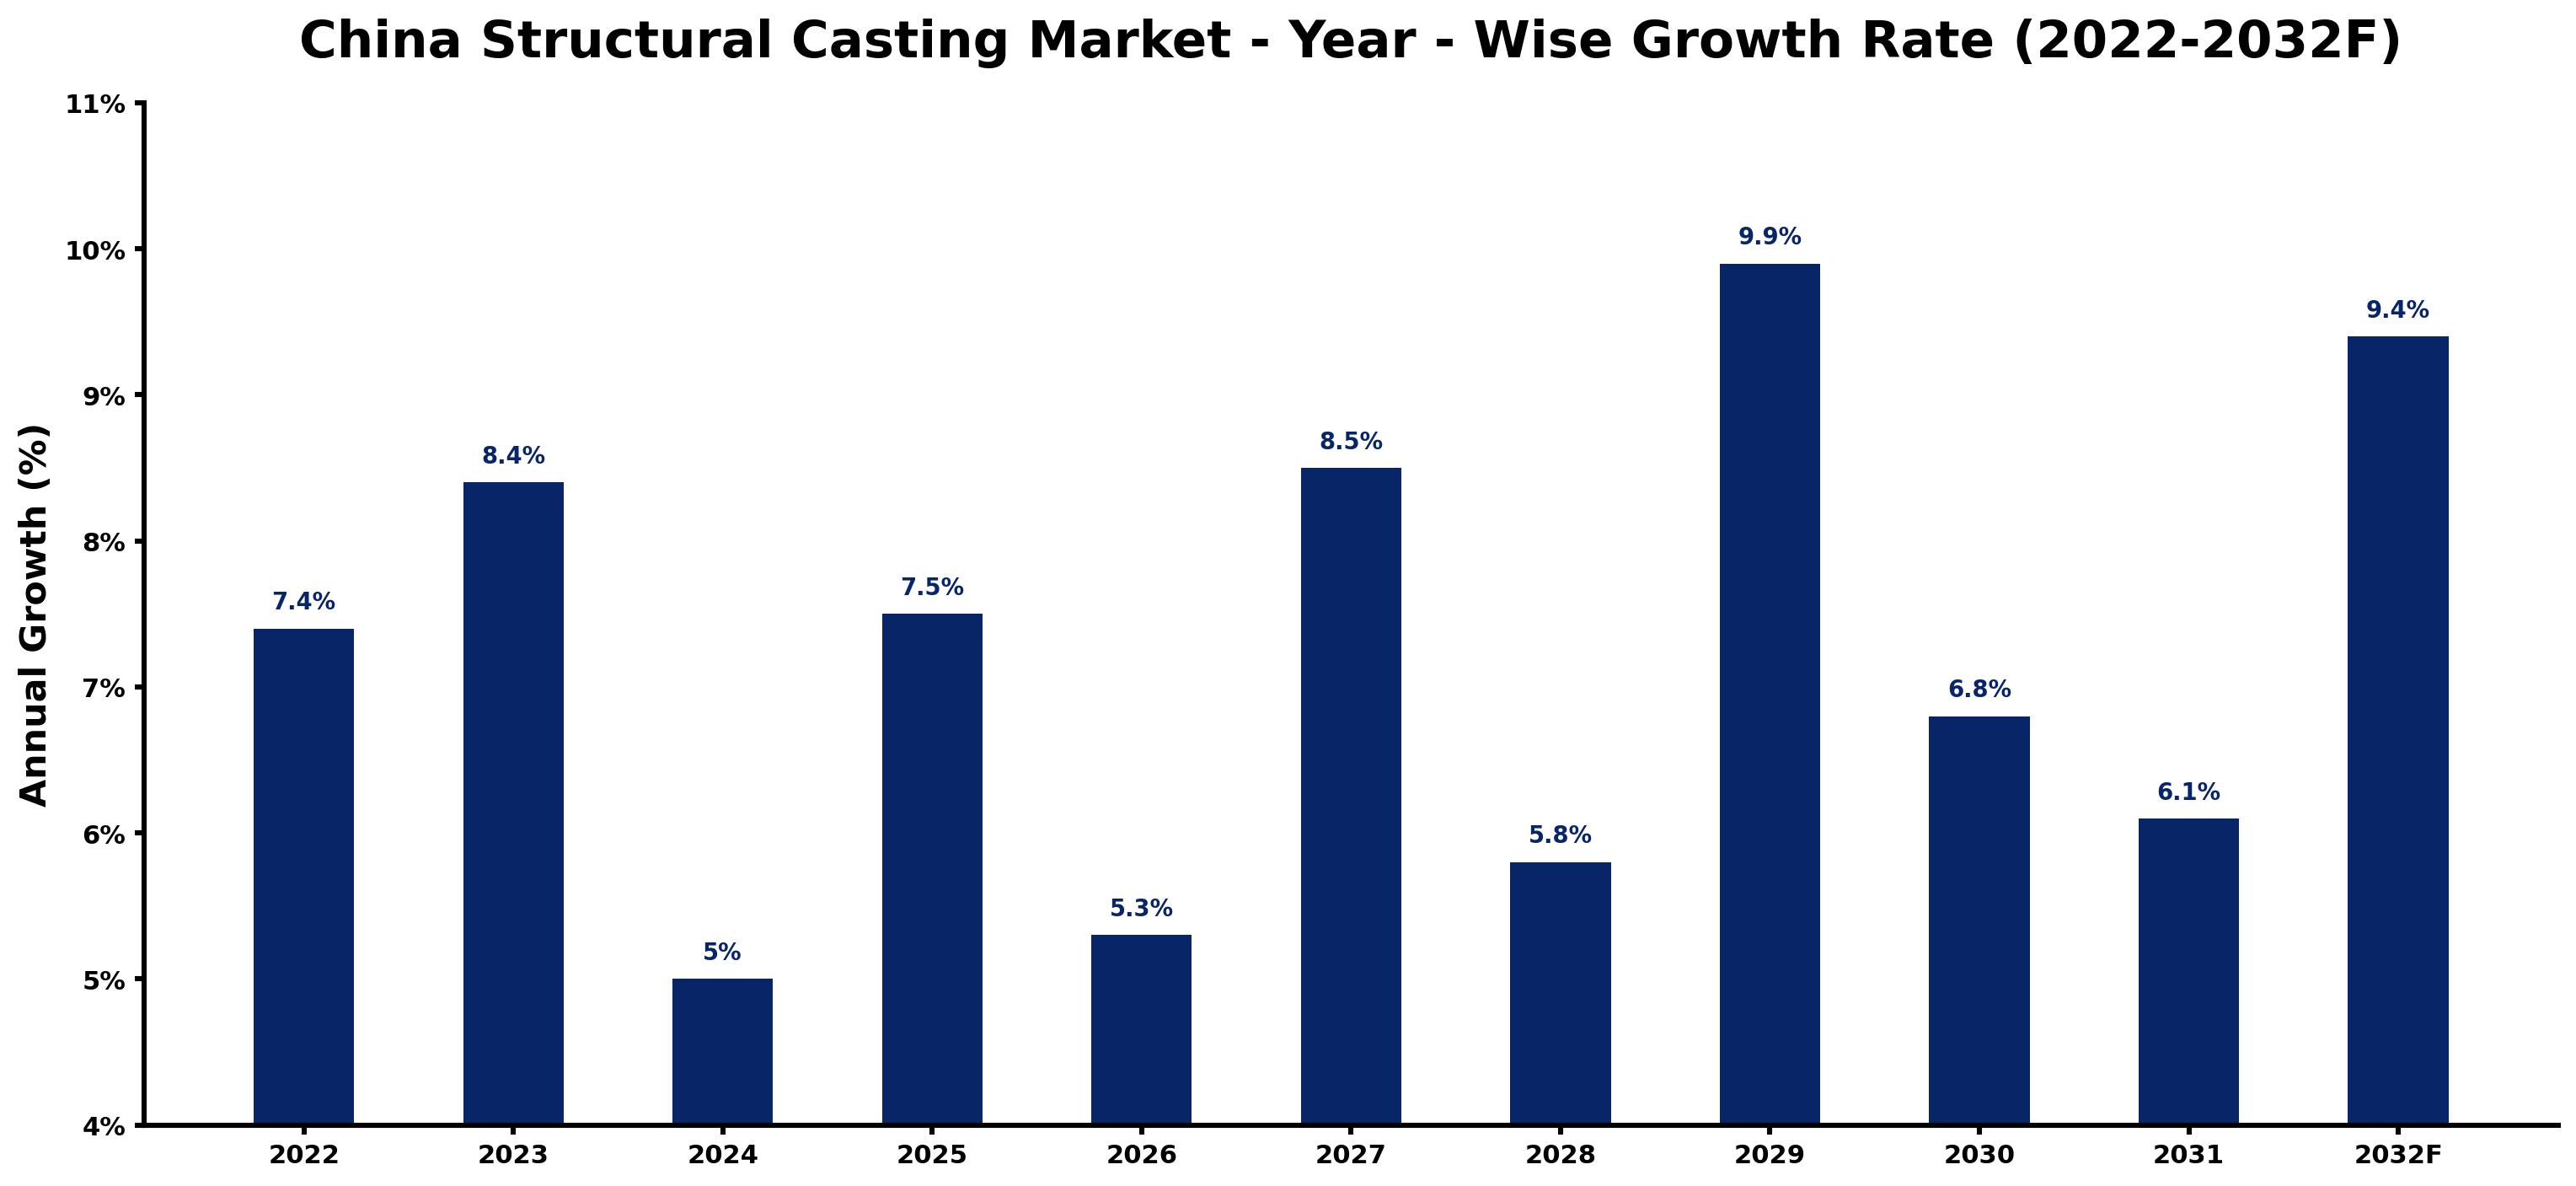
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.4 | The automotive industry produced over 25 million vehicles, driving demand for structural castings. |
| 2023 | 8.4 | Growth accelerated due to increased production in the construction sector, particularly in urban areas. |
| 2024 | 5.0 | Demand growth slowed as the market adjusted after rapid expansion in previous years. |
| 2025 | 7.5 | Investment in foundry modernization led to faster growth, particularly in the automotive segment. |
| 2026 | 5.3 | Demand growth is expected to slow as the market adapts to increased production capacities. |
| 2027 | 8.5 | A surge in aerospace demand is projected to boost growth, particularly for high-precision castings. |
| 2028 | 5.8 | Growth is anticipated to decelerate as the market faces temporary production challenges in Jiangsu. |
| 2029 | 9.9 | Demand is expected to peak due to substantial orders from the automotive sector, driving rapid expansion. |
| 2030 | 6.8 | A slowdown is projected as the market begins to stabilise after peak demand. |
| 2031 | 6.1 | Continued growth is expected to be supported by ongoing investments in construction and automotive sectors. |
| 2032 | 9.4 | A resurgence in demand is projected as infrastructure projects ramp up across the country. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Structural Casting Market Synopsis
The China Structural Casting Market involves the production of structural components through molten metal casting. This industry plays a crucial role in supplying components for construction, automotive, aerospace, and shipbuilding. As domestic demand rises, particularly from the automotive sector, which saw over 25 million vehicles produced in 2022, the market is experiencing growth. Investments in foundry modernization and advanced manufacturing technologies are further propelling this expansion, highlighting a robust demand environment. By 2025, the aerospace sector is expected to require 50,000 tons of castings annually, creating additional market opportunities.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing automotive production necessitates high-quality castings for engine and body parts. | Driver | High | Automotive Industry |
| Increasing infrastructure projects require durable structural components, boosting demand for castings. | Driver | High | Construction Equipment OEMs |
| The aerospace sector's projected need for 50,000 tons of castings annually by 2025 creates significant opportunities. | Opportunity | High | Aerospace Suppliers |
| Investment in sustainable casting practices aligns with government initiatives, creating new market avenues. | Opportunity | High | Sand Castings |
| High energy costs impact production efficiency, posing challenges for manufacturers. | Restraint | High | Sand Castings |
| Regulatory compliance with national standards can increase operational costs for producers. | Restraint | High | Ductile Iron |
| The Structural Casting Market in China faces challenges related to skilled labour shortages in foundries. | Challenge | Medium | Sand Castings |
| Technological advancements in casting processes require continuous investment, straining smaller manufacturers. | Challenge | Medium | Investment Castings |
Evaluation of Drivers in China Structural Casting Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased automotive production drives demand for structural castings, with over 25 million vehicles produced in 2022. | Automotive Industry | This surge in production requires high-quality castings for engine and body parts. |
| Rising infrastructure projects necessitate durable castings, with investments in urban development exceeding 500 billion yuan in 2022. | Construction Equipment OEMs | These projects create a steady demand for structural components. |
| The aerospace sector's anticipated need for 50,000 tons of castings annually by 2025 stimulates market growth. | Aerospace Suppliers | This demand encourages manufacturers to increase production capacities. |
| Investment in foundry modernization reached 10 billion yuan in 2021, improving production capabilities. | Sand Castings | Modernized facilities enhance efficiency and product quality. |
| The adoption of high-pressure die casting technology is growing, particularly in automotive applications, with a projected CAGR of 9.1%. | High-Pressure Die Casting | This technology allows for efficient mass production of complex shapes. |
The Structural Casting market in China is expanding as end-use demand rises from the automotive and construction sectors. In 2022, over 25 million vehicles were produced, increasing the need for high-quality castings. Investments in foundry modernization, reaching 10 billion yuan in 2021, improve production capabilities. The aerospace sector is projected to require 50,000 tons of castings annually by 2025, further stimulating demand. The growing adoption of high-pressure die casting technology in automotive applications allows for efficient mass production of complex shapes, responding to rising market needs.
Evaluation of Restraints in China Structural Casting Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High energy costs impact production efficiency, with energy expenses rising in recent years. | Sand Castings | These costs strain profit margins for manufacturers, affecting pricing strategies. |
| Regulatory compliance with national standards can increase operational costs for producers, particularly for ductile iron. | Ductile Iron | Meeting these standards requires investments in quality control and testing, raising production costs by 15%. |
| Skilled labour shortages in foundries hinder production capabilities, affecting overall output. | Sand Castings | This shortage leads to delays in production schedules and increased training costs. |
| Technological advancements require continuous investment, which can strain smaller manufacturers financially. | Investment Castings | Smaller firms may struggle to keep up with the pace of innovation, limiting their competitiveness. |
| Market fluctuations in raw material prices create uncertainty for producers, impacting profitability. | Steel | Volatility in material costs complicates budgeting and financial planning. |
China Structural Casting Market Challenges
The China Structural Casting Market encounters several practical issues, starting with outdated technology. Many producers continue to rely on traditional casting methods, which limits efficiency and can increase production costs by up to 15%. Regulatory challenges arise from the national standard GB/T 1348, imposing strict requirements that may delay production timelines by several weeks for suppliers. Intense competition from international markets pressures local producers to lower prices, affecting profit margins and leading some to operate at a loss. A shortage of skilled workers in advanced casting techniques restricts manufacturers' ability to innovate, resulting in a talent gap that can reduce production rates by up to 20%.
Trends in the China Structural Casting Market
Several trends are reshaping the China Structural Casting Market; the most important are set out below.
- Green Manufacturing System Initiative Promotes Eco-Friendly Practices: The 'Green Manufacturing System' initiative, introduced in 2023, encourages eco-friendly practices in the casting sector. This shift aims to reduce energy consumption by 20% by 2025, benefiting manufacturers pursuing sustainability.
- Aerospace Sector Demand for High-Precision Castings: Aerospace suppliers increasingly seek high-precision castings, with a projected requirement of 50,000 tons annually by 2025. This trend is reshaping production strategies across the industry, driving innovation.
- Shift Towards High-Pressure Die Casting Technology: The adoption of high-pressure die casting technology is gaining momentum, particularly in the automotive sector. This method is expected to grow at a CAGR of 9.1% from 2026 to 2032, improving production efficiency.
- Investment in Foundry Modernization: Investment in foundry modernization reached 10 billion yuan in 2021, focusing on technological advancements. This trend is vital for manufacturers aiming to improve product quality and operational efficiency.
Investment Opportunities in the China Structural Casting Market
Some of the investment opportunities in the China Structural Casting Market are mentioned below.
- Growing Demand from the Aerospace Sector: With the aerospace sector projected to require 50,000 tons of castings annually by 2025, there is a strong opportunity for suppliers to meet this demand through partnerships with aerospace manufacturers.
- Investment in Sustainable Practices: The push for sustainable casting practices aligns with government initiatives, creating opportunities for suppliers to invest in eco-friendly technologies and processes, particularly in urban areas.
- Emerging Markets in Construction: The ongoing urbanization in China, with a population exceeding 1.4 billion, creates a substantial opportunity for suppliers of structural castings to cater to the growing construction sector.
- High-Pressure Die Casting Growth: The increasing adoption of high-pressure die casting technology presents an opportunity for manufacturers to expand their product offerings.
Government Initiatives in the China Structural Casting Market
The '14th Five-Year Plan for the Foundry Industry', launched in 2021, focuses on technological innovation and sustainability. This plan aims to improve production efficiency and product quality in the structural casting sector. The 'National Standard for Foundry Industry Development', issued in 2022, establishes quality benchmarks for manufacturers. Compliance with these standards is essential for producers to remain competitive in the market. The 'Green Manufacturing System' initiative introduced in 2023 promotes eco-friendly practices, aiming to reduce energy consumption by 20% by 2025, benefiting manufacturers pursuing sustainability.
The Ministry of Industry and Information Technology oversees the implementation of various initiatives, including the 'Green Manufacturing System' introduced in 2023. This initiative promotes eco-friendly practices in the casting sector, aiming to reduce energy consumption significantly. Additionally, the National Development and Reform Commission funds projects that target energy efficiency improvements, with a goal of reducing energy use in foundries by 20% by 2025. These measures collectively enhance the operational capabilities of casting manufacturers.
Future Insight of the China Structural Casting Market
The China Structural Casting Market will undergo significant changes by 2032, primarily driven by advancements in technology and government initiatives. The aerospace sector is projected to require 50,000 tons of castings annually, prompting increased investments in modernisation and efficiency improvements. The Ministry of Industry and Information Technology will promote advanced manufacturing technologies, boosting production capabilities for suppliers. The government's commitment to reducing energy consumption in casting processes will compel buyers to adopt more sustainable sourcing practices, reshaping the market.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Casting Type – Sand Castings Dominated, Investment Castings Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, Sand Castings accounted for a 40% market share by casting type in 2025. Sand castings dominate the market share because they are cost-effective and suitable for producing large components. Their widespread use in construction equipment, especially in Jiangsu province, highlights the strong demand driving this segment. Investment Castings are set to record the highest CAGR in this split, 10.1% over 2026–2032. Investment castings are experiencing rapid growth due to their ability to create high-precision and complex shapes. The aerospace sector's projected need for 50,000 tons of castings annually by 2025 significantly fuels this expansion. Suppliers should focus on enhancing their investment casting capabilities to meet the rising demand for precision components across various industries.
By Material Type – Steel Dominated, Aluminum Expected to Grow Fastest
In 2025, Steel led the material type split with a 49% share. Steel holds the largest market share as it is fundamental for ensuring structural integrity across various industries. Its widespread use in infrastructure projects, particularly in urban areas, underlines its importance. Aluminum is projected to grow fastest, at a CAGR of 9.5% during 2026–2032. Aluminum is the fastest-growing material type due to its lightweight and corrosion-resistant properties, making it essential for automotive components. The automotive industry in China, which produced over 25 million vehicles in 2022, is a key driver of this growth. Suppliers should consider expanding their aluminum offerings to capitalise on the increasing demand from the automotive sector.
By Molding Method – Green Sand Molding Dominated, High-Pressure Die Casting Expected to Grow Fastest
With a 53% revenue share in 2025, Green Sand Molding was the largest molding method category. Green sand molding holds the largest market share as it is a traditional and effective method for producing large castings. This technique plays a vital role in heavy machinery production, accounting for a significant portion of overall casting output. The quickest growth will come from High-Pressure Die Casting, forecast to expand at a CAGR of 9.1% between 2026 and 2032. High-pressure die casting is growing quickly due to its efficiency in mass-producing complex shapes. Its essential role in the automotive supply chain, which is seeing increased production demands, drives this growth. Investing in high-pressure die casting technologies will be crucial for suppliers to remain competitive in the automotive sector.
By End User – Automotive Industry Dominated, Aerospace Suppliers Expected to Grow Fastest
Automotive Industry took a 40% share of end user in 2025, more than any other category. The automotive industry holds the largest market share as it is a major consumer of castings for engine and body components. The production of over 25 million vehicles in 2022 illustrates the substantial demand for structural castings in this sector. Over 2026–2032, Aerospace Suppliers are expected to post the fastest growth, at a CAGR of 9.0%. Aerospace suppliers represent the fastest-growing end user segment, driven by the rising need for high-precision castings in aircraft manufacturing. The expected increase in aerospace casting requirements indicates a strong growth trajectory in this area. Building partnerships with aerospace suppliers will be essential for suppliers looking to capitalise on this rapidly expanding market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Structural Casting Market Outlook
- Market Size of China Structural Casting Market, 2025
- Forecast of China Structural Casting Market, 2032
- Historical Data and Forecast of China Structural Casting Revenues & Volume for the Period 2022 - 2032F
- China Structural Casting Market Trend Evolution
- China Structural Casting Market Drivers and Challenges
- China Structural Casting Price Trends
- China Structural Casting Porter's Five Forces
- China Structural Casting Industry Life Cycle
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Casting Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Sand Castings for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Investment Castings for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Die Castings for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Permanent Mold Casting for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Ductile Iron for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Aluminum for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Magnesium for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Molding Method for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Green Sand Molding for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Lost Wax Process for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By High-Pressure Die Casting for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Gravity Molding for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Construction Equipment OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Aerospace Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Automotive Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Casting Market Revenues & Volume By Shipbuilding Companies for the Period 2022 - 2032F
- China Structural Casting Import Export Trade Statistics
- Market Opportunity Assessment By Casting Type
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Molding Method
- Market Opportunity Assessment By End User
- China Structural Casting Top Companies Market Share
- China Structural Casting Competitive Benchmarking By Technical and Operational Parameters
- China Structural Casting Company Profiles
- China Structural Casting Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Casting Type
- Sand Castings
- Investment Castings
- Die Castings
- Permanent Mold Casting
By Material Type
- Ductile Iron
- Aluminum
- Magnesium
- Steel
By Molding Method
- Green Sand Molding
- Lost Wax Process
- High-Pressure Die Casting
- Gravity Molding
By End User
- Construction Equipment OEMs
- Aerospace Suppliers
- Automotive Industry
- Shipbuilding Companies































