China Structural Component Overhaul Market Size & Growth Rate
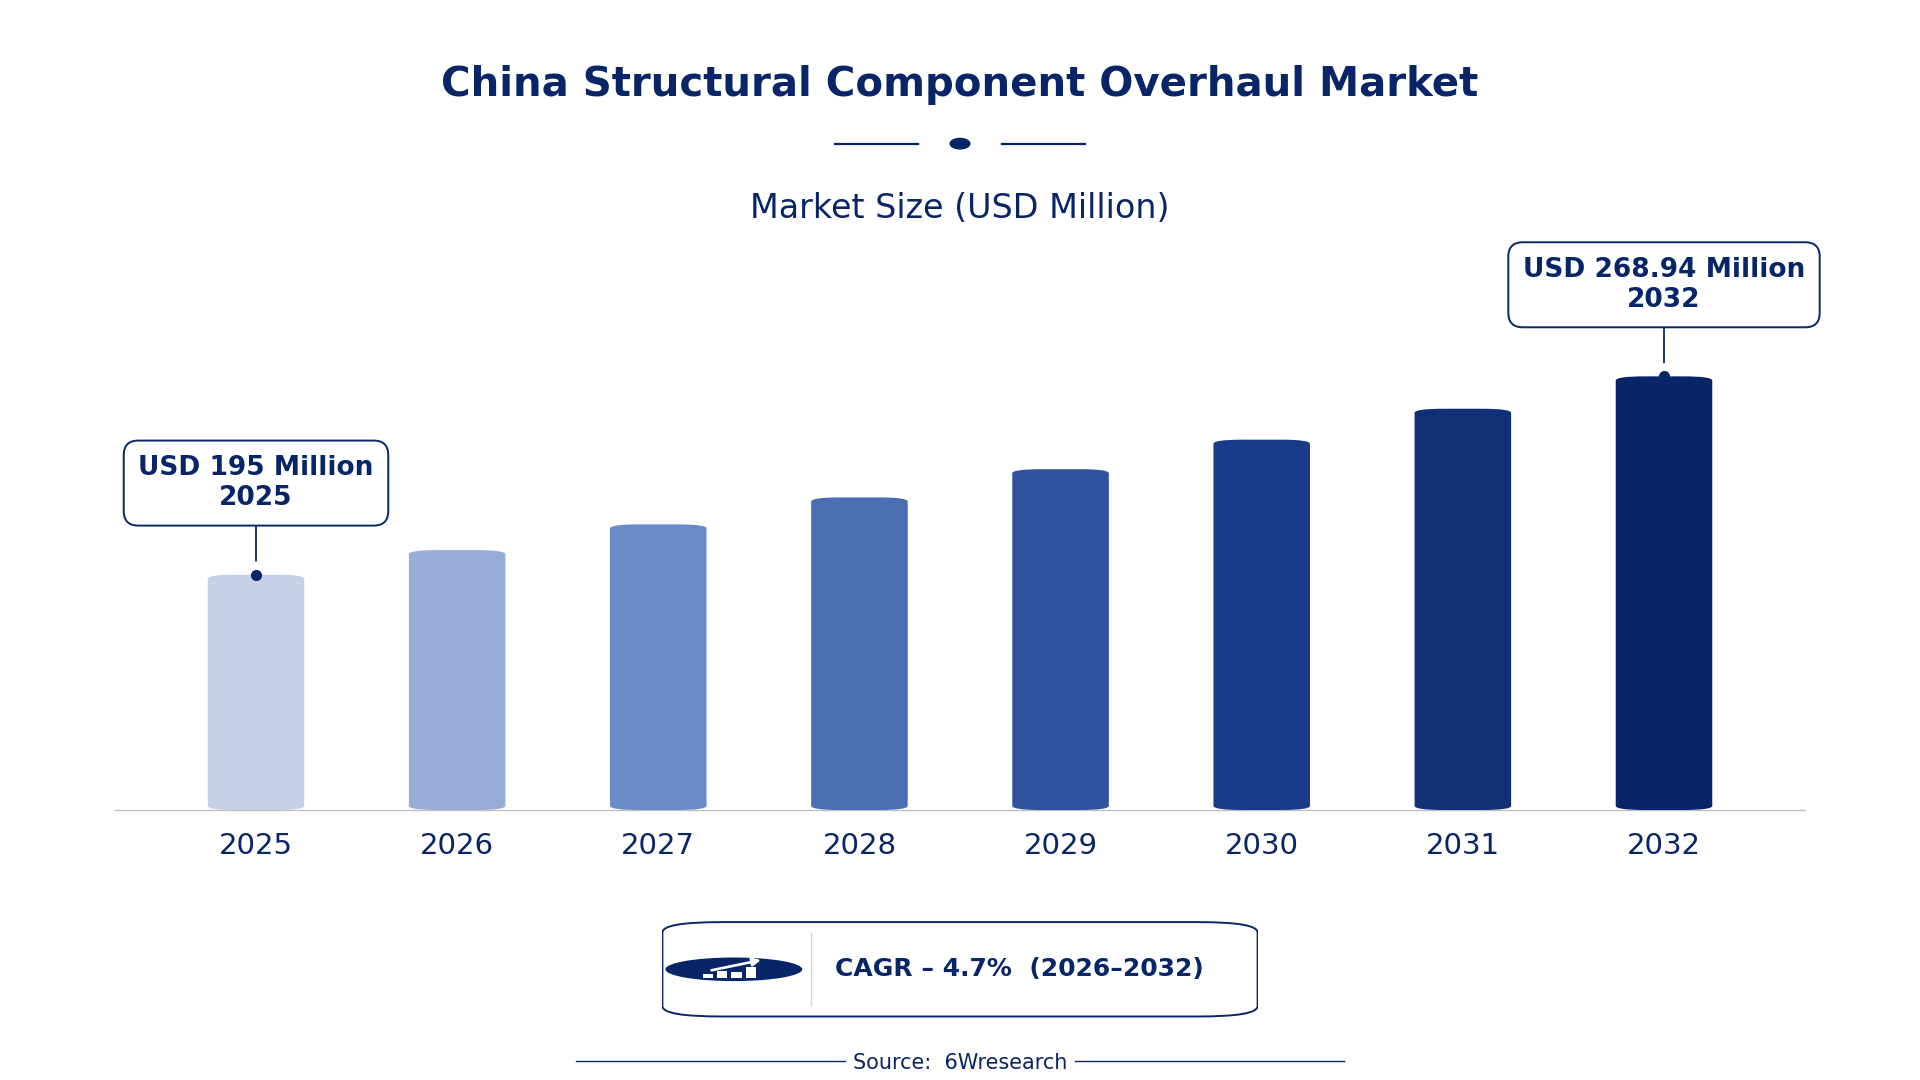
According to 6Wresearch internal database and industry insights, the China Structural Component Overhaul Market was valued at USD 195.0 million in 2025 and is projected to reach USD 268.94 million by 2032, growing at a CAGR of approximately 4.7% during 2026–2032.
China Structural Component Overhaul Market Highlights
| Report Metric | Details |
| Report Name | China Structural Component Overhaul Market |
| Market Size 2025 | USD 195.0 million |
| Market Size 2032 | USD 268.94 million |
| Absolute Growth 2025–2032 | USD 73.94 million |
| CAGR 2026–2032 | 4.7% |
| Peak Annual Growth | 7.2% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Wing Spars (43% share) |
| Leading Overhaul Level, 2025 | Full Rebuild (52% share) |
| Leading Platform Type, 2025 | Fixed-Wing Aircraft (45% share) |
| Leading End User, 2025 | MRO Providers (39% share) |
| Fastest-Growing Component Type | Landing Gear (6.6% CAGR) |
| Fastest-Growing Overhaul Level | Partial Refurbishment (6.2% CAGR) |
| Fastest-Growing Platform Type | Helicopters (7.0% CAGR) |
| Fastest-Growing End User | Defense Maintenance Units (7.4% CAGR) |
| Growing Sector | Aerospace and Defence |
| Key End Users | MRO Providers, Military Maintenance Units, Private Jet Operators, Air Force Bases |
China Structural Component Overhaul Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
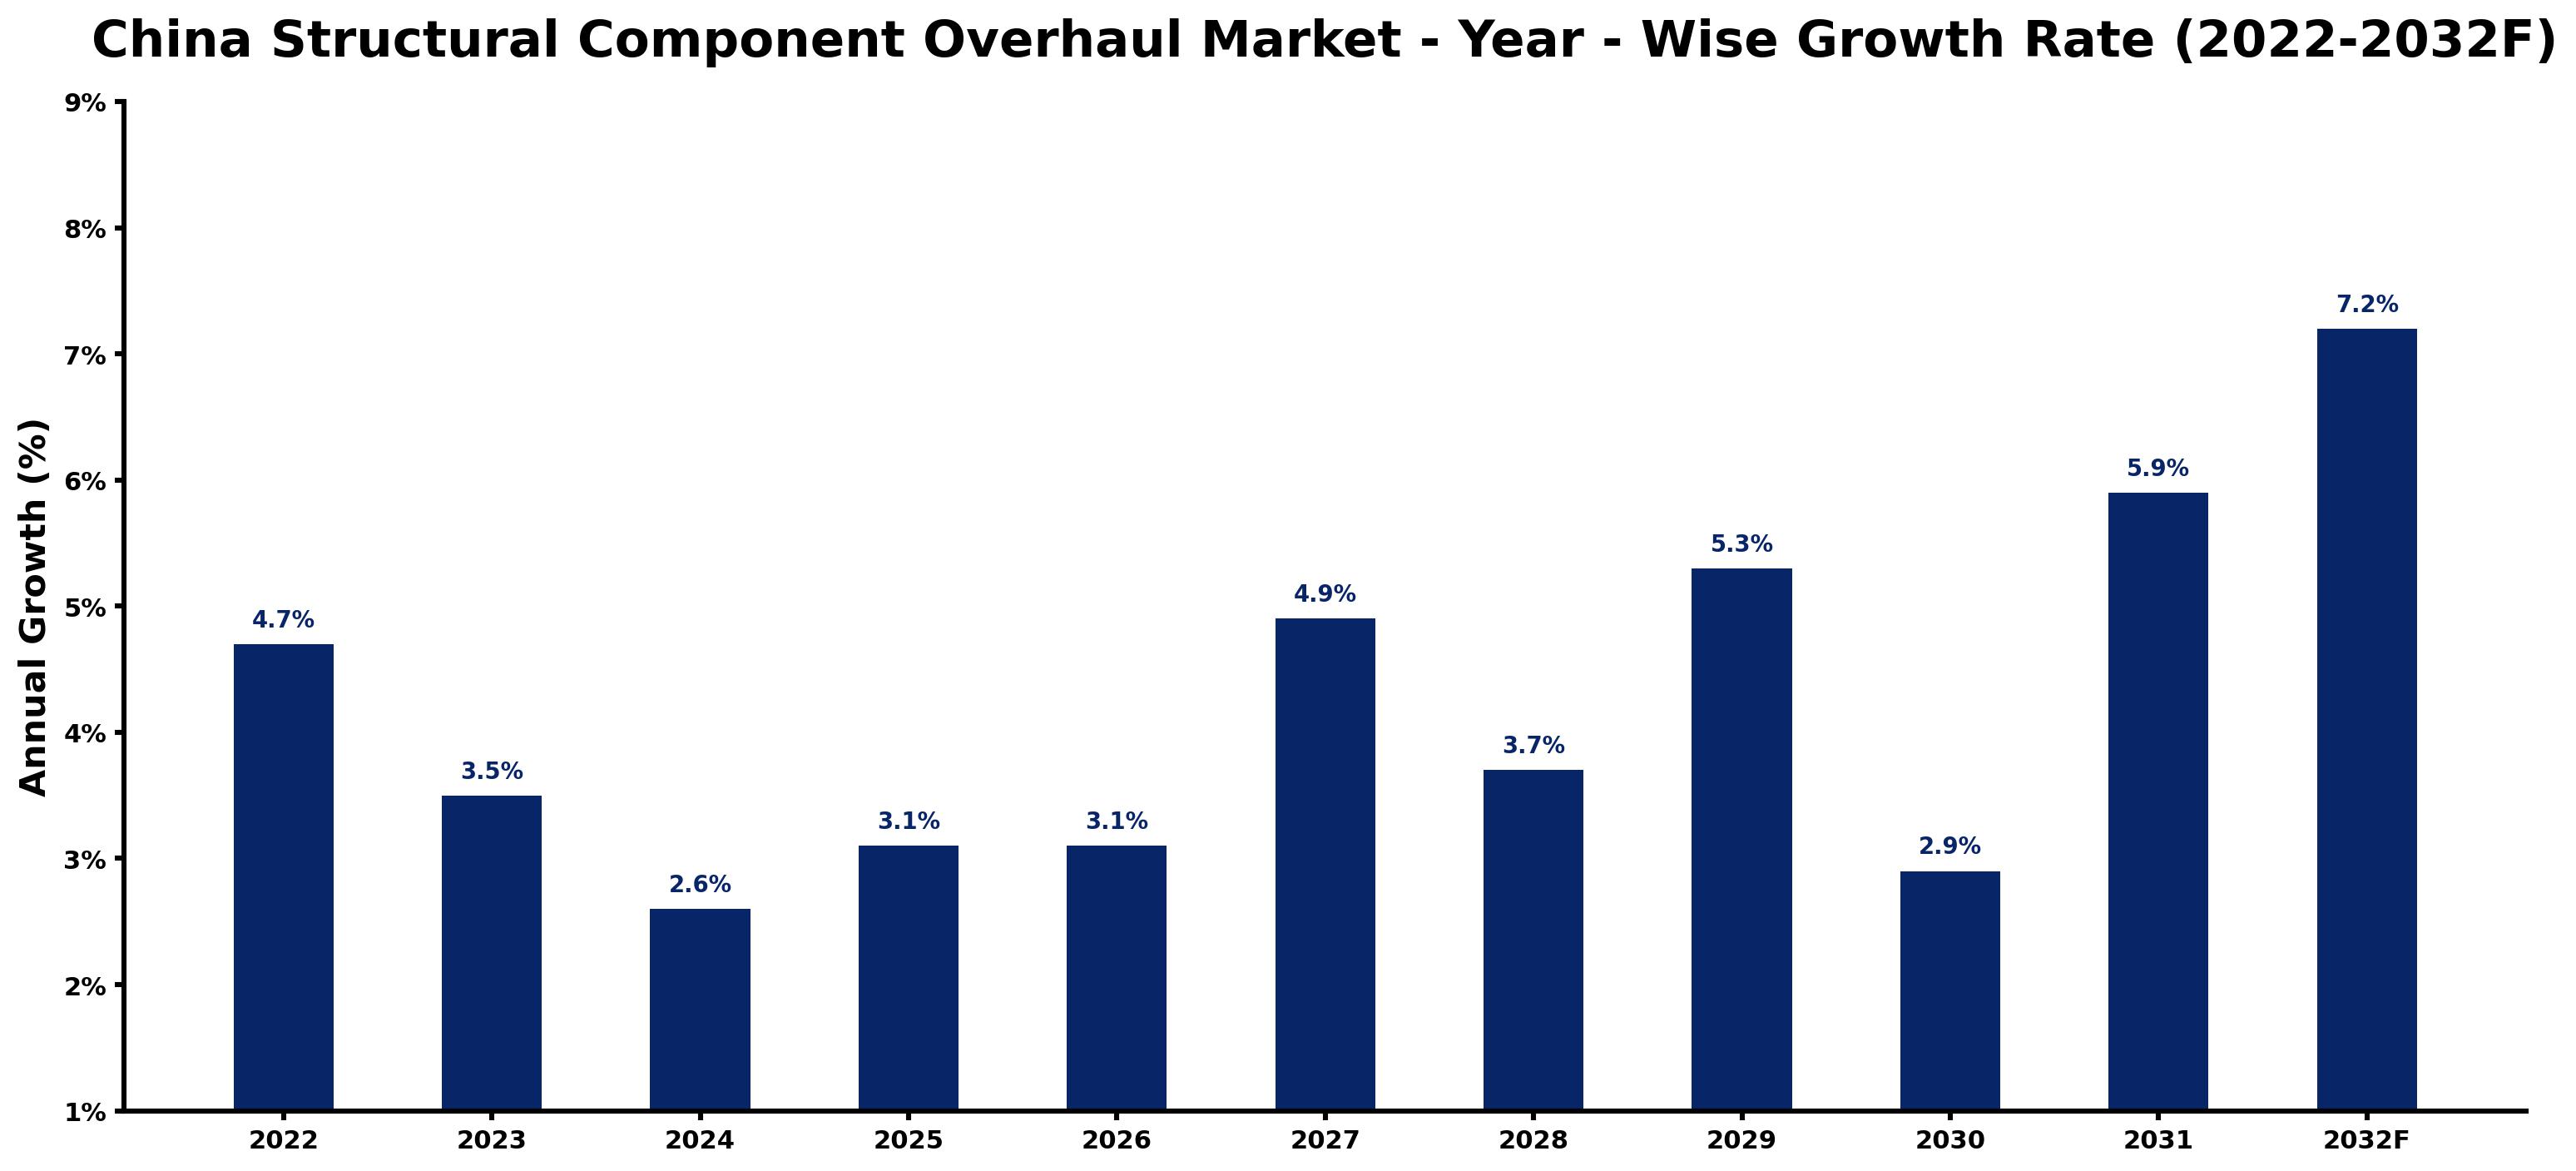
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.7 | The market experienced solid growth due to increased demand from MRO providers and military sectors. |
| 2023 | 3.5 | Growth slowed as the market adjusted to regulatory changes in aircraft maintenance standards. |
| 2024 | 2.6 | A further slowdown occurred as MRO providers faced challenges in meeting rising safety compliance demands. |
| 2025 | 3.1 | Growth picked up again as investments in aviation infrastructure began to yield results for MRO services. |
| 2026 | 3.1 | The market's growth rate slowed as competition intensified among MRO providers in key regions. |
| 2027 | 4.9 | Demand surged as military aircraft maintenance strategies were implemented, boosting service contracts. |
| 2028 | 3.7 | Growth decelerated as MRO providers faced resource allocation issues amid rising operational costs. |
| 2029 | 5.3 | An increase in air traffic led to heightened demand for overhaul services, particularly in commercial aviation. |
| 2030 | 2.9 | The market's growth rate slowed due to challenges in sourcing quality components for repairs. |
| 2031 | 5.9 | A rebound in growth occurred as the military budget for aviation maintenance was increased. |
| 2032 | 7.2 | The market is projected to peak as infrastructure investments and MRO capabilities expand. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Structural Component Overhaul Market Synopsis
Structural Component Overhaul in China focuses on the maintenance and repair of essential aircraft parts, ensuring safety and compliance with aviation regulations. This process encompasses full rebuilds, refurbishments, and non-destructive testing, which are crucial for extending aircraft lifespan. The China Structural Component Overhaul Market is expanding, driven by increasing demand from MRO providers and military sectors, backed by substantial investments in aviation infrastructure. In 2023, the government introduced the 'Aviation Industry Development Plan' to strengthen MRO capabilities, further propelling market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased military spending on aviation maintenance | Driver | High | Military Jets |
| Rising air traffic leading to higher demand for MRO services | Driver | High | Fixed-Wing Aircraft |
| Expansion of MRO facilities in key regions | Opportunity | Medium | MRO Providers |
| Growth in the private jet market requiring more maintenance services | Opportunity | Medium | Private Jet Operators |
| Challenges in sourcing quality components for repairs | Restraint | High | Landing Gear |
| Regulatory compliance costs impacting MRO providers | Restraint | High | Full Rebuild |
| Shortage of skilled technicians affecting service delivery | Challenge | High | MRO Providers |
| Increased competition among MRO providers leading to price pressures | Challenge | Medium | Defense Maintenance Units |
Evaluation of Drivers in China Structural Component Overhaul Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased military budget for aviation maintenance | Military Jets | China's military budget for aviation maintenance is projected at $10 billion in 2023, leading to more overhaul contracts. |
| Growing air traffic necessitating more MRO services | Fixed-Wing Aircraft | With air traffic expected to reach 1 billion passengers by 2035, MRO services are in higher demand. |
| Investment in aviation infrastructure improvements | MRO Providers | The National Development and Reform Commission initiated a $2 billion fund for aviation infrastructure improvements. |
| Expansion of private jet ownership | Private Jet Operators | China's private jet market is expected to grow by 15% annually through 2025, increasing maintenance needs. |
| Implementation of new safety regulations | Full Rebuild | The Civil Aviation Administration of China updated the 'Regulations on Aircraft Maintenance' in 2022 to improve safety standards. |
Growth in the Structural Component Overhaul market in China comes from increased military spending, rising air traffic and investments in infrastructure. The military budget for aviation maintenance is projected at $10 billion in 2023, resulting in more contracts for MRO providers. Air traffic is expected to reach 1 billion passengers by 2035, necessitating additional MRO services for the commercial fleet. The National Development and Reform Commission's $2 billion fund for aviation infrastructure improvements is enhancing service capabilities. The private jet market is projected to grow by 15% annually through 2025, driving demand for maintenance services.
Evaluation of Restraints in China Structural Component Overhaul Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Challenges in sourcing quality components for repairs | Landing Gear | MRO providers face difficulties in sourcing quality components, impacting repair timelines and costs. |
| Regulatory compliance costs impacting MRO providers | Full Rebuild | Compliance with updated regulations increases operational costs for MRO providers, limiting profitability. |
| Shortage of skilled technicians affecting service delivery | MRO Providers | The lack of skilled technicians delays service delivery, affecting overall market efficiency. |
| Increased operational costs due to inflation | Military Jets | Inflation has raised operational costs for MRO providers, impacting their pricing strategies. |
| Limited access to advanced repair technologies | Fixed-Wing Aircraft | MRO providers struggle with access to advanced repair technologies, hindering service quality. |
China Structural Component Overhaul Market Challenges
Buyers and suppliers in the China Structural Component Overhaul market encounter fierce competition, with over 200 registered MRO providers competing for a limited number of contracts, which drives down prices and squeezes profit margins for producers. This competitive pressure forces suppliers to reduce costs, potentially compromising repair quality and jeopardising safety for airlines and military operators. Regulatory challenges arise from stringent standards set by the Civil Aviation Administration of China; non-compliance can result in penalties exceeding $1 million for MRO providers, creating financial strain. Furthermore, supply chain disruptions can delay critical repairs; reliance on a few key suppliers for essential components risks postponing maintenance schedules, affecting operational readiness for aircraft operators.
Trends in the China Structural Component Overhaul Market
Buyers and suppliers in the China Structural Component Overhaul Market are adjusting to the following trends.
- Shift towards Advanced Non-Destructive Testing: China is increasingly adopting advanced non-destructive testing (NDT) methods for aircraft maintenance. The National Standard GB/T 12345-2020 governs these processes, ensuring safety and compliance. This shift improves the quality of overhauls and repairs.
- Transition from Full Rebuilds to Partial Refurbishments: MRO providers are shifting focus from full rebuilds to partial refurbishments as a cost-effective solution. The market for partial refurbishments is projected to grow at a CAGR of 6.2% through 2032, reflecting changing buyer preferences.
- Expansion of MRO Facilities in Key Regions: Significant investments in MRO facilities are occurring in the Beijing-Tianjin-Hebei region, a major hub for aviation activities. This area is expected to see a 20% increase in MRO capacity by 2025, enhancing service availability.
- Growth of Private Jet Maintenance Services: The private jet maintenance segment is experiencing rapid growth, with an expected annual increase of 15% through 2025. This trend is driven by rising disposable incomes and a growing affluent class in China.
Investment Opportunities in the China Structural Component Overhaul Market
Several openings in the China Structural Component Overhaul Market merit attention from investors.
- MRO Providers seeking advanced technologies: MRO providers need to invest in advanced repair technologies to meet rising safety standards. The Guangdong province, known for its aircraft manufacturing, presents opportunities for partnerships and technology transfer.
- Investment in Aviation Infrastructure Development: The $2 billion fund initiated by the National Development and Reform Commission creates opportunities for infrastructure development in MRO facilities. Collaborating with local governments can facilitate entry into this growing market.
- Growing demand for Military Aircraft Maintenance: With military budgets increasing, there is an opportunity for MRO providers to expand services. Defense Maintenance Units are seeking reliable partners to ensure aircraft readiness.
- Expansion of Private Jet Maintenance Services: The rapid growth of the private jet market presents opportunities for MRO providers to offer specialized services. Establishing partnerships with private jet operators can improve service offerings.
Government Initiatives in the China Structural Component Overhaul Market
In 2023, the National Development and Reform Commission initiated the $2 billion fund for aviation infrastructure improvements, which supports MRO capabilities across the country. This measure complements the 2022 updates to the 'Regulations on Aircraft Maintenance' by the Civil Aviation Administration of China, which aimed to improve safety standards and operational efficiency for MRO providers. Together, these initiatives support the growth of the Structural Component Overhaul market by ensuring that facilities are well-equipped to meet increasing demand.
MRO providers benefit from the 'Aerospace Industry Development Plan' launched by the Ministry of Industry and Information Technology in 2021, which supports domestic capabilities. This plan allocates funding for new technologies and training programs for technicians, ensuring that MRO providers can meet evolving industry standards. The Civil Aviation Administration of China also plays a role in approving safety protocols, ensuring compliance and quality assurance in maintenance services.
Future Insight of the China Structural Component Overhaul Market
The China Structural Component Overhaul market is poised for transformation by 2032, driven by the 'Aviation Industry Development Plan' which aims to strengthen MRO capabilities across the country. With China's air traffic projected to reach 1 billion passengers by 2035, MRO providers will likely adopt advanced technologies to improve service delivery. The 'Made in China 2025' initiative will further encourage advancements in aerospace technology, allowing suppliers to streamline operations. Additionally, the 'Green Aviation' initiative will promote environmentally friendly practices, shaping future operational standards for buyers and suppliers.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Component Type – Wing Spars Dominated, Landing Gear Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, the largest component type category in 2025 was Wing Spars, with a 43% share of total revenue. Wing spars command a substantial share of the China Structural Component Overhaul Market as they are essential for maintaining the structural integrity of aircraft. The high number of commercial aircraft produced, exceeding 300 in 2022, underscores the ongoing demand for this critical component type. Landing Gear is set to record the highest CAGR in this split, 6.6% over 2026–2032. Landing gear is experiencing rapid growth due to its crucial role in ensuring safe landings, with projections indicating air traffic could reach 1 billion passengers by 2035. This surge in demand aligns with the government's 'Aviation Industry Development Plan' aimed at enhancing maintenance capabilities. Suppliers should focus on landing gear solutions to meet the increasing demand in the structural component overhaul market.
By Overhaul Level – Full Rebuild Dominated, Partial Refurbishment Expected to Grow Fastest
With a 52% revenue share in 2025, Full Rebuild was the largest overhaul level category. Full rebuilds lead the market share as they are vital for comprehensive restoration, ensuring aircraft meet safety and regulatory standards. The rigorous maintenance regulations enforced by the Civil Aviation Administration of China necessitate thorough overhauls to maintain operational readiness. The quickest growth will come from Partial Refurbishment, forecast to expand at a CAGR of 6.2% between 2026 and 2032. Partial refurbishments are rapidly gaining traction as a cost-effective maintenance solution, appealing to MRO providers looking to optimise budgets amid rising operational expenses. The growth of registered MRO providers in China, now over 200, is a key factor driving this trend. Buyers should consider partial refurbishment options to balance cost management with the need for aircraft safety and compliance.
By Platform Type – Fixed-Wing Aircraft Dominated, Helicopters Expected to Grow Fastest
Fixed-Wing Aircraft accounted for a 45% market share by platform type in 2025. Fixed-wing aircraft dominate the market, accounting for the majority of the commercial fleet in China. The production of over 300 commercial aircraft in 2022 highlights the significant demand for overhaul services in this segment. Over 2026–2032, Helicopters are expected to post the fastest growth, at a CAGR of 7.0%. Helicopters are the fastest-growing segment, driven by their importance in military and civilian operations, especially in areas with high air traffic. The military's focus on maintaining operational readiness is a major factor propelling this growth. Suppliers should enhance their helicopter overhaul services to cater to the increasing demand from both military and civilian sectors.
By End User – MRO Providers Dominated, Defense Maintenance Units Expected to Grow Fastest
MRO Providers held a 39% share of the China Structural Component Overhaul Market by end user in 2025. MRO providers hold the largest share in the market as they are the primary service providers for aircraft maintenance and overhaul. Their established relationships with aircraft operators ensure a consistent demand for structural component services. Defense Maintenance Units are projected to grow fastest, at a CAGR of 7.4% during 2026–2032. Defense maintenance units are the fastest-growing segment, reflecting the military's dedication to maintaining operational readiness with a projected budget of $10 billion for aviation maintenance in 2023. This growth is vital for ensuring the safety and reliability of military aircraft. Suppliers should align their services with the requirements of defense maintenance units to tap into this expanding market segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Structural Component Overhaul Market Outlook
- Market Size of China Structural Component Overhaul Market, 2025
- Forecast of China Structural Component Overhaul Market, 2032
- Historical Data and Forecast of China Structural Component Overhaul Revenues & Volume for the Period 2022 - 2032F
- China Structural Component Overhaul Market Trend Evolution
- China Structural Component Overhaul Market Drivers and Challenges
- China Structural Component Overhaul Price Trends
- China Structural Component Overhaul Porter's Five Forces
- China Structural Component Overhaul Industry Life Cycle
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Wing Spars for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Landing Gear for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Empennage for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Airframe Sections for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Overhaul Level for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Full Rebuild for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Partial Refurbishment for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By NDT + Repair for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Surface Rework for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Platform Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Fixed-Wing Aircraft for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Helicopters for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Business Jets for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Military Jets for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By MRO Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Defense Maintenance Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Private Jet Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Component Overhaul Market Revenues & Volume By Air Force Bases for the Period 2022 - 2032F
- China Structural Component Overhaul Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Overhaul Level
- Market Opportunity Assessment By Platform Type
- Market Opportunity Assessment By End User
- China Structural Component Overhaul Top Companies Market Share
- China Structural Component Overhaul Competitive Benchmarking By Technical and Operational Parameters
- China Structural Component Overhaul Company Profiles
- China Structural Component Overhaul Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Component Type
- Wing Spars
- Landing Gear
- Empennage
- Airframe Sections
By Overhaul Level
- Full Rebuild
- Partial Refurbishment
- NDT + Repair
- Surface Rework
By Platform Type
- Fixed-Wing Aircraft
- Helicopters
- Business Jets
- Military Jets
By End User
- MRO Providers
- Defense Maintenance Units
- Private Jet Operators
- Air Force Bases































