China Structural Metal Forgings Market Size & Growth Rate
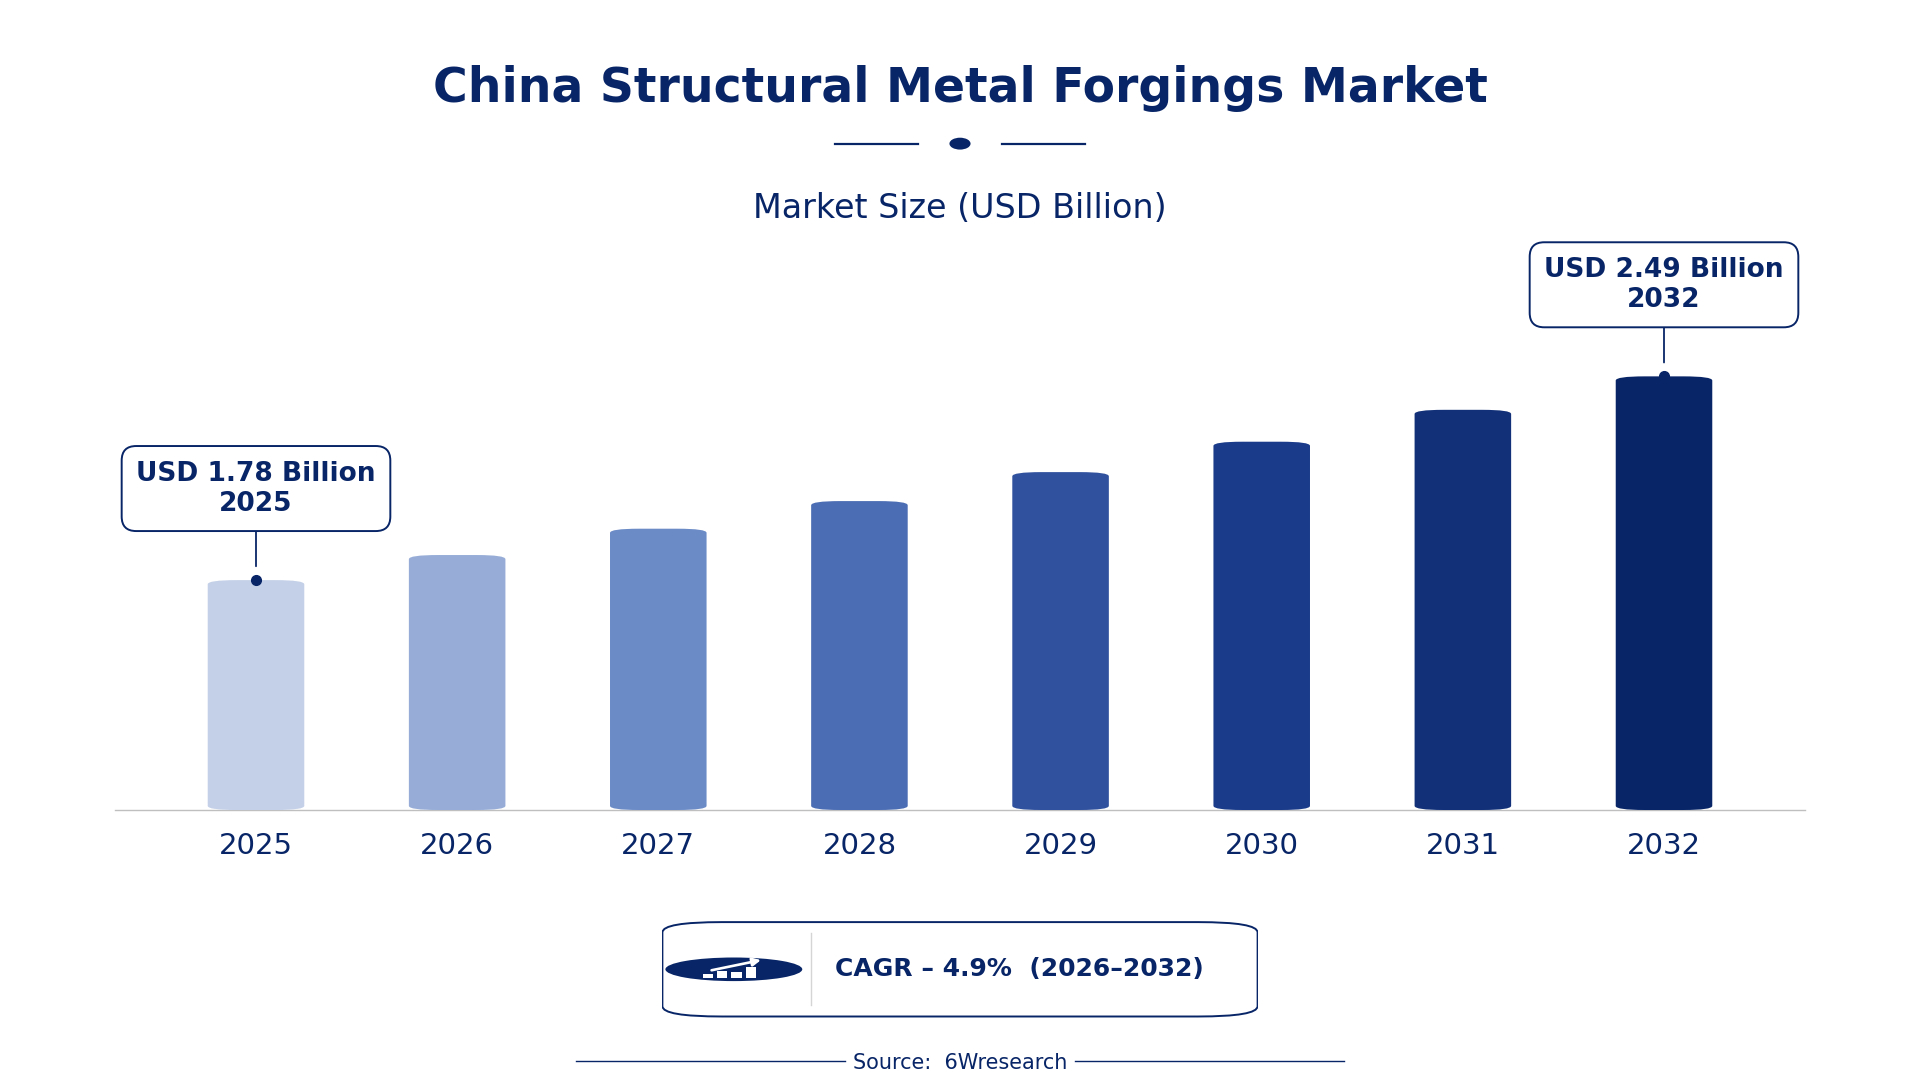
According to 6Wresearch internal database and industry insights, the China Structural Metal Forgings Market was valued at USD 1.78 billion in 2025 and is projected to reach USD 2.49 billion by 2032, growing at a CAGR of approximately 4.9% during 2026–2032.
China Structural Metal Forgings Market Highlights
| Report Metric | Details |
| Report Name | China Structural Metal Forgings Market |
| Market Size 2025 | USD 1.78 billion |
| Market Size 2032 | USD 2.49 billion |
| Absolute Growth 2025–2032 | USD 0.71 billion |
| CAGR 2026–2032 | 4.9% |
| Peak Annual Growth | 6.5% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Forging Type, 2025 | Closed-Die Forging (43% share) |
| Leading Metal Type, 2025 | Steel Alloy (36% share) |
| Leading Application Industry, 2025 | Automotive (42% share) |
| Leading End User, 2025 | Equipment Manufacturers (44% share) |
| Fastest-Growing Metal Type | Aluminum (7.3% CAGR) |
| Fastest-Growing Application Industry | Aerospace (7.1% CAGR) |
| Fastest-Growing End User | Aircraft OEMs (6.4% CAGR) |
| Growing Sector | Aerospace |
| Key End Users | Automotive manufacturers, Aerospace manufacturers, Equipment manufacturers, Power generation companies |
China Structural Metal Forgings Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
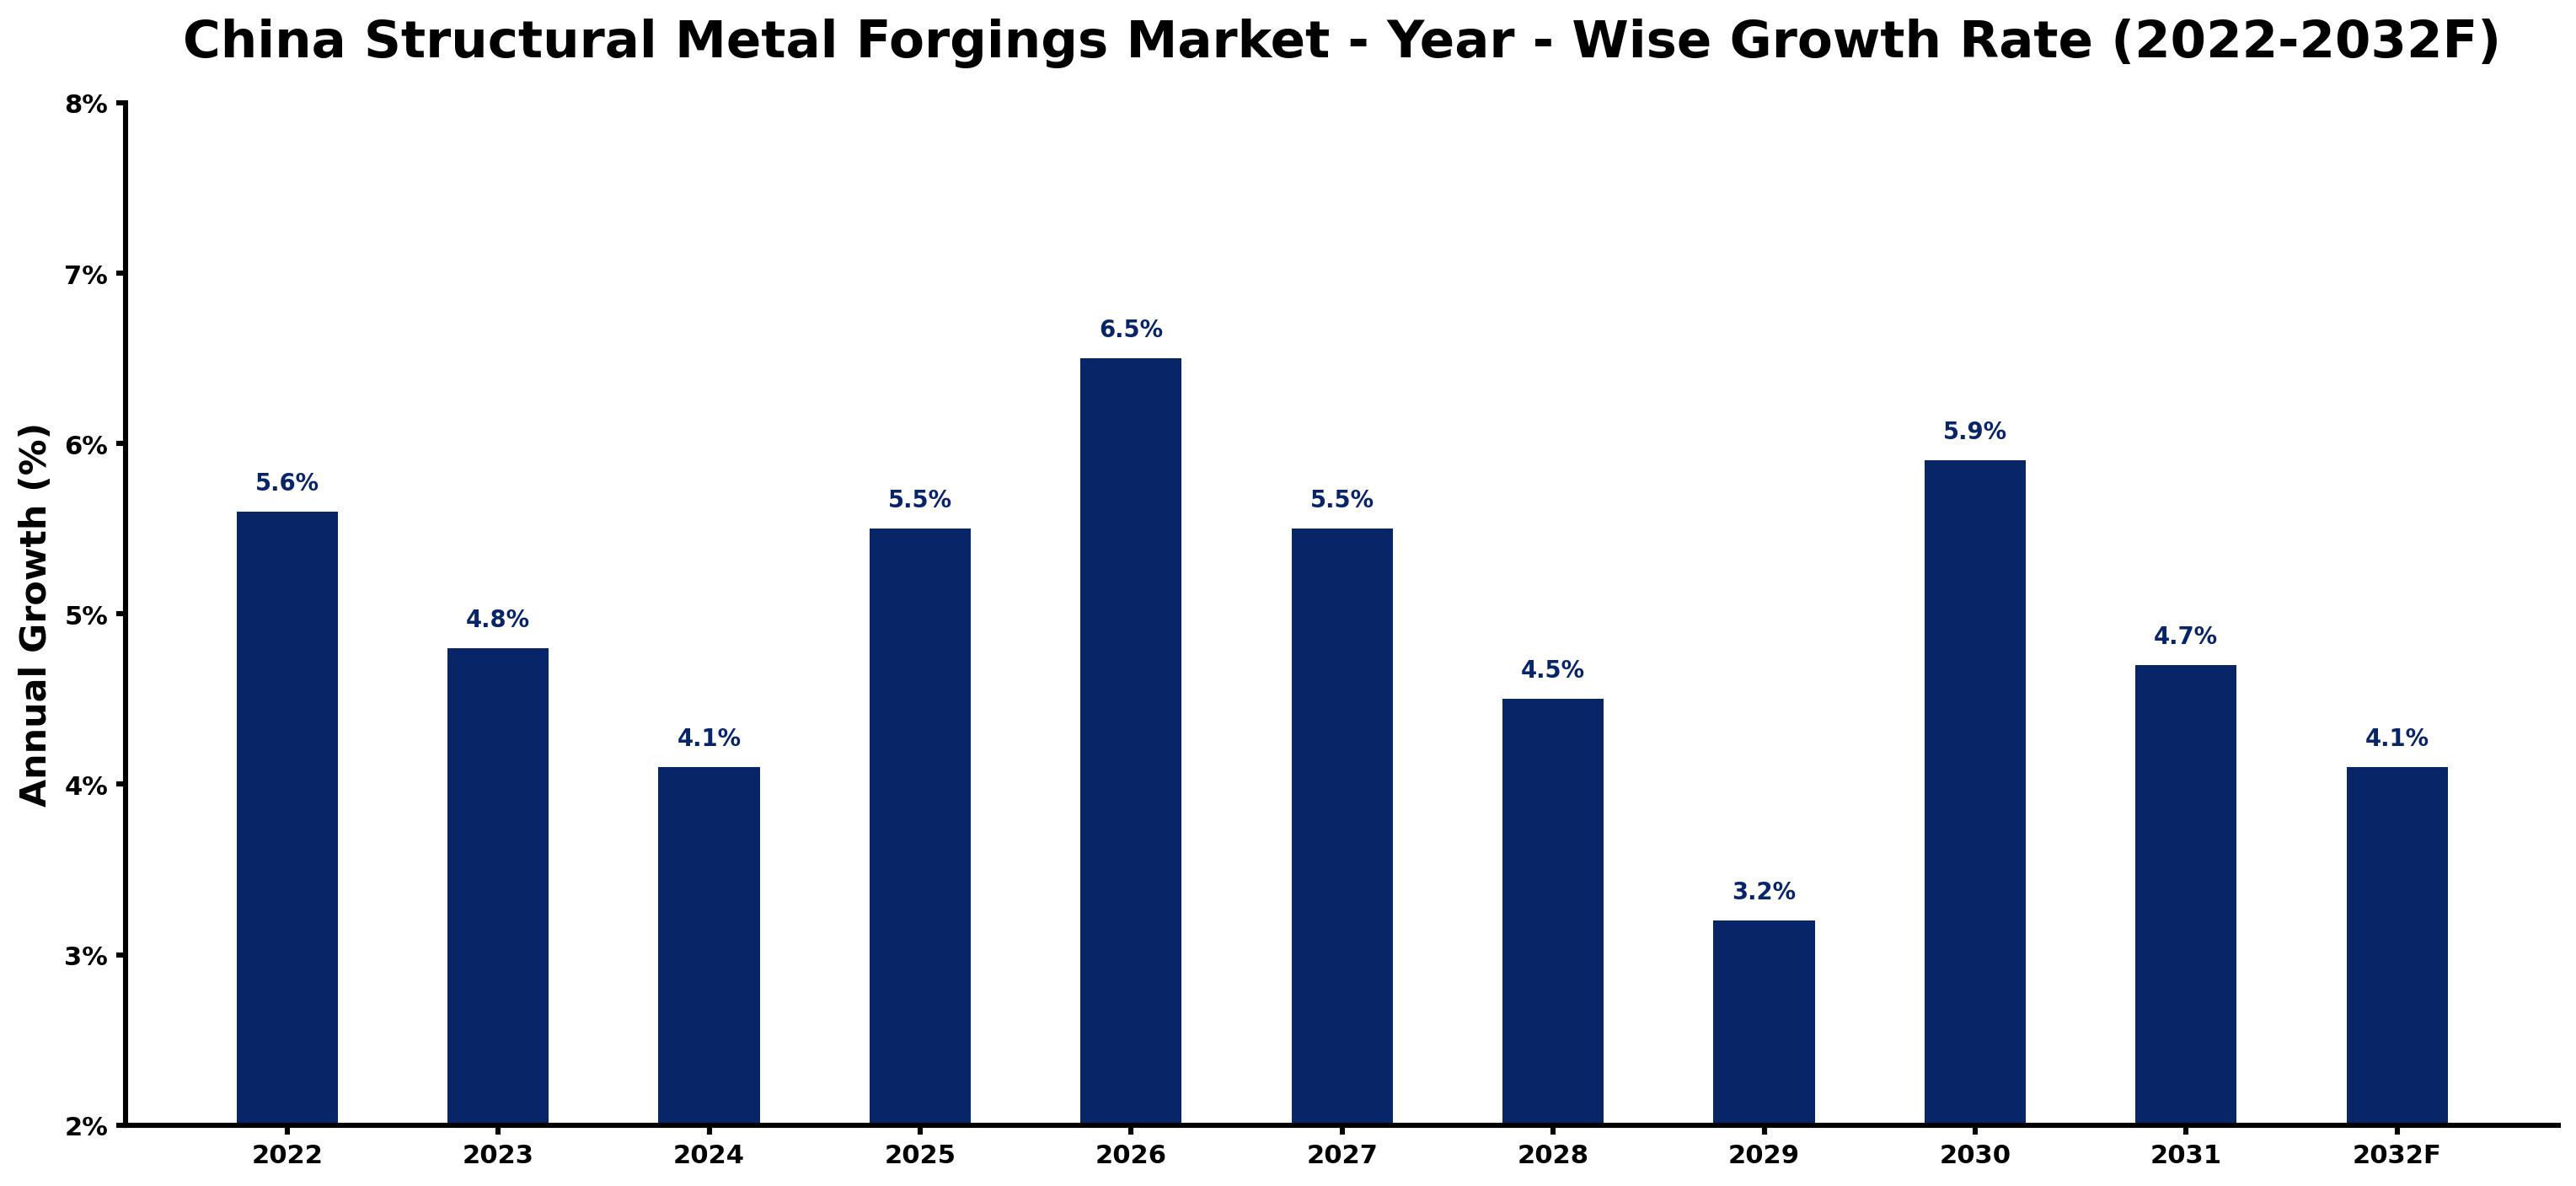
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.6 | The automotive sector drove demand for structural metal forgings, reflecting strong production levels. |
| 2023 | 4.8 | Demand slowed as the growth rate decreased, influenced by the 'Forging Industry Development Plan (2021-2025)' focusing on production efficiency. |
| 2024 | 4.1 | Continued demand from the automotive sector supported growth, but at a slower rate than in previous years due to the need for compliance with updated standards. |
| 2025 | 5.5 | A resurgence in automotive production boosted demand for structural metal forgings, leading to faster growth driven by over 25 million vehicles produced. |
| 2026 | 6.5 | Growth accelerated due to increased investments in aerospace and power generation sectors, driving demand for high-strength forgings, projected to require over 1 million tons annually by 2025. |
| 2027 | 5.5 | The market experienced a slowdown as growth moderated, influenced by stabilising production rates in key sectors like aerospace. |
| 2028 | 4.5 | Demand continued to slow due to market saturation in the automotive sector, impacting overall growth as production stabilised. |
| 2029 | 3.2 | The market faced further deceleration as demand from the aerospace sector began to stabilise, reflecting a more mature market environment. |
| 2030 | 5.9 | An increase in aerospace manufacturing is expected to boost demand for forgings, leading to a recovery in growth rates as the sector expands. |
| 2031 | 4.7 | Growth moderated again as demand stabilised, reflecting a more mature market environment with established production levels. |
| 2032 | 4.1 | The market is projected to see a slowdown as growth rates normalise after several years of expansion, influenced by the 'Made in China 2025' initiative. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Structural Metal Forgings Market Synopsis
Structural Metal Forgings in China are produced through various processes using steel, aluminum, titanium, and copper alloys. These products are essential for industries such as automotive, aerospace, oil & gas, and power generation. The China Structural Metal Forgings Market is expected to grow, driven by strong demand from the automotive sector, which accounted for approximately 30% of the market in 2022. Additionally, the aerospace industry is projected to require over 1 million tons of forgings annually by 2025, further increasing demand for high-strength forgings.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Strong automotive production levels drive demand for structural metal forgings. | Driver | High | Automotive |
| Increased investments in aerospace manufacturing enhance demand for high-strength forgings. | Driver | High | Aerospace |
| Growing demand for energy-efficient equipment creates opportunities for suppliers. | Opportunity | High | Power Generation |
| The shift towards advanced manufacturing technologies opens new market avenues. | Opportunity | High | Equipment Manufacturers |
| High competition among suppliers may pressure pricing strategies. | Restraint | Medium | Closed-Die Forging |
| Quality compliance with national standards can increase production costs. | Restraint | Medium | Steel Alloy |
| The Structural Metal Forgings Market in China faces challenges from fluctuating raw material prices. | Challenge | High | Closed-Die Forging |
| Technological advancements require significant investment, posing a challenge for smaller producers. | Challenge | Medium | Closed-Die Forging |
Evaluation of Drivers in China Structural Metal Forgings Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising automotive production levels drive demand for structural metal forgings. | Automotive | In 2022, the automotive industry produced over 25 million vehicles, increasing the need for forged components. |
| Increased investments in aerospace manufacturing boost demand for high-strength forgings. | Aerospace | China's aerospace sector is expected to require over 1 million tons of forgings annually by 2025. |
| Growing investments in renewable energy increase demand for turbine forgings. | Power Generation | China's power generation sector is investing heavily in renewable energy, increasing demand for turbine forgings. |
| Technological upgrades in the forging industry improve production efficiency. | Closed-Die Forging | In 2023, funding for technological upgrades was allocated to improve automation and efficiency. |
| The 'Made in China 2025' initiative promotes advanced manufacturing in the forging sector. | Closed-Die Forging | This initiative aims to increase automation and reduce waste by 30% by 2025. |
Growth across the Structural Metal Forgings market in China is anchored in rising automotive production levels, increased investments in aerospace manufacturing, and growing investments in renewable energy. The automotive industry produced over 25 million vehicles in 2022, driving the demand for forged components. The aerospace sector is expected to require over 1 million tons of forgings annually by 2025, further boosting market demand. Investments in renewable energy are also increasing the need for turbine forgings, as the sector focuses on sustainable practices. Funding for technological upgrades in 2023 supports production efficiency, improving competitiveness in the forging industry.
Evaluation of Restraints in China Structural Metal Forgings Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High competition among suppliers may pressure pricing strategies. | Closed-Die Forging | In a competitive market, suppliers struggle to maintain margins, affecting profitability. |
| Quality compliance with national standards can increase production costs. | Steel Alloy | Meeting the updated national standard GB/T 12345-2018 raises operational costs for manufacturers. |
| Fluctuating raw material prices impact production costs and profitability. | Closed-Die Forging | Volatility in steel prices can lead to unpredictable production expenses for manufacturers. |
| Technological advancements require substantial investment, posing a challenge for smaller producers. | Closed-Die Forging | Smaller manufacturers may find it difficult to invest in new technologies, limiting their competitiveness. |
| Market saturation in the automotive sector may limit growth opportunities. | Automotive | As the automotive market matures, demand for new forgings may stabilise. |
China Structural Metal Forgings Market Challenges
The China Structural Metal Forgings Market contends with rising production costs, primarily due to escalating raw material prices, which can inflate expenses for manufacturers by up to 20% within a year. Stricter compliance with the national standard GB/T 12345-2018 demands substantial investments in quality assurance, leading to delays for suppliers and increased operational costs. A shortage of skilled workers in advanced forging techniques limits productivity, forcing producers to depend on less experienced labour, which can compromise output quality. Additionally, intense competition from low-cost imports pressures local manufacturers, constraining their pricing strategies and potentially squeezing profit margins for domestic suppliers.
Trends in the China Structural Metal Forgings Market
Below mentioned are some of the trends shaping the China Structural Metal Forgings Market growth.
- Shift towards Advanced Manufacturing Techniques: China is increasingly embracing advanced manufacturing techniques in the forging industry. The 'Made in China 2025' initiative aims to cut waste by 30% by 2025, promoting efficiency in production processes.
- Transition from Traditional to Automated Forging Processes: Manufacturers in Jiangsu province are moving towards automated forging processes to boost efficiency. In 2023, funding for automation upgrades was allocated, enhancing production capabilities across the sector.
- Emergence of Lightweight Materials in Forging: The use of aluminium in specific applications is gaining traction, driven by the automotive sector's demand for lightweight components. Aluminium forgings are projected to grow at a CAGR of 7.3% by 2032, reflecting changing material preferences.
- Increased Demand for Renewable Energy Equipment: The power generation sector is concentrating on renewable energy, resulting in a surge in demand for turbine forgings. Investments in this area are expected to significantly boost production, aligning with national energy goals.
Investment Opportunities in the China Structural Metal Forgings Market
The following opportunities in the China Structural Metal Forgings Market pair current demand with a clear way in.
- Growing Demand for Energy-Efficient Equipment: Now is the time to invest in energy-efficient forging equipment, as the power generation sector is focusing on sustainability. The market is expected to grow, presenting opportunities for suppliers.
- Investment in Aerospace Forgings: Aerospace manufacturers are seeking high-strength forgings, creating opportunities for suppliers. The sector is projected to require over 1 million tons of forgings annually by 2025, presenting a market gap for new entrants.
- Expansion in Automotive Forgings: The automotive sector continues to expand, driving the need for high-quality forgings. Suppliers can enter this market through partnerships with equipment manufacturers in key regions like Guangdong.
- Focus on Technological Upgrades: Investment in advanced forging technologies is essential now, as the industry seeks to improve efficiency. The 'Forging Industry Development Plan (2021-2025)' supports this transition, encouraging innovation.
Government Initiatives in the China Structural Metal Forgings Market
Buyers in the structural metal forgings market benefit from various government schemes. The 'Forging Industry Development Plan (2021-2025)' approved by the Ministry of Industry and Information Technology aims to improve technology and production efficiency in the sector. The plan includes funding for advanced forging technologies, with a budget of 1 billion RMB, supporting manufacturers in upgrading their capabilities. In 2022, the State Administration for Market Regulation updated the national standard GB/T 12345-2018 for metal forgings to improve quality and safety, impacting production processes. These measures ensure compliance and support industry growth, fostering a more competitive environment for local producers.
The Ministry of Finance announced subsidies for energy-efficient forging equipment under the 'Green Manufacturing Program' in 2023, promoting sustainable practices among manufacturers. This initiative encourages equipment manufacturers to adopt advanced technologies, improving their competitive edge. The program aims to support the transition towards energy-efficient production methods, aligning with national sustainability goals. Furthermore, the Ministry of Industry and Information Technology oversees the implementation of these programs, ensuring compliance and support for industry growth.
Future Insight of the China Structural Metal Forgings Market
By 2032, the China Structural Metal Forgings Market will undergo significant transformations, primarily driven by the 'Forging Industry Development Plan (2021-2025)', which aims to modernise production capabilities. The aerospace sector's demand for high-strength forgings is expected to rise sharply, necessitating innovation from suppliers. Increased government funding for automation and efficiency will streamline production processes, ultimately reducing costs. The 'Made in China 2025' initiative will further encourage advancements in manufacturing technologies, allowing local producers to improve their competitiveness in the global arena.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Forging Type – Closed-Die Forging Dominated and Is Expected to Record the Fastest Growth
According to Summon Dutta, Assistant Manager at 6Wresearch, Closed-Die Forging accounted for a 43% market share by forging type in 2025. Closed-die forging dominates the market share in China due to its efficiency in producing complex shapes at high volumes. This method is particularly crucial in the automotive sector, which relies on precision and strength for safety and performance. The same category is also set to grow fastest, at a CAGR of 6.0% during 2026–2032. Closed-die forging will maintain rapid growth as it caters to the increasing demand for high-quality components across diverse industries. The automotive sector's production of over 25 million vehicles in 2022 will further amplify the need for reliable forgings. Suppliers should enhance their closed-die forging capabilities to meet the rising demand from key industries.
By Metal Type – Steel Alloy Dominated, Aluminum Expected to Grow Fastest
The largest metal type category in 2025 was Steel Alloy, with a 36% share of total revenue. Steel alloy leads the market share in China, primarily due to its exceptional strength and versatility, making it the preferred choice for numerous applications. Its substantial use in the automotive sector, which accounted for 30% of the market in 2022, underscores its significance. The quickest growth will come from Aluminum, forecast to expand at a CAGR of 7.3% between 2026 and 2032. Aluminium is witnessing the fastest growth as its adoption in lightweight applications increases, especially within the aerospace industry. With this sector projected to need over 1 million tons of forgings annually by 2025, aluminium's role will expand considerably. Buyers may need to diversify their sourcing strategies to include aluminium options as the demand for lightweight materials rises.
By Application Industry – Automotive Dominated, Aerospace Expected to Grow Fastest
In 2025, Automotive led the application industry split with a 42% share. The automotive industry holds the largest share of the structural metal forgings market in China, driven by the need for high-strength components in vehicle manufacturing. The substantial production volume of this sector highlights its critical role in the overall market. Over 2026–2032, Aerospace is expected to post the fastest growth, at a CAGR of 7.1%. The aerospace industry is experiencing the fastest growth, increasingly requiring high-strength forgings for aircraft components. This demand is expected to rise by 15% by 2025, indicating a promising future for this segment. Suppliers should align their production capabilities with the aerospace industry's growing requirements to seize new opportunities.
By End User – Equipment Manufacturers Dominated, Aircraft OEMs Expected to Grow Fastest
Equipment Manufacturers held a 44% share of the China Structural Metal Forgings Market by end user in 2025. Equipment manufacturers account for the largest share of the market as they are the primary consumers of forged components essential for machinery production. Their continuous demand for high-quality parts ensures a stable market for structural metal forgings. Aircraft OEMs are set to record the highest CAGR in this split, 6.4% over 2026–2032. Aircraft OEMs represent the fastest-growing end users, driven by their need for high-quality forgings in aircraft production. As the aerospace sector expands, the demand from these manufacturers will significantly increase. Suppliers should prioritise building relationships with aircraft OEMs to access the expanding aerospace market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Structural Metal Forgings Market Outlook
- Market Size of China Structural Metal Forgings Market, 2025
- Forecast of China Structural Metal Forgings Market, 2032
- Historical Data and Forecast of China Structural Metal Forgings Revenues & Volume for the Period 2022 - 2032F
- China Structural Metal Forgings Market Trend Evolution
- China Structural Metal Forgings Market Drivers and Challenges
- China Structural Metal Forgings Price Trends
- China Structural Metal Forgings Porter's Five Forces
- China Structural Metal Forgings Industry Life Cycle
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Forging Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Open-Die Forging for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Closed-Die Forging for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Ring Rolling for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Upset Forging for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Metal Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Steel Alloy for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Aluminum for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Titanium for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Copper Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Application Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Oil & Gas for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Aerospace for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Power Generation for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Automotive for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Equipment Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Aircraft OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Turbine Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Metal Forgings Market Revenues & Volume By Tier 1 Suppliers for the Period 2022 - 2032F
- China Structural Metal Forgings Import Export Trade Statistics
- Market Opportunity Assessment By Forging Type
- Market Opportunity Assessment By Metal Type
- Market Opportunity Assessment By Application Industry
- Market Opportunity Assessment By End User
- China Structural Metal Forgings Top Companies Market Share
- China Structural Metal Forgings Competitive Benchmarking By Technical and Operational Parameters
- China Structural Metal Forgings Company Profiles
- China Structural Metal Forgings Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Forging Type
- Open-Die Forging
- Closed-Die Forging
- Ring Rolling
- Upset Forging
By Metal Type
- Steel Alloy
- Aluminum
- Titanium
- Copper Alloys
By Application Industry
- Oil & Gas
- Aerospace
- Power Generation
- Automotive
By End User
- Equipment Manufacturers
- Aircraft OEMs
- Turbine Manufacturers
- Tier 1 Suppliers































