China Structural Steel Components for Vehicles Market Size & Growth Rate
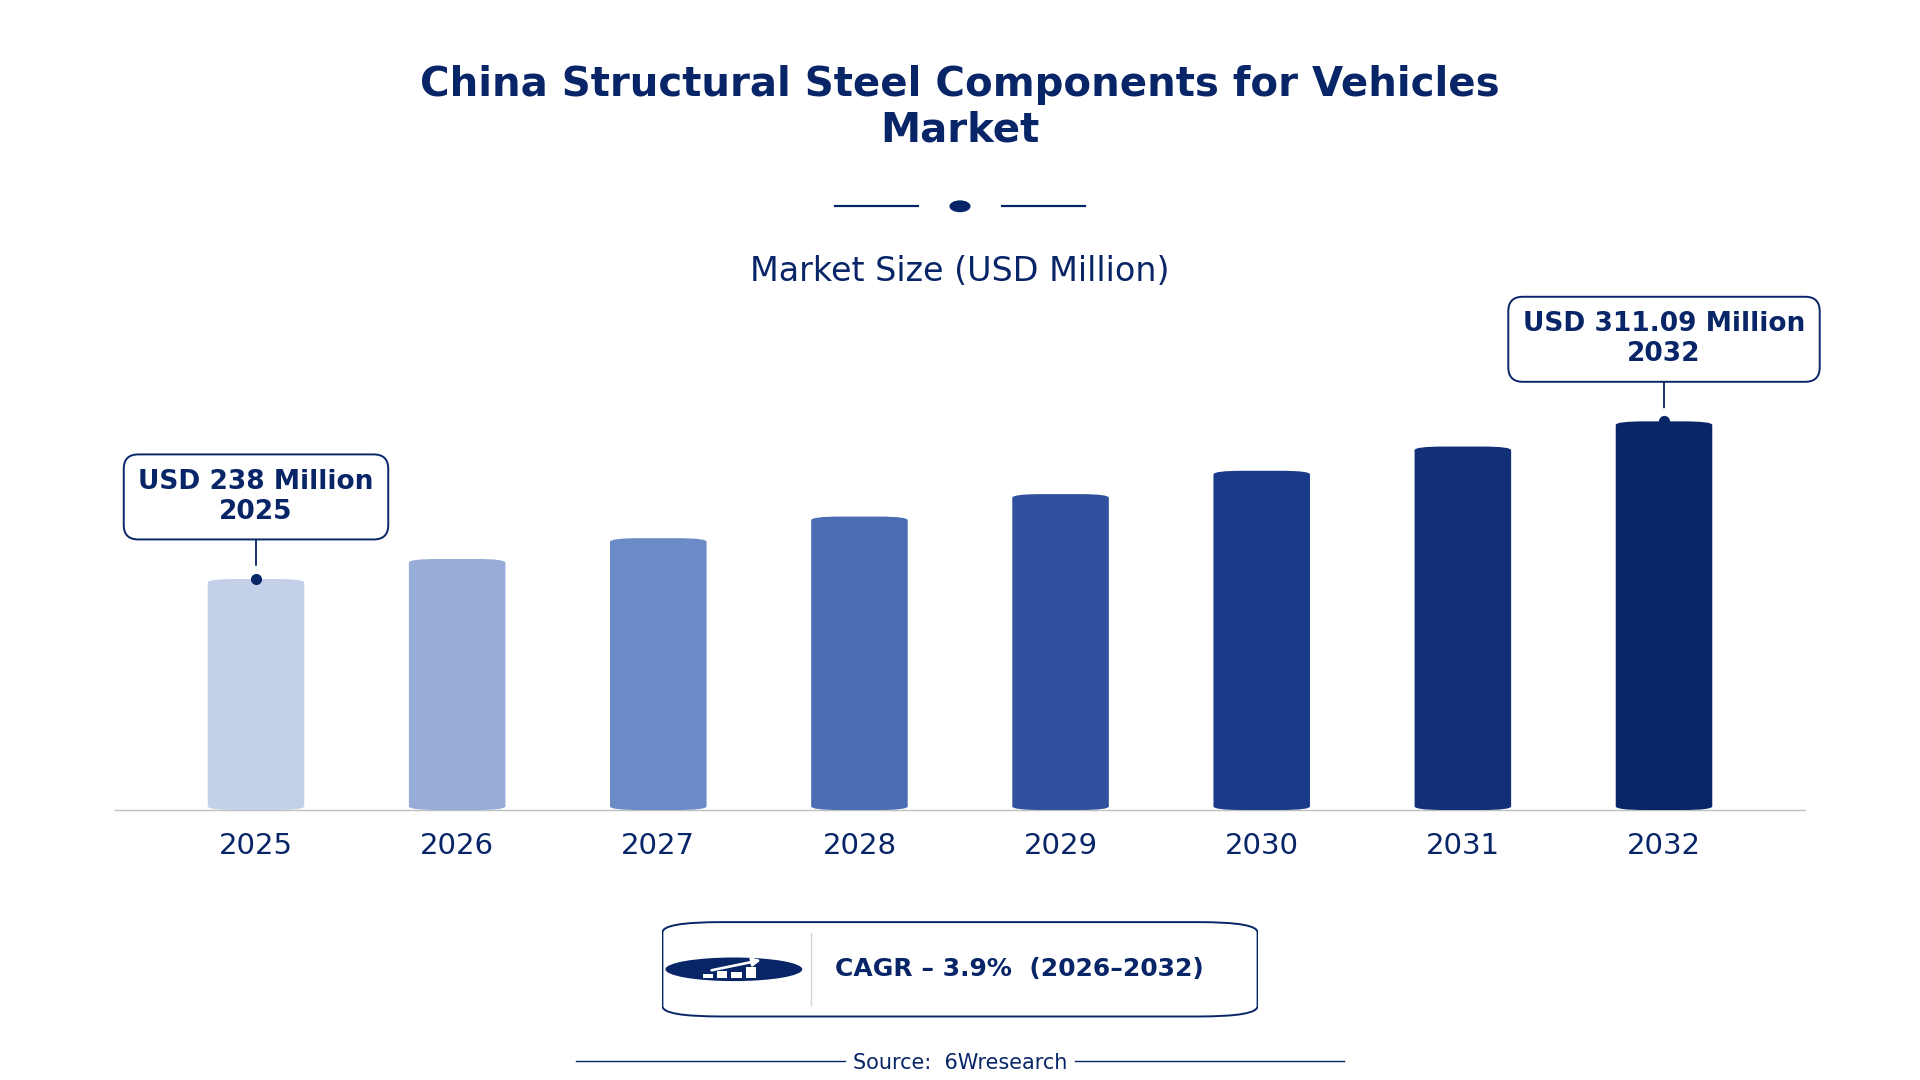
According to 6Wresearch internal database and industry insights, the China Structural Steel Components for Vehicles Market was valued at USD 238.0 million in 2025 and is projected to reach USD 311.09 million by 2032, growing at a CAGR of approximately 3.9% during 2026–2032.
China Structural Steel Components for Vehicles Market Highlights
| Report Metric | Details |
| Report Name | China Structural Steel Components for Vehicles Market |
| Market Size 2025 | USD 238.0 million |
| Market Size 2032 | USD 311.09 million |
| Absolute Growth 2025–2032 | USD 73.09 million |
| CAGR 2026–2032 | 3.9% |
| Peak Annual Growth | 6.2% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Side Impact Beams (46% share) |
| Leading Steel Grade, 2025 | High-Strength Steel (48% share) |
| Leading Vehicle Segment, 2025 | SUVs (42% share) |
| Leading End User, 2025 | Vehicle OEMs (34% share) |
| Fastest-Growing Component Type | Bumper Beams (5.8% CAGR) |
| Fastest-Growing Vehicle Segment | Sedans (5.2% CAGR) |
| Fastest-Growing End User | Safety System Providers (6.0% CAGR) |
| Growing Sector | automotive manufacturing |
| Key End Users | Vehicle OEMs, Safety System Providers, Body Structure Suppliers |
China Structural Steel Components for Vehicles Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
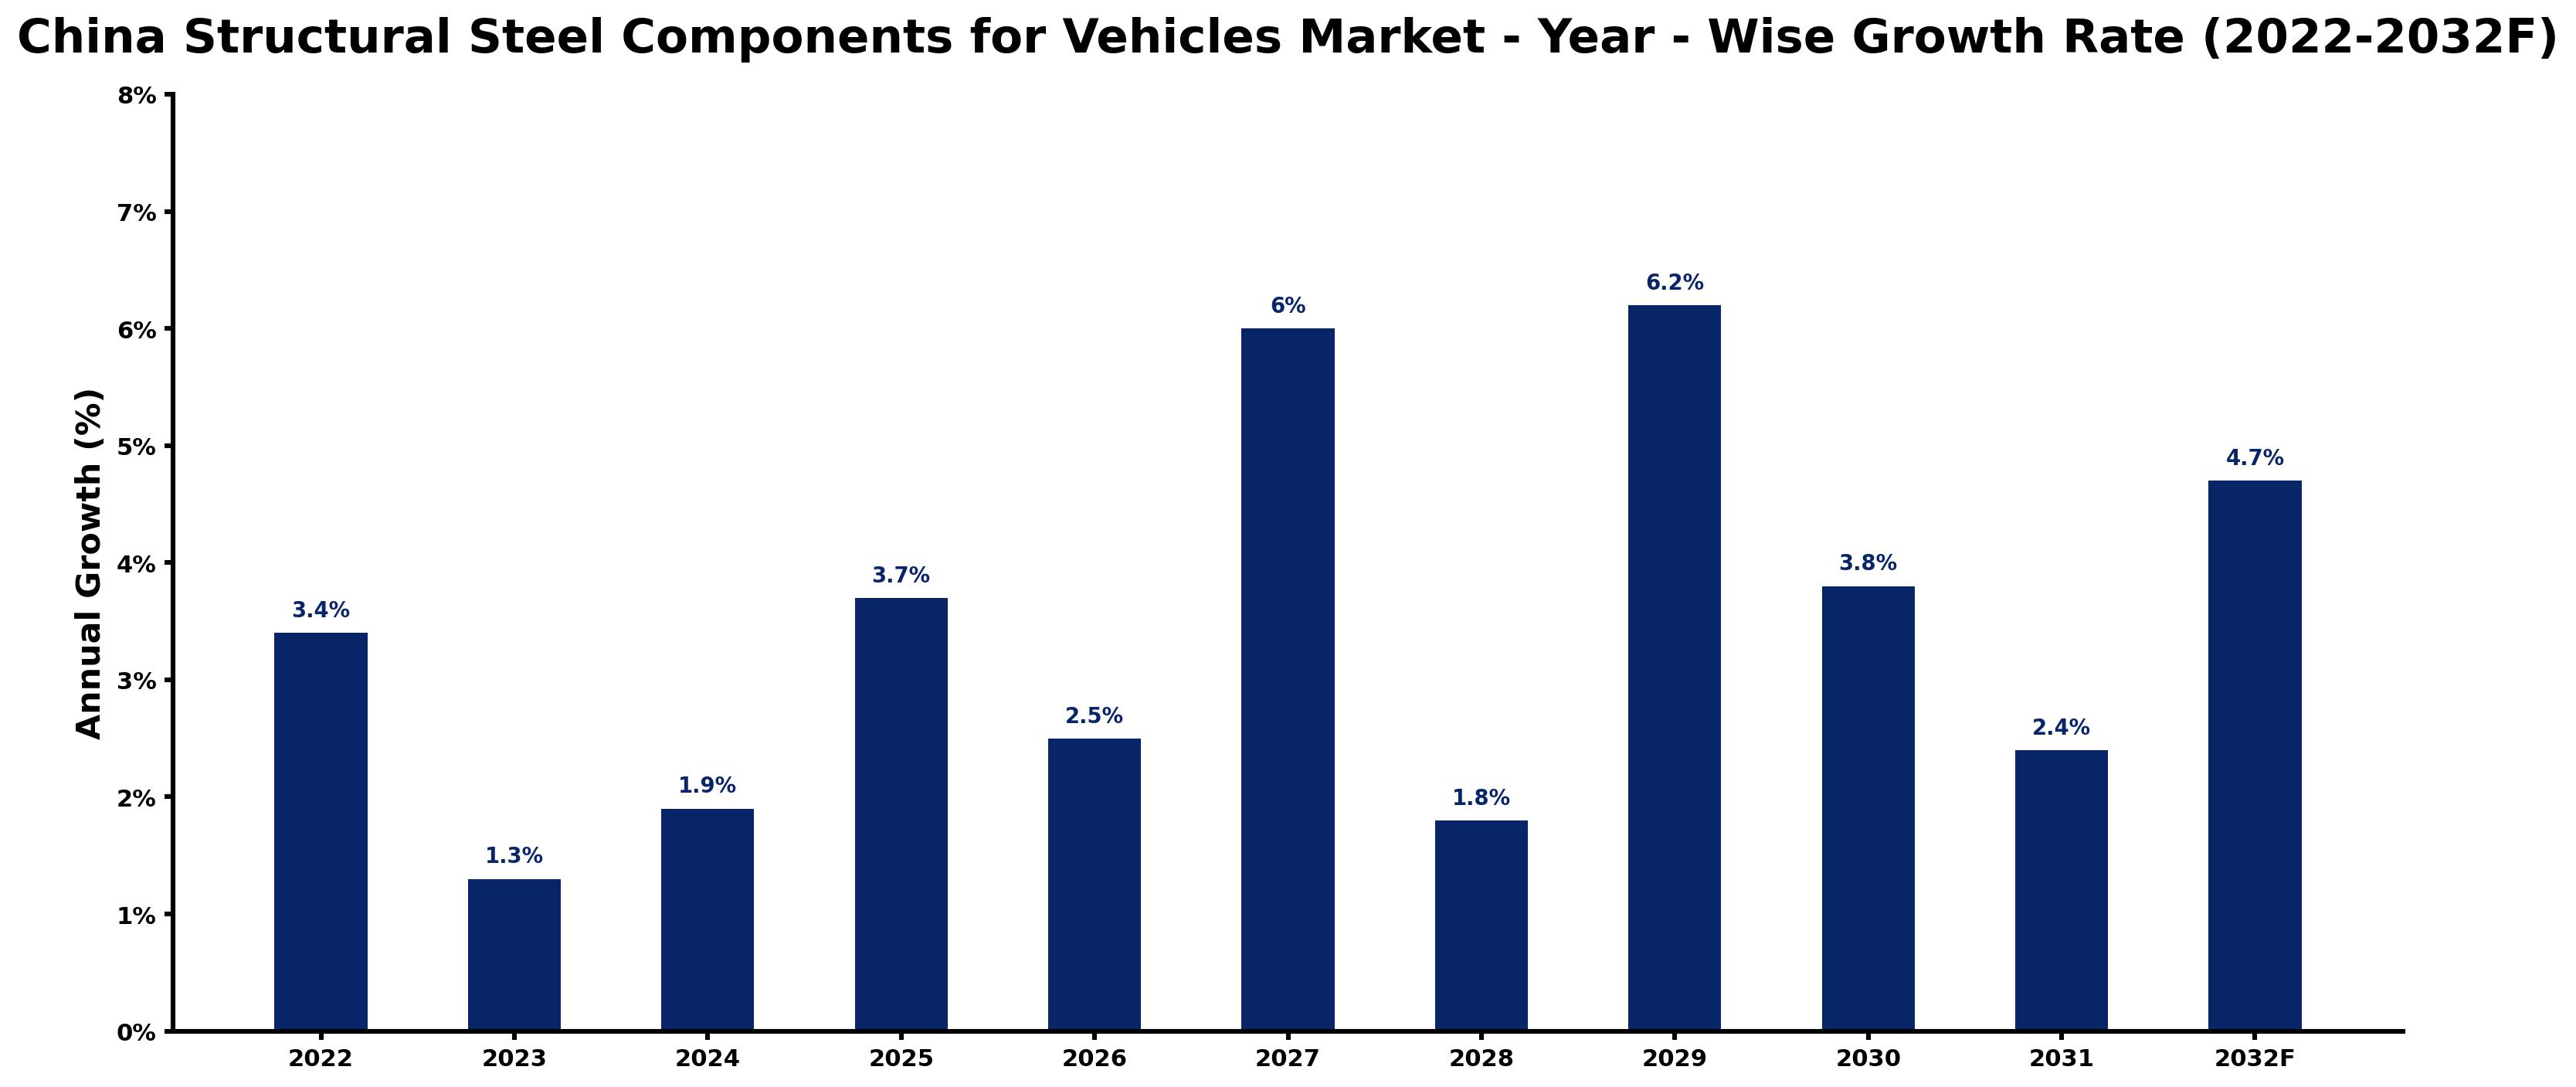
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.4 | The market experienced steady growth, driven by strong vehicle production figures. |
| 2023 | 1.3 | Growth slowed as manufacturers adjusted to evolving safety regulations and market demands. |
| 2024 | 1.9 | An increase in high-strength steel usage contributed to a faster growth rate compared to 2023. |
| 2025 | 3.7 | The market saw a notable rise as demand for structural components surged with vehicle production. |
| 2026 | 2.5 | Growth slowed as manufacturers faced challenges in sourcing high-quality materials. |
| 2027 | 6.0 | A significant increase in SUV production boosted demand for structural components. |
| 2028 | 1.8 | Growth slowed due to market adjustments and fluctuating demand for certain vehicle types. |
| 2029 | 6.2 | The market peaked with heightened demand for safety features in vehicles driving growth. |
| 2030 | 3.8 | Growth slowed as the market began to stabilise after the peak in 2029. |
| 2031 | 2.4 | The market continued to grow, albeit at a slower pace, reflecting a maturing phase. |
| 2032 | 4.7 | Demand is expected to rise again as new safety standards are implemented. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Structural Steel Components for Vehicles Market Synopsis
Structural Steel Components for Vehicles in China include crucial parts crafted from various steel grades that improve vehicle safety and performance. These components are manufactured through stamping, welding, and assembly processes. The China Structural Steel Components for Vehicles Market is expanding, driven by a strong automotive sector that produced over 25 million vehicles in 2022. Heightened safety regulations and a rising preference for SUVs are propelling market growth. High-strength steel is now incorporated in 70% of new vehicle models, indicating a marked shift towards enhanced safety features.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing vehicle production in China | Driver | High | Bumper Beams |
| Increasing demand for high-strength materials | Driver | High | High-Strength Steel |
| Rising consumer preference for SUVs | Opportunity | High | SUVs |
| Growing emphasis on safety regulations | Opportunity | High | Safety System Providers |
| Challenges in sourcing high-quality materials | Restraint | High | Side Impact Beams |
| Compliance with stringent safety standards | Restraint | High | Bumper Beams |
| Supply chain disruptions affecting production timelines | Challenge | High | Engine Mount Frames |
| Fluctuating steel prices impacting component costs | Challenge | High | Roof Bow Components |
Evaluation of Drivers in China Structural Steel Components for Vehicles Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased vehicle production | Bumper Beams | China produced over 25 million vehicles in 2022, leading to a higher demand for structural components. |
| Growing adoption of high-strength steel | High-Strength Steel | High-strength steel is used in 70% of new vehicle models, improving safety features and performance. |
| Rising consumer preference for SUVs | SUVs | The production of SUVs accounted for 40% of total vehicle production in 2022, boosting demand for structural components. |
| Emphasis on safety regulations | Safety System Providers | Updated safety standards in 2023 require compliance for all new vehicle models, increasing demand for compliant components. |
| Expansion of electric vehicle production | Alloy Steel | Alloy steel components are increasingly used in electric vehicles for weight reduction, improving efficiency. |
The Structural Steel Components for Vehicles market in China is expanding as increased vehicle production, growing adoption of high-strength steel, and rising consumer preference for SUVs drive demand. In 2022, vehicle production reached over 25 million units, significantly boosting the need for structural components. High-strength steel is now integral to 70% of new vehicle models, enhancing overall safety. The SUV segment accounted for 40% of total vehicle production, reflecting shifting consumer trends. Updated safety standards in 2023 necessitate compliance, prompting manufacturers to invest in quality components.
Evaluation of Restraints in China Structural Steel Components for Vehicles Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions | Side Impact Beams | Manufacturers faced delays in sourcing materials, impacting production schedules and increasing costs. |
| High costs of high-strength steel | Bumper Beams | Fluctuating steel prices have raised the costs of essential components, affecting profitability. |
| Compliance with stringent safety standards | Engine Mount Frames | Meeting updated safety regulations requires substantial investment in testing and certification processes. |
| Limited availability of skilled labour | Roof Bow Components | The automotive sector employs over 5 million people, but shortages hinder production efficiency. |
| Market fluctuations affecting demand | High-Strength Steel | Changes in consumer preferences can lead to unpredictable demand for specific materials, complicating inventory management. |
China Structural Steel Components for Vehicles Market Challenges
Rising raw material prices present challenges for buyers and suppliers in the China Structural Steel Components for Vehicles market, driving production costs up by as much as 15% and squeezing profit margins for producers. Compliance with updated safety standards from the Ministry of Industry and Information Technology has led to delays in product launches, affecting manufacturers' ability to meet the increasing demand from domestic vehicle manufacturers. The need for advanced technology in high-strength steel production requires substantial capital investment, which may hinder smaller producers' competitiveness in a fast-evolving market. A shortage of skilled workers limits the adoption of modern manufacturing techniques, costing the automotive sector potential efficiency gains and innovation.
Trends in the China Structural Steel Components for Vehicles Market
Several trends are reshaping the China Structural Steel Components for Vehicles Market; the most important are set out below.
- Shift towards High-Strength Steel Usage: The Yangtze River Delta region is increasingly adopting high-strength steel for vehicle manufacturing, with 70% of new models incorporating it. This shift began in 2023, improving safety and performance.
- Growing SUV Production: Since 2022, the production of SUVs has risen significantly, accounting for 40% of total vehicle production. This trend reflects consumer preferences for larger vehicles and their safety features.
- Increased Focus on Safety Standards: In 2023, the National Standard GB 7251.1-2023 was updated, strengthening vehicle safety regulations. This change drives manufacturers to comply with stricter safety requirements.
- Expansion of Electric Vehicle Components: The demand for alloy steel components in electric vehicles has risen as manufacturers aim for weight reduction. In 2022, the automotive industry saw a notable increase in electric vehicle production.
Investment Opportunities in the China Structural Steel Components for Vehicles Market
The following opportunities in the China Structural Steel Components for Vehicles Market pair current demand with a clear way in.
- Investment in High-Strength Steel Production: With 70% of new vehicle models using high-strength steel, manufacturers should invest in production capabilities. The Yangtze River Delta region is a prime location for such investments, given its automotive manufacturing hub.
- Supply of Safety System Components: Safety system providers are increasingly integrating advanced safety features into vehicles. The growing emphasis on safety regulations creates a demand for compliance-ready components.
- Development of Lightweight Vehicle Structures: As the average weight reduction target for vehicles in China is 10% by 2025, suppliers should focus on lightweight materials. This trend is particularly relevant for SUV manufacturers.
- Expansion of Electric Vehicle Supply Chain: With the rise of electric vehicles, there is a growing need for alloy steel components. Collaborating with vehicle OEMs can facilitate entry into this expanding market.
Government Initiatives in the China Structural Steel Components for Vehicles Market
In 2023, the Ministry of Industry and Information Technology launched the 'Automotive Industry Development Plan', which promotes innovation and safety standards in vehicle manufacturing. This measure builds on the 'Green Vehicle Promotion Strategy' approved in 2022, aiming to increase electric vehicle market share by 20% by 2025. Together, these initiatives improve competitiveness and safety across the automotive sector, directly impacting structural steel component producers and buyers.
The 'Automotive Industry Development Plan' encourages vehicle OEMs to adopt new safety standards and technologies. The National Development and Reform Commission funds projects aimed at improving vehicle emissions, targeting a 30% reduction by 2025. This funding supports manufacturers in complying with evolving regulations, enabling them to enhance their product offerings and meet market demands.
Future Insight of the China Structural Steel Components for Vehicles Market
The China Structural Steel Components for Vehicles market will experience substantial changes by 2032, primarily driven by stricter safety regulations and a shift towards lightweight materials. The average weight reduction target for vehicles is set at 10% by 2025, accelerating the use of high-strength steel in new models. The National Development and Reform Commission's 'Automotive Industry Development Plan' will promote innovation and technology investment, boosting competitiveness. The increasing focus on electric vehicles will further drive demand for structural components that enhance efficiency and performance.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Component Type – Side Impact Beams Dominated, Bumper Beams Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, with a 46% revenue share in 2025, Side Impact Beams was the largest component type category. Side impact beams are vital for enhancing passenger safety during collisions, making them a top choice for vehicle manufacturers. Their adherence to strict safety regulations ensures a strong market position, particularly in regions like the Yangtze River Delta, where automotive production is concentrated. Bumper Beams are projected to grow fastest, at a CAGR of 5.8% during 2026–2032. Bumper beams are essential for absorbing impact energy in crashes, which is increasingly important as safety standards become more rigorous. The updated National Standard GB 7251.1-2023 is driving their rapid adoption in new vehicle models, ensuring their market share continues to grow. Suppliers should focus on developing advanced bumper beam technologies to meet evolving safety standards and capture greater market share.
By Steel Grade – High-Strength Steel Dominated and Is Expected to Record the Fastest Growth
High-Strength Steel took a 48% share of steel grade in 2025, more than any other category. High-strength steel holds the largest market share due to its ability to deliver superior performance and safety features in vehicles. Its application in 70% of new vehicle models highlights its fundamental role in meeting safety regulations. The same category is also set to grow fastest, at a CAGR of 5.8% during 2026–2032. High-strength steel is experiencing rapid growth as its usage expands across various vehicle models, ensuring its lead continues to widen. The automotive industry's commitment to a 10% weight reduction target by 2025 further fuels this trend. Buyers should focus on sourcing high-strength steel to comply with safety standards and optimise vehicle performance.
By Vehicle Segment – SUVs Dominated, Sedans Expected to Grow Fastest
In 2025, SUVs led the vehicle segment split with a 42% share. SUVs dominate the market due to a rising consumer preference for larger vehicles, leading to substantial production volumes. With SUVs accounting for 40% of total vehicle production in 2022, their popularity significantly boosts demand for structural components. Sedans are set to record the highest CAGR in this split, 5.2% over 2026–2032. Sedans exhibit stable demand, yet the increasing popularity of SUVs is reshaping market dynamics. As consumer preferences shift, sedans may experience renewed interest, particularly in urban areas, which could enhance their growth prospects. Suppliers must adapt their strategies to cater to the growing SUV segment while also exploring opportunities within the sedan market.
By End User – Vehicle OEMs Dominated, Safety System Providers Expected to Grow Fastest
The largest end user category in 2025 was Vehicle OEMs, with a 34% share of total revenue. Vehicle OEMs hold the largest market share as the primary manufacturers of vehicles that utilise structural steel components. Their central role in the automotive supply chain ensures a consistent demand for these critical parts, particularly in a booming market. The quickest growth will come from Safety System Providers, forecast to expand at a CAGR of 6.0% between 2026 and 2032. Safety system providers are experiencing rapid growth as they incorporate advanced safety features into vehicle designs, reflecting the industry's heightened focus on safety. This trend is likely to continue as regulatory requirements become more stringent. Suppliers should strengthen collaborations with safety system providers to align with industry trends and capitalise on emerging opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Structural Steel Components for Vehicles Market Outlook
- Market Size of China Structural Steel Components for Vehicles Market, 2025
- Forecast of China Structural Steel Components for Vehicles Market, 2032
- Historical Data and Forecast of China Structural Steel Components for Vehicles Revenues & Volume for the Period 2022 - 2032F
- China Structural Steel Components for Vehicles Market Trend Evolution
- China Structural Steel Components for Vehicles Market Drivers and Challenges
- China Structural Steel Components for Vehicles Price Trends
- China Structural Steel Components for Vehicles Porter's Five Forces
- China Structural Steel Components for Vehicles Industry Life Cycle
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Side Impact Beams for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Bumper Beams for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Engine Mount Frames for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Roof Bow Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Steel Grade for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By High-Strength Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Mild Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Alloy Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Boron Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Vehicle Segment for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By SUVs for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Sedans for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Trucks for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Hatchbacks for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Safety System Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Vehicle OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Powertrain Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Steel Components for Vehicles Market Revenues & Volume By Body Structure Suppliers for the Period 2022 - 2032F
- China Structural Steel Components for Vehicles Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Steel Grade
- Market Opportunity Assessment By Vehicle Segment
- Market Opportunity Assessment By End User
- China Structural Steel Components for Vehicles Top Companies Market Share
- China Structural Steel Components for Vehicles Competitive Benchmarking By Technical and Operational Parameters
- China Structural Steel Components for Vehicles Company Profiles
- China Structural Steel Components for Vehicles Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Component Type
- Side Impact Beams
- Bumper Beams
- Engine Mount Frames
- Roof Bow Components
By Steel Grade
- High-Strength Steel
- Mild Steel
- Alloy Steel
- Boron Steel
By Vehicle Segment
- SUVs
- Sedans
- Trucks
- Hatchbacks
By End User
- Safety System Providers
- Vehicle OEMs
- Powertrain Integrators
- Body Structure Suppliers































