China Surface Engineering Market Size & Growth Rate
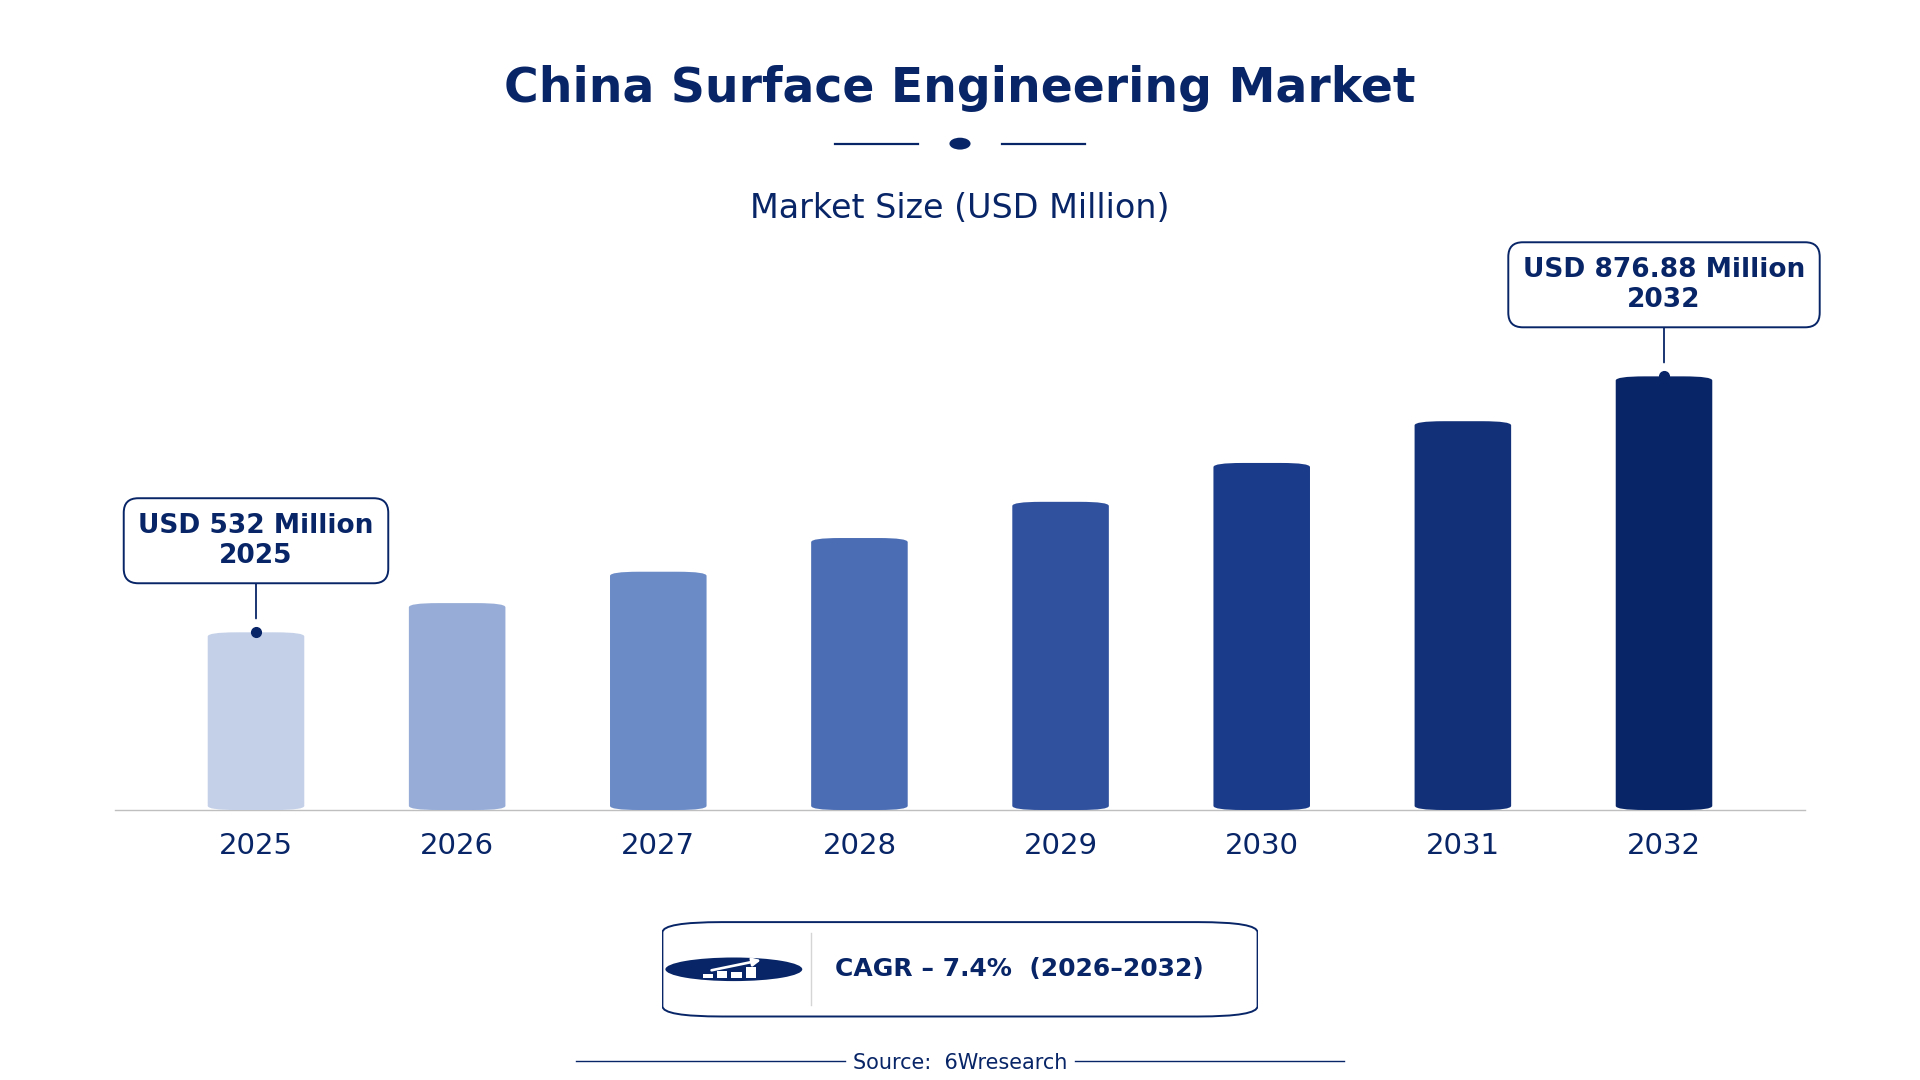
According to 6Wresearch internal database and industry insights, the China Surface Engineering Market was valued at USD 532.0 million in 2025 and is projected to reach USD 876.88 million by 2032, growing at a CAGR of approximately 7.4% during 2026–2032.
China Surface Engineering Market Highlights
| Report Metric | Details |
| Report Name | China Surface Engineering Market |
| Market Size 2025 | USD 532.0 million |
| Market Size 2032 | USD 876.88 million |
| Absolute Growth 2025–2032 | USD 344.88 million |
| CAGR 2026–2032 | 7.4% |
| Peak Annual Growth | 10.1% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Process Type, 2025 | Electroplating (45% share) |
| Leading Engineering Approach, 2025 | Physical Coating (42% share) |
| Leading Treated Material, 2025 | Steel/Alloys (42% share) |
| Leading End User, 2025 | Auto Component Manufacturers (53% share) |
| Fastest-Growing Process Type | Laser Cladding (9.7% CAGR) |
| Fastest-Growing Engineering Approach | Subsurface Modification (8.8% CAGR) |
| Fastest-Growing Treated Material | Semiconductors (9.8% CAGR) |
| Fastest-Growing End User | Microelectronics Producers (8.9% CAGR) |
| Growing Sector | Automotive |
| Key End Users | Auto Component Manufacturers, Aerospace OEMs, Microelectronics Producers, Industrial Tool Manufacturers |
China Surface Engineering Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
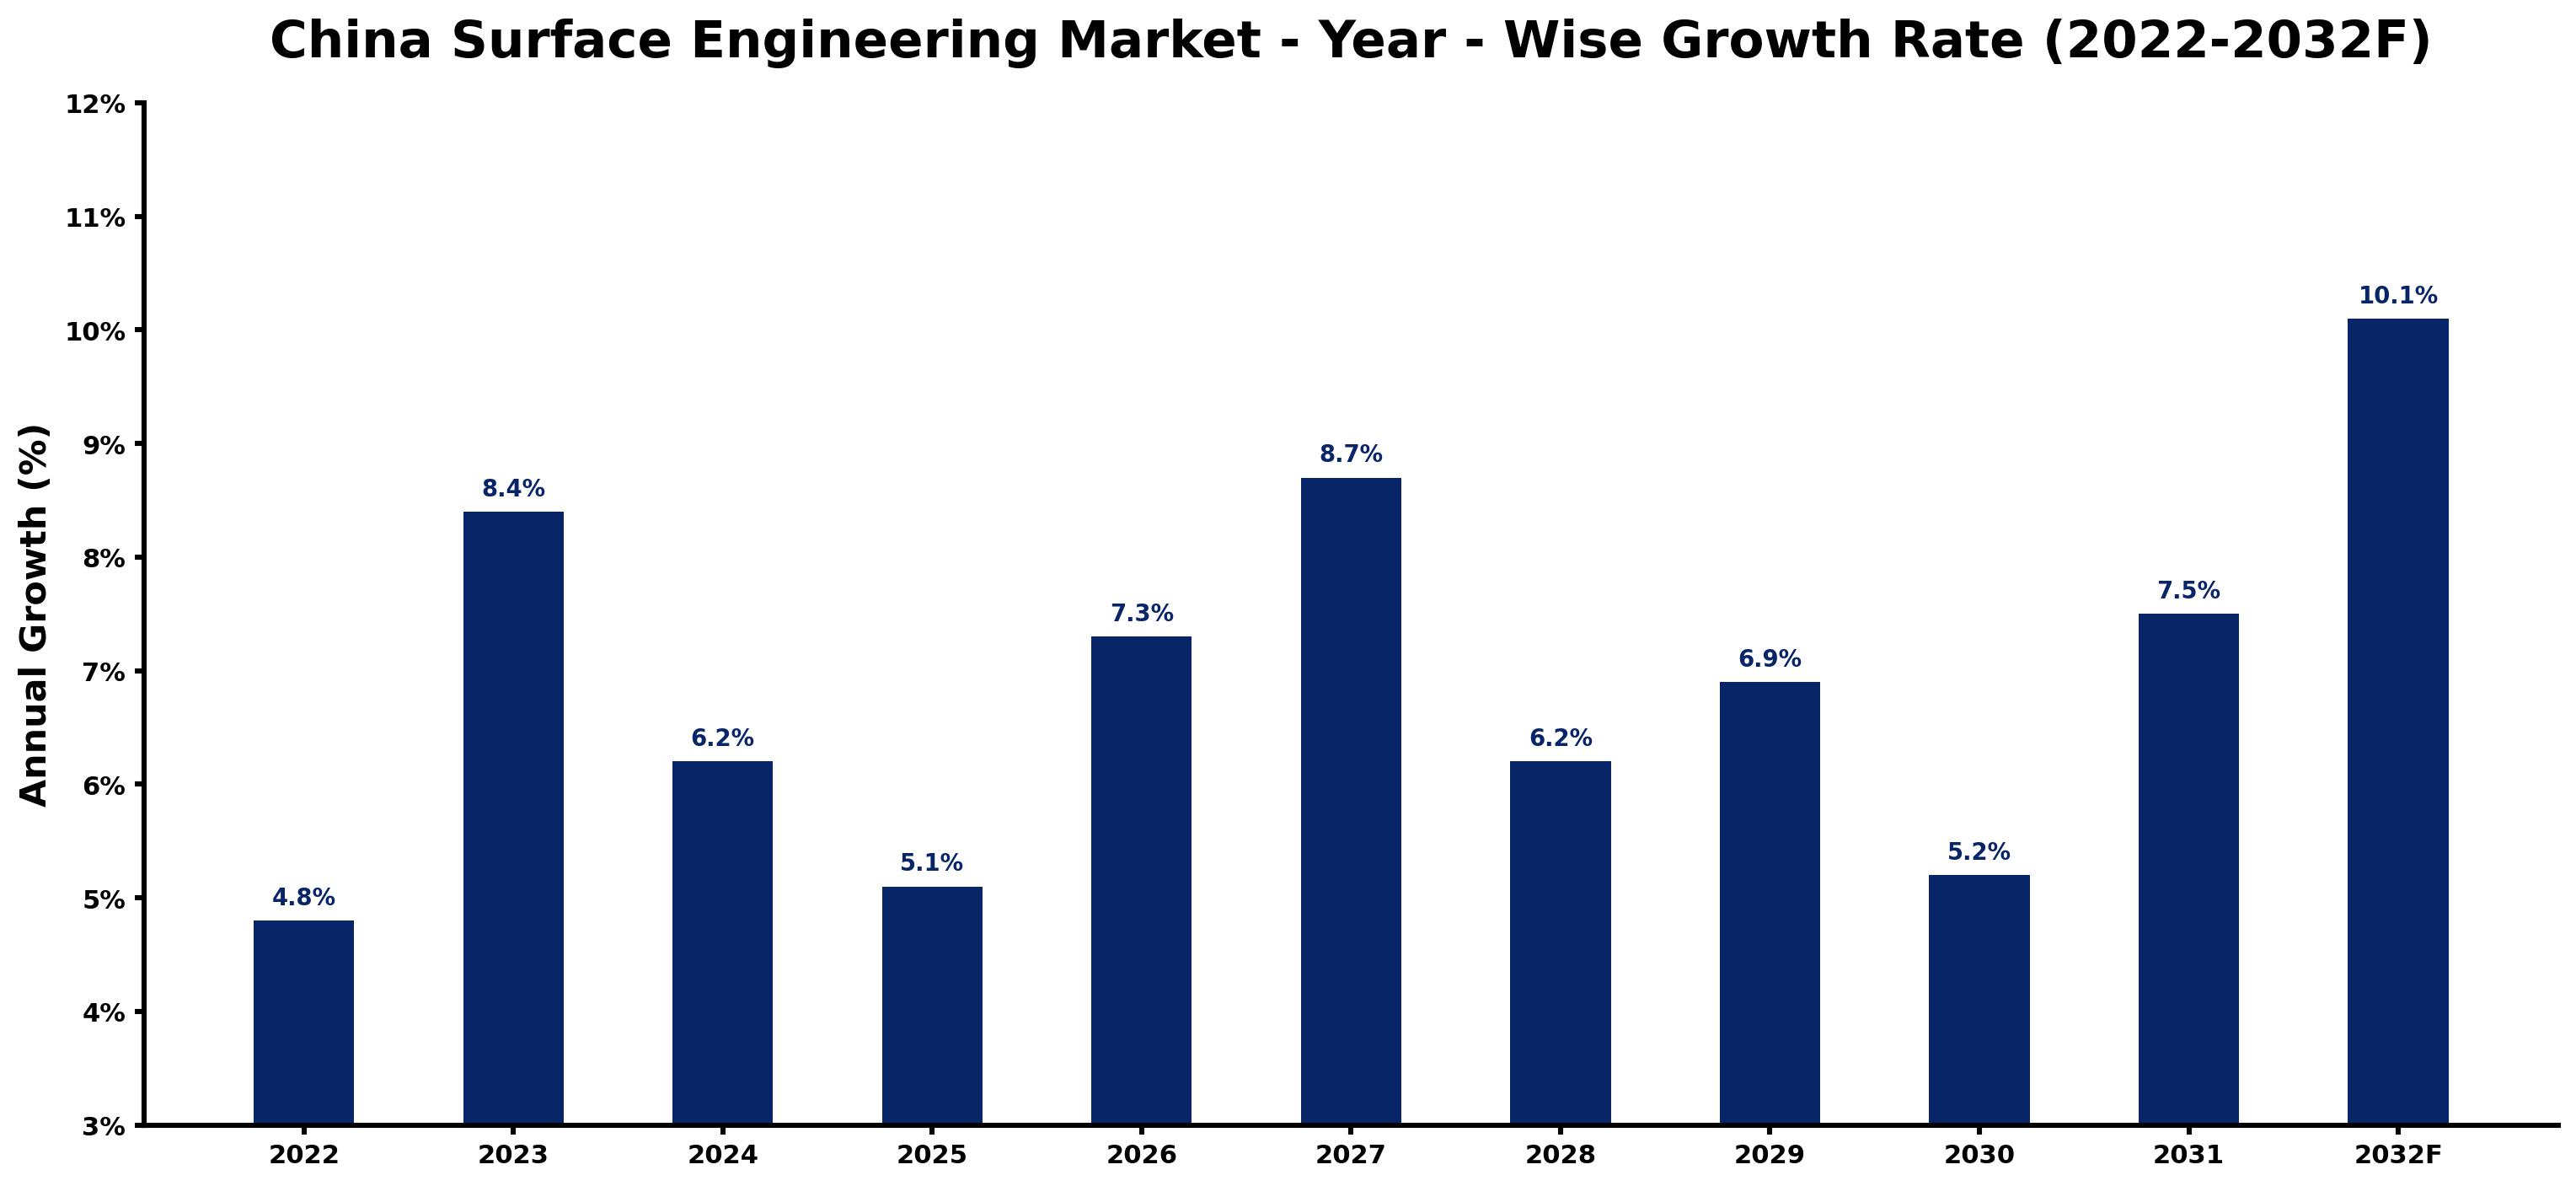
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.8 | The market showed steady demand driven by existing surface engineering applications across various sectors. |
| 2023 | 8.4 | Growth accelerated due to increased investments in the aerospace sector, boosting demand for surface engineering services. |
| 2024 | 6.2 | Demand slowed as manufacturers adjusted to supply chain challenges in the automotive industry. |
| 2025 | 5.1 | Growth continued to slow as the automotive sector faced production constraints and rising costs. |
| 2026 | 7.3 | The market is expected to grow faster as new technologies are adopted in manufacturing processes. |
| 2027 | 8.7 | Demand is projected to rise with increased production in the automotive industry, particularly for durable components. |
| 2028 | 6.2 | Growth is anticipated to slow as the National Standard for Surface Engineering begins to influence market dynamics. |
| 2029 | 6.9 | The market will see a resurgence as new applications in microelectronics emerge, driving demand for advanced coatings. |
| 2030 | 5.2 | Growth is projected to slow as competition intensifies among surface engineering firms in the automotive sector. |
| 2031 | 7.5 | Demand is expected to rise with advancements in surface treatment technologies for automotive applications. |
| 2032 | 10.1 | The market is projected to peak as investments in aerospace drive further growth in surface engineering. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Surface Engineering Market Synopsis
Surface Engineering in China includes various processes that improve material properties, such as wear and corrosion resistance. Techniques like thermal spraying and electroplating are prevalent in industries including aerospace and automotive. The China Surface Engineering Market is growing rapidly, driven by strong demand from domestic manufacturers and continuous investments in advanced manufacturing technologies. The automotive sector, which produced over 26 million vehicles in 2022, is a key contributor to this expansion. Furthermore, the semiconductor market's value of $150 billion in 2022 further stimulates the need for surface engineering services.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing investments in advanced manufacturing technologies | Driver | High | Thermal Spraying |
| Increased production of durable automotive components | Driver | High | Auto Component Manufacturers |
| Rising demand for wear-resistant coatings in heavy machinery | Opportunity | Medium | Industrial Tools |
| Expanding semiconductor market requiring advanced surface treatments | Opportunity | High | Semiconductors |
| High costs associated with advanced surface engineering technologies | Restraint | High | Laser Cladding |
| Supply chain disruptions affecting material availability | Restraint | Medium | Electroplating |
| Approval delays for new surface engineering technologies | Challenge | Medium | Physical Coating |
| Intense competition among surface engineering firms | Challenge | High | Subsurface Modification |
Evaluation of Drivers in China Surface Engineering Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investment in advanced manufacturing technologies | Automotive Parts | This investment drives demand for durable components, with the automotive sector producing over 26 million vehicles in 2022. |
| Growing aerospace industry | Aerospace OEMs | The aerospace sector is projected to expand, increasing the need for surface engineering services to enhance aircraft safety and performance. |
| Rising demand for semiconductor manufacturing | Semiconductors | The semiconductor market's value reached $150 billion in 2022, boosting the need for ion implantation technologies. |
| Technological advancements in surface treatment processes | Laser Cladding | Innovations in laser cladding attract investment, increasing overall demand for surface engineering solutions. |
| Expansion of microelectronics production | Microelectronics Producers | Shenzhen's growth as a microelectronics hub drives demand for advanced surface engineering solutions. |
Expansion of the Surface Engineering market in China is backed by increased investment in advanced manufacturing technologies, particularly in the automotive sector. The automotive industry produced over 26 million vehicles in 2022, driving demand for durable components. The semiconductor market's value reached $150 billion, boosting the need for ion implantation technologies. The growing aerospace industry further fuels demand for surface engineering services, improving safety and performance in aircraft. Technological advancements in surface treatment processes, such as laser cladding, are attracting investment and increasing overall demand for surface engineering solutions.
Evaluation of Restraints in China Surface Engineering Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with advanced surface engineering technologies | Laser Cladding | These costs can deter smaller firms from adopting new technologies, limiting market growth opportunities. |
| Supply chain disruptions affecting material availability | Electroplating | Disruptions can delay production schedules, impacting the ability to meet rising demand for coatings. |
| Approval delays for new surface engineering technologies | Physical Coating | Such delays can slow the introduction of new solutions, hindering competitiveness in the market. |
| Limited skilled workforce in surface engineering | Subsurface Modification | A shortage of qualified personnel can restrict operational capacity and efficiency in production processes. |
| Regulatory compliance costs for surface treatment processes | Thermal Spraying | Compliance can increase operational expenses by approximately 15%, affecting profitability for manufacturers in the sector. |
China Surface Engineering Market Challenges
In China, the surface engineering market encounters a skills shortage, with over 30% of workers lacking proficiency in advanced surface treatment techniques, leading to project delays for manufacturers. Regulatory hurdles emerge from the National Standard for Surface Engineering, which can extend approval processes by up to six months, delaying product launches for firms. Supply chain disruptions arise from dependence on imported materials, causing production costs to rise by 15% for producers during global shortages. Fierce competition among local suppliers drives prices down, squeezing profit margins and restricting their capacity to invest in technological advancements.
Trends in the China Surface Engineering Market
Four trends stand out in the China Surface Engineering Market.
- Shift towards Advanced Coating Technologies: The trend towards advanced coating technologies began in 2021, driven by the need for improved durability. The National Standard for Surface Engineering (GB/T 14957-2018) governs these advancements, ensuring quality and safety in coatings.
- Transition from Traditional to Innovative Surface Treatments: Since 2022, there has been a noticeable shift towards innovative surface treatments in the automotive sector. The automotive industry is expected to invest heavily in surface treatment technologies by 2025, targeting improved efficiency and performance.
- Emergence of Microelectronics as a Key Sector: The microelectronics sector has gained prominence since 2022, significantly impacting surface engineering demand. Shenzhen is a key region for microelectronics, with numerous producers relying on surface engineering to enhance product performance.
- Prioritisation of Sustainability in Surface Engineering: In 2023, sustainability became a focal point for surface engineering practices. The Ministry of Science and Technology initiated the 'Surface Coating Innovation Initiative' to support research in eco-friendly coatings, aligning with industry trends.
Investment Opportunities in the China Surface Engineering Market
Some of the investment opportunities in the China Surface Engineering Market are mentioned below.
- Investment gap in surface treatment technologies: With the automotive sector expected to invest heavily by 2025, there is a clear opportunity for suppliers of advanced surface treatment technologies. Collaborating with auto component manufacturers can facilitate market entry and growth.
- Demand for wear-resistant coatings in heavy machinery: The need for wear-resistant coatings presents an opportunity for suppliers to provide thermal spraying solutions. Targeting industrial tool manufacturers can enhance market presence and profitability.
- Expansion of the semiconductor market: The semiconductor market's growth offers opportunities for suppliers of ion implantation technologies. Engaging with microelectronics producers in Shenzhen can facilitate successful market entry and expansion.
- Aerospace industry investments: With the aerospace sector projected to grow, there is a demand for surface engineering services. Establishing partnerships with aerospace OEMs can provide a strategic entry point for suppliers.
Government Initiatives in the China Surface Engineering Market
The Ministry of Industry and Information Technology oversees the implementation of the 'Advanced Manufacturing 2025' plan, launched in 2021 with a budget of $500 million. This initiative aims to improve surface engineering capabilities, benefiting manufacturers by enhancing their production processes and technology adoption. Additionally, the National Development and Reform Commission approved the 'Surface Engineering Technology Development Program' in 2022 to promote innovation in surface treatment technologies, supporting research and development efforts across the sector.
The State Administration for Market Regulation manages the updated 'National Standard for Surface Engineering', revised in 2022 to enhance quality control measures for coatings. This regulation ensures that producers meet safety and quality standards, benefiting both manufacturers and consumers. Furthermore, the Ministry of Science and Technology funds various initiatives to support surface engineering capabilities, including grants for research projects and technology upgrades, aiming to boost the industry's overall competitiveness and innovation.
Future Insight of the China Surface Engineering Market
The surface engineering market in China is set for significant evolution by 2032, driven by technological advancements and increased investments in surface treatment processes. The automotive sector is expected to allocate over $10 billion to surface engineering technologies by 2025, improving component durability. The government's initiative launched in 2021 aims to enhance surface engineering capabilities, raising quality standards across the sector. As Shenzhen strengthens its position as a microelectronics centre, demand for innovative surface engineering solutions will expand, creating opportunities for both buyers and suppliers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Process Type – Electroplating Dominated, Laser Cladding Expected to Grow Fastest
According to Sumit Sagar, AM at 6Wresearch, in 2025, Electroplating led the process type split with a 45% share. Electroplating holds the largest share due to its widespread application in corrosion protection and aesthetic finishes across various industries, particularly in automotive and electronics. This method is essential for manufacturers seeking reliable surface treatments where durability is a key requirement. Laser Cladding is set to record the highest CAGR in this split, 9.7% over 2026–2032. Laser Cladding is experiencing rapid growth as it is increasingly applied for repairing and enhancing industrial tools, driven by the rising demand for durable components in manufacturing. This trend suggests that electroplating's lead will continue to widen as it remains a staple in various applications. Suppliers should focus on advancing laser cladding technologies to capture the growing market share.
By Engineering Approach – Physical Coating Dominated, Subsurface Modification Expected to Grow Fastest
Physical Coating held a 42% share of the China Surface Engineering Market by engineering approach in 2025. Physical Coating dominates the market owing to its critical role in improving surface characteristics across multiple sectors, including automotive and aerospace. Its effectiveness in enhancing wear and corrosion resistance makes it the preferred choice among manufacturers. Subsurface Modification is projected to grow fastest, at a CAGR of 8.8% during 2026–2032. Subsurface Modification is the fastest-growing approach, propelled by the increasing demand for enhanced material properties in high-performance applications, especially in aerospace and automotive. This growth indicates a shift towards more sophisticated engineering solutions, further solidifying the position of physical coating. Buyers should consider investing in subsurface modification technologies to enhance the performance of their products.
By Treated Material – Steel/Alloys Dominated, Semiconductors Expected to Grow Fastest
With a 42% revenue share in 2025, Steel/Alloys was the largest treated material category. Steel/Alloys command the largest share because of their essential role in automotive and construction applications, where enhanced strength and durability are crucial. Their extensive use in heavy-duty environments ensures their dominant market position. Over 2026–2032, Semiconductors are expected to post the fastest growth, at a CAGR of 9.8%. Semiconductors are the fastest-growing segment, primarily due to their vital importance in the electronics industry, particularly in microchip production. The booming semiconductor market in China, valued at $150 billion in 2022, significantly contributes to this growth, indicating a promising future for surface engineering in this area. Suppliers should develop surface engineering solutions tailored for semiconductor applications to seize emerging opportunities.
By End User – Auto Component Manufacturers Dominated, Microelectronics Producers Expected to Grow Fastest
The largest end user category in 2025 was Auto Component Manufacturers, with a 53% share of total revenue. Auto Component Manufacturers represent the largest share as they are major consumers of surface engineering services, prioritising component durability and performance. The automotive sector's massive production scale reinforces this sub-segment's dominance in the market. The quickest growth will come from Microelectronics Producers, forecast to expand at a CAGR of 8.9% between 2026 and 2032. Microelectronics Producers are the fastest-growing end user group, driven by the increasing need for advanced electronic components in a rapidly evolving technology landscape. This trend indicates a rising demand for high-quality surface treatments, suggesting that auto component manufacturers will maintain their lead. Suppliers must adapt their offerings to meet the specific needs of microelectronics producers to remain competitive in this expanding market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Surface Engineering Market Outlook
- Market Size of China Surface Engineering Market, 2025
- Forecast of China Surface Engineering Market, 2032
- Historical Data and Forecast of China Surface Engineering Revenues & Volume for the Period 2022 - 2032F
- China Surface Engineering Market Trend Evolution
- China Surface Engineering Market Drivers and Challenges
- China Surface Engineering Price Trends
- China Surface Engineering Porter's Five Forces
- China Surface Engineering Industry Life Cycle
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Process Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Thermal Spraying for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Ion Implantation for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Electroplating for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Laser Cladding for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Engineering Approach for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Physical Coating for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Subsurface Modification for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Metal Deposition for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Fusion Surface Treatment for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Treated Material for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Steel/Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Semiconductors for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Automotive Parts for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Industrial Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Aerospace OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Microelectronics Producers for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Auto Component Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Engineering Market Revenues & Volume By Tooling Companies for the Period 2022 - 2032F
- China Surface Engineering Import Export Trade Statistics
- Market Opportunity Assessment By Process Type
- Market Opportunity Assessment By Engineering Approach
- Market Opportunity Assessment By Treated Material
- Market Opportunity Assessment By End User
- China Surface Engineering Top Companies Market Share
- China Surface Engineering Competitive Benchmarking By Technical and Operational Parameters
- China Surface Engineering Company Profiles
- China Surface Engineering Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Process Type
- Thermal Spraying
- Ion Implantation
- Electroplating
- Laser Cladding
By Engineering Approach
- Physical Coating
- Subsurface Modification
- Metal Deposition
- Fusion Surface Treatment
By Treated Material
- Steel/Alloys
- Semiconductors
- Automotive Parts
- Industrial Tools
By End User
- Aerospace OEMs
- Microelectronics Producers
- Auto Component Manufacturers
- Tooling Companies































