China Surface Finishing Market Size & Growth Rate
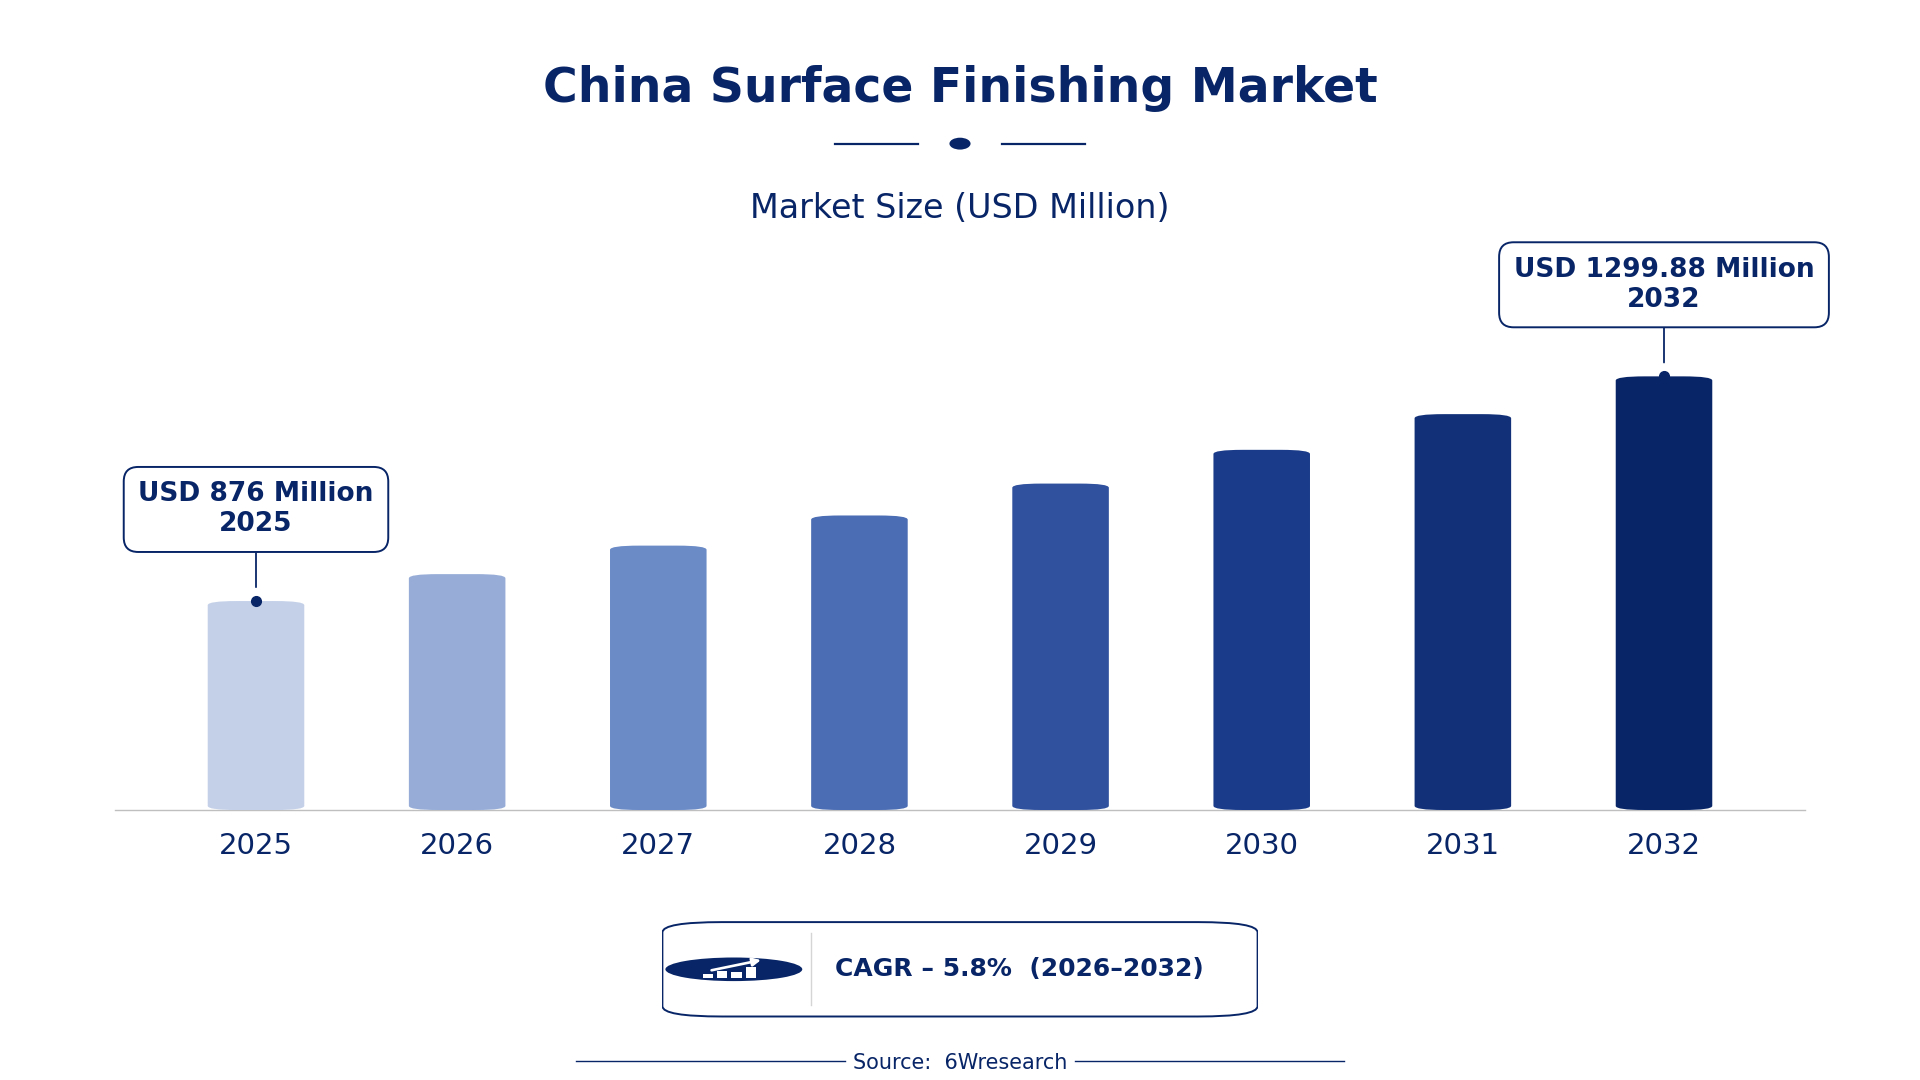
According to 6Wresearch internal database and industry insights, the China Surface Finishing Market was valued at USD 876.0 million in 2025 and is projected to reach USD 1,299.88 million by 2032, growing at a CAGR of approximately 5.8% during 2026–2032.
China Surface Finishing Market Highlights
| Report Metric | Details |
| Report Name | China Surface Finishing Market |
| Market Size 2025 | USD 876.0 million |
| Market Size 2032 | USD 1,299.88 million |
| Absolute Growth 2025–2032 | USD 423.88 million |
| CAGR 2026–2032 | 5.8% |
| Peak Annual Growth | 8.0% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Finishing Type, 2025 | Plating (36% share) |
| Leading Technique Used, 2025 | Electroplating (48% share) |
| Leading Surface Material, 2025 | Metal (42% share) |
| Leading End User, 2025 | Automotive Parts Manufacturers (38% share) |
| Fastest-Growing Finishing Type | Anodizing (7.9% CAGR) |
| Fastest-Growing Technique Used | Electrochemical (8.5% CAGR) |
| Fastest-Growing Surface Material | Aluminum (7.1% CAGR) |
| Fastest-Growing End User | Aerospace Component Suppliers (6.9% CAGR) |
| Growing Sector | Automotive Parts Manufacturing |
| Key End Users | Automotive Parts Manufacturers, Aerospace Component Suppliers, Machinery OEMs, Decorative Metal Fabricators |
China Surface Finishing Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
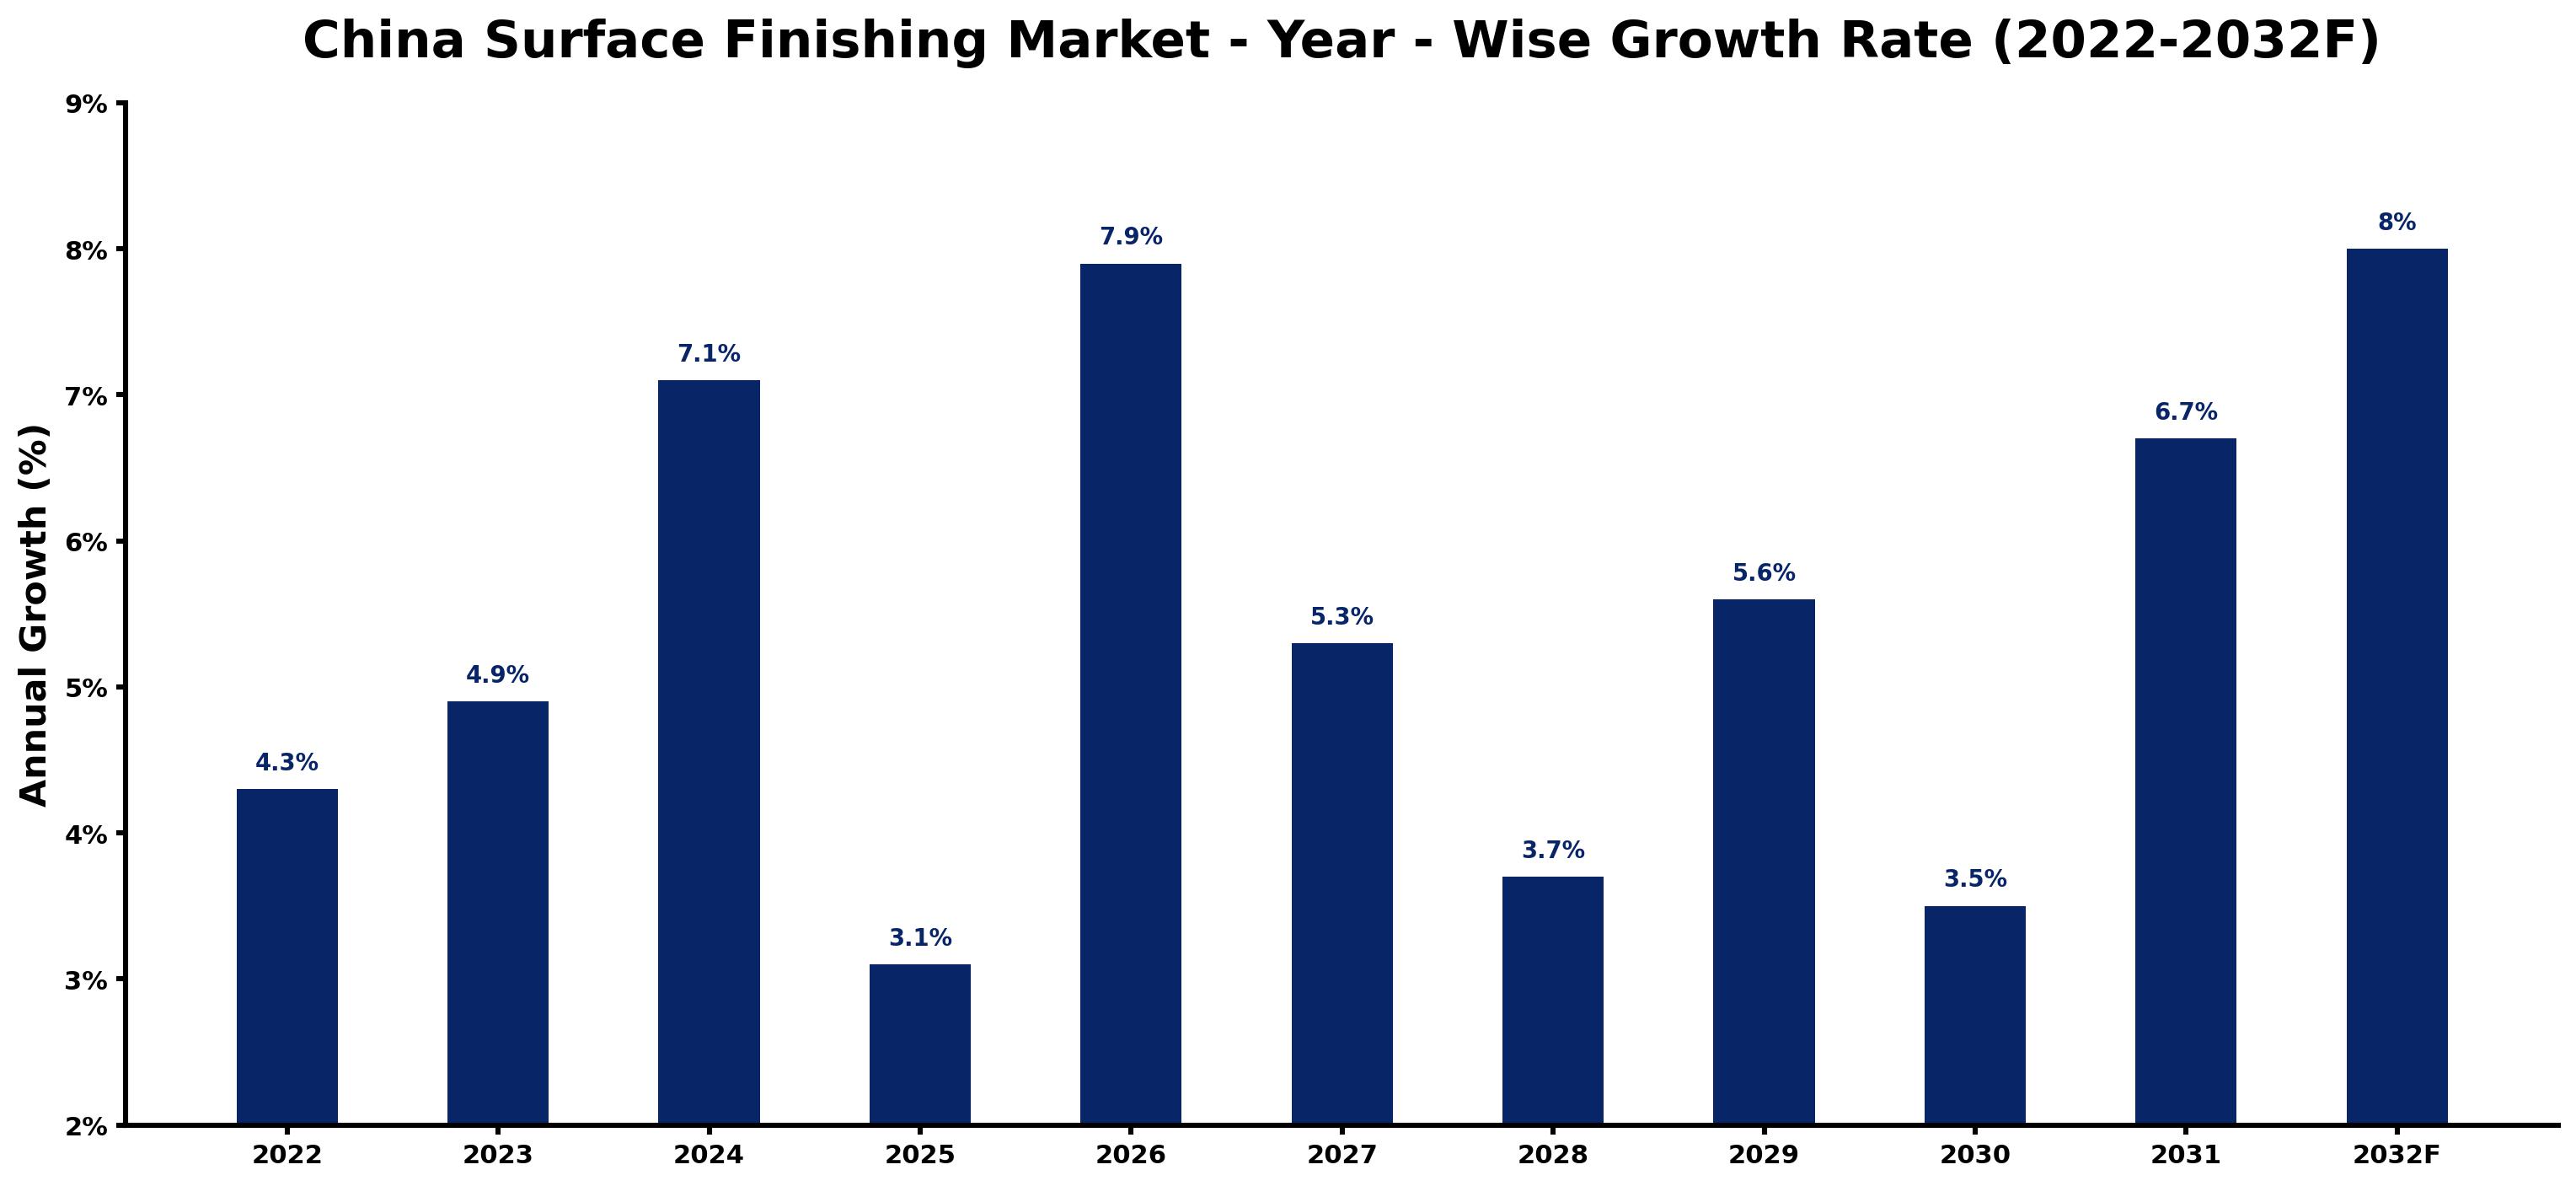
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.3 | The automotive sector maintained strong demand for surface finishing services throughout the year. |
| 2023 | 4.9 | Increased production of aluminum components drove higher demand for surface finishing processes. |
| 2024 | 7.1 | The aerospace industry expanded, requiring more surface finishing services for aircraft components. |
| 2025 | 3.1 | Growth slowed as manufacturers adjusted to the updated Product Quality Law affecting production. |
| 2026 | 7.9 | The introduction of advanced manufacturing technologies is projected to boost demand for surface finishing services. |
| 2027 | 5.3 | Demand from automotive parts manufacturers is projected to remain strong, sustaining market growth despite a slowdown. |
| 2028 | 3.7 | Growth is expected to slow as companies face challenges in meeting ISO 9001 certification standards. |
| 2029 | 5.6 | Rising demand from aerospace component suppliers will contribute to increased surface finishing activities. |
| 2030 | 3.5 | Market growth is expected to slow as competition intensifies among surface finishing providers. |
| 2031 | 6.7 | A resurgence in automotive production will lead to heightened demand for surface finishing services. |
| 2032 | 8.0 | The aerospace sector is projected to require 30% more surface finishing services. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Surface Finishing Market Synopsis
Surface Finishing in China encompasses various processes that improve the surface properties of metals, including polishing and anodizing. The market is growing, with the automotive sector accounting for approximately 40% of demand in 2022. This growth is driven by increasing vehicle production and advancements in manufacturing technologies. With over 1,000 registered companies, the industry is expanding due to strong domestic manufacturing and export demands. The aerospace sector is also contributing to the rising need for surface finishing services.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand from automotive parts manufacturers for enhanced vehicle components | Driver | High | Automotive Parts Manufacturers |
| Increased production of aluminum components for lightweight applications | Driver | High | Aluminum |
| Rising need for environmentally friendly surface finishing technologies | Opportunity | Medium | Electrochemical |
| Expansion of aerospace component suppliers requiring advanced finishing processes | Opportunity | High | Aerospace Component Suppliers |
| Challenges in meeting stricter quality standards imposed by regulations | Restraint | High | Plating |
| Competition among surface finishing companies leading to pricing pressures | Restraint | Medium | Plating |
| High costs associated with upgrading equipment to meet new standards | Challenge | High | Plating |
| Delays in obtaining necessary certifications for new technologies | Challenge | Medium | Plating |
Evaluation of Drivers in China Surface Finishing Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production of vehicles requiring surface finishing services | Automotive Parts Manufacturers | Approximately 20 million vehicles are produced annually in China, driving demand for surface finishing. |
| Rising demand for lightweight aluminum components | Aluminum | The annual production of aluminum components reached 5 million tons in 2023, increasing finishing needs. |
| Expansion of aerospace industry necessitating advanced surface finishing | Aerospace Component Suppliers | The aerospace sector is projected to require 30% more surface finishing services by 2025. |
| Adoption of ISO 9001 certification among surface finishing companies | Plating | This certification is increasingly sought after for quality assurance, improving competitiveness. |
| Government investment in advanced manufacturing technologies | Plating | The government allocated 500 million CNY in 2023 to support advancements in manufacturing, including surface finishing. |
Market growth for Surface Finishing in China is underpinned by demand from automotive parts manufacturers and aerospace component suppliers. The automotive sector, producing over 20 million vehicles annually, drives substantial demand for surface finishing services. In 2023, the production of aluminum components reached 5 million tons, further increasing the need for finishing processes. The aerospace industry is expected to require 30% more surface finishing services by 2025, necessitating advanced techniques. Investment in advanced manufacturing technologies will improve the industry’s capabilities and competitiveness.
Evaluation of Restraints in China Surface Finishing Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Stricter quality standards imposed by regulations | Plating | The updated Product Quality Law in 2023 enforces stricter compliance, increasing operational costs for producers. |
| Intense competition leading to pricing pressures | Plating | With over 1,000 registered companies, competition has driven down prices, affecting profitability. |
| High costs associated with upgrading equipment to meet new standards | Plating | Investment in new technologies is necessary to comply with evolving regulations, impacting cash flow. |
| Delays in obtaining necessary certifications for new technologies | Plating | The lengthy approval process for new surface finishing technologies can hinder timely market entry. |
| Challenges in sourcing high-quality raw materials | Plating | Fluctuations in raw material availability can disrupt production schedules and increase costs. |
China Surface Finishing Market Challenges
In China, regulatory challenges arise from the national standard GB/T 16583-2008, complicating compliance and delaying project approvals for producers. These delays can extend project timelines by up to three months, affecting over 1,000 registered surface finishing companies' ability to meet market demands. Rising operational costs, driven by a government investment of 500 million CNY in advanced manufacturing technologies, can increase service prices for buyers, particularly in the automotive sector, which accounts for 40% of demand. Supply chain disruptions occur due to the concentration of surface finishing operations in Guangdong and Jiangsu provinces, potentially delaying service delivery for importers. Technological advancements lag behind global standards, limiting the competitiveness of local producers in the aerospace industry, which requires 30% more surface finishing services by 2025.
Trends in the China Surface Finishing Market
Several trends are reshaping the China Surface Finishing Market; the most important are set out below.
- Shift towards Environmentally Friendly Surface Finishing: Automotive parts manufacturers are increasingly adopting environmentally friendly surface finishing technologies. In 2021, the 'Green Manufacturing' program was initiated to promote sustainable practices, resulting in a 20% increase in eco-friendly processes.
- Transition from Traditional to Advanced Finishing Techniques: Aerospace component suppliers are moving towards advanced surface finishing techniques. The '2022 Surface Finishing Technology Upgrade Plan' aims to improve efficiency, with a projected 30% increase in adoption by 2025.
- Emergence of Automated Surface Finishing Solutions: The market is seeing a rise in automated surface finishing solutions. In 2023, the installed base of surface finishing equipment reached 200,000 units, reflecting a shift towards automation.
- Prioritisation of Quality Assurance Standards: Surface finishing companies are increasingly prioritising ISO 9001 certification for quality assurance. This trend is evident as over 50% of companies sought certification in 2023.
Investment Opportunities in the China Surface Finishing Market
Investors looking at the China Surface Finishing Market should consider the following areas.
- Investment in Eco-Friendly Surface Finishing Technologies: There is a growing demand for eco-friendly surface finishing technologies, with an estimated market gap of 200 million CNY. Automotive parts manufacturers are seeking sustainable solutions to improve their production processes.
- Supply of Advanced Surface Finishing Equipment: The installed base of surface finishing equipment is projected to reach 300,000 units by 2030, indicating a strong investment opportunity for suppliers. Companies in Guangdong province are actively seeking modern equipment.
- Expansion of Aerospace Surface Finishing Services: With the aerospace industry projected to require 30% more services by 2025, there is a significant opportunity for finishing service providers. Suppliers can enter this market through partnerships with aerospace component suppliers.
- Development of Certification Programs for New Technologies: There is a need for certification programs for new surface finishing technologies, with a potential market of 150 million CNY. Collaborations with regulatory agencies can facilitate access to this growing sector.
Government Initiatives in the China Surface Finishing Market
The 'Made in China 2025' strategy, introduced in 2020, emphasises advancements in surface finishing technologies. This initiative aims to improve manufacturing quality and promote sustainable practices across the industry. In 2021, the Ministry of Industry and Information Technology initiated the 'Green Manufacturing' program to encourage environmentally friendly surface finishing technologies. This program has led to increased investments in sustainable practices, improving the industry's overall performance.
In 2023, the State Administration for Market Regulation updated the 'Product Quality Law' to enforce stricter quality standards for surface finishing processes. This law ensures that producers meet higher compliance levels, impacting production practices and costs.
Future Insight of the China Surface Finishing Market
By 2032, buyers and suppliers in the China surface finishing market can expect substantial advancements in service quality and efficiency, driven by the 'Made in China 2025' initiative aimed at elevating manufacturing standards. The increasing adoption of ISO 9001 certification will ensure higher quality assurance among surface finishing companies. With 200,000 units of surface finishing equipment in operation, upgrades will enable faster processing times. The aerospace industry's anticipated growth will further stimulate demand for high-quality surface finishing, encouraging local producers to improve their capabilities.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Finishing Type – Plating Dominated, Anodizing Expected to Grow Fastest
According to Sumit Sagar, AM at 6Wresearch, Plating took a 36% share of finishing type in 2025, more than any other category. Plating holds the largest share in the China Surface Finishing Market due to its essential role in coating metals, enhancing both appearance and corrosion resistance. Its importance is underscored by its application in the production of over 20 million vehicles annually, particularly benefiting automotive manufacturers. Over 2026–2032, Anodizing is expected to post the fastest growth, at a CAGR of 7.9%. Anodizing is experiencing rapid growth as it provides essential corrosion resistance and aesthetic appeal to aluminum surfaces, especially in the automotive and aerospace sectors. The aerospace industry's projected 30% increase in demand for surface finishing services by 2025 is a significant factor propelling this trend. Suppliers should enhance anodizing capabilities to meet the increasing demands of the aerospace sector.
By Technique Used – Electroplating Dominated, Electrochemical Expected to Grow Fastest
Electroplating accounted for a 48% market share by technique used in 2025. Electroplating commands a substantial share in the market as it is extensively used to deposit a layer of metal onto surfaces, enhancing durability and aesthetics. This technique is particularly vital for automotive components, where high-quality finishes are crucial. The quickest growth will come from Electrochemical, forecast to expand at a CAGR of 8.5% between 2026 and 2032. Electrochemical techniques are rapidly gaining traction due to their versatility in processes such as anodizing and plating, which are increasingly in demand. The government's investment in advanced manufacturing technologies is expected to further accelerate the adoption of these techniques. Buyers should seek suppliers that offer advanced electrochemical techniques to ensure superior surface finishes.
By Surface Material – Metal Dominated, Aluminum Expected to Grow Fastest
In 2025, Metal led the surface material split with a 42% share. Metal is the primary material in the China Surface Finishing Market, accounting for the largest share as it is the main substrate for finishing processes. The extensive use of metals in manufacturing across various industries solidifies its dominant position. Aluminum is set to record the highest CAGR in this split, 7.1% over 2026–2032. Aluminum is the fastest-growing segment due to its lightweight properties and increasing demand in automotive and aerospace applications. The annual production of aluminum components in China reached 5 million tons in 2023, highlighting its rising importance. Suppliers should prioritise aluminium finishing solutions to capture the growing demand in lightweight applications.
By End User – Automotive Parts Manufacturers Dominated, Aerospace Component Suppliers Expected to Grow Fastest
The largest end user category in 2025 was Automotive Parts Manufacturers, with a 38% share of total revenue. Automotive Parts Manufacturers represent the largest share in the market as they are the primary users of surface finishing to enhance vehicle components. With over 20 million vehicles produced annually, the automotive sector's demand for surface finishing remains strong. Aerospace Component Suppliers are projected to grow fastest, at a CAGR of 6.9% during 2026–2032. Aerospace Component Suppliers are the fastest-growing segment, driven by the critical need for high-quality finishes that ensure safety and performance in aircraft. The anticipated 30% increase in surface finishing services for the aerospace industry by 2025 underscores this growth. Suppliers should strategically focus on the aerospace sector to capitalise on its rapid growth potential.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Surface Finishing Market Outlook
- Market Size of China Surface Finishing Market, 2025
- Forecast of China Surface Finishing Market, 2032
- Historical Data and Forecast of China Surface Finishing Revenues & Volume for the Period 2022 - 2032F
- China Surface Finishing Market Trend Evolution
- China Surface Finishing Market Drivers and Challenges
- China Surface Finishing Price Trends
- China Surface Finishing Porter's Five Forces
- China Surface Finishing Industry Life Cycle
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Finishing Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Polishing for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Anodizing for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Plating for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Buffing for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Technique Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Mechanical for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Electrochemical for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Electroplating for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Abrasive Wheel for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Surface Material for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Metal for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Aluminum for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Stainless Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Automotive Parts Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Aerospace Component Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Machinery OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Surface Finishing Market Revenues & Volume By Decorative Metal Fabricators for the Period 2022 - 2032F
- China Surface Finishing Import Export Trade Statistics
- Market Opportunity Assessment By Finishing Type
- Market Opportunity Assessment By Technique Used
- Market Opportunity Assessment By Surface Material
- Market Opportunity Assessment By End User
- China Surface Finishing Top Companies Market Share
- China Surface Finishing Competitive Benchmarking By Technical and Operational Parameters
- China Surface Finishing Company Profiles
- China Surface Finishing Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Finishing Type
- Polishing
- Anodizing
- Plating
- Buffing
By Technique Used
- Mechanical
- Electrochemical
- Electroplating
- Abrasive Wheel
By Surface Material
- Metal
- Aluminum
- Steel
- Stainless Steel
By End User
- Automotive Parts Manufacturers
- Aerospace Component Suppliers
- Machinery OEMs
- Decorative Metal Fabricators































